
 Airport Moving Walkways Market | 2026-2036
Airport Moving Walkways Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Moving Walkways Market Analysis
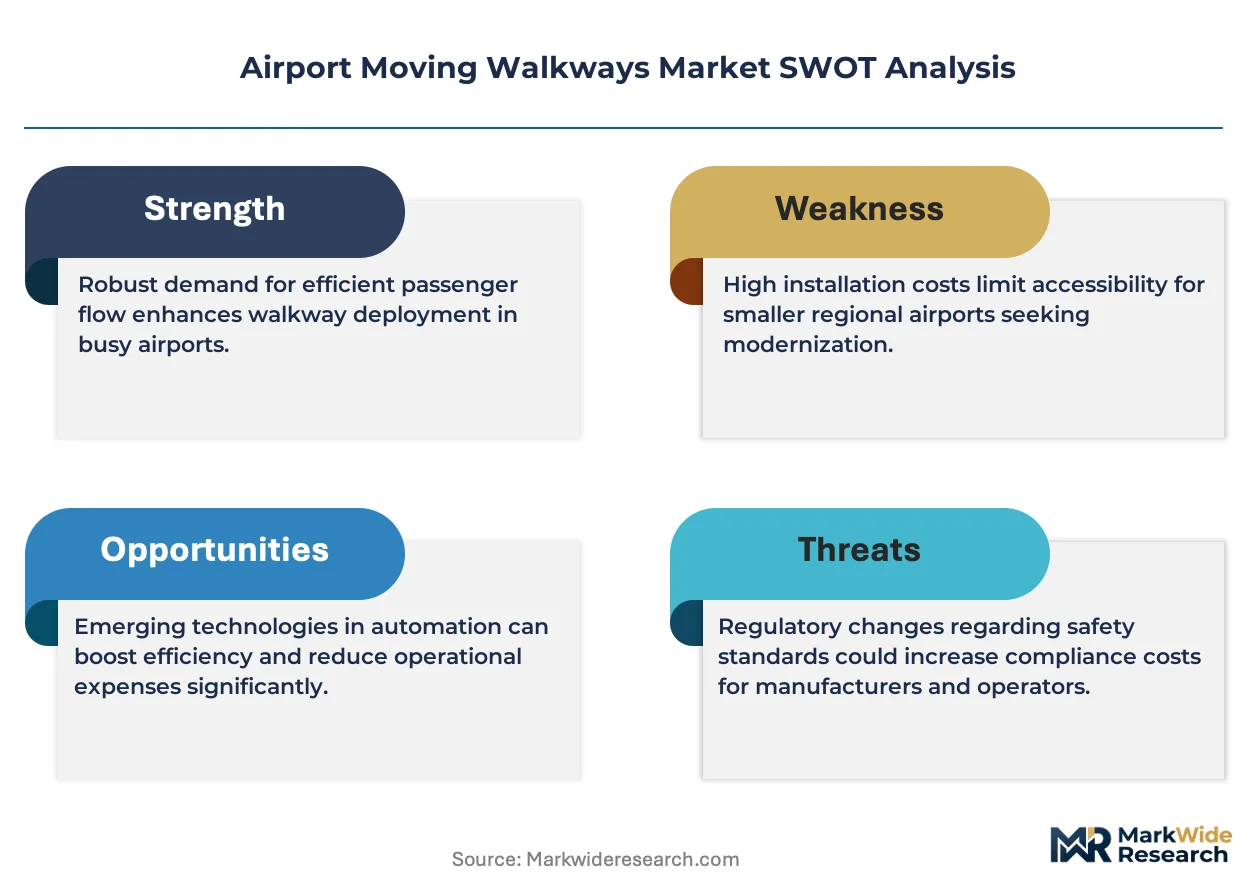
Modular walkway configurations with pre-integrated balustrades and lighting is repositioning how procurement teams evaluate lifecycle costs. Schindler Group leverages its European manufacturing footprint to anchor premium curved walkway contracts in hub airports. Mitsubishi Electric Corporation sustains technology leadership through in-house linear drive development for high-traffic international terminals. Otis Elevator Company dominates the North American aftermarket by controlling service networks across major aviation authorities.
Airport moving walkways are horizontal or slightly inclined conveyor systems, typically spanning 30 to 200 meters, that transport passengers and luggage on a continuous moving belt at speeds of 0.5 to 0.75 meters per second. These systems reduce pedestrian transit time between gates, terminals, and ground transport nodes in facilities exceeding one million annual passengers. Straight walkways occupy the largest installed base due to standardized geometry suited to linear concourse designs, while curved walkways command margin premiums in retrofit projects where existing architecture constrains alignment. Electric motor technology leads new installations for energy efficiency, though linear drives represent the fastest-growing segment in greenfield Middle Eastern and Asian mega-hubs seeking reduced maintenance intervals.
The European Union's Machinery Directive and CE marking requirements shape product compliance for walkway systems deployed across EU member states, while the FAA mandates specific fire-resistance and emergency-stop protocols for equipment installed in US federally funded airport improvements. China's SAMR enforces GB 16899 standards that govern escalator and moving walkway safety certifications, creating divergent testing protocols for multinational suppliers. India's BIS adoption of harmonized safety norms under the CEA's electrical installation codes is raising barriers for uncertified imports in UDAN-funded regional airports. Stakeholders must monitor how diverging national certification timelines affect project bid eligibility and spare parts interoperability across multi-terminal developments.
Market Dynamics
Terminal reconfiguration pressures in Asia-Pacific aviation hubs are forcing procurement teams toward modular walkway systems that minimize structural modification costs during operational expansion phases.
Growth Catalysts
- UDAN Regional Connectivity Scheme:India's greenfield airport construction is accelerating pedestrian circulation infrastructure deployment across tier-2 and tier-3 aviation nodes.
- GB 16899 Certification Tightening:China's SAMR is raising safety barriers for new installations, filtering out uncertified suppliers and consolidating procurement toward compliant system integrators.
- Linear Drive Technology:High-traffic international terminals in Middle Eastern and Asian mega-hubs are adopting in-house developed linear drives to compress maintenance intervals and energy consumption profiles.
Market Restraints
- Copper and Rare Earth Input Volatility:Electric motor manufacturing depends on concentrated supply chains for winding materials and permanent magnet components.
- European Manufacturing Concentration:Premium curved walkway contracts cluster around a limited footprint of certified production facilities, creating bid capacity constraints.
- Fire-Resistance Protocol Stringency:FAA mandates for emergency-stop systems and flame-retardant materials in federally funded US airport improvements extend certification timelines.
Strategic Opportunities
- India's UDAN-Funded Regional Airports:Greenfield construction outside major metropolitan hubs offers first-mover positioning for modular walkway suppliers.
- CEA Electrical Installation Harmonization:India's BIS adoption of unified safety norms creates regulatory tailwind for certified equipment imports.
- Linear Drive and LED Convergence:Integration of energy-efficient propulsion with pre-integrated balustrade lighting systems enables lifecycle cost repositioning in procurement evaluations.
Industry Challenges
- Multinational Certification Fragmentation:Divergent testing protocols across EU Machinery Directive, FAA fire-resistance mandates, and China's GB standards complicate spare parts interoperability.
- Retrofit Architectural Constraints:Existing terminal geometries force curved walkway specifications that demand custom engineering and extend project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Moving Walkways Market |
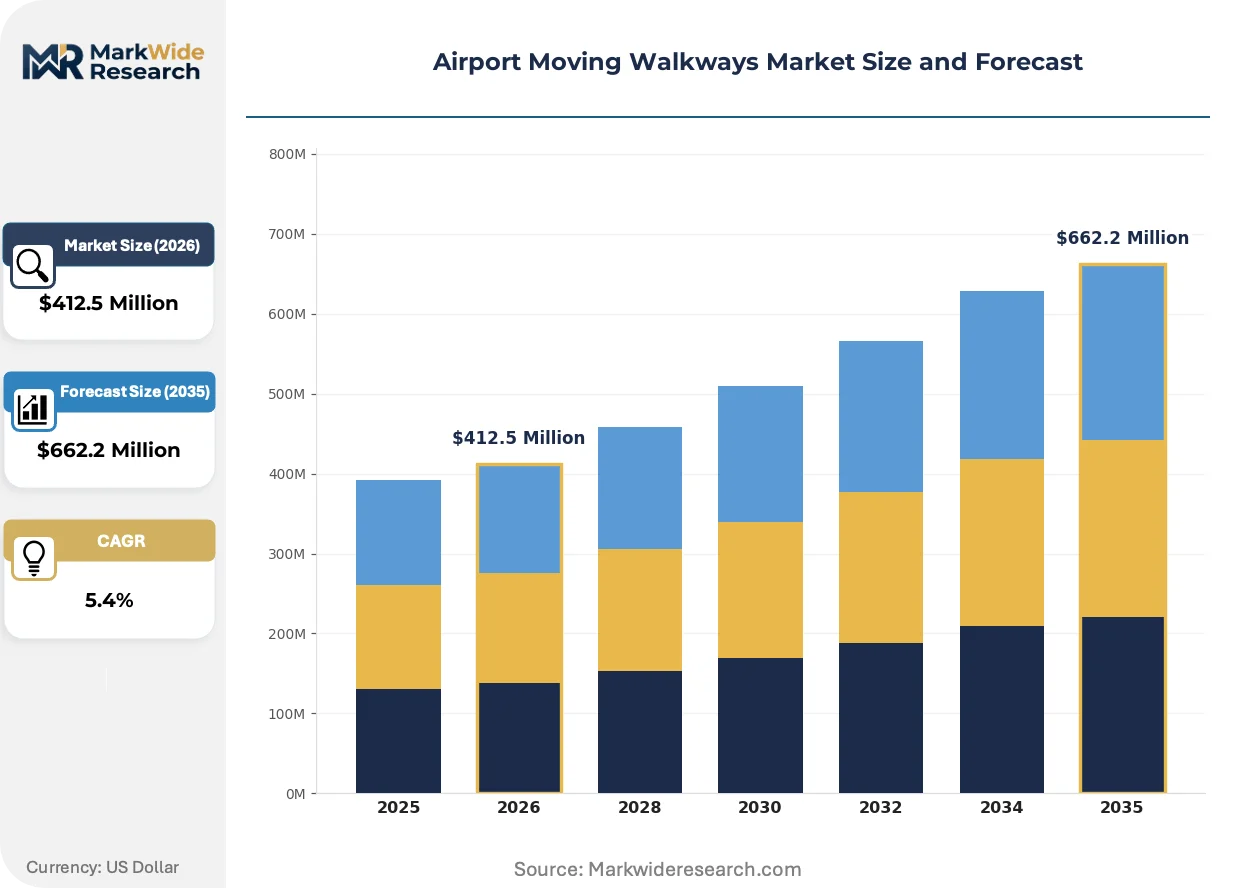
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $662.2 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Walkways, Curved Walkways, Portable Walkways, Custom Walkways Application: Domestic Terminals, International Terminals, Duty-Free Areas, Parking Structures End User: Aviation Authorities, Airport Operators, Construction Companies, Facility Managers Technology: Hydraulic Systems, Electric Motors, Linear Drives, Drive Belt Systems |
| Companies Covered | Schindler Group, Mitsubishi Electric Corporation, Otis Elevator Company, Toshiba Corporation, Fujitec Co., Ltd., Hitachi, Ltd., TK Elevator, Thyssenkrupp AG, KONE Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Moving Walkways Market Emerging Trajectories
Walkway system evolution centers on three vectors: propulsion technology substitution, regulatory compliance automation, and procurement model restructuring that unbundles capital expenditure from operational service obligations.
Magnetic linear drive systems are rewriting competitive positioning in high-throughput terminals. These frictionless propulsion mechanisms eliminate gearbox wear components. Middle Eastern and Asian mega-hubs are specifying linear drives for greenfield concourses exceeding two million annual passengers. The technology is compressing total cost of ownership calculations by extending major maintenance intervals beyond traditional electric motor replacement cycles.
China's SAMR enforcement of GB 16899 safety certifications is tightening supplier qualification protocols. The regulation mandates accelerated door-system testing and emergency-brake response validation. Domestic and multinational suppliers must maintain parallel certification tracks for China's divergent timeline. Equipment categories with integrated safety electronics face the steepest compliance cost adjustments.
Lifecycle contracting is displacing traditional capital purchase models in North American aviation authorities. Major hub operators now unbundle equipment procurement from 15-year service agreements. Channel intermediaries with captive maintenance networks capture margin previously retained by original equipment manufacturers. This shift is most visible among US airports receiving FAA-funded infrastructure grants with mandated performance-based maintenance clauses.
Airport Moving Walkways Market Segmentation
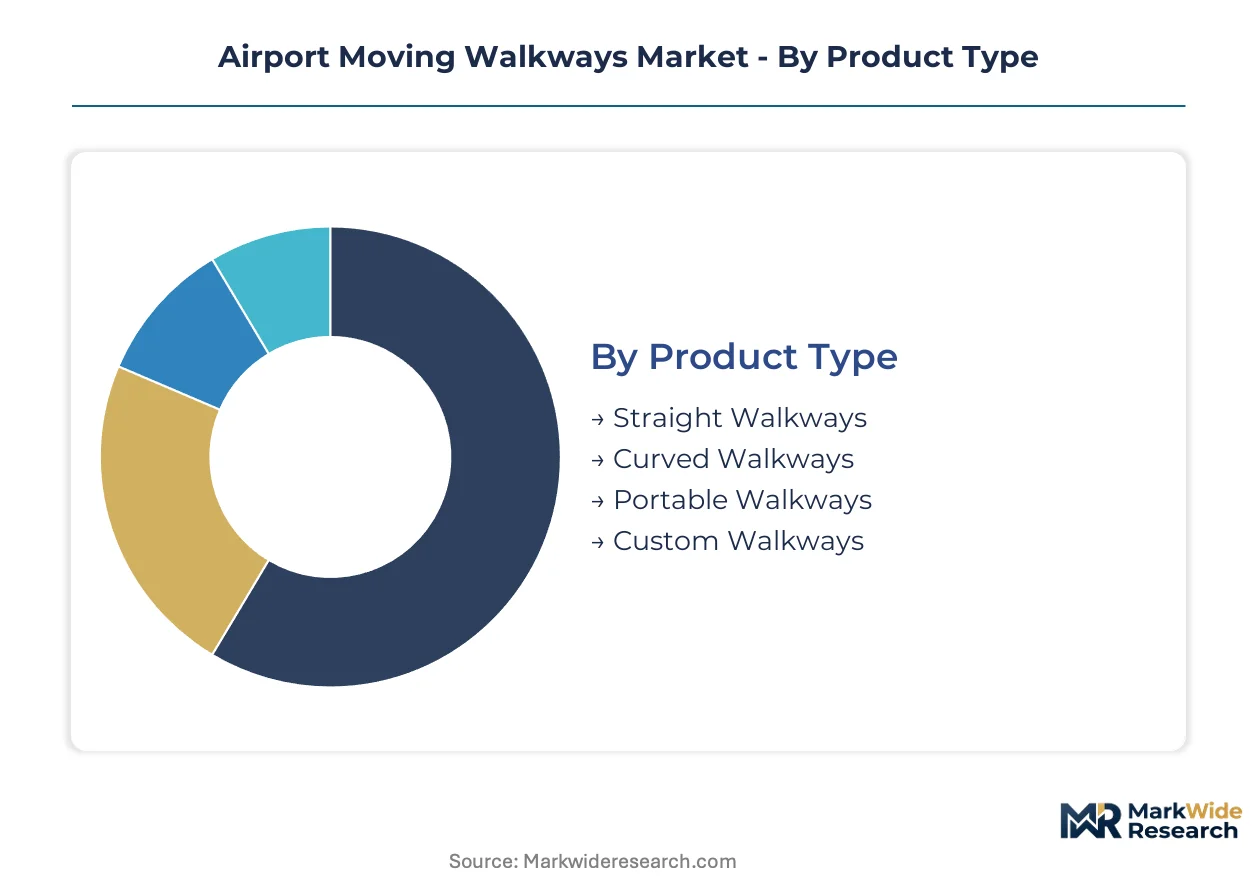
Segmentation in airport moving walkways reveals how procurement priorities diverge between high-volume standardized installations and premium engineered solutions. Terminal operators balance upfront capital constraints against lifecycle maintenance obligations when selecting across product, technology, and end-user categories.
Product Type:
Straight walkways dominate procurement volume through standardized geometry, while curved configurations capture premium margins in constrained retrofit environments.
- Straight Walkways:Linear conveyor systems spanning 30 to 200 meters with standardized balustrade and pallet configurations. Demand concentrates in China's greenfield mega-hubs and India's UDAN-funded regional airports where terminal geometry permits unimpeded concourse design.
- Curved Walkways:Custom-engineered systems with radius-specific pallet articulation and reinforced drive mechanisms. Procurement clusters in Asia-Pacific hub reconfigurations where existing structural constraints prevent linear alignment, commanding engineering premiums of 40-60 percent over standard equivalents.
- Portable Walkways:Modular, redeployable units with self-contained power and control systems for temporary terminal expansions or construction-phase passenger routing.
- Custom Walkways:Bespoke configurations integrating variable incline, dual-speed zones, or architectural cladding specifications for signature terminal interiors.
Mature deployment sits with straight walkways. Newer deployment is concentrated in curved walkways.
Application:
Domestic terminals prioritize throughput density, while international terminals emphasize passenger experience integration with retail and lounge adjacencies.
- Domestic Terminals:High-frequency, short-haul passenger circulation with compressed gate-to-gate transit requirements. India's tier-2 and tier-3 airports under UDAN procurement specifications are accelerating standardized walkway deployment.
- International Terminals:Extended transit corridors connecting immigration, security, and retail zones with integrated lighting and wayfinding systems. Middle Eastern mega-hubs specify linear drive technology to minimize maintenance disruption in 24-hour operations.
- Duty-Free Areas:Reduced-speed configurations encouraging retail exposure while maintaining passenger flow capacity.
- Parking Structures:Weather-resistant, inclined systems linking remote parking to terminal cores with enhanced corrosion protection specifications.
Volume procurement clusters in domestic terminals. Margin expansion concentrates in international terminals.
End User:
Aviation authorities impose certification mandates that filter supplier qualification, while airport operators directly negotiate lifecycle cost structures.
- Aviation Authorities:Regulatory bodies mandating FAA fire-resistance protocols or China's GB 16899 safety certifications that determine bid eligibility for federally funded improvements.
- Airport Operators:Direct procurement entities evaluating total cost of ownership across 15-20 year service horizons, increasingly unbundling equipment purchase from maintenance obligations.
- Construction Companies:Prime contractors integrating walkway specifications into terminal construction packages with milestone-based delivery schedules.
- Facility Managers:Post-handover operators responsible for uptime guarantees and predictive maintenance program execution.
Certification leverage sits with aviation authorities. Procurement decision authority is shifting toward airport operators.
Technology:
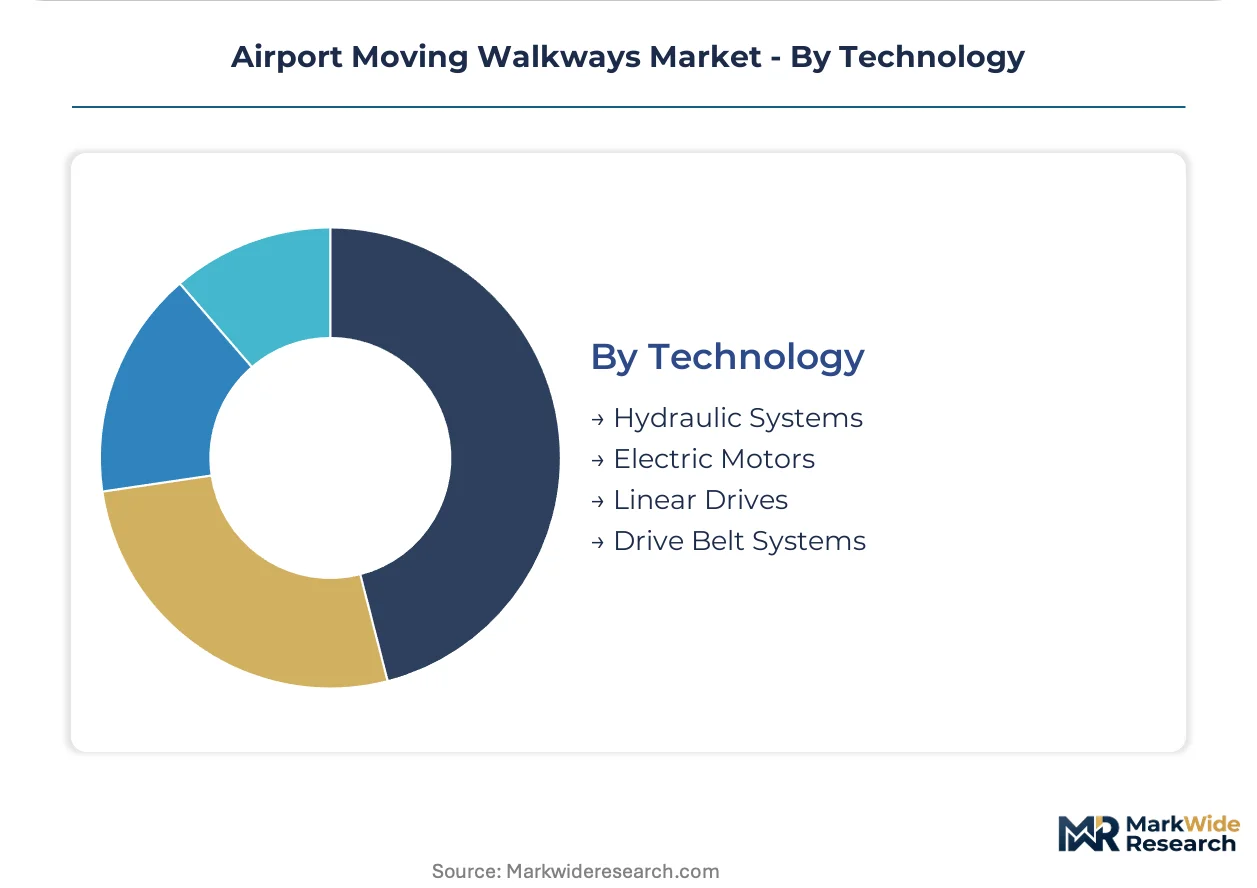
Electric motors retain installed base dominance, while linear drives are gaining share fastest in high-traffic greenfield specifications.
- Electric Motors:Conventional induction or permanent magnet motor configurations with gearbox reduction. Supply chain concentration for copper windings and rare earth magnets creates input cost volatility.
- Linear Drives:Frictionless magnetic propulsion eliminating mechanical wear components. Middle Eastern and Asian mega-hubs exceeding two million annual passengers specify this technology to extend major maintenance intervals.
- Hydraulic Systems:Legacy installations in inclined or heavy-load applications requiring precise torque control.
- Drive Belt Systems:Traction-based alternatives for low-speed, short-distance deployments with simplified maintenance access.
Installed base concentration remains with electric motors. Technology transition is accelerating in linear drives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European manufacturers supply curved walkway systems to Asia-Pacific hub reconfigurations while Chinese and Indian domestic demand absorbs standardized straight configurations from regional fabricators.
China
Greenfield mega-hubs in Beijing and Chengdu specify high-capacity straight walkways for linear concourse designs. SAMR enforcement of GB 16899 standards filters supplier qualification toward certified system integrators. Yangtze River Delta production clusters concentrate electric motor manufacturing for domestic installation and Southeast Asian export.
India
UDAN-funded regional airports in tier-2 and tier-3 cities accelerate procurement of modular walkway systems. BIS adoption of CEA harmonized electrical installation codes raises certification barriers for uncertified imports. Maharashtra and Karnataka aviation nodes anchor greenfield terminal construction with standardized pedestrian circulation infrastructure.
United States
Major hub operators unbundle equipment procurement from 15-year service agreements under FAA-funded infrastructure grants. FAA fire-resistance and emergency-stop protocols extend certification timelines for new installations. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor aftermarket service network concentration.
Germany
Premium curved walkway engineering serves retrofit projects across constrained European terminal architectures. EU Machinery Directive and CE marking requirements shape product compliance for cross-border deployment. Baden-Württemberg manufacturing clusters supply radius-specific pallet articulation systems to Middle Eastern mega-hub contracts.
United Arab Emirates
Dubai and Abu Dhabi mega-hubs specify linear drive technology to minimize maintenance disruption in 24-hour operations. MOHAP-adjacent aviation safety frameworks align with international certification standards for high-throughput specifications. Jebel Ali industrial zones concentrate logistics for regional spare parts distribution.
Airport Moving Walkways Market Vendor Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive elevator and escalator divisions. European and Japanese manufacturers dominate premium curved walkway engineering through certified production footprints. Three archetypes define positioning: integrated building technology conglomerates, specialized vertical transportation manufacturers, and regional system integrators with modular assembly capabilities. Capacity expansion in Asian manufacturing zones and strategic partnerships for local certification compliance constitute the dominant competitive moves.
Within the integrated conglomerate tier, Schindler Group, Mitsubishi Electric Corporation, and Otis Elevator Company exemplify divergent geographic anchoring strategies. Schindler occupies a position tied to European curved walkway engineering for hub reconfigurations. Mitsubishi Electric represents technology leadership through in-house linear drive development. Otis anchors aftermarket service network control across North American aviation authorities receiving federal infrastructure funding.
| Leading Market Players |
|---|
| Schindler Group |
| Mitsubishi Electric Corporation |
| Otis Elevator Company |
| Toshiba Corporation |
| Fujitec Co., Ltd. |
| Hitachi, Ltd. |
| TK Elevator |
| Thyssenkrupp AG |
| KONE Corporation |
| Others |
Supply Flow & Price Mechanics
China's GB 16899 safety certification tightening gates qualified supply and premium-tier pricing access for curved walkway systems in Asia-Pacific hub reconfigurations. Airport operators now face bifurcated procurement landscapes where certified integrators command margin premiums while uncertified fabricators retreat to standardized straight configurations.
Pricing Analysis
Margin tightening in curved walkway tiers reflects European manufacturing concentration and custom engineering requirements. Three-tier pricing structure across premium, standard, and economy levels separates GB 16899-certified curved systems from modular straight configurations and redeployable portable units. Cost compression in standard straight walkways accelerates because India's UDAN-funded regional airports prioritize capital efficiency over lifecycle optimization. Tier-2 and tier-3 airport operators exhibit highest price sensitivity, while Middle Eastern mega-hubs purchasing linear drive technology demonstrate lowest.
Supply Chain Analysis
India's BIS adoption of CEA harmonized electrical installation codes and domestic-content preferences reshapes sourcing toward Maharashtra and Karnataka fabrication clusters. Manufacturing concentrates in Germany, China, and India for pallet articulation systems, electric motor assemblies, and modular balustrade components. Copper winding materials and rare earth permanent magnets draw from concentrated extraction geographies. Single-source vulnerability persists for linear drive magnetic components. Distribution runs through certified system integrators with captive maintenance networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European curved walkway engineering capacity constitutes the binding constraint propping premium-tier pricing. Procurement bottlenecks at certified production facilities reward early-mover positioning in qualification pipelines.
For Market Incumbents: Anticipate linear drive technology substitution threatening electric motor aftermarket revenue streams. Defensive consolidation requires backward integration into rare earth magnet supply and capacity addition in India's UDAN-funded aviation nodes. Certification investment in China's parallel GB 16899 compliance tracks preserves bid eligibility. For New Entrants and Emerging Players: India's tier-2 airport operators under UDAN procurement specifications represent the most penetrable buyer archetype. White-space targets include modular portable walkways for temporary terminal expansions and LED-integrated balustrade systems for lifecycle contracting repositioning. Channel partnership with construction companies integrating milestone-based delivery schedules offers viable go-to-market angle. For Investors and Strategic Acquirers: Schindler Group's European manufacturing footprint expansion is the leading indicator that premium curved walkway capacity scarcity will persist. Long-term viability frames around 15-20 year service agreement unbundling and aftermarket network control. Acquisition target archetype includes regional system integrators with modular assembly capabilities and local certification compliance. Watch for India's BIS enforcement timeline as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| GB 16899 Certification Investment | SAMR compliance unlocks bid eligibility in China's greenfield mega-hub procurement cycles. |
| Linear Drive Technology Licensing | Frictionless propulsion systems extend maintenance intervals for Middle Eastern 24-hour operations. |
| Backward Integration into Rare Earth Supply | Magnet component sourcing control insulates against permanent magnet price volatility. |
| Regional Manufacturing Footprint Expansion | Maharashtra and Karnataka facilities capture UDAN-funded tier-2 airport construction demand. |
| Lifecycle Service Agreement Unbundling | FAA-funded infrastructure grants with performance clauses shift margin to channel intermediaries. |
Methodological Framework
Multi-period observation of terminal reconfiguration cycles, certification timeline divergences, and linear drive adoption rates anchored the trend analysis, supplemented by interviews with airport procurement directors, aviation authority certification officers, terminal construction project managers, and aftermarket service network heads. Secondary validation drew from FAA infrastructure grant disclosures, China's SAMR certification registries, India's UDAN project development databases, and EU Machinery Directive compliance filings. Bottom-up installation volume estimates triangulated against top-down aviation authority capital expenditure allocations.
Input-output matrices mapped propulsion technology substitution, product type geometry requirements, and end-user procurement authority shifts across the projection horizon. Segmentation dimensions modeled include walkway configuration type, terminal application category, technology architecture, and regional regulatory cluster. CAGRs derived from slope analysis of historic installation data and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated UDAN scheme funding disbursement schedules and GB 16899 enforcement phase-in timelines.
Revisions become necessary when copper and rare earth input volatility exceeds modeled bands, when certification timeline divergences compress spare parts interoperability, or when FAA fire-resistance protocol amendments extend approval timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Engineered Material Arresting System Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Fixed-Base Operator Market