
 Aerobridge Market | 2026-2036
Aerobridge Market Size, Share, and Industry Trends Forecast 2026-2036
Aerobridge Market Analysis
Low-cost carrier expansion is decoupling aerobridge procurement from full-service airline specifications. CIMC Tianda Holdings sustains manufacturing scale across Asian airport construction programs. ThyssenKrupp AG leverages its elevator and mobility engineering heritage to anchor European retrofit demand. Mitsubishi Heavy Industries competes through advanced automation integration in Japanese hub installations.
An aerobridge is a covered, enclosed passenger boarding bridge connecting airport terminal gates directly to aircraft doors, typically constructed from steel truss structures with climate control systems and adjustable height mechanisms to accommodate aircraft from regional turboprops to wide-body jets. Its primary purpose is to enable weather-protected, accessible passenger embarkation and disembarkation while reducing ground handling time and tarmac congestion. Fixed aerobridges dominate established hub infrastructure where terminal geometry permits permanent installation, while mobile aerobridges capture growth at regional airports and remote stand operations requiring equipment repositioning flexibility. Automation technologies represent the fastest-evolving segment as airports pursue reduced ground crew dependency and precision docking alignment.
The FAA mandates aerobridge design compliance with ADA accessibility standards and aircraft door envelope compatibility under Part 139 airport certification requirements. EASA enforces CE-marked structural safety and electromagnetic compatibility for European installations, while China's GB standards and MIIT directives govern domestic manufacturing certification and smart airport integration protocols. Airport operators and equipment suppliers must monitor evolving sustainability mandates and automation certification pathways as regulatory divergence between jurisdictions intensifies compliance complexity.
Market Dynamics
Airport infrastructure procurement is decoupling from legacy full-service airline specifications as low-cost carriers demand faster turnaround compatibility and modular aerobridge configurations. This structural shift is compressing design cycles and forcing manufacturers to reconcile automation integration with cost discipline across divergent operator requirements.
Growth Catalysts
- UDAN Regional Connectivity Schemes:India's subsidized regional air routes are accelerating greenfield airport development in Noida, Goa, and tier-2 cities, directly expanding passenger boarding bridge deployment pipelines.
- EU F-Gas Regulation Phase-Down:The European Union's hydrofluorocarbon reduction mandates are forcing climate-controlled aerobridge retrofits, creating replacement demand for low-global-warming-potential refrigeration systems.
- Automation Integration:Sensor-based precision docking and reduced ground crew dependency are becoming procurement prerequisites at Japanese and South Korean hub airports.
Market Restraints
- Steel and Aluminum Input Volatility:Aerobridge truss fabrication depends on structural steel and aluminum alloy prices, which fluctuate with energy costs and mining supply constraints.
- Specialized Hydraulics Supply Concentration:Precision height-adjustment mechanisms rely on a concentrated supplier base in Germany and Japan, creating single-source vulnerability.
- Aircraft Door Envelope Fragmentation:Incompatible door configurations across Airbus, Boeing, and COMAC fleets force costly adaptable docking head engineering.
Strategic Opportunities
- Remote Stand Operations in Southeast Asia:Indonesian and Philippine secondary airports lack fixed gate infrastructure, creating mobile aerobridge penetration potential.
- Dual Carbon Goals in China:Beijing's carbon neutrality targets are mandating electric ground support equipment integration, opening electrified aerobridge specification windows.
- Smart Airport Convergence:Integration of IoT sensors with building management systems is enabling predictive maintenance contracts as new revenue streams.
Industry Challenges
- Automation Certification Timelines:EASA and FAA divergent pathways for autonomous docking systems are delaying product launches and fragmenting development roadmaps.
- Legacy Terminal Geometry Constraints:Fixed aerobridge installation at established European hubs requires structural reinforcement of aging concrete aprons, complicating retrofit execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerobridge Market |
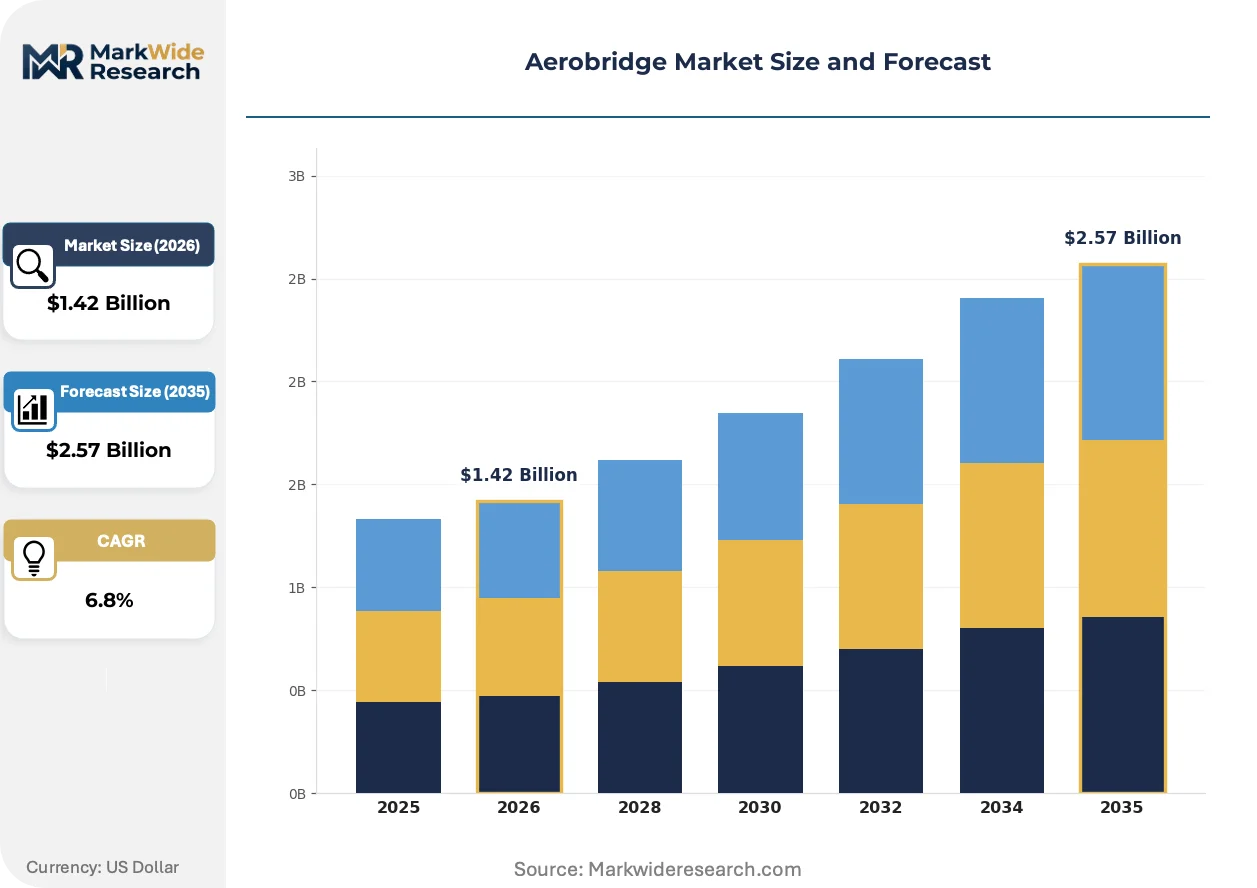
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Aerobridge, Mobile Aerobridge, Self-Propelled Aerobridge, Modular Aerobridge End User: Airports, Airlines, Ground Handling Service Providers, Government Agencies Deployment: On-Ground, In-Terminal, Remote Location, Temporary Installation Technology: Hydraulic Systems, Pneumatic Systems, Electrical Systems, Automation Technologies |
| Companies Covered | ShinMaywa Industries, Ltd., Mitsubishi Heavy Industries, Ltd., CIMC Tianda Holdings Co., Ltd., John Bean Technologies Corporation, ThyssenKrupp AG, TK Airport Solutions S.A., Oshkosh Corporation, PT Bukaka Teknik Utama Tbk, ADELTE Group S.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerobridge Market Emerging Trajectories
Automation technologies are compressing ground handling timelines while sustainability mandates reshape climate system specifications. These forces are simultaneously elevating technical barriers and opening specification windows for suppliers capable of integrating precision docking with energy-efficient operations.
Vision-based aircraft recognition systems are converging with machine learning algorithms to enable autonomous aerobridge alignment without ground crew intervention. Full-service carriers at Tokyo Haneda and Singapore Changi are piloting these systems for A380 and 747 operations. The technology is converging with predictive maintenance platforms to compress turnaround times and reduce tarmac congestion during peak scheduling windows.
The EU Green Deal's F-Gas Regulation is mandating hydrofluorocarbon phase-downs in climate-controlled aerobridge systems, forcing refrigerant transitions to CO2 or ammonia-based alternatives. European fixed-base operators face compliance deadlines that compress replacement cycles for installed base equipment. Mediterranean hub airports in Spain and Italy are responding with accelerated retrofit procurement to avoid operational penalties.
Airline procurement departments are unbundling aerobridge acquisition from long-term maintenance contracts, shifting toward competitive service provision by third-party ground handlers. This disintermediation pressures original equipment manufacturers to defend aftermarket revenue through predictive analytics and remote diagnostics. The pattern is most visible in India, where airport privatization and UDAN scheme expansion are fragmenting buyer concentration across regional operators.
Aerobridge Market Segmentation
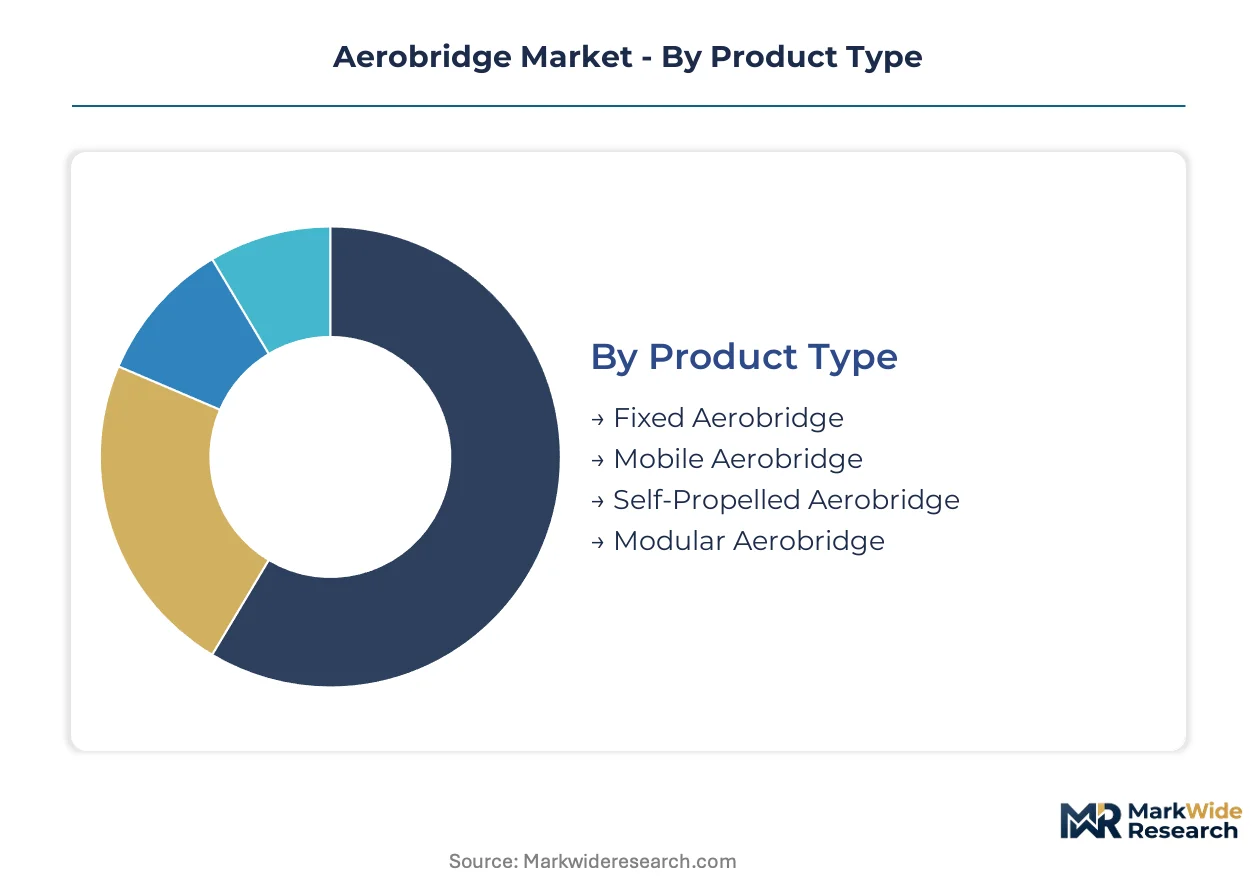
Aerobridge procurement decisions hinge on terminal infrastructure age, aircraft mix, and turnaround time requirements. Manufacturers must align product configurations with divergent operator economics across hub airports, regional terminals, and remote stand operations.
Product Type:
Buyers select fixed versus mobile configurations based on gate permanence and capital recovery timelines.
- Fixed Aerobridge:Permanent steel truss installations anchor established hub terminals with high daily aircraft movements. Demand concentrates at Indian greenfield airports under UDAN regional connectivity schemes, where permanent gate infrastructure supports subsidized route economics.
- Mobile Aerobridge:Wheeled or trailer-mounted units reposition across apron stands without structural foundations. Indonesian and Philippine secondary airports lacking fixed gate infrastructure drive penetration, as remote stand operations require equipment flexibility for irregular scheduling patterns.
- Self-Propelled Aerobridge:Motorized chassis enables autonomous positioning without tow vehicles.
- Modular Aerobridge:Prefabricated sections reduce on-site construction duration for rapid terminal expansion.
Volume sits with fixed installations at major hubs; growth tilts toward mobile configurations for regional airport flexibility.
End User:
Procurement authority fragmentation across airport operators, airlines, and ground handlers reshapes contract structures.
- Airports:Terminal owners specify aerobridge systems during construction or retrofit programs. Indian airport privatization and Noida International Airport development accelerate direct procurement by infrastructure concessionaires seeking long-term operational control.
- Airlines:Full-service carriers and low-cost operators negotiate dedicated gate equipment at hub bases. Low-cost carrier expansion in Southeast Asia compresses specification cycles, as carriers demand faster turnaround compatibility and standardized docking interfaces.
- Ground Handling Service Providers:Third-party handlers acquire mobile units for multi-client apron flexibility.
- Government Agencies:Military and state aviation authorities procure specialized configurations for dual-use airfields.
Airport operators dominate capital expenditure; airlines gain procurement influence where gate leasing shifts to preferential use agreements.
Deployment:
Site constraints and operational permanence determine installation methodology and equipment selection.
- On-Ground:Apron-level placement accommodates regional turboprops and narrow-body jets without vertical elevation requirements. Tier-2 Indian airports under UDAN schemes favor ground-level deployment for cost containment on low-traffic routes.
- In-Terminal:Elevated bridge systems integrate with passenger boarding lounges at major hubs. Tokyo Haneda and Singapore Changi automation pilots target in-terminal precision docking to minimize ground crew intervention during peak windows.
- Remote Location:Stand-alone positioning serves overflow parking and maintenance areas.
- Temporary Installation:Rapid deployment supports construction phasing and emergency capacity.
In-terminal systems command premium positioning; remote location deployment expands fastest as congestion management pressures intensify.
Technology:
Regulatory mandates and labor cost trajectories elevate automation and climate system specifications.
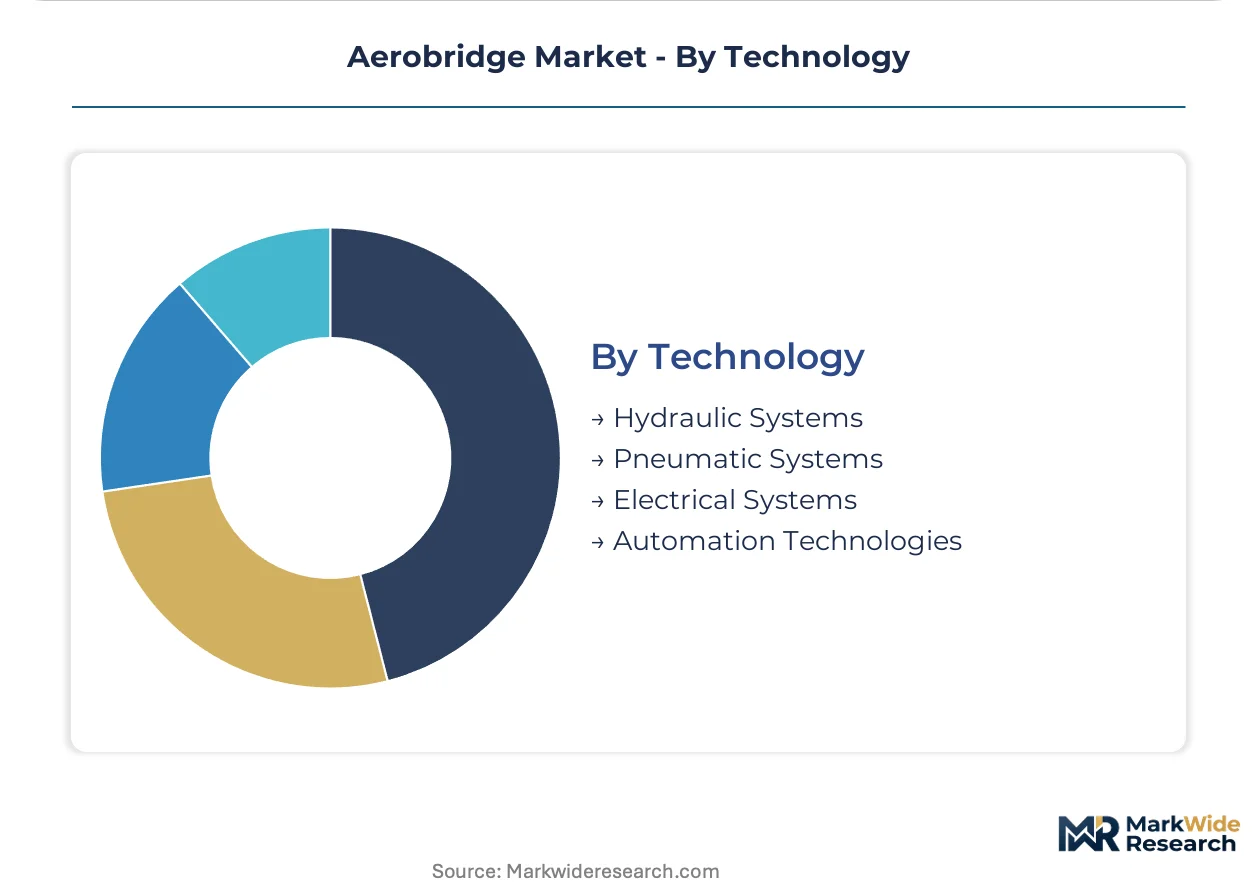
- Hydraulic Systems:Precision height-adjustment mechanisms dominate legacy installed base and heavy-lift applications. German and Japanese supplier concentration for specialized hydraulics creates single-source vulnerability, constraining procurement flexibility.
- Electrical Systems:Motor-driven elevation and extension align with China's dual carbon goals for electrified ground support equipment. Beijing's carbon neutrality mandates open specification windows for electric aerobridge variants at domestic hub installations.
- Pneumatic Systems:Compressed-air actuation serves specific environmental and safety requirements.
- Automation Technologies:Sensor-based precision docking and autonomous alignment represent the advancing frontier. EASA and FAA divergent certification pathways delay product launches, fragmenting development roadmaps across jurisdictions.
Hydraulic systems retain installed base dominance; automation technologies gain specification share fastest at Japanese and South Korean hub airports.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India's aviation corridor are concentrating aerobridge procurement around Noida International Airport and UDAN-subsidized regional routes. China's dual carbon mandates and Japan's automation pilots are reshaping specification patterns across manufacturing and installation clusters.
India
UDAN regional connectivity schemes are accelerating greenfield airport development in Noida, Goa, and tier-2 cities. The Ministry of Civil Aviation's infrastructure concessions are fragmenting procurement across private operators. The Delhi-Mumbai Industrial Corridor anchors manufacturing partnerships for steel truss fabrication serving domestic deployment pipelines.
China
Beijing's dual carbon goals are mandating electrified ground support equipment integration at hub airports. MIIT directives on smart airport protocols are governing domestic certification for automated docking systems. The Yangtze River Delta concentration of CIMC Tianda manufacturing scales output for Asia-Pacific terminal construction programs.
Japan
Tokyo Haneda and Osaka Kansai automation pilots are deploying vision-based precision docking for wide-body operations. METI standards on sensor integration are elevating technical barriers for foreign suppliers. The Chubu-Nagoya industrial belt concentrates precision hydraulics manufacturing for height-adjustment mechanisms.
Germany
The EU F-Gas Regulation is forcing climate-controlled aerobridge retrofits across Mediterranean hubs in Spain and Italy. EASA CE-marking requirements on structural safety are fragmenting certification timelines. The Ruhr industrial region retains specialized hydraulics supplier concentration for precision elevation systems.
United States
FAA Part 139 mandates on ADA accessibility and aircraft door envelope compatibility are governing retrofit specifications at aging hub terminals. The IRA's clean energy provisions are opening electrification windows for ground support equipment. The Pacific Northwest and Southeast aviation clusters are diversifying procurement across low-cost carrier expansion programs.
Aerobridge Market Vendor Landscape
Top-tier vendors anchor hub airport automation contracts, while mid-tier fabricators capture regional mobile unit demand. Japanese and German engineering heritage concentrates precision systems capability, while Chinese scale advantages dominate Asia-Pacific construction timelines. Strategic archetypes separate automation-integrated specialists from cost-optimized mobile suppliers and maintenance-contract defenders. Competitive moves center on predictive maintenance platform development and electrified product line expansion.
Within the automation-integrated tier, Mitsubishi Heavy Industries and ShinMaywa Industries occupy positions exemplifying Japanese precision engineering heritage. CIMC Tianda Holdings represents scale-driven manufacturing concentration serving Asia-Pacific infrastructure waves. ThyssenKrupp AG anchors European retrofit demand through elevator and mobility engineering lineage. These three archetypes—precision automation, manufacturing scale, and European engineering—capture divergent procurement vectors across hub modernization, greenfield construction, and regulatory compliance cycles.
| Leading Market Players |
|---|
| ShinMaywa Industries, Ltd. |
| Mitsubishi Heavy Industries, Ltd. |
| CIMC Tianda Holdings Co., Ltd. |
| John Bean Technologies Corporation |
| ThyssenKrupp AG |
| TK Airport Solutions S.A. |
| Oshkosh Corporation |
| PT Bukaka Teknik Utama Tbk |
| ADELTE Group S.L. |
| Others |
Supply Flow & Price Mechanics
EU F-Gas Regulation phase-down mandates are forcing climate-controlled aerobridge retrofits across Mediterranean hubs, compelling manufacturers to absorb refrigerant transition costs or pass them through to fixed-base operators while competing for replacement cycle contracts.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Indian greenfield airports under UDAN schemes compress procurement windows. Three-tier pricing structure across premium, standard, and economy levels segments by automation integration depth and climate system specifications. Cost compression in standard-tier hydraulic systems intensifies because steel and aluminum input volatility squeezes fabrication margins. Low-cost carriers exhibit highest price sensitivity, prioritizing turnaround compatibility over precision docking features.
Supply Chain Analysis
India's PLI scheme and China's domestic-content requirements for smart airport infrastructure are reshaping sourcing patterns for steel truss fabrication and sensor integration. Manufacturing gravity centers on China, Germany, and Japan for precision hydraulics and automation components. Structural steel and aluminum alloy procurement draws from energy-cost-sensitive smelters, while specialized hydraulic systems rest on single-source German and Japanese suppliers. Tariff exposure on steel inputs threatens margin stability. Distribution runs through airport infrastructure concessionaires and ground handling service providers with multi-year maintenance bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aerobridge market functions as a cost-of-compliance arena where EU F-Gas Regulation mandates erect regulatory moats favoring incumbents with certified low-global-warming-potential climate systems.
For Market Incumbents: Hedge automation certification fragmentation by pursuing parallel EASA and FAA pathway investments rather than sequential approvals. Prioritize predictive maintenance platform development to defend aftermarket revenue against third-party ground handler disintermediation. Backward integration into precision hydraulics reduces single-source vulnerability from German and Japanese supplier concentration. For New Entrants and Emerging Players: Vision-based aircraft recognition systems offer a technology-first wedge for autonomous docking contracts at Southeast Asian secondary airports lacking fixed gate infrastructure. Mobile aerobridge penetration in Indonesia and the Philippines presents the most penetrable white-space target. Pursue ground handling service provider direct sales channels bypassing established airport operator procurement hierarchies. For Investors and Strategic Acquirers: The window for entry favors automation-integrated specialists with EASA CE-marking and FAA Part 139 certification credentials already secured. Mid-cap fabricators serving Asia-Pacific greenfield construction timelines offer viable acquisition profiles within a five-to-ten-year infrastructure investment cycle. Watch for EASA-FAA regulatory convergence signals as inflection indicators for autonomous docking system commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Certification Parallel Pathway | Dual EASA-FAA pursuit compresses time-to-market for autonomous docking systems at Tokyo Haneda and Singapore Changi. |
| Predictive Maintenance Platform Development | IoT sensor integration with building management systems enables recurring revenue contracts with Indian airport concessionaires. |
| Low-GWP Refrigerant System Retrofit | CO2 and ammonia-based climate systems capture EU F-Gas Regulation compliance demand across Spanish and Italian Mediterranean hubs. |
| Mobile Aerobridge Geographic Expansion | Wheeled unit deployment addresses Indonesian and Philippine secondary airport remote stand flexibility requirements. |
| Electrified Product Line Introduction | Motor-driven elevation systems align with China's dual carbon mandates at Beijing and Shanghai Pudong hub installations. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this aerobridge market assessment. Primary interviews with airport infrastructure concessionaires, ground handling procurement directors, aerobridge maintenance heads, and OEM engineering teams combined with EASA certification databases, FAA Part 139 compliance records, MIIT smart airport directives, and steel trade association pricing data. Bottom-up installation forecasts triangulated against top-down infrastructure investment pipeline analysis.
Granularity-level modeling distinguished fixed versus mobile configurations, hydraulic versus electrical elevation technologies, and automation integration tiers across the projection horizon. Segmentation dimensions included product type, end-user procurement authority, deployment methodology, and technology specification. CAGRs derived from infrastructure investment schedules, airline fleet expansion patterns, and regulatory compliance deadline clustering. Aircraft door envelope fragmentation and steel input volatility served as scenario sensitivity inputs.
Several conditions sit outside the modeled scope, including unannounced airport privatization reversals, abrupt refrigerant technology shifts, and geopolitical trade restrictions on steel alloys. Forecasts reflect documented assumptions about UDAN scheme continuation, EU F-Gas Regulation enforcement intensity, and automation certification pathway convergence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
Engineered Material Arresting System Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Airfield Ground Lighting (AGL) Systems Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Passenger Boarding Bridge Market