
 Aircraft Tow Tractors Market | 2026-2036
Aircraft Tow Tractors Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Tow Tractors Market Analytics
F-Gas Regulation is repositioning the competitive landscape for airport ground support equipment across Europe. TLD Group leverages its vertical integration in electric drivetrain manufacturing to capture premium positioning in zero-emission tow tractors. JBT AeroTech anchors its market presence through extensive service networks spanning major North American and European hubs. Textron GSE competes on manufacturing scale, sustaining cost advantages in conventional diesel-powered units for cargo handler fleets.
Aircraft tow tractors are self-propelled vehicles engineered to push or pull aircraft on the ground, typically generating drawbar pull forces from 20,000 to 600,000 pounds depending on aircraft class, with diesel, battery-electric, or hybrid powertrains mated to hydrostatic or mechanical drivetrains. Their primary purpose is eliminating the need for aircraft engines during taxiing, reducing fuel consumption, emissions, and engine wear during ground operations. Electric tow tractors now represent the fastest-expanding product category as airports face binding net-zero commitments, while towbarless tractors command margin premiums due to their ability to handle wide-body aircraft without towbar attachment complexity. Conventional diesel units retain dominant installed-base share in cargo handler and remote parking deployments where charging infrastructure remains limited.
The FAA mandates airside equipment safety standards through AC 150/5220 specifications, while the EU Green Deal and associated F-Gas Regulation constrain fluorinated greenhouse gas use in ground support equipment manufacturing and operation. EASA enforces CS-25 compatibility requirements that govern tow tractor interface geometry and load ratings for commercial aircraft. Stakeholders must weigh battery-electric platform readiness against residual value risks in diesel assets as regulatory timelines tighten across major aviation jurisdictions.
Market Dynamics
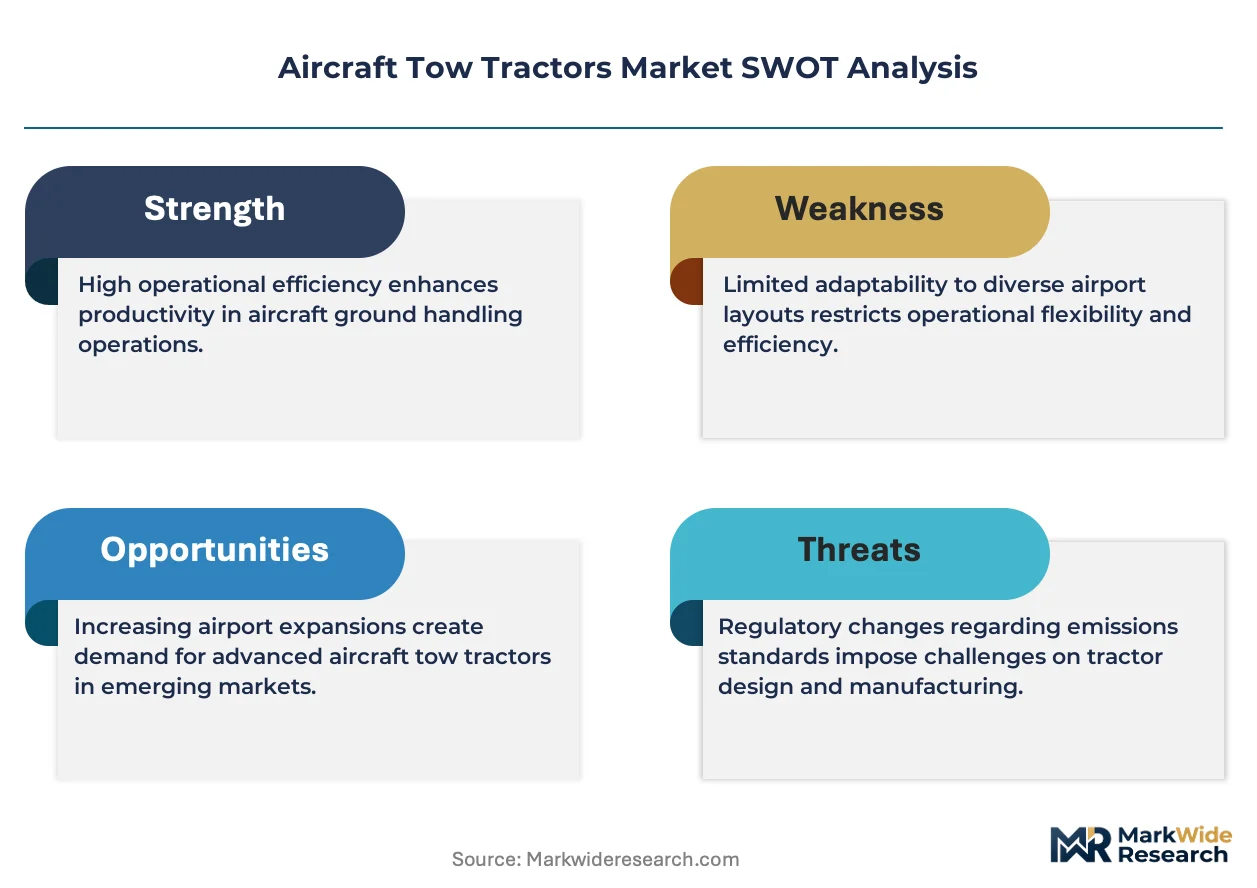
Europe's F-Gas Regulation is forcing a wholesale powertrain transition across airport ground support equipment, compressing diesel asset residual values while elevating battery-electric platform premiums in procurement decisions.
Growth Catalysts
- EU Green Deal mandates:Binding net-zero commitments at Frankfurt, Munich, and Amsterdam Schiphol are accelerating fleet replacement cycles for zero-emission tow tractors.
- Battery energy density gains:Lithium-iron-phosphate cell chemistry improvements now support 600,000-pound drawbar pull requirements for wide-body aircraft handling.
- Germany:Hub expansion projects at major airports are concentrating demand for towbarless electric tractors capable of handling A380 and 777X fleets.
Market Restraints
- Lithium supply concentration:Cathode material processing bottlenecks in China are creating input cost volatility for battery pack manufacturers.
- Charging infrastructure gaps:Remote cargo aprons and de-icing pads lack high-capacity grid connections needed for 350kW fast-charging deployment.
- Diesel asset stranding risk:Compressed regulatory timelines under F-Gas Regulation are eroding resale values for conventional hydrostatic drivetrain units.
Strategic Opportunities
- India:Greenfield airport construction under the UDAN regional connectivity scheme presents untapped demand for electric ground support equipment.
- Predictive maintenance convergence:Integration of telematics platforms with digital twin modeling is creating service revenue streams beyond hardware sales.
- Leasing channel innovation:Power-by-the-hour contracts for tow tractor fleets are reducing capital barriers for regional cargo handlers.
Industry Challenges
- High-voltage technician scarcity:Airports face recruitment gaps for personnel certified to service 800V battery architectures and DC fast-charging systems.
- EASA CS-25 interface certification:Towbarless tractor nose-gear compatibility testing requires 18-24 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Tow Tractors Market |
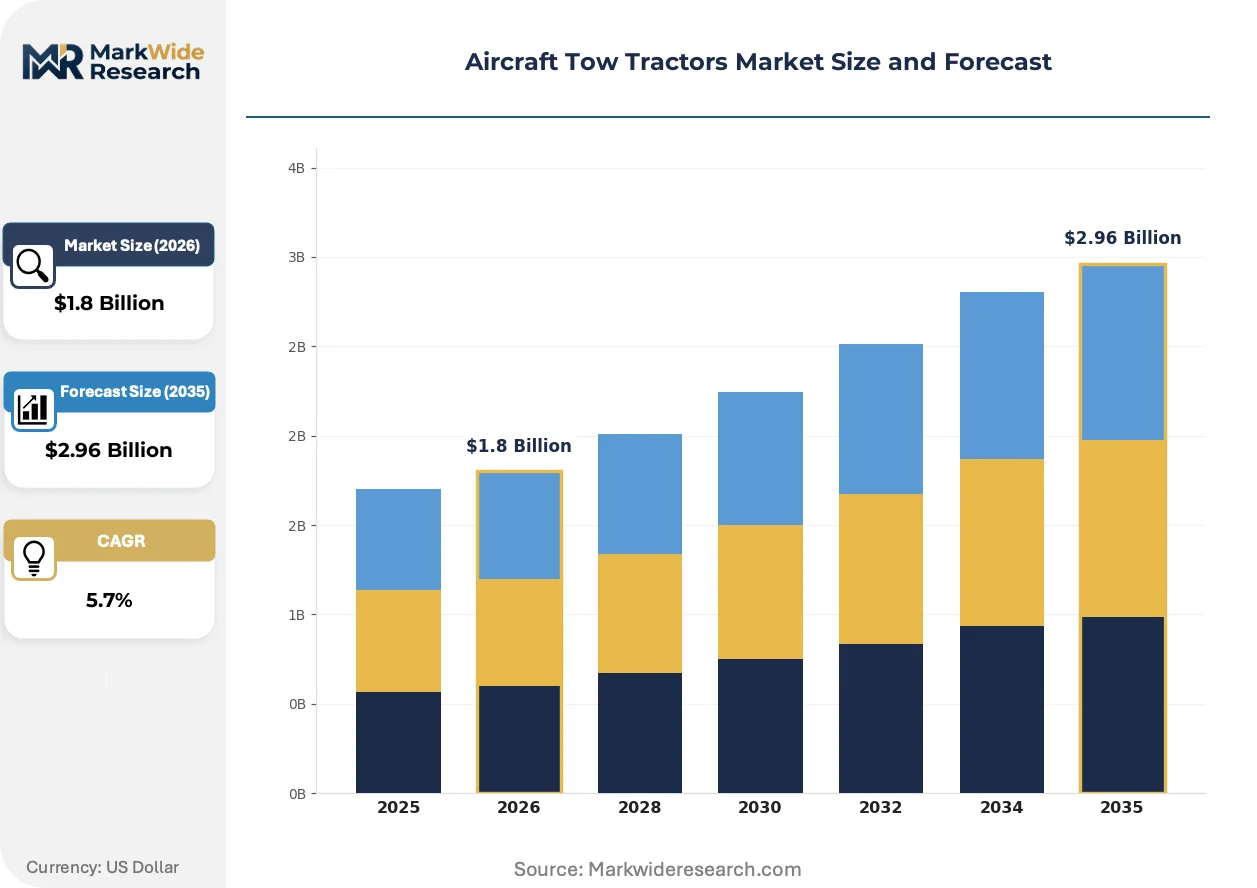
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Tow Tractors, Electric Tow Tractors, Towbarless Tractors, Hybrid Tow Tractors End User: Airports, Cargo Handlers, Airlines, Maintenance Organizations Deployment: On-Ground, Hangar Use, Remote Parking, Ramp Operations Power Source: Battery, Diesel, Electric, Hybrid |
| Companies Covered | TLD Group, JBT AeroTech, Textron GSE, Goldhofer AG, TREPEL Airport Equipment GmbH, Eagle Tugs, Mototok International GmbH, Kalmar Motor AB, MULAG Fahrzeugwerk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Tow Tractors Market Evolving Landscape
Powertrain electrification is fragmenting competitive advantage sources away from mechanical engineering toward battery thermal management and software-defined traction control. Three developments are compressing traditional differentiation models.
Battery pack architecture is modularizing around swappable sub-modules that enable rapid field replacement without removing the entire energy storage system. Ground handlers at high-utilization hubs in Germany and the Netherlands are adopting hot-swap protocols that eliminate charging downtime during peak turn windows. This design pattern is compressing tractor availability metrics from hours to minutes and repositioning service contracts around battery cycle management rather than drivetrain overhaul.
The EU F-Gas Regulation is prohibiting fluorinated greenhouse gases in ground support equipment manufacturing and mandating leak detection protocols for remaining refrigerant systems. This regulatory friction is accelerating phase-out timelines for diesel-hydraulic units that rely on conventional climate control compressors. Cargo operators at Amsterdam Schiphol and Brussels Airport are responding by front-loading electric fleet commitments to avoid stranded asset exposure.
Airport procurement teams are consolidating vendor relationships around integrated ground support equipment platforms rather than point-solution purchases. Single-source contracts spanning tow tractors, belt loaders, and pushback systems are displacing fragmented supplier bases at major European hubs. This consolidation pattern is most visible in Germany, where Frankfurt Airport's integrated fleet management tender specifications now require cross-platform telematics interoperability as a mandatory evaluation criterion.
Aircraft Tow Tractors Market Segmentation
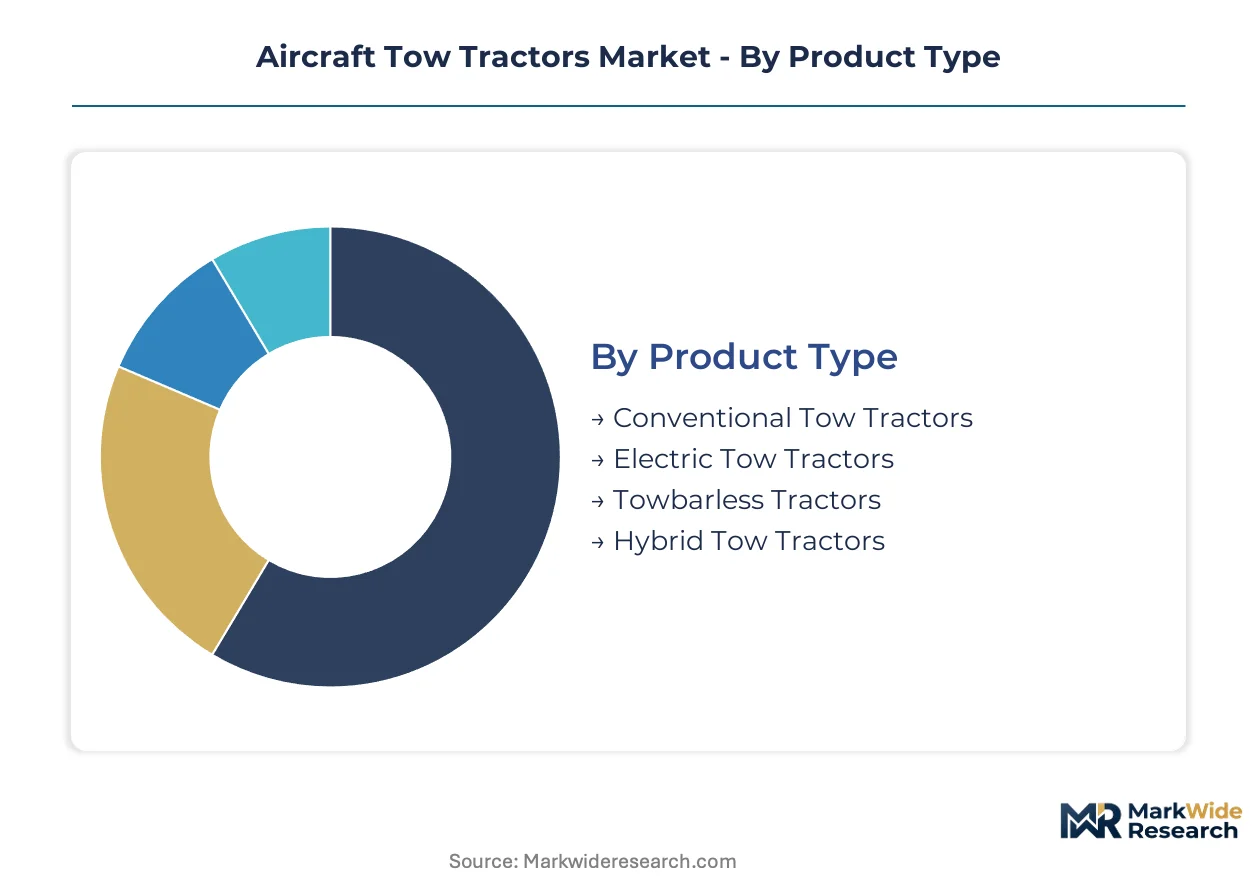
Powertrain electrification and towbarless handling capabilities are fragmenting procurement criteria across airport ground support equipment buyers. Fleet managers now weigh residual value risks against operational flexibility when segmenting tractor investments across hub operations.
Product Type:
Procurement teams prioritize drawbar pull capacity and turnaround speed when selecting between conventional and advanced tractor architectures.
- Electric Tow Tractors:Lithium-iron-phosphate battery packs deliver 600,000-pound drawbar pull for wide-body aircraft while eliminating scope-one emissions. Frankfurt and Munich airports are concentrating orders here to satisfy EU Green Deal compliance deadlines.
- Towbarless Tractors:Nose-gear engagement systems handle A380 and 777X fleets without towbar attachment delays, commanding procurement premiums at high-utilization European hubs where turn windows compress below 45 minutes.
- Conventional Tow Tractors:Diesel-hydrostatic drivetrains retain installed-base dominance at cargo aprons lacking high-capacity grid connections.
- Hybrid Tow Tractors:Dual-mode architectures bridge charging infrastructure gaps at remote parking positions and de-icing pads.
Volume sits with conventional units; growth tilts toward electric platforms.
End User:
Operational intensity and regulatory exposure shape fleet replacement cadences across buyer categories.
- Airports:Hub operators at Amsterdam Schiphol and Brussels Airport front-load zero-emission commitments to avoid F-Gas Regulation stranded asset exposure.
- Cargo Handlers:Third-party ground service providers at remote aprons favor diesel retention due to charging infrastructure deficits and 24-hour utilization cycles.
- Airlines:Network carriers consolidate tow tractor procurement with pushback system contracts under single-source integrated fleet management agreements.
- Maintenance Organizations:MRO facilities in Germany deploy towbarless units for hangar positioning of wide-body aircraft undergoing heavy checks.
Procurement volume concentrates with airports; cargo handlers represent the steepest expansion trajectory as e-commerce air freight volumes climb.
Deployment:
Physical location determines powertrain viability through grid access and utilization patterns.
- Ramp Operations:High-frequency gate positions at major European hubs drive battery-electric adoption where 350kW fast-charging infrastructure anchors tractor availability.
- On-Ground:Taxiway and apron maneuvers demand 20,000 to 600,000-pound drawbar pull range coverage across narrow-body and wide-body fleets.
- Hangar Use:Enclosed maintenance facilities prioritize zero-emission units to satisfy indoor air quality mandates under national occupational safety frameworks.
- Remote Parking:Peripheral aircraft stands lack electrical infrastructure, preserving diesel-hybrid demand for overflow capacity and seasonal peaks.
Utilization intensity peaks in ramp operations; remote parking sustains conventional powertrain demand.
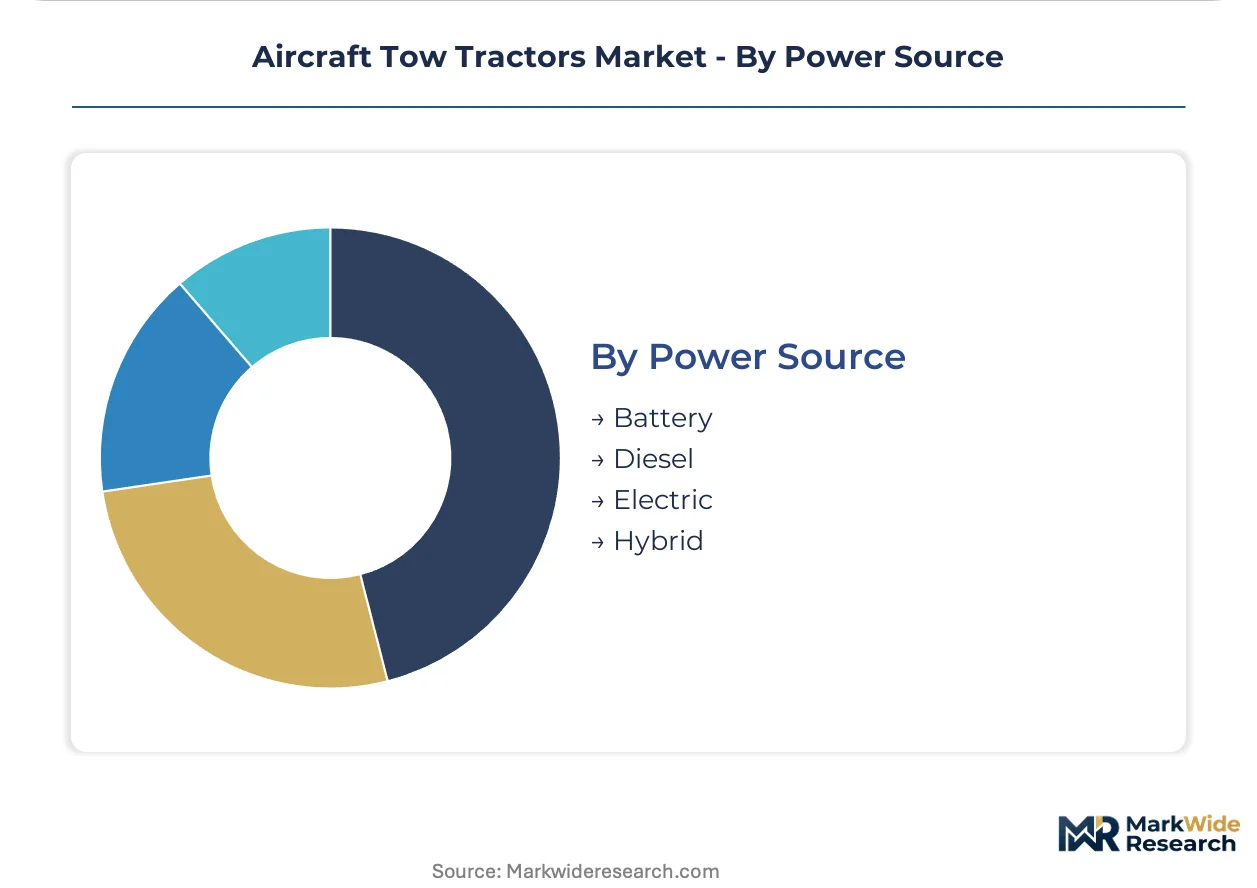
Power Source:
Energy storage chemistry and thermal management now differentiate competitive positioning more than mechanical engineering.
- Battery:Modular lithium-iron-phosphate architectures enable hot-swap protocols at Dutch and German hubs, compressing tractor downtime from hours to minutes during peak turn windows.
- Diesel:Conventional hydrostatic units face compressed residual values under F-Gas Regulation phase-out timelines, though cargo handlers retain deployed fleets where charging gaps persist.
- Electric:Grid-tied systems with regenerative braking capture energy during aircraft deceleration, improving cycle efficiency at high-utilization positions.
- Hybrid:Dual-power architectures bridge infrastructure deficits at de-icing pads and peripheral aprons while preserving operational flexibility.
Installed base tilts toward diesel; procurement momentum shifts to battery platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates tow tractor procurement through Frankfurt and Munich hub expansions, while regulatory pressure from Brussels reshapes fleet composition across Western Europe. Airports in the Netherlands and Belgium front-load electric commitments to avoid stranded diesel assets.
Germany
Frankfurt Airport's integrated fleet management tender and Munich's terminal expansion drive concentrated demand for towbarless electric units. The F-Gas Regulation accelerates diesel phase-out timelines for ground support equipment. Bavaria's manufacturing corridor around Munich anchors production of high-drawbar-pull battery systems for wide-body handling.
United States
Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor replacement cycles for aging diesel fleets at major connecting hubs. The FAA's AC 150/5220 specifications govern airside equipment safety standards and interface geometry requirements. Chicago O'Hare's cargo apron expansion preserves hybrid tractor demand where charging infrastructure remains incomplete.
Netherlands
Amsterdam Schiphol's binding net-zero commitment compresses procurement timelines for zero-emission ground support equipment. The EU Green Deal mandates leak detection protocols for remaining refrigerant systems in conventional units. Rotterdam The Hague Airport's regional cargo operations test swappable battery modules to eliminate charging downtime.
United Kingdom
Heathrow's fleet standardization program consolidates vendor relationships around integrated ground support equipment platforms. EASA CS-25 compatibility requirements extend to post-Brexit certification alignment for tow tractor nose-gear interfaces. London Stansted's low-cost carrier concentration drives demand for rapid-turnaround towbarless architectures.
India
Greenfield airport construction under the UDAN regional connectivity scheme opens procurement channels for electric ground support equipment. The country's national aviation regulator mandates safety compliance for airside vehicle operations. Maharashtra's Mumbai airport expansion and Karnataka's Bangalore cargo hub concentrate demand for 20,000 to 100,000-pound drawbar pull units.
Aircraft Tow Tractors Market Competitive Landscape
European producers anchor the premium electric tier; North American specialists hold installed-base positions in conventional diesel architectures. The vendor base separates into three strategic clusters: integrated platform providers, drivetrain component specialists, and regional fabrication houses serving cargo handler price sensitivity. Consolidation pressure intensifies as airports consolidate procurement around single-source fleet management contracts. Backward integration into battery thermal management and software-defined traction control distinguishes competitive positioning.
Within the integrated platform tier, TLD Group and JBT AeroTech exemplify contrasting geographic anchoring strategies. Textron GSE occupies a position calibrated to cargo handler fleets prioritizing acquisition cost over electrification timelines. TREPEL Airport Equipment GmbH and Goldhofer AG represent German engineering-intensive fabrication, while Mototok International GmbH anchors specialized towbarless innovation. Eagle Tugs and Kalmar Motor AB sit within the mid-tier segment serving regional airport operators with standardized mechanical architectures.
| Leading Market Players |
|---|
| TLD Group |
| JBT AeroTech |
| Textron GSE |
| Goldhofer AG |
| TREPEL Airport Equipment GmbH |
| Eagle Tugs |
| Mototok International GmbH |
| Kalmar Motor AB |
| MULAG Fahrzeugwerk |
| Others |
Value Network & Pricing Analysis
Binding net-zero procurement mandates from Frankfurt and Munich airports are forcing battery-electric platform commitments that compress diesel residual values and elevate lithium-iron-phosphate system premiums across European ground support equipment tenders.
Pricing Analysis
Volume concentrates in conventional diesel-hydrostatic units serving cargo aprons, while margin accrues to towbarless electric tractors handling wide-body aircraft at high-utilization hubs. Three-tier pricing structure across premium, standard, and economy levels separates nose-gear engagement systems with EASA CS-25 certification from modular battery architectures and legacy mechanical drivetrains. Cost compression in the standard tier is intensifying because cathode material processing bottlenecks in China are transmitting input volatility downstream. Cargo handlers at remote parking positions exhibit highest price sensitivity, while integrated fleet management contracts at major European hubs prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Refurbishment flows for end-of-life diesel tractors are creating secondary parts markets that compete with OEM service revenues, while remanufactured battery modules extend asset lifecycles at Dutch and German hubs. Manufacturing concentration centers on Germany, China, and the United States for complete vehicle assembly, with Bavaria's engineering corridor anchoring high-drawbar-pull electric system production. Lithium-iron-phosphate cathodes, permanent magnet motors, and hydrostatic transmission components constitute critical input dependencies. Single-source vulnerability in Chinese cathode processing creates supply chain risk exposure. Distribution runs through direct OEM channels for major hub operators and regional dealer networks serving price-sensitive cargo handlers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric tow tractors are displacing diesel-hydrostatic platforms as the dominant procurement specification, compressing the window for legacy asset repositioning and creating asymmetric opportunity across the vendor base.
For Market Incumbents: Lock in battery thermal management capabilities through captive supply of lithium-iron-phosphate modules or strategic partnerships with cell manufacturers. Secure EASA CS-25 certification pipelines for nose-gear engagement systems to defend against specialized towbarless entrants. Compress service contract pricing to retain cargo handler relationships threatened by Chinese electric platform imports. For New Entrants and Emerging Players: Capture modular battery swap protocols at Dutch and German hubs where hot-swap infrastructure eliminates charging downtime premiums. Target India's greenfield airport construction under UDAN regional connectivity schemes with standardized electric platforms priced below European OEM tiers. Lead with power-by-the-hour leasing structures that reduce capital barriers for regional cargo handlers. For Investors and Strategic Acquirers: The window for entry favors drivetrain component specialists with software-defined traction control capabilities over pure mechanical fabricators. Long-term viability rests on battery cycle management service revenues rather than hardware margins alone. Monitor F-Gas Regulation enforcement intensity and lithium supply contract pricing as inflection indicators for diesel asset stranding velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-iron-phosphate cell capacity from Chinese or South Korean producers for electric platform manufacturing. |
| EASA CS-25 Certification Investment | Validates nose-gear engagement geometry for A380 and 777X handling at European hub operators. |
| Telematics Platform Integration | Enables predictive maintenance contracts and cross-platform fleet management at consolidated procurement accounts. |
| Geographic Manufacturing Footprint | Positions assembly capacity near Bavaria's engineering corridor or India's UDAN airport development zones. |
| Swappable Battery Module Development | Supports hot-swap protocols that compress tractor downtime from hours to minutes at high-utilization positions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced against primary interviews with airport procurement directors, ground handler fleet managers, OEM platform engineers, and aftermarket service heads. EASA certification databases, FAA AC 150/5220 specifications, EU Green Deal implementation trackers, and airport capital expenditure disclosures provided secondary validation. Bottom-up unit demand modeling triangulated against top-down fleet replacement cycle analysis.
Segmentation granularity extended to powertrain architecture, towbar configuration, drawbar pull capacity tier, end-user category, and deployment location across the modeling period. CAGRs were derived from regression analysis of historical procurement patterns and regulatory timeline enforcement. Forecast inputs incorporated lithium supply contract pricing trajectories and charging infrastructure deployment schedules at major European hubs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to F-Gas Regulation phase-out acceleration and Chinese cathode export restriction policies. Forecasts reflect documented assumptions regarding battery energy density improvement curves and hub electrification capital commitment levels. Practitioners should monitor EASA CS-25 certification queue lengths and lithium hydroxide spot pricing for early signals of supply constraint or demand acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Airport Passenger Boarding Bridge Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Engineered Material Arresting System Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Global Aerospace Ground Handling System Market