
 Airport Services Market | 2026-2036
Airport Services Market Size, Share, and Industry Trends Forecast 2026-2036
Airport Services Market Intelligence
Demand from traditional airline customers is rotating toward a model where airport operators procure integrated service packages directly. This shift centralizes operational control and standardizes service levels across a facility. Fraport AG leverages its extensive experience managing complex international hubs. Vinci Airports differentiates its portfolio through an integrated concession, construction, and operations model. GMR Group sustains its market position by developing large-scale airport cities and ancillary service ecosystems in India.
Airport services encompass the array of ground-based activities required for aircraft turnaround, passenger processing, and cargo handling. These functions involve the precise coordination of ground support equipment, baggage handling systems, and refueling logistics to ensure operational safety and efficiency. The primary commercial purpose is to facilitate on-time performance for airlines and a seamless experience for travelers. Ground Handling and Fueling Services constitute the largest revenue streams, while technology-enabled Passenger Services, including automated check-in and baggage tracking, are expanding rapidly.
Regulatory frameworks from bodies like the US FAA and the European Union's aviation authorities establish stringent standards for ground safety and security. Global standards set by the International Civil Aviation Organization (ICAO) further govern operational protocols, influencing everything from security screening to aircraft maintenance procedures. Service providers must navigate these multi-layered compliance requirements to maintain market access. The key decision for operators now centers on whether to build proprietary digital platforms or partner with specialized tech firms to manage rising operational complexity.
Market Dynamics
The market's central dynamic is the consolidation of procurement power within airport operators, shifting away from airline-led contracting. This structural change centralizes operational control and standardizes service levels, driven by demands for efficiency and seamless passenger processing through technology.
Growth Catalysts
- Biometric Security Implementation:The deployment of facial recognition and automated gates, often aligned with security objectives from bodies like the US Transportation Security Administration, accelerates passenger throughput and creates demand for integrated technology services.
- E-commerce Freight Growth:Expedited handling requirements from freight forwarders to meet e-commerce delivery timelines are driving investment in advanced cargo logistics and ground support equipment, particularly at major cargo hubs.
- Middle East Airport Expansion:Large-scale development projects in the United Arab Emirates and Saudi Arabia are creating substantial greenfield opportunities for comprehensive ground handling, fueling, and passenger service contracts.
Market Restraints
- Labor Cost Volatility:High dependence on skilled and semi-skilled labor for ground handling and baggage services creates exposure to wage inflation and union-negotiated labor disputes, which consistently compresses service provider margins.
- High Capital Expenditure:The significant upfront investment required for specialized ground support equipment and advanced baggage handling systems acts as a primary barrier to entry for smaller, independent service providers.
- Multi-layered Compliance:Service providers must navigate complex operational standards from ICAO, the FAA, and European aviation authorities, which increases compliance costs and creates operational friction across different jurisdictions.
Strategic Opportunities
- Digital Twin Integration:Combining IoT sensors on ground support equipment with airport operational databases offers a new service layer for predictive maintenance, asset tracking, and real-time turnaround management for airline customers.
- Sustainable Aviation Fuel Logistics:Developing specialized infrastructure and handling procedures for Sustainable Aviation Fuel (SAF) presents a first-mover advantage as regulators push for decarbonization under frameworks like the EU's ReFuelEU Aviation initiative.
- African Aviation Modernization:Airport modernization programs across countries such as Nigeria and Ethiopia present a significant opportunity for integrated service providers to establish long-term concession agreements in an underpenetrated market.
Industry Challenges
- Cybersecurity Vulnerabilities:The integration of IT systems for passenger processing, baggage tracking, and flight operations creates new attack surfaces, demanding constant investment in cybersecurity to prevent operational disruptions.
- Skilled Labor Shortages:A persistent shortage of certified aircraft mechanics and ground crew personnel, particularly in rapidly expanding markets, constrains service capacity and drives up recruitment costs for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airport Services Market |
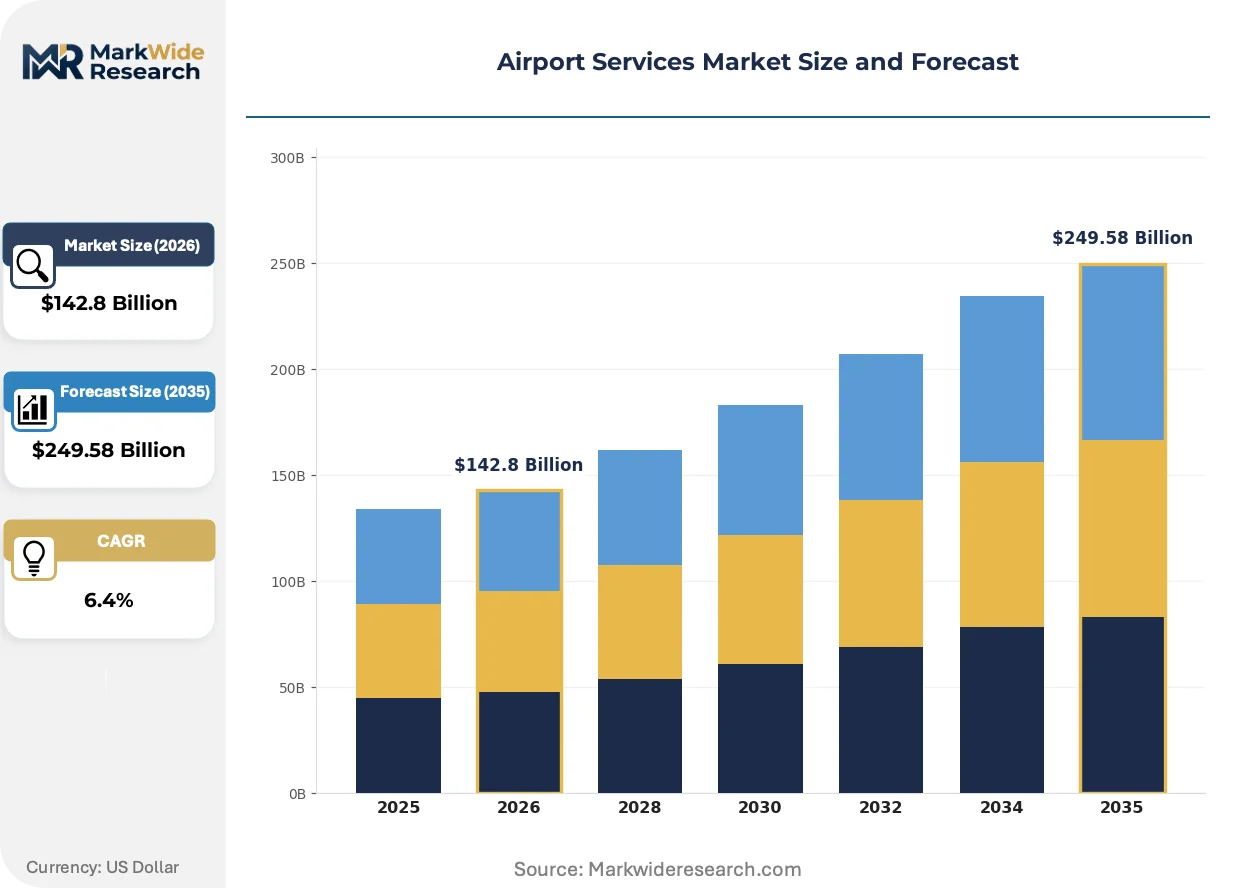
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $249.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ground Handling, Security Services, Passenger Services, Fueling Services Customer Type: Airlines, Airports, Freight Forwarders, Government Agencies Technology: Automated Check-in, Baggage Tracking, Security Scanning, Wi-Fi Services Delivery Model: On-site Services, Contract Services, Outsourced Solutions, In-house Operations |
| Companies Covered | Grupo Aeroportuario del Sureste, Fraport AG, Aena SME, Shanghai Airport, Vinci Airports, Groupe ADP, GMR Group, Zurich Airport, Grupo Aeroportuario del Pacífico, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airport Services Market Strategic Shifts & Innovations
Digitalization is transforming the operational model for airport services by unbundling monolithic service contracts. This enables a more modular, data-driven approach to managing aircraft turnaround, passenger flow, and cargo logistics.
Autonomous Ground Support Equipment, including robotic baggage tractors and aircraft tugs, automates repetitive tarmac activities. Major hub airports in Europe and Asia are leading pilot programs and initial deployments to address labor shortages. The technology is decomposing the traditional ground crew function into discrete, automated tasks managed by a central command system.
New regulations from the European Union Aviation Safety Agency are mandating enhanced cybersecurity for all critical airport systems. This requires service providers to implement rigorous security protocols and demonstrate compliance to maintain operating licenses. Ground handling and air traffic management services are most impacted, facing increased auditing and investment cycles for security.
Airlines are increasingly outsourcing the management of ground services to the airport operator, moving from direct contracts with multiple providers. This shift consolidates decision-making and lets airports enforce uniform service levels and facility-wide technology platforms. The trend is most prominent at large hubs in the Middle East and Europe, where complex operations benefit from centralized control.
Airport Services Market Segmentation
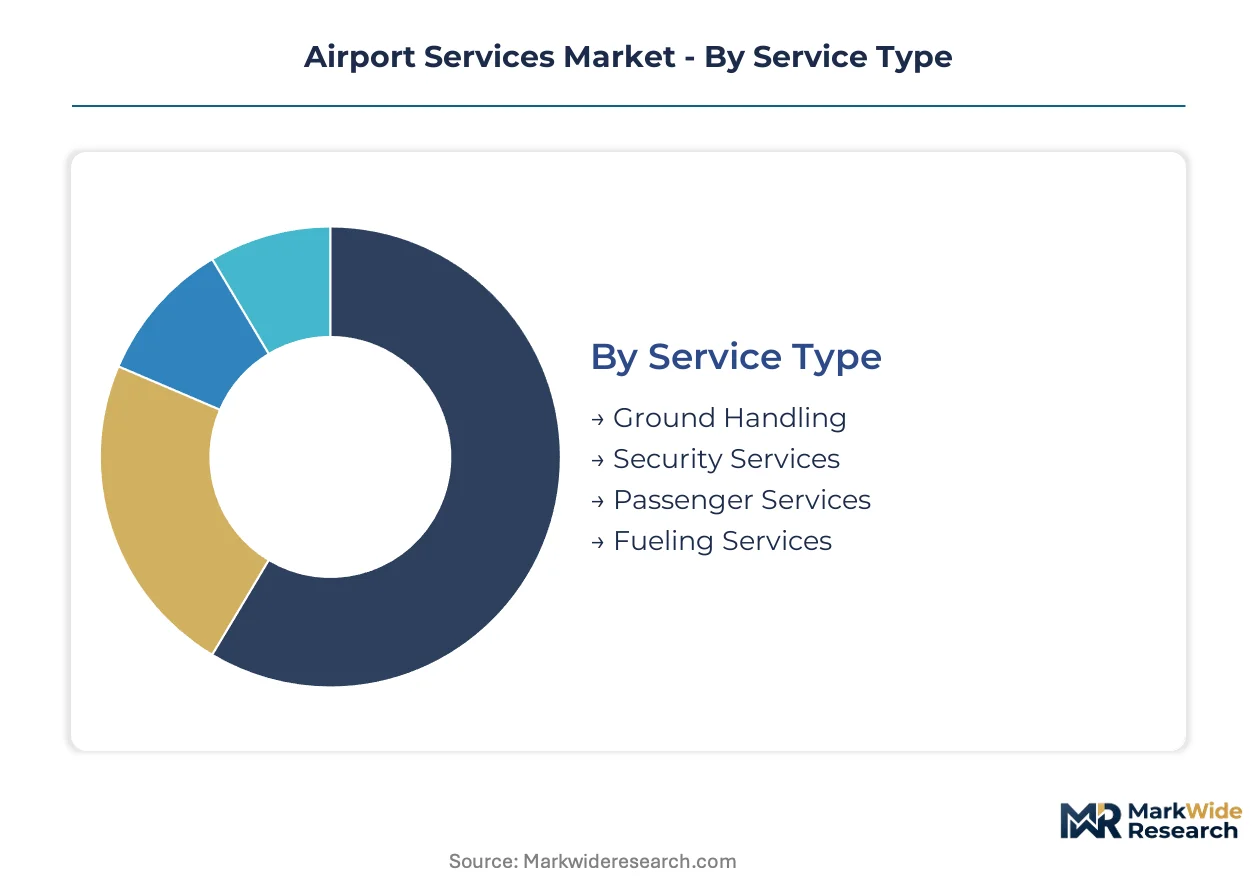
The airport services market segments across distinct operational functions, customer profiles, technological deployments, and delivery models. Understanding these delineations helps stakeholders identify specific growth vectors and address unique operational challenges within the aviation ecosystem.
Service Type:
Service providers in this category face substitution pressure from in-house airline operations or direct airport procurement models, especially for routine tasks.
- Ground Handling:This segment encompasses aircraft marshaling, baggage loading/unloading, cargo handling, and passenger boarding/deplaning. Precise coordination of ground support equipment and personnel ensures timely aircraft turnaround, with demand concentrating at major international hubs like Dubai International Airport due to high traffic volumes.
- Passenger Services:This segment includes check-in, boarding gate management, lounge access, and special assistance for travelers. Rapid expansion of automated check-in and biometric processing at European airports like Amsterdam Schiphol is driving demand for integrated technology solutions.
- Security Services:This segment involves passenger and baggage screening, perimeter security, and airside access control. Regulatory frameworks from bodies like the US Transportation Security Administration dictate operational protocols, creating a compliance-driven market.
- Fueling Services:This segment covers the storage, transport, and delivery of aviation fuel to aircraft. Specialized infrastructure and logistics are critical for maintaining safety standards and ensuring consistent supply across airport facilities.
Ground Handling retains volume leadership; Passenger Services holds the steepest expansion curve.
Customer Type:
Customer type segmentation reveals distinct procurement patterns and service level expectations across the aviation value chain.
- Airports:These entities increasingly centralize procurement for integrated service packages, shifting away from airline-led contracting. Major airport development projects in Saudi Arabia are driving demand for comprehensive service contracts.
- Freight Forwarders:These customers require expedited cargo handling and ground support to meet e-commerce fulfillment timelines. Demand concentrates at cargo hubs like Memphis International Airport, driven by global trade growth.
- Airlines:Traditional customers for various ground services, airlines increasingly outsource these functions to airport operators to streamline their own operations. Legacy carriers often maintain some in-house capabilities for strategic control.
- Government Agencies:These agencies often contract for specialized services like security screening, border control support, or emergency response logistics. Compliance with national security mandates is a primary driver for these contracts.
Airports are the largest customer segment by value; Freight Forwarders are exhibiting the strongest growth in demand.
Technology:
The application of technology in airport services streamlines operations and enhances the passenger experience.
- Automated Check-in:This technology includes self-service kiosks and mobile applications for passenger processing. Biometric security implementation, particularly facial recognition at airports in the United Arab Emirates, accelerates throughput and reduces manual intervention.
- Baggage Tracking:Systems utilizing RFID or barcode scanning provide real-time location data for luggage throughout its journey. Rapid expansion of these systems at major European hubs enhances operational efficiency and reduces mishandling incidents.
- Security Scanning:Advanced imaging technologies and explosive detection systems enhance threat detection capabilities. Regulatory mandates from the US FAA drive investment in next-generation screening equipment at all commercial airports.
- Wi-Fi Services:Providing internet connectivity to passengers within airport terminals. This service enhances the traveler experience and generates ancillary revenue streams for airport operators.
Security Scanning accounts for the largest technology investment; Automated Check-in is experiencing the fastest adoption rate.
Delivery Model:
Delivery models reflect the operational control and resource allocation strategies adopted by service providers and airport authorities.
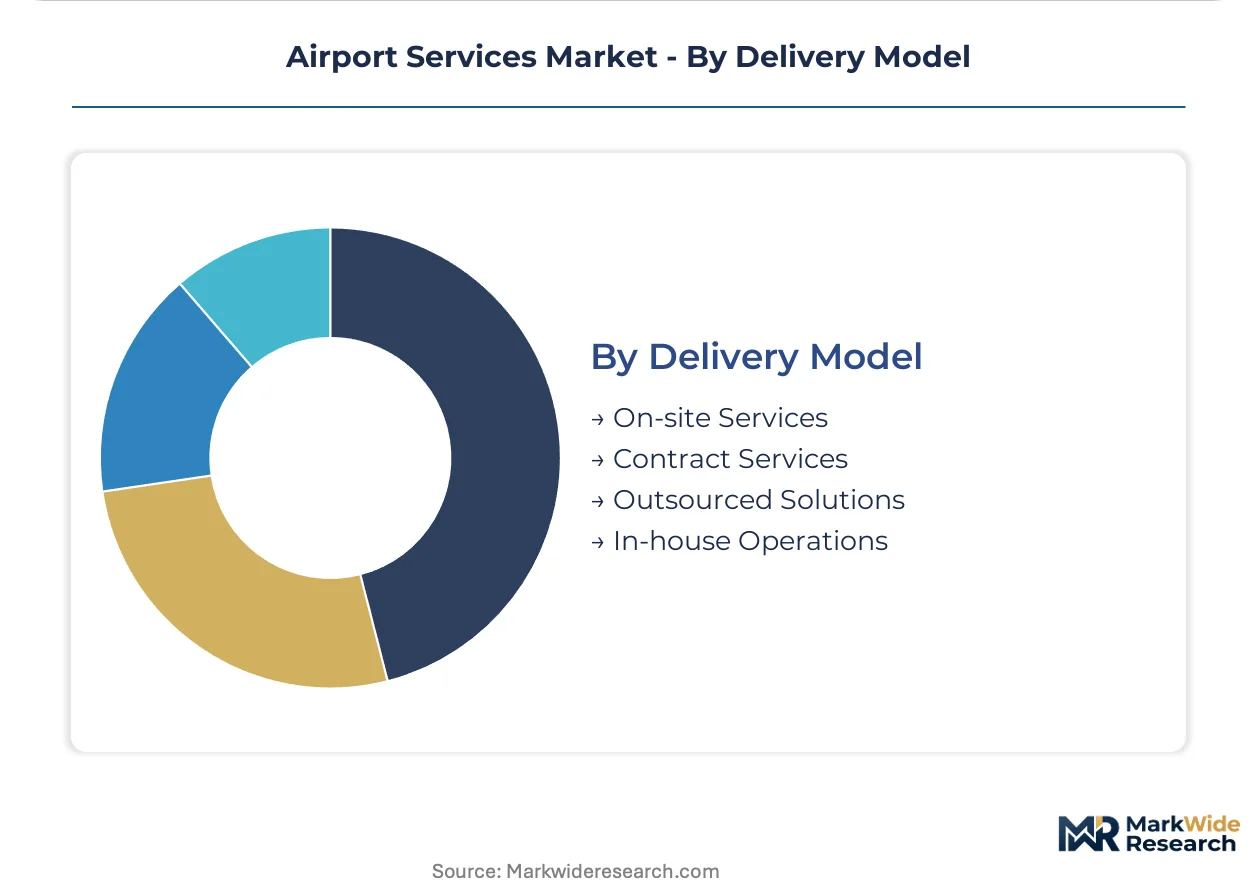
- Contract Services:External providers deliver specific services under a contractual agreement with an airline or airport. This model allows for specialized expertise and scalability, common in ground handling at large international airports.
- Outsourced Solutions:Comprehensive service packages are managed by third-party specialists, integrating multiple functions. This model centralizes operational control and standardizes service levels, popular at major hubs in the Middle East.
- On-site Services:Service personnel are stationed directly at the airport facility to provide immediate support. This ensures rapid response times for critical operations like aircraft maintenance or emergency services.
- In-house Operations:Airport authorities or airlines directly employ staff and manage assets for certain services. This model offers greater control over service quality and cost, often seen in smaller regional airports.
Outsourced Solutions command the highest market share; Contract Services are demonstrating sustained expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global network of interconnected airport hubs underwrites the diverse regional roles within the Airport Services Market. These critical aviation gateways facilitate international trade, tourism, and business travel, driving specialized service demand. Strategic investments in infrastructure and technology are differentiating regional market dynamics.
United Arab Emirates
The United Arab Emirates drives significant demand through ambitious airport expansion projects. ICAO standards influence operational protocols for ground handling and security. Dubai International Airport and Abu Dhabi International Airport are central to comprehensive service contracts.
Saudi Arabia
Saudi Arabia's Vision 2030 initiatives are fueling substantial greenfield opportunities for airport services. The General Authority of Civil Aviation (GACA) mandates stringent safety and security standards. New airport cities like NEOM and expansion in Riyadh are attracting major investments.
United States
United States demand stems from extensive domestic travel and robust e-commerce freight volumes. The US FAA and Transportation Security Administration (TSA) establish stringent safety and security protocols. Major cargo hubs like Memphis International Airport drive investment in advanced logistics.
Germany
Germany's central European location generates consistent demand for advanced airport services. European Union Aviation Safety Agency (EASA) regulations mandate enhanced cybersecurity for critical airport systems. Frankfurt Airport and Munich Airport lead pilot programs for autonomous ground support equipment.
India
India's rapid economic growth underwrites demand for large-scale airport cities and ancillary services. The Directorate General of Civil Aviation (DGCA) regulates operational safety and security for all airport functions. Major metropolitan airports in Delhi and Mumbai develop comprehensive service ecosystems.
Airport Services Market Key Industry Players
Listed leaders compete with private specialists across operational efficiency and service integration. The market exhibits a tiered structure, with large airport operators and global service providers dominating. Archetypes include integrated concessionaires, dedicated ground handling specialists, and technology solution providers. Dominant competitive moves involve portfolio diversification and strategic partnerships for digital platform development.
On the integrated concession and management vector, Fraport AG exemplifies operators managing complex international hubs, leveraging extensive experience. Vinci Airports, a French company, differentiates its portfolio through an integrated concession, construction, and operations model, emphasizing long-term asset control. India-based GMR Group sustains its market position by developing large-scale airport cities and ancillary service ecosystems, particularly in emerging economies. These entities collectively represent the market's shift towards comprehensive service packages and centralized operational control, impacting procurement patterns across the industry.
| Leading Market Players |
|---|
| Grupo Aeroportuario del Sureste |
| Fraport AG |
| Aena SME |
| Shanghai Airport |
| Vinci Airports |
| Groupe ADP |
| GMR Group |
| Zurich Airport |
| Grupo Aeroportuario del Pacífico |
| Others |
Cost & Logistics Intelligence
ICAO standards gate supply qualification for airport services and influence price differentiation for compliance-driven contracts. Stringent safety and security protocols impact service provider costs and market access.
Pricing Analysis
Volume-based contract pricing dominates the airport services market, particularly for ground handling and fueling services. Price differentiation stems from service level agreements (SLAs) and the integration of technology solutions like automated check-in. Pricing softness stems from intense competition among service providers, particularly for standardized ground handling tasks. Airport operators, as the largest customer segment, exhibit the least price sensitivity, while freight forwarders are highly price-sensitive.
Supply Chain Analysis
Inbound logistics costs for specialized ground support equipment, such as tugs and baggage systems, significantly impact service provider margins. Supply concentration for advanced ground support equipment centers in Germany, Japan, and the United States. Key raw material dependencies include specialized alloys for equipment manufacturing and petroleum for fueling services. Single-source vulnerability for proprietary software in automated passenger processing systems presents a structural risk.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airport services market presents a fragmentation opportunity as the shift towards integrated service packages creates specialized niches. Demand for technology-enabled passenger services drives new solution providers.
For Market Incumbents: Fortify operational efficiency through digital twin integration for predictive maintenance, countering labor cost volatility. Diversify service portfolios with Sustainable Aviation Fuel (SAF) logistics to mitigate future regulatory shifts like the EU's ReFuelEU Aviation initiative. Invest in cybersecurity protocols to protect integrated IT systems from increasing vulnerabilities.
For New Entrants and Emerging Players: Anchor in technology-enabled passenger services, particularly automated check-in and biometric security solutions, to address rapid adoption rates. Target underpenetrated African aviation modernization programs, like those in Nigeria and Ethiopia, for long-term concession agreements. Go-to-market strategies should emphasize modular, data-driven solutions that integrate with existing airport operational databases.
For Investors and Strategic Acquirers: European Union Aviation Safety Agency (EASA) mandates for enhanced cybersecurity reshape the acquisition landscape, favoring tech specialists. Long-term viability hinges on acquiring firms with proprietary digital platforms and strong compliance track records. Target archetype includes specialized tech firms offering integrated security and automation solutions. Watch for increased investment cycles in cybersecurity infrastructure as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Integration | Optimizes ground support equipment utilization and enables predictive maintenance for airport operators. |
| Sustainable Aviation Fuel Logistics | Positions providers for decarbonization mandates under frameworks like EU's ReFuelEU Aviation. |
| Biometric Security Deployment | Accelerates passenger throughput and enhances security screening efficiency for airports. |
| Autonomous Ground Support Equipment Pilots | Addresses labor shortages and automates repetitive tarmac activities at major hubs. |
| Cybersecurity Protocol Enhancement | Ensures compliance with EASA regulations and protects critical airport operational systems. |
Research Approach
Initial hypotheses were tested against primary input from airport operators, airline procurement managers, freight forwarder logistics heads, and ground handling service executives, then refined. Insights from these interviews were combined with secondary validation from ICAO reports, US FAA regulations, and European Union Aviation Safety Agency (EASA) publications. Bottom-up and top-down triangulation ensured data consistency.
Variance decomposition isolated key drivers like biometric security and e-commerce freight growth across the analysis window. The analytical framework modeled airport services by service type, customer type, technology, and delivery model. CAGRs were derived from historical trends and projected market dynamics, with inputs including air traffic volumes and infrastructure capital expenditure.
Material uncertainties — including geopolitical shifts and unforeseen technological disruptions — sit outside the modeled envelope. Forecasts reflect assumptions documented regarding regulatory stability and economic growth. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Airfield Ground Lighting (AGL) Systems Market