
 Europe, Middle-East and Africa Aviation Infrastructure Market | 2026-2036
Europe, Middle-East and Africa Aviation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Europe, Middle-East and Africa Aviation Infrastructure Market Insights
Gulf sovereign developers are expanding airport capacity ahead of scheduled mega-events and hub repositioning. VINCI Airports leverages its concession portfolio across Portugal, France, and Santiago de Chile to sustain long-dated revenue streams from terminal operations. Bechtel Corporation anchors its regional presence through engineering-procurement-construction contracts for greenfield airfields in Saudi Arabia. Skanska AB competes on Nordic sustainability credentials, differentiating its bids with embodied-carbon tracking for concrete runway pours.
Europe, Middle-East and Africa aviation infrastructure encompasses the physical systems and engineered assets that enable fixed-wing and rotary aircraft movements, including precision-graded runways with PCN ratings above 60, passenger terminal complexes with IATA Level C security screening, and air traffic control centers processing CNS/ATM data streams. Its primary purpose is maintaining safe aircraft separation while maximizing passenger throughput per gate hour. Terminal construction claims the largest share of current capital deployment across the region, driven by passenger experience upgrades and retail monetization requirements. Air Traffic Control technology represents the fastest-expanding technology segment, as ANSPs replace radar-centric architectures with satellite-based surveillance. Maintenance services command durable margin pools because airside assets require continuous pavement condition indexing and electrical system recertification under operational continuity rules.
EASA airworthiness directives and EU Green Deal emissions benchmarks shape material specifications and electrification timelines for ground support fleets. The UAE's General Civil Aviation Authority and Saudi Arabia's GACA enforce parallel certification standards for new airfield construction, creating overlapping compliance obligations for contractors operating across North Africa and the Levant. Stakeholders must monitor which regulatory jurisdiction claims primacy on cross-border hub projects before committing to design standards or equipment procurement.
Market Dynamics
EASA certification mandates for airfield lighting retrofits and the EU Green Deal's ground fleet electrification deadlines are compressing contractor procurement cycles across Europe, Middle-East and Africa. Terminal developers now bundle sustainability credentials into bid evaluations, favoring contractors with embodied-carbon tracking capabilities.
Growth Catalysts
- Biometric Passenger Processing:Dubai and Abu Dhabi terminal expansions mandate smart gate systems that integrate facial recognition with boarding pass validation. ANSPs in Saudi Arabia and the UAE are accelerating procurement ahead of passenger volume doubling.
- EASA Airworthiness Directives:Mandatory LED airfield lighting upgrades across EU member states are forcing pavement reconstruction contracts that bundle electrical infrastructure replacement. This creates bundled procurement opportunities for integrated airside contractors.
- Hub Repositioning:Gulf sovereign developers are commissioning greenfield airfields ahead of scheduled mega-events, with Saudi Arabia's GACA streamlining certification timelines for strategic projects. This concentrates demand in the Arabian Peninsula corridor.
Market Restraints
- Specialized Asphalt Supply Concentration:Polymer-modified binder formulations for PCN 60+ runways source from a limited base of European refiners. Disruptions at Rotterdam or Antwerp terminals propagate directly into EMEA contractor scheduling.
- Dual Certification Overlap:Cross-border hub projects spanning North Africa and the Levant face overlapping EASA, UAE GCAA, and Saudi GACA standards. Design freeze delays emerge when jurisdictions dispute primacy on specific airside systems.
- Skilled Pavement Engineering Scarcity:Qualified firms capable of precision-graded runway construction with continuous friction testing number fewer than twelve across the entire region. This concentrates pricing power with incumbent specialists.
Strategic Opportunities
- Satellite-Based Surveillance Convergence:ANSP replacement of radar-centric architectures with CNS/ATM data streams creates integration contracts for ground infrastructure providers. European ANSPs are piloting these systems at secondary airports first.
- Egypt and Morocco Greenfield Development:Underpenetrated North African markets are issuing concessions for secondary city airports. These projects carry lower certification stringency than Gulf hubs, enabling faster contractor entry.
- EU Green Deal Ground Fleet Electrification:Mandates for zero-emission ground support equipment at EU-27 airports by 2030 are reshaping apron infrastructure specifications. Charging infrastructure and electrical distribution retrofits represent new revenue pools.
Industry Challenges
- Air Traffic Control Integration Complexity:Legacy radar installations must operate in parallel with satellite-based surveillance during multi-year transition windows. ANSPs demand contractors with dual-system commissioning experience that remains scarce.
- Pavement Condition Indexing Talent Gap:Continuous airside asset monitoring requires certified inspectors capable of PCI scoring and electrical recertification under operational continuity rules. Training pipelines have not kept pace with regional expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe, Middle-East and Africa Aviation Infrastructure Market |
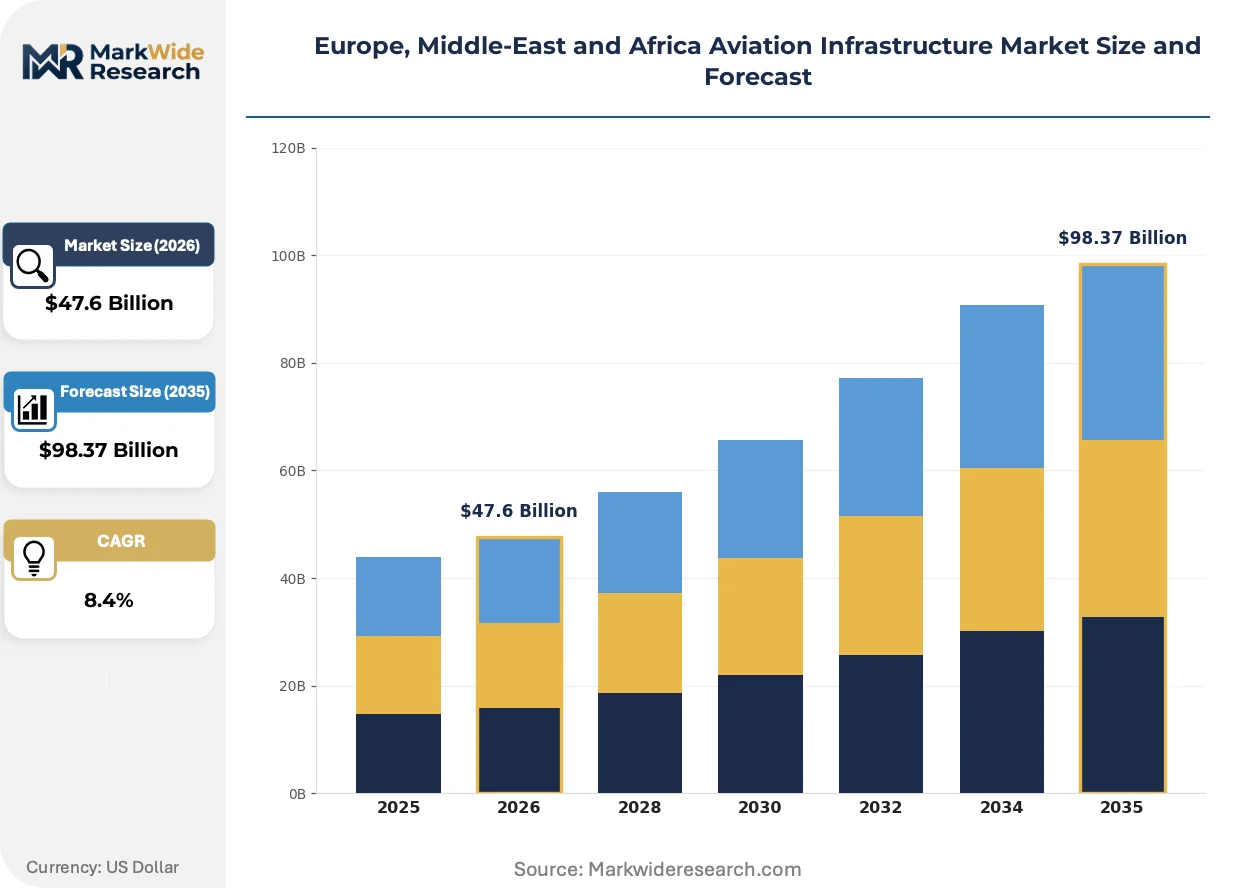
| Market Size in 2026 | $47.6 Billion |
| Market Size in 2035 | $98.37 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Runways, Terminals, Hangars, Taxiways Technology: Air Traffic Control, Ground Support Equipment, Security Systems, Lighting Solutions End User: Airlines, Governments, Airports, Contractors Service Type: Maintenance, Construction, Consulting, Design |
| Companies Covered | Bechtel Corporation, VINCI Airports, Eiffage S.A., Skanska AB, Bouygues Construction S.A., STRABAG SE, Balfour Beatty Plc, Royal BAM Group nv, Impresa Pizzarotti & C. S.p.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe, Middle-East and Africa Aviation Infrastructure Market Trends and Innovations
Digital twin modeling and predictive maintenance algorithms are displacing scheduled inspection regimes across EMEA airport portfolios. These technologies compress maintenance intervals while extending asset lifecycles.
Computer vision systems paired with IoT sensor networks are automating runway foreign object debris detection. Major hub operators in the UAE and Saudi Arabia are deploying these systems during overnight curfew windows. The technology is automating manual inspection rounds that previously required dedicated airside vehicles and crews, reducing operational continuity risks.
The EU Green Deal's emissions benchmarks for ground operations are mandating electric ground support equipment procurement at EU-27 airports. EASA is developing certification pathways for high-voltage charging infrastructure that must coexist with legacy fueling systems. Terminal operators in France, Germany, and the Netherlands are prioritizing contractors with demonstrated electrical infrastructure integration experience.
Hub operators are unbundling long-term maintenance contracts from initial construction awards. Dubai and Abu Dhabi airports now separate pavement warranty periods from electrical system service agreements, enabling specialized firms to compete on lifecycle cost rather than upfront capital. This shift is most visible in Gulf markets where sovereign developers seek operational expenditure transparency for concession refinancing.
Europe, Middle-East and Africa Aviation Infrastructure Market Segmentation
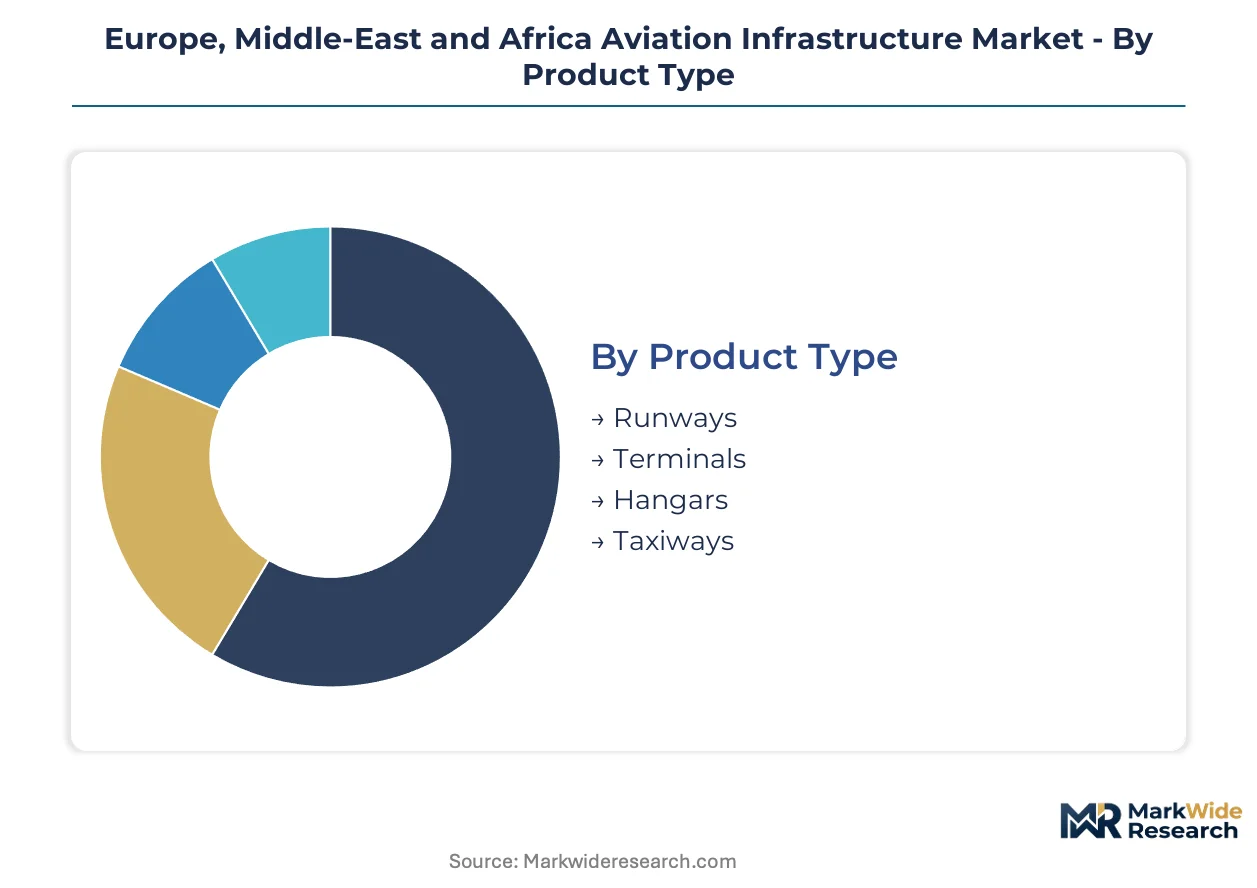
Segmentation reveals how certification burdens concentrate across distinct asset classes and stakeholder groups in the EMEA aviation infrastructure market. Each category carries unique compliance obligations that reshape contractor capabilities and procurement timelines.
Product Type:
EASA airworthiness directives and UAE GCAA certification standards impose divergent material specifications across physical infrastructure segments, with PCN ratings and electrical system integration demanding specialized contractor qualifications.
- Runways:Precision-graded asphalt surfaces with PCN 60+ ratings require polymer-modified binders and continuous friction testing. Demand concentrates in Saudi Arabia and the UAE where GACA and GCAA mandates for new greenfield airfields are compressing procurement cycles ahead of mega-events.
- Terminals:IATA Level C security screening complexes bundle biometric passenger processing with retail monetization infrastructure. Dubai and Abu Dhabi expansions mandate smart gate systems that integrate facial recognition, driving specification complexity for electrical and IT contractors.
- Hangars:Aircraft maintenance bays with fire suppression and ventilation systems face overlapping EASA and national building codes.
- Taxiways:Connecting pavement networks require coordinated electrical integration with runway lighting circuits under operational continuity rules.
Leading the category by volume: Terminals. Growing fastest: Runways.
Technology:
Technology segments split between operational continuity systems with legacy radar dependencies and emerging satellite architectures with distinct commissioning requirements.
- Air Traffic Control:CNS/ATM data stream infrastructure replaces radar-centric surveillance with satellite-based positioning. European ANSPs pilot these systems at secondary airports first, creating integration contracts for contractors with dual-system commissioning experience that remains scarce across the region.
- Ground Support Equipment:Electric fleet mandates under the EU Green Deal require high-voltage charging infrastructure coexisting with legacy fueling systems. France, Germany, and Netherlands airports prioritize contractors with demonstrated electrical integration capabilities for apron retrofit programs.
- Security Systems:Biometric processing and automated screening equipment must satisfy both EASA and national aviation authority standards.
- Lighting Solutions:LED airfield lighting retrofits bundle pavement reconstruction with electrical infrastructure replacement.
Dominating procurement value: Air Traffic Control. Expanding most quickly: Ground Support Equipment.
End User:
End user categories reflect diverging procurement authority structures, from sovereign concession holders to fragmented contractor ecosystems.
- Airlines:Fleet operators influence terminal gate configurations and ground handling specifications through long-term use agreements. Hub carriers in the UAE and Saudi Arabia are embedding sustainability requirements into apron access contracts ahead of fleet electrification timelines.
- Governments:Sovereign developers in the Gulf commission greenfield airfields through centralized procurement with streamlined GACA certification timelines.
- Airports:Terminal operators unbundle maintenance contracts from construction awards to improve operational expenditure transparency.
- Contractors:Engineering-procurement-construction firms face overlapping EASA, GCAA, and GACA obligations on cross-border projects.
Controlling capital deployment: Governments. Gaining procurement sophistication fastest: Airlines.
Service Type:
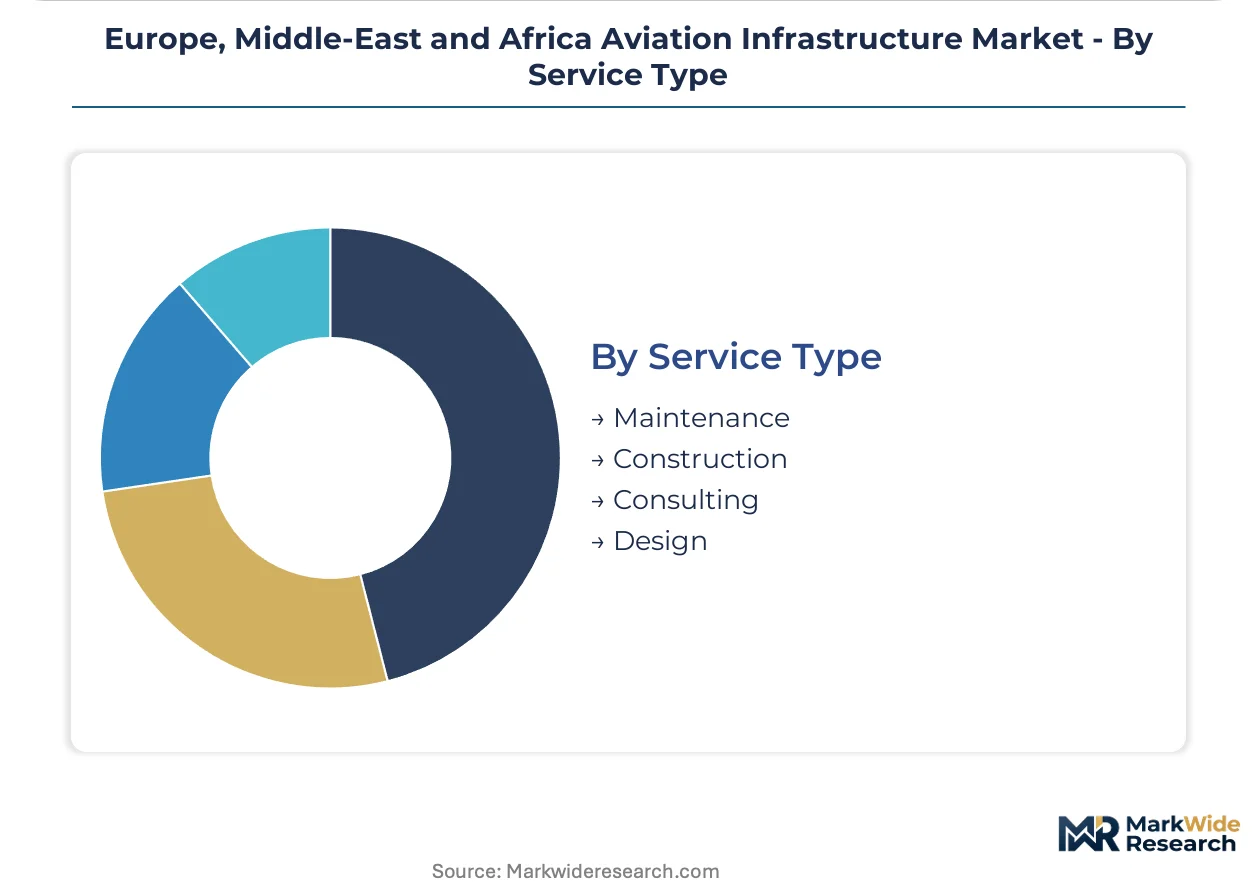
Service segments align with asset lifecycle stages, from initial design through continuous operational monitoring.
- Maintenance:Continuous pavement condition indexing and electrical recertification command durable margin pools under operational continuity rules. Airside assets require certified inspectors capable of PCI scoring, yet training pipelines have not kept pace with regional expansion.
- Construction:Greenfield and retrofit projects bundle civil works with technology integration under fixed-price risk allocation.
- Consulting:Regulatory navigation and certification pathway design support cross-border hub development.
- Design:Digital twin modeling and predictive maintenance algorithms are displacing scheduled inspection regimes across airport portfolios.
Capturing recurring revenue: Maintenance. Adopting predictive capabilities fastest: Design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer-modified asphalt refineries in Rotterdam and Antwerp supply critical binder formulations for PCN 60+ runway specifications across the EMEA corridor. These feedstock nodes anchor contractor procurement timelines for precision-graded pavement projects from the Arabian Peninsula to North Africa.
United Arab Emirates
Dubai and Abu Dhabi sovereign developers commission terminal expansions with biometric passenger processing mandates ahead of forecast passenger volume doubling. The UAE's General Civil Aviation Authority enforces streamlined certification timelines for strategic airfield projects. Dubai International Airport and Abu Dhabi Zayed International Airport anchor the Arabian Peninsula's hub repositioning investments.
Saudi Arabia
GACA greenfield airfield programs concentrate demand for precision-graded runways with PCN ratings above 60 ahead of scheduled mega-events. The Saudi General Authority of Civil Aviation compresses procurement cycles for strategic corridor projects. NEOM and Riyadh anchor the kingdom's aviation infrastructure expansion with sovereign-backed concession structures.
Germany
EASA LED airfield lighting retrofits force bundled pavement reconstruction contracts across EU member states. The EU Green Deal's ground fleet electrification deadlines reshape apron infrastructure specifications at Frankfurt and Munich hubs. Baden-Württemberg and Bavaria host specialized electrical contractors with demonstrated high-voltage integration capabilities.
France
VINCI Airports leverages its concession portfolio across Portugal and domestic terminals to sustain long-dated revenue streams from terminal operations. EASA certification mandates for airfield lighting retrofits compress contractor procurement cycles at Charles de Gaulle and Orly. The Île-de-France region concentrates design-engineering firms with embodied-carbon tracking capabilities for bid evaluations.
Egypt
Underpenetrated North African markets issue concessions for secondary city airports with lower certification stringency than Gulf hubs. The country's national aviation authority enables faster contractor entry for greenfield development outside Cairo's saturated corridor. New administrative capital and Red Sea coastal zones attract apron infrastructure investments with reduced regulatory overlap.
Europe, Middle-East and Africa Aviation Infrastructure Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue satellite-based surveillance integration and predictive maintenance algorithms. The vendor base stratifies across engineering-procurement-construction conglomerates, airport concession operators, and specialized pavement engineering boutiques. Two dominant archetypes prevail: sovereign-backed Gulf developers with streamlined certification timelines, and European contractors with EU Green Deal compliance credentials. Competitive moves concentrate on M&A for electrical infrastructure capabilities and strategic partnerships for CNS/ATM system integration.
Within the engineering-procurement-construction tier, Bechtel Corporation anchors regional presence through greenfield airfield contracts, VINCI Airports exemplifies concession-based revenue sustainability across multiple jurisdictions, and Skanska AB occupies a position differentiated by Nordic sustainability credentials and embodied-carbon tracking capabilities for concrete runway construction.
| Leading Market Players |
|---|
| Bechtel Corporation |
| VINCI Airports |
| Eiffage S.A. |
| Skanska AB |
| Bouygues Construction S.A. |
| STRABAG SE |
| Balfour Beatty Plc |
| Royal BAM Group nv |
| Impresa Pizzarotti & C. S.p.A. |
| Others |
Pricing and Supply Chain Analysis
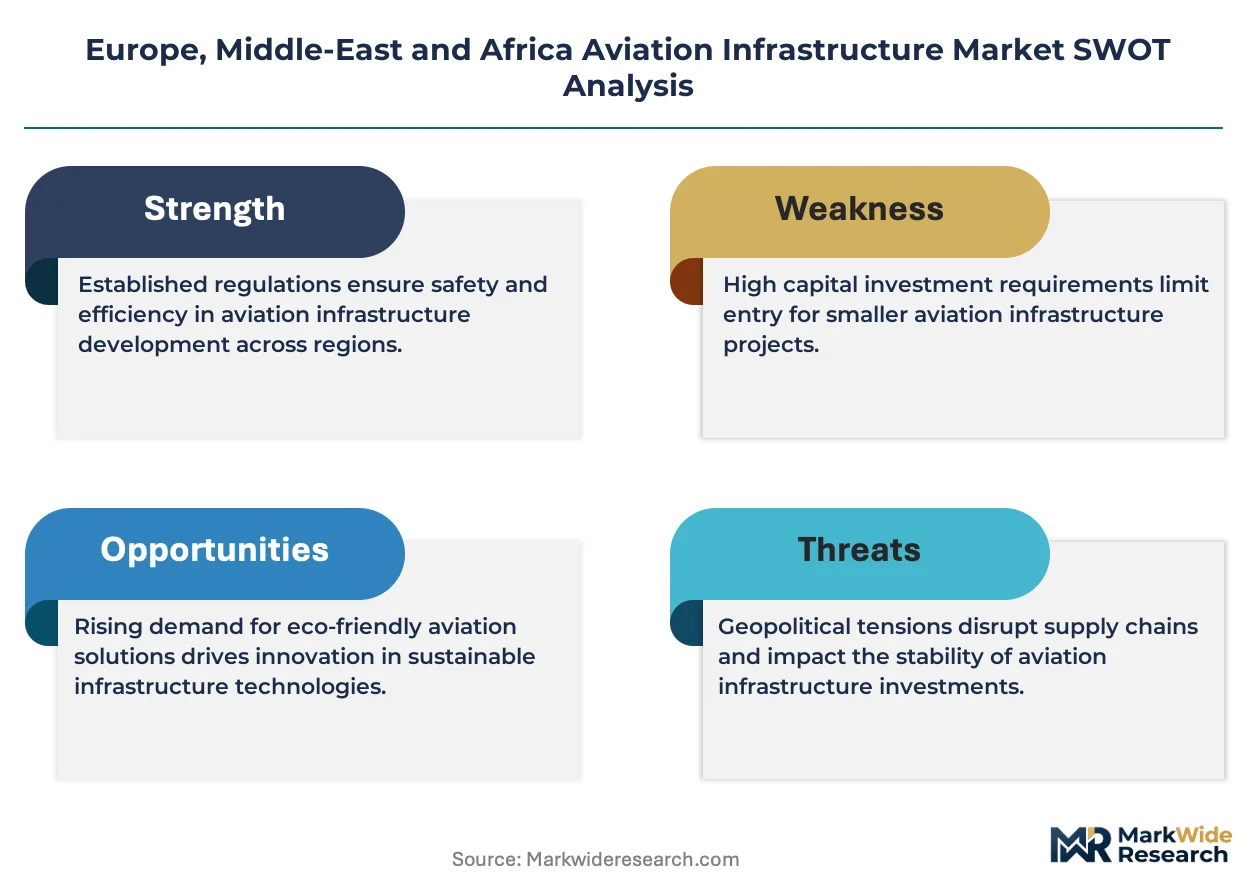
Gulf sovereign developers with centralized procurement authority anchor demand for bundled construction-maintenance contracts, compressing vendor margins while extending payment security through concession-backed structures. This buyer concentration rewards contractors with EASA and GACA dual-certification capabilities, creating tiered pricing based on compliance breadth rather than unit cost alone.
Pricing Analysis
Warranty unbundling from initial construction awards now separates pavement performance guarantees from electrical system service agreements. Three-tier pricing structure across premium, standard, and economy levels reflects certification tier and embodied-carbon tracking capabilities. Cost compression in standard-tier runway construction is intensifying because qualified pavement engineering firms number fewer than twelve across EMEA. Government procurement offices demonstrate highest price sensitivity; sovereign Gulf developers with concession refinancing requirements show lowest sensitivity to upfront capital.
Supply Chain Analysis
Direct-to-airport procurement channels handle sovereign developer demand, while tier-1 EPC contractors manage subcontractor tiers for specialized electrical and pavement work. Polymer-modified asphalt binders draw from refineries in the Netherlands and Belgium; LED airfield lighting systems source from German and French electrical manufacturers. Single-source vulnerability concentrates in Rotterdam and Antwerp terminal disruptions propagating into contractor scheduling. Distribution runs through engineering-procurement-construction conglomerates with established GACA and EASA relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EMEA aviation infrastructure market functions as a cost-of-compliance story where EASA airworthiness directives and UAE GCAA certification standards erect barrier-to-entry moats. Contractors lacking dual-jurisdiction capabilities face automatic disqualification from cross-border hub projects spanning North Africa and the Levant.
For Market Incumbents: Lock in long-term pavement engineering talent through captive training pipelines and certification sponsorships. Incumbent specialists must secure exclusive relationships with Rotterdam and Antwerp polymer-modified binder suppliers before specialty asphalt supply concentration worsens. Vertical integration into electrical infrastructure capabilities defends against unbundling trends separating construction from maintenance awards.
For New Entrants and Emerging Players: Digital twin modeling services offer a low-asset entry path into airport operator relationships without requiring heavy civil construction capabilities. Egypt and Morocco greenfield developments represent the most penetrable geography given lower certification stringency than Gulf hubs. New entrants should target predictive maintenance algorithm contracts as a beachhead for expanding into integrated airside services.
For Investors and Strategic Acquirers: The window for entry favors specialized pavement engineering boutiques with GACA relationships ahead of Saudi mega-event procurement acceleration. Long-term viability centers on recurring maintenance revenue pools under operational continuity rules rather than lumpy construction awards. Watch for ANSP satellite-based surveillance procurement announcements as inflection indicators for CNS/ATM integration contract availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | EASA-GACA dual credentials unlock cross-border hub projects in North Africa and the Levant corridor. |
| Specialized Talent Acquisition | Captive pavement engineering pipelines address PCI scoring scarcity constraining regional expansion. |
| Electrical Infrastructure Integration | High-voltage charging capabilities position contractors for EU Green Deal apron retrofit mandates. |
| Predictive Maintenance Platform Development | Digital twin algorithms displace scheduled inspection regimes across sovereign airport portfolios. |
| Polymer-Modified Binder Supply Security | Long-term offtake agreements with Rotterdam and Antwerp refiners mitigate asphalt supply concentration risk. |
Research Methodology
Regulatory filings from EASA and national aviation authorities, construction tender databases, and ANSP procurement records formed the secondary backbone of this analysis. Primary interviews with airport procurement directors, EPC contract managers, pavement engineering specialists, and electrical infrastructure integrators validated demand assumptions across the projection horizon. Bottom-up project pipeline analysis triangulated against top-down sovereign expenditure commitments.
Bottom-up modeling aggregated individual airport expansion programs across the UAE, Saudi Arabia, Germany, France, and Egypt. Segmentation dimensions included product type, technology category, end-user procurement authority, and service lifecycle stage. CAGRs were derived from weighted project commencement schedules and certification timeline compression factors. Industry-specific inputs incorporated EASA LED retrofit mandates and GACA streamlined approval pathways for strategic corridor projects.
The model holds under stable regulatory jurisdiction primacy; deviation in cross-border certification disputes or polymer-modified binder supply disruptions would shift contractor availability and pricing trajectories. Forecasts reflect documented assumptions regarding passenger volume growth and mega-event scheduling. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Aerotropolis Market