
 Europe Airport Baggage Handling Systems Market | 2026-2036
Europe Airport Baggage Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Airport Baggage Handling Systems Market Foresight
Modular sortation configurations is restructuring procurement patterns across European airports. Vanderlande Industries leverages its automated guided vehicle portfolio to anchor large-scale hub deployments in Amsterdam and Frankfurt. Siemens AG competes through integrated control software that synchronizes conveyor segments with airport operational databases. Daifuku Co. specializes in high-throughput sortation systems designed for ultra high capacity terminals handling over seventy million bags annually.
Airport baggage handling systems comprise mechanized conveyor networks, automated guided vehicles, and sortation equipment engineered to transport luggage between check-in counters, security screening points, and aircraft loading bays with throughput rates exceeding ten thousand bags per hour. These installations rely on radio frequency identification tags and barcode scanners to maintain traceability across multi-kilometer circuit paths. Conveyor systems still occupy the largest installed base across European airports, though automated guided vehicles represent the fastest-growing segment as operators seek flexible routing without fixed infrastructure. Sortation systems command the strongest margin pools due to proprietary control algorithms and integration complexity that limits vendor substitution.
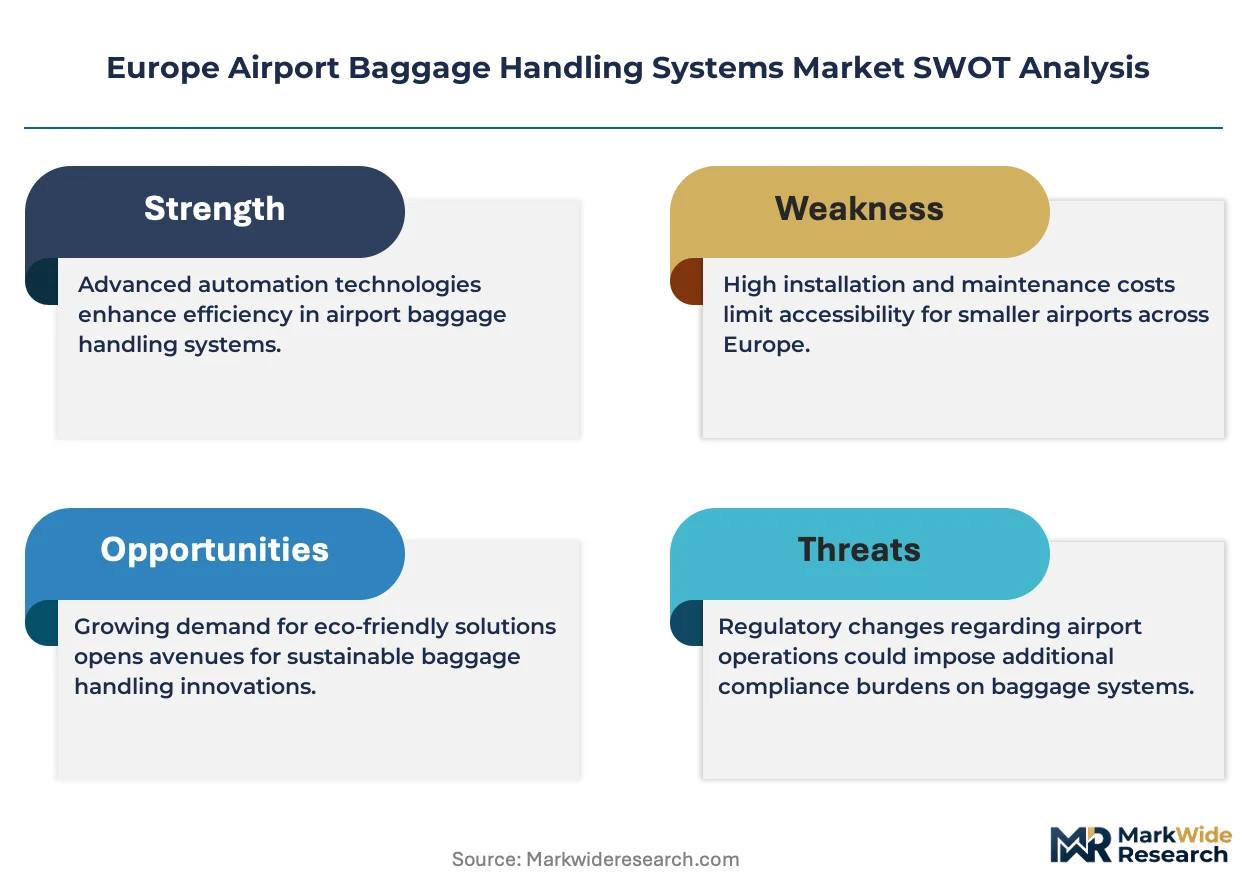
The EU Green Deal and REACH frameworks mandate energy efficiency disclosures and restricted substance compliance for electromechanical equipment deployed in airport infrastructure. EASA safety directives govern baggage system interoperability with aircraft loading operations and passenger screening protocols. The CE marking regime shapes market access by requiring electromagnetic compatibility and machinery safety validation before commercial deployment. Stakeholders must monitor how the EU AI Act classification rules affect automated decision-making in baggage routing algorithms and predictive maintenance platforms.
Market Dynamics
EU Green Deal emissions benchmarks are forcing electrification of conveyor networks across European airports, while hub-and-spoke carriers expand automated sortation capacity to manage passenger volume surges at gateway terminals.
Growth Catalysts
- EU Green Deal mandates:Binding emissions benchmarks push operators toward electrified conveyor networks and regenerative drive systems in baggage handling infrastructure.
- Terminal modernization programs:Hub-and-spoke airports in Germany, France, and the United Kingdom are retrofitting legacy systems with high-throughput automated sortation to accommodate rising passenger volumes.
- RFID traceability requirements:EASA interoperability directives mandate radio frequency identification integration across baggage circuit paths, driving replacement demand for legacy barcode-only installations.
Market Restraints
- Copper and rare earth price volatility:Electrified conveyor motors and automated guided vehicle battery packs face input cost pressure from commodity market swings.
- Proprietary control algorithm lock-in:Sortation system vendors maintain captive integration architectures that limit airport operator switching flexibility between equipment generations.
- REACH substance compliance:Electromechanical components containing restricted lubricants and coatings face extended validation timelines before CE marking approval.
Strategic Opportunities
- Central and Eastern European gateway expansion:Underpenetrated airports in Poland, Hungary, and the Czech Republic are greenfielding terminals without legacy infrastructure constraints.
- Predictive maintenance platforms:Convergence of machine learning with operational databases enables condition-based servicing of conveyor segments before failure-induced downtime.
- EU AI Act classification clarity:Automated baggage routing algorithms falling outside high-risk categories face streamlined conformity assessment procedures.
Industry Challenges
- Mechatronics technician scarcity:Specialized maintenance crews capable of servicing automated guided vehicle fleets and programmable logic controller networks remain concentrated in Western European labor markets.
- Multi-kilometer circuit integration:Retrofitting electrified conveyors into existing terminal footprints requires phased shutdowns that compress installation windows during low-traffic periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Airport Baggage Handling Systems Market |
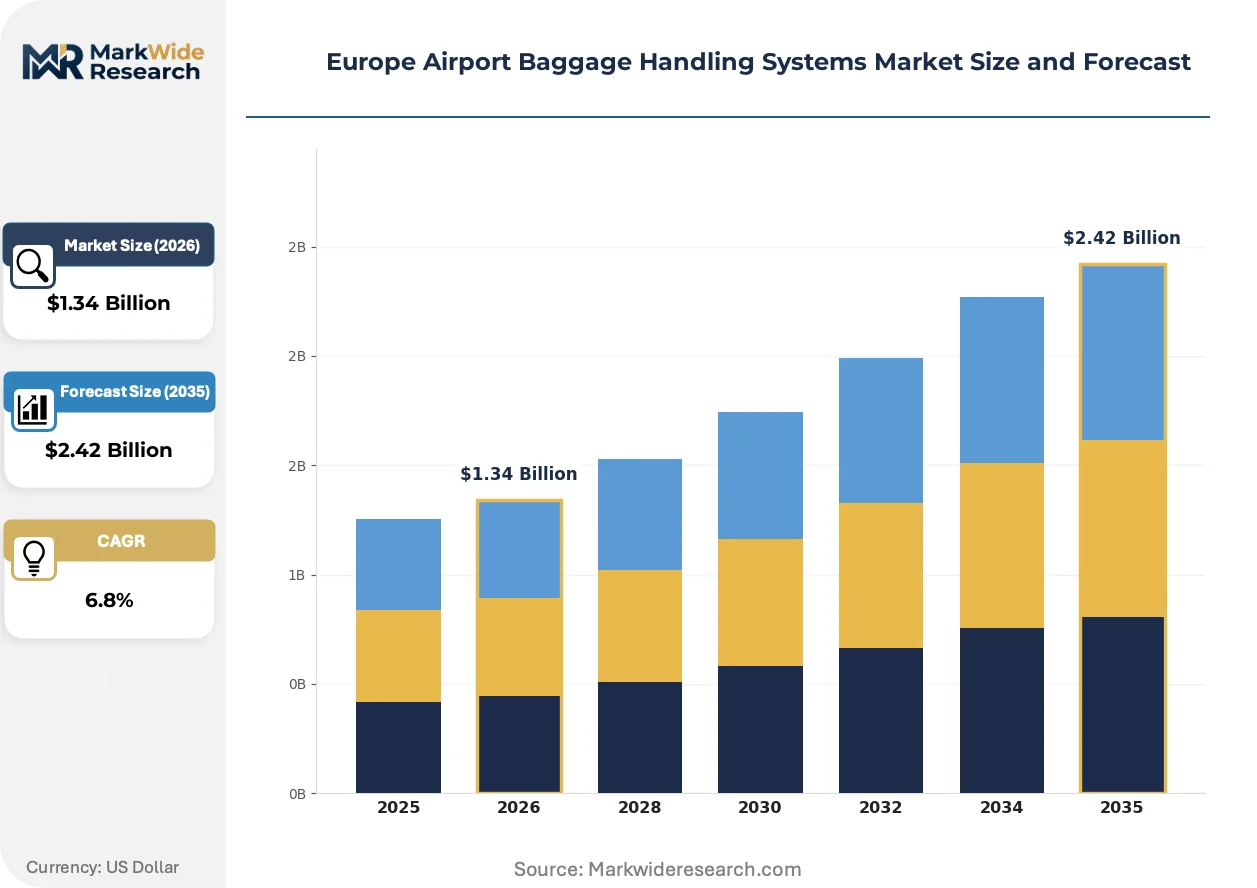
| Market Size in 2026 | $1.34 Billion |
| Market Size in 2035 | $2.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Conveyor Systems, Automated Guided Vehicles, Sortation Systems, Handling Systems Technology: Radio Frequency Identification, Barcode Systems, Magnetic Stripe, Optical Recognition End User: Airports, Airlines, Ground Handlers, Logistics Providers Capacity: Low Capacity, Medium Capacity, High Capacity, Ultra High Capacity |
| Companies Covered | Daifuku Co., Fives Group, Vanderlande Industries, Alstef Group, G&S Airport Conveyor, BEUMER Group, SITA, Sick AG, Siemens AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Airport Baggage Handling Systems Market Shifts & Advancements
Automated guided vehicle technology is restructuring baggage handling architectures across European airports, displacing fixed conveyor infrastructure with flexible routing systems that adapt to seasonal traffic fluctuations.
Autonomous mobile robotics is decentralizing baggage transport by replacing fixed-path conveyor belts with vehicle fleets that navigate terminal layouts dynamically. Hub operators at Amsterdam Schiphol and Frankfurt are deploying these systems to eliminate single points of failure in multi-kilometer circuit paths. The technology is decentralizing maintenance scheduling and capital allocation across distributed vehicle pools rather than centralized belt segments.
EU AI Act classification rules are reshaping vendor liability for automated decision-making in baggage routing algorithms. Systems performing predictive sortation without human-in-the-loop oversight face heightened conformity assessment requirements. High-throughput terminals handling over fifty million bags annually are most affected, with operators restructuring algorithm governance to secure CE marking compliance.
After-sales service unbundling is fragmenting vendor relationships as airport operators separate equipment procurement from maintenance contracts. Third-party technical service providers are capturing predictive maintenance and spare parts logistics functions previously bundled with original system sales. This shift is most visible at UK and German gateway airports where procurement teams prioritize operational expenditure flexibility over capital-intensive turnkey agreements.
Europe Airport Baggage Handling Systems Market Segmentation
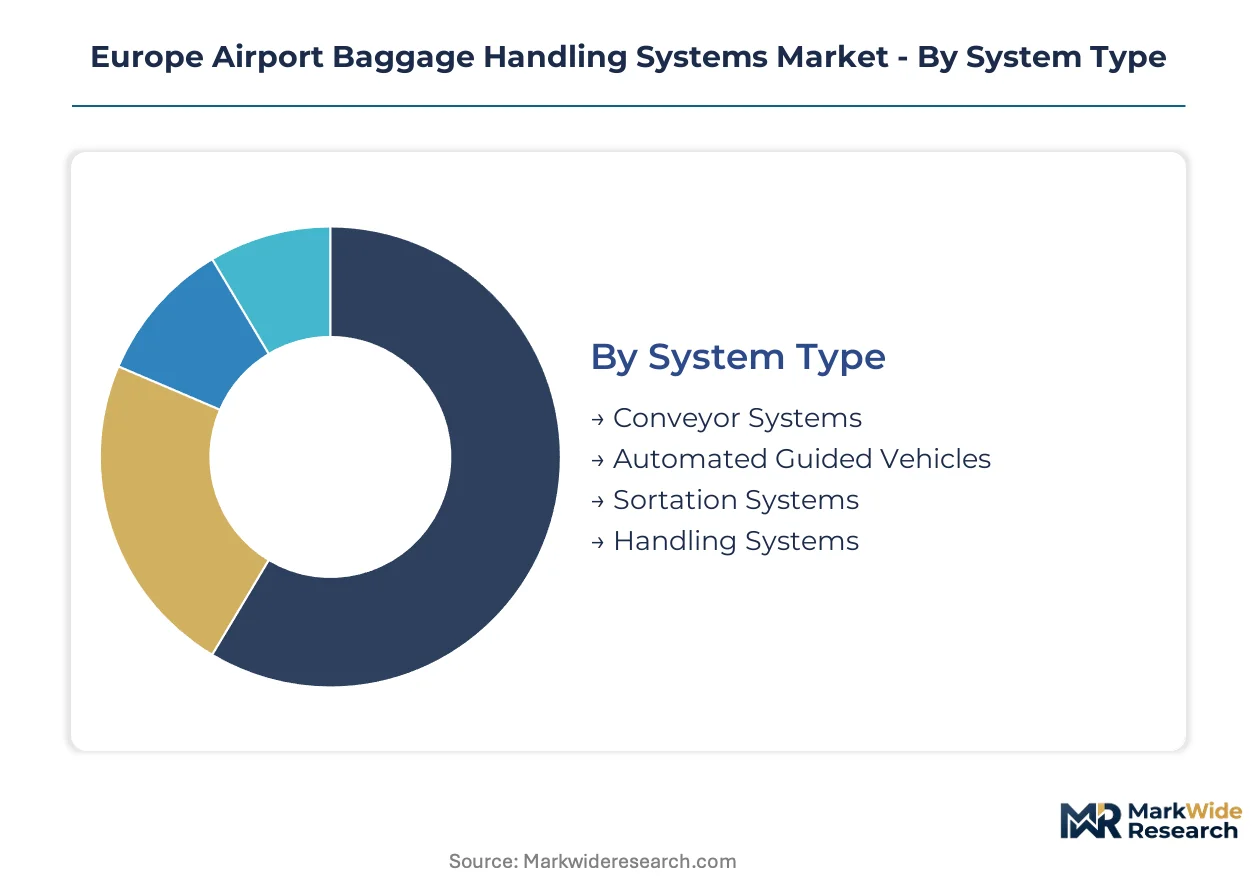
Segmentation in baggage handling systems reveals distinct procurement patterns across European airports. Integration depth varies sharply between standalone conveyor installations and fully embedded sortation networks requiring vendor lock-in.
System Type:
Standalone conveyor systems dominate retrofit projects where airports preserve existing control architectures. Embedded sortation and AGV networks demand deeper vendor relationships and longer commissioning cycles.
- Conveyor Systems:Belt and roller configurations transport bags across multi-kilometer terminal footprints at throughput rates exceeding ten thousand items hourly. German and French gateway airports prioritize electrified regenerative drives to meet EU Green Deal benchmarks while maintaining legacy circuit layouts.
- Automated Guided Vehicles:Battery-powered fleets navigate dynamically without fixed infrastructure, enabling seasonal capacity adjustments. Amsterdam Schiphol and Frankfurt hub operators deploy these systems to eliminate single points of failure in high-traffic corridors.
- Sortation Systems:Tilt-tray and cross-belt sorters execute high-speed routing decisions using proprietary control algorithms. Ultra-high-capacity terminals handling seventy million-plus bags annually require these installations.
- Handling Systems:Integrated check-in and loading bridge equipment bridges passenger-facing and airside operations. Ground handlers at UK airports favor modular units compatible with mixed fleet aircraft configurations.
Conveyor systems lead volumes today; automated guided vehicles are gaining share fastest.
Technology:
Traceability mandates from EASA reshape technology procurement, with radio frequency identification displacing legacy optical methods in new installations. Cost tiers separate premium RFID infrastructure from budget barcode retention strategies.
- Radio Frequency Identification:UHF tags and interrogators enable real-time bag tracking across circuit paths without line-of-sight constraints. EASA interoperability directives mandate RFID integration at major European gateways, driving replacement demand.
- Barcode Systems:Laser scanners and 2D imagers provide lower-cost traceability for regional airports with moderate throughput requirements. Polish and Hungarian operators retain these systems during phased modernization programs.
- Magnetic Stripe:Legacy encoding on bag tags persists in ground handler operations serving multiple airline clients with disparate IT systems. Compatibility requirements slow displacement timelines.
- Optical Recognition:Camera-based identification supplements primary traceability methods in high-speed sortation junctions. Siemens AG and Daifuku embed these sensors as redundancy layers.
Barcode systems retain installed base leadership; radio frequency identification climbs the fastest.
End User:
Customer type determines capital allocation authority and maintenance responsibility splits. Airlines direct specification at hub airports while ground handlers control procurement at spoke facilities.
- Airports:Terminal operators own infrastructure in concession-based models prevalent across Germany and France. These entities prioritize energy efficiency disclosures required under EU Green Deal frameworks.
- Airlines:Network carriers at Frankfurt and Amsterdam Schiphol specify sortation performance standards in long-term terminal use agreements. Lufthansa and KLM influence AGV fleet sizing decisions.
- Ground Handlers:Swissport and Menzies Aviation procure modular handling systems compatible with seasonal contract fluctuations. These operators favor unbundled maintenance contracts to preserve operational expenditure flexibility.
- Logistics Providers:DHL and FedEx integrate airport baggage infrastructure with broader express parcel networks at cargo-adjacent terminals. Belgian and Dutch gateways see concentrated demand from this segment.
Airports dominate capital deployment today; ground handlers are expanding procurement authority fastest.
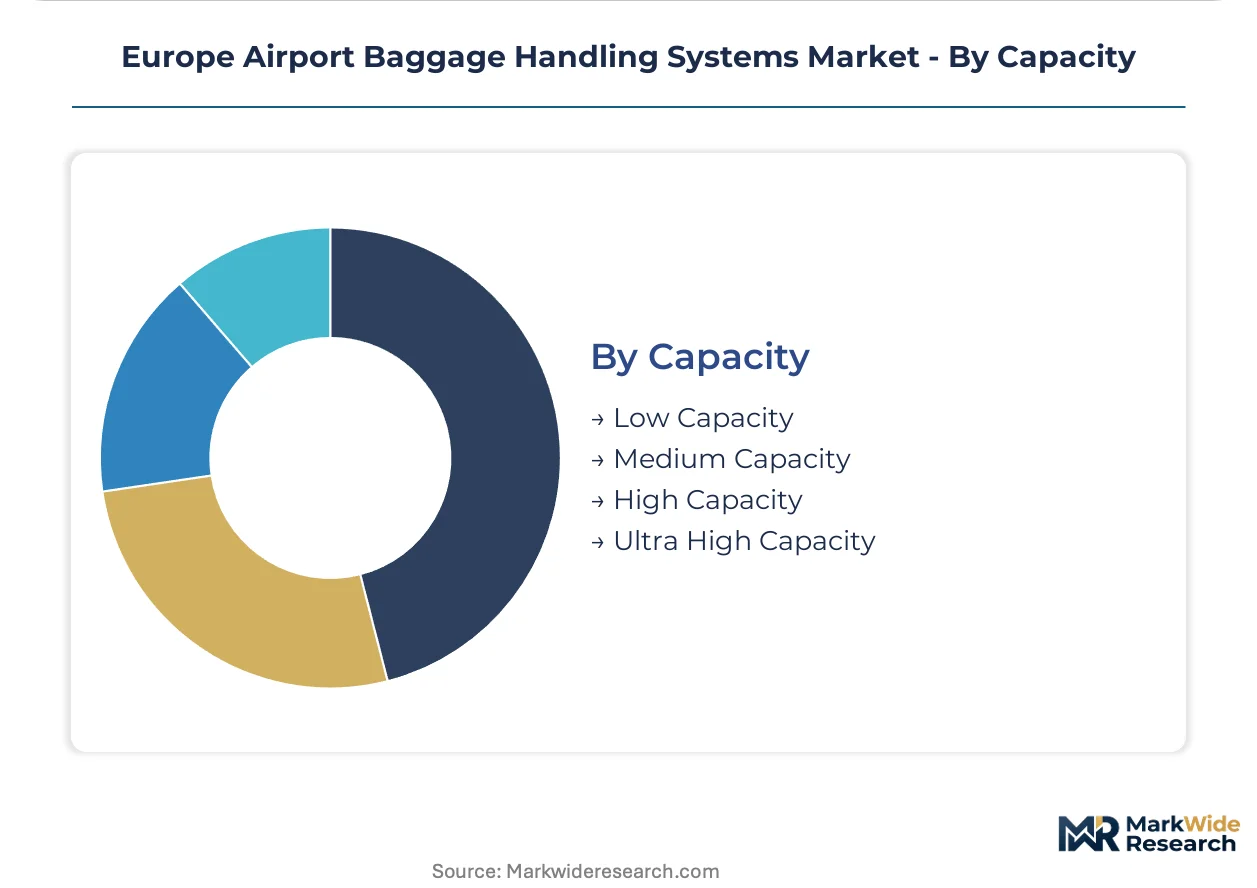
Capacity:
Volume thresholds segment vendor specialization, with ultra-high-capacity installations commanding proprietary engineering and extended commissioning timelines. Mid-tier airports face supplier selection constraints between scaled-down premium systems and upgraded standard offerings.
- Low Capacity:Systems processing under one million bags annually serve regional airports in the Czech Republic and Slovakia. These installations emphasize barcode-based traceability and manual sortation backup.
- Medium Capacity:Five to fifteen million bag throughput configurations dominate secondary European gateways. Hungarian and Romanian airports deploy these systems with phased RFID upgrade paths.
- High Capacity:Fifteen to fifty million bag installations require automated sortation with redundant control systems. UK terminal modernization programs concentrate demand in this tier.
- Ultra High Capacity:Exceeding fifty million bags annually, these systems integrate AGV fleets with predictive maintenance platforms. Frankfurt, Amsterdam Schiphol, and Paris Charles de Gaulle anchor European demand.
High capacity systems lead installation value today; ultra high capacity projects show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baggage handling automation first achieved industrial scale in Germany during the 1970s, with Frankfurt Airport pioneering early mechanized sortation for hub-and-spoke operations. This German engineering lineage established technical standards that spread across European gateway terminals over subsequent decades.
Germany
Frankfurt and Munich anchor the continent's densest concentration of ultra-high-capacity installations, with Lufthansa influencing AGV fleet specifications in long-term terminal use agreements. The KBA motor vehicle regulator's safety protocols extend to automated ground equipment interoperability, ensuring seamless aircraft loading coordination. North Rhine-Westphalia hosts BEUMER Group's engineering operations serving Düsseldorf and Cologne-Bonn gateway expansions.
United Kingdom
Heathrow Terminal 2 and Gatwick drive replacement demand for legacy barcode systems with EASA-mandated RFID traceability upgrades. The UK Civil Aviation Authority's operational resilience directives compress installation windows into nocturnal maintenance periods. London Stansted and Manchester anchor ground handler procurement autonomy, with Swissport and Menzies Aviation unbundling maintenance from equipment contracts.
France
Paris Charles de Gaulle's Terminal 2 expansion concentrates automated guided vehicle deployments for Air France-KLM network coordination. The ANSM technical safety agency's machinery conformity assessments shape CE marking timelines for electromechanical components. Lyon and Nice Côte d'Azur represent medium-capacity modernization priorities under regional airport concession frameworks.
Netherlands
Amsterdam Schiphol ranks among Europe's most automated baggage hubs, with Vanderlande Industries anchoring large-scale AGV deployments since the 1990s. The Dutch Human Environment and Transport Inspectorate enforces EU Green Deal emissions disclosures for electrified conveyor networks. Rotterdam The Hague Airport exemplifies regional spoke terminal procurement patterns favoring modular handling systems.
Poland
Warsaw Chopin and Kraków-Balice represent greenfield terminal construction without legacy infrastructure constraints, attracting standard-tier conveyor and sortation configurations. The Polish Office of Technical Inspection validates machinery safety compliance for CE marking equivalence. Katowice Airport's cargo-adjacent operations draw logistics provider integration with express parcel networks.
Europe Airport Baggage Handling Systems Market Competitive Landscape
The competitive structure tilts toward integrated system architects rather than component specialists. Vendor relationships concentrate around three to five full-line providers capable of delivering multi-kilometer circuit integration with proprietary control software. Two strategic archetypes dominate: European engineering conglomerates with airport-specific divisions, and Japanese material handling specialists with global terminal portfolios. Competitive moves center on predictive maintenance platform development and after-sales service unbundling to capture recurring revenue streams.
Within the integrated-system tier, Daifuku Co. and Vanderlande Industries occupy positions exemplifying scale-driven specialization in high-throughput sortation, while Siemens AG represents the diversified industrial conglomerate archetype with control software capabilities. BEUMER Group and Fives Group anchor the mid-market European engineering segment serving retrofit-intensive gateway terminals. Alstef Group occupies a niche position among French-origin specialists with concentrated hub deployment experience.
| Leading Market Players |
|---|
| Daifuku Co. |
| Fives Group |
| Vanderlande Industries |
| Alstef Group |
| G&S Airport Conveyor |
| BEUMER Group |
| SITA |
| Sick AG |
| Siemens AG |
| Others |
Supply & Pricing Matrix
Gateway airport procurement teams in Germany, France, and the United Kingdom concentrate demand for ultra-high-capacity installations, anchoring a project-based pricing model where long-term terminal use agreements bundle equipment procurement with multi-year service contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates proprietary sortation systems with predictive maintenance platforms from modular conveyor retrofits and basic handling equipment. Price differentiation centers on integration complexity and after-sales bundling, with CE marking compliance timelines adding certification premiums to EU-bound deliveries. Cost compression in standard-tier conveyor motors is intensifying because copper and rare earth price volatility feeds through electrified component sourcing. Ground handlers at UK spoke terminals exhibit highest price sensitivity, prioritizing unbundled maintenance contracts over capital-intensive turnkey agreements.
Supply Chain Analysis
Dual-sourcing requirements from Frankfurt and Amsterdam Schiphol operators mandate qualified supplier rosters spanning German engineering conglomerates, Japanese material handling specialists, and mid-tier European integrators. Component manufacturing concentrates in Germany, the Netherlands, and Japan, with programmable logic controllers and regenerative drive systems drawing from precision electromechanical clusters. Supply chain risk hinges on rare earth magnet sourcing concentration for AGV battery packs. Distribution runs through direct vendor-airport relationships for large-scale deployments, with third-party technical service providers capturing aftermarket parts logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe airport baggage handling systems market represents a late-cycle quality story as EU Green Deal emissions benchmarks force replacement demand toward electrified, RFID-integrated premium installations over legacy barcode-retrofit alternatives.
For Market Incumbents: To counter after-sales service unbundling by third-party technical providers, anchor client relationships through predictive maintenance platform subscriptions and deepen backward integration into proprietary control software development. Capture recurring revenue streams that resist procurement team pressure for operational expenditure flexibility. For New Entrants and Emerging Players: Begin with greenfield gateway terminals in Poland, Hungary, and the Czech Republic where legacy infrastructure constraints are absent and standard-tier conveyor configurations face qualified vendor shortages. Target modular AGV fleet deployments with seasonal capacity adjustment features as the most penetrable entry point. For Investors and Strategic Acquirers: Industrial engineering conglomerates seeking airport verticals represent the most active acquirer in this space, particularly those lacking integrated control software capabilities. Long-term viability favors targets with established CE marking validation infrastructure and EASA interoperability credentials. Watch for EU AI Act classification clarity as the signal indicating accelerated automated decision-making investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Siemens AG and Daifuku embed machine learning to enable condition-based conveyor servicing before failure-induced downtime. |
| Backward Integration into Control Software | Vanderlande Industries deepens proprietary algorithm development to limit airport operator switching flexibility between equipment generations. |
| CE Marking Pre-Validation Investment | BEUMER Group accelerates machinery safety assessments to compress commissioning timelines for German gateway terminal expansions. |
| RFID Infrastructure Partnership | SITA aligns with EASA interoperability directives to capture replacement demand from legacy barcode-only installations at Heathrow and Gatwick. |
| Greenfield Terminal Joint Venture | Alstef Group targets Warsaw Chopin and Kraków-Balice expansions without retrofit constraints from existing circuit footprints. |
Research Methodology
Coverage spans Western Europe, Central Europe, and the Nordic region, with primary inputs from each combining interviews with airport procurement directors, ground handler operations managers, AGV maintenance technicians, and electromechanical systems integrators. Secondary validation draws from EASA safety directives, EU Green Deal emissions disclosure databases, CE marking registration records, and airport authority capital expenditure reports. Bottom-up installation sizing triangulates against top-down terminal throughput capacity estimates.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon, modeling system type, technology tier, end-user category, and capacity threshold as core segmentation dimensions. CAGRs derive from installed base replacement cycles, greenfield terminal construction pipelines, and electrification retrofit intensities. Forecast inputs incorporate EU AI Act classification timelines and REACH substance compliance validation periods.
Several conditions sit outside the modeled scope, including abrupt copper commodity price spikes, unilateral tariff impositions on Japanese electromechanical imports, and EASA mandate acceleration beyond published interoperability deadlines. Deviation in EU Green Deal emissions benchmark stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Airport Passenger Boarding Bridge Market