
 Heliports Market | 2026-2036
Heliports Market Size, Share, and Industry Trends Forecast 2026-2036
Heliports Market Intelligence
Single-source procurement for steel substructures is decoupling from legacy supplier relationships as operators diversify fabrication partners. FEC Heliports leverages in-house engineering capabilities to control design-to-installation timelines. Heliport Systems Inc. anchors its position through geographic concentration in North American urban rooftop installations. Aluminium Offshore Pte Ltd dominates marine-grade alloy helideck supply for energy sector clients.
A heliport is a designated landing and takeoff area for rotorcraft, incorporating load-bearing surfaces rated for dynamic wheel loads, perimeter safety nets, and approach/departure clearances governed by ICAO Annex 14 Volume II specifications. Its primary commercial purpose is to enable point-to-point aerial mobility where runway infrastructure is impractical or unavailable. Fixed heliports sustain the largest installed base but carry mature margin profiles, while offshore heliports capture premium pricing due to corrosion-resistant material requirements and marine certification complexity. Rooftop heliports represent the fastest-growing installation category as urban air mobility corridors gain municipal approval in dense metropolitan zones.
FAA Advisory Circular 150/5390-2C and EASA CS-HPTD standards govern heliport dimensional criteria, lighting photometrics, and fire suppression integration, directly shaping product development roadmaps and market access conditions. OSHA fall-protection mandates and NFPA 418 fire codes further constrain design choices for elevated and offshore installations. Stakeholders must monitor evolving urban air mobility integration rules as municipalities reconcile helicopter operations with drone corridor planning.
Market Dynamics
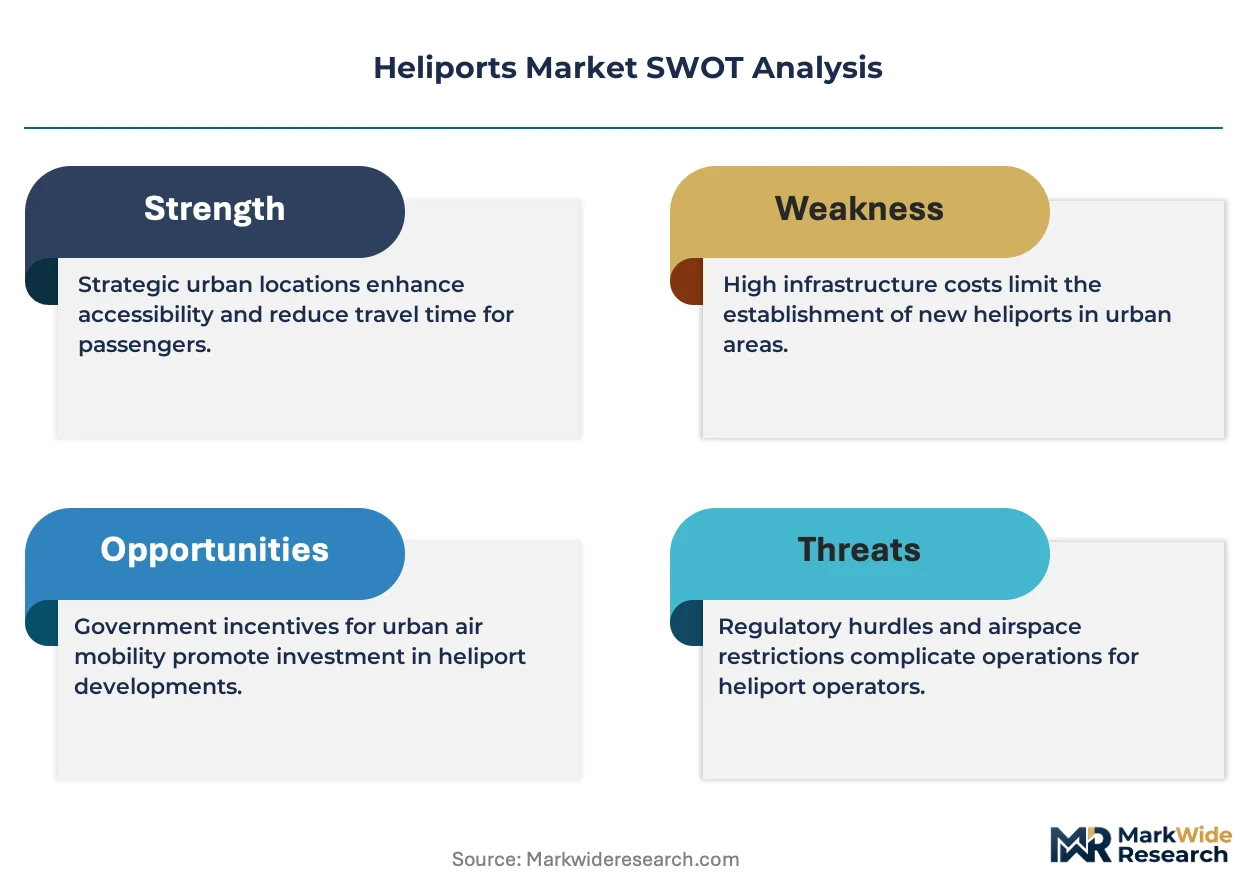
Urban air mobility corridors are forcing a recalibration of heliport design standards as municipalities integrate rotorcraft operations with emerging drone infrastructure. FAA and EASA rulemaking on vertiport specifications is compressing lead times for rooftop installations while elevating fire suppression and electrical load requirements.
Growth Catalysts
- Offshore Wind Buildouts:North Sea energy developers are commissioning purpose-built marine helidecks for turbine maintenance crews. EASA CS-HPTD certification requirements for marine environments are standardizing procurement specifications across European operators.
- Level 3 Trauma Network Expansion:Hospital systems in the United States Gulf Coast corridor are adding rooftop landing facilities to reduce patient transport times. NFPA 418 fire codes are mandating integrated foam suppression systems in new constructions.
- Composite Decking Materials:Glass-reinforced polymer surfaces are displacing traditional steel and aluminum platforms in corrosion-critical installations. The material's fatigue resistance is extending inspection intervals for offshore operators.
Market Restraints
- Aluminum Alloy Price Volatility:Marine-grade 5083-H321 plate costs are fluctuating with energy-intensive smelting economics. Fabricators in Southeast Asia are absorbing margin compression rather than passing through full input cost increases.
- Specialized Welder Scarcity:Helideck structural certification requires DNV-qualified aluminum welders. The credential pipeline constrains fabrication capacity in Norway, the United Kingdom, and the Netherlands.
- Helipad Lighting Certification Backlogs:FAA photometric testing queues for LED approach lighting systems are extending equipment delivery timelines. Manufacturers are pre-certifying modular kits to circumvent approval delays.
Strategic Opportunities
- Urban Air Mobility Vertiports:São Paulo, Brazil is approving multi-use landing infrastructure for both conventional helicopters and eVTOL aircraft. ANAC is developing transitional certification pathways for dual-purpose facilities.
- Integrated Drone Corridors:Heliport operators in Singapore are retrofitting existing platforms with unmanned aerial vehicle docking stations. The Civil Aviation Authority of Singapore is piloting shared airspace management protocols.
- Modular Prefabrication:Containerized helideck components are reducing installation downtime for offshore energy clients. Standardized subassemblies are enabling just-in-time deployment to remote platform locations.
Industry Challenges
- Structural Engineer Specialization Gap:Fewer than two dozen consultancies worldwide hold DNV-ST-C503 certification for marine helideck design. Project bottlenecks form at the engineering review stage.
- Legacy Platform Retrofit Complexity:Older offshore installations require load-bearing capacity upgrades to accommodate heavier next-generation rotorcraft. Structural reinforcement timelines often exceed original platform design lifecycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heliports Market |
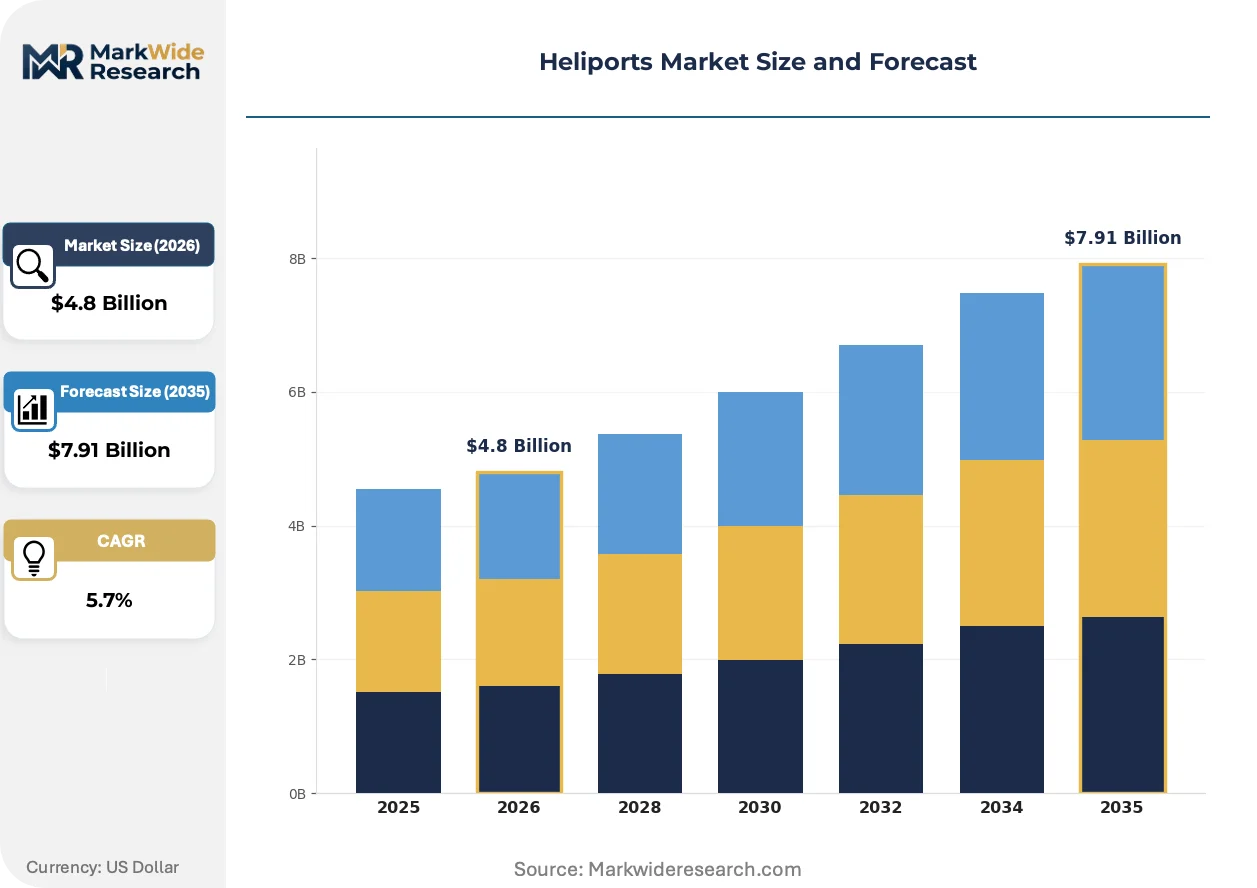
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Heliports, Mobile Heliports, Rooftop Heliports, Offshore Heliports Installation Type: Public, Private, Commercial, Emergency Services Usage: Tourism, Medical Evacuations, Corporate Transport, Freight Services Aircraft Type: Light Helicopters, Medium Helicopters, Heavy Helicopters, Unmanned Aerial Vehicles |
| Companies Covered | Aluminium Offshore Pte Ltd, FEC Heliports, Heliport Systems Inc., Helitecnica, Technokontrol Global Ltd, Bnnaviation, Helidex LLC, TKH Group NV, Calzoni, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heliports Market Strategic Shifts & Innovations
Digital twin technology is reshaping how operators monitor structural fatigue and schedule maintenance interventions. Real-time sensor networks are displacing periodic visual inspections as the primary condition assessment methodology.
Glass-reinforced polymer composite decking is consolidating its position in marine and coastal installations. Offshore energy operators in the North Sea and Gulf of Mexico are specifying the material for its corrosion immunity and reduced maintenance burden. The technology is consolidating supplier margins by compressing the addressable market for traditional steel fabricators.
EU F-Gas Regulation phase-down schedules are accelerating adoption of low-global-warming-potential fire suppression agents in enclosed helideck environments. Equipment manufacturers are re-engineering foam delivery systems to accommodate fluorine-free formulations. Rooftop urban installations in Germany, France, and the Netherlands are experiencing the most acute compliance-driven equipment replacement cycles.
Hospital systems are unbundling heliport operations from aviation service contracts. Direct ownership of landing infrastructure is replacing long-term lease arrangements with third-party operators. The United States trauma network corridor from Houston to Miami exhibits the most pronounced shift toward captive facility management.
Heliports Market Segmentation
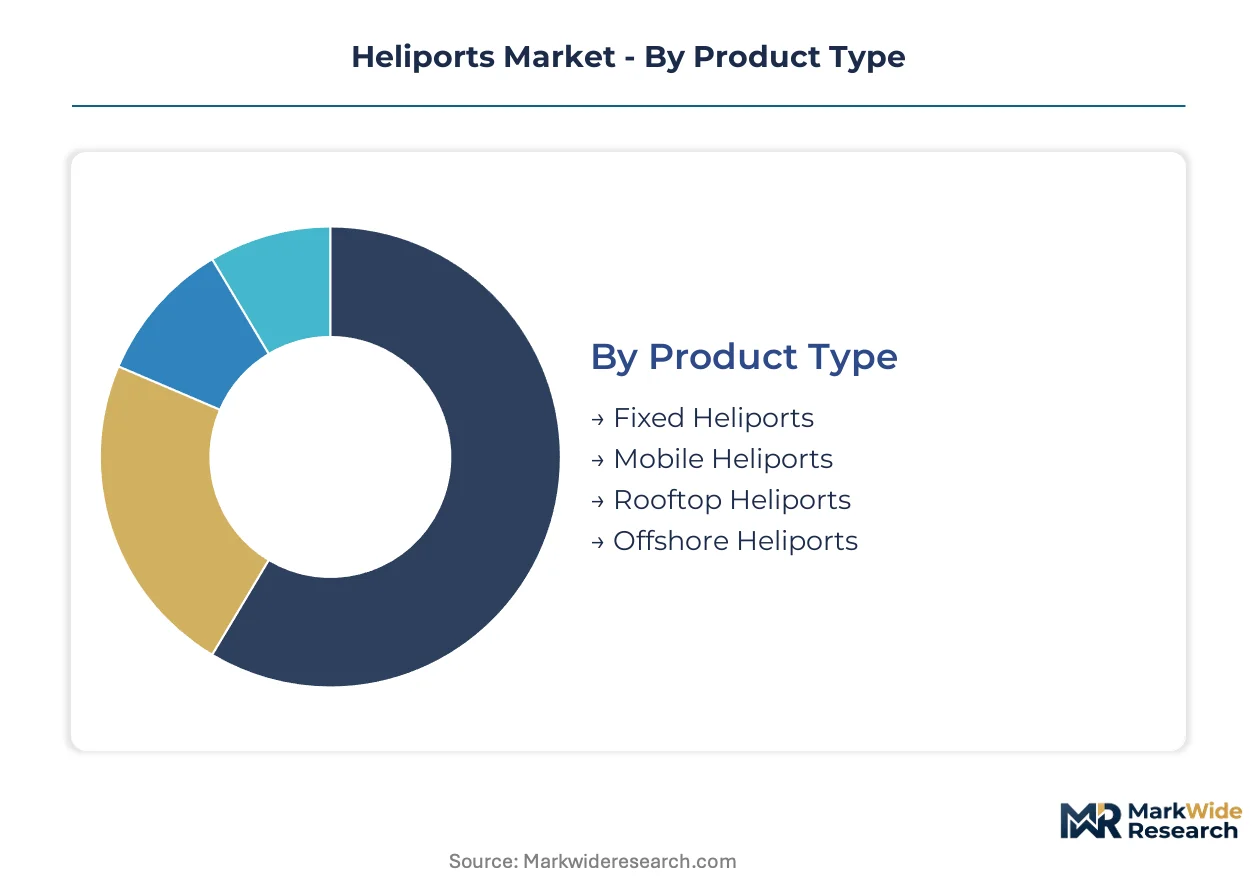
Heliport procurement decisions cascade through multiple technical and operational dimensions. Product specifications determine structural load ratings and certification pathways, while installation context shapes regulatory compliance requirements and operational protocols.
Product Type:
Supply concentration for steel substructures and marine-grade alloys varies sharply across product categories, with fabrication capacity clustering around specialized welding certifications and corrosion-resistant material expertise.
- Fixed Heliports:Permanent ground-level installations utilize reinforced concrete or steel platforms rated for repetitive dynamic loading. Demand concentrates in United States Gulf Coast hospital networks and municipal emergency response systems where FAA Advisory Circular 150/5390-2C compliance is mandatory.
- Offshore Heliports:Purpose-built marine helidecks employ 5083-H321 aluminum alloys or glass-reinforced polymer composites to withstand salt spray and wave impact. North Sea energy developers and Gulf of Mexico platform operators drive specification standards through EASA CS-HPTD and DNV-ST-C503 certification requirements.
- Mobile Heliports:Deployable aluminum platforms serve military field operations and disaster relief scenarios requiring rapid establishment.
- Rooftop Heliports:Elevated steel or composite structures integrate with urban high-rise architecture, with installations climbing fastest in São Paulo and Singapore as vertiport regulations mature.
Today's leader: Fixed Heliports. Tomorrow's challenger: Rooftop Heliports.
Installation Type:
Cost tier differentiation separates specification-intensive commercial installations from standardized public infrastructure, with emergency services commanding premium pricing for integrated fire suppression and lighting systems.
- Emergency Services:Hospital-affiliated rooftop facilities incorporate NFPA 418 foam suppression systems, ICU-grade electrical backup, and dedicated patient transfer protocols. United States Level 3 trauma networks from Houston to Miami represent the most concentrated demand cluster.
- Commercial:Corporate headquarters and luxury hospitality properties specify architecturally integrated designs with noise abatement features and VIP lounge connectivity. German and French urban installations face acute EU F-Gas Regulation compliance cycles for enclosed helideck fire suppression.
- Public:Municipal heliports serve law enforcement and general aviation access with standardized dimensional criteria.
- Private:Residential estates and exclusive club facilities emphasize aesthetic integration over operational intensity.
Commercial installations capture the steepest expansion trajectory. Emergency Services defend the highest margin position.
Usage:
Application-specific operational profiles dictate approach path geometry, fuel storage protocols, and ground handling equipment specifications across usage categories.
- Medical Evacuations:Time-critical patient transport requires 24/7 operational readiness, IFR-capable lighting systems, and direct hospital infrastructure integration. United States Gulf Coast corridor installations prioritize reduced transport times for trauma network coverage.
- Corporate Transport:Executive mobility services demand rapid turnaround capability, noise-compliant operations in dense urban zones, and seamless ground transportation handoffs. Singapore and São Paulo are approving multi-use infrastructure for conventional helicopters and emerging eVTOL aircraft.
- Tourism:Scenic flight operators utilize seasonal or remote installations with minimal permanent infrastructure.
- Freight Services:Logistics applications emphasize payload capacity and cargo handling equipment compatibility.
Medical Evacuations anchor current procurement volume. Corporate Transport is gaining share fastest.
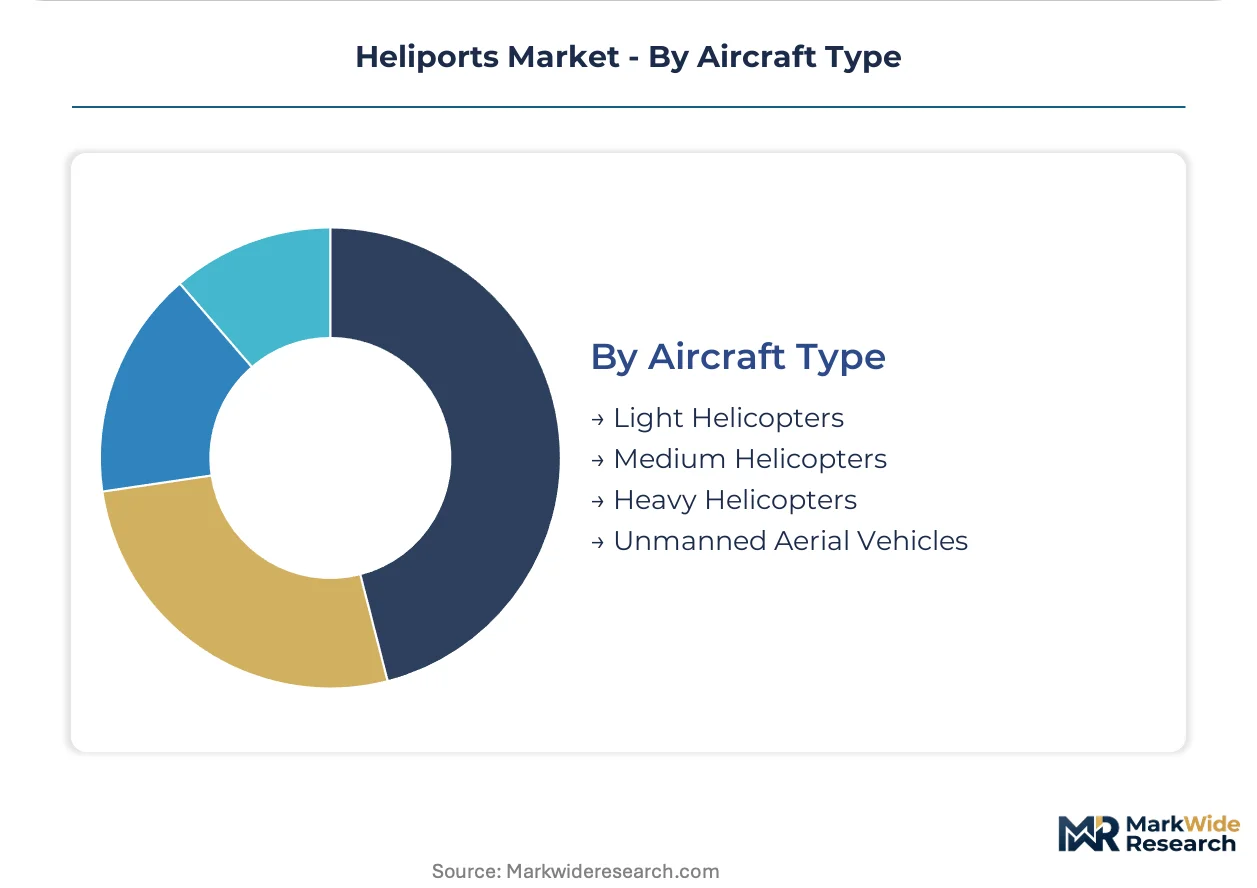
Aircraft Type:
Customer type segmentation separates legacy rotorcraft infrastructure from emerging unmanned system integration, with structural load ratings and electrical capacity requirements diverging sharply.
- Heavy Helicopters:Oil platform crew transport and military applications demand the highest dynamic load ratings, with DNV-qualified aluminum welders constraining fabrication capacity in Norway, the United Kingdom, and the Netherlands.
- Unmanned Aerial Vehicles:Drone corridor integration is forcing heliport design recalibration as Singapore's Civil Aviation Authority pilots shared airspace management protocols and retrofitting existing platforms with UAV docking stations.
- Medium Helicopters:Corporate and emergency medical services utilize intermediate load ratings with balanced operational flexibility.
- Light Helicopters:Training and private aviation applications utilize minimal structural requirements with cost-optimized specifications.
Heavy Helicopters dominate current structural engineering priorities. Unmanned Aerial Vehicles represent the most disruptive specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fabrication geography as EASA-certified welders in Northern Europe command premium rates while Southeast Asian fabricators absorb aluminum cost volatility without full pass-through. Production capacity migrates toward jurisdictions with qualified labor pools and marine certification infrastructure.
United States
Hospital systems across the Gulf Coast corridor from Houston to Miami are expanding Level 3 trauma networks with rooftop landing facilities. FAA Advisory Circular 150/5390-2C compliance is mandatory for all new constructions. The Southeast Florida cluster concentrates emergency medical heliport procurement as Miami-Dade and Broward health systems reduce patient transport times.
Norway
North Sea offshore wind developers are commissioning purpose-built marine helidecks for turbine maintenance crews. DNV-ST-C503 certification requirements standardize procurement specifications across Norwegian operators. Stavanger anchors the North Sea energy logistics hub where EASA CS-HPTD compliance drives specification intensity.
United Kingdom
Aberdeen's offshore supply base sustains demand for aluminum alloy helidecks serving North Sea platform access. Specialized DNV-qualified welder scarcity constrains fabrication capacity across Scotland and England's eastern seaboard. The Thames Estuary offshore wind zone is emerging as a secondary demand cluster for marine-grade installations.
Singapore
The Civil Aviation Authority of Singapore is piloting shared airspace management protocols integrating conventional helicopters with unmanned aerial vehicle corridors. Heliport operators are retrofitting existing platforms with UAV docking stations. The Marina Bay financial district concentrates corporate transport infrastructure as vertiport regulations mature.
Brazil
São Paulo's municipal government is approving multi-use landing infrastructure for both conventional helicopters and emerging eVTOL aircraft. ANAC is developing transitional certification pathways for dual-purpose facilities. The city's dense metropolitan core represents the fastest-growing rooftop installation category in Latin America.
Heliports Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue composite material specialization and modular prefabrication. The vendor base clusters around three strategic archetypes: in-house engineering integrators controlling design-to-installation timelines, geographic specialists anchoring regional procurement relationships, and marine-grade alloy fabricators dominating corrosion-resistant supply. Competitive moves concentrate on backward integration into steel substructure fabrication and geographic diversification away from legacy supplier concentrations.
Among marine-grade specialists, Aluminium Offshore Pte Ltd exemplifies the corrosion-resistant materials tier while FEC Heliports represents the in-house engineering integration archetype. Heliport Systems Inc. occupies a position within the North American geographic concentration cluster. These three anchors illustrate how supplier positioning fragments across certification capabilities and regional access rather than consolidating around scale advantages.
| Leading Market Players |
|---|
| Aluminium Offshore Pte Ltd |
| FEC Heliports |
| Heliport Systems Inc. |
| Helitecnica |
| Technokontrol Global Ltd |
| Bnnaviation |
| Helidex LLC |
| TKH Group NV |
| Calzoni |
| Others |
Cost & Logistics Intelligence
Offshore energy operators purchasing marine helidecks operate under project-based procurement frameworks that concentrate pricing power with DNV-certified fabricators. EASA CS-HPTD compliance requirements and limited welder pools in Northern Europe sustain premium pricing tiers for corrosion-resistant installations.
Pricing Analysis
Distributor margins compress in standard fixed heliport segments while direct-to-operator channels capture value in complex marine certifications. Three-tier pricing structure across premium, standard, and economy levels separates DNV-qualified marine installations from municipal emergency services specifications and basic private aviation platforms. Price differentiation hinges on certification grade and geographic delivery cost, with Gulf of Mexico operators absorbing logistics premiums for remote platform deployment. Cost compression in aluminum-intensive tiers is intensifying because Southeast Asian fabricators are absorbing input volatility without full pass-through. Hospital systems exhibit the highest price sensitivity due to capital budget constraints, while offshore wind developers defend premium positioning for turbine access infrastructure.
Supply Chain Analysis
DNV-ST-C503 certification requirements gate fabrication capacity to fewer than two dozen consultancies worldwide, concentrating supply in Norway, the United Kingdom, and the Netherlands. Raw material flows draw from marine-grade 5083-H321 aluminum plate producers, glass-reinforced polymer composite suppliers, and LED approach lighting system manufacturers. Single-source vulnerability runs through qualified aluminum welder pools, where credential pipelines constrain output across North Sea energy corridors. Distribution runs through EPC contractors for offshore energy clients and direct-to-hospital procurement for trauma network installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The heliports market compounds regulatory value through successive certification milestones, with FAA Advisory Circular 150/5390-2C updates and EASA vertiport rulemaking creating sustained procurement cycles for compliant infrastructure.
For Market Incumbents: Cement market position by deepening backward integration into steel substructure fabrication and securing captive DNV-qualified welding capacity in Stavanger or Aberdeen. Composite decking specialists threaten traditional aluminum margins; counter by pre-certifying modular helideck kits to circumvent FAA photometric testing backlogs for lighting systems. For New Entrants and Emerging Players: The price-point gap between premium marine-certified installations and economy-tier municipal emergency platforms opens entry pathways. Target São Paulo's rooftop vertiport segment where ANAC transitional certification creates first-mover latitude. Pursue containerized prefabrication for offshore energy clients requiring just-in-time deployment to remote platform locations. For Investors and Strategic Acquirers: Offshore wind developers are the most active acquirer in this space, vertically integrating turbine maintenance logistics through captive helideck infrastructure. Five-to-ten-year viability rests on urban air mobility corridor maturation and eVTOL certification convergence. Monitor EASA vertiport specification finalization as the inflection signal for dual-purpose facility investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Prefabrication Scale-Up | Containerized subassemblies compress installation downtime for North Sea offshore wind clients. |
| Composite Material Certification Investment | Glass-reinforced polymer expertise displaces traditional steel fabricators in corrosion-critical marine environments. |
| Urban Air Mobility Vertiport Partnership | São Paulo and Singapore municipalities pilot shared airspace protocols for dual-use infrastructure. |
| DNV Welder Pipeline Development | Credential expansion in Norway and the United Kingdom alleviates fabrication bottlenecks for marine helideck demand. |
| Integrated Fire Suppression Retrofit | EU F-Gas Regulation compliance drives equipment replacement cycles across German and French rooftop installations. |
Research Approach
Coverage spans the United States Gulf Coast corridor, North Sea energy logistics hubs, and Asia-Pacific vertiport development zones, with primary inputs from each. Interviews with heliport engineering directors, offshore platform procurement managers, hospital facility planners, and DNV certification specialists combined with secondary validation from FAA Advisory Circulars, EASA CS-HPTD documentation, and DNV-ST-C503 standards. Customs data on marine-grade aluminum trade flows and SEC filings from energy infrastructure operators anchored bottom-up and top-down triangulation.
Rate-of-change decomposition across the analysis window isolates volume drivers from price effects in fixed versus offshore versus rooftop installation categories. Segmentation dimensions modeled include product type, installation context, end-use application, and aircraft compatibility tier. CAGRs were derived from installed base growth rates, replacement cycle timing, and regulatory compliance-driven upgrade schedules. Offshore wind buildout pipelines and trauma network expansion plans provided industry-specific forecast inputs.
Caveats apply where aluminum alloy price volatility or specialized welder scarcity could materially shift the outlook for marine helideck delivery timelines. Forecasts reflect assumptions on EASA vertiport rulemaking progression and municipal airspace integration protocols. A model refresh is warranted upon material change in FAA photometric certification queue durations or EU F-Gas Regulation enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airfield Ground Lighting (AGL) Systems Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Airport Passenger Boarding Bridge Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Jet Bridge Market