
 Drone Motors Market | 2026-2036
Drone Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Motors Market Analysis
Software-defined motor tuning subscriptions is recalibrating how OEMs monetize propulsion systems, shifting revenue from hardware sales to recurring performance optimization. DJI Innovates leverages its flight controller ecosystem to bundle motor firmware updates with enterprise service contracts. T-Motor anchors its position in the cinematography segment through specialized high-torque designs for heavy-lift camera rigs. Faulhaber Group differentiates via precision micro-motor architectures that serve inspection-class drones requiring sub-millimeter positional accuracy.
Drone motors are electromechanical devices converting electrical energy into rotational mechanical force through electromagnetic interaction between stator windings and permanent magnet rotors, typically operating at 10,000–30,000 RPM for multirotor applications and requiring thermal management systems to dissipate copper and iron losses during sustained hover. Their primary commercial purpose is generating thrust-to-weight ratios sufficient for payload carriage across varying atmospheric densities and flight envelopes. Brushless DC architectures dominate commercial and military procurement due to superior efficiency and reduced maintenance intervals, while coreless designs occupy niche applications demanding minimal rotor inertia for rapid throttle response. High power and ultra high power ratings are capturing disproportionate margin pools as delivery and heavy-lift segments expand payload requirements beyond fifteen kilograms.
The FAA's Remote ID mandate and EU Drone Strategy 2.0 establish airworthiness baselines that directly influence motor EMI shielding, fail-safe braking, and traceability documentation requirements for type-certified operations. China's CAAC unmanned aviation regulations and NMPA component standards further segment market access between consumer-grade and certified commercial propulsion systems. ISO 21384-3 unmanned aircraft system standards provide harmonized testing protocols that reduce certification friction for cross-border motor suppliers. Stakeholders must monitor evolving battery-motor integration standards and propulsion redundancy requirements as beyond-visual-line-of-sight operations expand into urban air mobility corridors.
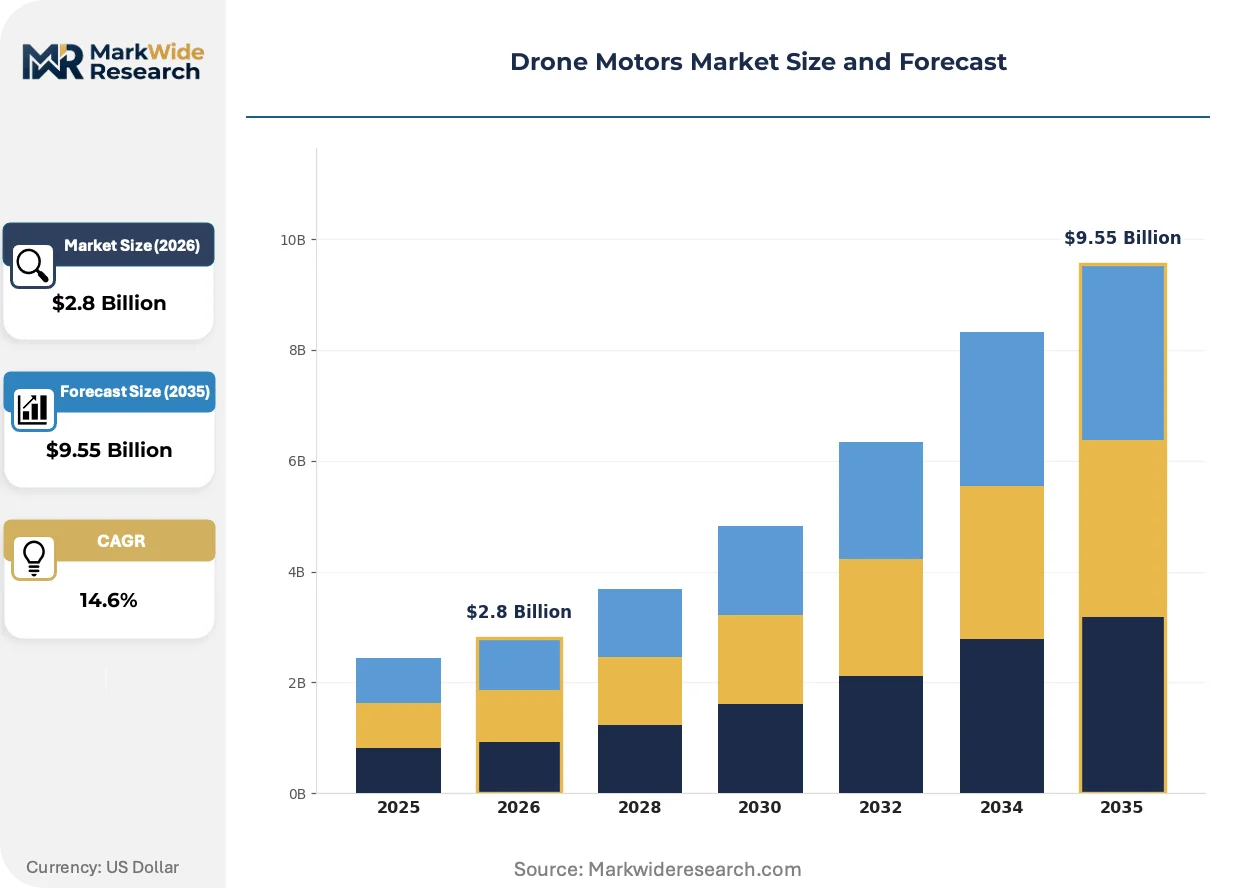
Market Dynamics
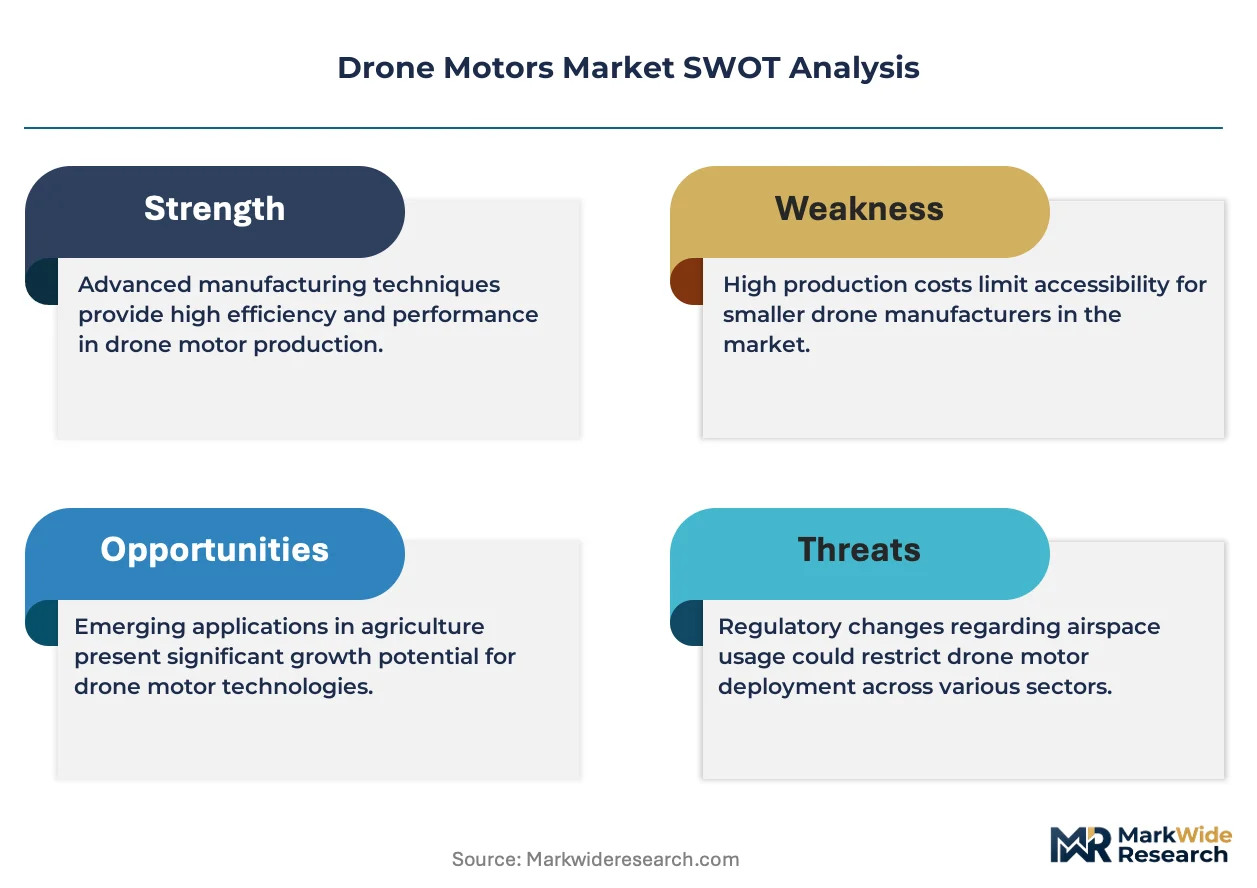
Software-defined motor architectures are compressing hardware refresh cycles while tightening certification requirements from the FAA Reauthorization Act and EU Drone Strategy 2.0 force suppliers to absorb compliance costs into R&D budgets.
Growth Catalysts
- Beyond-visual-line-of-sight mandates:The FAA's Remote ID requirements for type-certified commercial operations are forcing fleet operators to upgrade to EMI-shielded, traceable propulsion systems with fail-safe braking architectures.
- Precision agriculture penetration:Agricultural spraying fleets across Brazil and Southeast Asia are shortening motor replacement cycles as variable-rate application systems demand sustained hover performance under thermal stress.
- Neodymium-iron-boron magnet supply concentration:China's Guangdong manufacturing corridor controls upstream rare-earth magnet and precision winding supply, creating captive demand pull for integrated motor-controller packages.
Market Restraints
- Copper and rare-earth price volatility:Neodymium and copper spot markets expose motor manufacturers to input cost swings that compress gross margins on fixed-price enterprise contracts.
- Single-source winding equipment dependency:Automated precision winding machinery for high-fill-factor stators concentrates among German and Japanese capital equipment suppliers, creating capex bottlenecks for capacity expansion.
- Brushless DC thermal ceiling:Sustained high-RPM operation in dense urban air mobility corridors hits permanent magnet demagnetization thresholds, limiting power density for heavy-lift applications.
Strategic Opportunities
- Urban air mobility corridors:Beyond-visual-line-of-sight routes in Dallas, Dubai, and Singapore are creating certified propulsion demand that commands premium pricing for redundancy-integrated motor sets.
- Battery-motor integration standards:ISO 21384-3 harmonization is reducing certification friction for cross-border suppliers able to offer unified propulsion-energy storage architectures.
- Software-defined tuning subscriptions:Firmware-based performance optimization is shifting revenue from one-time hardware sales to recurring service contracts tied to flight controller ecosystems.
Industry Challenges
- Electromagnetic compatibility certification timelines:FAA and EASA type certification for EMI shielding in dense RF environments extends product launch schedules by 18-24 months.
- Thermal management engineering scarcity:Finite talent pools for copper loss modeling and forced-air cooling design in compact form factors constrain R&D throughput for next-generation architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Motors Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless DC, Brushless AC, Coreless, Stepper Application: Aerial Photography, Agriculture, Surveillance, Delivery Power Rating: Low Power, Medium Power, High Power, Ultra High Power End User: Commercial, Military, Emergency Services, Hobbyists |
| Companies Covered | T-Motor, DJI Innovations, XROTOR (Hobbywing), SunnySky Motors, KDE Direct, EMAX, Faulhaber Group, EMRAX, Hacker Motor USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Motors Market Emerging Trajectories
Active thermal management and embedded sensor fusion are redefining motor reliability benchmarks while regulatory mandates force hardware-software co-design approaches that favor integrated platform vendors over component specialists.
Integrated temperature and vibration sensing within stator windings is automating predictive maintenance scheduling for commercial drone fleets. Agricultural operators in Brazil and Southeast Asia are deploying these sensorized motors to preempt thermal failures during extended spraying missions. This capability is automating the shift from scheduled replacement to condition-based motor lifecycle management, compressing aftermarket parts revenue while expanding software service attach rates.
The EU Drone Strategy 2.0 establishes airworthiness baselines that directly dictate EMI shielding specifications and fail-safe braking documentation for type-certified operations. Motor suppliers must now embed traceability systems that satisfy EASA audit requirements from raw magnet sourcing through final assembly. Heavy-lift cinematography and delivery segments face the steepest compliance burden, driving consolidation toward vertically integrated manufacturers with captive certification expertise.
Fleet procurement managers are unbundling motor purchases from airframe OEM contracts to negotiate direct performance guarantees with specialized suppliers. Enterprise operators in precision agriculture and infrastructure inspection are demanding motor-specific MTBF warranties independent of platform vendor coverage. This disintermediation is most pronounced in China's Guangdong corridor, where Shenzhen-based suppliers leverage proximity to magnet and winding sources to offer pricing and customization terms that bypass traditional OEM markups.
Drone Motors Market Segmentation
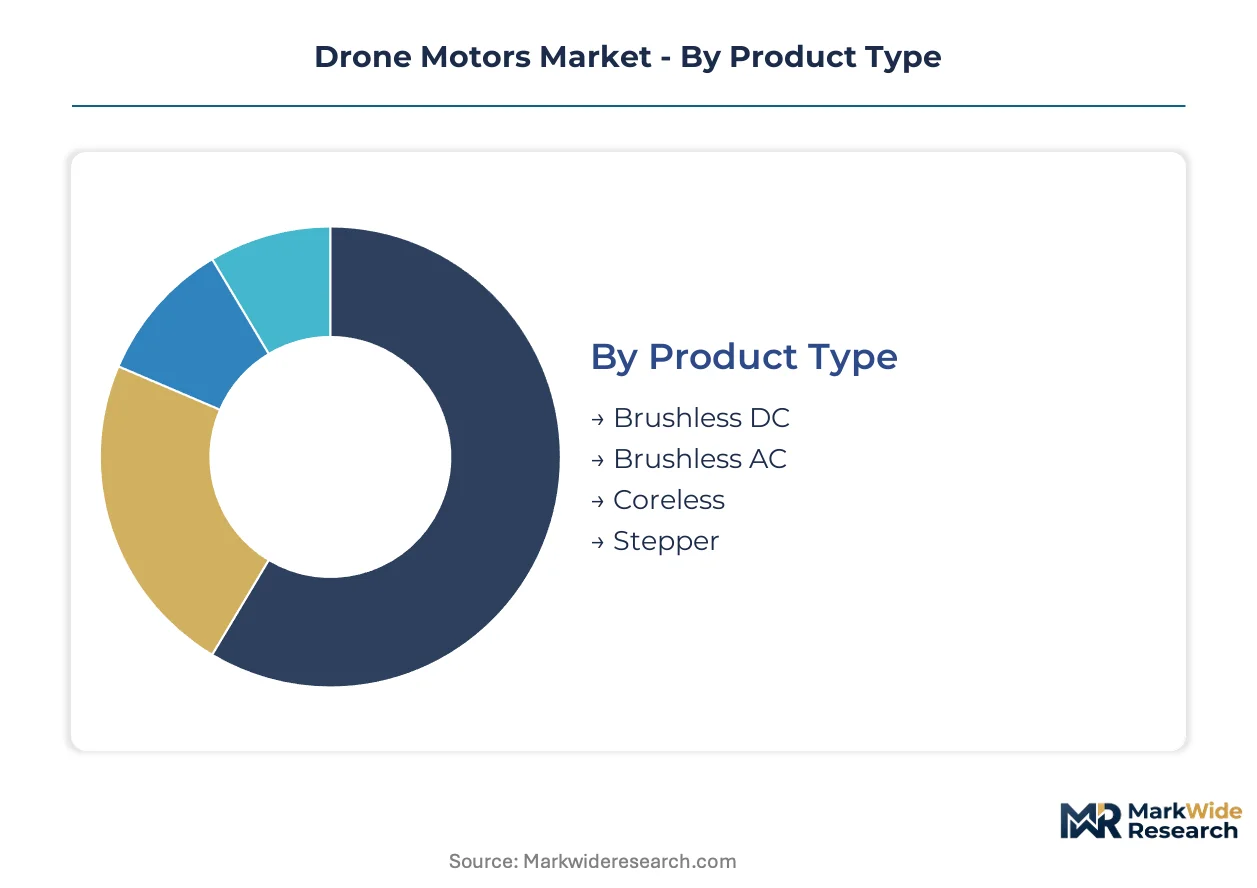
Drone motor segmentation reveals distinct performance-to-price tradeoffs across propulsion architectures. Procurement patterns diverge sharply between certified commercial fleets and consumer-grade applications, with regulatory compliance acting as the primary sorting mechanism for supplier selection.
Product Type:
Brushless DC architectures command premium positioning through efficiency advantages, while coreless and stepper variants occupy cost-optimized niches with distinct torque-response profiles.
- Brushless DC:Permanent magnet rotors paired with electronic commutation deliver 85-92% efficiency at 10,000-30,000 RPM operating ranges. Demand concentrates in agricultural spraying fleets across Brazil and Southeast Asia where sustained hover performance under thermal stress determines fleet uptime. FAA and EASA certification requirements for EMI shielding and fail-safe braking favor established brushless suppliers with captive testing facilities.
- Brushless AC:Sinusoidal drive waveforms reduce torque ripple for cinematography applications requiring sub-millimeter positional stability. Heavy-lift camera rig operators in Los Angeles and London specify these motors for gimbal precision where vibration transmission degrades image quality.
- Coreless:Eliminated iron cores minimize rotor inertia for rapid throttle response in racing and acrobatic drones. Hobbyist segments in Germany and Japan favor these designs despite 15-20% efficiency penalties.
- Stepper:Discrete angular positioning suits inspection-class drones requiring precise camera orientation without feedback encoders. Niche deployment in infrastructure monitoring applications with limited flight controller processing budgets.
Mature deployment sits with Brushless DC. Newer deployment is concentrated in Brushless AC as cinematography demands intensify.
Application:
End-use segmentation tracks payload mass and flight endurance requirements, with precision agriculture and urban delivery representing divergent thermal management challenges.
- Aerial Photography:Cinematography operators prioritize torque stability over peak power to isolate camera payloads from rotor-induced vibration. Los Angeles-based production houses specify motors with integrated vibration dampening for IMAX-certified aerial capture.
- Agriculture:Variable-rate spraying systems demand sustained hover at 80-100% throttle for 15-20 minute mission profiles. Brazilian soybean operators in Mato Grosso and Indonesian palm oil plantations are shortening replacement cycles as precision agriculture adoption deepens.
- Surveillance:Extended loiter requirements favor high-efficiency architectures with redundant winding configurations. Border patrol and critical infrastructure monitoring programs in the UAE and Saudi Arabia specify MIL-STD-810G qualified motors for desert thermal environments.
- Delivery:Urban air mobility corridors in Dallas, Dubai, and Singapore are creating certified propulsion demand with redundancy-integrated motor sets for beyond-visual-line-of-sight operations. Payload requirements exceeding fifteen kilograms are pushing thermal management toward active cooling architectures.
Procurement maturity clusters in Agriculture. Steepest expansion trajectory is concentrated in Delivery as regulatory frameworks for urban air mobility solidify.
Power Rating:
Power segmentation correlates directly with magnet mass and copper fill factor, creating discrete cost structures that separate hobbyist from enterprise procurement tiers.
- Low Power:Sub-200W designs for sub-1kg consumer drones dominate unit volumes. Shenzhen-based suppliers leverage proximity to rare-earth magnet sources for cost positioning in price-sensitive segments.
- Medium Power:200-800W range serves commercial inspection and mapping platforms with 2-5kg payloads. Enterprise operators in Germany and Japan negotiate direct motor warranties independent of airframe OEM coverage.
- High Power:800-2000W architectures enable agricultural spraying and light cargo delivery with 10-15kg payload capacity. Thermal management engineering scarcity constrains R&D throughput for next-generation architectures in this bracket.
- Ultra High Power:Exceeding 2000W for heavy-lift cinematography and urban air mobility applications requiring 20kg+ payload carriage. Permanent magnet demagnetization thresholds limit sustained high-RPM operation in dense urban corridors.
Volume concentration sits with Low Power. Margin expansion is concentrating in Ultra High Power as delivery and heavy-lift segments scale.
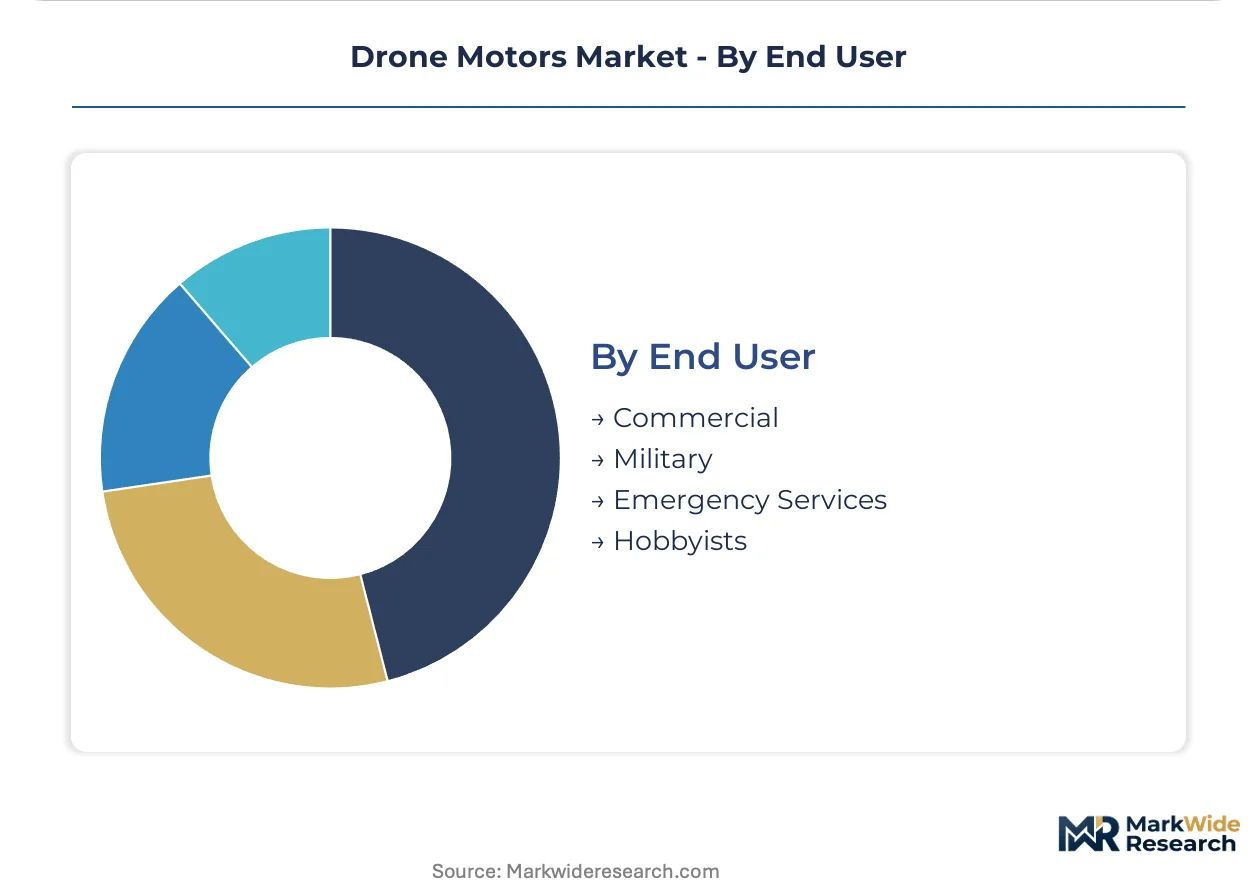
End User:
Customer type determines certification burden and procurement sophistication, with military and emergency services imposing traceability requirements that exclude consumer-grade suppliers.
- Commercial:Fleet operators in precision agriculture and infrastructure inspection unbundle motor purchases from platform OEM contracts. Direct procurement from Guangdong corridor suppliers bypasses traditional markups.
- Military:Defense procurement requires full supply chain traceability from raw magnet sourcing through final assembly. ITAR and EAR regulations restrict supplier pools to domestic or allied-country manufacturers.
- Emergency Services:Search-and-rescue and firefighting applications demand fail-safe braking and EMI shielding for operation in contested RF environments. ISO 21384-3 harmonization reduces certification friction for cross-border suppliers.
- Hobbyists:Price-sensitive segment with minimal regulatory exposure. Shenzhen direct-to-consumer channels dominate with unbundled motor-controller packages.
Procurement standardization sits with Military. Procurement flexibility is expanding fastest in Commercial as fleet operators develop direct supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Guangdong corridor concentrates upstream magnet and winding supply, while demand clusters in precision agriculture hubs across Brazil and Southeast Asia. Regulatory divergence between FAA Remote ID mandates and EU Drone Strategy 2.0 is fragmenting certification pathways.
United States
Beyond-visual-line-of-sight delivery corridors in Dallas and Phoenix are driving certified propulsion procurement for urban air mobility. FAA Remote ID requirements mandate EMI-shielded motor architectures with fail-safe braking documentation. Los Angeles production houses anchor cinematography demand for torque-stable designs isolating camera payloads from vibration.
China
Shenzhen-based suppliers leverage captive rare-earth magnet access to control upstream winding and controller integration. CAAC unmanned aviation regulations segment market access between consumer-grade and certified commercial systems. The Pearl River Delta manufacturing cluster exports integrated motor-controller packages to agricultural operators in Southeast Asia.
Brazil
Soybean spraying fleets in Mato Grosso are shortening motor replacement cycles as variable-rate application systems deepen precision agriculture adoption. ANVISA coordinates with aviation regulators on aerial application safety standards. São Paulo-based distributors negotiate direct procurement terms bypassing traditional OEM markups.
Germany
Industrial inspection operators demand motor-specific MTBF warranties independent of platform vendor coverage. KBA and EASA alignment on type certification reduces friction for cross-border motor suppliers. Bavaria's automation engineering base supplies precision winding equipment for high-fill-factor stator production.
Japan
Racing and acrobatic drone hobbyists favor coreless designs despite efficiency penalties for rapid throttle response. METI standards for component traceability influence procurement specifications for commercial fleet operators. Tokyo-area electronics distributors channel Shenzhen-sourced motors into domestic modification markets.
Drone Motors Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the propulsion value chain. Shenzhen-based integrated manufacturers absorb magnet sourcing and winding operations in-house, while European specialists outsource controller firmware development. Three archetypes dominate: vertically integrated Asian manufacturers with captive rare-earth supply, precision engineering houses serving certified commercial segments, and hobbyist-focused brands competing on price. Consolidation pressures concentrate among mid-tier suppliers lacking scale for certification investment or niche specialization for premium segments.
Among Asian integrated manufacturers, DJI Innovations and T-Motor exemplify contrasting strategic positions. DJI leverages its flight controller ecosystem to bundle motor firmware with enterprise service contracts, capturing recurring revenue streams. T-Motor occupies a specialization anchor in cinematography propulsion, where heavy-lift torque requirements command pricing premiums. European precision engineering is represented by Faulhaber Group, whose micro-motor architectures serve inspection-class applications demanding sub-millimeter accuracy. These three anchors illustrate how geographic supply concentration, certification capability, and application focus segment competitive positioning.
| Leading Market Players |
|---|
| T-Motor |
| DJI Innovations |
| XROTOR (Hobbywing) |
| SunnySky Motors |
| KDE Direct |
| EMAX |
| Faulhaber Group |
| EMRAX |
| Hacker Motor USA |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between FAA type-certified commercial systems and unregulated consumer-grade motors manifests in pricing spreads exceeding three-to-one, with EMI shielding and traceability documentation costs concentrating procurement power among Guangdong corridor suppliers who absorb compliance engineering into integrated motor-controller bundles.
Pricing Analysis
Margin tightening in ultra high power brackets reflects thermal management engineering scarcity and permanent magnet demagnetization thresholds that constrain R&D throughput. Three-tier pricing structure across certified commercial, enterprise uncertified, and hobbyist economy levels tracks FAA and EASA compliance burdens, with Brazilian agricultural fleet operators negotiating direct procurement terms that bypass traditional OEM markups. Cost-down pressure on medium power architectures accelerates because Shenzhen-based suppliers leverage captive rare-earth magnet access to undercut European precision winding houses.
Supply Chain Analysis
Neodymium-iron-boron magnet supply rests on Chinese rare-earth processing dominance, German and Japanese precision winding equipment, and Malaysian copper refining corridors. Raw material dependencies span neodymium concentrates, high-purity copper cathode, and thermal interface materials for active cooling architectures. Single-source vulnerability concentrates in automated stator winding machinery where two equipment houses control high-fill-factor production capacity. Distribution runs through direct enterprise procurement channels in Brazil and Southeast Asia alongside Shenzhen-export integrated packages for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FAA Reauthorization Act's Remote ID mandates erect a cost-of-compliance barrier that favors incumbents with captive certification expertise and integrated testing facilities, compressing margins for component specialists unable to absorb eighteen-to-twenty-four-month EMI certification timelines.
For Market Incumbents: Acquire thermal management engineering talent pools to preempt capability scarcity constraining next-generation high power architecture development. Consolidate winding operations in Guangdong corridor facilities to neutralize rare-earth price volatility exposure. Defend against fleet procurement disintermediation by embedding predictive maintenance firmware that raises switching costs for agricultural operators in Mato Grosso and Indonesian palm oil regions. For New Entrants and Emerging Players: EU Drone Strategy 2.0 in Europe opens a window for specialized EMI shielding component suppliers serving cinematography and urban air mobility segments facing steepest compliance burdens. Target condition-based motor lifecycle management software attach rates where incumbent hardware margins are compressing. Penetrate through direct warranty terms independent of platform OEM coverage, mirroring procurement patterns emerging in Germany's industrial inspection sector. For Investors and Strategic Acquirers: Exit pathways concentrate in vertical integration plays combining magnet sourcing with firmware development capabilities. Long-term viability favors manufacturers with captive Guangdong corridor production and EASA audit-ready traceability systems. Watch FAA beyond-visual-line-of-sight corridor expansion in Dallas, Dubai, and Singapore as inflection signal for certified propulsion demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment in EMI Shielding | FAA and EASA type certification creates eighteen-month moats against component specialists lacking testing facilities. |
| Software-Defined Motor Tuning Launch | Firmware subscription models shift revenue from hardware sales to recurring service contracts tied to flight controller ecosystems. |
| Guangdong Corridor Capacity Expansion | Proximity to Shenzhen magnet and winding sources enables pricing terms that bypass traditional OEM procurement markups. |
| Predictive Maintenance Sensor Integration | Embedded temperature and vibration sensing automates condition-based lifecycle management for Brazilian agricultural fleets. |
| Urban Air Mobility Partnership | Redundancy-integrated motor sets for Dallas and Dubai corridors command premium pricing in certified propulsion procurement. |
Methodological Framework
Trade databases, regulatory filings, and component supplier disclosures formed the secondary backbone, cross-referenced with primary interviews involving fleet procurement managers at Brazilian agricultural operators, EMI compliance engineers at EASA-notified bodies, thermal management specialists at German precision motor houses, and Guangdong corridor manufacturing directors. Bottom-up and top-down triangulation validated segment-level assumptions against customs data for rare-earth magnet flows and stator winding equipment import records.
Bottom-up modeling built from individual product type power ratings, application thermal profiles, and end-user certification requirements, while top-down verification anchored against national unmanned aviation fleet registrations and precision agriculture adoption curves across the analysis window. Segmentation dimensions spanned propulsion architecture, payload mass tier, geographic regulatory cluster, and procurement channel structure. CAGRs derived from weighted average replacement cycle compression in agricultural spraying fleets and urban air mobility corridor activation schedules.
Caveats apply where neodymium spot price volatility or FAA certification timeline extensions could materially shift the outlook for fixed-price enterprise contracts. Forecasts reflect assumptions around thermal management engineering talent availability and rare-earth processing capacity expansion. A small set of triggers—EMI shielding standard revisions, beyond-visual-line-of-sight route density, and magnet supply chain restructuring—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Europe Small UAV Market
UAV
Delivery Drones Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Racing Drone Market
UAV
Europe Drones Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Airborne Digital Battlefield Market
UAV
Ultra-Long Endurance Drone Market
UAV
North America Tactical UAV Market
UAV
Drone Delivery Services Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Global Renewable Drones Market
UAV
Fuel Cell UAV Market
UAV
Global Smartphone Controlled Drone Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Drone Powered Business Solutions Market