
 Airborne High Frequency Radio Market | 2026-2036
Airborne High Frequency Radio Market Size, Share, and Industry Trends Forecast 2026-2036
Airborne High Frequency Radio Market Insights
MIL-STD-188-141B certification is redrawing supplier eligibility for military airborne HF programs. L3Harris Technologies leverages its software-defined radio portfolio to sustain positions in tactical air platforms. Thales Group anchors European defense procurement through national industrial participation requirements.
Airborne high frequency radio denotes avionics equipment transmitting and receiving signals in the 3-30 MHz spectrum through skywave and surface-wave propagation, with typical output power ranging from 100W to 1kW for long-haul communication beyond VHF/UHF line-of-sight limits. Transceivers and multi-band configurations capture the dominant share of hardware expenditure as forces consolidate box counts and reduce antenna farms. Military Communications applications generate the strongest demand pull, while Search and Rescue platforms represent a specialized niche with distinct environmental ruggedization requirements.
FAA airworthiness standards, MIL-STD-461 electromagnetic compatibility requirements, and NATO STANAG 5066 interoperability protocols collectively shape product development roadmaps and procurement gatekeeping. The EU AI Act and CSRD reporting obligations are beginning to influence supply chain due diligence for European defense contractors sourcing HF subsystems. Stakeholders must monitor spectrum allocation debates at WRC conferences and allied interoperability mandates to anticipate platform integration requirements.
Market Dynamics
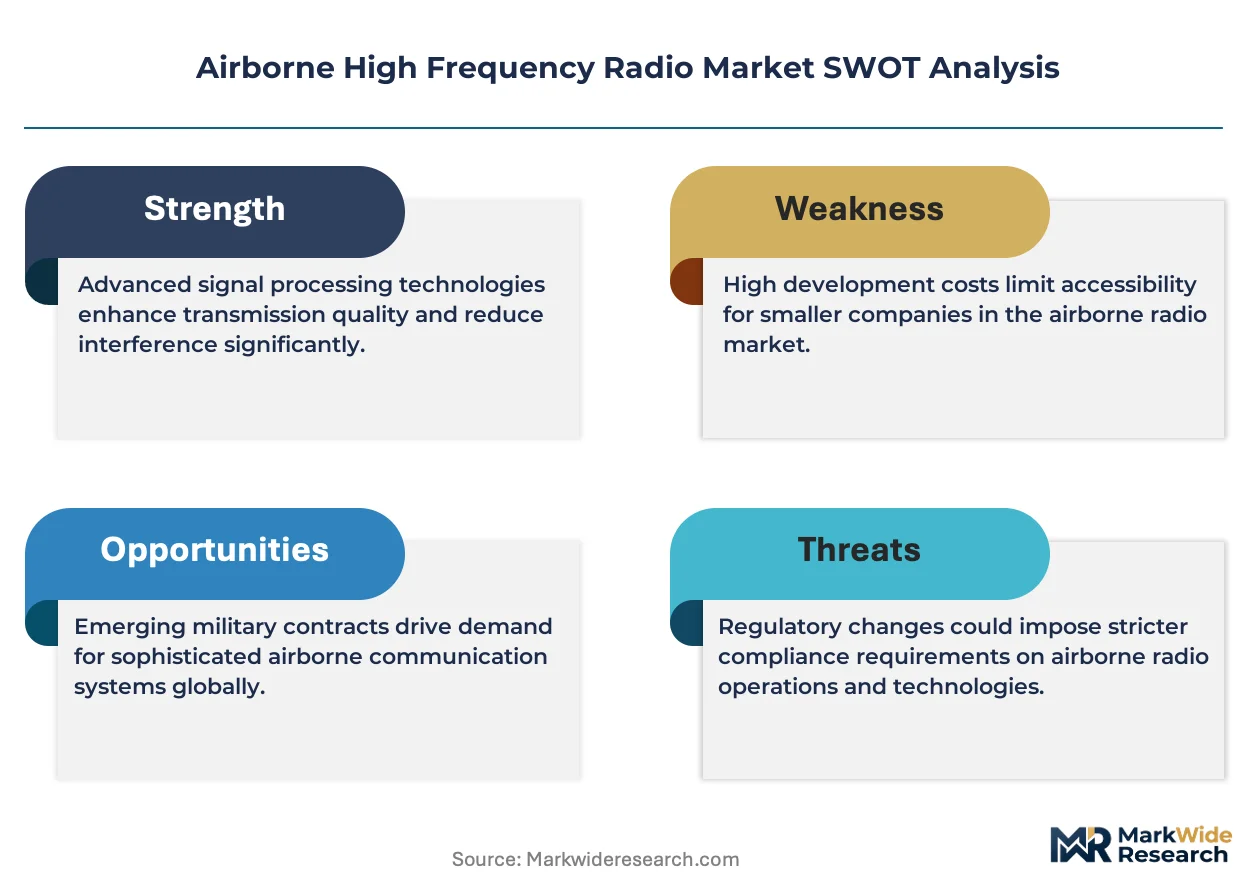
Software-defined radio architectures are fragmenting the installed base of legacy analog HF transceivers across NATO air fleets, forcing suppliers to requalify platforms under stricter MIL-STD-188-141B certification regimes.
Growth Catalysts
- Contested electromagnetic doctrine:The Department of Defense mandates resilient beyond-line-of-sight networks for Pacific theater operations. HF skywave propagation retains strategic value when satellite links face jamming.
- NATO STANAG 5066 interoperability:Allied procurement specifications require common data link protocols. Standardization reduces integration costs for multinational airborne platforms.
- Antenna consolidation:Multi-band transceivers eliminate dedicated antenna farms. Airframe weight reduction drives hardware refresh cycles in tactical airlift and maritime patrol segments.
Market Restraints
- GaN and GaAs semiconductor supply:Gallium nitride and gallium arsenide substrates for high-power RF amplification concentrate in East Asian foundries. Geopolitical export controls threaten component availability.
- MIL-STD-461 electromagnetic compatibility:Conducted emissions and susceptibility testing adds eighteen to twenty-four months to airworthiness qualification. Small suppliers lack anechoic chamber access.
- Satellite communications substitution:Commercial SATCOM leases offer higher bandwidth for non-contested routes. Budget-conscious operators defer HF modernization where link resilience is not mission-critical.
Strategic Opportunities
- Search and Rescue platform specialization:Canadian and Australian coastal patrol aircraft require environmental ruggedization beyond standard military specifications. Salt corrosion resistance and rapid frequency agility differentiate supplier offerings.
- EU AI Act supply chain due diligence:European defense contractors must document algorithmic transparency in software-defined radio firmware. Early compliance creates qualification advantages for subsystem vendors.
- Convergence with cognitive radio:Machine learning-enabled spectrum sensing merges with HF transceivers. Dynamic frequency selection automates link establishment in ionospheric disturbance conditions.
Industry Challenges
- RF systems engineering talent:Skywave propagation modeling and antenna coupling expertise retire faster than universities replenish pipelines. Defense primes poach from commercial wireless sectors.
- Legacy analog integration:Hybrid architectures bridging vacuum-tube-era transmitters with digital baseband processors demand custom interface hardware. Platform-specific engineering erodes economies of scale.
- WRC spectrum allocation uncertainty:International Telecommunication Union debates threaten exclusive military HF bands. Manufacturers face redesign risk if civil secondary use expands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airborne High Frequency Radio Market |
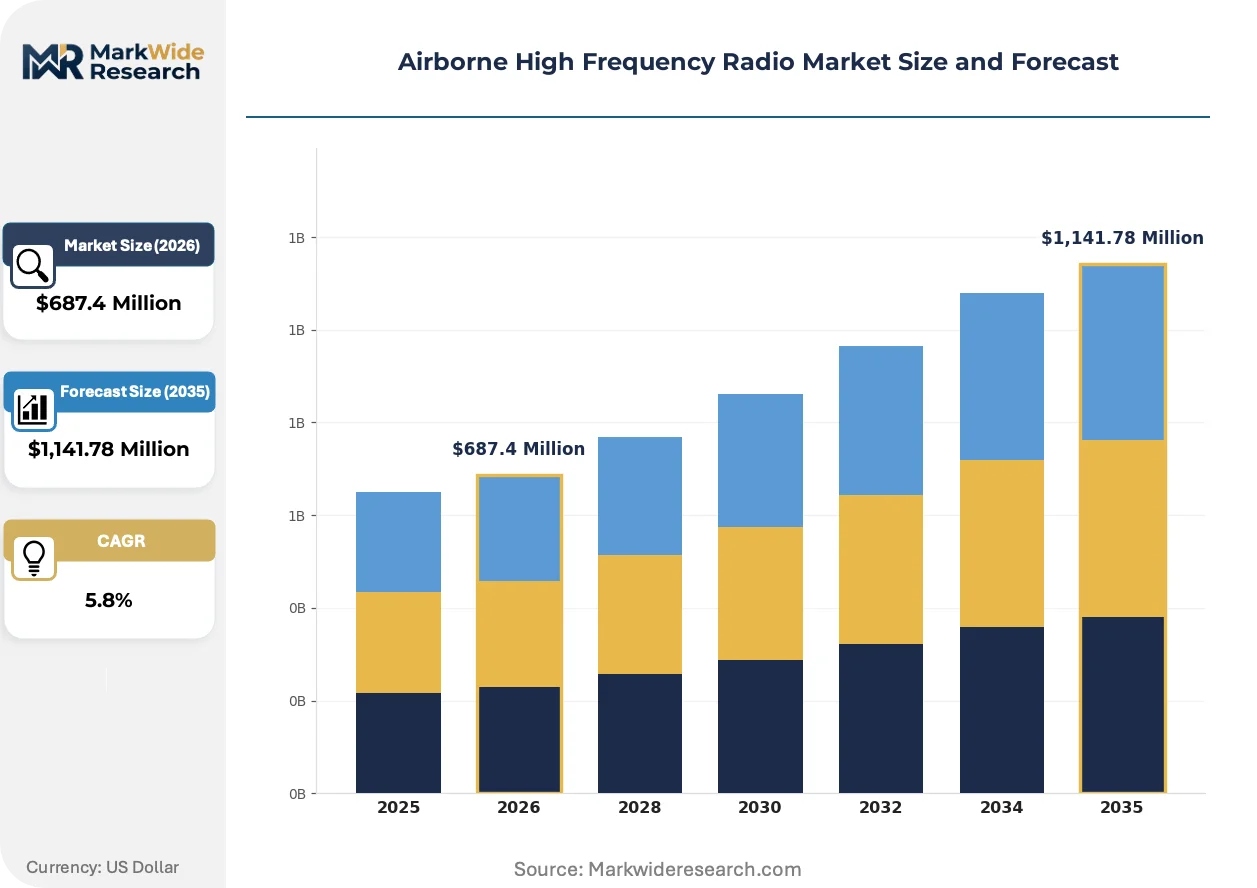
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,141.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transceivers, Receivers, Transmitters, Signal Processors, Antenna Systems Frequency Band: 3-10 MHz, 10-18 MHz, 18-30 MHz, Multi-Band Platform: Unmanned Aerial Vehicles, Military Aircraft, Commercial Aircraft, Helicopters, Research Aircraft Application: Military Communications, Search and Rescue, Weather Monitoring, Air Traffic Control, Disaster Management |
| Companies Covered | L3Harris Technologies, Thales Group, BAE Systems, Raytheon Technologies Corporation, Collins Aerospace, Leonardo S.p.A., Rohde & Schwarz, Northrop Grumman, Elbit Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airborne High Frequency Radio Market Trends and Innovations
Active electronically scanned arrays and cognitive processing are redefining airborne HF link reliability. Platform integrators now prioritize software upgrade paths over hardware refresh cycles.
Software-defined radio architectures are fragmenting procurement patterns across military avionics programs. Digital signal processing replaces analog filtering in 3-30 MHz transceivers. Tactical air platform integrators in the United States and United Kingdom now specify firmware-upgradeable waveforms rather than fixed-function hardware. This capability compression forces legacy suppliers to restructure product lines around open architecture standards.
The EU CSRD reporting obligation is reshaping defense contractor sourcing decisions. European airborne HF radio assemblers must now document Scope 3 emissions from semiconductor foundries and rare earth magnet suppliers. German and French prime contractors are consolidating vendor lists to reduce audit complexity. Subsystem suppliers with verified carbon accounting gain preferential placement in platform bids.
Platform-as-a-service contracting is altering aftermarket revenue structures. United States Air Force sustainment organizations now lease transceiver capacity rather than purchasing hardware outright. L3Harris and Thales compete on mean-time-between-failure guarantees rather than unit price. This shift concentrates in strategic airlift and tanker fleets where operational availability metrics dominate total cost calculations.
Airborne High Frequency Radio Market Segmentation
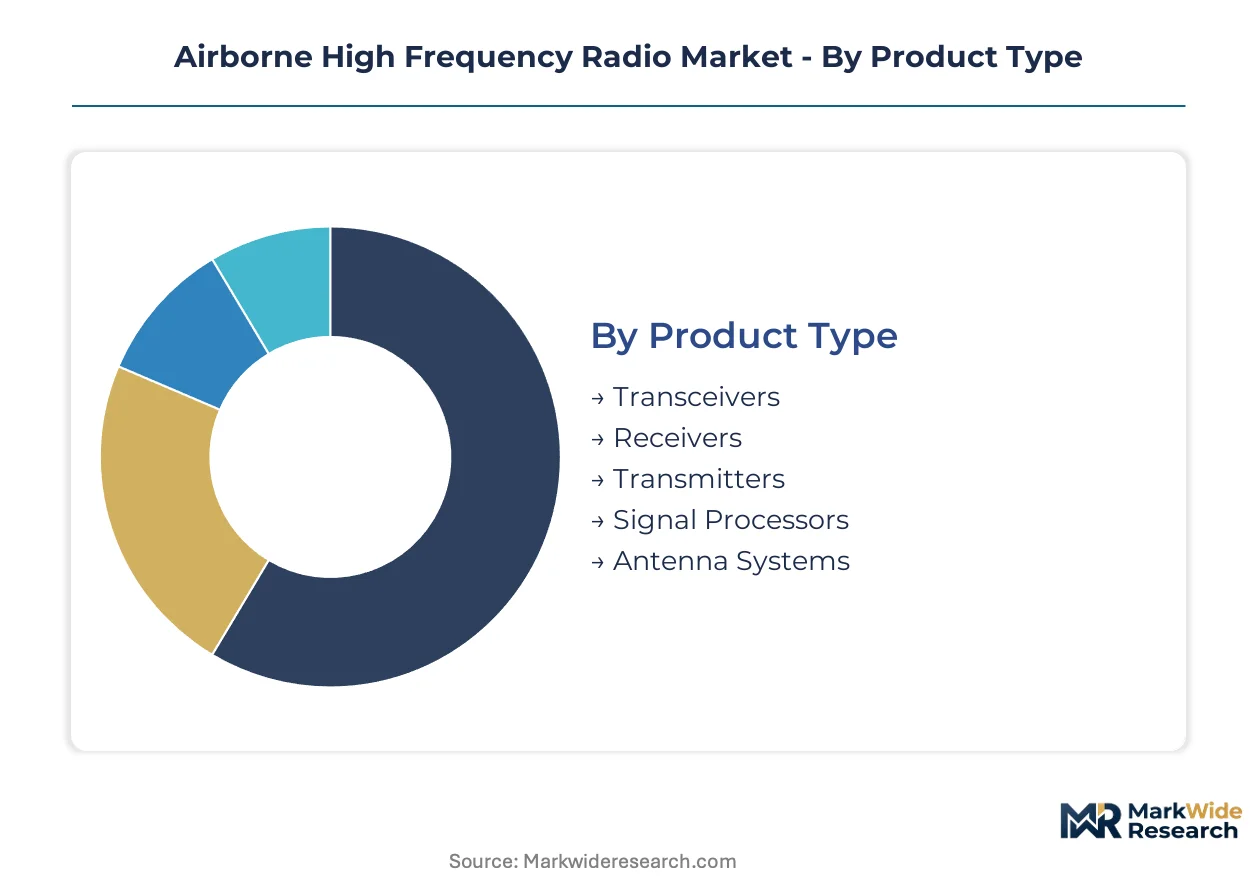
Segmentation in airborne HF radio markets reveals how procurement priorities diverge across mission profiles and platform architectures. Defense contractors align product portfolios with specific frequency bands and installation constraints rather than pursuing universal solutions.
Product Type:
Domestic procurement in the United States concentrates on integrated transceiver systems, while European and Asia-Pacific buyers increasingly source antenna systems and signal processors as separate line items for platform customization.
- Transceivers:Combined transmit-receive units with 100W to 1kW output power dominate tactical aircraft retrofits. United States Air Force tanker and airlift fleets drive procurement volume as MIL-STD-188-141B certification deadlines approach.
- Antenna Systems:Multi-band couplers and automatic antenna tuners enable consolidated installations. NATO STANAG 5066 interoperability mandates accelerate replacement of dedicated single-band antenna farms on maritime patrol platforms.
- Signal Processors:Digital baseband modules perform modem functions and encryption.
- Receivers:Standalone units serve electronic intelligence and monitoring roles.
- Transmitters:High-power amplifiers for ground-based relay applications.
Transceivers command the established base. The steepest expansion runs through antenna systems.
Frequency Band:
Cost tiering separates military-grade multi-band units from single-band commercial alternatives, with price differentials exceeding threefold for equivalent power ratings.
- Multi-Band:Software-defined architectures span 3-30 MHz without hardware switching. Department of Defense Pacific theater requirements prioritize frequency agility for contested electromagnetic operations.
- 3-10 MHz:Lower HF spectrum supports long-haul skywave links during ionospheric disturbance conditions. Canadian and Australian coastal patrol aircraft specify rapid frequency hopping in this band for Search and Rescue coordination.
- 10-18 MHz:Mid-range propagation for continental coverage.
- 18-30 MHz:Shorter range with reduced atmospheric noise.
Multi-Band configurations dominate new procurement. The 3-10 MHz segment expands most quickly in specialized maritime applications.
Platform:
Application maturity varies sharply: military fixed-wing programs run decade-long refresh cycles while unmanned platforms iterate on 18-24 month timelines.
- Military Aircraft:Strategic airlift, tanker, and maritime patrol fleets carry the installed base volume. FAA and MIL-STD-461 certification requirements extend development timelines to 24-36 months.
- Unmanned Aerial Vehicles:Reduced size-weight-power constraints favor solid-state miniaturization. United States Navy MQ-4C Triton and comparable platforms specify embedded HF for beyond-line-of-sight relay when satellite links degrade.
- Helicopters:Rotary-wing installations face unique vibration and rotor modulation challenges.
- Commercial Aircraft:Regulatory mandates for over-ocean communication drive limited adoption.
- Research Aircraft:Polar and atmospheric science platforms require specialized environmental ruggedization.
Military Aircraft carry the volume base. Unmanned Aerial Vehicles gain share fastest as software-defined architectures shrink hardware footprints.
Application:
Customer type separation distinguishes defense procurement with classified requirements from civil agencies operating under transparent budget processes.
- Military Communications:Beyond-line-of-sight networks for contested environments represent the core revenue pool. NATO allied interoperability specifications standardize data link protocols across member nation fleets.
- Search and Rescue:Environmental ruggedization exceeds standard military specifications. Canadian Coast Guard and Australian Border Force coastal patrol programs specify salt corrosion resistance and rapid link establishment protocols.
- Air Traffic Control:Oceanic and remote area coverage supplements VHF line-of-sight networks.
- Disaster Management:Emergency response coordination when infrastructure fails.
- Weather Monitoring:Hurricane hunter and research aircraft telemetry relay.
Military Communications anchors procurement volume. Search and Rescue climbs fastest as coastal nations expand sovereign patrol capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement incentives in NATO member states are accelerating airborne HF radio modernization timelines. Military doctrine shifts toward contested electromagnetic operations favor resilient beyond-line-of-sight communication networks. National industrial participation requirements shape supplier selection across allied air fleets.
United States
Department of Defense Pacific theater requirements drive demand for frequency-agile transceivers in strategic airlift and tanker fleets. FAA and MIL-STD-461 certification mandates extend development timelines to 24-36 months for platform integration. The aerospace and defense industrial base concentrates around Washington DC metro, Greater Boston, and Southern California clusters where prime contractors coordinate subsystem sourcing.
Germany
Bundeswehr maritime patrol aircraft procurement prioritizes NATO STANAG 5066 interoperability for allied coordination. EU CSRD reporting obligations and the EU AI Act impose supply chain due diligence requirements on defense contractors sourcing HF subsystems. The Baden-Württemberg and Bavaria regions host system integrators managing pan-European platform programs.
United Kingdom
Royal Air Force fleet modernization emphasizes software-defined radio architectures for firmware-upgradeable waveforms. Ministry of Defence procurement specifications align with NATO standardization protocols for multinational interoperability. The South East England and Midlands aerospace corridors concentrate avionics engineering and qualification testing capabilities.
France
Dassault Aviation and maritime patrol platform programs sustain demand for multi-band HF configurations with rapid frequency hopping. National industrial participation requirements anchor Thales Group positions in domestic and export markets. The Île-de-France and Provence-Alpes-Côte d'Azur regions host prime contractor headquarters and integration facilities.
Australia
Border Force and Coast Guard coastal patrol aircraft specify environmental ruggedization exceeding standard military specifications for salt corrosion resistance. Sovereign capability policies prioritize local industrial participation in search and rescue platform communications suites. The Victoria and Queensland aerospace maintenance clusters support regional fleet sustainment and upgrade cycles.
Airborne High Frequency Radio Market Competitive Landscape
Listed leaders compete with private specialists across defense contracting channels, creating a tiered structure where scale advantages meet national champion protections. The vendor base fragments across platform-specific qualification regimes, with prime contractors maintaining long-term supplier relationships. Two strategic archetypes dominate: diversified aerospace conglomerates with software-defined radio portfolios, and specialized RF subsystem houses with deep military certification expertise. Competitive moves center on platform-as-a-service contracting and open architecture standard adoption.
Within the diversified conglomerate tier, L3Harris Technologies and Thales Group exemplify scale-driven positions spanning tactical air platforms and maritime patrol systems. BAE Systems anchors the British national champion archetype, occupying a position shaped by UK Ministry of Defence procurement preferences. These three entities represent the dominant competitive anchors, with their geographic footprints and corporate structures reflecting the national industrial participation requirements that structure defense procurement across NATO markets.
| Leading Market Players |
|---|
| L3Harris Technologies |
| Thales Group |
| BAE Systems |
| Raytheon Technologies Corporation |
| Collins Aerospace |
| Leonardo S.p.A. |
| Rohde & Schwarz |
| Northrop Grumman |
| Elbit Systems |
| Others |
Pricing and Supply Chain Analysis
Long production runs for MIL-STD-188-141B certified transceivers generate steep scale economies at L3Harris and Thales facilities, compressing unit costs for qualified suppliers while erecting price floors that exclude uncertified competitors from military procurement channels.
Pricing Analysis
Certification level creates the primary spread between qualified and unqualified suppliers. Three-tier pricing structure across full-platform systems, modular subsystems, and component spares reflects integration depth and after-sales bundling. Pricing pressure stems from platform-as-a-service contracting at United States Air Force sustainment organizations, which shifts buyer focus from unit acquisition to availability guarantees. Small RF subsystem houses exhibit highest price sensitivity due to anechoic chamber access costs, while primes with captive test facilities maintain margin buffers.
Supply Chain Analysis
Container availability constraints on transpacific lanes from Taiwanese and South Korean foundries delay GaN and GaAs semiconductor deliveries to North American assembly plants. Raw material dependencies center on gallium nitride substrates, rare earth magnets for antenna couplers, and high-purity copper for RF shielding. Single-source vulnerability concentrates in East Asian foundries subject to export control uncertainty. Distribution runs through defense prime contractor vendor-managed inventory systems rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through platform-as-a-service consolidation at United States Air Force and NATO joint procurement programs, fragmenting supplier leverage across fewer contracting vehicles with stricter performance guarantees.
For Market Incumbents: Fortify positions through backward integration into GaN semiconductor sourcing and expansion of MIL-STD-461 test chamber capacity in Southern California clusters. Satellite communications substitution threatens HF modernization budgets; certification investment in EU AI Act algorithmic transparency protocols creates qualification barriers against emerging software-defined radio competitors. For New Entrants and Emerging Players: FAA Part 23 fast-track certification for commercial derivative platforms offers entry path around military qualification bottlenecks. Search and Rescue platform specialization in Australian and Canadian coastal patrol programs presents most penetrable white-space, with environmental ruggedization requirements distinct from standard military specifications. Go-to-market angle should emphasize salt corrosion resistance testing and rapid frequency agility demonstrations. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors software-defined radio specialists with firmware-upgradeable waveform portfolios over legacy analog hardware suppliers. Long-term viability rests on open architecture standard adoption and cognitive radio convergence. Acquisition target archetype: mid-tier RF subsystem houses with deep MIL-STD-188-141B certification expertise and established prime contractor relationships. Signal to watch: WRC spectrum allocation debates threatening exclusive military HF band assignments.| Strategic Initiative | Industry Significance |
|---|---|
| MIL-STD-188-141B Certification Investment | Qualification barrier secures access to United States Air Force tanker and airlift fleet procurement. |
| GaN Semiconductor Backward Integration | Captive supply of high-power RF amplification substrates insulates against East Asian export controls. |
| EU AI Act Compliance Documentation | Algorithmic transparency in firmware creates preferential placement with German and French prime contractors. |
| Search and Rescue Platform Specialization | Salt corrosion resistance and rapid link establishment differentiate offerings for Australian Border Force. |
| Platform-as-a-Service Contracting Shift | Mean-time-between-failure guarantees replace unit price competition in strategic airlift sustainment. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Department of Defense budget justifications, NATO STANAG documentation, and FAA certification databases. Primary interviews engaged platform integration engineers at defense primes, RF systems procurement officers at military sustainment organizations, and antenna subsystem specialists at tier-two suppliers. Secondary validation drew from MIL-STD-188-141B test reports, EU CSRD disclosure filings, and WRC spectrum allocation proceedings. Bottom-up unit shipment estimates triangulated against top-down defense budget allocation analysis.
Segmentation dimensions modeled span product type, frequency band configuration, platform architecture, and application mission profile across the projection horizon. CAGRs derived from installed base replacement cycles, procurement timeline analysis, and platform delivery schedules. Industry-specific forecast inputs incorporated ionospheric propagation modeling advances and cognitive radio technology readiness levels.
Decision-makers should treat outputs as directional under assumptions of sustained Pacific theater contested electromagnetic doctrine and stable NATO STANAG 5066 interoperability mandates; material deviation would warrant model refresh. Specific risk factors include WRC spectrum reallocation, GaN foundry export restrictions, and satellite communications substitution acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Navigation and Communication
Asia-Pacific Air Traffic Management Market
Aircraft Navigation and Communication
Airborne Radars Market
Aircraft Navigation and Communication
Ground to Air on-Board Connectivity Market
Aircraft Navigation and Communication
5G in Aviation Market
Aircraft Navigation and Communication
Europe Inertial Systems Market
Aircraft Navigation and Communication
Helicopter Meteorological Software Market
Aircraft Navigation and Communication
Air-Based Tactical Data Link Market
Aircraft Navigation and Communication
Aircraft Communication System Market
Aircraft Navigation and Communication
Global Drone Navigation System Market
Aircraft Navigation and Communication
Aircraft Turn Coordinator Market
Aircraft Navigation and Communication
Middle-East and Africa Air Traffic Management Market
Aircraft Navigation and Communication
Global Air Traffic Control Equipment Market
Aircraft Navigation and Communication
Aircraft Navigation System Market
Aircraft Navigation and Communication
Global Aviation Mapping Software Market
Aircraft Navigation and Communication
Air Traffic Management Market
Aircraft Navigation and Communication
Aircraft Navigation Software Market