
 Jet Bridge Market | 2026-2036
Jet Bridge Market Size, Share, and Industry Trends Forecast 2026-2036
Jet Bridge Market Analysis
Aluminum honeycomb composites are rebalancing weight-to-strength economics in jet bridge manufacturing, enabling longer cantilever spans without steel reinforcement penalties. JBT AeroTech leverages its North American installed base to sustain aftermarket service contracts across legacy hydraulic fleets. CIMC-Tianda Holdings anchors its cost position through captive steel fabrication and in-house production of electrical drive trains. Thyssenkrupp Airport Systems differentiates via precision docking automation that reduces aircraft turnaround times.
A jet bridge is a covered, enclosed passenger boarding bridge that connects an airport terminal gate directly to an aircraft door, typically spanning 15 to 35 meters with vertical adjustment ranges of ±3 meters to accommodate varying fuselage heights. The structure employs steel or aluminum truss frameworks with climate-controlled tunnel sections, powered by electrical, hydraulic, or pneumatic elevation and extension mechanisms to enable all-weather, level-entry boarding. Fixed jet bridges dominate mature hub airports where gate geometries are standardized, while mobile jet bridges represent the fastest-growing configuration category as regional airports prioritize apron flexibility over permanent infrastructure. Electrical systems are displacing hydraulic actuators across new procurement specifications, driven by reduced maintenance intervals and elimination of fluid leak hazards on tarmacs.
The FAA's Advisory Circular on passenger boarding bridge structural integrity shapes North American procurement standards, while the EU's Machinery Directive and CE marking requirements govern European market access for automated docking systems. China's GB standards for airport ground support equipment and India's BIS certification for structural steel components create parallel compliance pathways for equipment suppliers. Stakeholders must monitor how electrical system standardization across ICAO guidelines reshapes supplier qualification criteria and aftermarket parts compatibility.
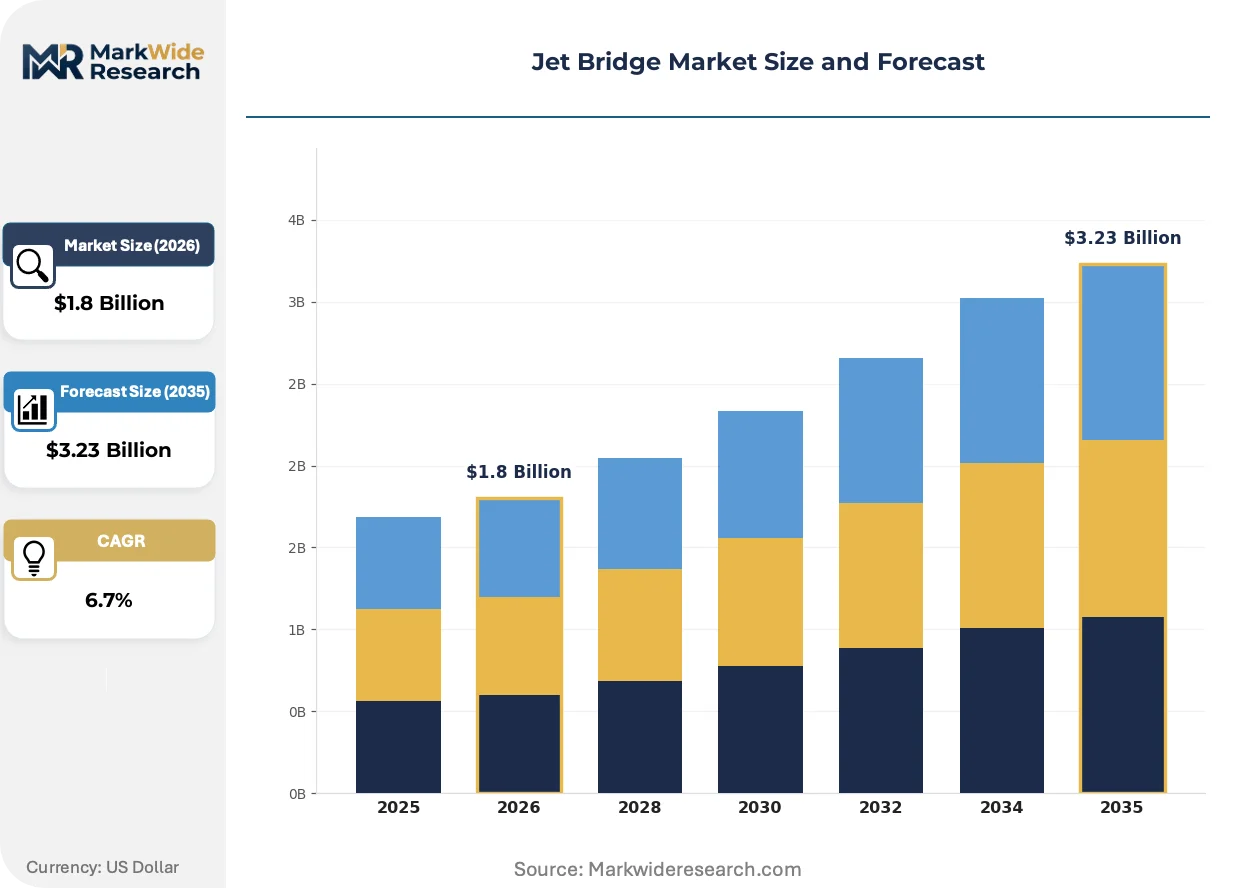
Market Dynamics
Electrical drive systems are compressing maintenance intervals and eliminating hydraulic fluid hazards, forcing incumbent suppliers to reengineer actuator architectures across their installed base. This technology transition is redistributing competitive advantage toward manufacturers with in-house electrical drive train capabilities.
Growth Catalysts
- UDAN Regional Connectivity Scheme:India's greenfield airport development under this framework is generating concentrated procurement windows for mobile jet bridge configurations. State-level aviation authorities are bundling ground support equipment tenders with terminal construction contracts.
- FAA Advisory Circular Updates:Structural certification requirements for passenger boarding bridges are tightening in North America, pulling replacement demand toward compliant new-build units. Airport operators face accelerated depreciation schedules for pre-2020 installations.
- Aluminum Honeycomb Composites:These materials are extending cantilever spans without steel reinforcement weight penalties, enabling modular bridge designs for apron-flexible regional airports.
Market Restraints
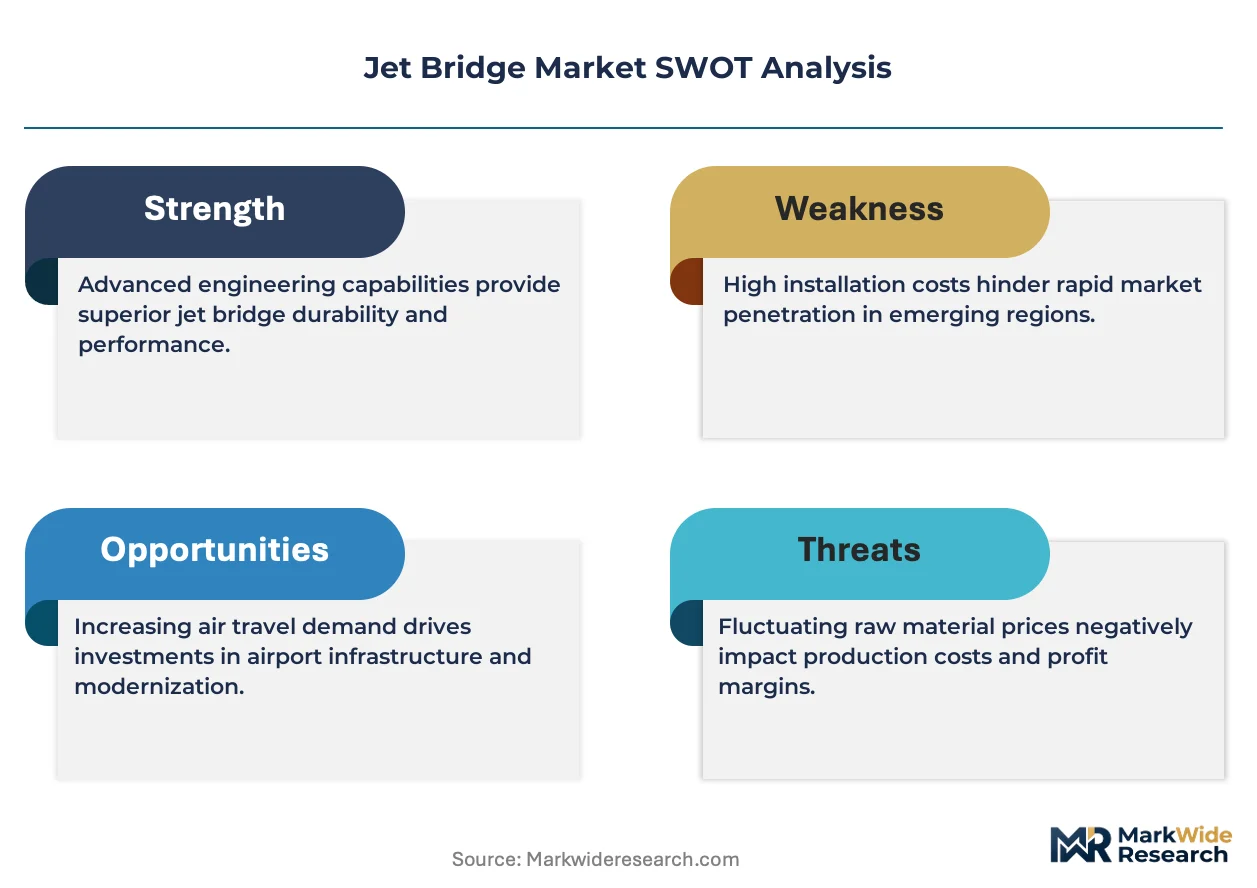
- Steel Input Volatility:Captive steel fabrication capacity at major Chinese suppliers insulates them from spot price swings that squeeze Western manufacturers dependent on merchant metallurgy.
- Gate Geometry Standardization:Fixed jet bridge architectures lock mature hub airports into replacement cycles rather than expansion procurement, capping addressable market growth at legacy facilities.
- Mobile Configurations:These flexible alternatives substitute for permanent infrastructure investment in markets prioritizing apron capacity over terminal construction, diverting capital from traditional jet bridge procurement.
Strategic Opportunities
- India Greenfield Development:Regional airports under UDAN phase expansions represent underpenetrated demand for modular electrical-drive bridges with rapid deployment timelines.
- Precision Docking Automation:Integration of sensor arrays with elevation controls creates white space for aftermarket retrofit packages at existing installations.
- ICAO Electrical Standardization:Emerging international guidelines for aircraft ground support equipment are creating first-mover advantage for suppliers with certified electrical architectures.
Industry Challenges
- Legacy Hydraulic Fleet Transition:Airport operators face technical complexity migrating from fluid-based actuators to electrical systems without disrupting gate availability during retrofit windows.
- Structural Certification Timelines:FAA and BIS compliance pathways for new composite materials extend product qualification cycles, compressing revenue recognition for innovation-led suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jet Bridge Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Jet Bridges, Fixed Jet Bridges, Modular Jet Bridges, Inflatable Jet Bridges End User: Airports, Airlines, Ground Handling Companies, Private Jet Operators Deployment: On-site Installation, Transportation, Maintenance Services, Upgrades Technology: Hydraulic Systems, Pneumatic Systems, Electrical Systems, Manual Systems |
| Companies Covered | Thyssenkrupp Airport Systems, CIMC-Tianda Holdings, JBT AeroTech, FMT Aircraft Gate Support Systems, ADELTE Group, ShinMaywa Industries, Ameribridge, Airport Equipment, UBS Airport Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jet Bridge Market Emerging Trajectories
Automation and material science are converging to redefine jet bridge performance metrics, shifting buyer evaluation from capital cost toward total lifecycle operational efficiency and aircraft turnaround optimization.
Precision docking automation is unifying optical sensing with predictive elevation algorithms to eliminate manual alignment procedures. Full-service network carriers at tier-one hubs are deploying these systems to compress ground time on narrow-body rotations. The technology is unifying gate throughput metrics with airline operational reliability contracts, embedding bridge performance into slot allocation negotiations.
China's GB standards for airport ground support equipment are mandating electrical system architectures in new domestic procurement specifications. Provincial airport groups under the Civil Aviation Administration of China are disqualifying hydraulic-actuator bids from state-funded tenders. Domestic suppliers with captive electrical drive train production are capturing market share from import-dependent competitors.
Service contract unbundling is fragmenting the aftermarket into component-level maintenance agreements separate from OEM comprehensive packages. Third-party ground handling operators at European hub airports are sourcing electrical drive modules from independent suppliers to bypass proprietary OEM pricing. This pattern is most visible in Germany and the Netherlands where ground handling deregulation has accelerated competitive tendering for lifecycle support.
Jet Bridge Market Segmentation
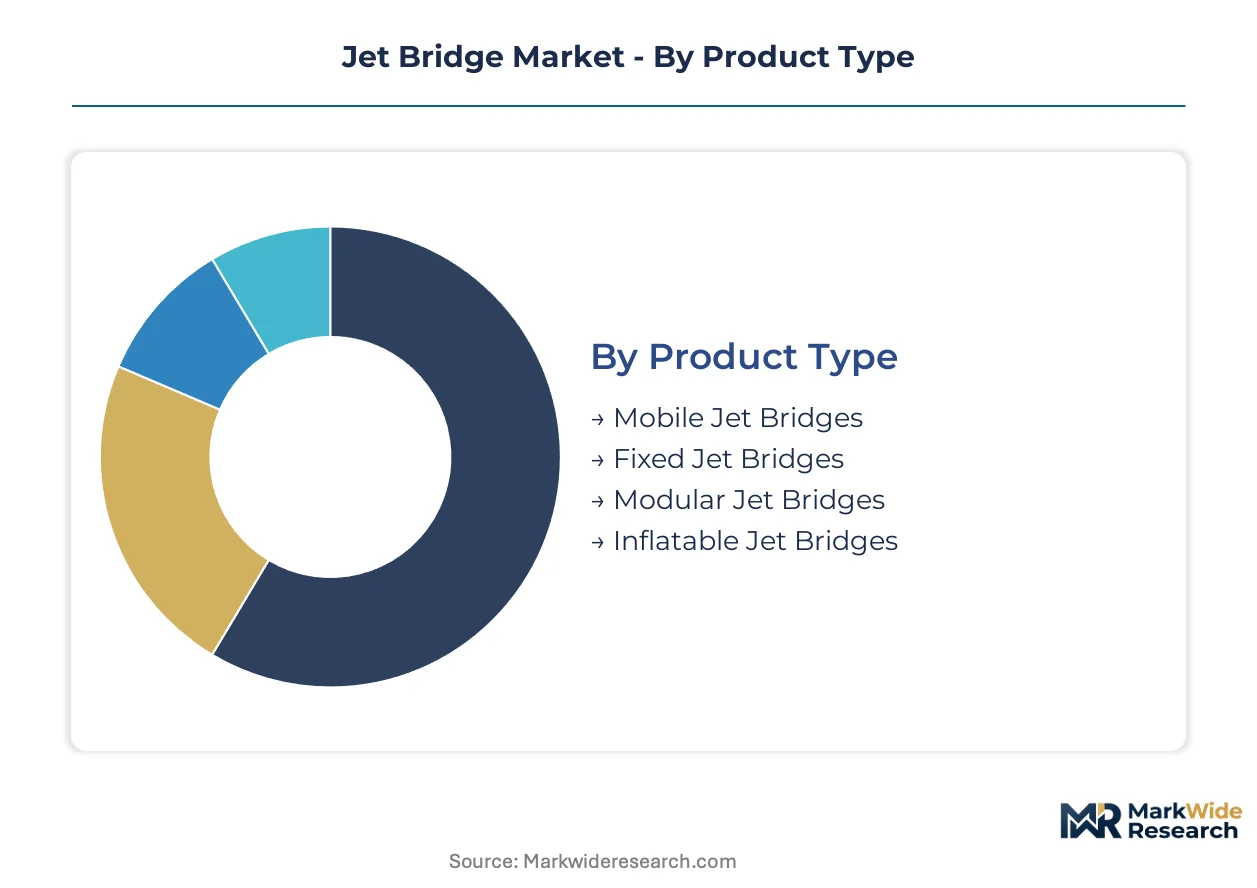
Jet bridge procurement splits across four structural dimensions that reshape supplier economics and competitive positioning. Product configuration determines steel versus aluminum intensity, while technology choice locks operators into maintenance ecosystems with diverging lifecycle costs.
Product Type:
Supply concentration tilts toward manufacturers with captive steel fabrication and modular assembly capabilities, rewarding integrated production over merchant sourcing.
- Mobile Jet Bridges:Self-propelled units mounted on rubber-tired chassis with 360-degree rotation capability and diesel-electric hybrid power. Demand concentrates in India under UDAN regional connectivity schemes, where apron flexibility outweighs permanent infrastructure investment and procurement bundles with ground support equipment tenders.
- Fixed Jet Bridges:Permanent steel-truss structures anchored to terminal buildings with cantilever spans reaching 35 meters and climate-controlled tunnel sections. Mature hub airports in Germany and the Netherlands dominate replacement demand, though gate geometry standardization limits expansion procurement to retrofit cycles.
- Modular Jet Bridges:Prefabricated aluminum-honeycomb sections enabling rapid field assembly without heavy crane requirements.
- Inflatable Jet Bridges:Deployable fabric tunnels with internal inflation systems for emergency and remote airfield operations.
Today's leader: Fixed Jet Bridges. Tomorrow's challenger: Mobile Jet Bridges.
End User:
Cost tier stratification separates capital-intensive airport authorities from operating-expense-focused ground handlers with diverging procurement timelines.
- Airports:Terminal-owning authorities with 15-20 year infrastructure depreciation schedules and FAA or BIS compliance mandates. Tier-one hubs in the United States and India bundle jet bridge procurement with gate reconstruction programs, creating concentrated tender windows.
- Airlines:Network carriers seeking dedicated gate control at fortress hubs, particularly full-service operators at Frankfurt and Amsterdam with operational reliability contracts tied to turnaround metrics.
- Ground Handling Companies:Third-party operators sourcing electrical drive modules independently to bypass OEM proprietary pricing, most visible in deregulated European markets.
- Private Jet Operators:Fractional ownership fleets and fixed-base operators with specialized requirements for executive aircraft door heights.
Procurement volume clusters with Airports. Margin expansion favors Ground Handling Companies.
Deployment:
Application lifecycle patterns separate upfront capital expenditure from recurring revenue streams with contrasting margin profiles.
- On-site Installation:Foundation work, structural anchoring, and utility connection requiring civil engineering coordination.
- Transportation:Oversized load logistics with modular disassembly and reassembly for mobile unit redeployment.
- Maintenance Services:Preventive and corrective work spanning electrical drive train overhaul, structural weld inspection, and climate system refurbishment. Aftermarket unbundling fragments this segment as independent suppliers capture electrical module replacement demand.
- Upgrades:Precision docking automation retrofits and hydraulic-to-electrical actuator conversions with extended qualification timelines under FAA Advisory Circular requirements.
Revenue stability resides in Maintenance Services. Growth acceleration centers on Upgrades.
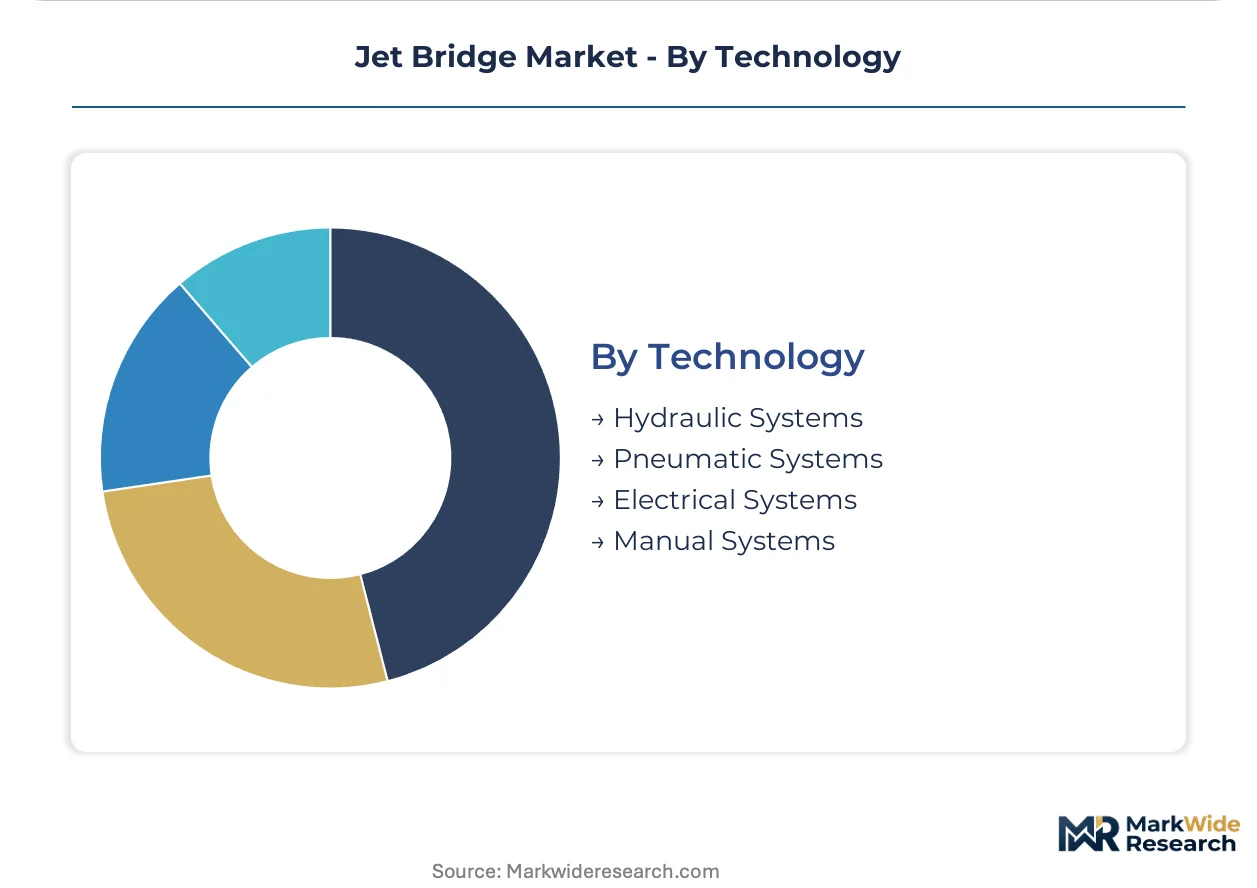
Technology:
Customer type preferences divide between legacy hydraulic fleets and electrical architectures with diverging supplier qualification criteria.
- Hydraulic Systems:Fluid-powered actuators with established installed base requiring specialized maintenance expertise and leak containment protocols. JBT AeroTech sustains aftermarket service contracts across this legacy fleet in North America.
- Pneumatic Systems:Compressed-air elevation mechanisms with limited new procurement but residual presence in cold-climate installations.
- Electrical Systems:Servo-motor drive trains with predictive maintenance capability and eliminated fluid hazards, now mandated under China's GB standards for state-funded tenders. CIMC-Tianda Holdings anchors market position through in-house electrical drive train production.
- Manual Systems:Hand-crank or towed configurations for general aviation and emergency backup roles.
Installed base dominance belongs to Hydraulic Systems. Procurement momentum shifts to Electrical Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta anchors global jet bridge manufacturing capacity through integrated steel fabrication and electrical component clusters serving domestic airport expansion and export markets.
United States
The FAA's updated Advisory Circular on passenger boarding bridge structural integrity is accelerating replacement demand at legacy hub airports. Tier-one facilities in Atlanta and Chicago bundle gate reconstruction programs with compliant new-build procurement. JBT AeroTech sustains aftermarket service contracts across the installed hydraulic fleet concentrated in these metropolitan aviation clusters.
Germany
Ground handling deregulation in Frankfurt and Amsterdam is fragmenting aftermarket demand toward independent electrical module suppliers. The EU Machinery Directive and CE marking requirements govern automated docking system certification. Precision docking automation retrofits concentrate at Lufthansa hub operations seeking turnaround compression.
China
Provincial airport groups under the Civil Aviation Administration are disqualifying hydraulic-actuator bids from state-funded tenders. GB standards mandate electrical system architectures in new domestic procurement. CIMC-Tianda Holdings leverages captive steel fabrication and in-house electrical drive train production from its Shenzhen base.
India
The UDAN regional connectivity scheme is generating concentrated procurement windows for mobile jet bridge configurations at greenfield airports. State-level aviation authorities bundle ground support equipment tenders with terminal construction contracts. Development concentrates in Maharashtra and Karnataka where apron flexibility outweighs permanent infrastructure investment.
Japan
ShinMaywa Industries anchors domestic supply through precision manufacturing heritage in aircraft support equipment. METI industrial standards shape electrical system reliability requirements for automated docking. Demand clusters at Tokyo Haneda and Osaka Kansai where narrow-body rotation efficiency drives precision automation adoption.
Jet Bridge Market Vendor Landscape
Global majors compete with regional champions across electrical drive train integration and structural certification capabilities. The supplier base stratifies into integrated manufacturers with captive metallurgy, automation specialists with sensor-array differentiation, and regional fabricators serving procurement localization mandates. Three archetypes dominate: vertically integrated steel-electrical hybrids, precision automation pure-plays, and mobile configuration specialists. Competitive intensity centers on M&A to secure electrical drive train technology and strategic partnerships to penetrate UDAN-scheme tenders.
Among German-anchored automation specialists, Thyssenkrupp Airport Systems exemplifies precision docking differentiation. Chinese integrated manufacturers occupy the cost-position tier, with CIMC-Tianda Holdings representing captive supply chain architecture. North American aftermarket incumbents sit within the legacy fleet service tier, where JBT AeroTech anchors installed-base retention strategies.
| Leading Market Players |
|---|
| Thyssenkrupp Airport Systems |
| CIMC-Tianda Holdings |
| JBT AeroTech |
| FMT Aircraft Gate Support Systems |
| ADELTE Group |
| ShinMaywa Industries |
| Ameribridge |
| Airport Equipment |
| UBS Airport Systems |
| Others |
Supply Flow & Price Mechanics
Captive steel fabrication and in-house electrical drive train production at CIMC-Tianda Holdings anchors both supply security and pricing power, insulating integrated manufacturers from merchant metallurgy volatility while compressing procurement costs for state-funded tenders under China's GB standards.
Pricing Analysis
Steel input cost pass-through dominates pricing dynamics, with Chinese integrated manufacturers absorbing spot price swings that squeeze Western competitors dependent on merchant sourcing. Three-tier pricing structure across premium automation, standard electrical, and economy hydraulic levels separates precision docking systems from basic configurations. Cost compression in economy tiers is intensifying because provincial airport groups under China's Civil Aviation Administration now disqualify hydraulic-actuator bids. Ground handling companies in deregulated European markets exhibit highest price sensitivity, while tier-one hub authorities in the United States and India prioritize certification compliance over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's BIS certification for structural steel components and China's GB standards for electrical architectures are reshaping sourcing patterns toward local fabrication. Manufacturing gravity centers on China, Germany, and the United States, with supply chains drawing from specialized steel truss producers, electrical servo-motor suppliers, and climate-control system integrators. Single-source vulnerability concentrates in precision sensor arrays for automated docking systems. Distribution runs through direct OEM contracting with airport authorities and bundled ground support equipment tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through divergent certification timelines, where FAA Advisory Circular structural requirements accelerate North American replacement cycles while India's UDAN scheme concentrates greenfield procurement windows.
For Market Incumbents: Anticipate electrical system standardization across ICAO guidelines by deepening in-house drive train capabilities before qualification deadlines tighten. Defend installed-base retention through aftermarket service contract unbundling that matches independent supplier pricing on electrical module replacement. Prioritize certification investment in aluminum honeycomb composites to extend product lifecycles under tightened FAA structural integrity requirements. For New Entrants and Emerging Players: Launch via mobile jet bridge configurations targeting India's UDAN regional connectivity scheme, where apron flexibility priorities outrank permanent infrastructure investment. Penetrate the precision docking automation retrofit segment at European hub airports where ground handling deregulation fragments legacy OEM service relationships. White space concentrates in rapid-deployment modular bridges for greenfield regional airports with compressed construction timelines. For Investors and Strategic Acquirers: Roll-up economics work for electrical drive train specialists because technology transition is redistributing competitive advantage toward manufacturers with certified architectures and captive production. Five-to-ten year viability hinges on positioning ahead of hydraulic fleet replacement cycles. Acquisition targets should demonstrate in-house servo-motor production and BIS or FAA certification pathways. Monitor ICAO electrical standardization guideline progression as inflection indicator for supplier qualification reshaping.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrical Drive Trains | CIMC-Tianda Holdings secures cost position through captive servo-motor production for state-funded tenders. |
| Precision Docking Automation Retrofit | Thyssenkrupp Airport Systems compresses aircraft turnaround times at Lufthansa hub operations. |
| Mobile Configuration Specialization | Regional airports under India's UDAN scheme prioritize apron flexibility over permanent infrastructure. |
| Aftermarket Service Unbundling | Third-party ground handlers in Germany bypass OEM proprietary pricing on electrical module replacement. |
| Composite Material Certification | Aluminum honeycomb suppliers extend cantilever spans without steel reinforcement weight penalties. |
Methodological Framework
Coverage spans the United States, Germany, China, India, and Japan, with primary inputs from each market combining structured interviews with airport procurement directors, ground handling operations managers, electrical systems engineers, and aftermarket service heads alongside secondary validation through FAA Advisory Circular documentation, EU Machinery Directive filings, China's GB standards registry, and India's BIS certification database. Bottom-up demand modeling triangulates against top-down infrastructure investment tracking.
Rate-of-change decomposition separates volume expansion from value migration across the projection horizon, with analytical frameworks modeling product configuration, technology architecture, end-user type, and deployment mode as core segmentation dimensions. CAGRs derive from infrastructure investment pipeline analysis, gate reconstruction program tracking, and regulatory compliance timeline mapping. Industry-specific forecast inputs incorporate UDAN scheme phase progression and FAA structural certification update adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under steel price volatility and regulatory timeline acceleration scenarios. Forecasts reflect documented assumptions regarding electrical system displacement rates and regional infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Global Green Airport Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market