
 Middle-East and Africa Aviation Infrastructure Market | 2026-2036
Middle-East and Africa Aviation Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Aviation Infrastructure Market Foresight
Composite materials are displacing conventional steel in airfield pavement and terminal roofing, which is rebalancing lifecycle cost calculations for new airport builds. Bechtel Corporation leverages its engineering pedigree to anchor mega-project credibility across the Gulf. VINCI Airports sustains operational excellence metrics that differentiate its concession bids. TAV Construction competes aggressively on Turkish-African corridor expertise.
Middle-East and Africa aviation infrastructure encompasses runways, taxiways, aprons, terminals, control towers, and ancillary support systems engineered to ICAO Category III precision-approach standards and designed for passenger throughput exceeding 30 million annually at major hubs. The primary purpose is enabling safe, efficient aircraft movement while processing commercial, cargo, and diplomatic traffic through integrated ground-to-air networks. Terminal and hub segments lead capital deployment as Gulf states prioritize passenger experience differentiation and retail monetization. Ground handling services represent the fastest-growing service category, driven by third-party outsourcing trends at privatized airports. Cargo services remain structurally underdeveloped outside Ethiopian Airlines' Addis Ababa hub and Dubai's Al Maktoum expansion.
General Authority of Civil Aviation in Saudi Arabia and the UAE's General Civil Aviation Authority enforce design standards that mandate biometric passenger processing and sustainable construction materials, which elevates project complexity and vendor qualification thresholds. South Africa's Airports Company must reconcile ICAO Annex 14 compliance with national procurement regulations that prioritize local construction content. Stakeholders must monitor how civil aviation authorities across the region harmonize sovereign infrastructure ambitions with available debt capacity and concession structuring expertise.
Market Dynamics
Gulf Cooperation Council full-service carriers are pressing for terminal capacity upgrades as composite materials displace steel in airfield construction, rebalancing lifecycle cost calculations and vendor qualification thresholds across mega-project pipelines.
Growth Catalysts
- Biometric Processing Mandates:Saudi Arabia's General Authority of Civil Aviation and the UAE's General Civil Aviation Authority enforce passenger processing standards that elevate project complexity and lock in technology upgrade cycles.
- Privatization Frameworks:Streamlined private sector participation rules in Saudi Arabia accelerate airport development timelines and attract concession operators with operational excellence track records.
- Composite Material Adoption:Airfield pavement and terminal roofing specifications increasingly specify carbon-fiber reinforced polymers, cutting maintenance intervals and extending asset lifespans.
Market Restraints
- Specialized Contractor Concentration:Mega-project credibility concentrates among engineering firms with Gulf delivery track records, limiting bid competition and inflating risk premiums for new entrants.
- Local Content Procurement Rules:South Africa's Airports Company must reconcile ICAO Annex 14 compliance with national regulations mandating domestic construction content, compressing contractor margins.
- Debt Capacity Constraints:Sovereign infrastructure ambitions in multiple Gulf states outstrip available concession structuring expertise and project finance depth.
Strategic Opportunities
- Ground Handling Outsourcing:Third-party service provision at privatized airports across the UAE and Saudi Arabia represents the fastest-growing service category as carriers shed non-core operations.
- Cargo Hub Development:Ethiopian Airlines' Addis Ababa hub and Dubai's Al Maktoum expansion demonstrate underexploited potential for dedicated freight infrastructure elsewhere in Africa.
- Sustainable Construction Incentives:Regulatory pressure for green building materials creates first-mover advantages for contractors with certified sustainable supply chains.
Industry Challenges
- ICAO Category III Certification Timelines:Precision-approach standard compliance for runways and control towers demands extended validation periods that delay revenue commencement.
- Legacy System Integration:New biometric passenger processing infrastructure must interface with existing baggage handling and security architectures without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Aviation Infrastructure Market |
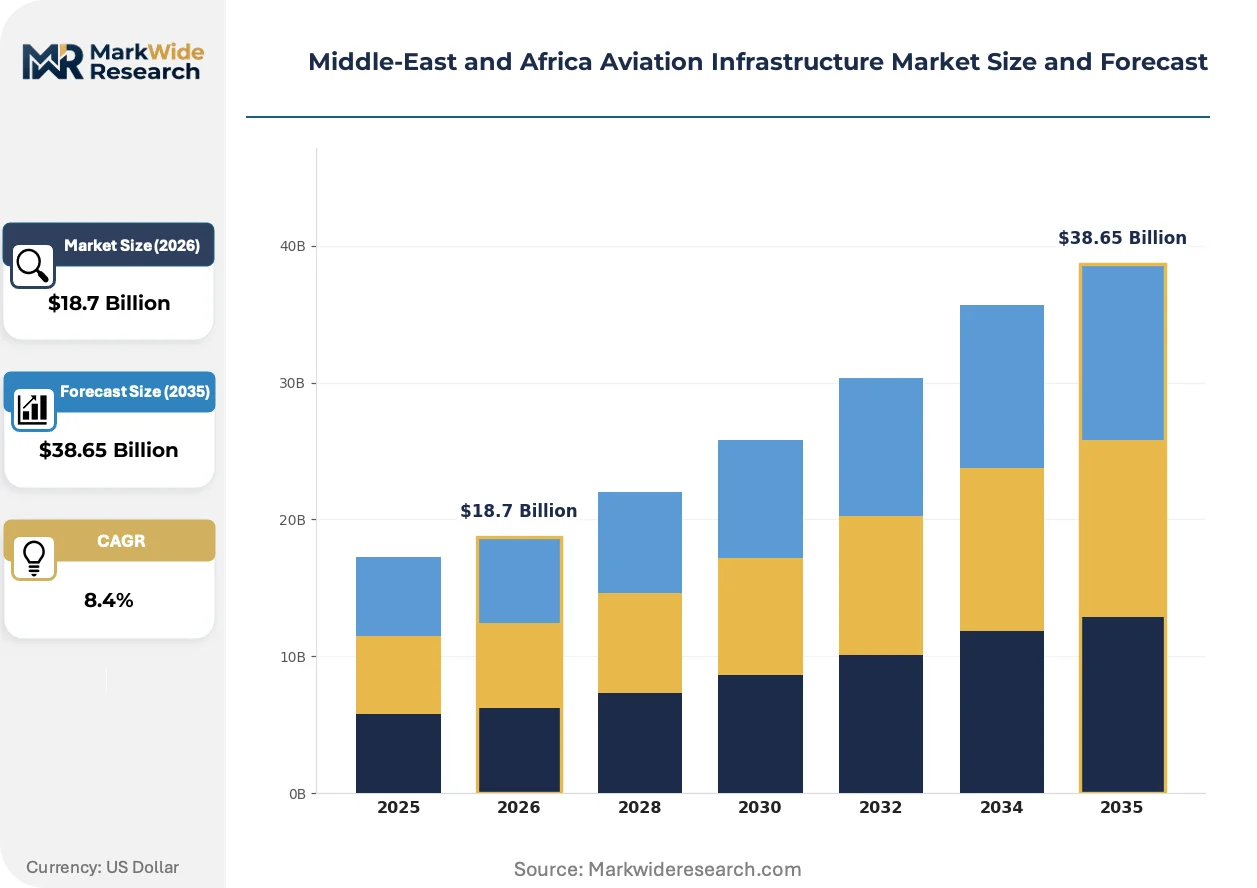
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Ground Handling, Air Traffic Control, Maintenance Services, Cargo Services Facility Type: Airports, Hubs, Terminals, FBOs End User: Commercial Airlines, Cargo Carriers, Government Agencies, Private Operators Technology: Aviation Security, Navigation Systems, Communication Tools, Infrastructure Management |
| Companies Covered | Bechtel Corporation, VINCI Airports, Eiffage S.A., Skanska AB, Bouygues Construction S.A., TAV Construction, Limak Group of Companies, ALEC Engineering & Contracting LLC, BIC Contracting LLC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Aviation Infrastructure Market Shifts & Advancements
Aviation infrastructure development across the Middle-East and Africa is pivoting toward passenger experience differentiation, sustainable material specifications, and operational outsourcing models that reshape capital deployment priorities.
Composite reinforcement systems are absorbing structural loads in airfield pavement and terminal roofing applications that previously demanded steel. Major hub developers in the UAE and Saudi Arabia specify carbon-fiber reinforced polymers for new builds. This material transition is absorbing maintenance budget allocations into higher upfront capital expenditure while compressing long-term lifecycle cost projections.
Biometric passenger processing mandates from the General Authority of Civil Aviation in Saudi Arabia and the UAE's General Civil Aviation Authority now govern terminal design standards. These regulations force integration of facial recognition and automated border control gates into new construction. Full-service carriers and ground handlers in Dubai and Abu Dhabi are responding by front-loading technology infrastructure spend to secure operating certificates.
Carrier procurement of ground handling services is consolidating around long-term concession agreements rather than in-house operations. Third-party specialists are displacing airline-owned equipment and staff at privatized airports across the Gulf. This pattern is most visible in the UAE, where Dubai South and Zayed International Airport anchor regional hub expansion through outsourced service models.
Middle-East and Africa Aviation Infrastructure Market Segmentation
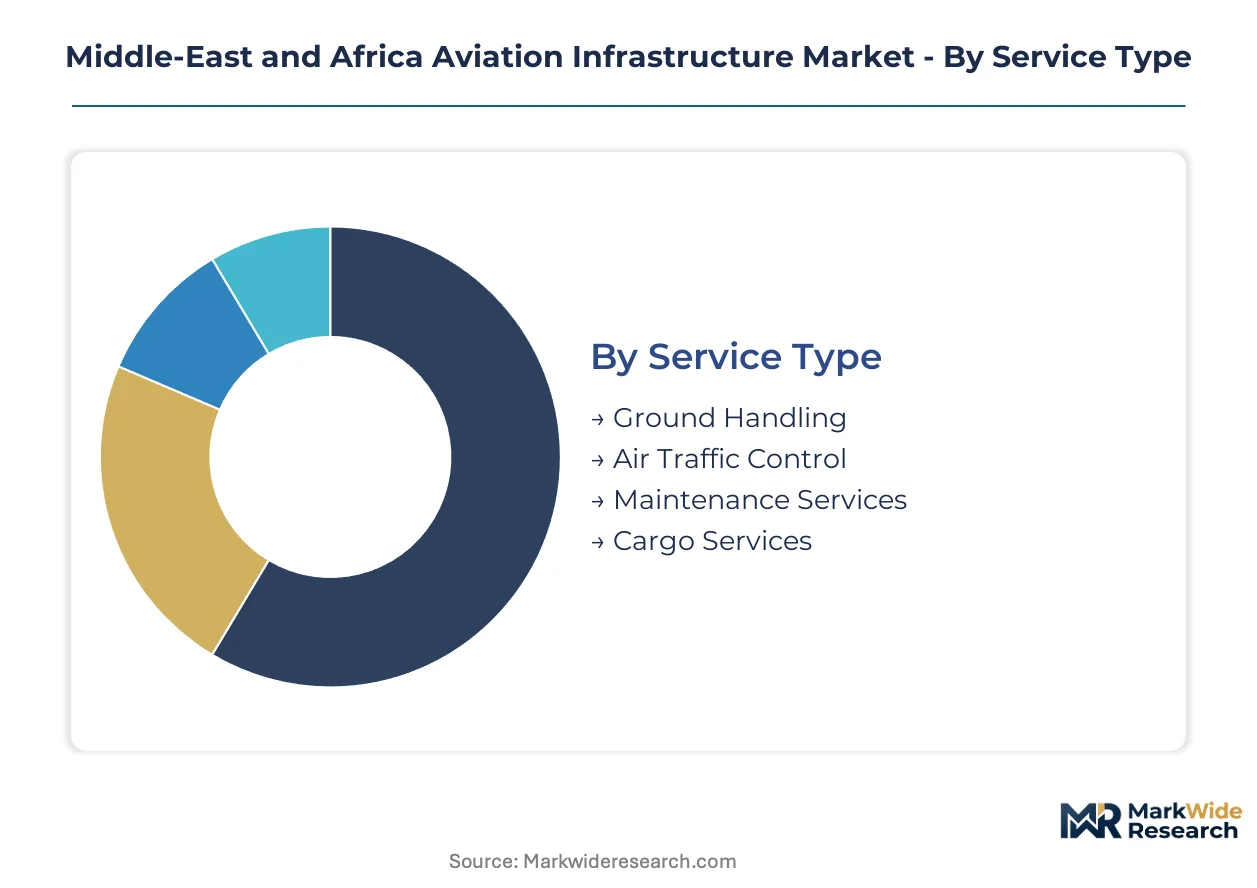
Segmentation reveals how capital deployment priorities diverge across the Middle-East and Africa aviation infrastructure landscape. Procurement patterns for composite-intensive airfield construction differ sharply from biometric-enabled terminal upgrades, while ground handling outsourcing reshapes service-type economics.
Service Type:
Customization intensity varies from standardized regulatory-mandated services to carrier-specific operational outsourcing arrangements across this category.
- Ground Handling:Passenger boarding, baggage processing, and aircraft turnaround services delivered under long-term concession agreements. Demand concentrates at Dubai South and Zayed International Airport as Emirates and Etihad shed non-core operations to third-party specialists.
- Air Traffic Control:ICAO Category III precision-approach systems integrating radar, surveillance, and communication infrastructure. Saudi Arabia's General Authority of Civil Aviation mandates biometric-compatible control tower specifications that elevate vendor qualification thresholds.
- Maintenance Services:MRO infrastructure supporting fleet expansion by Gulf Cooperation Council full-service carriers.
- Cargo Services:Dedicated freight handling and cold-chain logistics, structurally underdeveloped outside Ethiopian Airlines' Addis Ababa hub and Dubai's Al Maktoum expansion.
Most installed capacity flows through Ground Handling. Expansion is steepest in Cargo Services.
Facility Type:
Revenue concentration tilts toward assets with retail monetization potential and passenger throughput scale rather than pure operational utility.
- Airports:Integrated airfield and terminal complexes engineered to ICAO Annex 14 standards with runway-taxiway-apron systems. The UAE anchors regional hub expansion through Dubai South and Abu Dhabi's Zayed International Airport developments prioritizing passenger experience differentiation.
- Hubs:Transfer-optimized facilities designed for 30+ million annual passenger throughput with automated baggage sorting and biometric processing gates. Saudi Arabia's streamlined private sector participation rules accelerate hub development timelines.
- Terminals:Carbon-fiber reinforced polymer roofing and composite structural systems cutting maintenance intervals.
- FBOs:Fixed-base operations serving private aviation and diplomatic traffic with specialized apron and lounge facilities.
Terminals capture the dominant share of current capital expenditure. Hubs are climbing the fastest as Gulf states compete for transfer traffic.
End User:
Procurement authority fragments between sovereign aviation authorities, privatized airport operators, and carrier-owned infrastructure divisions.
- Commercial Airlines:Full-service carriers in the Gulf Cooperation Council pressing for upgraded terminal capacity and ground handling outsourcing. Fleet order backlogs at Emirates, Qatar Airways, and Etihad drive infrastructure demands across the UAE and Saudi Arabia.
- Cargo Carriers:Ethiopian Airlines and dedicated freight operators requiring specialized apron and cold-chain facilities.
- Government Agencies:Civil aviation authorities mandating biometric processing and sustainable construction standards.
- Private Operators:Business aviation and charter services utilizing FBO infrastructure with lower regulatory compliance burdens.
Commercial Airlines command the largest facility investment pipelines. Cargo Carriers are gaining share fastest as dedicated freight infrastructure gaps close.
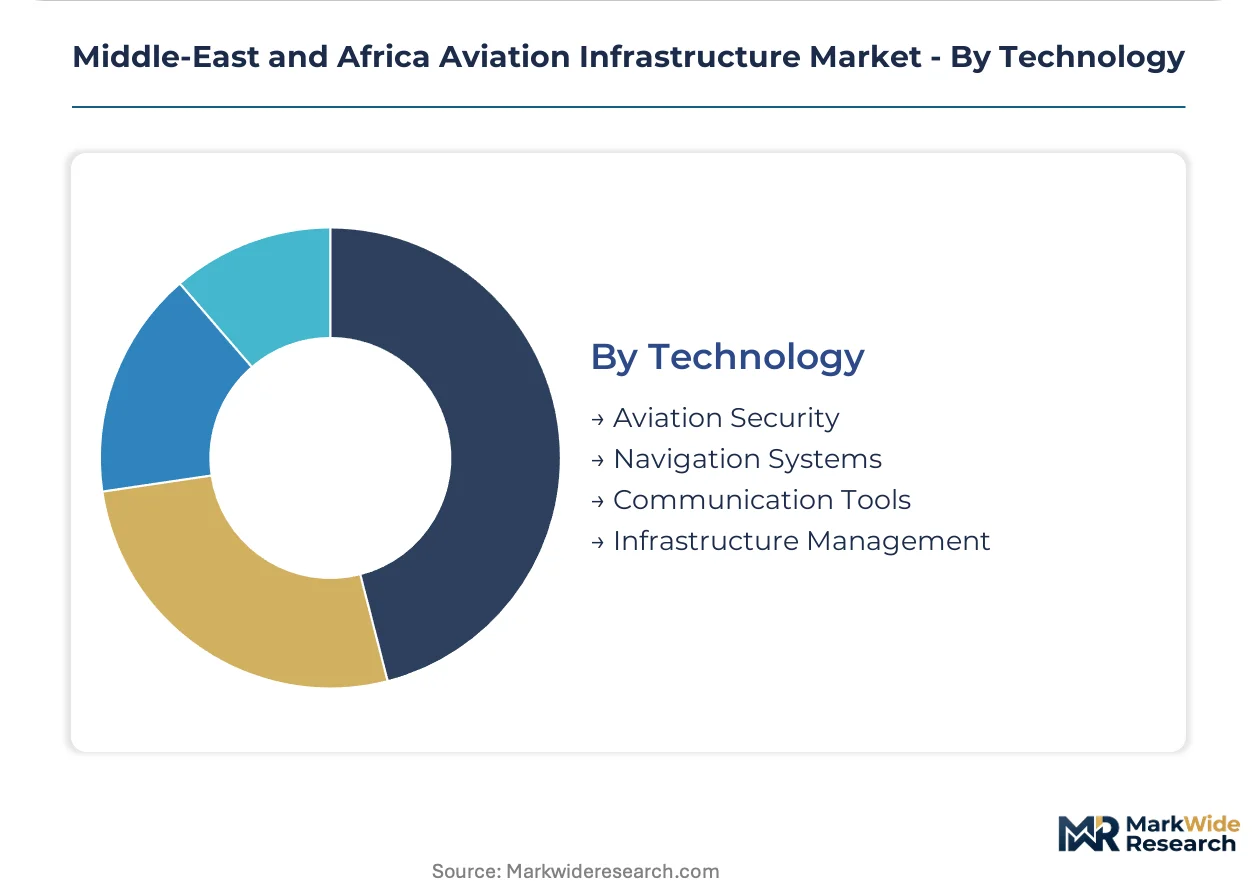
Technology:
Regulatory mandates from the General Authority of Civil Aviation and the UAE's General Civil Aviation Authority force technology refresh cycles that standardize previously discretionary upgrades.
- Aviation Security:Biometric passenger processing infrastructure including facial recognition and automated border control gates. Dubai and Abu Dhabi front-load technology spend to secure operating certificates under authority mandates.
- Navigation Systems:Precision-approach equipment meeting ICAO Category III standards for low-visibility operations.
- Communication Tools:Integrated ground-to-air networks linking control towers, aircraft, and ground handling systems.
- Infrastructure Management:Building automation and energy systems supporting sustainable construction material specifications.
Aviation Security absorbs the dominant technology budget allocation. Infrastructure Management is expanding most quickly as green building incentives take hold.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai South anchors aviation infrastructure demand across the Middle-East and Africa region, with Gulf carriers pressing for expanded terminal capacity and upgraded airfield systems to match fleet growth trajectories.
United Arab Emirates
Dubai South and Zayed International Airport drive capital deployment as Emirates and Etihad expand fleet orders. The General Civil Aviation Authority enforces biometric passenger processing mandates that elevate terminal design standards. Abu Dhabi's hub expansion prioritizes retail monetization and automated baggage sorting systems.
Saudi Arabia
Riyadh and the Eastern Province concentrate mega-project development aligned with sovereign diversification targets. The General Authority of Civil Aviation streamlined private sector participation rules to accelerate concession timelines. NEOM Northwest anchors greenfield airport construction with sustainable material specifications.
South Africa
Johannesburg and Cape Town metro areas reconcile infrastructure modernization with fiscal constraints. The Airports Company must balance ICAO Annex 14 compliance against national procurement rules mandating local construction content. OR Tambo International anchors regional connectivity upgrades.
Turkey
Istanbul anchors Turkish-African corridor expertise as carriers expand into sub-Saharan markets. Turkish contractors leverage regional delivery track records to compete for Gulf mega-projects. Ankara's civil aviation authority harmonizes EU-aligned standards with emerging market cost structures.
Ethiopia
Addis Ababa anchors African cargo hub development outside Gulf-dominated passenger flows. Ethiopian Airlines drives dedicated freight infrastructure investment as regional connectivity gaps persist. Bole International Airport expansion targets cold-chain logistics capabilities for perishable exports.
Middle-East and Africa Aviation Infrastructure Market Competitive Landscape
Long-term concession agreements dominate the current landscape as operators seek operational excellence credentials to secure privatized airport contracts. Engineering firms with Gulf delivery track records concentrate mega-project credibility among a narrow tier of qualified bidders. Two strategic archetypes define positioning: integrated infrastructure developers with full EPC capabilities, and specialized airport concessionaires with operational metrics differentiation. Competitive intensity manifests through portfolio diversification into adjacent ground handling services and geographic expansion along Turkish-African corridors.
Among European-based infrastructure developers, Bechtel Corporation and VINCI Airports exemplify contrasting archetypes within the qualified bidder tier. Bechtel represents the engineering pedigree anchor for mega-project credibility across complex airfield and terminal developments. VINCI Airports occupies a position emphasizing operational excellence metrics that differentiate concession bids in privatized airport frameworks. TAV Construction sits within the regional specialist tier, leveraging Turkish-African corridor expertise to compete for ground handling and terminal upgrade contracts.
| Leading Market Players |
|---|
| Bechtel Corporation |
| VINCI Airports |
| Eiffage S.A. |
| Skanska AB |
| Bouygues Construction S.A. |
| TAV Construction |
| Limak Group of Companies |
| ALEC Engineering & Contracting LLC |
| BIC Contracting LLC |
| Others |
Supply & Pricing Matrix
Gulf Cooperation Council full-service carriers concentrate procurement authority for aviation infrastructure projects, locking contract structures around long-term concession frameworks with performance-linked payment schedules.
Pricing Analysis
Carbon-fiber reinforced polymer and composite material costs pass through directly to project budgets, elevating upfront capital expenditure against compressed lifecycle maintenance projections. Pricing stratifies across ICAO Category III precision-approach certification tiers, with biometric-enabled terminal builds commanding premium positioning over standard airfield pavement contracts. Cost compression in ground handling concessions is intensifying as third-party operators compete for privatized airport mandates. Cargo infrastructure buyers exhibit highest price sensitivity due to structurally underdeveloped freight networks outside Ethiopian Airlines' Addis Ababa hub and Dubai's Al Maktoum expansion.
Supply Chain Analysis
Specialized engineering labor availability in Turkey, South Korea, and Germany constrains contractor capacity for mega-project delivery across the Gulf. Composite manufacturing for airfield applications draws from carbon-fiber suppliers in Japan, Germany, and the United States, while precision-approach navigation equipment sources from specialized avionics producers in France and the United States. Single-source vulnerability concentrates in ICAO-certified control tower system integrators with Gulf delivery track records. Distribution runs through sovereign aviation authority procurement frameworks with mandated local content thresholds compressing contractor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biometric passenger processing mandates from Saudi Arabia's General Authority of Civil Aviation and the UAE's General Civil Aviation Authority compound project complexity and vendor qualification thresholds, creating sustained demand for certified infrastructure developers.
For Market Incumbents: Cement mega-project credibility through sustained Gulf delivery track records and operational excellence metrics that differentiate concession bids. Lock in long-term ground handling agreements at Dubai South and Zayed International Airport before third-party competition intensifies. Counter emerging Turkish-African corridor specialists by front-loading technology infrastructure spend for biometric compatibility certification.
For New Entrants and Emerging Players: Enter via cargo hub development gaps in sub-Saharan Africa outside Ethiopian Airlines' Addis Ababa dominance and Dubai's Al Maktoum expansion. Target South Africa's Airports Company procurement pipelines where local content rules create entry wedges against established Gulf contractors. Lead with sustainable construction material certifications to capture green building incentives from Saudi Arabia's NEOM Northwest development.
For Investors and Strategic Acquirers: Sovereign wealth funds and infrastructure-focused private equity are the most active acquirers in this space, prioritizing operational concession platforms over pure engineering capabilities. Long-term viability rests on exposure to privatized airport frameworks with outsourced service models. Monitor ICAO Category III certification timeline delays as inflection indicators for revenue commencement risk across project pipelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Infrastructure Integration | General Authority of Civil Aviation mandates facial recognition systems in new terminal builds, elevating vendor qualification thresholds. |
| Composite Material Specification | Carbon-fiber reinforced polymers in airfield pavement cut maintenance intervals while absorbing higher upfront capital allocation. |
| Ground Handling Concession Expansion | Emirates and Etihad outsourcing non-core operations creates third-party service growth at Dubai South and Zayed International Airport. |
| Cargo Hub Development | Ethiopian Airlines' Addis Ababa expansion and Al Maktoum freight capacity demonstrate underexploited African infrastructure potential. |
| Sustainable Construction Certification | NEOM Northwest greenfield projects prioritize contractors with verified sustainable supply chains for regulatory compliance. |
Research Methodology
Coverage spans the Middle East, Africa, and Turkey, with primary inputs from each region combining structured interviews with airport development executives, civil aviation authority procurement officers, ground handling operations directors, and EPC contractor project managers. Secondary validation draws from ICAO regulatory filings, General Authority of Civil Aviation tender announcements, UAE General Civil Aviation Authority standards documentation, and sovereign infrastructure budget disclosures. Bottom-up project pipeline aggregation triangulates against top-down concession value estimates.
Rate-of-change decomposition separates fleet expansion trajectories from terminal capacity utilization, regulatory mandate implementation timelines, and privatization framework maturation across the analysis window. Segmentation modeling incorporates facility type, service category, technology tier, and end-user procurement authority. CAGRs derive from project-level capital expenditure tracking and concession revenue forecasting, with cross-reference to composite material cost curves and biometric system deployment schedules.
The model holds under sustained sovereign diversification spending and streamlined private sector participation rules; deviation in debt capacity constraints or ICAO certification delays would shift project commencement timelines. Forecasts reflect documented assumptions around carrier fleet delivery schedules and concession structuring expertise availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Airport Passenger Boarding Bridge Market
Airport Infrastructure
Europe Airport Baggage Handling Systems Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Runway Lighting System Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Ground Support Equipment Market