
 Airfield Ground Lighting Market | 2026-2036
Airfield Ground Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Airfield Ground Lighting Market Insights
Aftermarket service revenue is fragmenting across the airfield ground lighting value chain as original equipment manufacturers and third-party maintenance providers contest recurring contract streams. ADB SAFEGATE leverages its installed base of intelligent lighting platforms to capture long-term service agreements. TKH Airport Solutions anchors its competitive stance through deep specialization in LED-based airfield solutions. OCEM Airfield Technology differentiates by controlling niche manufacturing capabilities for military-grade obstruction lighting systems.
Airfield ground lighting comprises luminaires, control systems, and monitoring equipment engineered to provide visual guidance for aircraft during taxi, takeoff, and landing operations under all weather conditions, typically operating at 6.6 ampere series circuits with photometric outputs measured in candela. Runway lights and taxiway lights constitute the dominant product categories by installed volume, while LED technology is displacing halogen as the primary illumination source due to energy efficiency gains and extended operational lifespans exceeding 50,000 hours. Commercial airports represent the largest application segment, though military airbases are emerging as a concentrated demand pocket driven by defense infrastructure modernization programs.
The Federal Aviation Administration mandates photometric and chromaticity standards under AC 150/5345-53, while ICAO Annex 14 establishes international baseline requirements for airfield lighting configuration and performance. The European Union Aviation Safety Agency enforces certification protocols through CS-ADR-DSN specifications, creating compliance-driven replacement cycles across member states. Stakeholders must monitor the convergence of smart airfield technologies with cybersecurity mandates as connected lighting networks become integral to airport digital infrastructure.
Market Dynamics
LED retrofit mandates from aviation regulators are compressing replacement cycles across commercial airport infrastructure, forcing operators to accelerate capital deployment while third-party maintenance providers capture recurring service revenue streams.
Growth Catalysts
- ICAO Annex 14 Compliance Deadlines:International airports face mandatory photometric upgrades to meet visibility standards, triggering system-wide procurement of intelligent lighting platforms.
- LED Technology Maturation:Extended operational lifespans exceeding 50,000 hours reduce total cost of ownership for hub operators managing 24/7 flight schedules.
- United States Hub Expansions:Major infrastructure projects in Atlanta and Dallas are driving bulk orders for airfield lighting control systems.
Market Restraints
- Copper and Semiconductor Input Volatility:Series circuit cabling and LED driver components face price instability from concentrated Asian supply bases.
- Specialized Installer Scarcity:Certified airfield electrical technicians require FAA-approved training programs with limited annual graduation capacity.
- 6.6 Ampere Legacy Infrastructure Lock-in:Existing series circuit architecture constrains rapid technology migration without complete airfield shutdowns.
Strategic Opportunities
- Smart Airfield Convergence:Integration of lighting networks with IoT sensors and predictive maintenance platforms creates new service revenue pools.
- Military Airbase Modernization:Defense infrastructure programs in NATO member states are opening dedicated procurement channels for obstruction lighting systems.
- Cybersecurity Certification Demand:Connected lighting infrastructure requires compliance with emerging aviation cybersecurity frameworks, favoring vendors with integrated security architectures.
Industry Challenges
- FAA AC 150/5345-53 Certification Timelines:Photometric and chromaticity testing protocols extend product validation cycles by 12-18 months.
- Legacy Control System Integration:Intelligent lighting platforms must interface with decades-old airfield monitoring equipment without disrupting operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airfield Ground Lighting Market |
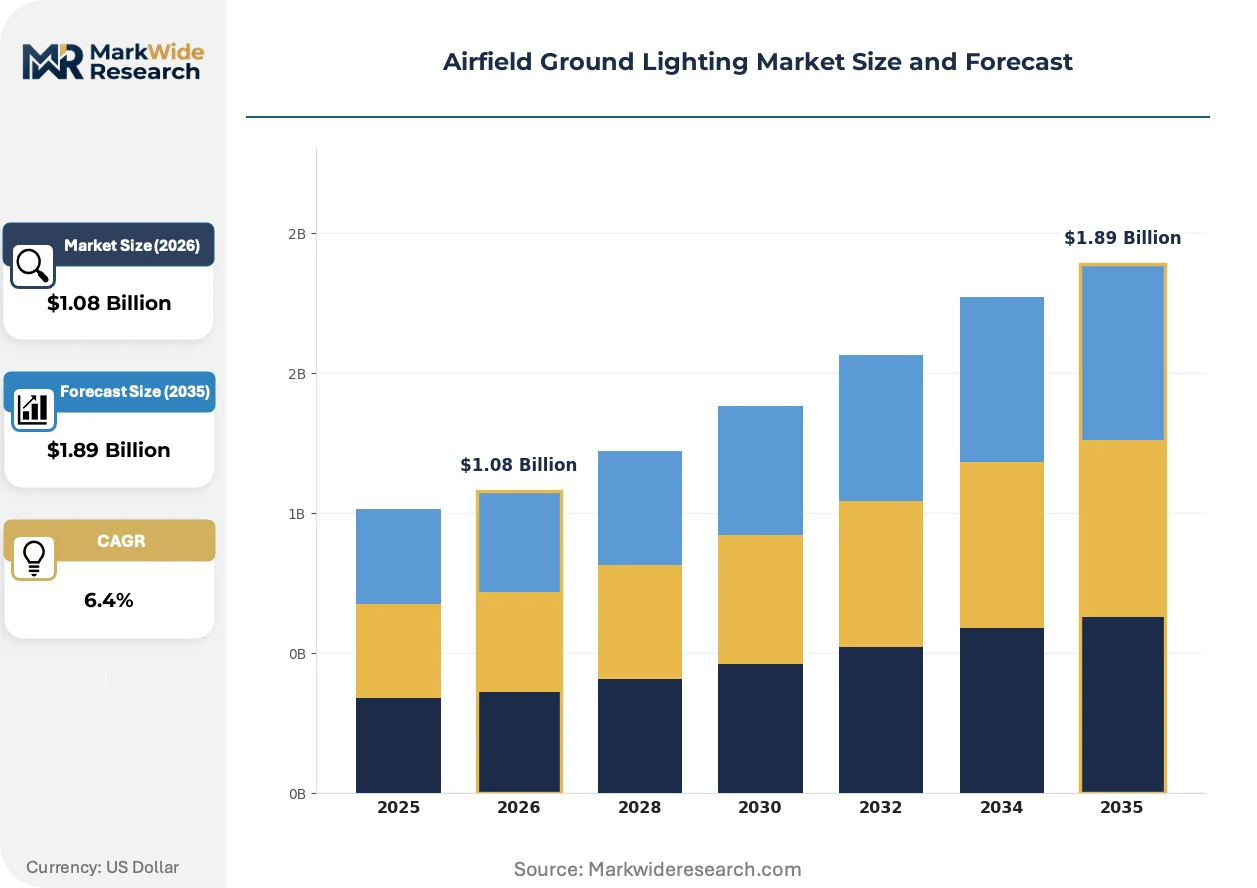
| Market Size in 2026 | $1.08 Billion |
| Market Size in 2035 | $1.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Runway Lights, Taxiway Lights, Apron Lights, Threshold Lights, Obstruction Lights Technology: LED, Halogen, Solar, Fluorescent, Xenon Application: Commercial Airports, Military Airbases, Private Airstrips, Cargo Terminals, Heliports End User: Airport Operators, Airfield Maintenance Companies, Aviation Authorities, Ground Handling Services |
| Companies Covered | TKH Airport Solutions, ATG Airports Limited, ADB SAFEGATE, Signify Netherlands BV, Astronics Corporation, Honeywell International Inc., OCEM Airfield Technology, Siemens AG, Eaton Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airfield Ground Lighting Market Trends and Innovations
Digitalization of airfield infrastructure is redefining competitive advantage around data-enabled service models rather than hardware shipment volumes alone.
Solid-state LED illumination with embedded dimming control and fault detection circuitry is rendering obsolete conventional halogen systems with separate mechanical regulators. Hub operators in the United States and Germany are completing full airfield conversions within 24-month windows to capture energy rebates. The technology compression is eliminating mid-tier suppliers lacking embedded software development capabilities.
The European Union Aviation Safety Agency enforces CS-ADR-DSN certification protocols that mandate documented traceability for all photometric components. This regulatory architecture is fragmenting vendor qualification pools as smaller manufacturers lack documentation infrastructure. Airports in France and the Netherlands are consolidating procurement around pre-qualified supplier lists to accelerate compliance verification.
Performance-based maintenance contracts are displacing traditional break-fix service arrangements across major hub operators. Lighting system providers now guarantee availability metrics and absorb operational risk through multi-year service agreements. This contractual evolution is most advanced in the United Kingdom and Scandinavian markets where airport privatization has sharpened focus on operational expenditure predictability.
Airfield Ground Lighting Market Segmentation
Airfield ground lighting procurement patterns diverge sharply across operational contexts. Product specifications, energy mandates, and regulatory compliance timelines create distinct demand profiles that reshape vendor positioning and technology roadmaps.
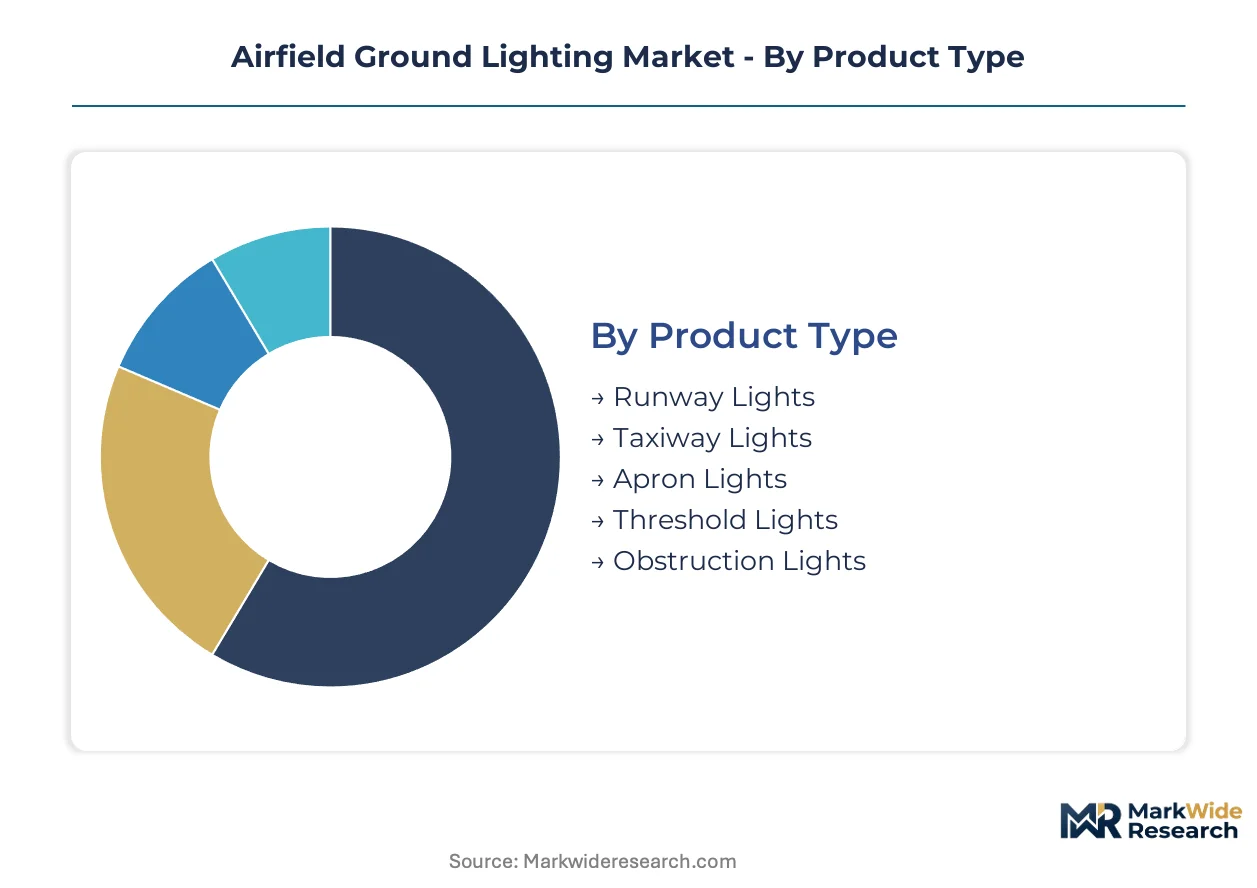
Product Type:
Cost tier separation across airfield zones determines procurement volume and margin structure for each luminaire category.
- Runway Lights:Precision-graded LED arrays with photometric outputs measured in candela dominate new installations. Demand concentrates at major United States hubs including Atlanta and Dallas where FAA AC 150/5345-53 compliance deadlines force accelerated replacement cycles.
- Taxiway Lights:Blue-green chromaticity systems with embedded fault detection circuitry serve high-traffic movement areas. German and Dutch airports are consolidating procurement around pre-qualified supplier lists to satisfy EASA CS-ADR-DSN traceability mandates.
- Apron Lights:High-mast floodlighting systems for aircraft parking and servicing operations.
- Threshold Lights:Wing bar and runway end identifier configurations for approach visibility.
- Obstruction Lights:Military-grade systems for tower and structure marking in defense infrastructure programs.
Runway lights hold installed capacity. Taxiway lights are rotating up the share rankings.
Technology:
Application maturity separates legacy illumination sources from next-generation platforms competing on total cost of ownership.
- LED:Solid-state systems with embedded dimming control and 50,000-hour operational lifespans. Hub operators in Germany and the United Kingdom are capturing energy rebates through full airfield conversions completed within 24-month windows.
- Halogen:Incandescent filament technology with separate mechanical regulators facing mandated phase-out. Aging infrastructure at commercial airports across France and Italy is driving retrofit demand before ICAO Annex 14 compliance deadlines.
- Solar:Photovoltaic-powered units for remote or auxiliary airfield locations.
- Fluorescent:Gas-discharge systems limited to support building and non-movement area applications.
- Xenon:High-intensity discharge technology for specialized obstruction and beacon lighting.
LED platforms command margin expansion. Solar configurations are climbing the fastest.
Application:
Customer type and operational intensity create divergent specification requirements across airfield categories.
- Commercial Airports:24/7 hub operations requiring intelligent lighting platforms with predictive maintenance integration. United States operators managing Atlanta and Dallas expansions are driving bulk procurement of control systems with IoT sensor networks.
- Military Airbases:Defense infrastructure programs in NATO member states opening dedicated procurement channels. Obstruction lighting and hardened control systems face specialized electromagnetic compatibility requirements.
- Private Airstrips:Owner-operated facilities with limited capital budgets and simplified regulatory exposure.
- Cargo Terminals:All-weather operations demanding high-reliability apron and taxiway illumination.
- Heliports:Vertiport and hospital landing zone configurations with compact footprint requirements.
Commercial airports anchor procurement volume. Military airbases are expanding most quickly.
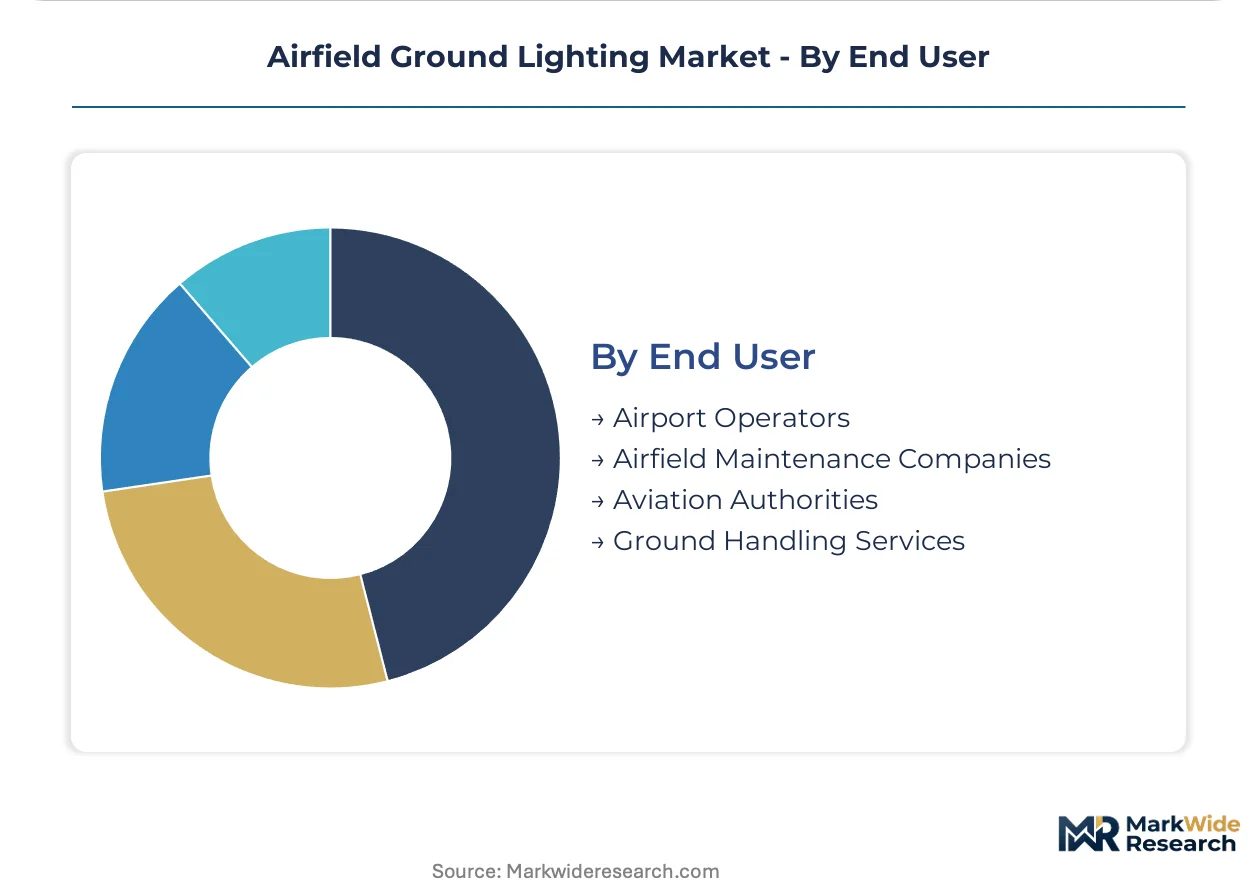
End User:
Procurement authority and maintenance responsibility determine contract structure and vendor relationship models.
- Airport Operators:Direct capital deployment by hub management with long-term operational risk absorption. United Kingdom and Scandinavian operators are shifting toward performance-based maintenance contracts guaranteeing availability metrics.
- Airfield Maintenance Companies:Third-party service providers contesting recurring revenue streams through multi-year agreements. FAA-approved technician certification scarcity limits qualified vendor pools.
- Aviation Authorities:Regulatory bodies mandating compliance verification and certification oversight.
- Ground Handling Services:Apron-area operators with localized lighting requirements tied to fleet contracts.
Airport operators control capital allocation. Airfield maintenance companies are gaining contract share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vendor manufacturing concentrates in Western Europe and North America, with German and Dutch firms controlling precision photometric component supply. Regulatory certification requirements favor established producers with documented traceability infrastructure.
United States
FAA mandates under AC 150/5345-53 are compressing replacement timelines at major hubs. The Infrastructure Investment and Jobs Act directs federal funding toward airfield modernization at congested facilities. Hartsfield-Jackson Atlanta International Airport and Dallas-Fort Worth International Airport are executing bulk procurement of intelligent lighting control systems.
Germany
EASA CS-ADR-DSN specifications enforce component-level traceability that fragments vendor qualification pools. Energy rebate programs accelerate full airfield LED conversions within 24-month windows. Frankfurt and Munich airports are consolidating procurement around pre-qualified supplier lists to streamline compliance verification.
United Kingdom
Airport privatization has sharpened operator focus on operational expenditure predictability through performance-based contracts. The Civil Aviation Authority maintains stringent photometric testing protocols for runway lighting systems. London Heathrow and Manchester Airport Group are shifting toward availability-guarantee maintenance arrangements.
France
Aging halogen infrastructure at regional commercial airports faces mandated phase-out before ICAO Annex 14 compliance deadlines. DGAC oversight requires documented certification for all airfield electrical installations. Paris-Charles de Gaulle and Lyon-Saint Exupéry are prioritizing taxiway lighting upgrades with embedded fault detection circuitry.
Netherlands
Schiphol Group's sustainability targets drive procurement of extended-lifespan LED systems with predictive maintenance integration. The Human Environment and Transport Inspectorate enforces harmonized standards with EASA baseline requirements. Rotterdam The Hague Airport is piloting IoT-connected lighting networks for real-time operational monitoring.
Airfield Ground Lighting Market Competitive Landscape
Full-service platform providers and specialized component fabricators split the market along the hardware-software boundary. The installed base of legacy series circuit infrastructure creates stickiness that favors incumbents with long-term service relationships. Three archetypes dominate: integrated lighting-control system vendors, LED-specific technology specialists, and diversified industrial conglomerates with aviation divisions. Competitive dynamics center on multi-year performance contracts and cybersecurity certification for connected infrastructure.
Among European-anchored specialists, TKH Airport Solutions and OCEM Airfield Technology exemplify the technology-specialist archetype through concentrated focus on LED-based airfield applications. ADB SAFEGATE occupies a position representing the integrated platform model, leveraging control system expertise to capture recurring service revenue streams. These three firms illustrate how vendor positioning stratifies between hardware shipment volumes and data-enabled long-term contracts.
| Leading Market Players |
|---|
| TKH Airport Solutions |
| ATG Airports Limited |
| ADB SAFEGATE |
| Signify Netherlands BV |
| Astronics Corporation |
| Honeywell International Inc. |
| OCEM Airfield Technology |
| Siemens AG |
| Eaton Corporation |
| Others |
Pricing and Supply Chain Analysis
Dutch and German precision photometric component clusters anchor global supply capacity for LED driver assemblies and series circuit cabling, concentrating manufacturing leverage among established vendors who translate input cost stability into premium pricing power for certified airfield systems.
Pricing Analysis
Extended maintenance contracts and performance-based service agreements drive lifetime value capture for platform providers. Pricing stratifies across premium certified tiers, standard compliance-grade systems, and economy retrofit configurations differentiated by FAA AC 150/5345-53 validation status and embedded software capabilities. Cost compression in halogen replacement segments is intensifying because energy rebate programs accelerate procurement timelines. Regional airport operators in France and Italy exhibit highest price sensitivity due to constrained capital budgets, while United States hub operators absorb premium pricing for intelligent control integration.
Supply Chain Analysis
Supplier financing facilities with 90-180 day extended payment terms are becoming standard for LED array and copper conductor procurement, easing working capital pressure on airfield electrical contractors. Manufacturing concentrates in Germany, the Netherlands, and the United States for precision photometric components, while semiconductor inputs for embedded control systems draw from Taiwan and South Korea. Single-source vulnerability for FAA-certified LED drivers creates structural exposure to qualification timeline delays. Distribution runs through authorized airfield electrical contractors with FAA-approved technician certification, limiting direct vendor access to end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating around major United States hub operators and privatized European airport groups, consolidating procurement authority into fewer decision-makers with multi-year framework agreements.
For Market Incumbents: Build switching-cost moats through deep integration of predictive maintenance platforms with legacy 6.6 ampere series circuit infrastructure. Incumbents should capture long-term service agreements before LED retrofit cycles conclude, leveraging installed base data to preempt third-party maintenance providers. Certification investment in emerging cybersecurity frameworks for connected lighting networks provides defensive leverage against software-native entrants. For New Entrants and Emerging Players: Establish a beachhead in military airbase modernization programs across NATO member states, where specialized electromagnetic compatibility requirements create qualification barriers that filter out generalist competitors. Obstruction lighting for defense infrastructure offers penetrable white space with dedicated procurement channels. A go-to-market angle anchored in documented component traceability for EASA CS-ADR-DSN compliance accelerates vendor list inclusion. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because performance-based maintenance contracts displace transactional hardware sales across privatized airport portfolios. Acquisition targets should display embedded software development capabilities and established FAA or EASA certification pipelines. The signal to watch is consolidation of third-party airfield maintenance providers as airport operators outsource operational risk.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Investment | FAA and EASA frameworks for connected lighting networks favor vendors with integrated security architectures. |
| Performance-Based Maintenance Contracting | United Kingdom and Scandinavian airport privatization models shift risk to vendors through availability guarantees. |
| LED Retrofit Acceleration | German energy rebate programs compress 24-month conversion windows, eliminating mid-tier suppliers lacking software capabilities. |
| Military Airbase Specialization | NATO defense infrastructure programs open dedicated procurement channels for electromagnetic-hardened obstruction systems. |
| Component Traceability Infrastructure | EASA CS-ADR-DSN mandates fragment vendor pools by requiring documented photometric component documentation systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airport electrical engineering directors, FAA-certified airfield maintenance contractors, procurement leads at major United States hub operators, and EASA compliance officers at European airport groups. Secondary validation drew from FAA AC 150/5345-53 certification databases, EASA CS-ADR-DSN regulatory filings, airport capital expenditure disclosures, and customs records for photometric component trade flows. Bottom-up installation volume estimates triangulated against top-down market sizing from regulatory compliance deadline analysis.
Calibration against historical replacement cycle data and announced hub expansion projects anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application context, and end-user procurement authority, with regional regulatory cluster as an additional aviation-specific dimension. CAGRs were derived from fitting logistic adoption curves to LED penetration rates and retrofit mandate timelines. Forecast inputs incorporated copper and semiconductor price volatility indices alongside certified technician graduation capacity constraints.
Sensitivities concentrate around FAA certification timeline extensions, EASA traceability mandate enforcement intensity, and defense infrastructure budget allocation shifts. Forecasts reflect assumptions regarding regulatory deadline adherence and technology substitution rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
North America Aviation Infrastructure Market