
 North America Ground Handling System Market | 2026-2036
North America Ground Handling System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ground Handling System Market Analytics
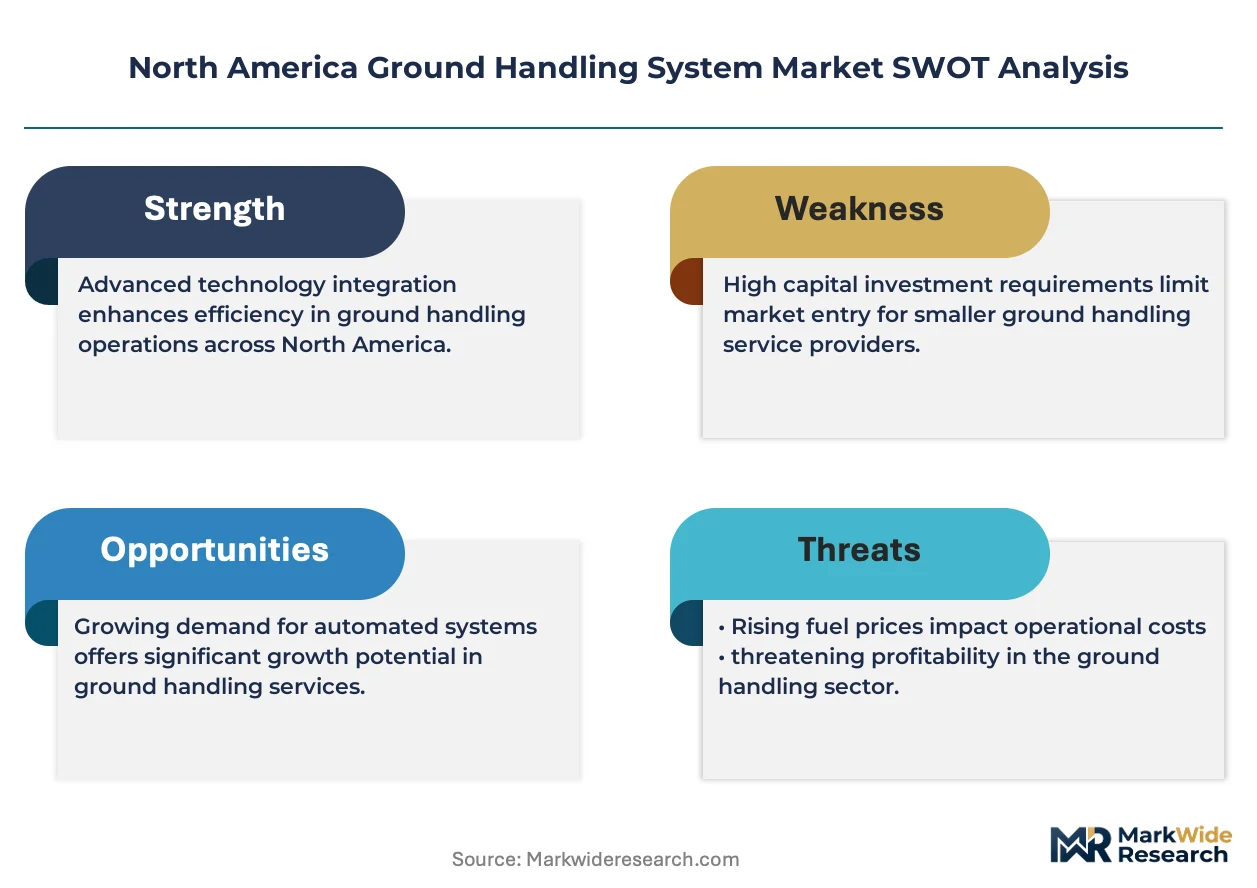
Software-defined fleet management is recalibrating how ground handling contracts are priced and fulfilled across North American airports. JBT Corporation leverages its integrated Jetway and ground support portfolio to anchor long-term service agreements with major hub operators. Textron Ground Support Equipment Inc. competes through specialized military-to-commercial product lines that sustain margin pools in niche segments. Cavotec SA differentiates via automated aircraft docking and electrified apron solutions that reduce turnaround variability.
North America Ground Handling Systems encompass the mechanized equipment, control software, and service protocols used to service aircraft between flights, including baggage tractors rated for 25-ton drawbar pull, cargo loaders with 35-foot vertical reach, and conveyor systems processing 3,000 items per hour. These systems exist to minimize aircraft ground time while ensuring safety compliance during fueling, cleaning, catering, and cargo exchange. Equipment Type segmentation shows tractors and baggage tugs dominating current procurement volumes as airports replace diesel fleets, while automated systems within the Technology dimension represent the fastest-expanding margin pool as operators seek to reduce labor dependency on congested aprons. Cargo Services under Service Type are gaining structural importance as e-commerce flows through Memphis, Louisville, and Cincinnati hubs reshape utilization patterns.
FAA airworthiness directives and OSHA workplace safety standards govern equipment certification and operator training requirements across the United States, while Transport Canada regulations enforce parallel standards for Canadian airport operators. The EPA's emissions thresholds for non-road equipment are accelerating electric and hybrid propulsion investments among equipment lessors and airport authorities. Stakeholders must monitor how pending infrastructure legislation affects apron electrification funding and whether union labor agreements adapt to autonomous ground support deployment timelines.
Market Dynamics
Fleet electrification mandates from the FAA are compressing equipment replacement cycles across North American airports. Airlines now prioritize turnaround speed over capital longevity, forcing ground handlers to renegotiate service-level agreements around electric asset availability.
Growth Catalysts
- FAA Electrification Directives:The FAA's updated ground support equipment emissions standards are compelling airports in Atlanta and Charlotte to accelerate battery-powered tug procurement. Hub operators face 2027 compliance deadlines.
- E-Commerce Cargo Volumes:Memphis, Louisville, and Cincinnati sorting facilities are driving demand for high-throughput conveyor systems capable of processing 3,000 items per hour. Express carriers are expanding dedicated freighter stands.
- Automated Docking Systems:Cavotec SA's electrified apron solutions are reducing aircraft parking variability at congested gates. Major carriers are retrofitting legacy terminals with sensor-guided alignment equipment.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production for electric tugs concentrates in Asian manufacturing clusters, exposing North American equipment lessors to raw material price volatility and extended lead times.
- OSHA Training Mandates:The Occupational Safety and Health Administration's updated powered industrial truck certification requirements are extending operator onboarding timelines and inflating labor costs for ground handling contractors.
- Legacy Diesel Asset Stranding:Airports with recent diesel fleet investments face accelerated depreciation as EPA non-road emissions thresholds tighten, creating balance sheet pressure for municipal authorities.
Strategic Opportunities
- Canadian Hub Electrification:Transport Canada regulations are trailing FAA timelines by 18-24 months, creating a secondary procurement window for electric ground support equipment suppliers targeting Toronto Pearson and Vancouver International.
- Software-Defined Fleet Management:Predictive maintenance algorithms and real-time asset tracking are enabling outcome-based service contracts that tie vendor compensation to aircraft turnaround performance metrics.
- Autonomous Apron Operations:Convergence of LiDAR navigation and 5G private networks is expanding into unmanned baggage tractor pilots at Dallas-Fort Worth and Denver International, reducing labor dependency during peak banks.
Industry Challenges
- Certified Electric Technician Shortage:High-voltage ground support equipment maintenance requires specialized training that community colleges and union apprenticeship programs have not yet scaled to match fleet conversion timelines.
- Retrofit Integration Complexity:Battery-powered tugs must interface with legacy aircraft tow bars and cargo loader interfaces designed for hydraulic systems, creating engineering validation bottlenecks.
- Union Labor Agreement Friction:International Association of Machinists locals are negotiating autonomous equipment deployment protocols that extend implementation timelines beyond technical readiness dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ground Handling System Market |
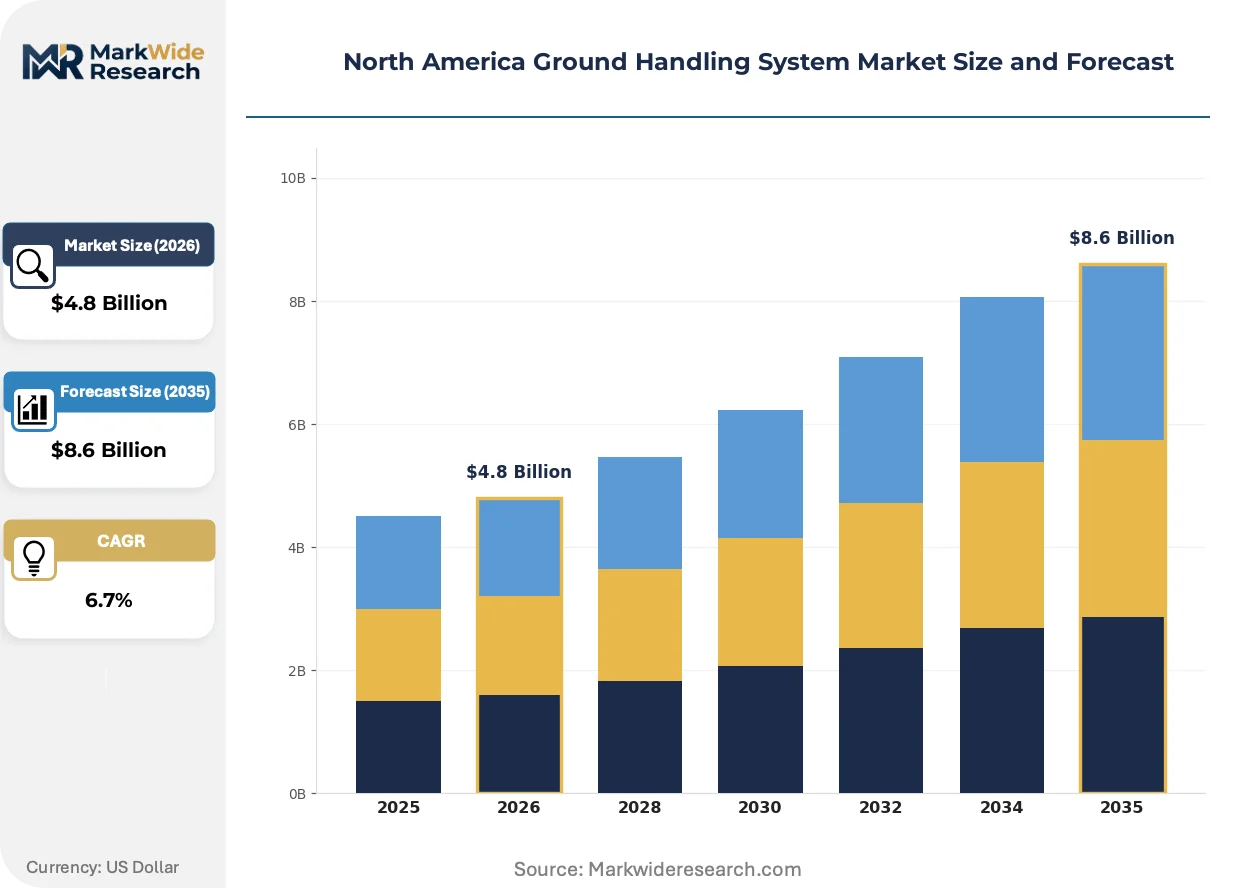
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Passenger Services, Cargo Services, Ramp Services, Technical Services Equipment Type: Tractors, Baggage Tugs, Loaders, Conveyors End User: Airlines, Airport Authorities, Ground Service Providers, Cargo Handlers Technology: Automated Systems, Mobile Apps, RFID Solutions, Ground Support Equipment |
| Companies Covered | JBT Corporation, Textron Ground Support Equipment Inc., Cavotec SA, ALVEST International, ADELTE Group SL, BEUMER Group, Mototok International GmbH, TLD Group, Tronair Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ground Handling System Market Evolving Landscape
Digital twin technology is redefining how ground handling assets are monitored and maintained across North American airport networks. Real-time simulation of equipment stress loads is compressing failure prediction windows from days to hours.
Battery-electric propulsion systems are expanding into the heavy-duty baggage tug segment previously dominated by diesel engines. Delta Air Lines and American Airlines are piloting 40-ton drawbar pull electric tractors at their Atlanta and Dallas-Fort Worth hubs. This shift is expanding into requirements for megawatt-scale apron charging infrastructure that airports must finance through passenger facility charges.
The EPA's Tier 4 Final non-road emissions standards are forcing equipment lessors to retire pre-2015 diesel fleets ahead of depreciation schedules. California's Air Resources Board is enforcing parallel zero-emission mandates for ground support equipment at Los Angeles International and San Francisco International. Cargo handlers operating at Ontario International and Oakland International are responding by consolidating electric equipment orders to achieve volume pricing from manufacturers.
Airline procurement departments are consolidating ground handling contracts under performance-based frameworks that penalize missed connection windows. United Airlines and Southwest Airlines are unbundling equipment ownership from operational service, shifting capital burden to specialized lessors. This restructuring is most visible at Chicago O'Hare and Houston Intercontinental, where hub carriers have transferred fleet management to JBT Corporation and Textron Ground Support Equipment under decade-long agreements.
North America Ground Handling System Market Segmentation
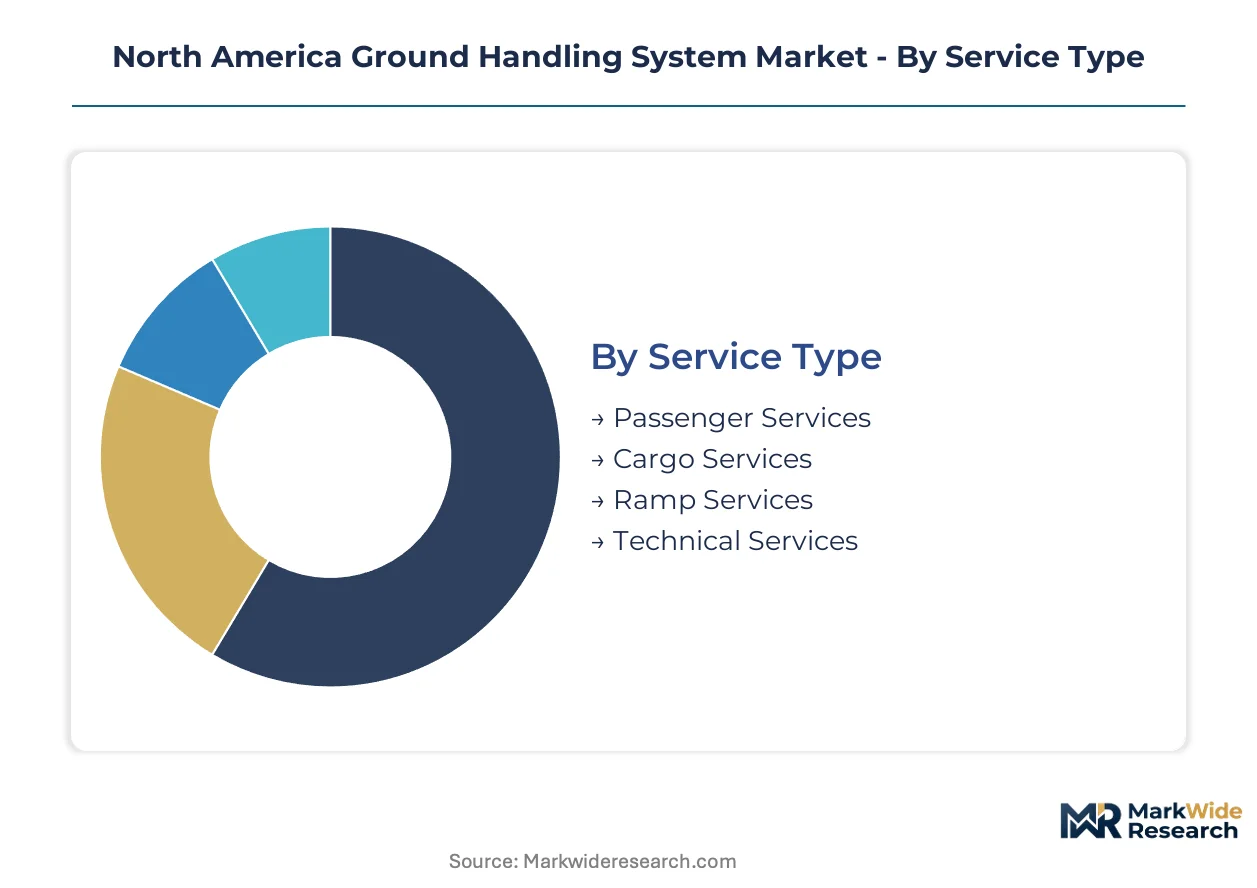
Ground handling system procurement patterns diverge sharply between high-frequency passenger operations and specialized cargo workflows. Equipment specifications, technology integration depth, and contract structures all pivot on which segment anchor dominates a given airport's apron economics.
Service Type:
Volume concentration sits with high-turnaround passenger operations, while premium margins attach to specialized technical and cargo workflows.
- Passenger Services:Aircraft cleaning, catering replenishment, and gate coordination systems designed for sub-45-minute turnarounds. Demand concentrates at Atlanta and Dallas-Fort Worth where Delta and American Airlines compress ground times through synchronized crew deployment.
- Cargo Services:Express parcel sorting, dedicated freighter stand management, and cold-chain handling infrastructure. Memphis, Louisville, and Cincinnati hubs are driving conveyor system upgrades as FedEx and UPS expand overnight sorting capacity.
- Ramp Services:Aircraft marshalling, pushback coordination, and apron safety perimeter management.
- Technical Services:Lavatory servicing, potable water replenishment, and auxiliary power unit maintenance.
Mature deployment sits with Passenger Services. Newer deployment is concentrated in Cargo Services.
Equipment Type:
Cost tier separation runs from diesel legacy fleets at the low end to electrified and autonomous systems commanding procurement premiums.
- Tractors:25-ton to 40-ton drawbar pull vehicles for aircraft positioning and baggage train hauling. The southeastern United States is replacing diesel fleets fastest as Atlanta and Charlotte face FAA electrification deadlines.
- Baggage Tugs:Electric and hybrid units rated for 15-ton to 25-ton loads with rapid-swap battery architecture. California's Air Resources Board mandates are forcing conversions at Los Angeles International and San Francisco International ahead of federal timelines.
- Loaders:35-foot vertical reach cargo loaders with hydraulic or electric lift mechanisms.
- Conveyors:Belt and roller systems processing 3,000 items per hour for baggage claim and sortation facilities.
Procurement volume clusters around Tractors. Technology transition is accelerating fastest in Baggage Tugs.
End User:
Customer type determines capital ownership models, with airlines retaining control at fortress hubs while outsourcing dominates spoke airports.
- Airlines:Major network carriers specifying equipment standards for proprietary ground operations. United and Southwest at Chicago O'Hare and Houston Intercontinental are unbundling ownership from operations, shifting fleet management to specialized lessors under performance-based contracts.
- Airport Authorities:Municipal and regional entities financing apron infrastructure through passenger facility charges. Toronto Pearson and Vancouver International are trailing FAA electrification timelines by 18-24 months, creating secondary procurement windows.
- Ground Service Providers:Third-party contractors operating multi-airline equipment pools.
- Cargo Handlers:Express carriers and freight forwarders managing dedicated sorting facilities.
Contract consolidation is most advanced with Airlines. Infrastructure financing innovation is concentrated with Airport Authorities.
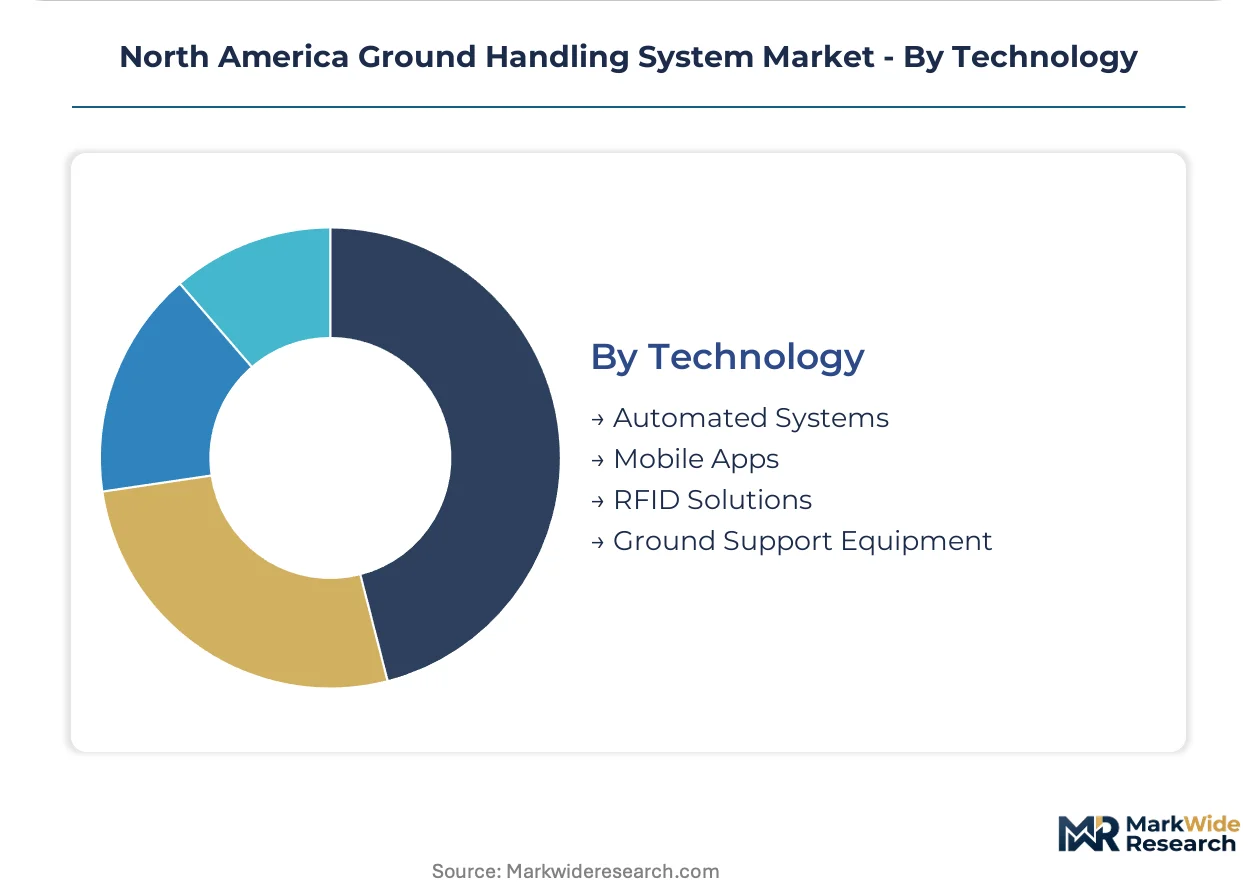
Technology:
Margin concentration shifts from mechanical equipment toward software-defined fleet management and sensor integration layers.
- Automated Systems:Sensor-guided aircraft docking, autonomous baggage tractors, and LiDAR-based apron navigation. Dallas-Fort Worth and Denver International are piloting unmanned tractor operations using 5G private networks to reduce labor dependency during peak banks.
- Mobile Apps:Real-time asset tracking and turnaround coordination interfaces for ground crews. Digital twin deployments are compressing equipment failure prediction windows from days to hours across major hub networks.
- RFID Solutions:Baggage and cargo tracking tags integrated with conveyor sortation systems.
- Ground Support Equipment:Conventional mechanized systems without integrated connectivity layers.
Installed base dominance rests with Ground Support Equipment. Steepest expansion trajectory belongs to Automated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturing concentrates in the industrial Midwest and Southeast United States, while Canadian procurement trails by 18-24 months. Mexican airports serve as secondary demand nodes for refurbished diesel fleets displaced by EPA mandates north of the border.
United States
FAA electrification deadlines are compressing replacement cycles at Atlanta and Charlotte hubs. The EPA's Tier 4 Final non-road emissions standards are forcing early retirement of pre-2015 diesel tugs. California's Air Resources Board enforces parallel zero-emission mandates at Los Angeles International and San Francisco International ahead of federal timelines.
Canada
Transport Canada regulations are trailing FAA mandates by 18-24 months, creating a secondary procurement window. Toronto Pearson and Vancouver International are financing apron electrification through airport improvement fees. Cold-weather battery performance testing is delaying electric tug deployment at Edmonton International and Calgary International.
Mexico
Mexico City International and Cancun International are absorbing refurbished diesel equipment from US fleet retireals. The country's federal aviation regulator maintains less stringent emissions thresholds than the EPA. Guadalajara International and Monterrey International are expanding cargo handling capacity for cross-border e-commerce flows.
North America Ground Handling System Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North American ground handling equipment sector. The vendor base separates between integrated system suppliers and specialized component fabricators. Three archetypes dominate: full-service ground support conglomerates, military-to-commercial crossover specialists, and electrification-focused automation vendors. Consolidation is accelerating through long-term service agreements that bundle equipment ownership with operational performance guarantees.
Among integrated system suppliers, JBT Corporation anchors long-term hub contracts through combined Jetway and ground support portfolios. Textron Ground Support Equipment Inc. exemplifies the military-to-commercial crossover archetype, sustaining margin pools in specialized segments. Cavotec SA occupies a position within the electrification-focused tier, differentiating through automated aircraft docking and apron infrastructure solutions.
| Leading Market Players |
|---|
| JBT Corporation |
| Textron Ground Support Equipment Inc. |
| Cavotec SA |
| ALVEST International |
| ADELTE Group SL |
| BEUMER Group |
| Mototok International GmbH |
| TLD Group |
| Tronair Inc. |
| Others |
Value Network & Pricing Analysis
Lithium-ion battery cell costs cascade through electric tug and loader pricing tiers, originating from concentrated Asian manufacturing clusters and amplifying procurement premiums for North American airport operators facing FAA electrification mandates. Equipment lessors pass through raw material volatility via contract escalation clauses, while hub carriers absorb upfront capital premiums to secure fleet availability ahead of compliance deadlines.
Pricing Analysis
Cost-down pressure on electric ground support equipment accelerates because lithium-ion supply concentration in Asian manufacturing clusters exposes North American lessors to raw material price swings and extended fulfillment timelines. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified electric fleets from transitional hybrid units and stranded diesel assets. Price differentiation rests on EPA Tier 4 Final compliance certification and after-sales service bundling. Cargo handlers at Memphis and Louisville express highest price sensitivity due to volume procurement cycles, while fortress hub operators at Atlanta and Dallas-Fort Worth prioritize performance guarantees over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale airline procurement, while specialized distributors serve municipal airport authorities and third-party ground handlers. Manufacturing concentrates in China, South Korea, and Japan for battery cells, with final assembly and system integration distributed across the US industrial Midwest and Southeast. Raw material dependencies include lithium carbonate, nickel sulfate, and rare earth permanent magnets for electric motor assemblies. Single-source vulnerability in semiconductor power electronics creates fulfillment bottlenecks for smart charging infrastructure. Distribution runs through equipment lessors holding long-term service agreements with major hub operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Ground Handling System Market functions as a cost-of-compliance arena where FAA electrification mandates erect regulatory moats favoring incumbent suppliers with certified electric portfolios and established service networks.
For Market Incumbents: Acquire certified electric technician training capabilities to address the widening gap between fleet conversion timelines and available maintenance labor pools. Consolidate aftermarket parts distribution in the southeastern United States to capture recurring revenue from Atlanta and Charlotte hub expansions. Battery cell supply agreements represent the critical defensive lever against Asian manufacturing concentration risks. For New Entrants and Emerging Players: Launch via outcome-based service contracts that tie compensation to aircraft turnaround performance metrics rather than equipment ownership transfers. Canadian hub electrification presents the most penetrable geography, with Transport Canada regulations trailing FAA timelines and Toronto Pearson financing apron infrastructure through airport improvement fees. Specialized cold-weather battery performance solutions offer differentiation at Edmonton International and Calgary International. For Investors and Strategic Acquirers: Transport Canada regulatory publication schedules are the leading indicator that Canadian procurement windows will open 18-24 months after FAA compliance deadlines. Long-term viability centers on vendors controlling software-defined fleet management layers rather than mechanical equipment fabrication. Acquisition targets should display integrated Jetway and ground support portfolios or electrified apron automation capabilities. Monitor union labor agreement negotiations at International Association of Machinists locals as the inflection signal for autonomous equipment deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Mitigates lithium-ion price volatility exposure for electric tug manufacturers serving FAA-mandated hubs. |
| Software-Defined Fleet Management Platform Launch | Enables outcome-based contracts tying JBT Corporation compensation to Delta turnaround metrics at Atlanta. |
| Canadian Hub Electrification Partnership | Positions vendors ahead of Transport Canada deadlines at Toronto Pearson and Vancouver International. |
| Autonomous Apron Operations Pilot | Leverages 5G private networks at Dallas-Fort Worth to reduce labor dependency during peak banks. |
| Certified Electric Technician Apprenticeship Program | Addresses maintenance labor scarcity threatening fleet conversion timelines across southeastern US airports. |
Research Methodology
Document review covered FAA airworthiness directives, EPA non-road emissions standards, Transport Canada regulations, and equipment manufacturer technical specifications, complemented by interviews with airport operations directors, ground handling contract managers, airline procurement executives, and electric vehicle charging infrastructure specialists. Secondary validation drew from SEC filings of publicly traded ground support equipment vendors, customs trade data on battery cell imports, and municipal airport authority capital improvement plans. Bottom-up equipment procurement forecasts were triangulated against top-down airport passenger and cargo volume projections.
Cross-referencing historical replacement cycle patterns with expert panel input on electrification adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include equipment type, service category, technology tier, and end-user ownership structure. CAGRs were derived from equipment unit demand projections and average selling price trajectories for electric versus diesel propulsion systems. Industry-specific forecast inputs incorporated FAA compliance deadline schedules and union labor agreement negotiation timelines.
Regulatory enforcement delays, battery cell supply disruptions, and autonomous equipment deployment friction are the dominant revision risks to base case assumptions. Forecasts reflect documented electrification mandates and announced hub expansion timelines. Periodic stress-testing of base assumptions against Transport Canada publication schedules and lithium carbonate price indices is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Aerobridge Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Aircraft Ground Support Equipment Market
Airport Infrastructure
Airport Stands Equipment Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Aircraft Cargo Handling Equipment Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Global Commercial Airport Lighting Market