
 Runway Lighting System Market | 2026-2036
Runway Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
Runway Lighting System Market Analytics
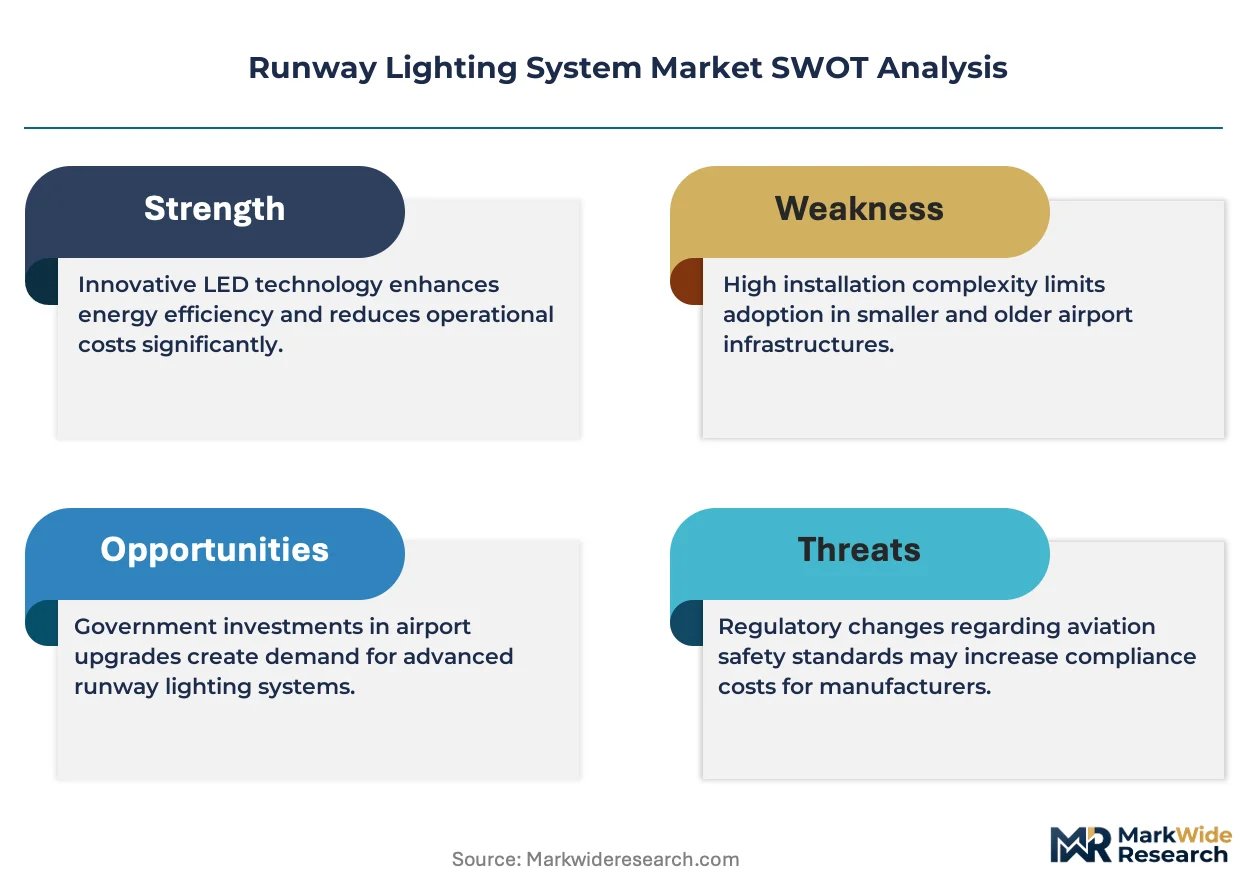
Civil aviation authorities is reorganizing procurement priorities toward energy-efficient airfield illumination. ADB SAFEGATE leverages its vertical integration across design, manufacturing, and installation services to capture turnkey contracts. Honeywell International Inc. sustains technology leadership through embedded sensor networks that enable remote monitoring of runway edge fixtures. Eaton Corporation anchors its position in North American military airbase retrofits with hardened electrical infrastructure.
Runway lighting systems comprise precision-engineered luminaires, electrical cabling, and control cabinets engineered to deliver specified candela output under International Civil Aviation Organization photometric requirements. These systems enable pilots to maintain situational awareness during low-visibility operations including night flights and instrument meteorological conditions. LED product types command expanding share as operators prioritize lumens-per-watt efficiency and maintenance interval extension. Smart lighting technology segments attract capital as airports deploy centralized dimming protocols and fault-detection algorithms. Commercial airports represent the dominant end-user category, though cargo terminals exhibit accelerated retrofit cycles driven by 24-hour operational schedules.
FAA Advisory Circulars and ICAO Annex 14 establish mandatory luminance thresholds and color specifications that manufacturers must certify before airfield deployment. EPA energy efficiency guidelines additionally shape product development roadmaps for domestic suppliers. Stakeholders must monitor evolving photometric standards and assess supply chain exposure to semiconductor components essential for intelligent control systems.
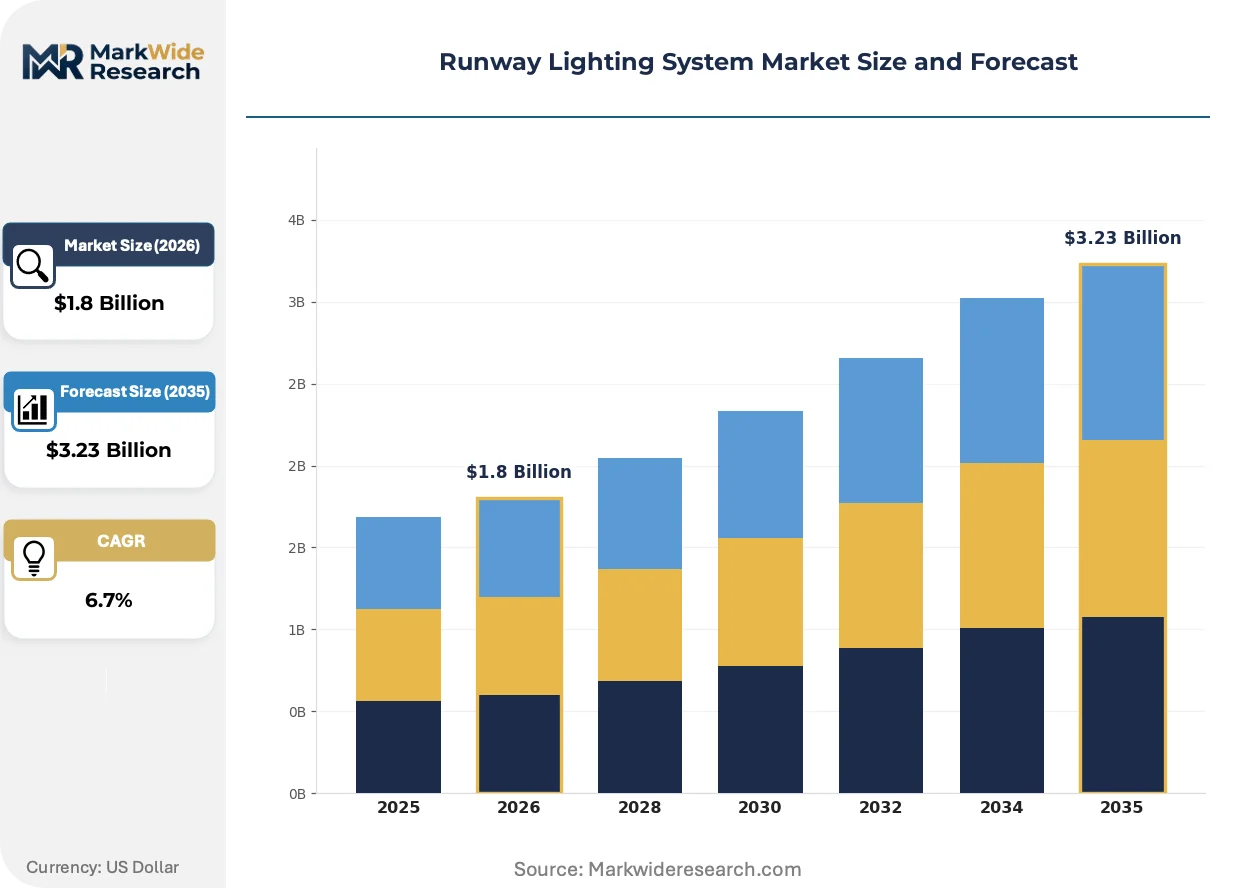
Market Dynamics
FAA Advisory Circular 150/5345-46D mandates photometric upgrades that force airports into synchronized replacement cycles, compressing procurement timelines and concentrating vendor selection around certified turnkey providers.
Growth Catalysts
- LED Retrofit Mandates:EPA energy efficiency guidelines and ICAO Annex 14 luminance standards compel commercial airports to replace incandescent systems. Federal infrastructure programs in the United States accelerate funding availability for these conversions.
- Smart Airport Integration:Centralized dimming protocols and fault-detection algorithms reduce maintenance labor. Cargo terminals with 24-hour operational schedules prioritize these intelligent control systems for uninterrupted throughput.
- Low-Visibility Operations Expansion:Rising instrument meteorological condition flight volumes require enhanced runway edge visibility. Category III precision approach specifications tighten candela output requirements across major hubs.
Market Restraints
- Semiconductor Supply Concentration:Intelligent control systems depend on specialized LED drivers and microcontrollers. East Asian foundry concentration creates procurement vulnerability for North American and European system integrators.
- Copper and Aluminum Price Volatility:Runway lighting infrastructure requires extensive electrical cabling. Base metal commodity swings directly impact project budgeting accuracy for airport authorities.
- Incumbent System Compatibility:Legacy halogen infrastructure uses proprietary control protocols. Retrofit projects face integration friction when mixing generations of airfield lighting technology.
Strategic Opportunities
- Secondary Airport Modernization:Regional and municipal airports in the United States lag major hubs in LED adoption. Federal Airport Improvement Program grants create accessible funding pathways for these facilities.
- Photovoltaic-LED Hybrid Systems:Solar-powered taxiway edge lights reduce grid dependency. Remote airfields and military forward operating bases represent untapped deployment terrain.
- Performance-Based Navigation Infrastructure:ICAO PBN implementation requires synchronized ground lighting upgrades. Contractors offering bundled design-certification-installation services capture expanded contract scopes.
Industry Challenges
- Photometric Certification Timeline:FAA Engineering Brief 67 and ICAO certification processes require 18-24 month validation cycles. Product development roadmaps must accommodate regulatory lead times.
- Legacy Control System Integration:Airports operate mixed-vendor lighting networks spanning decades. Interoperability testing consumes significant engineering resources during upgrade projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Runway Lighting System Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Halogen, Xenon, Fluorescent Technology: Smart Lighting, Traditional Lighting, Solar-Powered, Wireless End User: Commercial Airports, Military Bases, Private Airfields, Cargo Terminals Installation Type: Permanent, Temporary, Modular, Integrated |
| Companies Covered | ADB SAFEGATE, Honeywell International Inc., Eaton Corporation, OCEM Airfield Technology, Siemens AG, TKH Airport Solutions, Astronics Corporation, Carmanah Technologies Corporation, ATG Airports Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Runway Lighting System Market Evolving Landscape
Photometric engineering and control intelligence are converging to redefine how airfield lighting systems specify, procure, and maintain operational readiness across commercial and military installations.
Adaptive LED arrays with individually addressable nodes are fragmenting the traditional luminaire market. Major international hubs deploy these systems for dynamic intensity adjustment based on real-time meteorological data. The technology compresses hardware standardization as airports demand software-configurable rather than fixed-optic solutions.
ICAO is revising Annex 14 Volume I provisions for sustainable airfield design. The framework will mandate lifecycle carbon accounting for lighting infrastructure materials and energy consumption. European airports under EU Green Deal compliance timelines are pre-positioning procurement specifications to meet anticipated requirements.
Consolidated facility management contracts now bundle lighting maintenance with broader airfield operations. Large hub airports in the United States favor single-source providers responsible for both capital installation and decade-long service agreements. This restructuring displaces traditional equipment-only vendors and elevates turnkey contractors with in-house electrical maintenance capabilities.
Runway Lighting System Market Segmentation
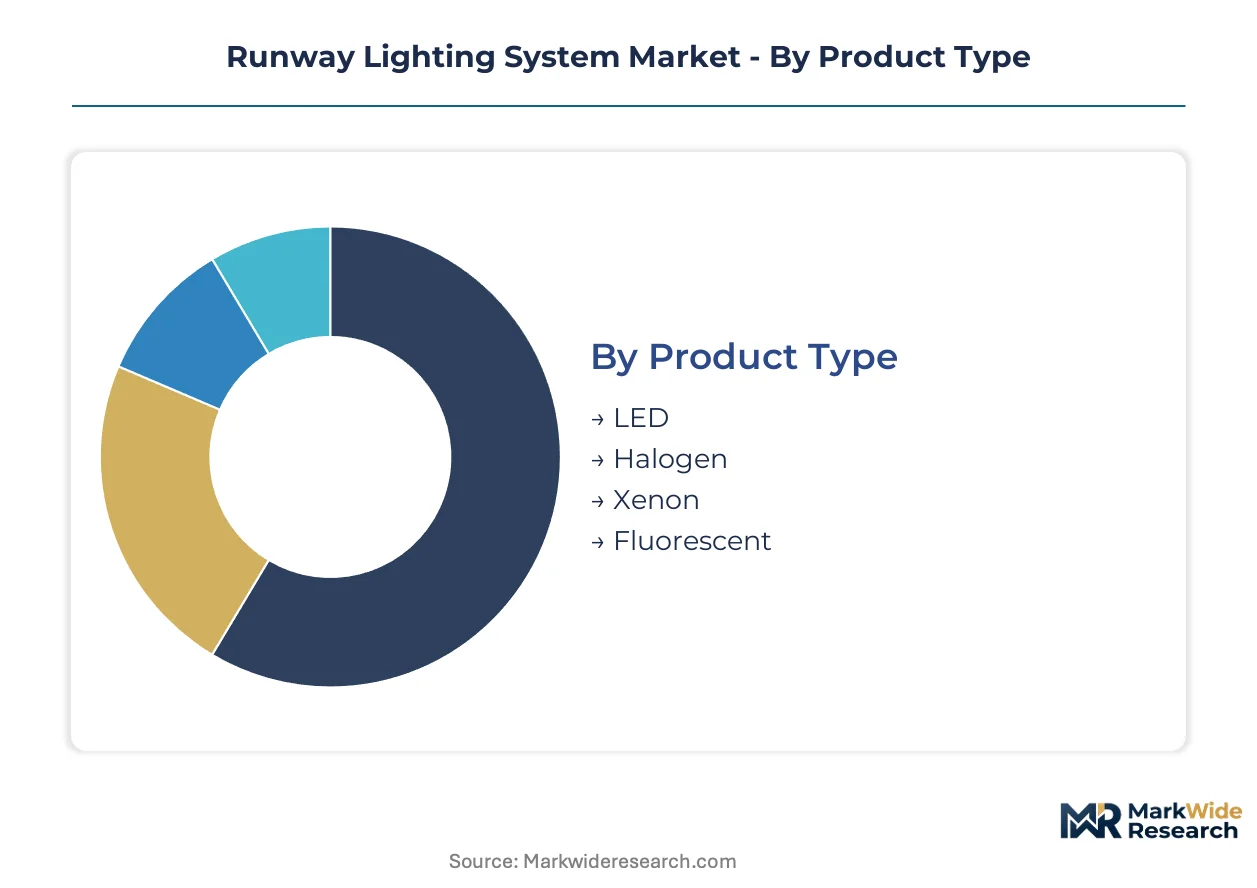
Runway lighting procurement decisions hinge on certification tiers, operational duty cycles, and infrastructure lifecycle positioning. Segmentation reveals where capital concentrates versus where retrofit urgency builds.
Product Type:
FAA Advisory Circular 150/5345-46D and ICAO Annex 14 establish divergent photometric thresholds that manufacturers must certify against, creating product-tier stratification based on regulatory jurisdiction rather than pure performance metrics.
- LED:Solid-state semiconductor arrays deliver specified candela output with lumens-per-watt efficiency exceeding legacy alternatives. Commercial airports in the United States prioritize LED retrofits under federal infrastructure funding timelines, though semiconductor supply concentration constrains procurement velocity for North American system integrators.
- Halogen:Tungsten-filament technology with established FAA certification histories dominates incumbent installed bases. Military airbase retrofits in the United States sustain residual demand where hardened electrical infrastructure compatibility outweighs efficiency gains.
- Xenon:High-intensity discharge lamps serve specialized approach lighting applications requiring precise color temperature control.
- Fluorescent:Linear tube configurations persist in taxiway sign illumination and secondary airfield marking applications.
Established volume favors halogen; emerging adoption favors LED.
Technology:
Control architecture sophistication separates capital-intensive new-build projects from maintenance-budget retrofit cycles across airport categories.
- Smart Lighting:Centralized dimming protocols with embedded sensor networks enable remote monitoring of runway edge fixtures. Cargo terminals with 24-hour operational schedules deploy these systems for fault-detection algorithms that reduce maintenance labor and sustain uninterrupted throughput.
- Traditional Lighting:Hardwired relay-based control systems without data connectivity dominate secondary airport infrastructure. Regional and municipal airports in the United States lag major hubs in intelligent control adoption due to constrained Airport Improvement Program grant accessibility.
- Solar-Powered:Photovoltaic-LED hybrid configurations reduce grid dependency for remote airfields and military forward operating bases.
- Wireless:Radio-frequency control links eliminate trenching requirements for temporary runway configurations and rapid-deployment scenarios.
Smart lighting commands premium contract scopes; solar-powered configurations address infrastructure gaps where grid extension proves uneconomical.
End User:
Operational tempo and regulatory scrutiny intensity create distinct procurement patterns across airfield categories.
- Commercial Airports:Category III precision approach specifications at major hubs mandate enhanced runway edge visibility systems. FAA mandates for photometric upgrades compress procurement timelines and concentrate vendor selection around certified turnkey providers capable of synchronized replacement cycles.
- Cargo Terminals:24-hour operational schedules prioritize intelligent control systems with predictive maintenance capabilities. These facilities exhibit accelerated retrofit cycles driven by throughput continuity requirements and labor cost containment objectives.
- Military Bases:Hardened electrical infrastructure specifications and electromagnetic interference resilience dominate procurement criteria.
- Private Airfields:Owner-operator budget constraints favor modular upgrade pathways over comprehensive system replacements.
Commercial airports anchor capital deployment; cargo terminals represent the steepest expansion trajectory for smart technology penetration.
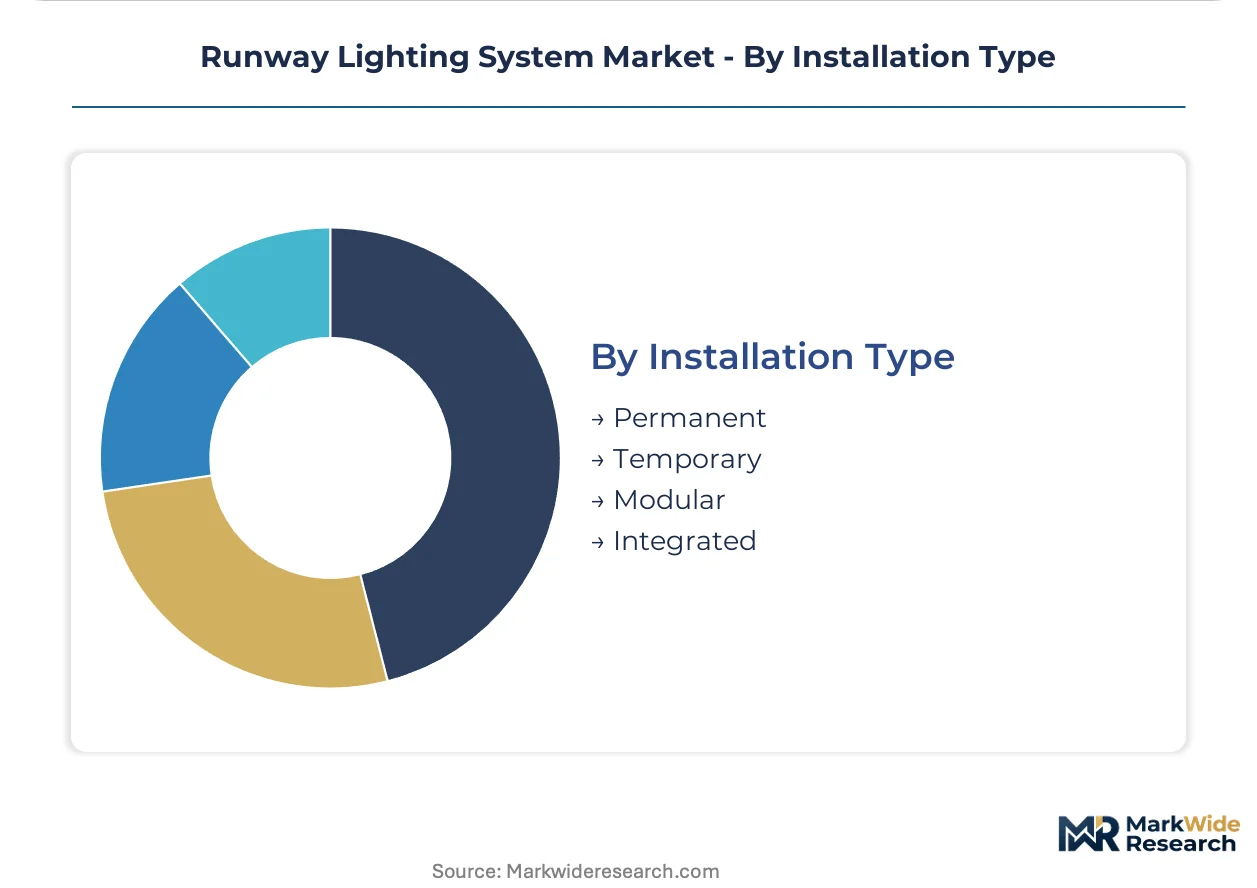
Installation Type:
Project delivery methodology shapes contractor selection and long-term service obligation structures.
- Permanent:Cast-in-place concrete foundations with integrated electrical conduit systems serve core runway infrastructure at hub airports. Large hub airports in the United States favor single-source providers responsible for both capital installation and decade-long service agreements under consolidated facility management contracts.
- Modular:Pre-cast base assemblies with plug-and-play electrical connections enable phased retrofit sequences without full runway closures. Secondary airport modernization projects leverage these configurations to accommodate intermittent funding availability and operational continuity requirements.
- Temporary:Portable lighting arrays support construction zones and emergency runway restoration scenarios.
- Integrated:Bundled design-certification-installation services capture expanded contract scopes under ICAO Performance-Based Navigation implementation timelines.
Permanent installations dominate replacement cycles; modular approaches gain traction where operational disruption minimization overrides first-cost optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and French manufacturers export precision-engineered runway lighting systems to Middle Eastern and Asian airport authorities. These trade corridors concentrate high-value contracts for Category III precision approach infrastructure. Procurement timelines compress as federal infrastructure programs accelerate funding disbursements.
United States
Federal Airport Improvement Program grants drive LED retrofit cycles at commercial hubs. FAA Advisory Circular 150/5345-46D mandates photometric upgrades that synchronize replacement timelines. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor North American procurement volume for turnkey installation contracts.
Germany
Industrial automation expertise feeds demand for intelligent control systems at Frankfurt and Munich airports. EU Green Deal compliance timelines pre-position procurement specifications for lifecycle carbon accounting. Bavaria's engineering clusters supply embedded sensor networks for remote runway monitoring.
China
Beijing Daxing and Shanghai Pudong expansion projects absorb high volumes of LED-based smart lighting infrastructure. GB standards and MIIT directives shape domestic certification requirements for airfield illumination. Yangtze River Delta manufacturing bases produce semiconductor components for intelligent control systems.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International prioritize 24-hour operational continuity through predictive maintenance systems. Federal aviation regulations align with ICAO Annex 14 luminance thresholds. Dubai South's aviation district concentrates regional distribution for Middle Eastern airport retrofits.
United Kingdom
Heathrow and Gatwick modernization programs drive demand for modular installation configurations. CAA regulations enforce photometric standards equivalent to FAA and ICAO mandates. London's engineering consultancies bundle design-certification-installation services for Performance-Based Navigation upgrades.
Runway Lighting System Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with airfield lighting divisions alongside specialized airfield technology pure-plays. Consolidation pressure intensifies as airports favor single-source providers for decade-long service agreements. Two strategic archetypes dominate: vertically integrated turnkey contractors capturing design-installation-maintenance bundles, and component specialists supplying LED drivers and control modules. Geographic expansion and strategic partnerships represent the dominant competitive moves as vendors chase federal infrastructure funding windows.
Among diversified industrial conglomerates, Honeywell International Inc. and Siemens AG occupy positions spanning building automation into airfield infrastructure. Eaton Corporation exemplifies the North American military-retrofit archetype with hardened electrical infrastructure capabilities. ADB SAFEGATE represents the vertically integrated pure-play model with captive design, manufacturing, and installation capabilities. These three anchors illustrate how certification depth and service bundling separate contract winners from equipment-only vendors in procurement decisions at major international hubs.
| Leading Market Players |
|---|
| ADB SAFEGATE |
| Honeywell International Inc. |
| Eaton Corporation |
| OCEM Airfield Technology |
| Siemens AG |
| TKH Airport Solutions |
| Astronics Corporation |
| Carmanah Technologies Corporation |
| ATG Airports Limited |
| Others |
Value Network & Pricing Analysis
Turnkey installation contracts with decade-long service agreements lock in semiconductor procurement pipelines and stabilize unit economics for airport authorities navigating volatile component markets. FAA-mandated LED retrofit timelines compress vendor selection cycles, forcing buyers into fixed-price arrangements that transfer commodity risk to system integrators.
Pricing Analysis
LED-halogen-xenon pricing stratification reflects certification depth and energy efficiency differentials. Three-tier pricing structure across premium smart systems, standard LED retrofits, and economy halogen replacements dominates procurement. Price differentiation hinges on FAA/ICAO certification tier and bundled maintenance scope. Cost compression in standard LED tiers intensifies because semiconductor foundry concentration limits supply elasticity. Regional and municipal airports exhibit highest price sensitivity; major hubs prioritize certification reliability over first-cost optimization.
Supply Chain Analysis
China and Taiwan anchor LED driver and microcontroller fabrication for intelligent control systems. Yangtze River Delta manufacturing clusters feed semiconductor components to North American and European system integrators. Copper and aluminum draw from Chilean and Australian mining operations for electrical cabling infrastructure. Single-source vulnerability in East Asian foundry networks creates procurement risk for FAA-certified product lines. Distribution runs through vertically integrated turnkey contractors capturing design-installation-maintenance bundles at hub airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar-powered taxiway edge lighting and photovoltaic-LED hybrid architectures threaten incumbent grid-dependent system architectures, forcing established vendors to defend installed base relationships through service contract extensions.
For Market Incumbents: Fortify certification depth through accelerated FAA Engineering Brief 67 validation cycles to outpace emerging solar-hybrid competitors. Captive supply of LED drivers via backward integration into Taiwanese semiconductor partnerships reduces foundry exposure. Extend service contract durations at cargo terminals to lock out modular installation challengers. For New Entrants and Emerging Players: Lead with photovoltaic-LED hybrid configurations targeting remote airfields and military forward operating bases where grid extension costs exclude incumbent solutions. Secondary airport modernization in the United States offers the most penetrable entry point through Federal Airport Improvement Program grant accessibility. Bundle rapid-deployment wireless control systems with solar autonomy to bypass trenching requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated turnkey contractors with in-house electrical maintenance capabilities and decade-long facility management contracts. Long-term viability over a multi-year horizon favors acquisition targets with FAA/ICAO dual certification depth and established relationships at Category III precision approach hubs. Watch for semiconductor supply normalization as the inflection signal for margin expansion in LED retrofit tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Taiwanese foundry partnerships reduce LED driver procurement vulnerability for North American integrators. |
| Photovoltaic-LED Hybrid System Development | Solar autonomy opens remote airfield segments previously uneconomical for grid-dependent incumbents. |
| FAA Dual-Certification Investment | Engineering Brief 67 validation accelerates product approval timelines for synchronized replacement cycles. |
| Consolidated Facility Management Contracting | Single-source decade-long service agreements displace equipment-only vendors at major United States hubs. |
| Performance-Based Navigation Bundling | ICAO PBN implementation creates expanded contract scopes for design-certification-installation integrators. |
Research Methodology
Desk research of FAA Advisory Circulars, ICAO Annex 14 documentation, and federal infrastructure program disbursement records preceded structured interviews with airport procurement directors, electrical engineering consultants, and airfield lighting system integrators. Primary fieldwork with maintenance supervisors at commercial hubs and cargo terminals validated retrofit cycle timing assumptions. Secondary sources included EPA energy efficiency guidelines, EU Green Deal compliance timelines, and semiconductor trade flow data. Bottom-up project pipeline analysis triangulated against top-down federal funding allocation models.
Variance decomposition across technology generation, installation type, and end-user operational tempo shaped the analytical framework throughout the projection horizon. Segmentation dimensions modeled encompassed product type, control architecture sophistication, and regulatory jurisdiction cluster. CAGRs derived from fitted adoption curves for LED retrofit penetration and smart lighting deployment rates. Industry-specific inputs included FAA mandate implementation schedules and Airport Improvement Program grant accessibility patterns.
The analysis sits within stated boundaries; outcomes outside sustained federal infrastructure funding or semiconductor supply normalization would require recalibration. Forecasts reflect assumptions regarding photometric certification timelines and copper commodity stability. Regulatory delay in ICAO Annex 14 revision cycles or tariff escalation in East Asian electronics trade represent specific revision triggers. Recalibration cycles align with material shifts in federal appropriations and foundry capacity expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Global Commercial Airport Lighting Market
Airport Infrastructure
India Aviation Infrastructure Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
Airport Passenger Boarding Bridge Market
Airport Infrastructure
GCC Aviation Infrastructure Market
Airport Infrastructure
Passenger Boarding Bridge Market
Airport Infrastructure
Airfield Ground Lighting (AGL) Systems Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Airport Kiosk Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
Heliports Market