
 Aircraft Ground Support Equipment Market | 2026-2036
Aircraft Ground Support Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Ground Support Equipment Market Analysis
Software-defined fleet management is restructuring how ground support equipment gets sold and serviced. Oshkosh Corporation leverages predictive maintenance platforms to extend equipment uptime for military and commercial clients. TLD Group anchors its European position through electric tow tractor specialization. JBT Corporation competes globally with integrated cargo loader systems that combine hardware with real-time diagnostics.
Aircraft ground support equipment comprises mobile and fixed assets used to service aircraft between flights, including tow tractors with drawbar pull ratings exceeding 600 kN for wide-body jets and 400 Hz solid-state ground power units delivering clean electrical output. The primary purpose is ensuring safe, efficient turnaround operations while minimizing aircraft on-ground time. Electric technology leads growth as airports phase out diesel-powered units under emission reduction programs. Power units command premium pricing due to precision electrical specifications and regulatory certification requirements. Cargo loaders sustain steady demand from e-commerce freight expansion at major hubs.
FAA emission standards under EPA coordination, EU Green Deal aviation sustainability targets, and ICAO carbon reduction frameworks shape product design and procurement criteria across major markets. Ground handling companies and airport authorities must now certify equipment against multi-jurisdiction environmental standards before fleet deployment. Stakeholders should monitor how battery energy density improvements and charging infrastructure investments reshape total cost of ownership calculations for electrified ground fleets.
Market Dynamics
Electrification mandates are restructuring procurement criteria across airport authorities, forcing ground handling operators to retire diesel fleets ahead of depreciation cycles. Battery-powered tow tractors and ground power units now dominate capital expenditure planning.
Growth Catalysts
- EU Green Deal aviation targets:Binding emission reduction frameworks for airport operations are accelerating fleet replacement timelines across European ground handling contracts.
- China airport modernization:Beijing Daxing, Shanghai Pudong, and Guangzhou Baiyun are expanding electrified apron infrastructure to accommodate wide-body traffic growth.
- Solid-state ground power technology:400 Hz frequency converters with silicon carbide inverters are replacing rotary converters due to precision power delivery requirements.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing capacity clusters in China, creating input cost volatility for battery pack assembly.
- Charging infrastructure capex:Airport electrical grid upgrades for high-power charging stations require multi-year capital commitment cycles.
- FAA airworthiness certification timelines:New electric tow tractor designs face extended validation periods for drawbar pull safety testing.
Strategic Opportunities
- India airport privatization wave:Greenfield terminals in Delhi, Mumbai, and Bangalore lack legacy diesel infrastructure, enabling pure-electric fleet deployment.
- Predictive maintenance convergence:IoT sensor networks married with fleet management software are creating subscription revenue streams for equipment OEMs.
- US Inflation Reduction Act clean vehicle credits:Commercial airport equipment qualifies for federal tax incentives when battery sourcing meets domestic content thresholds.
Industry Challenges
- High-voltage technician scarcity:Maintenance crews trained on 800V battery systems and DC fast charging protocols remain insufficient across ground handling workforces.
- Legacy fleet integration:Mixed diesel-electric operations create apron traffic management complexity and require dual training programs for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Ground Support Equipment Market |
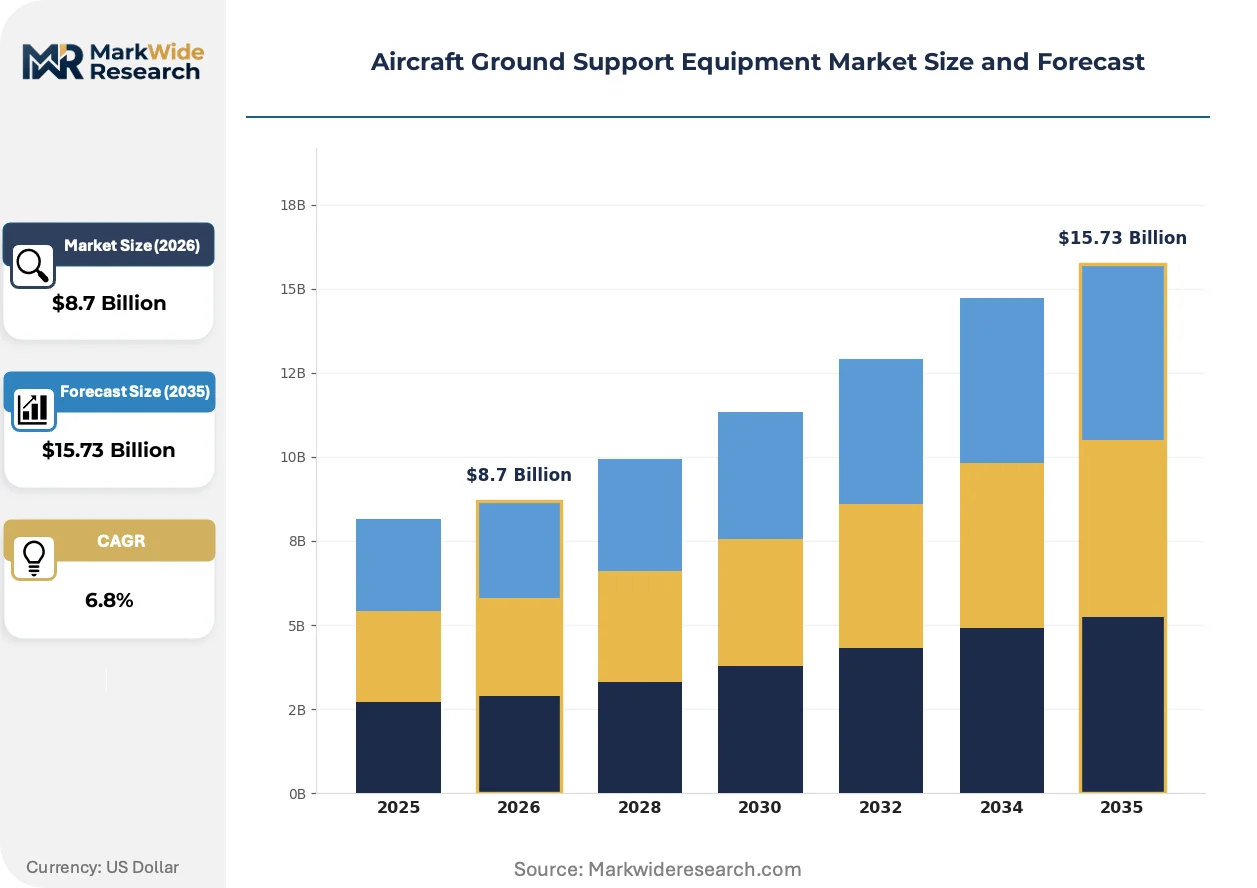
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Units, Baggage Tugs, Tow Tractors, Cargo Loaders Technology: Hydraulic, Electric, Pneumatic, Mechanical Application: Commercial Aviation, Military Aviation, Cargo Handling, Aircraft Maintenance End User: Airports, Airlines, Ground Handling Companies, Defense Contractors |
| Companies Covered | Oshkosh Corporation, TLD Group, JBT Corporation, Textron Ground Support Equipment Inc., China International Marine Containers (Group) Ltd., TCR Group, Weihai Guangtai Airport Equipment Co., Limited, Tronair Inc., ITW GSE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Ground Support Equipment Market Emerging Trajectories
Software-defined functionality is displacing mechanical control systems across ground support equipment categories. Real-time diagnostics and over-the-air updates are becoming standard procurement requirements rather than premium options.
Solid-state power electronics is consolidating aircraft ground power architecture. Silicon carbide and gallium nitride inverters deliver cleaner 400 Hz output with reduced harmonic distortion. Major hub airports in Germany and the Netherlands are specifying these units for wide-body gate positions. The technology is compressing maintenance intervals and extending mean time between failures for ground power operations.
EPA-coordinated FAA emission standards are tightening particulate matter limits for non-road diesel engines used in legacy ground support equipment. Equipment lessors face stranded asset risk on diesel tow tractors and air start units. California Air Resources Board thresholds are influencing procurement specifications at Los Angeles International and San Francisco International ahead of federal compliance deadlines.
Ground handling contracts are unbundling equipment ownership from operational service. Airport authorities increasingly lease electric tow tractors and cargo loaders through power-by-the-hour arrangements rather than capital purchase. This shift concentrates fleet decisions with specialized lessors and compresses switching costs between equipment suppliers. The model is most visible at major European hubs where ground handling deregulation has fragmented service providers.
Aircraft Ground Support Equipment Market Segmentation
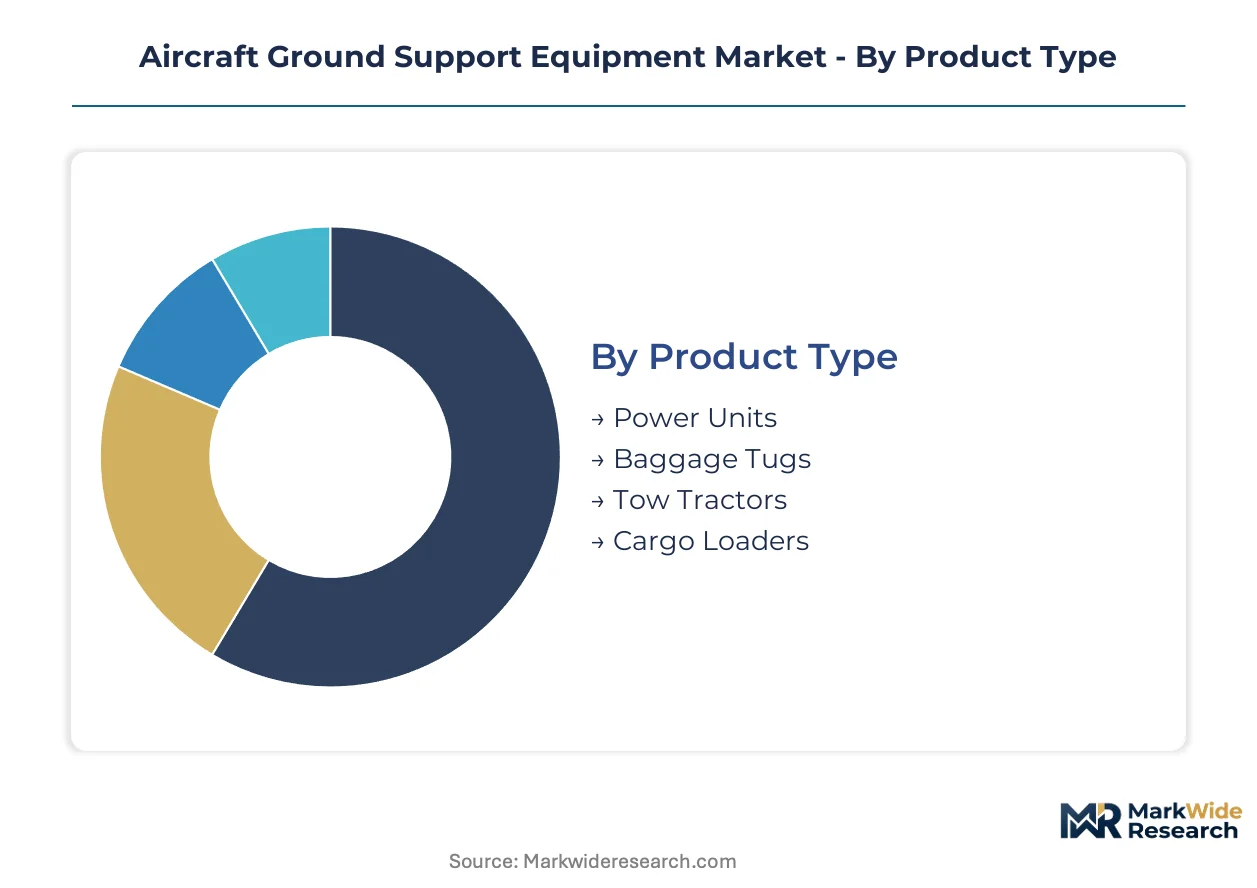
Equipment segmentation reveals distinct replacement cycles across airport infrastructure. Fleet managers align procurement schedules with gate electrification timelines and airframe compatibility requirements.
Product Type:
Upgrade cycles vary sharply by product category, with electrification mandates forcing premature retirement of diesel assets before full depreciation.
- Power Units:400 Hz solid-state frequency converters with silicon carbide inverters deliver precision electrical output for wide-body aircraft. Demand clusters at Beijing Daxing and Amsterdam Schiphol where gate electrification programs require clean power delivery.
- Tow Tractors:Drawbar pull ratings exceeding 600 kN for wide-body jets dominate capital allocation. European ground handling contracts now specify electric variants under EU Green Deal procurement rules, compressing replacement timelines for diesel fleets.
- Baggage Tugs:Battery-powered variants with lithium-iron-phosphate packs serve narrow-body turnaround operations.
- Cargo Loaders:E-commerce freight expansion at Dubai and Memphis hubs sustains steady demand for high-reach units.
Volume placements concentrate in Tow Tractors; the faster expansion belongs to Power Units.
Technology:
Cost tier stratification separates mature mechanical systems from premium electric platforms requiring specialized technician training.
- Electric:Battery-powered tow tractors and ground power units now dominate capital expenditure planning at major hubs. Total cost of ownership calculations increasingly favor electric variants as charging infrastructure scales at Frankfurt and Singapore Changi.
- Hydraulic:Legacy cargo loader systems retain installed base at cargo-focused airports with limited electrification budgets. Maintenance complexity and fluid handling requirements constrain new deployments.
- Pneumatic:Air start units serve regional aircraft at facilities without solid-state ground power infrastructure.
- Mechanical:Basic tow bars and manual baggage carts persist at general aviation terminals with minimal traffic volume.
Revenue concentration sits with Electric systems; Pneumatic platforms face steepest contraction.
Application:
Customer type differentiation separates scheduled passenger operations from defense procurement cycles with distinct certification requirements.
- Commercial Aviation:Turnaround efficiency metrics drive equipment specification at full-service carriers. Gate-compatible electric tow tractors with autonomous docking capabilities command procurement priority.
- Cargo Handling:Dedicated freighter operations at Louisville and Leipzig require specialized high-capacity loaders. E-commerce volume growth reshapes apron layout requirements.
- Military Aviation:Defense contractors specify ruggedized variants with NATO standard interfaces. Procurement cycles align with base modernization programs rather than commercial traffic patterns.
- Aircraft Maintenance:Heavy maintenance hangars utilize fixed-position jacking systems and engine change dollies with extended duty cycles.
Procurement volume concentrates in Commercial Aviation; Cargo Handling claims the steepest expansion trajectory.
End User:
Supply concentration varies by ownership model, with airport authorities increasingly leasing equipment through power-by-the-hour arrangements.
- Ground Handling Companies:Deregulated European markets fragment fleet ownership across specialized service providers. Swissport and dnata specify standardized electric platforms to enable crew rotation across multiple airport contracts.
- Airports:Authority-owned fleets at Singapore and Denver International centralize procurement decisions with long-term electrification roadmaps. Direct ownership enables charging infrastructure coordination.
- Airlines:Hub carriers at Atlanta and Dallas-Fort Worth maintain captive ground support fleets for premium gate positions.
- Defense Contractors:Military ground handling services operate under separate procurement frameworks with airworthiness certification requirements.
Equipment placements concentrate with Ground Handling Companies; Airports demonstrate the fastest adoption of integrated fleet management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in China and Germany while fleet deployment concentrates at hub airports across multiple continents. Consumption patterns diverge between mature markets retiring diesel assets and emerging economies building electrified infrastructure from inception.
United States
Atlanta Hartsfield-Jackson and Dallas-Fort Worth anchor domestic fleet replacement demand as hub carriers modernize captive ground support assets. FAA emission standards under EPA coordination mandate particulate matter reductions for non-road diesel engines at California airports ahead of federal deadlines. Denver International centralizes procurement decisions with long-term electrification roadmaps and charging infrastructure coordination.
China
Beijing Daxing, Shanghai Pudong, and Guangzhou Baiyun drive apron infrastructure expansion to accommodate wide-body traffic growth. National dual carbon goals accelerate fleet electrification mandates across state-owned airport authorities. Weihai-based equipment fabricators supply domestic carriers while expanding export capacity for belt loaders and tow tractors.
Germany
Frankfurt and Munich airports specify silicon carbide inverter ground power units for wide-body gate positions under EU Green Deal procurement rules. ECHA chemical registration requirements constrain hydraulic fluid formulations in legacy cargo loader systems. Baden-Württemberg engineering clusters develop precision frequency converter technology for 400 Hz solid-state applications.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International sustain demand for high-capacity cargo loaders serving e-commerce freight expansion. Federal aviation regulations align with ICAO carbon reduction frameworks for ground handling operations. Emirates Group engineering subsidiaries specify ruggedized electric tow tractors for desert climate operations with extended battery thermal management.
India
Delhi Indira Gandhi, Mumbai Chhatrapati Shivaji, and Bangalore Kempegowda greenfield terminals enable pure-electric fleet deployment without legacy diesel infrastructure. PLI scheme incentives support domestic assembly of battery packs for airport equipment applications. GMR Group and Adani Airports Holdings centralize procurement across multiple concession contracts with standardized electrification specifications.
Aircraft Ground Support Equipment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent investment models in ground support equipment. Integrated conglomerates with captive aerospace divisions maintain cost advantages through shared component sourcing and cross-divisional R&D amortization. The vendor base stratifies into three archetypes: diversified industrial conglomerates, specialized airport equipment pure-plays, and regional fabrication specialists serving single-country markets. Dominant competitive moves include backward integration into battery pack assembly and geographic expansion through airport concession bundling.
Among diversified industrial conglomerates, Oshkosh Corporation and Textron Inc. occupy positions spanning defense and commercial aviation applications. TLD Group and JBT Corporation exemplify the specialized pure-play archetype with concentrated product portfolios. Weihai Guangtai Airport Equipment Co., Limited and China International Marine Containers (Group) Ltd. represent regional fabrication specialists leveraging domestic supply chain density for cost-competitive export positioning.
| Leading Market Players |
|---|
| Oshkosh Corporation |
| TLD Group |
| JBT Corporation |
| Textron Ground Support Equipment Inc. |
| China International Marine Containers (Group) Ltd. |
| TCR Group |
| Weihai Guangtai Airport Equipment Co., Limited |
| Tronair Inc. |
| ITW GSE |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate price volatility cascades through battery pack assembly into tiered equipment pricing, compressing margins for electric tow tractor manufacturers while amplifying cost advantages for Chinese cathode processors serving domestic OEMs.
Pricing Analysis
Margin tightening in mid-tier electric ground power units reflects silicon carbide inverter supply constraints and extended FAA certification timelines. Pricing stratifies across premium CE-marked systems, standard domestic-certified units, and economy-grade mechanical alternatives. Cost-down pressure on hydraulic cargo loaders accelerates because European ground handling contracts now mandate electric fleet percentages. Airport authorities exhibit highest price sensitivity; defense contractors demonstrate lowest sensitivity due to ruggedization requirements and NATO interface specifications.
Supply Chain Analysis
Dual-sourcing requirements for lithium-iron-phosphate cathode materials now appear in major European ground handling contracts, forcing battery pack assemblers to qualify secondary suppliers beyond dominant Chinese processors. Manufacturing capacity clusters in China, Germany, and the United States. Supply chains draw from silicon carbide wafer fabrication, rare-earth magnet processing, and precision aluminum casting. Single-source vulnerability concentrates in 400 Hz inverter controller chips. Distribution runs through specialized airport equipment lessors and OEM direct sales to airport authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cathode material processing bottlenecks prop equipment pricing, creating durable margin pools for integrated battery producers while squeezing pure-play hardware fabricators.
For Market Incumbents: Cement fleet management platform dominance by acquiring predictive maintenance software specialists before autonomous docking capabilities commoditize hardware differentiation. Backward integration into battery pack assembly protects margin pools against cathode price volatility. Prioritize charging infrastructure partnerships with Frankfurt and Singapore Changi authorities to lock in long-term service contracts.
For New Entrants and Emerging Players: EU Green Deal aviation targets in Germany and the Netherlands open a window for silicon carbide ground power unit specialists to capture gate electrification contracts at Amsterdam Schiphol and Munich. Target India's greenfield terminal segment where GMR Group and Adani Airports Holdings seek pure-electric fleet deployment without legacy diesel conversion costs. Lead with power-by-the-hour leasing models to bypass capital purchase barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized electric tow tractor designers with FAA certification progress and stranded diesel fleet replacement pipelines. Long-term viability hinges on software-defined functionality convergence and battery energy density trajectories. Monitor charging infrastructure capex commitment cycles at Denver International and Beijing Daxing as inflection indicators for fleet electrification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captive cathode supply insulates Oshkosh Corporation and TLD Group from lithium price volatility. |
| Silicon Carbide Inverter Technology Licensing | Baden-Württemberg engineering clusters license precision frequency converter IP to Asian fabricators. |
| Power-by-the-Hour Leasing Model Expansion | TCR Group and specialized lessors concentrate fleet decisions and compress supplier switching costs. |
| Predictive Maintenance Platform Acquisition | IoT sensor networks married with fleet software create recurring revenue streams for equipment OEMs. |
| Desert Climate Battery Thermal Management Development | Emirates Group engineering subsidiaries specify ruggedized electric tow tractors for Dubai operations. |
Methodological Framework
Independent corroboration across ground handling operations directors, airport authority procurement managers, and battery pack engineering leads underwrites the qualitative findings. Primary interviews with maintenance directors at Swissport and dnata, OEM aftermarket service heads, and FAA certification specialists combined with secondary validation from EPA emission standard filings, EU Green Deal procurement documentation, and ICAO carbon reduction framework submissions. Bottom-up equipment shipment tallies and top-down airport capex budget analysis provide triangulation.
Rate-of-change decomposition separates volume growth from mix-shift effects across the analysis window. Segmentation dimensions modeled include equipment product type, electric-hydraulic-pneumatic-mechanical technology tier, commercial-cargo-military-maintenance application, and ground handling company-airport-airline-defense contractor end user. CAGRs derive from gate electrification timeline alignment with airframe traffic growth projections. Forecast inputs incorporate battery energy density improvement curves and charging infrastructure deployment schedules at named hub airports.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery chemistry would alter the outlook. Forecasts reflect assumptions regarding EU Green Deal enforcement timelines and FAA certification velocity. Deviation in lithium-ion cell supply concentration or airport electrical grid upgrade funding would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Heliports Market
Airport Infrastructure
Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Airport Moving Walkways Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Ground Handling Systems Market
Airport Infrastructure
Aircraft Catering Vehicle Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
South-East Asia Aviation Infrastructure Market
Airport Infrastructure
Airport Ground Support Equipment Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Fixed-Base Operator Market
Airport Infrastructure
Asia-Pacific Aviation Infrastructure Market