
 Fixed-Base Operator Market | 2026-2036
Fixed-Base Operator Market Size, Share, and Industry Trends Forecast 2026-2036
Fixed-Base Operator Market Intelligence
North American hangar construction is decoupling from legacy airport development timelines as private aviation traffic reshapes infrastructure planning. Signature Aviation plc leverages its network density across major US metropolitan airports to sustain premium positioning. Atlantic Aviation LLC anchors its growth through fuel service contracts at high-traffic general aviation facilities. Jetex Flight Support FZ LLC differentiates via integrated concierge and ground transport capabilities in the Middle East and Asia.
A fixed-base operator delivers essential ground services to general aviation aircraft, including fueling, hangar storage, maintenance, and passenger handling through dedicated ramp and terminal facilities. Fuel Sales remains the dominant revenue stream due to high transaction frequency and volume-based contracting, while Hangar Services captures disproportionate margin pools from long-term corporate aircraft storage agreements. Corporate Clients represent the most structurally important end-user segment given their predictable scheduling and multi-service bundling preferences.
The FAA governs US FBO safety and operational standards, while the EU Green Deal and F-Gas Regulation reshape European fuel service compliance requirements. EASA-aligned carbon accounting rules are forcing European operators to reconfigure fuel offerings and document emissions traceability. Stakeholders must monitor regulatory divergence between SAF mandates in Europe and the slower federal standard-setting trajectory in the United States.
Market Dynamics
Corporate flight departments are consolidating their ground service contracts around multi-service bundles, compressing vendor counts and elevating FBOs with integrated fuel-storage-maintenance capabilities into preferred-provider status.
Growth Catalysts
- SAF Mandates:The EU Green Deal is compelling European FBOs to reconfigure fuel farm infrastructure for sustainable aviation fuel blending and traceability documentation.
- Corporate Fleet Expansion:Fractional ownership programs and flight departments are demanding dedicated hangar capacity with rapid-turn fueling protocols at secondary airports.
- Electrification Infrastructure:Battery-electric ground support equipment is penetrating ramp operations, reducing local emissions profiles and qualifying operators for airport sustainability incentives.
Market Restraints
- Jet Fuel Price Volatility:Crack spread fluctuations compress fuel sale margins and complicate long-term contract pricing for independent operators without integrated refining access.
- Airport Lease Concentration:Single-source municipal airport authorities in tier-one markets extract premium concession terms, raising fixed-cost barriers for new entrants.
- Emissions Accounting Complexity:EASA-aligned carbon reporting requirements impose documentation burdens that smaller FBOs lack systems to automate.
Strategic Opportunities
- Secondary Airport Penetration:Under-served general aviation reliever airports in the United States present whitespace for full-service FBO development outside saturated primary markets.
- Concierge Integration:Ground transport and luxury hospitality bundling is capturing high-net-worth traveler spend previously leaking to third-party providers.
- Digital Ramp Management:AI-driven slot allocation and predictive fuel ordering are converging with mobile passenger interfaces to compress turnaround times.
Industry Challenges
- Certified Technician Scarcity:A&P mechanic and fuel quality control specialist pipelines are failing to match fleet complexity growth, extending maintenance backlogs.
- Legacy System Integration:Proprietary fuel management software from incumbent vendors resists API connectivity with modern reservation and billing platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed-Base Operator Market |
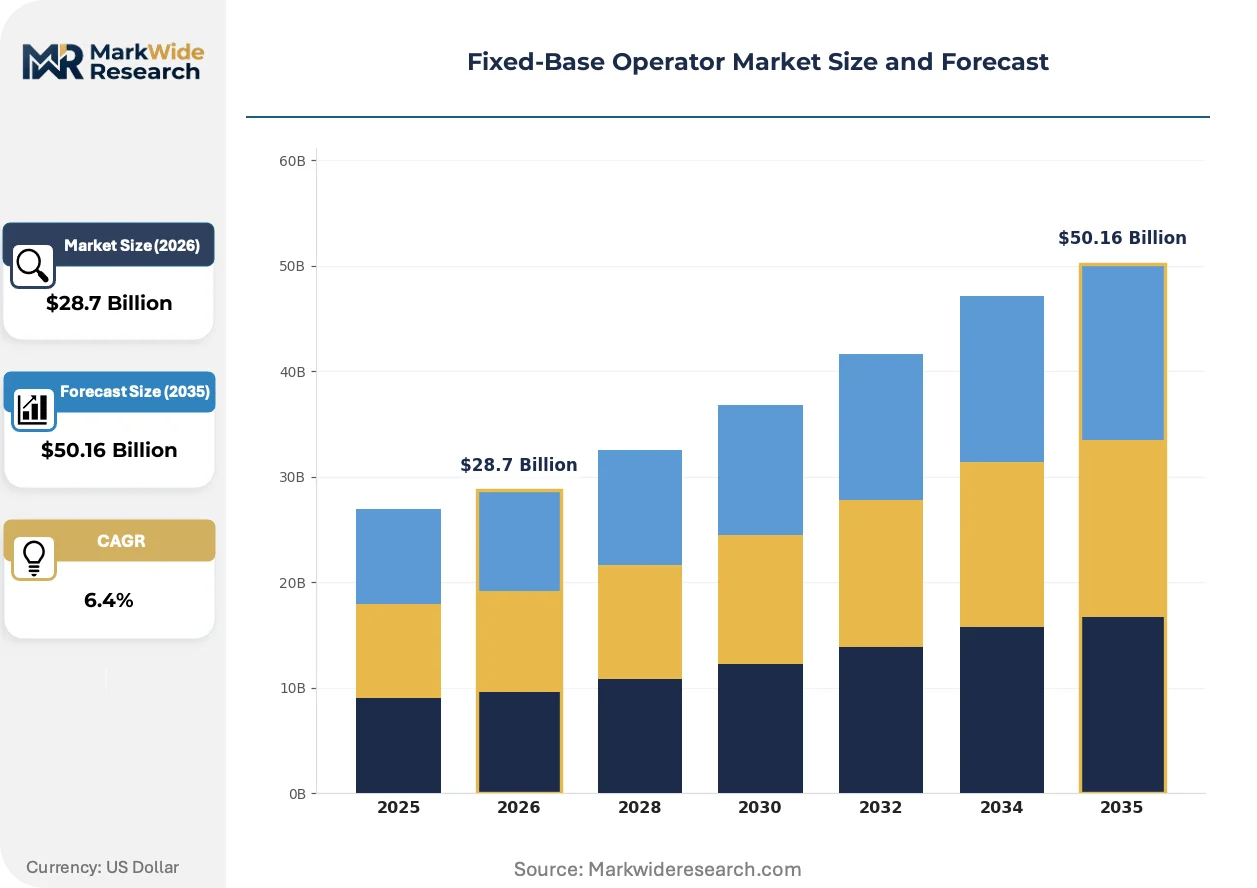
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fuel Sales, Hangar Services, Maintenance, Flight Training End User: Corporate Clients, Private Pilots, Flight Schools, Charter Operators Operation Type: Scheduled Services, On-Demand Services, Dedicated Support, Emergency Services Delivery Model: In-Hangar Services, Ramp Services, Concierge Services, Ground Transport |
| Companies Covered | Universal Aviation, TAC Air Inc., Signature Aviation plc, Luxaviation Group SA, Landmark Aviation, LLC, Atlantic Aviation LLC, Million Air International, Inc., Jetex Flight Support FZ LLC, Jet Aviation AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed-Base Operator Market Strategic Shifts & Innovations
Sustainable aviation fuel logistics and digital passenger experience platforms are restructuring how FBOs capture value, moving competition beyond commodity fuel pricing toward service integration depth.
Automated fuel farm management systems with real-time quality monitoring and blockchain-anchored custody documentation are rewriting compliance workflows for European operators facing EU Green Deal traceability requirements. Signature Aviation plc and Atlantic Aviation LLC are deploying these systems at high-traffic facilities to preempt regulatory audit exposure. The technology is compressing the advantage window for operators still relying on manual sampling and paper chain-of-custody records.
The F-Gas Regulation and EASA carbon accounting mandates are forcing fuel service reconfiguration across European Union member states, requiring infrastructure investment in segregated SAF storage and metered blending equipment. Operators serving corporate flight departments must now document lifecycle emissions per uplifted liter to maintain contract eligibility. Germany and France are seeing accelerated hangar lease renegotiations as landlords pass compliance capital costs through to FBO tenants.
Corporate procurement departments are consolidating ground service contracts under master service agreements that bundle fuel, hangar, and concierge spend across multiple airport pairs. This behavior is displacing transactional spot purchasing and elevating FBO network scale as a selection criterion. The United States exhibits the most pronounced concentration, where flight departments with twenty-plus based aircraft are mandating single-source billing and standardized service level agreements across their route networks.
Fixed-Base Operator Market Segmentation

FBO revenue streams diverge sharply in margin profile and capital intensity. Service type determines fuel farm investment requirements, while end-user concentration shapes contract duration and pricing power. Understanding these segment boundaries clarifies where network scale delivers sustainable advantage versus where local operational excellence dominates.
Service Type:
Fuel Sales concentrates supply-side investment in storage infrastructure and quality control systems, while Hangar Services locks in long-term real estate commitments with municipal airport authorities.
- Fuel Sales:High-volume throughput operations with metered blending capabilities for sustainable aviation fuel integration. Demand clusters at facilities serving corporate flight departments with predictable scheduling and volume commitments. EU Green Deal traceability mandates are forcing capital upgrades for segregated SAF storage and blockchain-anchored custody documentation.
- Hangar Services:Climate-controlled aircraft storage with dedicated security protocols and rapid-access ramp positioning. Corporate fleet expansion at secondary US airports is driving lease renegotiations as landlords pass compliance capital costs through to operators. Long-term agreements with fractional ownership programs provide revenue visibility across economic cycles.
- Maintenance:A&P-certified technician labor pools with specialized avionics and powerplant capabilities. Backlogs are extending due to certified mechanic scarcity.
- Flight Training:Simulator-equipped facilities with FAA Part 141 certification pathways. Demand concentrates at reliever airports near metropolitan flight schools.
Fuel Sales absorbs the bulk of installed capacity; Hangar Services is expanding most quickly.
End User:
Corporate Clients command multi-service bundling and standardized SLAs across airport pairs, while Private Pilots drive transactional spot demand with minimal contract stickiness.
- Corporate Clients:Flight departments with twenty-plus based aircraft mandating single-source billing and network-wide service consistency. Master service agreements displace transactional purchasing and elevate FBO network scale as a selection criterion. Procurement departments now bundle fuel, hangar, and concierge spend under unified contracts.
- Charter Operators:Rapid-turn fueling protocols with 24/7 dispatch requirements and dedicated line service crews. Demand concentrates at high-traffic general aviation facilities with concurrent runway capacity.
- Private Pilots:Owner-flown aircraft with discretionary scheduling and price-sensitive fuel purchasing behavior. Activity clusters at lower-cost reliever airports outside saturated primary markets.
- Flight Schools:High-frequency training operations with specialized insurance requirements and block fuel contracting. Volume concentrates at FAA-designated pilot production facilities.
Corporate Clients anchor revenue stability; Charter Operators are climbing the fastest as on-demand aviation scales.
Operation Type:
Scheduled Services generate predictable utilization patterns for staffing and inventory planning, while On-Demand Services require surge capacity buffers that compress margin at low-volume facilities.
- Scheduled Services:Recurring flight department rotations with fixed-base aircraft positioning and pre-positioned fuel reserves. Fractional ownership programs drive this segment with predictable daily utilization.
- On-Demand Services:Ad-hoc charter dispatch with compressed turnaround windows and dynamic crew scheduling. Digital ramp management platforms are compressing slot allocation times.
- Dedicated Support:Exclusive-use agreements with single corporate tenants for hangar and line service priority. Long-term contracts provide revenue visibility.
- Emergency Services:Medevac and disaster response operations with specialized ground handling protocols. Demand spikes correlate with regional weather events.
Scheduled Services dominates facility utilization; On-Demand Services is gaining share fastest as charter fragmentation accelerates.
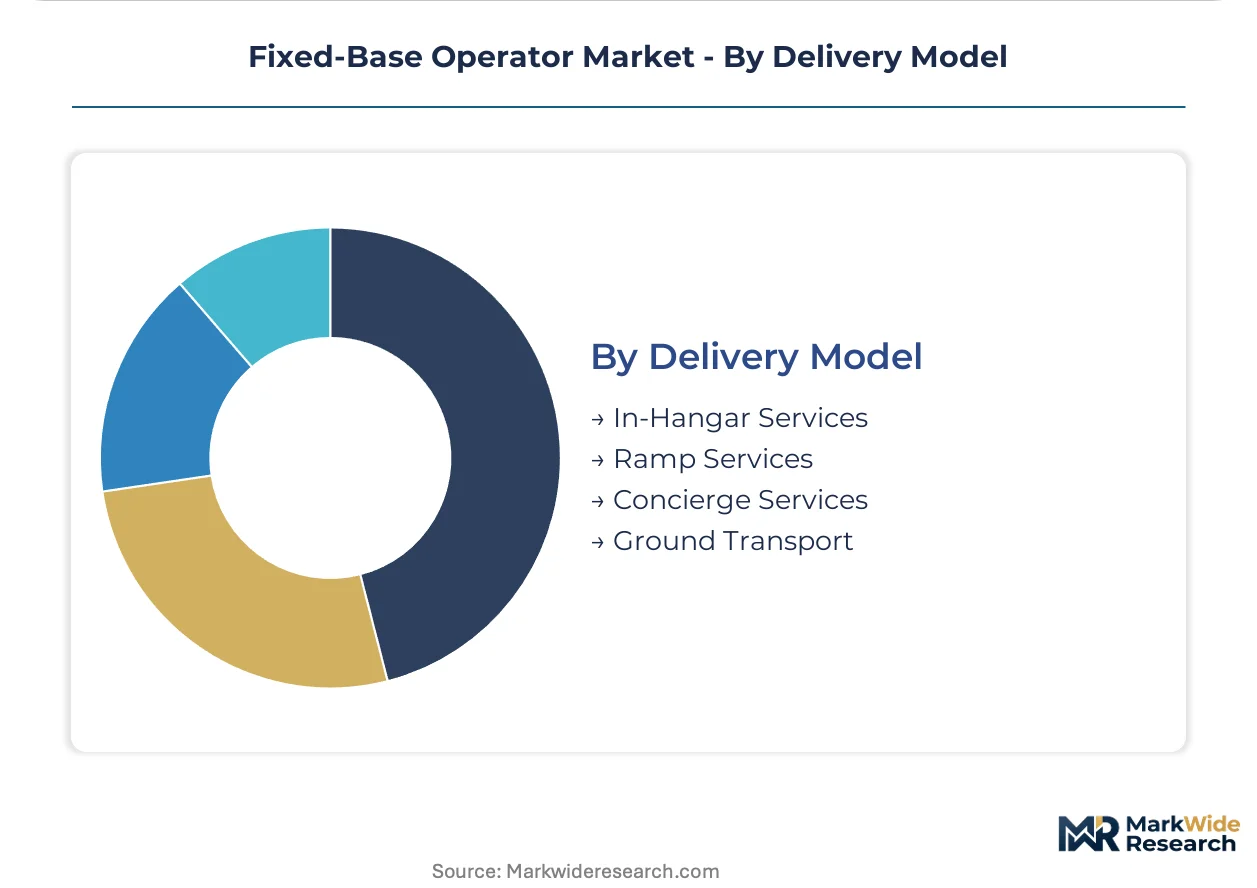
Delivery Model:
In-Hangar Services capture premium pricing through controlled-environment aircraft handling, while Ramp Services compete on throughput speed and concurrent aircraft capacity.
- In-Hangar Services:Climate-controlled aircraft movement with specialized towing equipment and hangar-specific insurance coverage. Corporate clients pay premiums for reduced weather exposure and security protocols.
- Concierge Services:Integrated ground transport and luxury hospitality bundling capturing spend previously leaking to third-party providers. High-net-worth travelers drive demand at major metropolitan facilities.
- Ramp Services:Open-air aircraft positioning with rapid fuel connect and disconnect protocols. Battery-electric ground support equipment is penetrating this segment for emissions reduction.
- Ground Transport:Dedicated crew and passenger vehicle fleets with real-time flight tracking integration. Demand concentrates at facilities serving remote executive terminals.
In-Hangar Services commands the highest margin per aircraft movement; Concierge Services shows the steepest expansion trajectory as service integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jet fuel supply corridors anchor geographic positioning across the fixed-base operator landscape, with infrastructure density clustering around refining hubs and executive aviation corridors.
United States
Private jet utilization and dedicated hangar construction at reliever airports drive infrastructure investment outside saturated primary markets. The FAA governs safety and operational standards while airport lease structures concentrate concession authority with municipal authorities. Texas and Florida metropolitan clusters exhibit the fastest hangar lease renegotiations as fractional ownership programs expand fleet positioning.
Germany
Corporate flight departments demand segregated sustainable aviation fuel storage with documented emissions traceability per uplifted liter. The EU Green Deal and F-Gas Regulation reshape fuel service compliance requirements while EASA-aligned carbon accounting rules force operational reconfiguration. Frankfurt and Munich airport vicinities concentrate infrastructure investment as landlords pass compliance capital costs through to FBO tenants.
United Arab Emirates
Integrated concierge and ground transport capabilities capture high-net-worth traveler spend at Dubai and Abu Dhabi executive terminals. The General Civil Aviation Authority oversees operational licensing while free zone structures enable foreign ownership of ground handling entities. Dubai South and Al Maktoum International anchor luxury service integration as competition moves beyond commodity fuel pricing.
France
Master service agreements bundling fuel, hangar, and concierge spend displace transactional spot purchasing among corporate procurement departments. EU Green Deal mandates accelerate SAF infrastructure deployment while the country's national civil aviation authority enforces emissions documentation protocols. Paris-Le Bourget and Nice Côte d'Azur concentrate network-scale operators capable of standardized service level agreements across airport pairs.
United Kingdom
Digital ramp management platforms compress slot allocation times for on-demand charter dispatch at high-traffic general aviation facilities. The Civil Aviation Authority regulates ground handling safety standards while post-Brexit regulatory divergence creates compliance complexity for cross-border operators. London Biggin Hill and Farnborough anchor premium positioning through controlled-environment hangar services and rapid-turn fueling protocols.
Fixed-Base Operator Market Key Industry Players
Global majors compete with regional champions across network density and service integration depth, producing a tiered structure where scale-driven operators face pressure from specialists in luxury hospitality bundling. Market concentration elevates around multi-service capabilities rather than fuel volume alone, with preferred-provider status flowing to FBOs offering unified billing across airport pairs. Three archetypes dominate: network-scale integrators with metropolitan density, regional specialists in secondary airport penetration, and luxury service bundlers capturing concierge spend. Consolidation through airport concession acquisitions and strategic partnerships for SAF infrastructure sharing represent the dominant competitive vectors.
Within the network-scale tier, Signature Aviation plc and Atlantic Aviation LLC exemplify operators leveraging US metropolitan density for premium positioning, while Jetex Flight Support FZ LLC occupies a position among integrated service bundlers in Middle Eastern and Asian markets. These entities anchor archetypal strategies rather than defining market boundaries, with their structural approaches informing competitor positioning across fuel service, hangar real estate, and passenger experience integration.
| Leading Market Players |
|---|
| Universal Aviation |
| TAC Air Inc. |
| Signature Aviation plc |
| Luxaviation Group SA |
| Landmark Aviation, LLC |
| Atlantic Aviation LLC |
| Million Air International, Inc. |
| Jetex Flight Support FZ LLC |
| Jet Aviation AG |
| Others |
Cost & Logistics Intelligence
Jet fuel crack spread volatility cascades through FBO pricing tiers from Gulf Coast refining hubs to corporate flight department contracts, with integrated operators capturing margin buffers unavailable to independents sourcing through third-party fuel farms. Municipal airport lease structures concentrate concession authority and amplify fixed-cost pass-through to end-users.
Pricing Analysis
Warranty-backed fuel quality certification and unbundled line service labor define the core pricing architecture. Three-tier pricing structure across premium, standard, and economy levels segments corporate master service agreements from transactional private pilot purchases. Price differentiation hinges on SAF blending capability and hangar climate-control certification. Pricing pressure stems from crack spread compression eroding fuel sale margins. Private pilots exhibit highest price sensitivity; corporate flight departments with network-scale contracts demonstrate lowest.
Supply Chain Analysis
Jet fuel supply rests on Gulf Coast refining concentration, with supplemental sourcing from Midwest pipelines and Northeast terminal networks. Key inputs include kerosene feedstock, SAF blendstocks, and fuel quality additives. Single-source vulnerability concentrates at municipal airport authorities controlling exclusive concession agreements. Distribution runs through integrated fuel farm infrastructure at high-traffic general aviation facilities.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified A&P mechanic scarcity constrains maintenance capacity expansion, propping pricing power for operators with established technician pipelines. This supply bottleneck sustains margin structures across service bundles.
For Market Incumbents: Lock in long-term hangar lease renewals at secondary US airports before fractional ownership programs expand fleet positioning. Secure exclusive fuel service contracts with municipal authorities to preempt independent entry. Invest in automated fuel farm management systems to offset EASA-aligned carbon accounting documentation burdens threatening smaller competitors. For New Entrants and Emerging Players: EU Green Deal SAF mandates in Germany and France open a window for infrastructure-light operators partnering with existing fuel farms for segregated storage access. Target under-served reliever airports in Texas and Florida metropolitan clusters where hangar construction lags private aviation traffic growth. Deploy digital ramp management platforms as differentiated entry wedge against legacy incumbent systems. For Investors and Strategic Acquirers: Accelerated master service agreement signings between corporate flight departments and network-scale FBOs is the leading indicator that consolidation value is shifting toward multi-airport platform operators. Position for 5-10 year horizon exposure to operators with integrated fuel-storage-maintenance capabilities across 10-plus airport pairs. Monitor SAF infrastructure sharing partnerships as signal of preferred-provider status crystallization.| Strategic Initiative | Industry Significance |
|---|---|
| SAF Infrastructure Deployment | EU Green Deal traceability mandates force capital allocation toward segregated storage and blockchain-anchored custody systems at Frankfurt and Munich facilities. |
| Digital Ramp Management Integration | AI-driven slot allocation compresses turnaround times for on-demand charter operators at high-traffic general aviation reliever airports. |
| Secondary Airport Concession Acquisition | Texas and Florida metropolitan clusters exhibit fastest lease renegotiations as fractional ownership programs expand fleet positioning. |
| Certified Technician Pipeline Development | A&P mechanic scarcity extends maintenance backlogs, elevating operators with established training partnerships into preferred-provider status. |
| Concierge Service Bundling | Integrated ground transport and luxury hospitality capture high-net-worth traveler spend previously leaking to third-party providers at Dubai and Abu Dhabi terminals. |
Research Approach
Multi-period observation of fuel throughput volumes, hangar lease rates, and SAF infrastructure deployment anchored the trend analysis, supplemented by interviews with FBO operations directors, corporate flight department procurement managers, municipal airport authority leasing officers, and fuel quality control specialists. Secondary validation drew from FAA safety compliance filings, EASA carbon accounting protocols, EU Green Deal regulatory texts, and airport concession contract databases. Bottom-up facility-level capacity assessment triangulated against top-down market size estimation.
Segment-weighting across service type, end user, operation type, and delivery model dimensions structured the analytical framework. CAGRs were derived from facility expansion pipelines, fleet positioning forecasts from fractional ownership programs, and regulatory mandate implementation timelines. SAF blending capacity buildout and certified technician pipeline development served as industry-specific forecast inputs throughout the projection horizon.
The model assumes a particular technology adoption path for automated fuel farm management systems; alternative pathways for blockchain-anchored custody documentation would alter the outlook for European operator compliance cost structures. Forecasts reflect assumptions regarding municipal lease renewal rates and corporate procurement consolidation velocity. A small set of named triggers—SAF mandate acceleration, A&P certification program expansion, and airport privatization waves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Airport Infrastructure
Airport Lighting Market
Airport Infrastructure
Aerotropolis Market
Airport Infrastructure
Airport Services Market
Airport Infrastructure
North America Ground Handling System Market
Airport Infrastructure
Airport Logistics Systems Market
Airport Infrastructure
Jet Bridge Market
Airport Infrastructure
Telescopic Masts Market
Airport Infrastructure
Global Aerospace Ground Handling System Market
Airport Infrastructure
Ground Support Equipment Market
Airport Infrastructure
Airfield Ground Lighting Market
Airport Infrastructure
North America Aviation Infrastructure Market
Airport Infrastructure
Aircraft Tow Tractors Market
Airport Infrastructure
Europe, Middle-East and Africa Aviation Infrastructure Market
Airport Infrastructure
Airport Passenger Boarding Bridge Market
Airport Infrastructure
Aviation Infrastructure Market
Airport Infrastructure
Ground Handling Systems Market