
 Airplane Pushback Tug Market | 2026-2036
Airplane Pushback Tug Market Size, Share, and Industry Trends Forecast 2026-2036
Airplane Pushback Tug Market Insights
Market Context with Strategic Players
China's airport infrastructure expansion is reshaping manufacturing priorities across the pushback tug supply base. TLD Group leverages its European engineering heritage to compete in the electric segment, while JBT Corporation anchors North American aftermarket service networks through proprietary telematics platforms. Goldhofer dominates the ultra-heavy-duty niche with specialized towbarless systems rated above 60 tons.
Technical Definition and Structural Segments
An airplane pushback tug is a motorized ground support vehicle that exerts controlled horizontal force on an aircraft's nose gear or towbar to reposition it away from the gate, typically delivering drawbar pull between 15 and 70 tons depending on aircraft class. The equipment operates via diesel combustion, electric battery packs, or hybrid architectures, with towbarless designs clamping directly onto nose gear to eliminate pin shear risks. Electric and battery-powered types are capturing margin pools as airports phase out diesel fleets under emissions mandates, while the 41-60 ton power rating band leads volume due to its coverage of narrow-body and regional jet fleets. Commercial airports represent the most mature application channel, whereas cargo handling operations show structural growth as e-commerce air freight volumes expand dedicated freighter turn requirements.
Regulatory Framework and Forward Outlook
The EPA enforces Tier 4 Final emissions standards for off-road diesel equipment operating at US airports, while the EU Green Deal and F-Gas Regulation constrain fluorinated greenhouse gas use in ground support vehicle climate systems. China's MIIT mandates GB standard compliance for new energy vehicle performance, including airport electric ground equipment. Stakeholders must monitor evolving carbon border adjustment mechanisms and local air quality ordinances to determine fleet electrification sequencing and powertrain sourcing strategies.
Market Dynamics
Electrification mandates from aviation regulators are compressing diesel equipment replacement cycles while airport infrastructure investment in Asia-Pacific concentrates procurement power among state-backed fleet operators.
Growth Catalysts
- EPA Tier 4 Final standards:US airports face compliance deadlines that accelerate diesel-to-electric conversions and expand addressable market for zero-emission ground support equipment.
- E-commerce air freight expansion:Dedicated freighter operations at cargo hubs drive demand for heavy-duty towbarless systems with rapid turnaround capabilities.
- Lithium-ion battery energy density improvements:Extended operational range enables electric tugs to service wide-body aircraft without mid-shift charging interruptions.
Market Restraints
- Cobalt and lithium price volatility:Battery raw material cost swings compress electric tug manufacturing margins and create pricing uncertainty for fleet procurement contracts.
- Ultra-heavy-duty powertrain supply concentration:Specialized electric motors above 500kW remain concentrated among German and Japanese suppliers, creating single-source vulnerability.
- Towbar legacy infrastructure lock-in:Existing gate modifications and maintenance crew training investments delay towbarless adoption at older airport terminals.
Strategic Opportunities
- India's airport privatization wave:Greenfield terminal developments at Delhi, Mumbai, and Bangalore bypass legacy infrastructure constraints and specify electric-first ground support fleets.
- Predictive maintenance telematics convergence:Integration of battery health monitoring with aircraft turnaround scheduling software creates subscription revenue streams.
- EU Green Deal carbon border adjustments:Import tariffs on high-carbon ground equipment incentivize local European manufacturing and captive production investments.
Industry Challenges
- High-voltage electrical technician scarcity:Airport maintenance departments lack certified personnel for 800V battery system diagnostics and repair.
- Multi-aircraft-type certification complexity:Towbarless nose gear clamp designs require separate airframe manufacturer approvals, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airplane Pushback Tug Market |
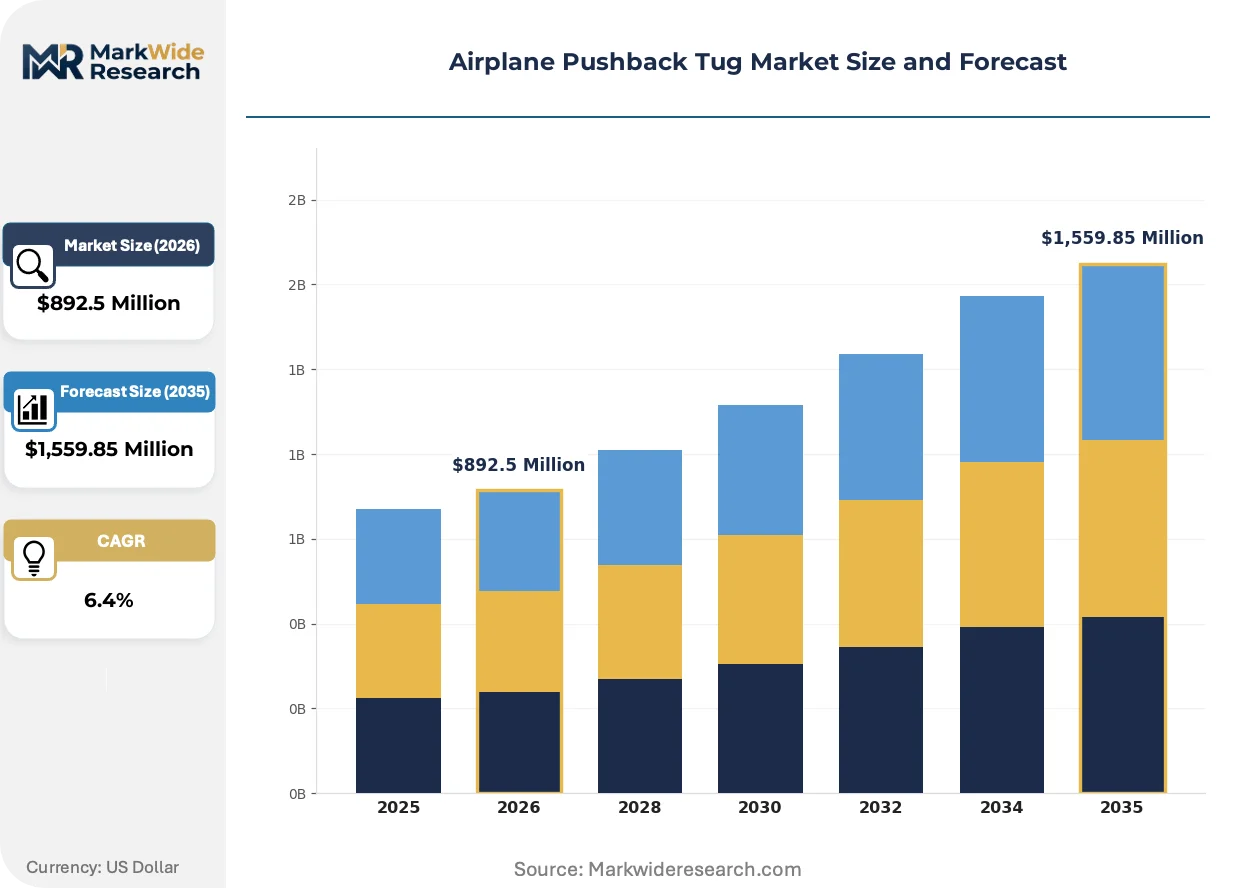
| Market Size in 2026 | $892.5 Million |
| Market Size in 2035 | $1,559.85 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Electric, Diesel, Hybrid, Towbarless, Battery-Powered Application: Commercial Airports, Cargo Handling, Military Airbases, Maintenance Facilities Power Rating: 10-20 Tons, 21-40 Tons, 41-60 Tons, Above 60 Tons End User: Ground Handling Service Providers, Airport Authorities, Aircraft Operators, Fixed Base Operators |
| Companies Covered | Aero Specialties, Textron GSE, TLD Group, TREPEL Airport Equipment, Goldhofer, JBT Corporation, TUG Technologies Corporation, Tronair, MULAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airplane Pushback Tug Market Trends and Innovations
Digital twin technology is compressing product development cycles while regulatory pressure on airport emissions intensifies specification requirements for ground support equipment procurement.
Autonomous tug navigation systems are virtualizing manual operator functions through LiDAR-based obstacle detection and precision docking algorithms. Major hub airports in Germany and Singapore are piloting unmanned pushback operations during low-visibility conditions. This capability is virtualizing traditional labor scheduling models and enabling 24-hour continuous operations without shift-change downtime.
The EU F-Gas Regulation constrains hydrofluorocarbon use in ground vehicle climate systems, forcing manufacturers to adopt CO2-based heat pumps for operator cabins. Equipment suppliers must redesign thermal management architectures to maintain operator comfort across temperature extremes. Narrow-body servicing tugs operating at Mediterranean airports face the most acute redesign pressure due to summer heat load requirements.
Airport operators are unbundling after-sales service contracts from initial equipment purchases, creating independent maintenance provider ecosystems. Third-party service networks in China and the UAE are capturing brake system and battery replacement work previously performed by OEM technicians. This fragmentation is most advanced at Dubai International Airport and Shenzhen Bao'an International Airport, where competitive tendering has reduced service contract values.
Airplane Pushback Tug Market Segmentation
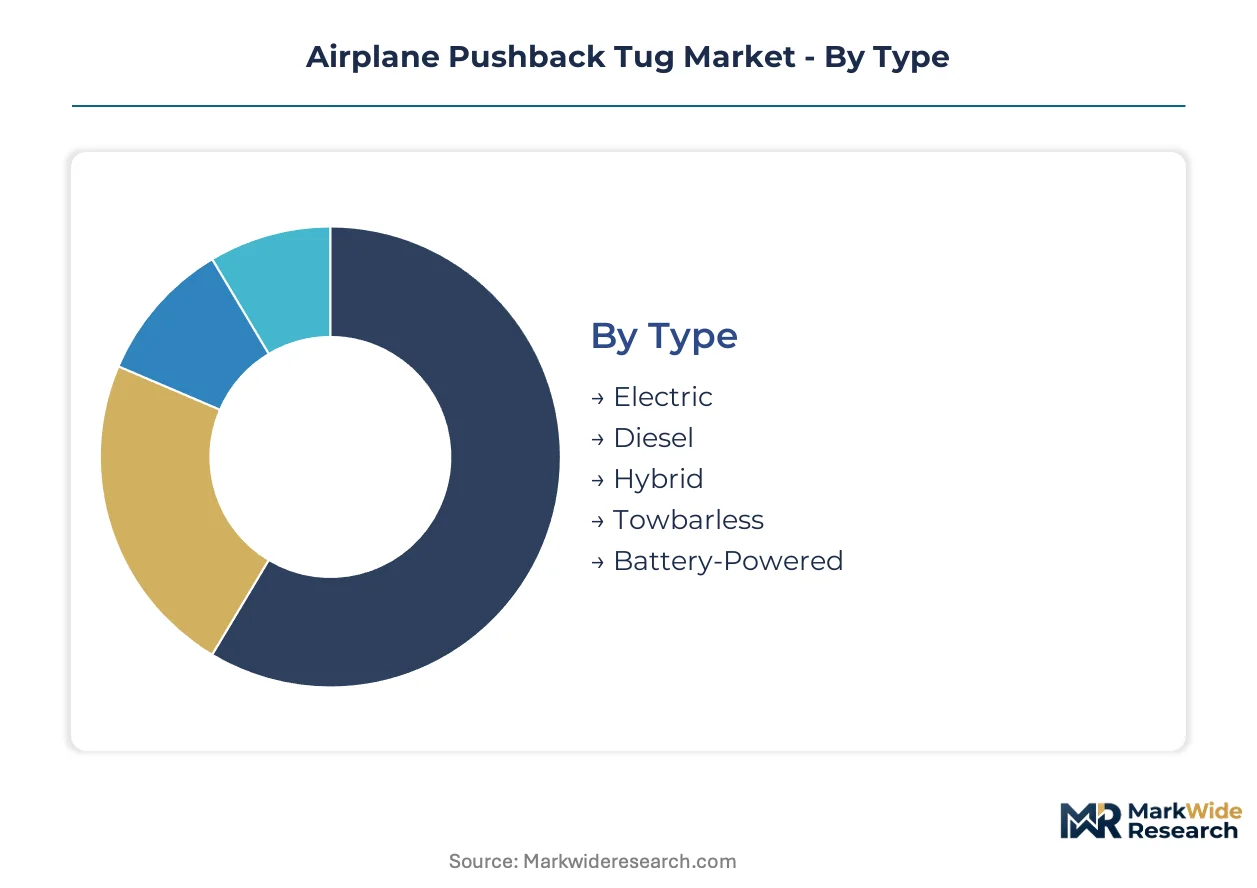
Pushback tug procurement patterns diverge sharply across powertrain technologies and operational contexts. Fleet operators prioritize electrification timelines and aircraft compatibility when segmenting addressable demand.
Type:
Powertrain architecture determines compliance positioning against aviation emissions mandates and total cost of ownership trajectories.
- Electric:Battery-electric architectures eliminate tailpipe emissions at the point of use. Chinese airports under MIIT new energy vehicle mandates are procuring electric fleets fastest, with state-backed operators at Beijing Daxing and Shanghai Pudong specifying zero-emission ground support equipment exclusively.
- Towbarless:Clamp-based nose gear engagement eliminates towbar pin shear risks and reduces turnaround times. German hub airports including Frankfurt and Munich are standardizing on towbarless designs for narrow-body fleets to minimize gate congestion during peak scheduling windows.
- Diesel:Compression-ignition engines dominate legacy installed base but face accelerated replacement cycles under EPA Tier 4 Final compliance deadlines.
- Hybrid:Dual-mode powertrains bridge range anxiety gaps for wide-body servicing at facilities with incomplete charging infrastructure.
- Battery-Powered:Lithium-ion cell configurations enable opportunity charging during aircraft loading intervals.
Electric commands the established base. The steepest expansion runs through towbarless.
Application:
Operational environment shapes duty cycle intensity, turnaround speed requirements, and fleet standardization pressures.
- Commercial Airports:Scheduled passenger operations demand highest equipment utilization rates with strict on-time performance dependencies. Singapore Changi and Dubai International operate captive pushback tug fleets exceeding 200 units each, with electrification roadmaps targeting full diesel phase-out.
- Cargo Handling:Dedicated freighter operations at express hubs require heavy-duty towbarless systems rated for loaded wide-body aircraft. Memphis and Louisville cargo superhubs are expanding towbarless procurement as e-commerce air freight volumes strain existing ground handling capacity.
- Military Airbases:Defense procurement prioritizes interoperability across aircraft types and expeditionary deployment requirements.
- Maintenance Facilities:Hangar-based repositioning tasks tolerate lower utilization rates and slower charging cycles.
Commercial airports absorb the majority of installed capacity. Cargo handling is climbing the fastest as dedicated freighter fleets expand.
Power Rating:
Drawbar pull specification aligns directly with aircraft weight categories and gate assignment protocols.
- 41-60 Tons:This band covers narrow-body and regional jet fleets comprising the majority of commercial aircraft movements. Airport authorities in India privatizing Delhi and Mumbai terminals are specifying 41-60 ton electric units as baseline equipment for new greenfield gates.
- Above 60 Tons:Ultra-heavy-duty ratings service wide-body and cargo aircraft with loaded weights exceeding 400 tons. German manufacturers dominate this niche due to specialized electric motor supply concentration above 500kW.
- 21-40 Tons:Mid-range ratings address regional turboprop and small jet fleets at secondary airports.
- 10-20 Tons:Light-duty segment serves general aviation and business aircraft at fixed base operations.
The 41-60 ton band holds the volume base. Above 60 tons is gaining share fastest as wide-body fleet renewal accelerates.
End User:
Procurement authority distribution determines contract structures, financing arrangements, and service bundling preferences.
- Ground Handling Service Providers:Swissport, dnata, and Menzies Aviation operate multi-airport equipment pools with standardized fleet specifications. These providers face margin compression from unbundled maintenance contracts and are negotiating predictive maintenance subscriptions to preserve service revenue streams.
- Airport Authorities:State-owned operators in China and the UAE centralize procurement across terminal complexes, enabling volume-based electrification roadmaps.
- Aircraft Operators:Airlines with captive ground handling capabilities at hub airports maintain dedicated tug fleets.
- Fixed Base Operators:FBOs serving general aviation prioritize compact electric units for hangar maneuverability.
Ground handling service providers control the largest equipment base. Airport authorities are expanding fastest as infrastructure privatization concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese suppliers dominate ultra-heavy-duty electric motor production above 500kW, concentrating critical powertrain technology in two manufacturing clusters. Airport infrastructure investment patterns diverge sharply between mature hubs retrofitting legacy fleets and greenfield developments specifying electric-first procurement.
United States
Memphis and Louisville cargo superhubs drive heavy-duty towbarless demand as e-commerce air freight strains ground handling capacity. EPA Tier 4 Final compliance deadlines accelerate diesel-to-electric replacement cycles at major commercial airports. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor the Southeast and Southwest electrification corridors with captive fleet conversion roadmaps.
China
State-backed airport operators at Beijing Daxing and Shanghai Pudong specify zero-emission ground support equipment exclusively under MIIT new energy vehicle mandates. The country's dual carbon goals compress procurement timelines for electric pushback tugs. Shenzhen Bao'an International Airport hosts competitive third-party maintenance networks that fragment traditional OEM service revenue.
Germany
Frankfurt and Munich airports standardize on towbarless designs for narrow-body fleets to minimize gate congestion during peak scheduling windows. The EU Green Deal and F-Gas Regulation constrain hydrofluorocarbon use in vehicle climate systems. Bavarian manufacturing clusters specialize in electric motors above 500kW for ultra-heavy-duty applications.
India
Greenfield terminal developments at Delhi and Mumbai bypass legacy infrastructure constraints with electric-first ground support fleet specifications. Airport privatization concentrates procurement authority among state-owned operators. The PLI scheme for advanced chemistry cell manufacturing reduces battery import dependency for domestic electric tug assembly.
Singapore
Changi Airport operates captive pushback tug fleets exceeding 200 units with electrification roadmaps targeting full diesel phase-out. The city-state's regulator mandates sustainable aviation fuel and ground equipment emissions reductions in tandem. Autonomous tug navigation pilots during low-visibility conditions position the hub as a testing ground for unmanned pushback operations.
Airplane Pushback Tug Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in battery cell and high-voltage motor supply. The vendor base organizes around three strategic archetypes: European engineering houses with towbarless heritage, North American aftermarket service platforms, and Asian state-backed equipment fabricators. Consolidation pressure concentrates in the 41-60 ton power band where volume procurement enables scale economics. Dominant competitive moves include predictive maintenance telematics integration and geographic expansion through airport authority framework agreements.
Within the European engineering tier, TLD Group and Goldhofer exemplify towbarless specialization with ultra-heavy-duty system capabilities. JBT Corporation anchors North American aftermarket positioning through proprietary service networks. Among diversified ground support equipment portfolios, Textron GSE occupies a position spanning multiple airport vehicle categories. These archetypes represent divergent strategic bets on electrification timing, aftermarket capture, and geographic footprint density.
| Leading Market Players |
|---|
| Aero Specialties |
| Textron GSE |
| TLD Group |
| TREPEL Airport Equipment |
| Goldhofer |
| JBT Corporation |
| TUG Technologies Corporation |
| Tronair |
| MULAG |
| Others |
Pricing and Supply Chain Analysis
Cobalt and lithium price volatility compresses electric tug manufacturing margins while simultaneously forcing tiered pricing spreads between battery-electric and diesel alternatives. This raw material cost instability determines both procurement contract structures and supplier geographic diversification strategies across the pushback tug value chain.
Pricing Analysis
EPA Tier 4 Final dictates the pricing tier structure across the US installed base, with compliance deadlines compressing diesel equipment residual values and expanding electric premiums. Three-tier pricing structure across premium towbarless, standard towbar, and economy diesel levels reflects certification grade and after-sales service bundling. Cost compression in the mid-range electric segment is intensifying because battery cell cost swings transfer directly to fleet operators. Ground handling service providers exhibit highest price sensitivity due to margin pressure from unbundled maintenance contracts, while airport authorities in China and the UAE show lowest sensitivity given state-backed electrification mandates.
Supply Chain Analysis
German and Japanese export-control classifications on high-voltage electric motors above 500kW restrict technology flows to non-allied manufacturing jurisdictions. Geographic supply concentration centers on Germany for ultra-heavy-duty powertrains, China for lithium-ion cell production, and Japan for precision motor components. Raw material dependencies draw from Chilean lithium, Congolese cobalt, and Chinese processed cathode materials. Single-source vulnerability pervades the specialized electric motor tier above 500kW. Distribution runs through airport authority framework agreements and ground handler fleet standardization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous tug navigation systems threaten incumbent equipment suppliers with technology substitution, forcing traditional manufacturers to defend against virtualization of manual operator functions.
For Market Incumbents: Insulate installed base positions through predictive maintenance telematics integration that locks in aftermarket revenue streams. Secure captive supply of high-voltage electric motors above 500kW through backward integration or exclusive supplier agreements to mitigate German and Japanese single-source concentration. Battery health monitoring platforms represent the critical defensive lever against third-party service network fragmentation. For New Entrants and Emerging Players: Establish a beachhead in India's greenfield terminal developments at Delhi and Mumbai, where electric-first procurement specifications bypass legacy towbarless infrastructure constraints. Target the 41-60 ton power rating band with standardized electric platforms that exploit volume procurement economics at privatizing airport authorities. Telematics-enabled predictive maintenance subscriptions offer the most penetrable go-to-market angle against incumbent aftermarket dominance. For Investors and Strategic Acquirers: EU Green Deal carbon border adjustments reshape the acquisition landscape by incentivizing local European manufacturing capacity. Long-term viability concentrates on suppliers with captive electric motor production or exclusive technology licensing above 500kW. Vertically integrated engineering houses with towbarless heritage represent the priority acquisition archetype. Monitor lithium-ion battery energy density improvement trajectories as the signal indicating when electric range eliminates hybrid bridge products.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Telematics Integration | Battery health monitoring with turnaround scheduling software creates subscription revenue at Changi and Dubai. |
| Backward Integration into High-Voltage Motors | Captive supply above 500kW mitigates German and Japanese single-source vulnerability for ultra-heavy-duty ratings. |
| Geographic Expansion via Framework Agreements | Airport authority electrification roadmaps in China and India enable volume-based procurement lock-in. |
| Towbarless Nose Gear Certification Investment | Airframe manufacturer approvals compress product launch timelines at Frankfurt and Munich hubs. |
| Autonomous Navigation Pilot Programs | LiDAR-based docking algorithms position suppliers for unmanned pushback operations at Singapore and German hubs. |
Research Methodology
Operator-level perspectives from fleet managers at ground handling service providers, airport authority procurement directors, and maintenance directors at major commercial hubs anchored the qualitative base. Primary interviews with equipment engineering leads at TLD Group, JBT Corporation, and Goldhofer supplemented field perspectives. Secondary validation drew from EPA regulatory filings, EU Green Deal implementation documents, MIIT new energy vehicle mandates, and airport infrastructure investment disclosures. Customs data on lithium and cobalt trade flows, plus SEC filings from diversified ground support equipment suppliers, provided quantitative anchors. Bottom-up fleet size modeling and top-down infrastructure investment projections were triangulated to constrain volume estimates.
Scenario-bracketing around battery energy density improvement trajectories and electrification mandate compliance deadlines bounded the projection range across the analysis window. Segmentation dimensions modeled included powertrain architecture, power rating band, application context, and end-user procurement authority. CAGRs were derived from installed base replacement cycles and greenfield fleet expansion rates. Industry-specific forecast inputs incorporated e-commerce air freight volume growth at Memphis and Louisville, plus airport privatization timelines in India.
Sensitivities concentrate around lithium and cobalt price volatility, carbon border adjustment implementation timing, and autonomous navigation regulatory approval trajectories. Forecasts reflect assumptions on battery cost decline curves and charging infrastructure deployment rates at major hub airports. Material shifts in raw material supply chain configuration or aviation emissions mandate stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Military Aircraft Maintenance, Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aircraft Wheel Bead Breakers Market
Aircraft Maintenance and MRO Solutions
Aircraft Line Maintenance Market
Aircraft Maintenance and MRO Solutions
Aviation Maintenance Training Market
Aircraft Maintenance and MRO Solutions
Wide-Body Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Distributed Electric Propulsion System MRO Services Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Aircraft Engine Hoists Market
Aircraft Maintenance and MRO Solutions
Air Transport MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Maintenance Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Latin America Aircraft MRO Market