
 Airplane Machmeter Market | 2026-2036
Airplane Machmeter Market Size, Share, and Industry Trends Forecast 2026-2036
Airplane Machmeter Market Analysis
Defense procurement for fighter and trainer aircraft is shifting toward electronic machmeter configurations with embedded air data computation. Honeywell leverages its integrated flight deck portfolio to anchor military contracts across NATO operator nations. Garmin competes in the general aviation retrofit segment with compact digital units that reduce panel space requirements. Thales Group dominates European platform programs through its flight control and air data sensor integration capabilities.
An airplane machmeter measures an aircraft's speed relative to the speed of sound, typically displaying Mach number through pitot-static pressure differential sensing with resolution to 0.01 Mach. The instrument serves critical functions in high-altitude flight regimes where compressibility effects render indicated airspeed unreliable for aerodynamic control. Digital machmeters now lead product type demand as glass cockpit retrofits accelerate across aging regional jet and turboprop fleets. Electronic technology captures the fastest expansion trajectory, displacing pneumatic and mechanical architectures that require frequent calibration and lack digital bus connectivity for modern flight management systems. Multi-function machmeters command margin concentration by combining Mach indication with total air temperature and angle-of-attack data on single displays.
FAA Technical Standard Orders govern U.S. machmeter certification under TSO-C8, while EASA CS-25 airworthiness codes shape European large aircraft requirements. China's CAAC harmonizes with these standards but imposes additional GB certification testing for avionics manufactured domestically. Military operators reference MIL-STD-1553 and ARINC 429 bus standards for electronic machmeter integration into digital flight control architectures. Stakeholders must monitor accelerating air data computer consolidation trends that threaten standalone machmeter demand as multifunction sensors absorb discrete instrumentation functions.
Market Dynamics
Digital avionics consolidation is compressing standalone machmeter demand as multifunction air data computers absorb discrete instrumentation functions into integrated flight deck architectures.
Growth Catalysts
- FAA TSO-C8 mandates:Updated certification requirements for glass cockpit retrofits in aging regional jet fleets are forcing operators to replace legacy pneumatic instruments with electronic machmeters.
- Air data computer convergence:The fusion of Mach indication with angle-of-attack and total air temperature sensing is creating demand for multi-function displays in next-generation cockpit designs.
- China's fleet expansion:CAAC GB certification requirements for domestically manufactured avionics are stimulating local production capacity for electronic flight instrumentation.
Market Restraints
- Input cost volatility:Precision pressure sensors and aerospace-grade microprocessors face supply constraints from concentrated semiconductor foundry capacity in East Asia.
- Technical obsolescence pressure:Standalone machmeters face substitution risk from integrated air data computers that bundle Mach computation with primary flight displays.
- Regulatory fragmentation:Divergent certification timelines between FAA, EASA, and CAAC create compliance overhead for manufacturers seeking multi-jurisdiction approvals.
Strategic Opportunities
- General aviation retrofit:Compact digital machmeters with reduced panel space requirements address unmet demand in aging turboprop and light jet fleets.
- Military digital migration:MIL-STD-1553 and ARINC 429 bus integration requirements for fighter and trainer programs favor electronic configurations with embedded computation.
- Sensor miniaturization:MEMS-based pressure sensing technology is converging with solid-state air data architectures to enable lighter, more reliable instruments.
Industry Challenges
- Certification timeline compression:TSO-C8 and CS-25 compliance cycles for new electronic designs require extended validation periods that strain product development schedules.
- Legacy system integration:Digital machmeters must interface with aging pneumatic pitot-static plumbing in retrofit applications, creating installation complexity and airworthiness documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airplane Machmeter Market |
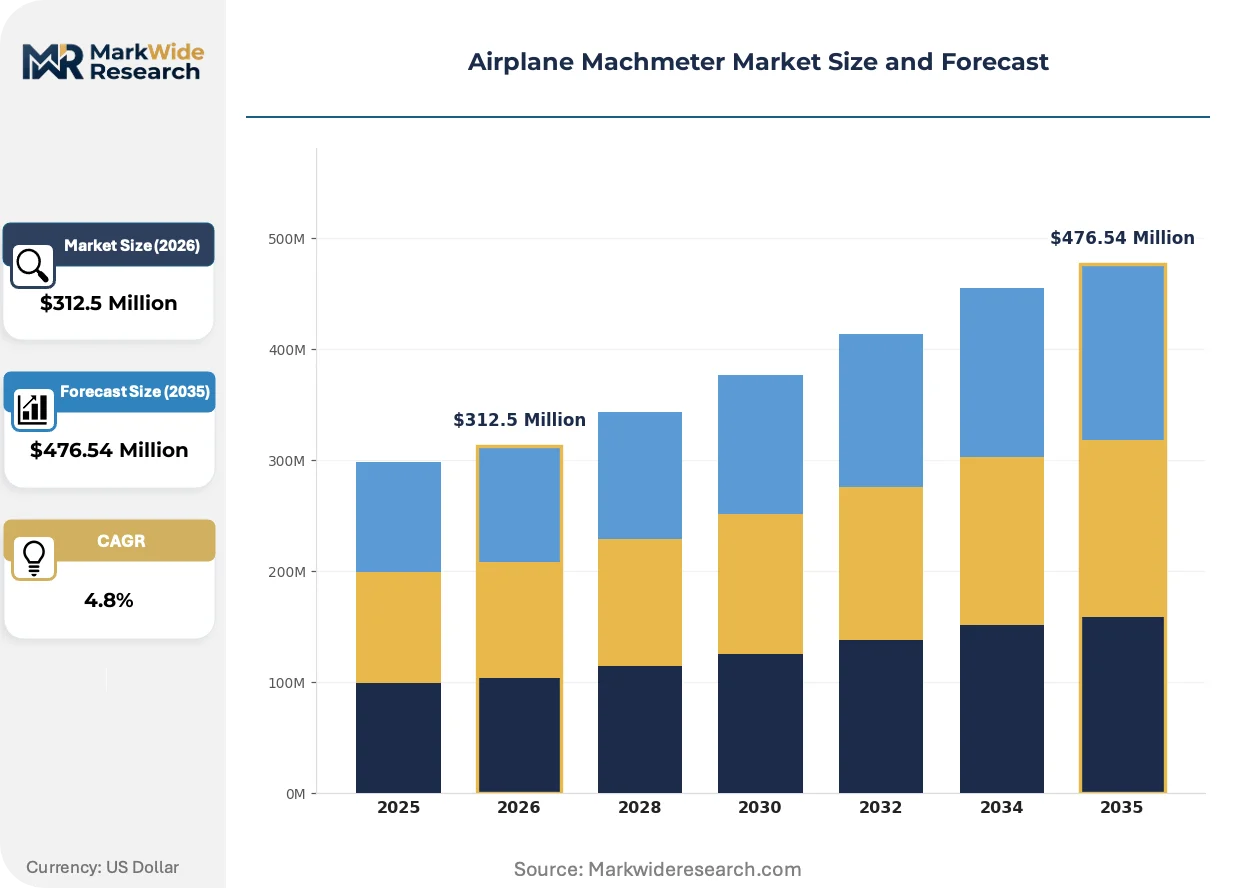
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Machmeters, Digital Machmeters, Multi-Function Machmeters, Standalone Machmeters End User: Commercial Aviation, Military Aviation, General Aviation, Aerospace Manufacturers Technology: Pneumatic, Electronic, Hybrid, Mechanical Application: Flight Navigation, Performance Monitoring, Safety Systems, Simulation Training |
| Companies Covered | Garmin, Mid-Continent Instruments and Avionics, Honeywell, Aerosonic Corporation, Ametek, Rockwell Collins, L3Harris Technologies, Universal Avionics, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airplane Machmeter Market Emerging Trajectories
Solid-state sensing architectures are displacing mechanical pressure measurement systems across commercial and military platforms, enabling direct digital bus connectivity while eliminating pneumatic lag and calibration drift.
MEMS-based differential pressure transducers are integrating pitot-static sensing with onboard temperature compensation and digital signal processing. Regional carriers operating Bombardier CRJ and Embraer E-Jet fleets are adopting these units at accelerated rates during scheduled heavy maintenance checks. The technology is integrating Mach computation directly into air data computers, compressing demand for standalone instruments.
EASA CS-25 airworthiness codes now mandate redundant air data sources for extended over-water operations, compelling twin-aisle operators to install backup electronic machmeters even where primary displays already show Mach readouts. Large aircraft manufacturers in Germany and France are responding by specifying dual-channel architectures with independent sensor inputs.
Aftermarket service contracts are unbundling from original equipment sales as lessors and maintenance-repair-overhaul providers seek component-level availability guarantees separate from airframe purchase agreements. Third-party MRO facilities in the United States are capturing calibration and overhaul volume previously retained by OEM service networks, particularly for pneumatic-to-digital upgrade programs.
Airplane Machmeter Market Segmentation
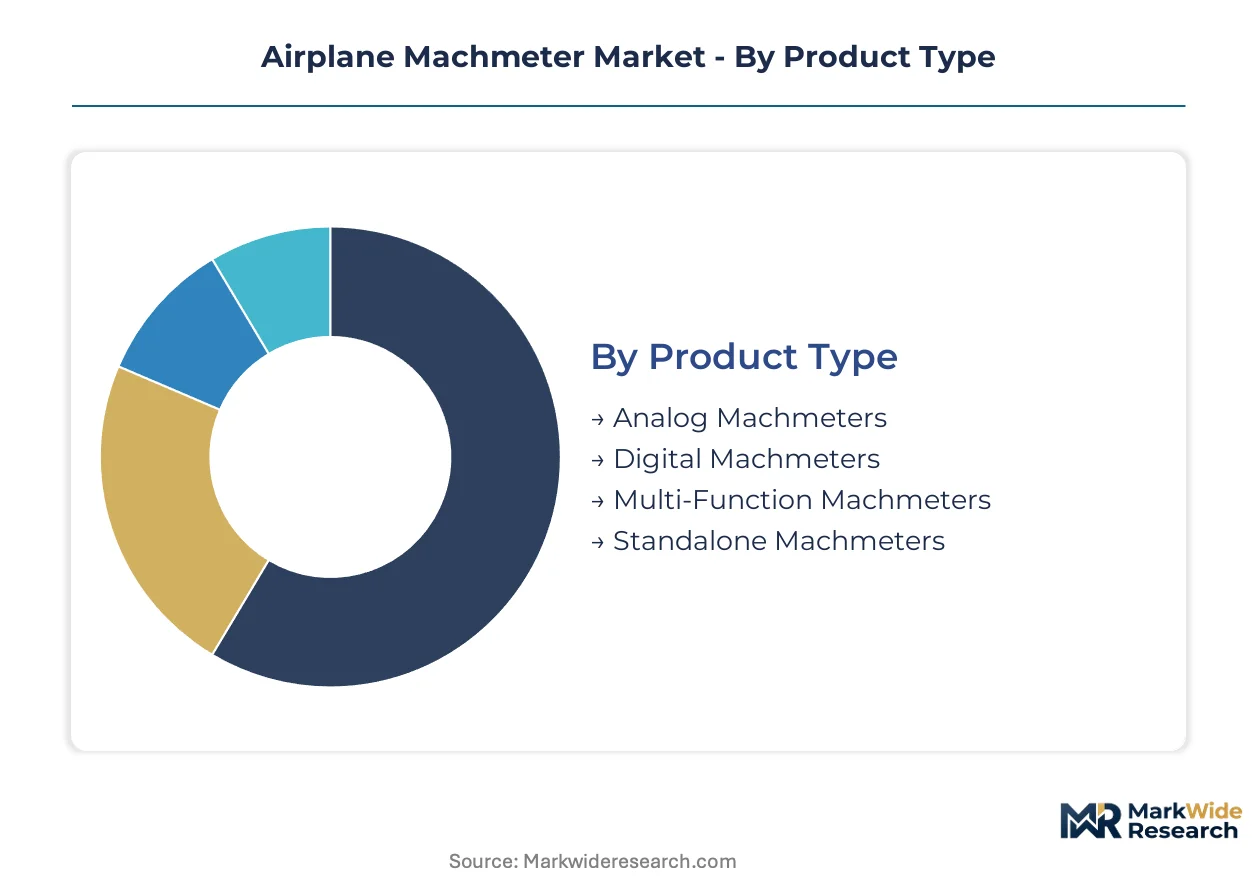
Airplane machmeter procurement hinges on certification grade, cockpit integration complexity, and fleet renewal cycles. Segment boundaries blur as multifunction air data computers absorb discrete instrument functions, reshaping how operators specify speed indication systems across platform types.
Product Type:
Buyer decisions pivot on panel space constraints and digital bus compatibility with existing flight deck architectures.
- Digital Machmeters:Solid-state pressure transducers feed ARINC 429 or MIL-STD-1553 buses with 0.01 Mach resolution and automatic temperature compensation. Regional carriers in the United States retrofitting Bombardier CRJ fleets during heavy maintenance checks drive replacement volume as FAA TSO-C8 mandates phase out pneumatic alternatives.
- Multi-Function Machmeters:Integrated displays combine Mach indication with total air temperature and angle-of-attack data on single screens, reducing instrument count. European twin-aisle operators responding to EASA CS-25 redundant source requirements for extended over-water routes specify these units even where primary flight displays already show Mach readouts.
- Analog Machmeters:Mechanical pointer-and-dial instruments persist in legacy turboprop fleets awaiting full glass cockpit upgrades.
- Standalone Machmeters:Discrete instruments face substitution pressure as air data computers bundle Mach computation with primary flight displays.
Volume sits with Digital Machmeters; growth tilts toward Multi-Function Machmeters.
End User:
Procurement scale and specification authority vary sharply across operator categories, with military and commercial fleets driving divergent technology roadmaps.
- Commercial Aviation:Scheduled carriers operating Airbus A320 and Boeing 737 families specify electronic machmeters as standard fit during new production and mid-life avionics refreshes. Fleet-wide mandates from United States and European regulators accelerate pneumatic-to-digital transitions during scheduled heavy checks.
- Military Aviation:Fighter and trainer programs demand embedded air data computation with MIL-STD-1553 bus integration for flight control system compatibility. NATO operator nations prioritize electronic configurations that eliminate pneumatic lag in high-G maneuvering envelopes.
- General Aviation:Light jet and turboprop owners seek compact digital units that minimize panel space requirements during retrofit installations.
- Aerospace Manufacturers:Airframe OEMs specify machmeter architectures during initial type certification, locking supplier relationships for production runs spanning decades.
Revenue concentrates in Commercial Aviation; expansion rates peak in Military Aviation.
Technology:
Architecture selection determines calibration intervals, failure modes, and integration pathways with modern flight management systems.
- Electronic:MEMS-based differential pressure sensing with onboard digital signal processing eliminates pneumatic plumbing and enables direct flight computer connectivity. Solid-state reliability and reduced weight position this architecture for dominance across new-production commercial and military platforms.
- Pneumatic:Legacy pitot-static systems require frequent calibration and suffer from altitude-induced lag, constraining demand to aging fleets pending retirement.
- Hybrid:Transitional designs bridge pneumatic sensing with electronic display outputs for retrofit applications where full digital replacement proves cost-prohibitive.
- Mechanical:Purely mechanical pressure measurement survives only in non-transport category aircraft with minimal avionics requirements.
Installation base remains with Pneumatic; technology transition favors Electronic.
Application:
Use case dictates accuracy requirements, redundancy levels, and regulatory scrutiny intensity.
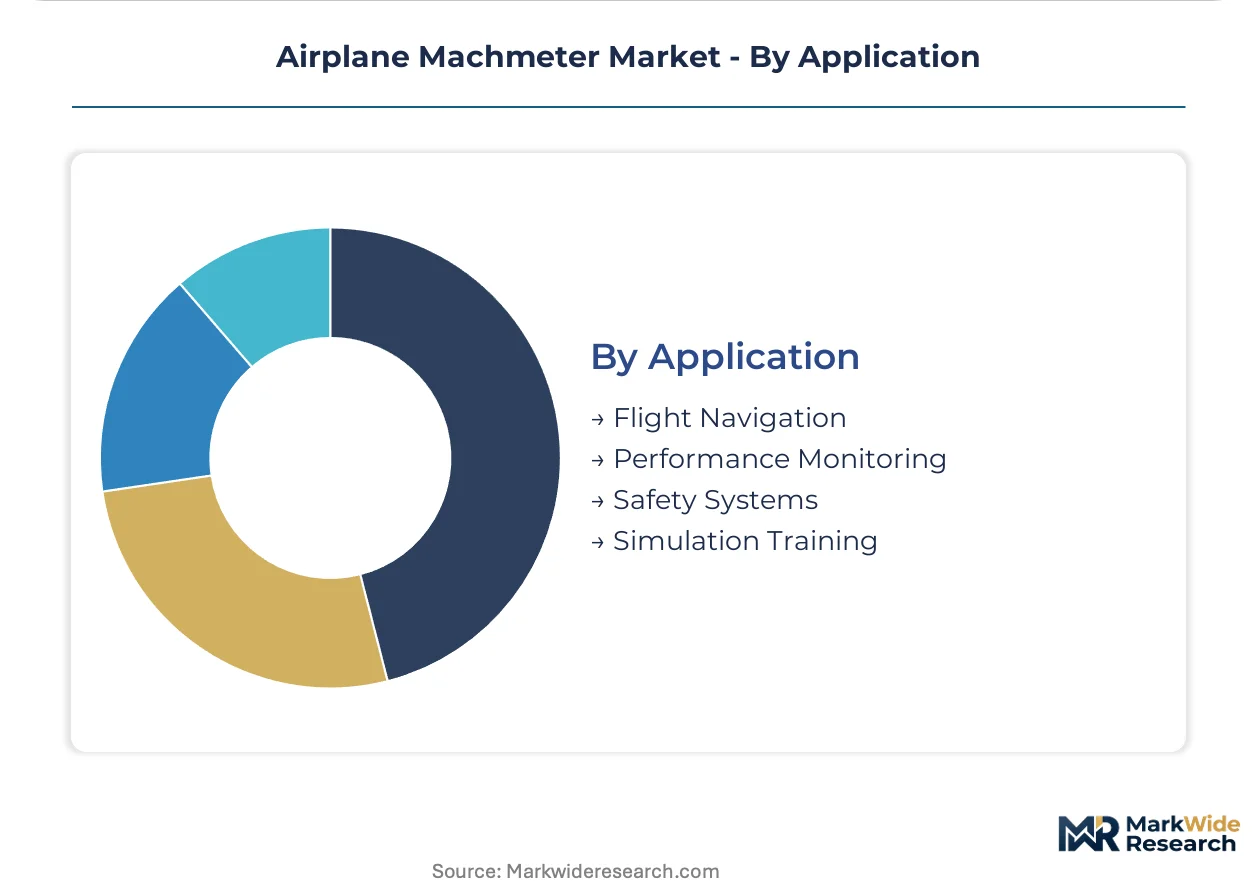
- Flight Navigation:Primary Mach indication for en-route and terminal area operations demands TSO-C8 or CS-25 certification with demonstrated reliability in compressibility-critical altitude regimes. All transport category aircraft require certified Mach indication for high-altitude flight above approximately 25,000 feet.
- Safety Systems:Backup Mach sources support envelope protection and stall warning functions, with EASA now mandating redundant electronic architectures for extended over-water operations.
- Performance Monitoring:Flight test and ferry operations utilize precision Mach measurement for fuel optimization and structural load verification.
- Simulation Training:Full-flight simulators replicate cockpit Mach indication for pilot training without airworthiness certification requirements.
Deployment breadth centers on Flight Navigation; specification intensity peaks in Safety Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Wichita, Kansas aviation cluster anchors North American air data instrumentation demand through concentrated MRO activity and OEM production corridors. Special economic zones in Zhuhai and Tianjin drive Chinese manufacturing scale for avionics components. German precision engineering hubs around Munich and Hamburg sustain European certification-grade instrument production.
United States
FAA TSO-C8 mandates for glass cockpit retrofits propel electronic machmeter demand across aging regional jet fleets. The Wichita aviation industrial corridor concentrates MRO providers performing pneumatic-to-digital upgrades during heavy maintenance checks. Dallas-Fort Worth and Seattle aerospace clusters host major avionics integration facilities serving Boeing and Airbus final assembly lines.
Germany
EASA CS-25 redundant source requirements for extended over-water operations stimulate multi-function machmeter procurement by Lufthansa and Condor fleets. The Munich precision engineering cluster houses Thales Group air data sensor integration facilities. Hamburg's Airbus final assembly line drives specification authority for next-generation cockpit architectures across European twin-aisle programs.
China
CAAC GB certification requirements for domestically manufactured avionics stimulate local production capacity expansion. The Zhuhai aviation industrial zone concentrates avionics assembly operations for COMAC C919 and ARJ21 programs. Tianjin's Airbus A320 final assembly line creates demand pull for flight instrumentation meeting dual certification standards.
France
EASA airworthiness codes shape large aircraft requirements through the Toulouse aerospace cluster. Dassault Aviation's fighter and business jet programs demand MIL-STD-1553 compatible electronic machmeters with embedded air data computation. The Paris-Saclay research corridor advances MEMS-based pressure sensing technology for next-generation solid-state architectures.
United Kingdom
BAE Systems military aircraft programs drive procurement of electronic machmeters with ARINC 429 bus integration for flight control compatibility. The Farnborough aerospace cluster hosts avionics suppliers serving RAF Typhoon and F-35 sustainment contracts. Bristol's engineering heritage supports precision instrument calibration services for European operator fleets.
Airplane Machmeter Market Vendor Landscape
Top-tier vendors anchor integrated flight deck portfolios, while specialized avionics houses occupy retrofit and general aviation segments. The vendor base stratifies across three tiers: diversified aerospace conglomerates with air data computer consolidation capabilities; dedicated instrument manufacturers with TSO-C8 certification expertise; and regional electronics fabricators serving price-sensitive aftermarket demand. Strategic moves center on sensor miniaturization partnerships and MIL-STD-1553 bus integration capabilities for military platform capture.
Within the diversified avionics tier, Honeywell and Thales Group exemplify integrated flight deck strategies spanning commercial and military verticals. Garmin occupies a distinct position in compact digital units for general aviation retrofit applications. Mid-Continent Instruments and Avionics represents the specialized instrument archetype with concentrated certification-grade production. These three anchors illustrate how competitive positioning diverges between platform-integrated and standalone instrument business models.
| Leading Market Players |
|---|
| Garmin |
| Mid-Continent Instruments and Avionics |
| Honeywell |
| Aerosonic Corporation |
| Ametek |
| Rockwell Collins |
| L3Harris Technologies |
| Universal Avionics |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Aerospace-grade MEMS pressure sensor pricing indices cascade through three distinct procurement tiers, compressing margins for pneumatic-to-digital upgrade programs while amplifying premium capture for TSO-C8 certified electronic architectures. Buyers with extended fleet retrofit timelines exploit spot inventory discounts, whereas operators facing FAA mandate deadlines absorb expedited delivery premiums.
Pricing Analysis
Lead-time-driven pricing stratification rewards advance procurement commitments with standard-tier rates, while compressed delivery windows trigger premium surcharges exceeding economy-tier baselines. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with TSO-C8 and MIL-STD-1553 compliant units commanding brand premiums over uncertified alternatives. Cost compression in economy-tier pneumatic replacements is intensifying because semiconductor foundry capacity constraints limit MEMS sensor availability. Regional carriers operating aging CRJ and E-Jet fleets exhibit highest price sensitivity, whereas military procurement offices prioritize performance specifications over unit economics.
Supply Chain Analysis
CAAC GB domestic-content mandates and EASA local-assembly requirements are reshaping sourcing patterns, compelling OEMs to establish certified production lines within Chinese and European economic zones. Component fabrication concentrates in Germany, China, and the United States, with precision pressure transducers drawing from Taiwanese semiconductor foundries and aerospace-grade aluminum housings sourced from German metallurgical suppliers. Single-source vulnerability permeates MEMS die supply, where concentrated East Asian wafer capacity creates chokepoint exposure. Distribution runs through airframe OEM specification channels, MRO procurement networks, and direct military contracting offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airplane machmeter sector sits in a technology-transition phase, with solid-state electronic architectures systematically displacing pneumatic and mechanical instruments across commercial and military platforms.
For Market Incumbents: Deepen backward integration into MEMS pressure sensor fabrication to secure captive supply against foundry capacity constraints, while accelerating TSO-C8 certification pipelines to defend against emerging avionics houses targeting retrofit segments. Threat substitution from integrated air data computers bundling Mach computation demands defensive positioning through multi-function display development. For New Entrants and Emerging Players: The price-point gap between premium certified electronic units and economy-tier pneumatic alternatives creates entry space for hybrid transitional designs targeting general aviation turboprop retrofits. White-space concentrates in compact digital units for light jet panel upgrades and aftermarket calibration services for aging pneumatic inventories. Go-to-market execution should prioritize FAA repair station partnerships over direct OEM competition. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized instrument manufacturers with dormant TSO-C8 certifications in the United States, where regional carrier fleet renewals will reactivate dormant production assets. Long-term viability hinges on electronic architecture transition completion within the next decade. Acquisition targets should demonstrate embedded air data computation capabilities or established MIL-STD-1553 integration track records. The signal to watch is CAAC certification acceleration for COMAC platform programs, indicating inflection toward Chinese domestic supply chain preference.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Sensor Backward Integration | Captive supply of pressure transducers insulates against Taiwanese foundry capacity constraints affecting competitors. |
| TSO-C8 Certification Pipeline Expansion | Accelerated FAA approval cycles capture regional carrier retrofit demand ahead of mandate deadlines. |
| MIL-STD-1553 Bus Integration Development | Military platform compatibility opens NATO fighter and trainer procurement channels. |
| Multi-Function Display Architecture | Combined Mach-temperature-angle indication counters air data computer substitution threats. |
| CAAC GB Certification Investment | Domestic Chinese approval enables COMAC C919 and ARJ21 program participation. |
Methodological Framework
Document review covered FAA TSO-C8 certification databases, EASA CS-25 airworthiness filings, and CAAC GB standards repositories, complemented by interviews with avionics integration engineers, MRO procurement directors, military platform program managers, and flight test instrumentation specialists. Secondary validation drew from airframe OEM specification sheets, semiconductor trade flow data, and airline fleet renewal announcements. Bottom-up unit demand estimates triangulated against top-down fleet projection models.
Output modeling produced volume and value trajectories across the projection horizon, with segmentation dimensions spanning product type, end user category, technology architecture, and application function. CAGRs were derived from fitted growth curves incorporating fleet renewal cycles, regulatory mandate timelines, and technology substitution elasticities. Industry-specific inputs included pitot-static system retirement schedules, glass cockpit retrofit penetration rates, and military platform production forecasts.
Inputs from OEM specification channels and MRO procurement databases were available through the study window; gaps in real-time military program budget allocations introduce uncertainty bands around defense segment projections. Forecasts reflect assumptions regarding regulatory harmonization timelines and semiconductor supply normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Global Aircraft Health Monitoring Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market