
 Early Warning Radar Market | 2026-2036
Early Warning Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Early Warning Radar Market Intelligence
Active electronically scanned array technology is fragmenting traditional radar procurement into modular, software-defined subsystems that integrate with broader command networks. Raytheon Technologies leverages its GaN transmitter foundries to sustain cost advantages in high-power ground-based segments. Lockheed Martin anchors the long-range ballistic missile defense niche with layered sensor architectures. Thales Group competes across European consortium programs while specializing in naval rotating electronically scanned array variants.
Early warning radar denotes long-range detection systems operating in L-, S-, or UHF-bands to identify aircraft, missiles, or maritime threats at standoff distances exceeding 300 nautical miles, typically employing solid-state transmitters and digital beamforming processors to filter clutter and track multiple targets simultaneously. Phased array deployments dominate defense budgets due to their multi-target tracking and rapid beam steering capabilities, while frequency modulated continuous wave systems are gaining share in wind farm monitoring and low-altitude drone detection where cost and power constraints matter. Satellite-based systems represent the fastest-growing deployment category as space sensor layers complement terrestrial gaps in polar and oceanic coverage.
FAA coordination with military air defense networks shapes dual-use air traffic management requirements in the United States, while NATO STANAG standards harmonize interoperability demands across European procurement. The EU's European Defence Fund and GDPR-linked data sovereignty rules complicate cross-border sensor data sharing architectures. Stakeholders must weigh sovereign supply chain requirements against the cost efficiencies of transatlantic component sourcing as export control regimes tighten on gallium nitride substrates and advanced signal processing chipsets.
Market Dynamics
Active electronically scanned array technology is collapsing the cost-performance curve for long-range detection, forcing defense procurement offices to abandon mechanically rotated dish architectures in favor of software-defined distributed networks that integrate with layered missile defense command systems.
Growth Catalysts
- EU European Defence Fund:Collaborative radar development programs channel member state budgets into shared R&D platforms, reducing per-unit development costs for participating nations.
- NATO STANAG interoperability mandates:Standardized data protocols accelerate cross-border sensor network integration across continental European air defense corridors.
- Gallium nitride transmitter substrates:Solid-state GaN power amplifiers deliver higher output with reduced thermal load, enabling compact mobile deployments previously impossible with vacuum tube transmitters.
Market Restraints
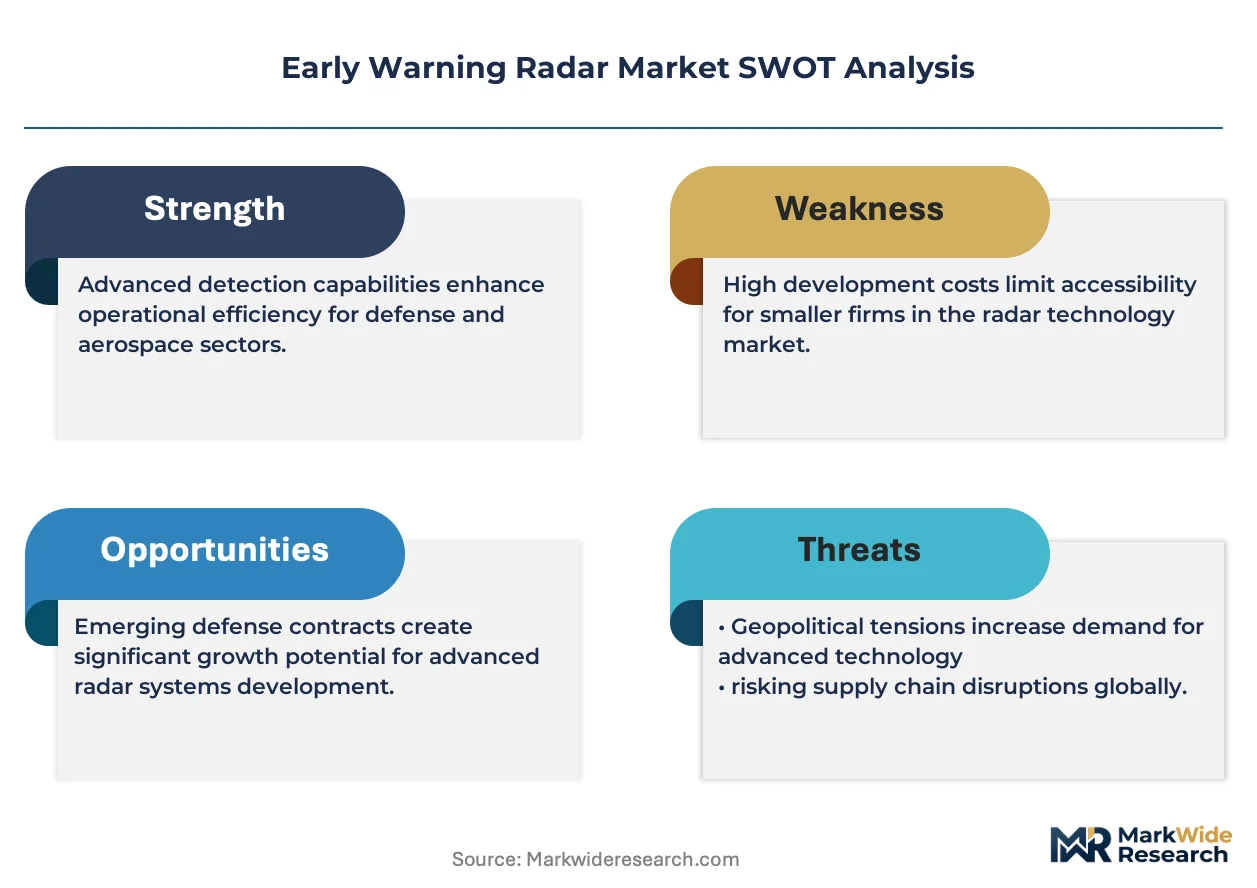
- Export control regimes:US International Traffic in Arms Regulations and EU dual-use technology restrictions constrain cross-border transfer of advanced signal processing chipsets and digital beamforming algorithms.
- Specialized foundry concentration:High-reliability GaN-on-SiC wafer production concentrates among three US and Japanese suppliers, creating single-source vulnerability for prime contractors.
- Frequency allocation congestion:Commercial 5G deployment in C-band spectrum encroaches on radar operating windows, forcing costly filter redesigns and operational coordination protocols.
Strategic Opportunities
- Arctic sensor gaps:Satellite-based radar constellations address polar coverage deficiencies where terrestrial installations face extreme maintenance costs and limited accessibility.
- Wind farm interference mitigation:Frequency modulated continuous wave systems penetrate turbine blade clutter for low-altitude drone detection, opening civilian energy sector contracts.
- Dual-use FAA-military coordination:Civil aviation authorities in the United States seek integrated air traffic and defense surveillance, creating unified procurement vehicles.
Industry Challenges
- Digital beamforming engineering scarcity:Phased array algorithm development requires rare combinations of RF physics and real-time embedded systems expertise, constraining program staffing.
- Legacy analog radar integration:Fielded mechanical systems lack digital interfaces for network-centric warfare architectures, forcing expensive retrofit or parallel infrastructure builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Early Warning Radar Market |
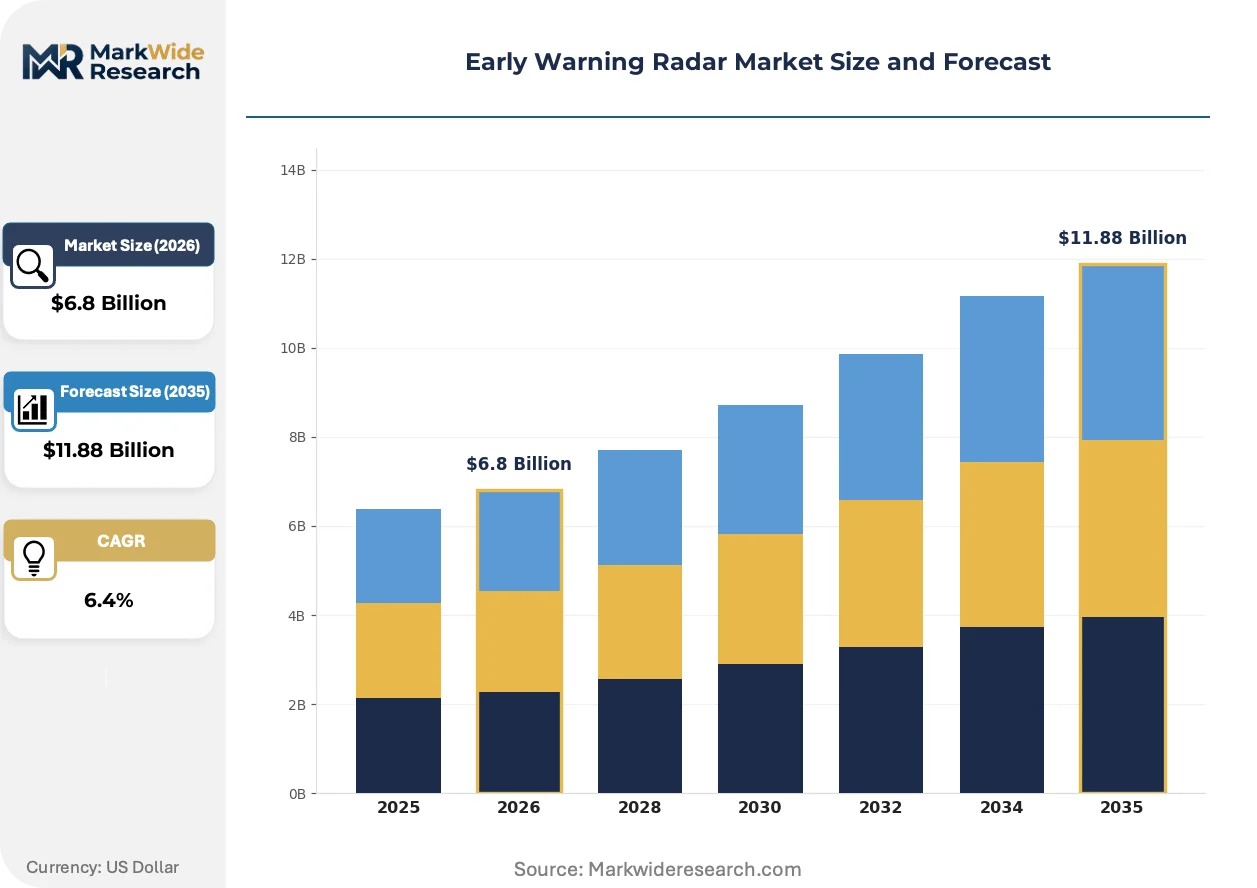
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Pulse-Doppler, Continuous Wave, Phased Array, Synthetic Aperture, Frequency Modulated Continuous Wave Application: Maritime Security, Border Surveillance, Air Traffic Management, Disaster Management, Wind Farm Monitoring Deployment: Fixed Stations, Mobile Units, Naval Vessels, Airborne Platforms, Satellite-Based Systems End User: Defense Forces, Coast Guard, Aviation Authorities, Meteorological Agencies, Environmental Monitoring |
| Companies Covered | BAE Systems, Raytheon Technologies, Lockheed Martin, Leonardo, General Dynamics, Thales Group, L3Harris Technologies, Israel Aerospace Industries, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Early Warning Radar Market Strategic Shifts & Innovations
Software-defined radio architectures are dissolving hardware-software boundaries in radar procurement, enabling capability upgrades through firmware rather than physical replacement cycles.
Digital twin simulation is collapsing development timelines for complex phased array calibration, allowing Thales and Raytheon to validate beamforming algorithms in virtual electromagnetic environments before physical prototype fabrication. Naval procurement offices now mandate digital twin deliverables alongside hardware, compressing sea trial schedules and reducing at-sea testing costs for rotating electronically scanned array variants.
EU GDPR-linked data sovereignty rules are fragmenting cross-border sensor data sharing architectures, compelling NATO members to deploy federated processing nodes that retain raw signal data within national borders while sharing only processed tracks. Germany and France lead implementation of edge-computing gateway standards that satisfy CNIL and BfDI oversight requirements without degrading collective defense response times.
Defense procurement offices are consolidating vendor relationships around system-of-systems integrators capable of delivering command-and-control networks alongside sensor hardware. United Kingdom Strategic Command now evaluates radar procurements on network integration metrics rather than standalone detection specifications, disqualifying component specialists lacking proven battle management system interfaces.
Early Warning Radar Market Segmentation
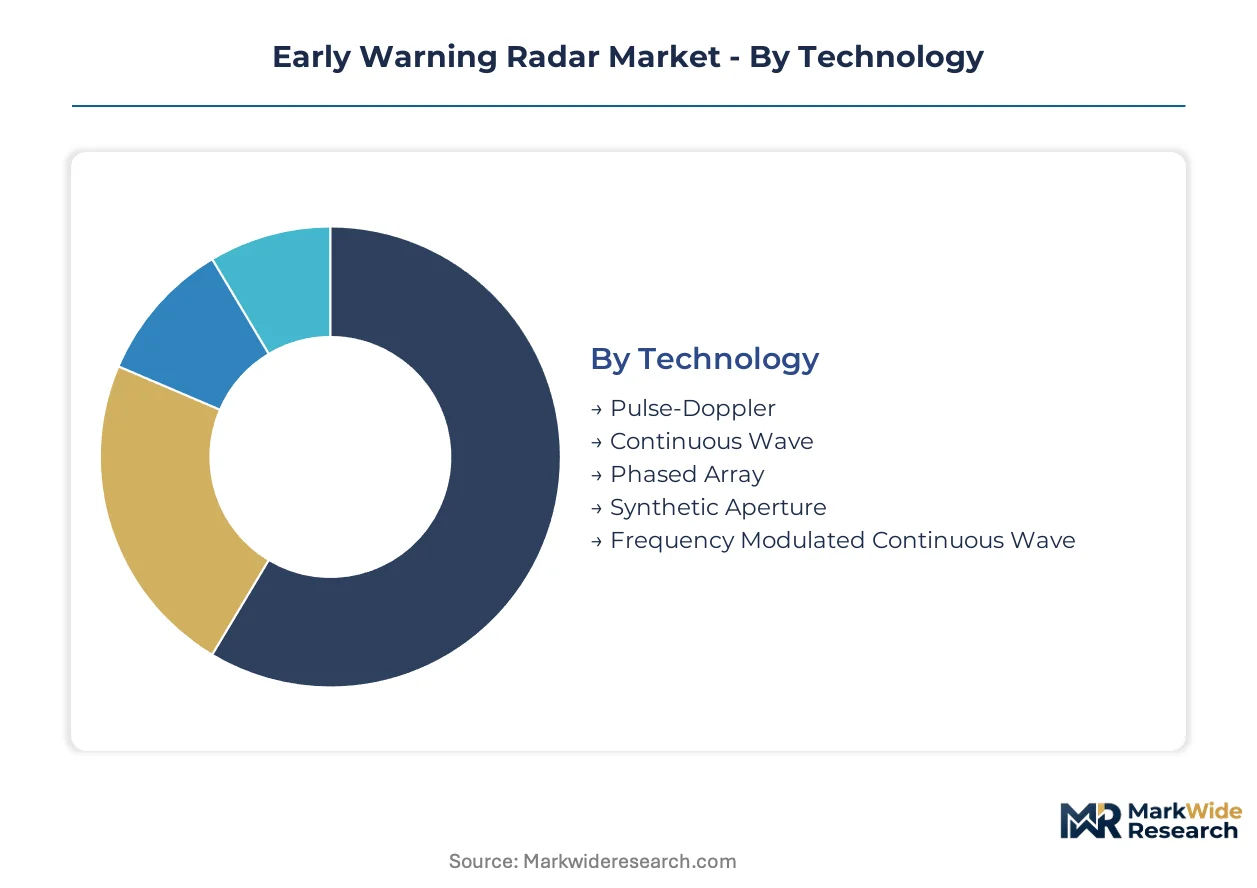
Early warning radar procurement divides sharply between legacy mechanical systems with decade-long replacement cycles and software-defined architectures that refresh through firmware updates. Understanding these velocity differences shapes supplier strategy and investment prioritization across defense and civilian applications.
Technology:
Cycle times vary dramatically: solid-state transmitters on gallium nitride substrates turn over every 7-10 years while analog vacuum tube systems persist for 20+ years in remote installations.
- Phased Array:Active electronically scanned arrays eliminate mechanical rotation through thousands of solid-state transmit-receive modules. Defense forces in the United States and United Kingdom prioritize these for integrated air and missile defense networks where rapid beam steering enables multi-target tracking.
- Frequency Modulated Continuous Wave:Low-power solid-state architecture penetrates turbine blade clutter for wind farm monitoring and low-altitude drone detection. Civilian energy sector contracts in Germany concentrate here due to cost constraints and spectral efficiency requirements.
- Pulse-Doppler:Conventional magnetron-based systems dominate legacy air traffic management infrastructure.
- Continuous Wave:Simple Doppler processing suits harbor surveillance and small-craft detection.
- Synthetic Aperture:Airborne and satellite platforms leverage motion-induced resolution enhancement for mapping and change detection.
Phased Array dominates installed base. Frequency Modulated Continuous Wave is where expansion concentrates.
Application:
Cost tiers separate mission-critical defense programs from commercial monitoring contracts, with dual-use aviation systems occupying a middle tier that blends FAA coordination with military interoperability mandates.
- Air Traffic Management:Long-range en-route surveillance radars operating in L-band coordinate with military air defense networks under FAA-led dual-use frameworks. Procurement in the United States increasingly specifies software-defined architectures that accommodate both civil aviation and NORAD mission requirements.
- Maritime Security:Coastal surveillance systems integrate with Coast Guard command networks for vessel traffic service and search-and-rescue coordination. Naval procurement offices mandate rotating electronically scanned array variants with digital twin deliverables to compress sea trial schedules.
- Border Surveillance:Ground-based radars monitor remote terrain gaps where tower infrastructure proves uneconomical.
- Disaster Management:Portable weather radars deploy for flood and storm tracking in coordination with meteorological agencies.
- Wind Farm Monitoring:Specialized clutter mitigation enables turbine-embedded drone detection for energy sector security.
Maritime Security commands premium pricing. Wind Farm Monitoring is climbing the fastest as renewable energy security budgets expand.
Deployment:
Volume concentrates in fixed terrestrial installations while mobility premiums reward integrated platform suppliers capable of delivering compact, ruggedized variants.
- Fixed Stations:Ground-based installations with dedicated power and cooling infrastructure provide continental air defense coverage. NATO STANAG interoperability mandates accelerate cross-border sensor network integration across European corridors.
- Satellite-Based Systems:Orbiting radar constellations address polar coverage deficiencies where terrestrial maintenance costs prove prohibitive. EU investment through the European Defence Fund channels collaborative development into shared space sensor layers.
- Mobile Units:Transportable systems deploy to expeditionary bases and forward operating locations.
- Naval Vessels:Shipboard rotating electronically scanned arrays integrate with combat management systems.
- Airborne Platforms:AWACS and maritime patrol aircraft carry synthetic aperture and pulse-Doppler systems for standoff detection.
Fixed Stations anchor procurement volume. Satellite-Based Systems are gaining share fastest as polar coverage gaps drive constellation deployment.
End User:
Customer type determines specification rigor: defense procurement offices mandate network-centric warfare interfaces while civilian agencies prioritize cost efficiency and regulatory compliance.
- Defense Forces:Integrated air and missile defense networks require multi-static coordination, low probability of intercept modes, and hardened command links. United Kingdom Strategic Command now evaluates procurements on network integration metrics rather than standalone detection specifications.
- Aviation Authorities:Dual-use air traffic management demands harmonized civil-military coordination protocols. FAA specifications shape procurement vehicles that unify civilian surveillance with defense requirements.
- Coast Guard:Maritime domain awareness programs blend search-and-rescue with law enforcement and environmental protection.
- Meteorological Agencies:Weather radar networks prioritize precipitation measurement accuracy over target discrimination.
- Environmental Monitoring:Remote sensing applications track ice sheet dynamics and deforestation through synthetic aperture satellite systems.
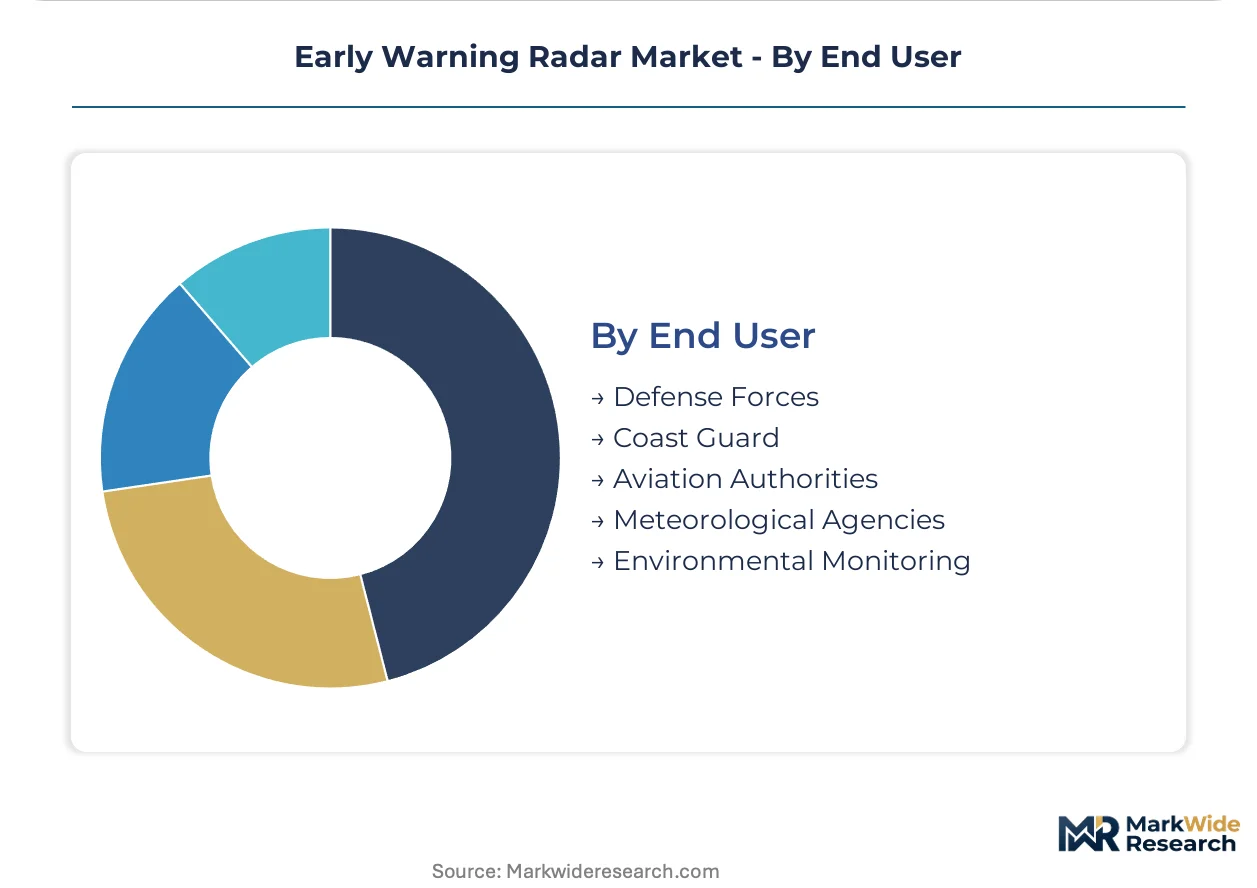
Defense Forces control the largest budget allocation. Aviation Authorities represent the steepest expansion trajectory as dual-use coordination deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices in the United States, United Kingdom, and Germany concentrate the majority of phased array radar spending. Military modernization budgets across NATO member states prioritize distributed sensor architectures over legacy single-site installations.
United States
The Pentagon's integrated air and missile defense networks drive demand for active electronically scanned arrays with rapid beam steering capabilities. FAA coordination with NORAD shapes dual-use procurement vehicles that unify civil aviation surveillance with defense requirements. Raytheon Technologies leverages its GaN transmitter foundries from Massachusetts and Arizona facilities to sustain cost advantages in high-power ground-based segments.
United Kingdom
Strategic Command evaluates radar procurements on network integration metrics rather than standalone detection specifications. The country's defense procurement office mandates proven battle management system interfaces, disqualifying component specialists lacking integration credentials. BAE Systems anchors domestic production from its Hampshire and Lancashire engineering centers while participating in European consortium programs.
Germany
The BfDI data sovereignty oversight and GDPR-linked rules complicate cross-border sensor data sharing architectures with neighboring NATO members. Germany leads implementation of edge-computing gateway standards that satisfy federal data protection requirements without degrading collective defense response times. Hensoldt and other Bavaria-based electronics clusters specialize in naval rotating electronically scanned array variants for Bundeswehr modernization.
France
CNIL oversight requirements shape federated processing node deployments that retain raw signal data within national borders while sharing processed tracks with allied networks. Thales Group competes across European consortium programs from its Paris and Toulouse engineering centers. The country's European Defence Fund allocations channel collaborative radar development into shared space sensor layers addressing Arctic coverage gaps.
Japan
METI industrial policy supports domestic GaN-on-SiC substrate research to reduce dependence on US and Japanese foundry suppliers for high-reliability components. The Japan Self-Defense Forces prioritize layered sensor architectures for ballistic missile defense against regional threats. Mitsubishi Electric and other Tokyo-Osaka corridor manufacturers develop compact mobile deployments previously impossible with vacuum tube transmitters.
Early Warning Radar Market Key Industry Players
Channel-controlling players compete with product-specialist players across procurement tiers defined by network integration capability. The vendor base organizes around three strategic archetypes: system-of-systems integrators delivering command-and-control networks alongside sensor hardware, component specialists focused on transmit-receive modules and signal processing chipsets, and platform-agnostic software vendors supplying digital beamforming algorithms. Prime contractors deepen backward integration into GaN substrate supply while mid-tier specialists pursue strategic partnerships with battle management system developers.
Among US-based defense conglomerates, Raytheon Technologies and Lockheed Martin exemplify the system-of-systems integrator archetype. Thales Group represents the European consortium participant model with specialization across naval and ground-based variants. These three anchors demonstrate how geographic origin and corporate structure shape competitive positioning within procurement frameworks that prioritize software-defined architectures and digital twin deliverables.
| Leading Market Players |
|---|
| BAE Systems |
| Raytheon Technologies |
| Lockheed Martin |
| Leonardo |
| General Dynamics |
| Thales Group |
| L3Harris Technologies |
| Israel Aerospace Industries |
| Northrop Grumman |
| Others |
Cost & Logistics Intelligence
Undercapacity at Japanese GaN-on-SiC foundries drives supplier prioritization toward defense primes with long-term offtake agreements, compressing margins for mid-tier contractors while elevating pricing power for integrated transmitter manufacturers with captive wafer supply.
Pricing Analysis
Cost-plus contracts with Bureau of Labor Statistics producer price indexation dominate defense procurement, insulating prime contractors from raw material volatility while transferring gallium nitride substrate cost escalations to government buyers. Three-tier pricing structure across premium, standard, and economy levels separates networked command-and-control systems from standalone sensor hardware and refurbished legacy installations. Price differentiation hinges on ITAR compliance certification and after-sales technical support bundling. Cost compression in frequency modulated continuous wave segments is intensifying because commercial drone detection vendors compete on unit economics. Aviation authorities exhibit the highest price sensitivity due to civil budget constraints, while defense forces accept premium positioning for hardened, low-probability-of-intercept variants.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for digital signal processing chipsets and rare earth magnet components. High-reliability GaN-on-SiC wafer production concentrates in Japan, the United States, and Germany, drawing from specialized epitaxy equipment and ultra-high-purity precursor gases. Raw material dependencies rest on gallium metal refinement, silicon carbide substrates, and advanced ceramic packaging. Single-source vulnerability persists for radiation-hardened field-programmable gate arrays. Distribution runs through defense contractor tiered supplier networks with DFARS compliance mandates, rather than open commercial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early warning radar sits in early-cycle expansion as distributed sensor architectures displace legacy mechanically rotated systems across NATO integrated air and missile defense networks.
For Market Incumbents: Entrench GaN transmitter foundry capacity through backward integration into substrate supply, locking out competitors from high-reliability component access. Deepen command-and-control software integration credentials to satisfy United Kingdom Strategic Command network-centric evaluation criteria. Emerging software-defined radio entrants threaten component specialists lacking battle management system interfaces. For New Entrants and Emerging Players: Frequency modulated continuous wave wind farm monitoring in Germany represents the most penetrable entry point, bypassing ITAR-controlled defense procurement barriers. Arctic satellite-based radar constellations offer white-space access through European Defence Fund collaborative programs with reduced sovereign supply chain requirements. Pursue civilian energy sector security contracts as a beachhead before attempting defense certification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined architectures as firmware upgrades replace physical replacement cycles. Long-term viability favors system-of-systems integrators with demonstrated NATO STANAG interoperability over component specialists facing margin compression. Watch for European Defence Fund allocation announcements as inflection indicators for consortium program participation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Transmitter Foundry Expansion | Captive gallium nitride substrate supply secures cost advantages against competitors dependent on Japanese wafer allocation. |
| Digital Twin Deliverable Mandate | Virtual electromagnetic validation compresses sea trial schedules for naval rotating electronically scanned array programs. |
| Federated Processing Node Deployment | Edge-computing gateways satisfy Germany BfDI data sovereignty requirements without degrading NATO collective defense response times. |
| Dual-Use FAA Coordination | Unified procurement vehicles blend civil aviation surveillance with NORAD mission requirements in United States airspace. |
| Arctic Satellite Constellation Buildout | Space-based radar layers address polar coverage gaps where terrestrial maintenance costs prove prohibitive. |
Research Approach
Operator-level perspectives from radar program managers at defense procurement offices, GaN foundry operations directors, systems integration engineers, and battle management software architects anchored the qualitative base. Primary interview data combined with secondary validation from NATO STANAG documentation, FAA technical standard orders, Bureau of Industry and Security export control classifications, and SEC 10-K filings from prime contractors. Bottom-up unit deployment estimates across fixed station, satellite-based, mobile, naval, and airborne platforms triangulated against top-down defense budget allocation analysis.
Scenario-bracketing framed volume and value outputs across the projection horizon, modeling technology segmentation by phased array, frequency modulated continuous wave, pulse-Doppler, continuous wave, and synthetic aperture architectures alongside deployment mode and end-user categories. CAGRs derived from deployment velocity differentials between legacy mechanical replacement cycles and software-defined refresh patterns, incorporating gallium nitride transmitter adoption curves and European Defence Fund allocation trajectories as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in defense appropriations cycles, rare earth export restrictions, or C-band spectrum reallocation would shift the trajectory. Forecasts reflect documented assumptions regarding NATO interoperability mandate timing and ITAR regulatory continuity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
North America Signals Intelligence (SIGINT) Market
Military Surveillance
Europe Hydrographic Survey Equipment Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Air-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Tactical Scope Market
Military Surveillance
EO/IR Gimbal Market