
 Airplane Landing Gear Market | 2026-2036
Airplane Landing Gear Market Size, Share, and Industry Trends Forecast 2026-2036
Airplane Landing Gear Market Insights
FAA corrosion-related airworthiness directives is realigning the cost-of-entry calculus for landing gear manufacturers serving the North American aftermarket. Safran Landing Systems leverages its integrated brake-and-gear architecture to sustain pricing power across OEM contracts. Collins Aerospace anchors its position through hydraulic actuation expertise inherited from legacy UTC platforms. Héroux-Devtek competes on precision-machined structural components for regional jet programs.
Airplane landing gear comprises the undercarriage assembly—struts, wheels, brakes, and retraction mechanisms—designed to absorb impact loads exceeding ten times aircraft weight during touchdown and support taxi operations up to rated maximum takeoff weights. Retractable landing gear dominates commercial aviation applications where drag reduction directly improves fuel efficiency on long-haul routes. Electric actuation technology is displacing legacy hydraulic systems in next-generation narrow-body designs, concentrating R&D investment among tier-one suppliers. Maintenance & Repair Organizations represent a deepening margin pool as fleet age extension programs proliferate across North American and European operators.
FAA airworthiness directives and EASA certification standards jointly govern structural integrity testing, fatigue life limits, and corrosion prevention protocols that define product qualification timelines. The EU Green Deal's aviation decarbonization pathway is forcing material substitutions toward lighter titanium alloys and composite brake heat shields. China's CAAC type certification requirements create parallel compliance tracks for Western suppliers accessing COMAC programs. Stakeholders must monitor electric landing gear maturation timelines and corresponding hydraulic system obsolescence risks.
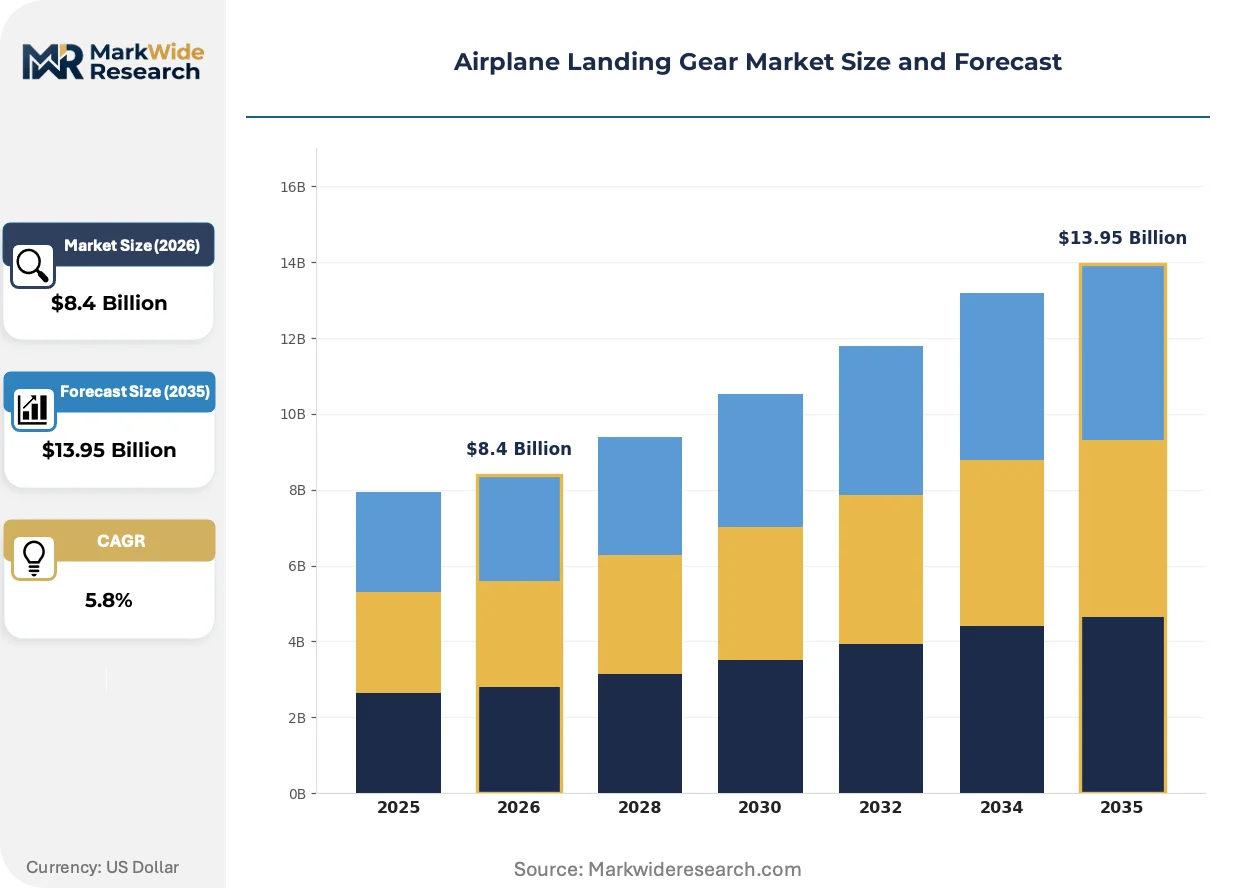
Market Dynamics
Electric actuation systems are compressing hydraulic component demand while FAA corrosion directives force material recertification across North American MRO networks, fundamentally restructuring supplier qualification timelines and OEM sourcing hierarchies.
Growth Catalysts
- FAA Airworthiness Directives:Corrosion-resistant material mandates are accelerating fleet-wide landing gear replacement cycles among narrow-body operators, expanding addressable aftermarket volume.
- China CAAC Certification:COMAC program participation requirements are pulling Western suppliers into parallel compliance tracks, opening domestic supply chain integration opportunities.
- Titanium Alloy Substitution:EU Green Deal decarbonization pathways are forcing lighter material adoption in brake heat shields and structural struts, creating specification upgrade revenue.
Market Restraints
- Titanium Price Volatility:Sponge and mill product cost swings compress margin predictability for precision-machined structural component manufacturers.
- Single-Source Hydraulic Actuation:Collins Aerospace's inherited UTC platform dominance concentrates critical subsystem supply, creating procurement risk for tier-two integrators.
- Fatigue Life Testing Bottlenecks:Extended FAA and EASA certification timelines for new alloy formulations delay product commercialization by 18-36 months.
Strategic Opportunities
- Southeast Asia Narrow-Body Expansion:Fleet growth in Indonesia, Vietnam, and Philippines is outpacing indigenous MRO capacity, creating aftermarket service white space.
- Electric-Hydraulic Convergence:Brake-by-wire integration with electromechanical retraction systems enables subsystem bundling for next-generation narrow-body platforms.
- China MRO Hub Network:Tianjin and Guangzhou maintenance cluster development offers joint venture pathways for Western landing gear overhaul specialists.
Industry Challenges
- Electromechanical Systems Integration:Legacy hydraulic architecture compatibility with electric actuation requires costly platform-specific engineering, stretching R&D budgets.
- Fatigue Analysis Talent Scarcity:Specialized structural integrity modeling expertise concentrates among retiring aerospace engineers, constraining design team scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Airplane Landing Gear Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.95 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable Landing Gear, Fixed Landing Gear, Tailwheel Landing Gear, Tandem Landing Gear Technology: Hydraulic, Electric, Pneumatic, Mechanical Application: Commercial Aircraft, Military Aircraft, Business Jets, Cargo Planes End User: OEMs, Maintenance & Repair Organizations, Aircraft Manufacturers, Aviation Service Providers |
| Companies Covered | Liebherr-Aerospace, Sumitomo Precision Products, Collins Aerospace, SPP Canada Aircraft, Magellan Aerospace, Safran Landing Systems, Triumph Group, AAR Corp, Héroux-Devtek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Airplane Landing Gear Market Trends and Innovations
Electrification is compressing established hydraulic supply chains while regulatory material mandates and shifting MRO procurement models are redefining competitive advantage around certification speed and aftermarket reach.
Electromechanical actuation is electrifying landing gear retraction and braking functions previously served by centralized hydraulic systems. Narrow-body OEMs are specifying distributed electric architectures for fuel efficiency gains on medium-haul routes. This transition is electrifying tier-one supplier R&D allocation and marginalizing legacy hydraulic component manufacturers unable to pivot.
EU Green Deal aviation decarbonization mandates are forcing titanium alloy and composite material substitutions across brake and strut assemblies. EASA certification standards for lighter structural configurations are tightening fatigue testing protocols. European narrow-body operators are responding by accelerating specification upgrades in scheduled overhaul windows.
Airline procurement teams are unbundling aftermarket service contracts from OEM original equipment purchases, creating independent MRO bidding opportunities. Third-party maintenance organizations in China's hub network are capturing brake overhaul volume previously captive to manufacturer service agreements. This disintermediation is most visible among Southeast Asian low-cost carriers optimizing unit economics through competitive tendering.
Airplane Landing Gear Market Segmentation
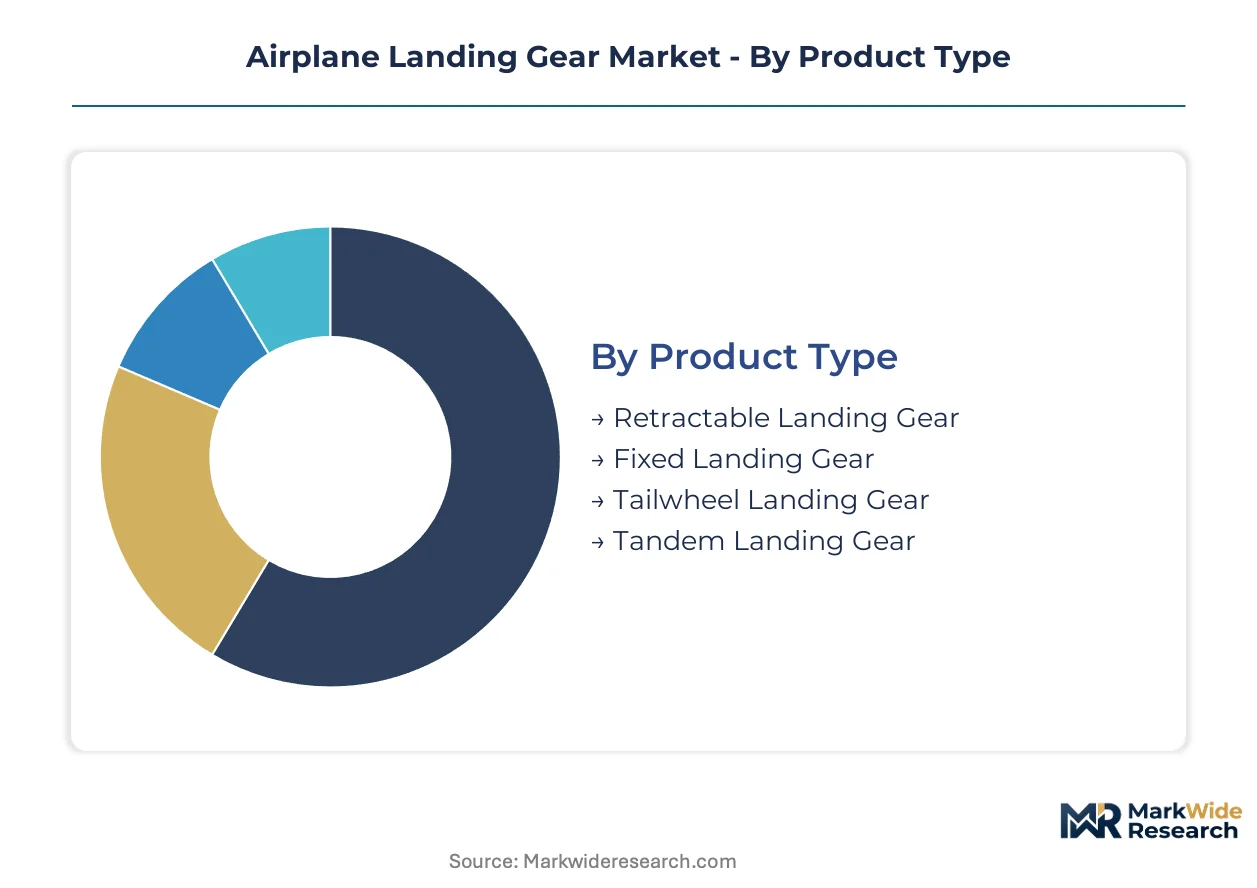
Segmentation in landing gear markets tracks the divergence between legacy hydraulic architectures and emerging electric systems, while application splits reveal where fleet renewal cycles concentrate replacement demand. Product type distinctions separate retractable commercial platforms from fixed-gear general aviation, with technology choices determining supplier qualification pathways.
Product Type:
Integration depth varies sharply: retractable systems embed within complex airframe architectures, while fixed and tailwheel configurations remain standalone assemblies with minimal subsystem coupling.
- Retractable Landing Gear:Hydraulically or electrically actuated undercarriage assemblies that stow within airframe compartments during flight to reduce drag. Narrow-body commercial fleets in Southeast Asia drive replacement cycles as corrosion-resistant material mandates from the FAA accelerate overhaul timelines. Electric actuation retrofits on legacy Boeing and Airbus platforms concentrate R&D investment among tier-one suppliers.
- Fixed Landing Gear:Permanently extended strut-and-wheel assemblies common to general aviation and training aircraft where simplicity outweighs aerodynamic penalty. Flight schools across the United States sustain steady component demand for Cessna and Piper fleets, though unit economics limit pricing power relative to commercial retractable systems.
- Tailwheel Landing Gear:Two main wheels forward with a steerable tailwheel aft, preserving directional stability on unpaved runways. Bush aviation operators in Alaska and Canadian remote regions maintain niche demand for ruggedized strut configurations.
- Tandem Landing Gear:Single-file wheel arrangement centered on fuselage longitudinal axis, found on glider tow planes and certain military reconnaissance platforms. Specialized aerobatic manufacturers in Germany and the Czech Republic anchor residual production volumes.
Volume placements concentrate in Retractable Landing Gear; the faster expansion belongs to Electric-actuated retractable variants.
Technology:
Cost tier stratification separates mature hydraulic systems with amortized tooling from capital-intensive electric architectures requiring fresh certification investment.
- Hydraulic:Pressurized fluid power systems delivering high force density for brake and retraction functions across legacy commercial fleets. Collins Aerospace's inherited UTC platform dominance concentrates critical subsystem supply, creating procurement concentration risk for tier-two integrators serving Boeing and Airbus programs.
- Electric:Electromechanical actuators replacing centralized hydraulic circuits with distributed motor-drive units. EU Green Deal decarbonization mandates and fuel efficiency targets on next-generation narrow-bodies pull development resources toward brake-by-wire integration with electromechanical retraction.
- Pneumatic:Compressed air systems limited to emergency extension backups and certain regional jet brake applications. Russian and Chinese indigenous programs sustain residual demand where Western hydraulic component access faces export control constraints.
- Mechanical:Direct linkage systems without power assistance, confined to light sport aircraft and vintage restoration markets. European microlight certification categories preserve minimal production footprints in Poland and Italy.
Revenue concentration remains with Hydraulic systems; the steepest expansion trajectory belongs to Electric architectures on new narrow-body platforms.
Application:
Customer type segmentation distinguishes fleet operators with scheduled overhaul windows from defense procurement with platform-specific qualification requirements.
- Commercial Aircraft:Scheduled airline operations with mandatory landing gear overhaul intervals tied to flight cycle accumulation. China's expanding MRO hub network around Tianjin and Guangzhou captures brake and strut refurbishment volume previously captive to OEM service agreements.
- Military Aircraft:Defense procurement with ruggedized requirements for unimproved runway operations and combat damage tolerance. Pentagon Foreign Military Sales channels sustain qualification pathways for landing gear suppliers serving F-35 and C-130 programs.
- Business Jets:Fractional ownership and corporate flight departments with discretionary replacement timing. Gulfstream and Dassault Falcon operators in the United States and France concentrate premium aftermarket demand.
- Cargo Planes:High-cycle express freight operations with accelerated wear patterns on brake and tire components. Amazon Air and FedEx Express 767-300 freighter fleets in Kentucky and Tennessee drive predictable overhaul scheduling.
Procurement scale favors Commercial Aircraft; the most rapid demand shift is occurring in Cargo Plane conversions of passenger narrow-bodies.
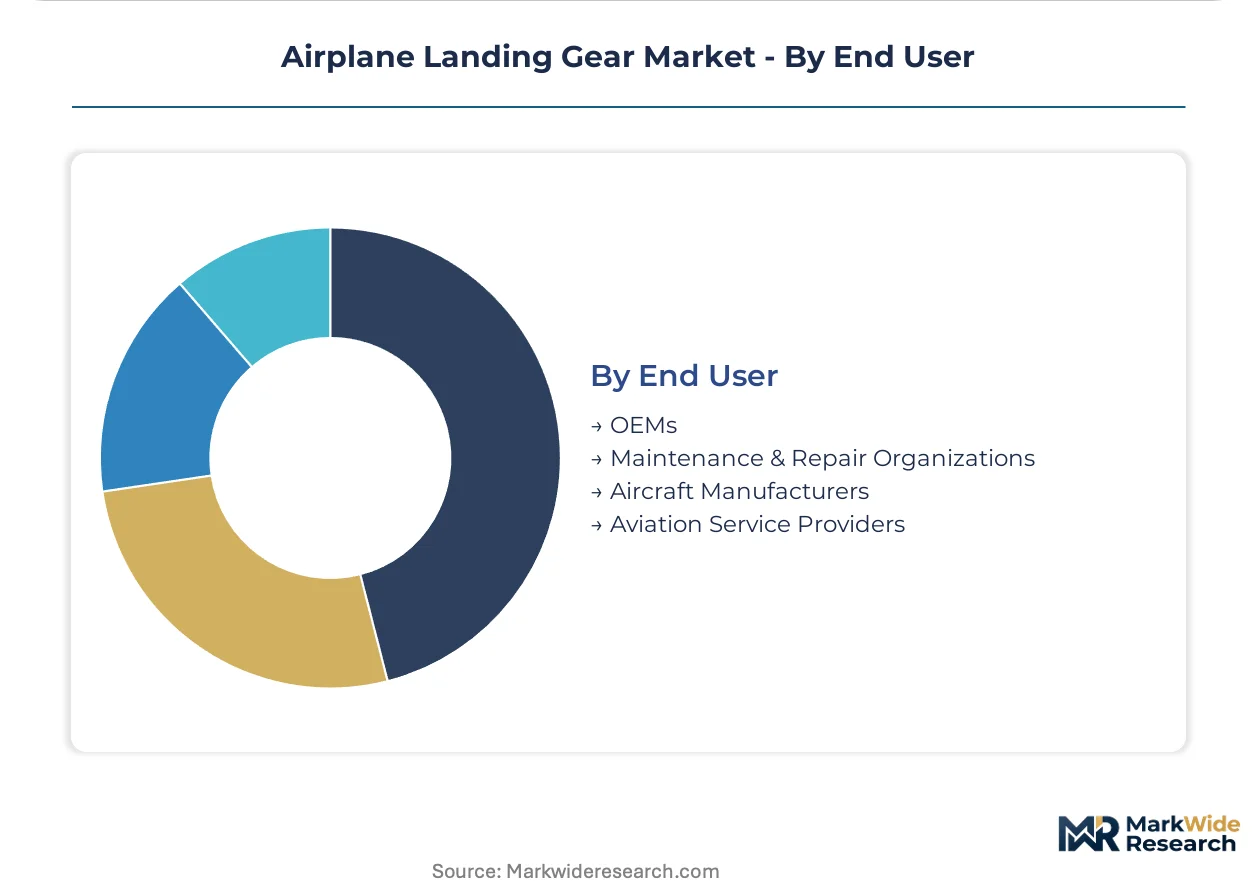
End User:
Supply concentration patterns separate OEM original equipment contracts with multi-year qualification horizons from aftermarket MRO bidding with compressed procurement cycles.
- OEMs:Original equipment manufacturers integrating landing gear as shipset components on new aircraft programs. Boeing and Airbus supply chain qualification timelines stretch 24-36 months for new alloy formulations, gating market entry for specialized suppliers.
- Maintenance & Repair Organizations:Independent overhaul facilities unbundling service contracts from manufacturer agreements. Third-party MROs in Indonesia, Vietnam, and the Philippines capture brake overhaul volume as Southeast Asian low-cost carriers optimize unit economics through competitive tendering.
- Aircraft Manufacturers:Tier-one airframe integrators specifying landing gear architectures during preliminary design phases. COMAC program participation requirements pull Western suppliers into parallel CAAC certification tracks, opening domestic supply chain integration opportunities in Shanghai.
- Aviation Service Providers:Leasing companies and asset managers overseeing landing gear condition monitoring across portfolio aircraft. AerCap and SMBC Aviation Capital technical teams in Dublin and Tokyo enforce specification compliance during lease return inspections.
Contract value aggregates at OEMs; the fastest share gain is occurring among Maintenance & Repair Organizations disintermediating manufacturer service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest share of narrow-body fleet expansion, while FAA corrosion directives in the United States and EU Green Deal material mandates in Europe reshape supplier qualification requirements across three continents.
United States
Narrow-body operators at Delta, United, and American Airlines accelerate landing gear replacement cycles under FAA airworthiness directives targeting corrosion-resistant materials. The FAA mandates extended fatigue testing protocols for new titanium alloy formulations, stretching OEM qualification timelines. MRO clusters in Kentucky and Tennessee capture brake overhaul volume from cargo operators including FedEx Express and Amazon Air.
China
COMAC C919 and ARJ21 production ramp-up pulls Western suppliers into parallel CAAC certification tracks for structural strut assemblies. The country's dual carbon goals force lighter material adoption in brake heat shields. Tianjin and Guangzhou maintenance hubs expand indigenous MRO capacity, unbundling service contracts previously captive to manufacturer agreements.
Germany
EU Green Deal aviation decarbonization pathways mandate titanium substitution in landing gear assemblies, tightening EASA fatigue testing standards for lighter configurations. Lufthansa Technik in Hamburg anchors premium aftermarket demand for business jet and narrow-body overhaul. Bavaria-based precision machiners supply structural components for Airbus A320 family programs.
France
Safran Landing Systems leverages integrated brake-and-gear architecture from its Toulouse and Vélizy engineering centers to sustain OEM contract pricing power. EASA certification standards govern structural integrity testing for next-generation electric actuation systems. The Île-de-France aerospace cluster concentrates R&D investment toward electromechanical retraction technology.
Japan
Sumitomo Precision Products anchors domestic supply for Boeing 787 and 777X shipset components from its Aichi Prefecture manufacturing base. METI industrial policy supports carbon fiber brake heat shield development under aviation decarbonization targets. Kansai region MRO facilities capture narrow-body overhaul volume from ANA and JAL fleet renewal programs.
Airplane Landing Gear Market Competitive Landscape
North American producers anchor one tier; European specialists hold another through integrated system architectures. The market structures around three tiers: tier-one integrators commanding OEM shipset contracts, tier-two precision machiners feeding structural components, and independent MRO operators unbundling aftermarket services. Two dominant competitive moves define current positioning: vertical integration into brake-and-gear bundled architectures, and geographic expansion into China's Tianjin and Guangzhou hub networks through joint venture structures.
Within the tier-one integrator tier, Safran Landing Systems and Collins Aerospace exemplify the bundled architecture approach, while Héroux-Devtek occupies a position among precision-machined structural specialists serving regional jet programs. Liebherr-Aerospace anchors European-based hydraulic actuation expertise inherited through legacy platform development. Sumitomo Precision Products represents Japanese fabrication depth on Boeing wide-body programs. Triumph Group and AAR Corp sit within the aftermarket service tier capitalizing on disintermediation trends among Southeast Asian low-cost carriers.
| Leading Market Players |
|---|
| Liebherr-Aerospace |
| Sumitomo Precision Products |
| Collins Aerospace |
| SPP Canada Aircraft |
| Magellan Aerospace |
| Safran Landing Systems |
| Triumph Group |
| AAR Corp |
| Héroux-Devtek |
| Others |
Pricing and Supply Chain Analysis
Tier-one OEM procurement teams at Boeing and Airbus anchor pricing power through multi-year shipset contracts, compressing margin capture for precision-machined component suppliers while independent MRO operators exploit disintermediation to extract spot-market discounts on brake overhaul services.
Pricing Analysis
Short lead-time premiums concentrate among narrow-body operators facing FAA-mandated corrosion-resistant material retrofits on compressed timelines. Three-tier pricing structure across premium, standard, and economy levels separates OEM shipset contracts with 24-36 month qualification horizons from aftermarket spot purchases and surplus inventory liquidation. Cost compression in titanium-machined structural components is intensifying because sponge and mill product volatility transfers downstream. Cargo operators at Amazon Air and FedEx Express exhibit highest price sensitivity due to high-cycle wear patterns, while business jet fractional owners show lowest sensitivity on discretionary replacement timing.
Supply Chain Analysis
Regional distribution centers in Germany, France, and Japan coordinate hub-and-spoke patterns for precision-machined strut assemblies and brake heat shields. Manufacturing gravity draws from titanium sponge producers in Russia and China, precision forging houses in Germany and Japan, and composite brake disc specialists in the United States and France. Single-source vulnerability concentrates in Collins Aerospace's inherited UTC hydraulic actuation platforms, creating procurement risk for tier-two integrators. Distribution runs through OEM-authorized service centers, independent MRO facilities in China's Tianjin and Guangzhou hubs, and third-party logistics providers serving Southeast Asian low-cost carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The airplane landing gear market sits in a technology-transition phase where electromechanical actuation is displacing legacy hydraulic architectures on next-generation narrow-body platforms, forcing supplier R&D reallocation and recertification investment.
For Market Incumbents: Extend aftermarket service reach through joint venture structures in China's expanding Tianjin and Guangzhou MRO hub networks, capturing brake overhaul volume disintermediated from manufacturer agreements. Deepen backward integration into titanium alloy precision forging to offset sponge price volatility compressing structural component margins. Prioritize CAAC certification investment for COMAC C919 and ARJ21 program participation before parallel compliance tracks close to late entrants. For New Entrants and Emerging Players: Independent MRO operators in Indonesia, Vietnam, and the Philippines represent the most penetrable channel partner type for brake refurbishment services, as Southeast Asian low-cost carriers unbundle service contracts from OEM agreements. Target electric-hydraulic convergence subsystems for next-generation narrow-body platforms where tier-one suppliers face R&D stretch. Pursue go-to-market angles through technical licensing partnerships with Chinese domestic MRO facilities seeking Western certification expertise. For Investors and Strategic Acquirers: The window for entry favors precision-machined structural component specialists with established EASA and FAA fatigue testing credentials, as qualification timeline bottlenecks create defensive moats. Long-term viability hinges on electric actuation pivot capacity and China market access. Monitor CAAC type certification approval velocity for Western suppliers as the inflection indicator for domestic supply chain integration opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CAAC Certification Investment | Parallel compliance tracks for COMAC programs open domestic China supply chain integration pathways for Western suppliers. |
| Electric Actuation R&D Scale-Up | Development resources concentrate toward brake-by-wire integration with electromechanical retraction on next-generation narrow-bodies. |
| China MRO Joint Venture | Tianjin and Guangzhou hub partnerships capture aftermarket volume disintermediated from OEM service agreements. |
| Titanium Alloy Backward Integration | Upstream control over precision forging offsets sponge price volatility compressing structural component margins. |
| Southeast Asia Distribution Expansion | Indonesia, Vietnam, and Philippines aftermarket service white space outpaces indigenous MRO capacity growth. |
Research Methodology
Document review covered FAA airworthiness directive filings, EASA certification standards, CAAC type certification requirements, and OEM procurement disclosures, complemented by interviews with landing gear program managers at tier-one integrators, MRO operations directors at China hub facilities, procurement leads at Southeast Asian low-cost carriers, and fatigue analysis specialists at precision machining houses. Secondary validation drew from customs trade data, aerospace supplier SEC filings, and fleet renewal databases. Bottom-up and top-down triangulation cross-referenced component-level production estimates with airframe delivery schedules.
Historical delivery patterns were cross-referenced against panel input from industry stakeholders to construct projection frameworks across the analysis window. Segmentation dimensions modeled include product type, technology architecture, application category, and end-user procurement channel. CAGRs were derived through regression analysis of fleet age distributions, replacement cycle acceleration under regulatory mandates, and narrow-body production ramp rates. Industry-specific forecast inputs incorporated FAA corrosion directive implementation timelines and EU Green Deal material substitution mandates.
Several conditions sit outside the modeled scope, including geopolitical disruption to titanium sponge supply from Russia, unanticipated EASA fatigue testing protocol revisions, and COMAC production rate volatility. Forecasts reflect documented assumptions regarding electric actuation adoption curves and China MRO hub development velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Galley Equipment Market
Aircraft
Aircraft Seals Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Asia-Pacific Aviation Market
Aircraft
Light and Very Light Jets Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Military Transport Aircraft Market
Aircraft
Global Aircraft Transparencies Market
Aircraft
South Korea Aviation Market
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Middle-East and Africa Business Jet Market
Aircraft
Aircraft Hangar Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Commercial Aircraft Aerostructures Market