
 Aviation Compliance Monitoring Tools Market | 2026-2036
Aviation Compliance Monitoring Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Compliance Monitoring Tools Market Insights
The direct-to-operator software channel is rewriting how aviation compliance tools reach end users, bypassing traditional systems integrators and compressing deployment timelines. SafetyCulture leverages its mobile-first architecture to sustain engagement among flight training centers and charter operators. Ramp Ready anchors its position through specialized audit management solutions tailored to FAA and EASA protocols. Drata competes by extending its automated evidence-collection engine into aviation-specific control frameworks, occupying a niche between generic GRC platforms and vertical specialists.
Aviation compliance monitoring tools encompass software systems that capture, analyze, and report flight operational data against regulatory standards, typically processing parameters from flight recorders, maintenance logs, and crew scheduling systems to flag deviations in real time. Their primary purpose is to enable proactive risk management and demonstrate regulatory adherence to civil aviation authorities. Cloud-based platforms now lead deployment preferences among commercial airlines seeking scalable infrastructure without capital-intensive on-premise installations. Artificial intelligence represents the fastest-expanding technology segment as operators demand predictive capabilities for incident prevention rather than retrospective compliance verification. Safety management systems constitute the most mature product category, while predictive analytics tools command the strongest margin pools due to specialized algorithm development requirements.
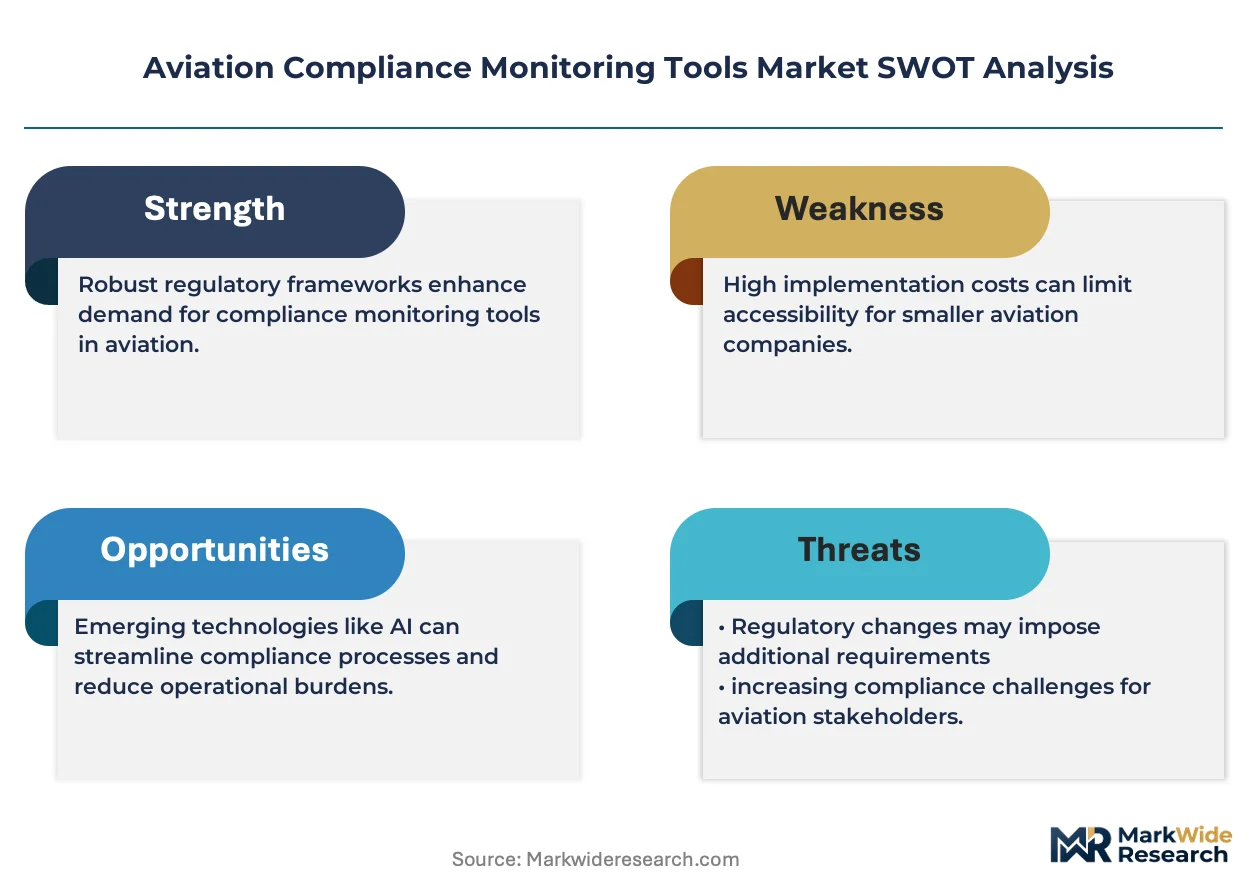
The FAA mandates Safety Management System implementation under Part 5 regulations, compelling U.S. operators to invest in integrated monitoring infrastructure that automates hazard identification and risk mitigation documentation. EASA's management system requirements under Regulation 965/2012 similarly shape product standards across European commercial airlines and maintenance organizations, with CE marking considerations affecting software procurement decisions. Stakeholders must monitor evolving cybersecurity annexes to aviation safety frameworks, as regulators in multiple jurisdictions are embedding digital resilience requirements into compliance mandates that will reshape vendor qualification criteria and procurement specifications.
Market Dynamics
Artificial intelligence is compressing incident detection cycles from weeks to hours, forcing operators to replace retrospective audit tools with predictive platforms that flag deviations before regulatory filings become necessary.
Growth Catalysts
- FAA Part 5 Mandate:U.S. operators must maintain automated Safety Management Systems, creating baseline demand for integrated hazard documentation platforms across commercial fleets.
- Flight Data Recorders:Next-generation FDRs output structured telemetry streams that compliance software ingests directly, eliminating manual transcription bottlenecks.
- United Arab Emirates:GCAA enforcement of management system requirements drives procurement among Dubai and Abu Dhabi-based carriers expanding long-haul networks.
Market Restraints
- Aviation-Grade Cloud Infrastructure:FedRAMP and equivalent sovereign cloud certifications limit vendor pool to providers with defense-adjacent data center footprints.
- Algorithm Development Costs:Predictive models require proprietary training datasets from incident histories that operators treat as competitively sensitive intellectual property.
- EASA Cybersecurity Annexes:Evolving digital resilience requirements force software recertification cycles that extend procurement timelines by 8-14 months.
Strategic Opportunities
- Saudi Arabia:Vision 2030 airport privatization and new airline launches create greenfield deployment opportunities without legacy system migration burdens.
- Maintenance Organization Convergence:MROs adopting unified compliance platforms for both EASA Part 145 and FAA Part 145 operations seek multi-jurisdiction tools.
- API-First Architecture:Open integration protocols enable compliance modules to embed directly into airline ERP systems, bypassing standalone software procurement cycles.
Industry Challenges
- Aviation Cybersecurity Expertise:Shortage of professionals holding both airworthiness engineering credentials and cloud security certifications delays implementation teams.
- Multi-Jurisdiction Audit Trails:Operators serving FAA, EASA, and CAAC jurisdictions simultaneously must reconcile conflicting evidence retention periods and access log formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Compliance Monitoring Tools Market |
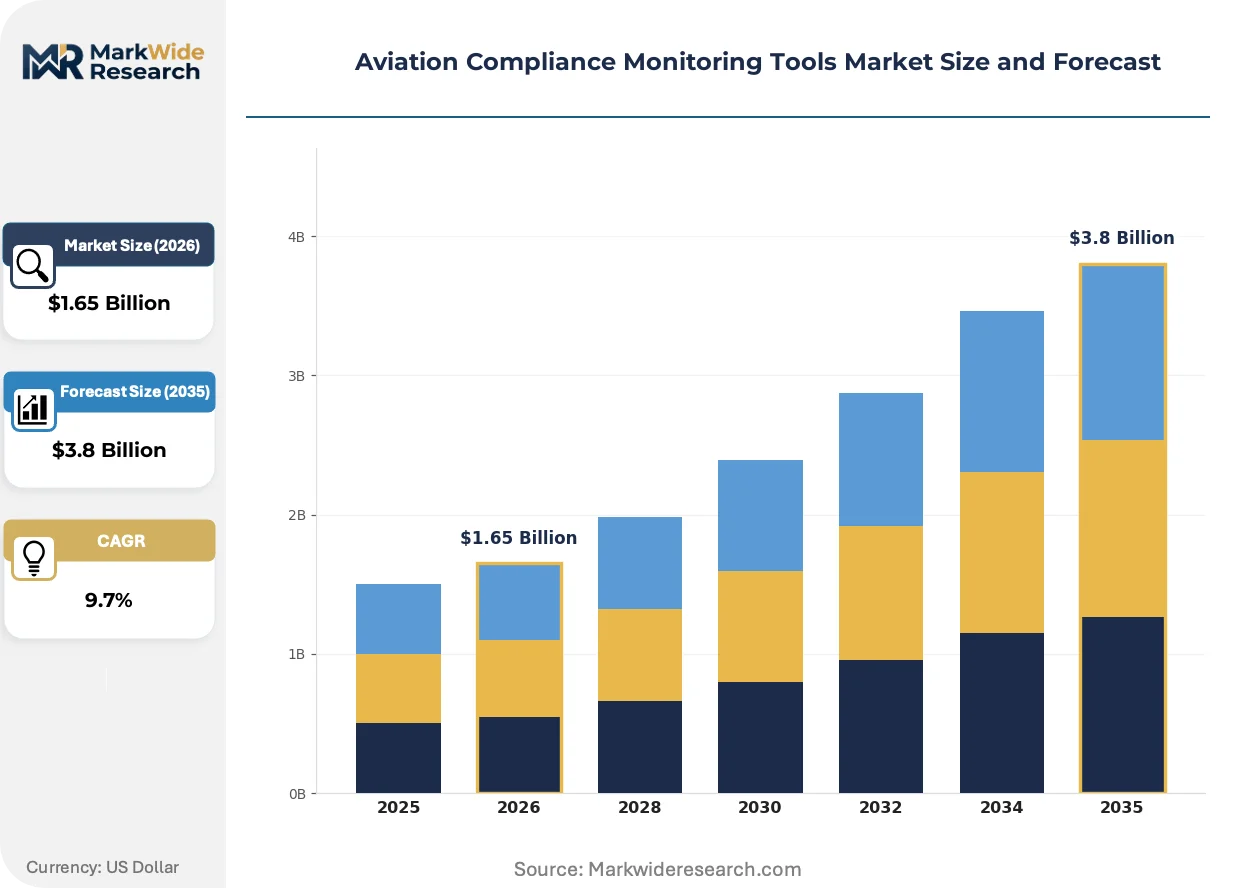
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flight Data Monitoring, Safety Management Systems, Automated Compliance Software, Predictive Analytics Tools, Audit Management Solutions Technology: Cloud-Based Platforms, On-Premise Systems, Artificial Intelligence, Data Visualization, Mobile Integration Application: Regulatory Reporting, Risk Assessment, Incident Investigation, Pilot Performance Tracking, Maintenance Scheduling End User Industry: Commercial Airlines, Airport Authorities, Aircraft Maintenance Organizations, Flight Training Centers, Charter Operators |
| Companies Covered | Ramp Ready, Tactical Decisions, SafetyCulture, Drata, Scrut, Shift5, SAFVR, Sprinto, Osprey Flight Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Compliance Monitoring Tools Market Trends and Innovations
Digital twin architectures are replacing static compliance dashboards, embedding regulatory verification into live operational workflows rather than periodic reporting cycles.
Edge computing nodes deployed on aircraft are virtualizing pre-flight compliance checks, processing maintenance log anomalies and crew duty-time violations during turnaround windows. Regional carriers with thinner IT departments adopt these systems fastest, outsourcing infrastructure management to specialized aviation SaaS providers. The technology is virtualizing the traditional ground-station compliance workflow into continuous airborne verification.
EASA's forthcoming AI Act implementation rules for safety-critical systems will mandate algorithmic transparency documentation for predictive compliance tools. European operators preparing for 2025-2026 enforcement windows are demanding vendor roadmaps for explainable AI features. Maintenance organizations with EASA Part 145 approval face the steepest documentation burden and are consolidating procurement around vendors with pre-validated control frameworks.
Charter operators and flight training centers now purchase compliance tools through direct software marketplaces rather than aviation-specific systems integrators. This channel compression reduces deployment timelines from 18 months to 6 weeks for standardized configurations. North American fractional ownership fleets demonstrate the most aggressive adoption of self-service procurement models, treating compliance software as operational infrastructure rather than capital projects.
Aviation Compliance Monitoring Tools Market Segmentation
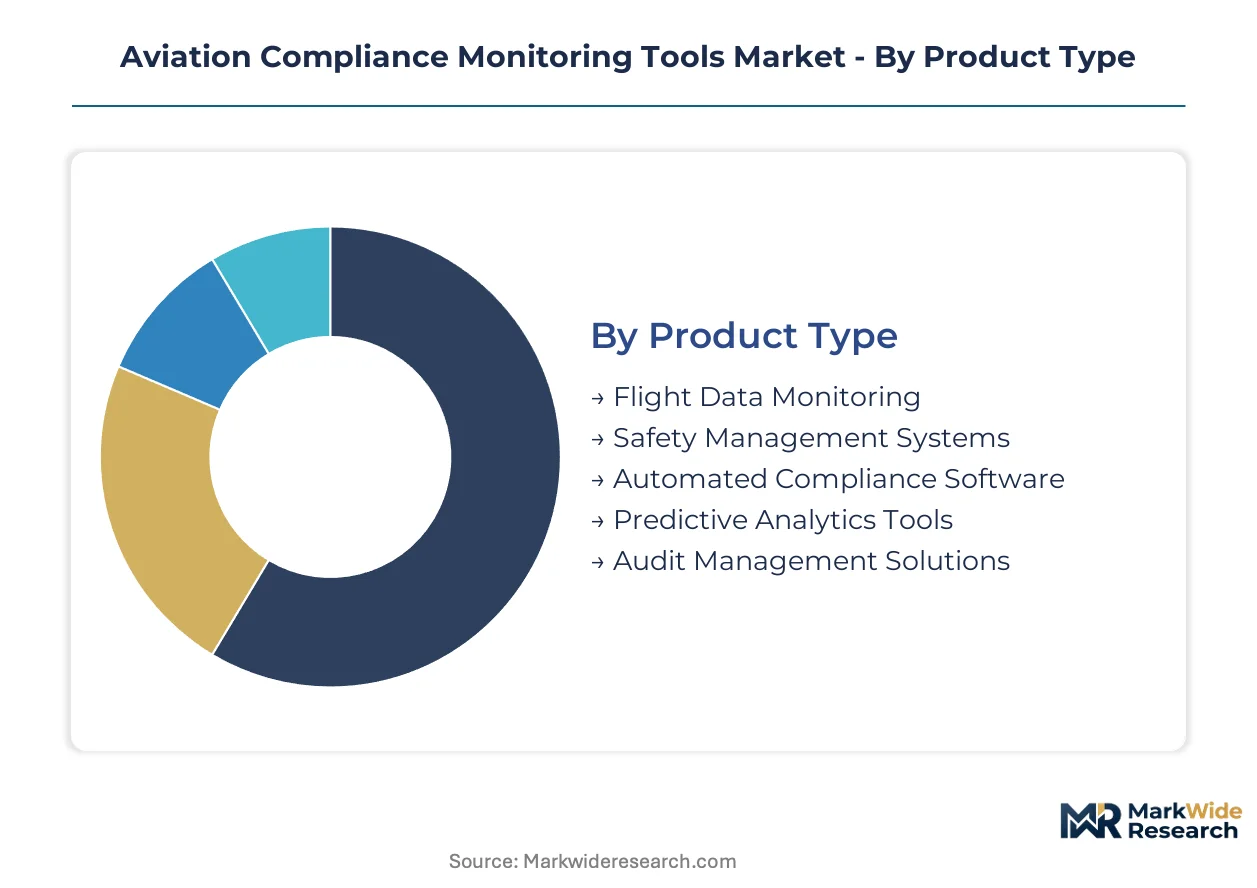
Aviation compliance monitoring tools fragment across four structural dimensions that shape procurement patterns and vendor specialization. Product type determines the core functional architecture, while technology choices dictate deployment economics and integration complexity. Application focus and end user industry together determine feature prioritization and regulatory alignment requirements.
Product Type:
Cost tier separates legacy documentation systems from predictive platforms commanding premium pricing through algorithmic differentiation.
- Safety Management Systems:These platforms automate hazard identification, risk assessment, and mitigation tracking against FAA Part 5 and EASA management system requirements. Commercial airlines in the United States and Germany concentrate procurement here, driven by mandatory compliance deadlines and audit trail standardization needs.
- Predictive Analytics Tools:Machine learning engines process flight recorder telemetry and maintenance histories to forecast operational deviations before regulatory filings become necessary. Demand clusters among long-haul carriers in the United Arab Emirates seeking to minimize ground time through proactive intervention.
- Flight Data Monitoring:Systems capturing and analyzing flight recorder outputs against performance envelopes and procedural compliance.
- Automated Compliance Software:Rule-based engines generating regulatory submissions for multiple jurisdictions without manual transcription.
- Audit Management Solutions:Workflow platforms coordinating internal and external audit schedules with evidence collection and corrective action tracking.
Safety Management Systems command the established base. The steepest expansion runs through Predictive Analytics Tools.
Technology:
Deployment architecture determines capital intensity, with cloud migration reshaping vendor qualification criteria through FedRAMP and sovereign certification requirements.
- Cloud-Based Platforms:Scalable infrastructure delivered via SaaS models eliminates on-premise server procurement and maintenance overhead. Regional carriers and charter operators in North America adopt these fastest, prioritizing operational flexibility over capital preservation.
- Artificial Intelligence:Neural networks and machine learning models enable predictive capabilities across anomaly detection, risk scoring, and automated evidence classification. European operators preparing for EASA AI Act implementation drive roadmap demands for explainable algorithm documentation.
- On-Premise Systems:Locally hosted infrastructure maintained for air-gapped security or legacy integration requirements.
- Data Visualization:Dashboard and reporting layers translating compliance metrics into executive and regulatory-facing formats.
- Mobile Integration:Native applications enabling field personnel to capture audit evidence and access compliance status during remote operations.
On-Premise Systems retain share in defense-adjacent installations. Cloud-Based Platforms are climbing the fastest as procurement shifts to operational expenditure models.
Application:
Functional use case determines data source integration requirements and user workflow design, with regulatory reporting commanding the most standardized feature sets.
- Regulatory Reporting:Automated generation and submission of mandated documentation to civil aviation authorities including FAA, EASA, and GCAA. Full-service carriers operating across multiple jurisdictions prioritize these capabilities to reconcile conflicting filing formats and retention periods.
- Risk Assessment:Quantitative and qualitative evaluation of operational hazards with prioritization matrices linking probability to severity outcomes.
- Incident Investigation:Structured workflows for root cause analysis, corrective action assignment, and closure verification against regulatory timelines.
- Pilot Performance Tracking:Individual and fleet-level monitoring of flight parameter adherence, training currency, and duty time compliance.
- Maintenance Scheduling:Integration of airworthiness directive tracking with component life limits and labor resource planning.
Regulatory Reporting anchors procurement budgets. Risk Assessment is gaining share fastest as predictive methodologies displace retrospective audit cycles.
End User Industry:
Customer type shapes pricing tolerance, implementation complexity, and feature depth, with commercial airlines demanding the most comprehensive multi-jurisdiction coverage.
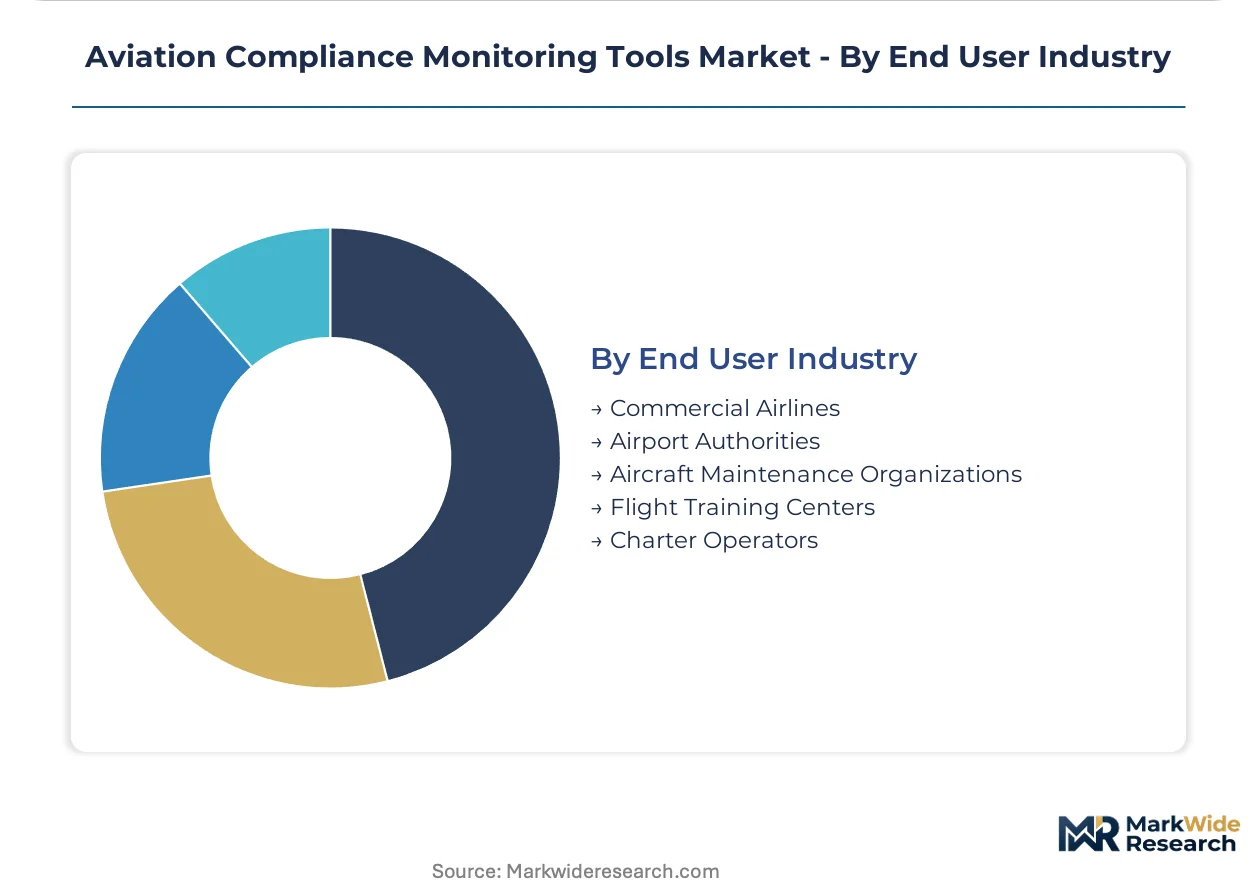
- Commercial Airlines:Full-service and low-cost carriers operating scheduled passenger services with fleet-wide compliance mandates. United States and European network carriers drive platform consolidation around integrated SMS and predictive analytics suites.
- Aircraft Maintenance Organizations:EASA Part 145 and FAA Part 145 approved facilities requiring dual-jurisdiction audit management and component traceability documentation.
- Airport Authorities:Ground handling safety and airside operations compliance with local regulatory variations and airline service level agreements.
- Flight Training Centers:Curriculum compliance, instructor qualification tracking, and student progress documentation against civil aviation authority syllabi.
- Charter Operators:Flexible compliance frameworks accommodating variable fleet composition and ad-hoc operational approvals.
Commercial Airlines represent the revenue concentration. Aircraft Maintenance Organizations are expanding most quickly as MRO consolidation creates multi-site deployment opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States aviation infrastructure, anchored by the Next Generation Air Transportation System (NextGen) modernization program, underwrites North America's central role in compliance technology deployment. FAA mandates drive procurement velocity across commercial carrier networks.
United States
Domestic carriers operate under FAA Part 5 Safety Management System mandates that require automated hazard documentation platforms. The NextGen program's data infrastructure enables real-time telemetry ingestion from flight recorders. Dallas-Fort Worth and Atlanta hubs concentrate procurement decisions for network carriers consolidating compliance suites.
Germany
Lufthansa Group and maintenance organizations anchor European demand for EASA-aligned management systems. Regulation 965/2012 shapes product standards across commercial airlines and MRO facilities. Frankfurt and Munich airport clusters host EASA Part 145 approved facilities pursuing dual-jurisdiction tool standardization.
United Arab Emirates
Dubai and Abu Dhabi-based carriers expanding long-haul networks drive GCAA enforcement of management system requirements. Emirates and Etihad procurement teams prioritize predictive analytics for ground-time minimization. Dubai South's aviation district concentrates software vendor qualification activity.
Saudi Arabia
Vision 2030 airport privatization and new airline launches create greenfield deployment opportunities without legacy migration burdens. The General Authority of Civil Aviation (GACA) aligns with international safety standards while building domestic regulatory capacity. Riyadh and Jeddah aviation clusters host new entrants procuring cloud-native compliance infrastructure.
United Kingdom
Post-Brexit regulatory divergence creates demand for tools reconciling UK CAA requirements with retained EASA standards. British Airways and low-cost carriers drive platform consolidation around integrated SMS capabilities. London Heathrow and Gatwick operational centers anchor procurement for transatlantic route compliance.
Aviation Compliance Monitoring Tools Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying audit modules and data ingestion layers. The vendor base separates between vertical aviation specialists and horizontal GRC platforms extending into the sector. Three archetypes dominate: mobile-first field tools, predictive analytics engines, and audit workflow specialists. Consolidation pressure intensifies as airlines demand unified platforms over point solutions, while API-first architectures enable embedded deployment bypassing standalone procurement cycles.
Within the mobile-first tier, SafetyCulture exemplifies field-engagement architecture for flight training centers and charter operators. Ramp Ready occupies a position among audit specialists tailoring solutions to FAA and EASA protocols. Drata sits within the horizontal-extender archetype, bridging generic GRC infrastructure with aviation-specific control frameworks. These three anchors illustrate how competitive positioning fragments across deployment models rather than consolidating around unified feature sets.
| Leading Market Players |
|---|
| Ramp Ready |
| Tactical Decisions |
| SafetyCulture |
| Drata |
| Scrut |
| Shift5 |
| SAFVR |
| Sprinto |
| Osprey Flight Solutions |
| Others |
Pricing and Supply Chain Analysis
Frankfurt-Dubai air freight corridors transmit specialized aviation-grade server hardware from German manufacturing clusters to UAE data centers, with transport cost volatility feeding directly into subscription pricing tiers and compressing margins for cloud-native compliance vendors serving Middle Eastern carriers.
Pricing Analysis
Volume-discount tiering structures dominate SaaS procurement, with three-tier pricing separating FedRAMP-authorized enterprise suites from standard cloud configurations and economy-tier audit modules. Certification grade and integration complexity drive price differentiation, with EASA Part 5 pre-validated platforms commanding substantial premiums. Pricing pressure stems from charter operators and flight training centers bypassing traditional integrators for direct marketplace procurement. Regional carriers exhibit highest price sensitivity, while network carriers prioritize compliance coverage breadth over unit economics.
Supply Chain Analysis
Upstream feedstock for aviation compliance infrastructure draws from semiconductor fabrication in Taiwan, specialized server assembly in Germany, and sovereign cloud data center construction in the United Arab Emirates. Critical dependencies include aviation-grade encryption modules, real-time telemetry processing chips, and FedRAMP-authorized hosting infrastructure. Single-source vulnerability concentrates in Taiwan's advanced node production for edge computing components. Distribution runs through aviation-specific systems integrators, though direct-to-operator channels are compressing this layer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation compliance monitoring tools constitute a high-growth disruption as EASA's AI Act implementation forces algorithmic transparency investments that reshape vendor qualification criteria across European operator procurement.
For Market Incumbents: Pre-empt horizontal GRC platform encroachment by deepening aviation-specific control framework investments and accelerating FedRAMP-authorized sovereign cloud certifications. Acquire specialized audit workflow providers to consolidate around unified platforms before API-first architectures enable embedded deployment bypassing standalone procurement. For New Entrants and Emerging Players: Saudi Arabian greenfield airline launches and Vision 2030 airport privatization represent the most penetrable entry point, with maintenance organization convergence for dual-jurisdiction EASA-FAA operations offering secondary white-space. API-first architecture partnerships with airline ERP providers enable channel bypass without legacy migration burdens. For Investors and Strategic Acquirers: Mobile-first field engagement specialists with validated training center and charter operator customer bases offer the strongest acquisition profile for platform consolidation plays. Long-term viability hinges on predictive analytics algorithm development capabilities and explainable AI documentation readiness. Monitor EASA cybersecurity annex enforcement timelines as inflection signals for vendor recertification cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Investment | Sovereign cloud certification unlocks U.S. defense-adjacent carrier procurement and compresses competitor qualification timelines. |
| Explainable AI Roadmap Development | EASA AI Act compliance documentation becomes mandatory vendor selection criterion across European commercial airline RFPs. |
| API-First Architecture Deployment | Embedded ERP integration bypasses standalone software procurement cycles and captures operational expenditure budget shifts. |
| Dual-Jurisdiction Control Framework | Pre-validated EASA-FAA compliance coverage addresses MRO consolidation demand for unified multi-site audit management. |
| Edge Computing Node Virtualization | Airborne pre-flight compliance processing captures regional carrier outsourcing demand from thin IT departments. |
Research Methodology
A spread of perspectives from airline safety directors, aviation software procurement officers, EASA Part 145 audit managers, and cloud infrastructure architects converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FAA regulatory filings, EASA management system guidance documents, GCAA enforcement notices, and carrier annual sustainability disclosures. Bottom-up segment sizing triangulated against top-down market construction across deployment models, regulatory jurisdictions, and end-user industry categories.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation modeled across product type, technology architecture, application function, and end-user industry. CAGRs derived from historical penetration rates adjusted for regulatory mandate enforcement timelines and cloud migration adoption curves. Forecast inputs incorporated NextGen data infrastructure rollout pace and EASA AI Act implementation preparation activity among European operators.
Practitioners should monitor cybersecurity annex enforcement acceleration and sovereign cloud certification backlog durations for early signals of vendor pool constriction. Forecasts reflect assumptions about regulatory harmonization persistence and airline capital expenditure recovery trajectories. Cross-checking against FAA Safety Management System implementation compliance audits and EASA management system oversight reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Commercial Aviation Crew Management Systems Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Aircraft Health Monitoring System (AHMS) Market
Aircraft Data and Diagnostics
Flight Line Testing Equipment Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Aerospace and Defense Telemetry Market
Aircraft Data and Diagnostics
Aerospace Data Recorder Market
Aircraft Data and Diagnostics
Global Connected Aircraft Solutions Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market