
 Flight Line Testing Equipment Market | 2026-2036
Flight Line Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Flight Line Testing Equipment Market Foresight
Buyer concentration among defense contractors and major airline maintenance groups is hardening as procurement shifts toward multi-year integrated logistics contracts. BAE Systems leverages its sovereign UK defense relationships to anchor flight line test programs across Royal Air Force bases. L3Harris competes through technology leadership in automated test systems for fifth-generation fighter platforms. Marvin Test Solutions specializes in compact, ruggedized analyzers that sustain margins in deployed military environments.
Flight line testing equipment comprises portable and fixed diagnostic instruments used to verify aircraft system integrity, electrical continuity, avionics functionality, and environmental parameter compliance without removing components to central depots. These systems typically operate across temperature ranges from -40°C to +55°C and must meet MIL-STD-810 shock and vibration specifications to function on active tarmacs. Avionics analyzers and automated test systems capture the most concentrated investment as fleets digitize, while communication testers face margin compression from software-defined radio obsolescence cycles. Portable analyzers occupy the fastest-expanding technology tier as line maintenance teams prioritize reduced aircraft on ground time.
The FAA mandates periodic airworthiness verification through specific test protocols that shape equipment specification requirements for US-registered operators, while the EASA framework in Europe imposes comparable standards through its Part-145 maintenance organization regulations. The US Department of Defense imposes additional MIL-STD and NAVAIR testing specifications that filter through to defense contractor procurement. Stakeholders must monitor how emerging sustainable aviation fuel compatibility testing and next-generation avionics bus architectures reshape equipment refresh cycles and certification burdens.
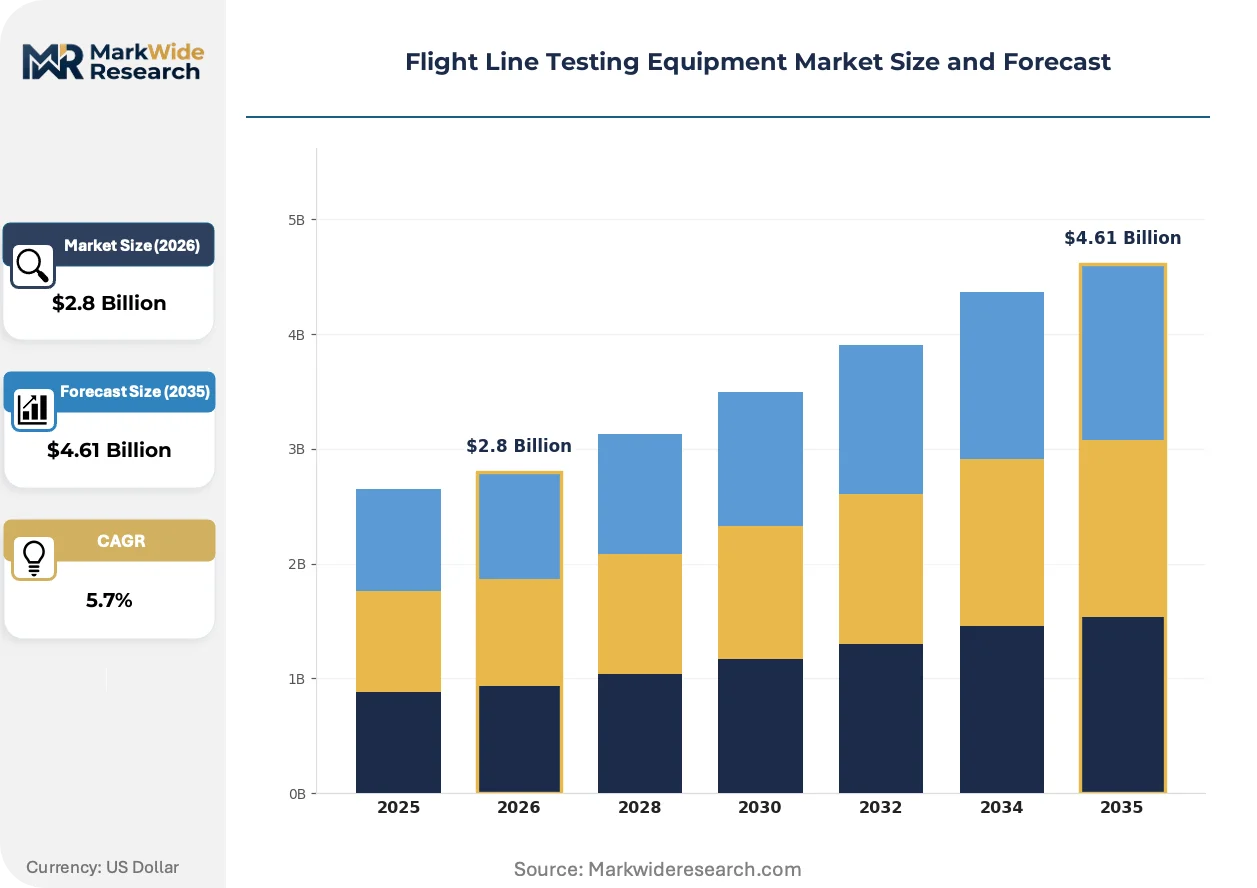
Market Dynamics
Defense sustainment budgets and commercial fleet age profiles are tightening the link between test equipment refresh cycles and regulatory compliance windows, compressing replacement timelines from five-year horizons to three-year procurement programs.
Growth Catalysts
- FAA Airworthiness Directives:Aging commercial fleet mandates are accelerating hardware replacement schedules for US-registered operators, forcing line maintenance stations to upgrade diagnostic capabilities ahead of compliance deadlines.
- NATO Defense Procurement:Allied air forces are standardizing portable diagnostic suites across forward operating bases, creating pooled demand for ruggedized test systems that operate across shared technical specifications.
- Avionics Bus Modernization:MIL-STD-1553 to Ethernet backbone transitions in military platforms are rendering legacy interface testers obsolete, opening replacement demand for fiber-optic capable analyzers.
Market Restraints
- Semiconductor Supply Concentration:FPGA and high-speed ADC components rely on concentrated East Asian foundry capacity, exposing lead times to geopolitical disruption and export control volatility.
- Calibration Infrastructure Scarcity:Precision RF and microwave reference standards require specialized metrology labs that cluster in Germany, the United Kingdom, and the United States, limiting field deployment flexibility.
- Software-Defined Radio Obsolescence:Rapid protocol evolution in tactical communications is shortening functional lifespans of dedicated comms testers before hardware depreciation completes.
Strategic Opportunities
- Sustainable Aviation Fuel Compatibility Testing:Emerging seal material and fuel system verification protocols for SAF blends create demand for new chemical exposure and permeation test modules.
- India Defense Modernization:Indigenization mandates under the country's procurement rules are opening partnership pathways for foreign test equipment vendors to establish local assembly and calibration facilities.
- Edge Computing Convergence:On-tarmac AI inference engines for predictive maintenance are integrating with traditional test hardware, creating hybrid diagnostic platforms that compress fault isolation timelines.
Industry Challenges
- Systems Engineering Talent Shortage:Flight line test equipment development requires rare combinations of RF engineering, embedded software, and aerospace domain expertise that compete with commercial 5G and automotive radar programs.
- Multi-Domain Certification Burden:Products must simultaneously satisfy FAA Part 145, EASA Part-145, and MIL-STD-810 qualification tracks, tripling documentation and test matrix requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flight Line Testing Equipment Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrical Testers, Avionics Analyzers, Cable Assemblers, Hydraulic Test Kits, Communication Testers, Environmental Sensors Technology: Wireless Diagnostics, Automated Test Systems, Portable Analyzers, Remote Monitoring, Digital Signal Processing, Real-Time Data Acquisition Application: Routine Maintenance, Troubleshooting, System Calibration, Pre-flight Inspections, Post-flight Assessments, Component Validation End User: Airlines, Defense Contractors, Aerospace Suppliers, Ground Support Providers, Maintenance Repair Organizations, Flight Schools |
| Companies Covered | BAE Systems, CAST Navigation, VIAVI Solutions, Aeroflex, SPHEREA Group, Textron Systems, Frontier Electronic Systems Corp., L3Harris, Marvin Test Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flight Line Testing Equipment Market Shifts & Advancements
Digital thread architectures are collapsing the boundary between factory acceptance testing and operational flight line diagnostics, enabling continuous configuration traceability from production through depot maintenance cycles.
Modular synthetic instrument architectures are integrating software-defined measurement engines with reconfigurable RF front ends. Fifth-generation fighter sustainment programs are adopting these platforms at accelerated procurement tempos. This convergence is integrating multiple legacy single-purpose boxes into consolidated test sets that reduce aircraft on ground intervals and spare part inventories.
EASA Part-145 maintenance organization regulations are tightening documentation requirements for digital test record retention and audit trail integrity. European MRO providers are retrofitting legacy equipment with secure data logging modules to satisfy these mandates. Avionics analyzer segments face the steepest compliance burden as bus traffic capture and cryptographic signature verification become mandatory for release-to-service documentation.
Airline maintenance groups are consolidating vendor relationships around multi-year integrated logistics support contracts that bundle equipment, calibration services, and technical training. Regional carriers and independent MRO facilities are responding by forming cooperative purchasing consortia to match the volume leverage of major fleet operators. This concentration is most visible in the United States, where domestic airline groups have established preferred supplier frameworks that exclude smaller equipment vendors from line maintenance station procurement.
Flight Line Testing Equipment Market Segmentation
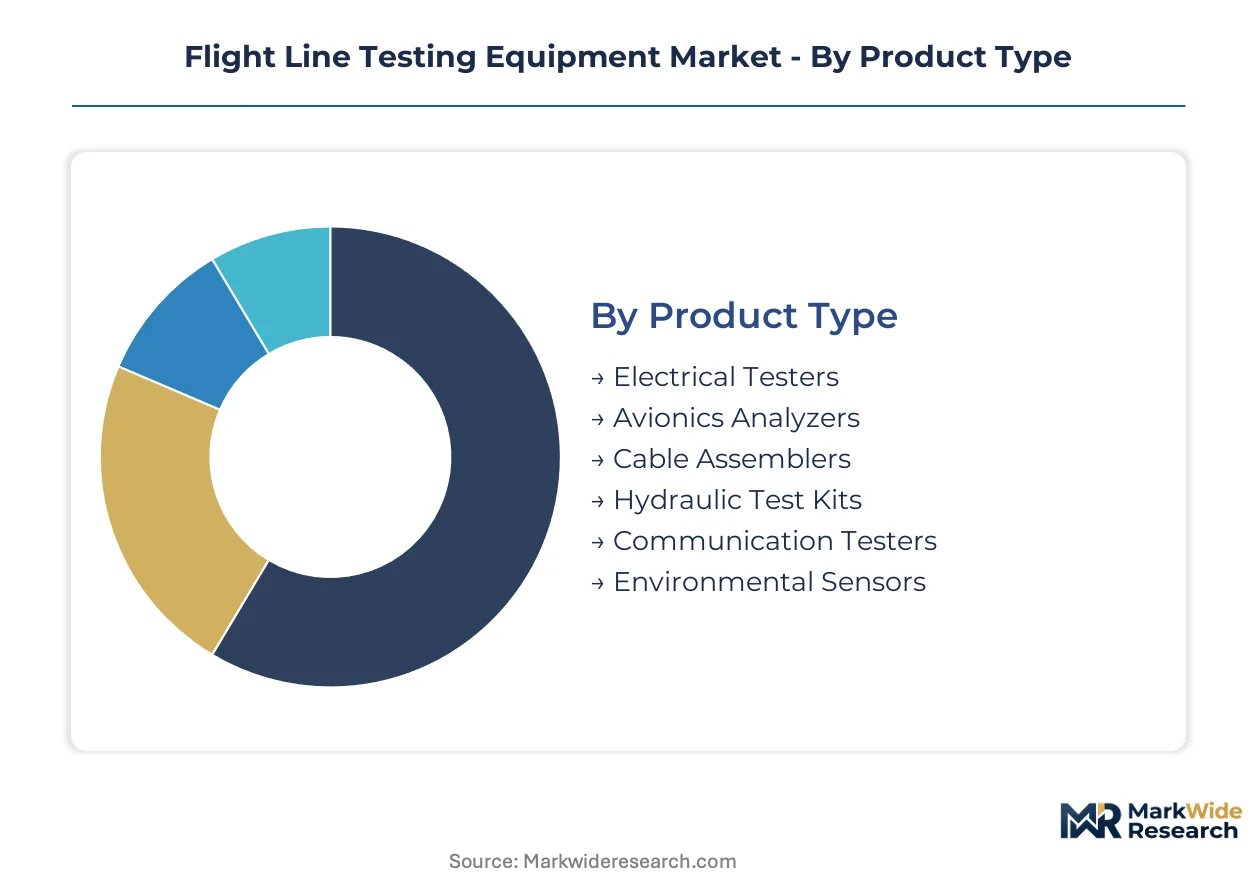
Flight line testing equipment segmentation reveals how capital deployment, technical complexity, and regulatory compliance intersect across procurement decisions. Equipment buyers prioritize segments that compress aircraft on ground intervals while satisfying multi-domain certification requirements.
Product Type:
Capital intensity varies sharply across product categories, with avionics analyzers and automated electrical test platforms demanding the highest upfront investment in precision RF components and calibration infrastructure.
- Avionics Analyzers:These systems verify MIL-STD-1553 and Ethernet backbone integrity across navigation, communication, and flight control buses. Demand concentrates in United States defense sustainment depots where fifth-generation fighter programs require fiber-optic capable diagnostic suites. FAA airworthiness directives on aging commercial fleets are accelerating replacement schedules for legacy interface testers.
- Electrical Testers:Portable continuity and insulation resistance instruments operate across -40°C to +55°C ranges per MIL-STD-810 specifications. European MRO providers under EASA Part-145 regulations are retrofitting units with secure data logging modules to satisfy audit trail mandates. NATO-aligned air forces are standardizing these units across forward operating bases.
- Cable Assemblers:Specialized harness verification tools for military and commercial aircraft.
- Hydraulic Test Kits:Pressure and flow validation equipment for flight control actuation systems.
- Communication Testers:Tactical radio and transponder verification instruments facing functional compression from software-defined radio evolution.
- Environmental Sensors:Temperature, vibration, and contamination monitoring devices for tarmac deployment.
Avionics analyzers absorb the bulk of installed capacity; portable electrical testers are expanding most quickly as line maintenance teams prioritize reduced aircraft on ground time.
Technology:
Technology segmentation tracks the shift from dedicated single-purpose instruments toward reconfigurable software-defined platforms that consolidate multiple measurement functions.
- Automated Test Systems:Synthetic instrument architectures integrate software-defined measurement engines with modular RF front ends. These platforms collapse multiple legacy boxes into consolidated test sets, reducing spare part inventories and maintenance training burdens. United States defense contractors are adopting these systems at accelerated procurement tempos for F-35 and next-generation bomber sustainment.
- Portable Analyzers:Compact, battery-powered diagnostic units weighing under 15 kilograms enable point-of-fault testing without component removal. Regional airlines and independent MRO facilities in the United States are forming cooperative purchasing consortia to acquire these units, matching volume leverage of major fleet operators. Marvin Test Solutions and comparable vendors specialize in ruggedized variants for deployed military environments.
- Wireless Diagnostics:Bluetooth and Wi-Fi enabled sensors for cable-free data transmission.
- Remote Monitoring:Cloud-connected diagnostic platforms enabling centralized fleet health oversight.
- Digital Signal Processing:FPGA-based measurement engines for high-speed avionics bus analysis.
- Real-Time Data Acquisition:Continuous monitoring systems for flight-critical parameter logging.
Automated test systems command the highest average selling prices; portable analyzers are climbing the fastest as distributed maintenance models displace centralized depot diagnostics.
Application:
Application segmentation reflects how maintenance organizations allocate diagnostic resources across scheduled versus unscheduled work scopes.
- Troubleshooting:Fault isolation procedures demand the most technically sophisticated equipment combinations, including protocol analyzers, spectrum monitors, and environmental stress simulators. United States-based airline maintenance groups are consolidating vendor relationships around multi-year integrated logistics contracts that bundle troubleshooting equipment with technical training and calibration services.
- Routine Maintenance:Periodic inspection protocols per FAA and EASA intervals require standardized test sequences with documented traceability. European MRO providers face tightening documentation requirements under EASA Part-145 for digital test record retention, driving retrofit demand for legacy equipment with secure logging modules.
- System Calibration:Precision alignment of flight instruments and sensors against certified reference standards.
- Pre-flight Inspections:Rapid verification checks performed immediately before aircraft release to service.
- Post-flight Assessments:Deferred maintenance item identification and mission data extraction.
- Component Validation:Shop-level testing of removed units prior to return to service.
Troubleshooting applications consume the most equipment hours per maintenance event; routine maintenance generates the steepest expansion trajectory as fleet age profiles compress inspection intervals.
End User:
End user segmentation captures divergent procurement patterns between consolidated fleet operators and fragmented service providers.
- Defense Contractors:Prime sustainment organizations including BAE Systems and L3Harris anchor flight line test programs through sovereign defense relationships and technology leadership in automated systems. These buyers impose MIL-STD and NAVAIR testing specifications that filter through to equipment vendor qualification requirements. India defense modernization is opening partnership pathways for foreign vendors to establish local assembly under indigenization mandates.
- Airlines:Major United States carrier groups have established preferred supplier frameworks that exclude smaller equipment vendors from line maintenance station procurement. These organizations prioritize multi-year integrated logistics support contracts bundling equipment, calibration, and training.
- Maintenance Repair Organizations:Independent and airline-affiliated MRO facilities serving third-party customers.
- Aerospace Suppliers:Tier 1 and Tier 2 manufacturers performing factory acceptance testing and warranty support.
- Ground Support Providers:Fixed-base operators and airport service companies handling transient aircraft.
- Flight Schools:Training organizations with limited budgets and simplified maintenance requirements.
Defense contractors and major airline groups concentrate procurement volume; MRO providers are gaining share fastest as outsourcing trends expand third-party maintenance scope.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense sustainment budgets and commercial MRO capacity concentrate procurement in the United States, while European regulatory tightening and Asian defense modernization reshape geographic demand patterns.
United States
Pentagon maintenance depots and domestic airline groups anchor global demand for portable diagnostic suites. The FAA's updated airworthiness directive framework accelerates replacement cycles for legacy test hardware at line maintenance stations. Dallas-Fort Worth and Seattle-Tacoma clusters concentrate MRO investment as major carriers consolidate vendor relationships around multi-year integrated logistics contracts.
United Kingdom
Royal Air Force base modernization programs sustain demand for ruggedized analyzers operating across NATO shared technical specifications. BAE Systems leverages sovereign defense relationships to anchor flight line test programs. The Bristol and BAE Systems' Warton facilities cluster defense electronics engineering talent for synthetic instrument development.
Germany
Luftwaffe procurement through NATO standardization frameworks creates pooled demand for fiber-optic capable diagnostic equipment. EASA Part-145 documentation requirements for digital test record retention drive retrofit investment at independent MRO facilities. Hamburg and Munich maintenance hubs concentrate calibration infrastructure for precision RF reference standards.
France
Dassault Aviation sustainment networks and Armée de l'Air procurement sustain demand for automated test systems on Rafale and future combat aircraft programs. EASA tightening of audit trail integrity mandates shapes equipment specification at Orly and Charles de Gaulle maintenance bases. The Toulouse aerospace cluster integrates flight line diagnostics into factory-to-field digital thread architectures.
India
Indigenization mandates under defense procurement rules open partnership pathways for foreign test equipment vendors establishing local assembly facilities. Hindustan Aeronautics Limited and private sector offsets drive demand for MIL-STD qualified portable analyzers. Bangalore and Hyderabad defense electronics corridors concentrate calibration infrastructure development under technology transfer agreements.
Flight Line Testing Equipment Market Competitive Landscape
United States producers anchor the high-capability tier; European specialists hold sovereign defense relationships. Market structure consolidates around multi-year integrated logistics contracts that bundle equipment, calibration services, and technical training. Three archetypes dominate: defense primes with sustainment depot relationships, automated test system specialists with fifth-generation fighter platform credentials, and compact analyzer vendors focused on deployed military margins. Competitive moves center on geographic expansion through local assembly partnerships and technology licensing for synthetic instrument architectures.
Among defense prime contractors, BAE Systems and L3Harris occupy positions reflecting contrasting geographic anchoring and technology specialization. BAE Systems exemplifies the sovereign relationship archetype through UK-based defense electronics integration. L3Harris represents the automated systems leadership tier with positioning on US fighter sustainment programs. Marvin Test Solutions sits within the compact ruggedized specialist segment, serving deployed military environments where portability and shock tolerance command premium positioning.
| Leading Market Players |
|---|
| BAE Systems |
| CAST Navigation |
| VIAVI Solutions |
| Aeroflex |
| SPHEREA Group |
| Textron Systems |
| Frontier Electronic Systems Corp. |
| L3Harris |
| Marvin Test Solutions |
| Others |
Supply & Pricing Matrix
FPGA and high-speed ADC component indices from East Asian foundries cascade through three pricing tiers in flight line testing equipment, compressing margins on standard-grade portable analyzers while premium automated test systems retain pricing power through calibration infrastructure scarcity.
Pricing Analysis
High-volume portable electrical testers compete on thin margins as regional airline consortia consolidate procurement, while low-volume automated test systems for fifth-generation fighter sustainment command premium positioning through MIL-STD certification bundling. Price differentiation rests on FCC/FAA certification grade and after-sales calibration service integration. Cost compression in the mid-tier portable segment is intensifying because semiconductor supply concentration extends component lead times. Independent MRO facilities exhibit the highest price sensitivity; Pentagon maintenance depots demonstrate the least due to sovereign defense procurement protocols.
Supply Chain Analysis
Freight costs for precision RF and microwave reference standards concentrate supply chain risk around specialized metrology labs in Germany, the United Kingdom, and the United States. Manufacturing draws from Taiwan and South Korea for FPGA components, Japan for high-reliability connectors, and domestic US facilities for final assembly and MIL-STD qualification. Single-source vulnerability in East Asian foundry capacity exposes lead times to export control volatility. Distribution runs through defense prime contractor logistics networks and airline group preferred supplier frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flight line testing equipment has become a vertical-integration race where control over calibration infrastructure and semiconductor sourcing determines margin sustainability. Players are pursuing backward integration into precision RF reference standard production to escape metrology lab bottlenecks.
For Market Incumbents: Hedge against software-defined radio obsolescence by accelerating synthetic instrument architecture development and securing long-term FPGA supply agreements with foundries outside export-controlled jurisdictions. Reinforce sovereign defense relationships through local assembly partnerships in India under indigenization mandates. Certification investment in sustainable aviation fuel compatibility modules offers defensive positioning against emerging regulatory test protocols. For New Entrants and Emerging Players: Regional airline maintenance consortia in the United States represent the most penetrable buyer archetype as these organizations seek alternatives to major carrier preferred supplier frameworks. Independent European MRO facilities under EASA Part-145 retrofit mandates present secondary white-space opportunity for secure data logging module integration. A calibration-as-a-service bundling approach bypasses capital-intensive metrology infrastructure requirements. For Investors and Strategic Acquirers: The window for entry favors compact ruggedized analyzer specialists with deployed military credentials and established MIL-STD-810 qualification track records. Long-term viability hinges on positioning within fifth-generation fighter sustainment programs as avionics bus modernization cycles accelerate. Watch for India defense procurement rule amendments on foreign partnership equity limits as the inflection signal for geographic expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Instrument Architecture Development | Consolidates multiple legacy test boxes into single platforms for F-35 sustainment depots. |
| Local Assembly Partnership | Satisfies India's indigenization mandates while accessing HAL procurement channels. |
| Calibration Infrastructure Acquisition | Captures scarce metrology lab capacity in Germany and the United Kingdom. |
| Secure Data Logging Module Integration | Addresses EASA Part-145 digital test record retention mandates for European MRO retrofit demand. |
| SAF Compatibility Test Module Launch | Positions for emerging FAA seal material verification protocols on aging commercial fleets. |
Research Methodology
Defense procurement databases, FAA airworthiness directive filings, and EASA Part-145 maintenance organization records formed the secondary backbone, cross-referenced with primary interviews across Pentagon sustainment depot directors, airline group procurement VPs, independent MRO facility managers, and calibration infrastructure operators. Bottom-up and top-down triangulation validated equipment shipment volumes against defense budget appropriation tracks and commercial fleet age profiles.
Bottom-up modeling aggregated segment-level equipment deployments across avionics analyzers, portable electrical testers, and automated test systems, while top-down analysis calibrated total addressable market boundaries against NATO defense expenditure patterns and US airline MRO capacity expansion. CAGRs derived from regression against fleet modernization timelines, regulatory compliance windows, and semiconductor supply elasticity. Synthetic instrument adoption curves and fiber-optic avionics bus penetration served as industry-specific forecast inputs.
Revisions become necessary when export control expansions disrupt East Asian foundry access, when EASA or FAA mandates accelerate airworthiness directive compliance deadlines, or when India defense procurement rules alter foreign partnership equity thresholds. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Data and Diagnostics
Embedded Structural Health Monitoring Networks for Aircraft Skins Market
Aircraft Data and Diagnostics
Flight Data Recorder (FDR) Market
Aircraft Data and Diagnostics
Aircraft Control Software Market
Aircraft Data and Diagnostics
Commercial Aircraft Health Monitoring Systems Market
Aircraft Data and Diagnostics
Helicopter Aeronautical Software Market
Aircraft Data and Diagnostics
Aviation Compliance Monitoring Tools Market
Aircraft Data and Diagnostics
Air Data Calibrators Market
Aircraft Data and Diagnostics
Aircraft Attitude Indicators Market
Aircraft Data and Diagnostics
Flight Data Monitoring Market
Aircraft Data and Diagnostics
Global Flight Inspection Market
Aircraft Data and Diagnostics
Airplane Machmeter Market
Aircraft Data and Diagnostics
Europe Aircraft Health Monitoring System Market
Aircraft Data and Diagnostics
Automated Composite Structure Inspection Systems for Aerospace Market
Aircraft Data and Diagnostics
Aircraft Flight Recorder Market
Aircraft Data and Diagnostics
Air Data Systems Market
Aircraft Data and Diagnostics
NDT in the Aerospace and Defense Market