
 Commercial Aircraft Manufacturing Market | 2026-2036
Commercial Aircraft Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Aircraft Manufacturing Market Insights
Consolidation among full-service network carriers is repositioning procurement leverage toward mega-fleet agreements. Airbus SE dominates wide-body deliveries through manufacturing scale in Toulouse and Hamburg. Boeing sustains twin-aisle leadership despite supply chain recalibration. COMAC competes on single-aisle cost positioning with the C919 program targeting domestic Chinese operators first.
Commercial aircraft manufacturing encompasses the design, assembly, and certification of fixed-wing aircraft exceeding 19 passenger seats or equivalent cargo capacity, typically involving aluminum-lithium fuselage structures, turbofan propulsion systems generating 20,000–115,000 pounds of thrust, and fly-by-wire flight control architectures. The primary industrial purpose is to produce revenue-generating assets for scheduled air transport operators. Single-aisle aircraft anchor volume demand from low-cost carriers seeking fuel efficiency on sectors under 3,000 nautical miles. Composite materials displace conventional aluminum in wing and fuselage applications to reduce operating empty weight. Wide-body aircraft concentrate margin pools on premium cabin configurations and freighter conversions for express logistics networks.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements govern structural integrity, emissions limits, and noise thresholds for all new type certificates. The EU Green Deal's ReFuelEU Aviation mandate progressively requires sustainable aviation fuel blending at European airports, forcing engine OEMs to redesign combustor systems and fuel injectors. China's CAAC aligns with ICAO carbon offset standards while accelerating indigenous certification timelines for COMAC products. Stakeholders must monitor how bilateral safety agreements between regulators affect market access for emerging manufacturers.
Market Dynamics
Fleet renewal cycles intersect with sustainable aviation fuel mandates to compress development timelines for next-generation propulsion architectures. Manufacturers must reconcile aluminum-lithium fuselage investments against composite material adoption curves while certifying hybrid-electric systems under evolving FAA Part 33 and EASA CS-E engine standards.
Growth Catalysts
- ReFuelEU Aviation Mandate:Progressive SAF blending requirements at European airports force combustor redesigns, creating aftermarket retrofit demand and new engine platform development cycles.
- Southeast Asian LCC Expansion:Low-cost carriers in Indonesia, Vietnam, and the Philippines drive narrow-body orders for sub-3,000 nautical mile sectors with high daily utilization rates.
- Thermoplastic Composites:Automated fiber placement of PEEK and PPS matrices reduces wing assembly hours while improving damage tolerance for next-generation single-aisle programs.
Market Restraints
- Titanium Sponge Concentration:Russian and Chinese suppliers control 70% of aerospace-grade titanium feedstock, exposing airframe manufacturers to export restriction risks and price volatility.
- Single-Source Avionics Dependency:Flight control computer architectures rely on concentrated semiconductor foundry capacity in Taiwan, creating single-point-of-failure exposure for production ramp rates.
- Legacy Alloy Substitution Limits:Fatigue-critical wing splice fittings retain 7075-T6 aluminum specifications due to certification database gaps for additive-manufactured replacements.
Strategic Opportunities
- Indian MRO Infrastructure:Bangalore and Hyderabad maintenance clusters lack wide-body hangar capacity, creating greenfield investment openings for line maintenance and engine overhaul services.
- Urban Air Mobility Convergence:Distributed electric propulsion architectures from eVTOL programs transfer battery thermal management IP to regional turboprop electrification roadmaps.
- Carbon Offset Monetization:ICAO CORSIA compliance creates revenue streams for manufacturers offering verified emission reduction certificates bundled with new aircraft deliveries.
Industry Challenges
- Aerospace Welding Technician Scarcity:Automated riveting and friction stir welding operations require specialized certifications that outpace vocational training pipeline output in Toulouse, Hamburg, and Charleston.
- Type Certificate Amendment Delays:FAA Organization Designation Authorization audits extend software update approvals for fly-by-wire flight control laws, compressing service bulletin implementation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Aircraft Manufacturing Market |
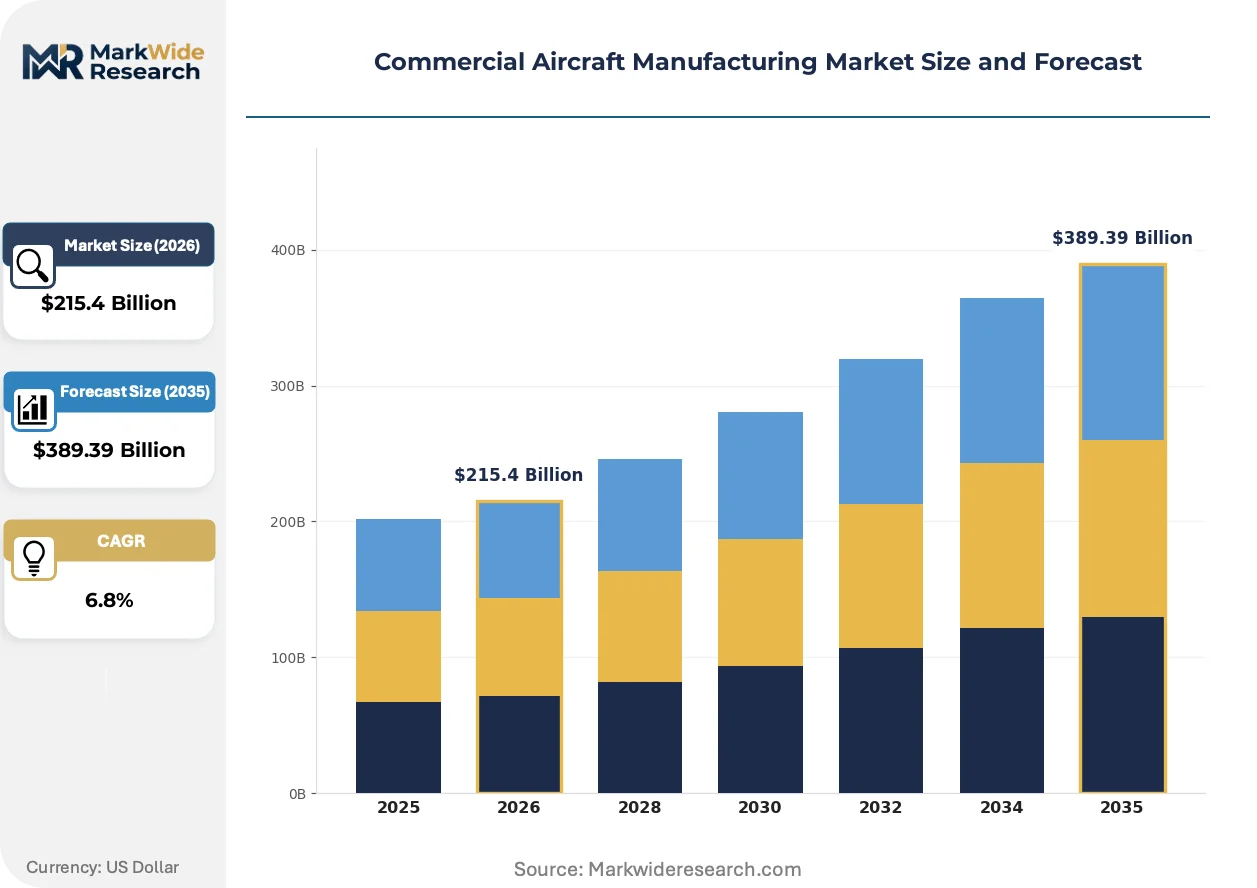
| Market Size in 2026 | $215.4 Billion |
| Market Size in 2035 | $389.39 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Aisle Aircraft, Wide-Body Aircraft, Regional Jets, Business Jets Technology: Composite Materials, Turbofan Engines, Fly-by-Wire Systems, Advanced Avionics Application: Passenger Transport, Cargo Transport, Special Mission Aircraft, Airborne Surveillance End User: Commercial Airlines, Charter Operators, Leasing Companies, Maintenance Organizations |
| Companies Covered | Embraer, Mitsubishi Aircraft Corporation, Airbus SE, Irkut Corporation, Sukhoi Civil Aircraft Company, Boeing, Bombardier, Kawasaki Aerospace Company, COMAC (Commercial Aircraft Corporation of China), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Aircraft Manufacturing Market Trends and Innovations
Propulsion electrification and digital thread manufacturing are collapsing traditional development cycles while forcing new certification frameworks for hybrid architectures. Material science advances compete against supply security priorities in supplier selection criteria.
Digital twin architectures for structural health monitoring are modularizing maintenance planning across long-haul fleets. Singapore Airlines and Lufthansa Technik deploy sensor fusion algorithms that predict fatigue crack initiation in crown skin panels. This capability compresses heavy check intervals from six-year to four-year cycles, altering aftermarket revenue timing for OEM service divisions.
EASA CS-25 Amendment 26 noise stringency and the EU Green Deal's 2050 climate neutrality target are accelerating open-rotor propulsion investment. Engine OEMs redesign nacelle structures to accommodate contra-rotating fan stages with 15% fuel burn improvement potential. Regional operators in Scandinavia and the Baltic states face earliest compliance pressure due to airport curfew regulations in Stockholm, Oslo, and Copenhagen.
Airline technical procurement departments consolidate fleet-type decisions under chief financial officer oversight, displacing traditional chief pilot influence. Mega-fleet agreements with Airbus and Boeing now bundle training, spares provisioning, and predictive analytics subscriptions. This concentration is most visible among Middle Eastern network carriers and US ultra-low-cost operators seeking scale economies across 200-plus unit commitments.
Commercial Aircraft Manufacturing Market Segmentation
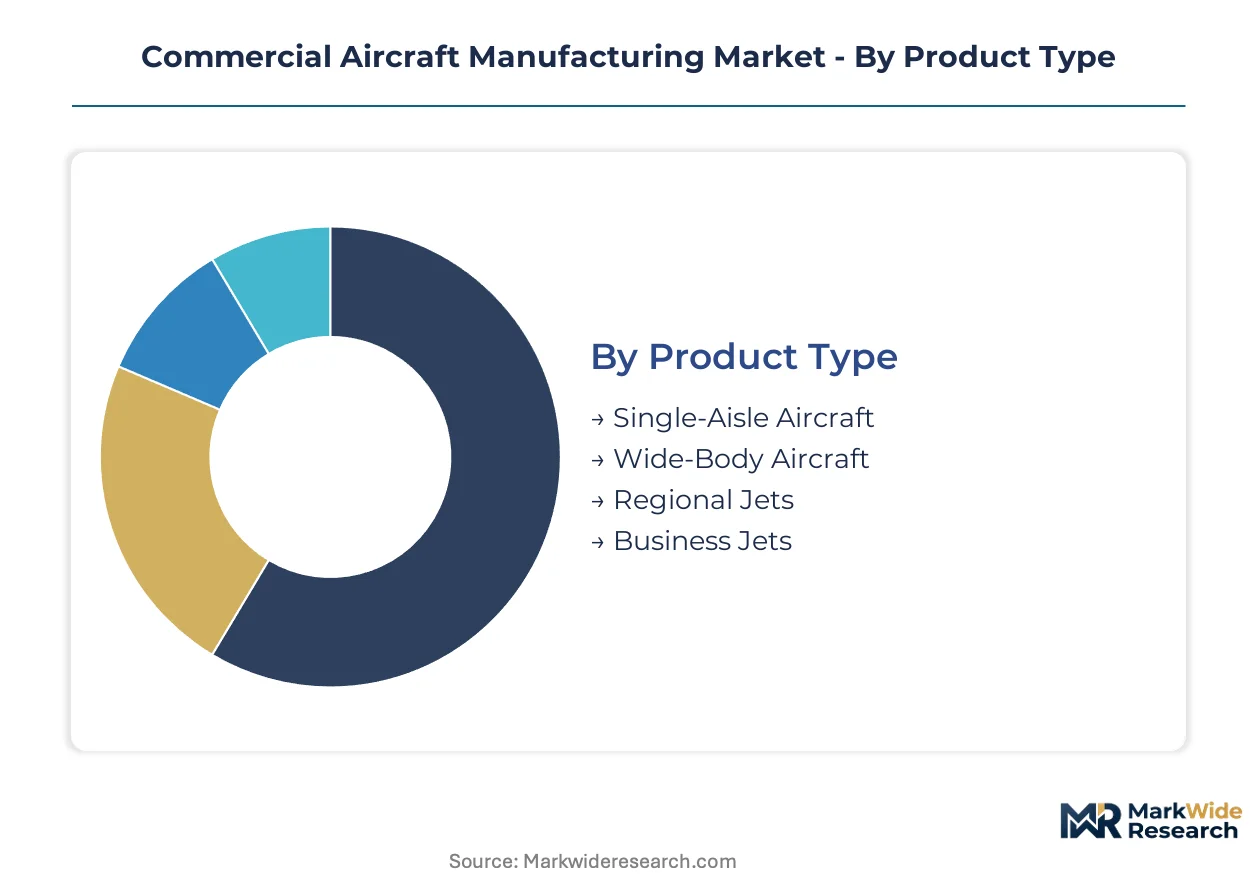
Commercial aircraft manufacturing segments align with distinct procurement economics and certification pathways. Fleet planners match product categories to route structures, while technology choices determine long-term operating cost profiles and residual value trajectories.
Product Type:
Assembly line capacity concentrates in Tianjin, Mobile, and Hamburg for narrow-body programs, while wide-body output remains anchored in Toulouse and Everett.
- Single-Aisle Aircraft:Aluminum-lithium fuselage structures and high-bypass turbofan configurations dominate this category. Low-cost carriers in Indonesia, Vietnam, and the Philippines drive procurement for sub-3,000 nautical mile sectors with daily utilization rates exceeding 12 hours.
- Wide-Body Aircraft:Twin-aisle configurations with composite wing boxes and 115,000-pound thrust engines serve premium long-haul routes. Middle Eastern network carriers concentrate mega-fleet agreements here, bundling training and predictive analytics subscriptions.
- Regional Jets:70-100 seat turbofan aircraft bridge thin routes between secondary cities.
- Business Jets:Customized cabin architectures and transcontinental range specifications serve corporate flight departments.
Single-Aisle Aircraft absorbs the bulk of installed capacity; Wide-Body Aircraft is expanding most quickly in absolute delivery value.
Technology:
Material substitution decisions and propulsion architectures determine competitive positioning across OEM portfolios.
- Composite Materials:Automated fiber placement of carbon fiber reinforced polymers reduces wing assembly hours while improving damage tolerance. Thermoplastic PEEK and PPS matrices are displacing thermoset prepregs in next-generation single-aisle programs.
- Turbofan Engines:Geared turbofan architectures with 12:1 bypass ratios deliver 15% fuel burn improvement over legacy powerplants. EASA CS-E and FAA Part 33 certification standards govern combustor redesigns for sustainable aviation fuel compatibility.
- Fly-by-Wire Systems:Digital flight control laws with triple-redundant architectures replace mechanical linkages.
- Advanced Avionics:Integrated modular avionics suites consolidate display and communication functions.
Composite Materials command the steepest expansion trajectory as weight reduction targets intensify; Turbofan Engines retain the largest installed base across active fleets.
Application:
End-use requirements shape airframe specifications, from pressurization cycles to cargo door configurations.
- Passenger Transport:Revenue-generating configurations range from 180-seat single-aisle density to four-class wide-body layouts exceeding 350 seats. Low-cost carrier procurement concentrates on quick-turnaround galleys and slimline seating.
- Cargo Transport:Dedicated freighter conversions and factory-built cargo variants serve express logistics networks. Wide-body converted freighters command premium lease rates on trans-Pacific routes.
- Special Mission Aircraft:Modified airframes accommodate maritime patrol, aerial refueling, or medical evacuation roles.
- Airborne Surveillance:Sensor-integrated platforms support border monitoring and environmental monitoring missions.
Passenger Transport absorbs the bulk of installed capacity; Cargo Transport is climbing the fastest as e-commerce fulfillment reshapes air freight demand.
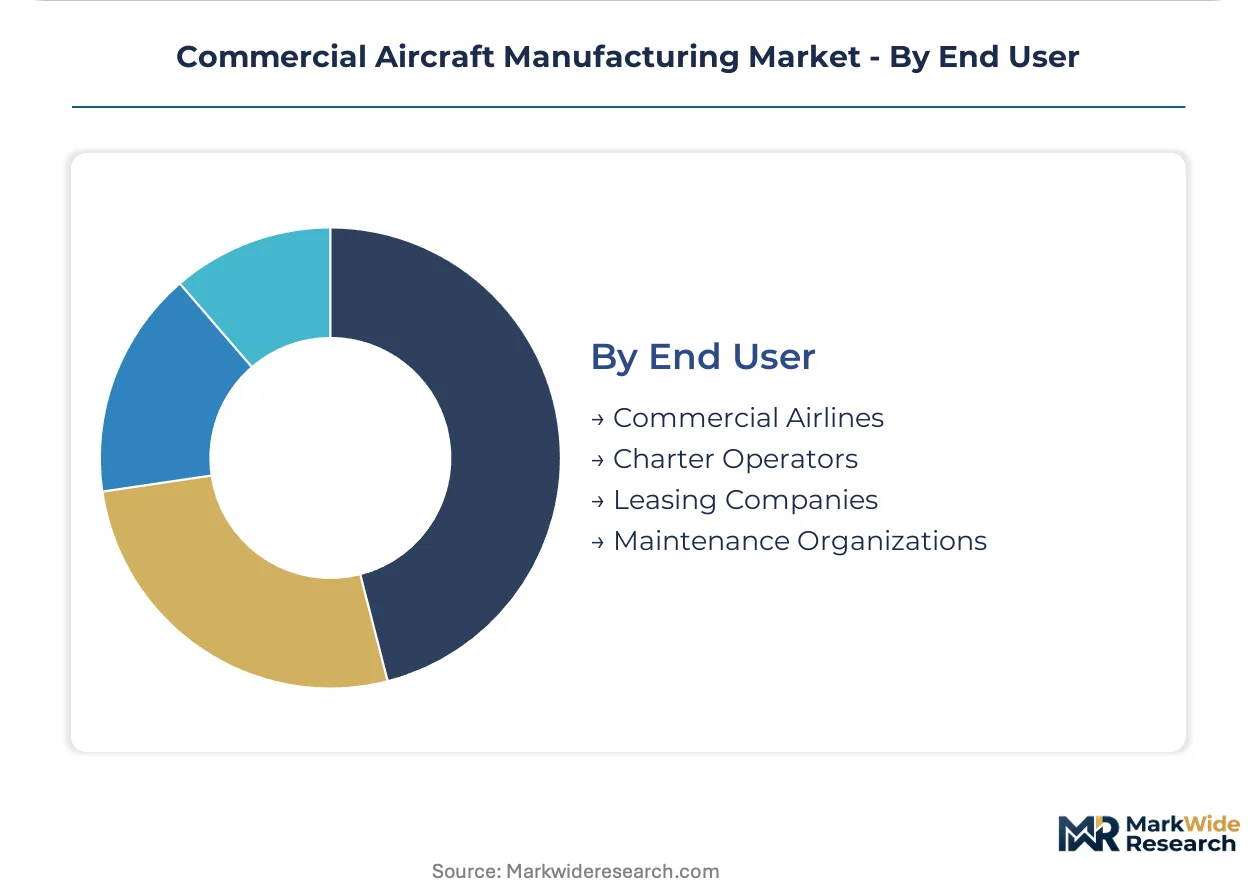
End User:
Procurement authority consolidation is redefining contract structures and aftermarket service bundling.
- Commercial Airlines:Full-service network carriers and low-cost operators account for the majority of OEM backlog. CFO-led procurement teams now displace traditional chief pilot influence in fleet-type decisions.
- Leasing Companies:Aircraft lessors concentrate speculative orders to secure early delivery slots, then place assets with credit-constrained operators. Residual value guarantees and maintenance reserve structures define contract economics.
- Charter Operators:Ad-hoc and on-demand service providers acquire mid-life assets for seasonal capacity.
- Maintenance Organizations:Third-party MRO providers influence spare parts procurement and component repair strategy.
Commercial Airlines absorb the bulk of installed capacity; Leasing Companies is gaining share fastest as balance-sheet financing displaces direct airline purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium sponge deposits in Russia and China anchor aerospace-grade feedstock security for airframe manufacturers. Assembly line output concentrates in Toulouse, Hamburg, and Everett, while emerging production nodes reshape supplier geography across three continents.
United States
Low-cost carriers in the Southwest and Southeast drive narrow-body fleet renewal for high-utilization domestic networks. FAA Part 25 certification standards govern structural integrity and emissions thresholds for all new type certificates. Final assembly lines in Everett, Washington and Charleston, South Carolina concentrate wide-body and single-aisle output respectively.
France
Full-service network carriers from the Middle East anchor mega-fleet procurement negotiations for premium cabin configurations. EASA CS-25 certification requirements align with EU Green Deal mandates for sustainable aviation fuel compatibility. Toulouse hosts the dominant wide-body assembly complex, while Saint-Nazaire specializes in fuselage section fabrication.
China
Domestic airline operators prioritize indigenous single-aisle procurement under fleet standardization programs. CAAC accelerates certification timelines for COMAC products while aligning with ICAO carbon offset standards. Tianjin's final assembly line concentrates A320-family output for Asia-Pacific delivery schedules.
Germany
ReFuelEU Aviation mandates force combustor redesigns for European operator compliance by progressive SAF blending deadlines. EASA noise stringency amendments drive open-rotor propulsion investment from engine OEMs. Hamburg anchors A320-family final assembly alongside premium cabin completion centers for wide-body programs.
Japan
Composite materials suppliers and tier-one aerostructures fabricators support Boeing and Airbus subcontracting networks. METI industrial policy prioritizes aerospace supply chain resilience through domestic content requirements. Nagoya's manufacturing cluster concentrates wing component fabrication and advanced materials processing.
Commercial Aircraft Manufacturing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cost-positioning and domestic market capture. The vendor base concentrates around three airframe OEMs with final assembly authority, while engine and systems suppliers consolidate through long-term sole-source agreements. Strategic archetypes include full-line integrators, regional jet specialists, and state-sponsored challengers. Competitive moves center on mega-fleet bundling and supply chain backward integration to secure titanium and composite feedstocks.
Among the full-line integrators, Airbus SE and Boeing exemplify the established tier through manufacturing scale and certification authority. COMAC occupies the state-sponsored challenger position, targeting domestic Chinese operators first with single-aisle cost positioning. Embraer represents the regional jet specialist archetype, concentrating on 70-150 seat segments where production flexibility outweighs scale economies.
| Leading Market Players |
|---|
| Embraer |
| Mitsubishi Aircraft Corporation |
| Airbus SE |
| Irkut Corporation |
| Sukhoi Civil Aircraft Company |
| Boeing |
| Bombardier |
| Kawasaki Aerospace Company |
| COMAC (Commercial Aircraft Corporation of China) |
| Others |
Pricing and Supply Chain Analysis
Mega-fleet procurement consolidation among Middle Eastern network carriers and US ultra-low-cost operators is forcing OEMs to unbundle training, spares provisioning, and predictive analytics from base airframe pricing. This procurement shift concentrates pricing power with buyers placing 200-plus unit commitments while compressing margins for manufacturers unable to offer integrated service ecosystems.
Pricing Analysis
Extended warranty and power-by-the-hour service bundles increasingly separate Airbus and Boeing's premium pricing tier from COMAC's economy positioning on unbundled airframe-only transactions. Price differentiation rests on EASA CS-25 and FAA Part 25 certification pedigree versus CAAC type certificate acceptance in secondary markets. Cost compression in the regional jet segment is intensifying because Embraer and Mitsubishi compete for thin-route operators with aggressive financing terms. Leasing companies exhibit highest price sensitivity due to residual value guarantee exposure, while full-service network carriers prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through long-term offtake agreements, while tier-one distributors manage aftermarket spare parts for MRO providers. Feedstock security draws from Russian and Chinese titanium sponge deposits, Japanese carbon fiber precursor manufacturing, and German precision forging capabilities. Raw material dependencies center on aerospace-grade aluminum-lithium sheet, PEEK thermoplastic matrices, and single-crystal superalloys for turbine blades. Single-source vulnerability concentrates in Taiwanese semiconductor foundry capacity for flight control computers. Distribution runs through airframe OEM captive supply chains, engine OEM sole-source networks, and third-party aerostructures integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EASA CS-25 Amendment 26 noise stringency and ReFuelEU Aviation mandates erect regulatory moats favoring incumbent OEMs with established certification infrastructure and retrofit service networks.
For Market Incumbents: Anchor manufacturing scale in Toulouse, Hamburg, and Everett through selective capacity additions while deepening backward integration into titanium and composite feedstocks. Defensive consolidation must address COMAC's domestic capture threat in China and emerging electric propulsion substitutes from urban air mobility programs. Priority investment centers on hybrid-electric certification capabilities and SAF-compatible combustor architectures. For New Entrants and Emerging Players: Enter via Indian MRO infrastructure gaps in Bangalore and Hyderabad where wide-body hangar capacity scarcity creates greenfield openings for line maintenance and engine overhaul services. The most penetrable segment sits in regional turboprop electrification roadmaps transferring battery thermal management IP from eVTOL programs. Go-to-market positioning requires partnership with established lessors seeking residual value guarantees on alternative propulsion platforms. For Investors and Strategic Acquirers: The window for entry favors tier-two aerostructures fabricators with Boeing and Airbus subcontracting relationships and demonstrated composite processing capabilities. Long-term viability hinges on 5-10 year fleet renewal cycle visibility and SAF mandate compliance trajectories. The critical signal to watch is bilateral safety agreement expansions between FAA, EASA, and CAAC affecting COMAC market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| SAF-Compatible Combustor Development | Engine OEMs redesign fuel injectors to meet ReFuelEU Aviation progressive blending mandates at European airports. |
| Titanium Feedstock Backward Integration | Airframe manufacturers secure captive supply chains against Russian and Chinese export restriction exposure. |
| Digital Twin Platform Deployment | Singapore Airlines and Lufthansa Technik compress heavy check intervals through sensor fusion algorithms. |
| Indian MRO Infrastructure Buildout | Greenfield investment openings emerge in Bangalore and Hyderabad for wide-body maintenance capacity. |
| Open-Rotor Propulsion Investment | Scandinavian regional operators face earliest compliance pressure from Stockholm, Oslo, and Copenhagen airport curfews. |
Research Methodology
SEC filings from Boeing and Airbus, EASA certification databases, and FAA type certificate records formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with fleet planning executives at low-cost carriers, procurement directors at aircraft lessors, MRO operations managers, and engine OEM program managers validated demand assumptions and pricing dynamics. Bottom-up triangulation across assembly line output data and top-down reconciliation against airline fleet renewal announcements anchored volume estimates.
Bottom-up modeling of single-aisle and wide-body delivery schedules combined with top-down macroeconomic scenario analysis across the projection horizon. Segmentation dimensions included product type, propulsion architecture, material composition, end-use application, and buyer category. CAGRs were derived from fleet replacement cycle analysis intersecting with sustainable aviation fuel mandate compliance timelines. Industry-specific forecast inputs incorporated titanium sponge price volatility indices and bilateral safety agreement negotiation status between regulatory authorities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under export restriction scenarios affecting Russian titanium feedstock and Taiwanese semiconductor foundry capacity. Periodic stress-testing of base assumptions is recommended given regulatory uncertainty around ReFuelEU Aviation blending mandates and ICAO CORSIA carbon offset implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Europe Light and Very Light Jets Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Aircraft Flight Control System Market
Aircraft
Fighter Aircraft Market
Aircraft
Belly Fairing Modifications for Freighter and Combi Aircraft Market
Aircraft
Regional Jet Market
Aircraft
Aircraft Leasing Market
Aircraft
Military Aircraft Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Special Mission Aircraft Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Electric Aircraft Market
Aircraft
Airplane and Helicopter Hangar Doors Market
Aircraft
Supersonic Jet Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Airship Market