
 MRO Protective Coatings Market | 2026-2036
MRO Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
MRO Protective Coatings Market Outlook
Southeast Asian capacity expansion is tilting the regional supply balance for MRO protective coatings. PPG Industries leverages its marine coatings expertise to sustain long-term service contracts across major shipyard networks. Akzo Nobel N.V. differentiates through high-performance zinc-rich systems that dominate corrosion protection specifications for offshore structures.
MRO protective coatings are formulated systems applied to maintain, repair, and overhaul existing substrates, typically comprising resin binders such as epoxy or polyurethane, corrosion inhibitors, and functional pigments that cure to form adherent barrier films. These coatings extend asset life cycles by preventing electrochemical degradation, chemical attack, and mechanical wear in demanding operating environments. Epoxy formulations anchor the product mix due to their superior adhesion and chemical resistance in industrial maintenance cycles, while polyurethane topcoats command premium positioning for UV stability and aesthetic durability in exterior applications. Water-based technology represents the fastest-growing formulation segment as environmental compliance tightens across jurisdictions, though solvent-based systems still occupy substantial share in heavy marine and immersion-service specifications.
EPA regulations in the United States restrict volatile organic compound emissions from industrial coating operations, compelling reformulation investments and application equipment upgrades across the value chain. REACH registration requirements in Europe and evolving MEE enforcement in China further shape product portfolios, with compliance costs filtering through to specification decisions by asset owners. Stakeholders must monitor regulatory divergence across major economies, as incompatible standards threaten to fragment formulation strategies and complicate global supply chain planning.
Market Dynamics
Offshore platform life extension programs are redirecting specification priorities toward high-performance corrosion protection systems that withstand immersion service and cyclic thermal stress. Asset owners now bundle coating procurement into integrated maintenance contracts spanning multiple turnaround cycles.
Growth Catalysts
- Offshore platform refurbishment:Oil and gas operators in the Gulf of Mexico and North Sea are accelerating recoating schedules to extend asset lifespans beyond original design horizons.
- REACH compliance deadlines:ECHA registration requirements for corrosion inhibitors are forcing formulation upgrades that favor compliant suppliers with established dossiers.
- Epoxy-polyurethane hybrid systems:These dual-layer specifications are capturing specification share in chemical processing facilities requiring both chemical resistance and UV stability.
Market Restraints
- Zinc raw material volatility:Zinc-rich primer formulations face margin pressure from London Metal Exchange price swings and concentrate supply disruptions.
- Solvent-based system lock-in:Heavy marine specifications still mandate solvent-borne chemistries that conflict with tightening EPA VOC thresholds in port-adjacent application zones.
- Specialized applicator scarcity:Certified coating inspectors and NACE-qualified surface preparation crews command premium wages that inflate project labor costs.
Strategic Opportunities
- Digital coating monitoring:IoT-enabled thickness sensors and electrochemical impedance spectroscopy are creating recurring revenue streams beyond initial material sales.
- EU Green Deal procurement mandates:Public infrastructure tenders in Germany and France now weight environmental product declarations heavily in contractor selection.
- Water-based immersion grades:Breakthroughs in latex-epoxy hybrids are opening tank lining applications previously reserved for solvent systems.
Industry Challenges
- Surface preparation standard enforcement:SSPC-SP 10 near-white blast specifications require specialized containment and abrasive recovery systems that extend project timelines.
- Multi-coat system compatibility:Mismatched cure chemistries between primer and topcoat layers cause intercoat adhesion failures requiring costly strip-and-recoat remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRO Protective Coatings Market |
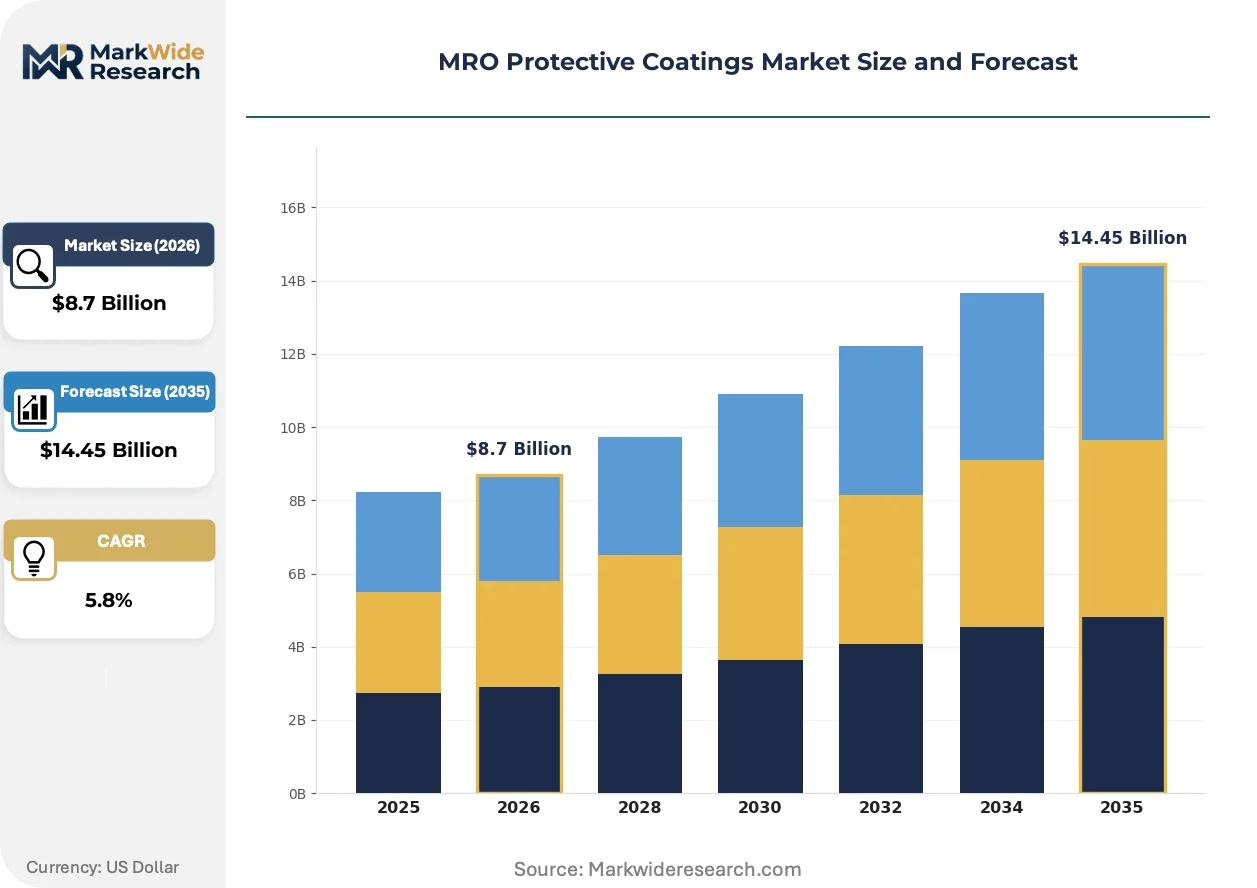
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPOXY, POLYURETHANE, ACRYLIC, ZINC Application: Aerospace, Marine, Industrial Equipment, Construction End User: Aerospace Manufacturers, Oil & Gas Operators, Power Plants, Railways Technology: Nanotechnology, Dual Cure, Solvent-based, Water-based |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Akzo Nobel N.V., BASF SE, Jotun, Hempel A/S, Axalta Coating Systems, H.B. Fuller, Nippon Paint Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRO Protective Coatings Market Strategic Shifts
Formulation chemistry is pivoting toward lower-carbon curing mechanisms while application methods integrate automation to reduce labor dependency and improve film thickness consistency.
Self-healing microcapsule technology is migrating from aerospace prototypes to offshore splash zone specifications. Norwegian platform operators are piloting these systems in high-fatigue areas where mechanical damage propagates rapidly. The shift is compressing maintenance windows from five-year cycles toward condition-based intervention schedules.
EPA Method 24 VOC testing protocols are tightening enforcement around industrial maintenance coatings in Houston and Los Angeles port complexes. Refineries and chemical terminals face permit modifications requiring emission capture systems or immediate reformulation to compliant chemistries. Water-based epoxy tank linings are capturing specification share in these jurisdictions despite longer cure schedules.
Integrated service contracts now bundle material supply with surface preparation, application, and inspection under single-source accountability. Offshore rig operators in the Gulf Coast corridor favor these arrangements over fragmented procurement that splits liability across subcontractors. The model compresses project administration overhead while shifting performance risk toward coating system providers.
MRO Protective Coatings Market Segmentation
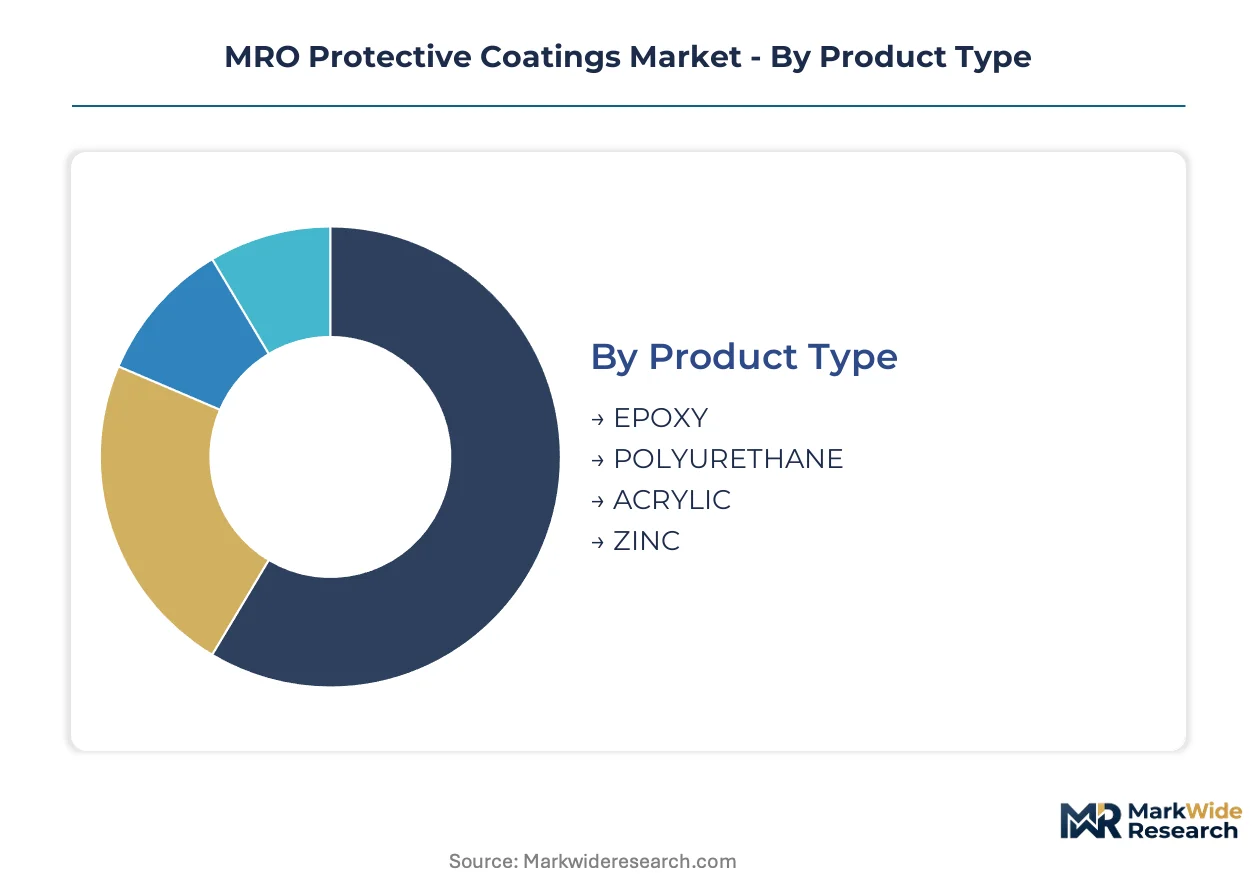
Segmentation in MRO protective coatings reveals how specification priorities diverge across asset classes and regulatory jurisdictions. Procurement patterns cluster around lifecycle extension economics rather than initial capital expenditure, reshaping supplier engagement models across each dimension.
Product Type:
After-sales service intensity varies sharply by resin chemistry, with immersion-grade systems demanding continuous technical support through multi-year maintenance contracts.
- EPOXY:Two-component amine-cured formulations deliver superior substrate adhesion and chemical resistance for tank linings and secondary containment. Gulf Coast petrochemical terminals specify these systems for 15-year corrosion protection cycles, though extended cure times complicate turnaround scheduling.
- POLYURETHANE:Aliphatic topcoats provide UV stability and color retention for exterior architectural and offshore platform applications. North Sea operators prioritize these finishes for helideck and superstructure maintenance where aesthetic durability affects operational certification.
- ACRYLIC:Water-dispersed acrylics serve light industrial maintenance with faster dry-to-recoat intervals and lower application temperatures.
- ZINC:Inorganic zinc-rich primers sacrifice themselves galvanically to protect steel substrates in splash zones and atmospheric exposures.
By volume, EPOXY leads. By growth pace, POLYURETHANE is ahead.
Application:
Cost tier differentiation separates specification-grade marine systems from commodity industrial maintenance products.
- Aerospace:Chromate-free conversion coatings and qualified manufacturer list approvals govern MRO hangar operations. FAA repair station regulations in Oklahoma and Kansas maintenance hubs drive documentation burdens that favor established coating system providers with dedicated aerospace technical service teams.
- Marine:Immersion service specifications for ballast tanks and cargo holds require NORSOK M-501 prequalification for North Sea deployment. Singapore shipyard networks concentrate demand for high-build epoxy systems that withstand cyclic wet-dry exposure in tropical humidity.
- Industrial Equipment:Chemical processing vessels and pipeline exteriors demand chemical-resistant formulations compatible with thermal insulation systems.
- Construction:Bridge and infrastructure recoating prioritizes rapid return-to-service and traffic-bearing cure characteristics.
By installed base, Industrial Equipment dominates. By specification value, Marine commands premium positioning.
End User:
Customer type determines procurement centralization, with integrated oil majors consolidating coating decisions across global asset portfolios.
- Aerospace Manufacturers:OEM-approved repair schemes limit MRO material selection to qualified product lists with traceable batch documentation. Boeing and Airbus maintenance manual cross-references create specification lock-in that extends across third-party MRO providers.
- Oil & Gas Operators:Integrated majors bundle coating procurement into multi-asset framework agreements spanning offshore platforms, refineries, and pipelines. ExxonMobil and Shell procurement teams in Houston and The Hague negotiate volume commitments that reshape supplier margin structures.
- Power Plants:Coal and nuclear facilities face stack emissions compliance deadlines that accelerate protective coating replacement cycles.
- Railways:Rolling stock and infrastructure maintenance specifications prioritize abrasion resistance and graffiti removal compatibility.
By contract value, Oil & Gas Operators lead. By specification complexity, Aerospace Manufacturers set the tightest constraints.
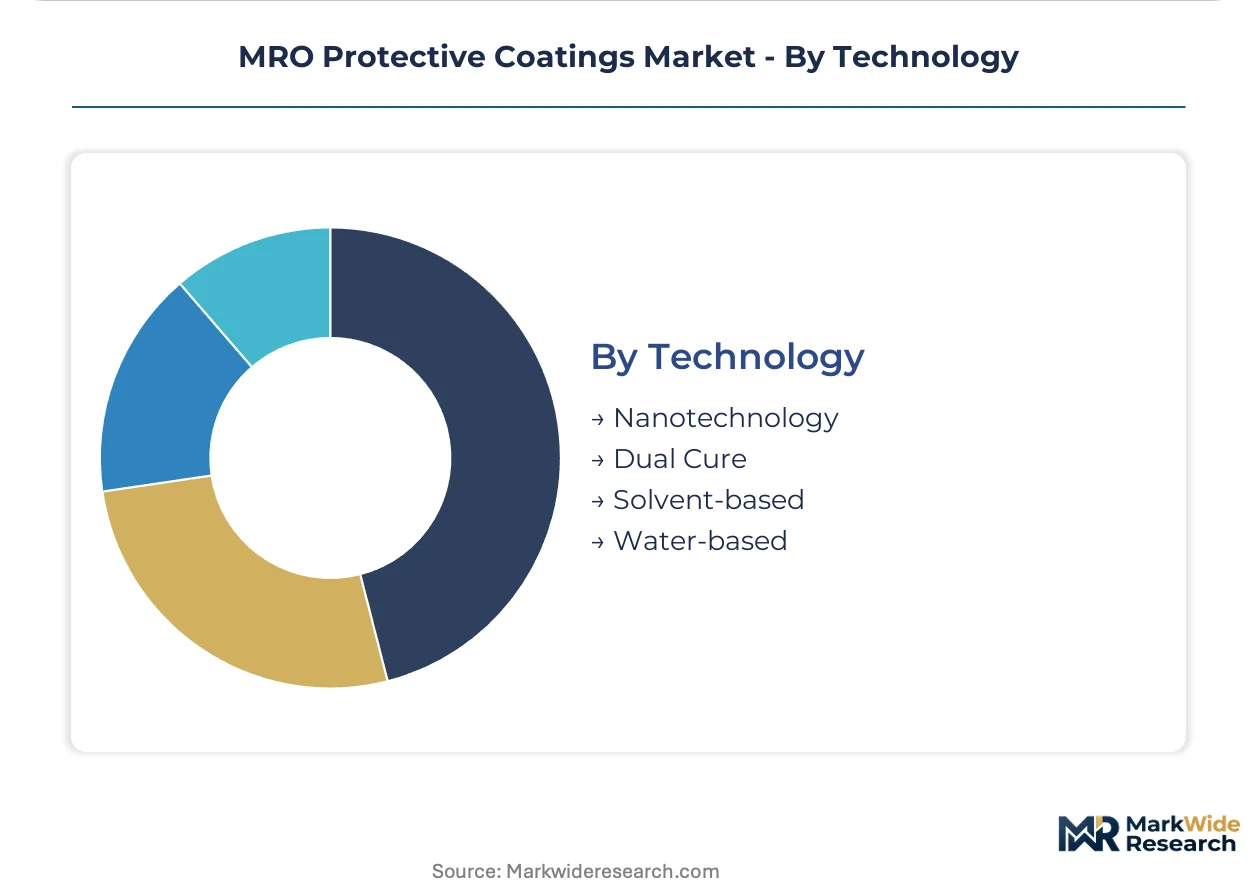
Technology:
Supply concentration in water-based formulation expertise is displacing legacy solvent-borne production capacity.
- Nanotechnology:Self-assembling silane and ceramic nanoparticle additives enhance barrier properties at reduced film thickness. Norwegian platform operators in Equinor's portfolio pilot these systems for splash zone applications where mechanical damage tolerance justifies material cost premiums.
- Dual Cure:UV-thermal hybrid curing mechanisms enable rapid throughput in shop-applied industrial maintenance while accommodating complex geometries that resist pure UV penetration. German automotive supplier paint shops adopt these systems for tooling and fixture refurbishment.
- Solvent-based:High-solids alkyds and epoxies retain specification share in heavy marine immersion service where water-based alternatives fail performance qualification.
- Water-based:Latex-epoxy hybrids and acrylic dispersions capture specification share as EPA VOC enforcement tightens in Houston and Los Angeles port complexes.
By current specification share, Solvent-based leads. By regulatory tailwinds, Water-based is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Louisiana Offshore Oil Port pipeline network and Gulf Coast petrochemical corridor anchor the United States' dominant position in MRO protective coatings procurement. Aging North Sea platforms and Singapore's shipyard concentration drive secondary demand clusters.
United States
Houston-area refineries and Corpus Christi export terminals drive specification volume for high-solids epoxy systems. EPA Method 24 VOC enforcement in Texas and California port complexes compels water-based formulation adoption. The Gulf Coast petrochemical corridor concentrates demand around integrated maintenance contracts bundling coating procurement with turnaround services.
Norway
Equinor's offshore portfolio and North Sea platform life extension programs prioritize NORSOK M-501 prequalified systems. REACH compliance deadlines for corrosion inhibitor registrations reshape supplier qualification requirements. Stavanger and Bergen technical service hubs support subsea infrastructure maintenance specifications demanding 25-year corrosion protection cycles.
Singapore
Jurong shipyard networks and Tuas port expansion generate concentrated demand for immersion-grade marine coatings. MEE enforcement alignment with IMO environmental standards accelerates low-VOC formulation adoption. The Singapore Maritime Foundation's sustainability certification programs now weight coating procurement decisions in favor of water-based tank lining systems.
Germany
Ruhr Valley chemical processing clusters and Hamburg port infrastructure drive specification-grade polyurethane demand. EU Green Deal procurement mandates in federal infrastructure tenders elevate environmental product declaration weighting. Bavarian automotive supplier paint shops adopt dual-cure UV-thermal systems for tooling refurbishment cycles.
China
Yangtze River Delta shipyards and Ningbo-Zhoushan port expansion sustain heavy marine coating volume. MEE enforcement of GB standards for industrial VOC emissions tightens solvent-based system specifications. Shandong Province petrochemical corridor operators pilot nanotechnology-enhanced barrier systems for splash zone applications.
MRO Protective Coatings Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying resin binders and functional pigments. The vendor base concentrates around integrated coating system providers with established marine and industrial maintenance service networks. Three archetypes dominate: diversified chemical conglomerates with captive coating divisions, pure-play protective coatings specialists with regional technical service density, and marine-focused formulators with NORSOK and IMO prequalification portfolios. Competitive positioning hinges on backward integration into resin production and geographic expansion through dedicated technical service hubs.
Among diversified chemical conglomerates, BASF SE and The Sherwin-Williams Company exemplify platform-scale competitors with integrated raw material positions. Akzo Nobel N.V. occupies a specialist position within the high-performance zinc-rich primer segment, while PPG Industries anchors the marine coatings tier through long-term service contract relationships with major shipyard networks. Hempel A/S and Jotun represent Nordic-origin specialists with concentrated offshore platform specification share.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries |
| Akzo Nobel N.V. |
| BASF SE |
| Jotun |
| Hempel A/S |
| Axalta Coating Systems |
| H.B. Fuller |
| Nippon Paint Holdings Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Chinese epoxy resin production concentration and German specialty additive manufacturing anchor upstream supply positions, directing margin capture toward formulation houses with captive raw material positions and NORSOK prequalification portfolios. Integrated coating system providers leverage these dependencies to bundle material supply with technical service contracts that lock in multi-year procurement commitments.
Pricing Analysis
EPA Method 24 VOC enforcement dictates the pricing tier structure across the Gulf Coast and California port complexes. Three-tier pricing structure across premium, standard, and economy levels separates NORSOK-prequalified marine systems from commodity industrial maintenance grades, with zinc-rich primer formulations commanding spreads based on London Metal Exchange volatility. Pricing pressure stems from certified applicator scarcity that inflates project labor components, while oil and gas operators exhibit lowest price sensitivity due to bundled framework agreements.
Supply Chain Analysis
Extended payment terms from integrated oil majors and supply-chain finance facilities from German chemical distributors reshape working capital requirements across the value chain. Raw material sourcing concentrates in China for epoxy resins, Germany for isocyanate precursors, and Norway for zinc concentrates. Formulation draws from these inputs while facing tariff exposure on specialty corrosion inhibitors. Distribution runs through authorized technical service hubs that prequalify applicators and inspectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive outcomes as integrated service contracts bundle material, application, and inspection under single-source accountability. Interoperability between IoT-enabled coating monitoring systems and asset integrity management platforms creates winner-take-most dynamics.
For Market Incumbents: Build certification moats through accelerated NORSOK M-501 and REACH corrosion inhibitor dossier investments. Defensive moves center on acquiring regional technical service hubs in Singapore and Stavanger to lock out challengers from shipyard and offshore platform specifications. Threat substitution from self-healing microcapsule technology demands R&D allocation toward condition-based monitoring integration. For New Entrants and Emerging Players: Establish a beachhead in water-based immersion-grade tank linings for EPA-regulated port complexes. White-space targets include dual-cure UV-thermal systems for German automotive supplier tooling refurbishment and nanotechnology-enhanced barrier coatings for Norwegian splash zone pilots. Go-to-market leverage rests on supply-chain finance partnerships that match incumbent payment terms. For Investors and Strategic Acquirers: Capital is best deployed toward formulation specialists with captive resin production and established marine prequalification portfolios. Long-term viability favors assets with backward integration into epoxy intermediates and geographic density in Gulf Coast technical service. Signal to watch: integrated oil major procurement consolidation that collapses supplier counts from fragmented regional bases to global framework agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resins | Captive supply of amine-cured intermediates insulates margin from Chinese feedstock volatility. |
| NORSOK M-501 Prequalification Investment | North Sea platform specifications require documented immersion service performance history. |
| IoT-Enabled Coating Monitoring Launch | Electrochemical impedance spectroscopy creates recurring revenue beyond material sales. |
| Water-Based Formulation Scale-Up | EPA VOC enforcement in Houston and Los Angeles accelerates specification capture. |
| Technical Service Hub Acquisition | Stavanger and Singapore density locks in offshore platform and shipyard access. |
Study Parameters
A standing panel of maintenance directors at Gulf Coast refineries, coating procurement leads at integrated oil majors, NACE-certified inspection contractors, and technical service managers at marine formulators provided ongoing calibration. Primary fieldwork combined structured interviews with these stakeholders against secondary validation through customs trade data, SEC 10-K filings of listed coating manufacturers, American Chemistry Council sector reports, and ECHA registration dossiers. Bottom-up volume modeling across resin chemistry tiers triangulated against top-down expenditure estimates from asset owner maintenance budgets.
Scenario bracketing around regulatory enforcement intensity and raw material price volatility shaped the analytical framework. Segmentation dimensions modeled include resin chemistry, application environment, cure mechanism technology, and end-user procurement centralization across the projection horizon. CAGRs derived from asset lifecycle extension economics and specification-grade adoption curves, with particular sensitivity to REACH compliance deadlines and EPA Method 24 enforcement trajectories.
Sensitivities concentrate around zinc price volatility, certified applicator availability, and regulatory divergence between EPA and MEE standards. Forecasts reflect assumptions on coating procurement bundling trends and water-based formulation performance qualification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Aviation MRO Software Market
Aircraft Maintenance and MRO Solutions
Aircraft Recycling Market
Aircraft Maintenance and MRO Solutions
Southeast Asia Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
North America Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Landing Gear Repair and Overhaul Market
Aircraft Maintenance and MRO Solutions
Colombia Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weight Scale Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Disassembly Dismantling and Recycling Market
Aircraft Maintenance and MRO Solutions
Regional Turboprop Engine MRO Services Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Landing Gear MRO Market
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market