
 North America Aircraft MRO Market | 2026-2036
North America Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
North America Aircraft MRO Market Analytics
The gap between legacy analog maintenance protocols and digital-first operations is narrowing as North American carriers retrofit fleets with connected sensor arrays and cloud-based diagnostics. StandardAero leverages its specialized engine overhaul capabilities to dominate the regional turboprop segment. Boeing Global Services anchors its position through integrated logistics networks that bind OEM parts distribution directly to airline flight operations.
Aircraft maintenance, repair, and overhaul encompasses the technical inspection, restoration, and modification of airframes, powerplants, and avionics systems to sustain airworthiness certifications under FAA Part 145 standards. Engine Maintenance commands the largest value pool given the capital intensity of turbine overhauls and the finite cycle limits on high-pressure components. Predictive Maintenance is expanding fastest as operators deploy machine-learning models to forecast component failures before they trigger unscheduled downtime.
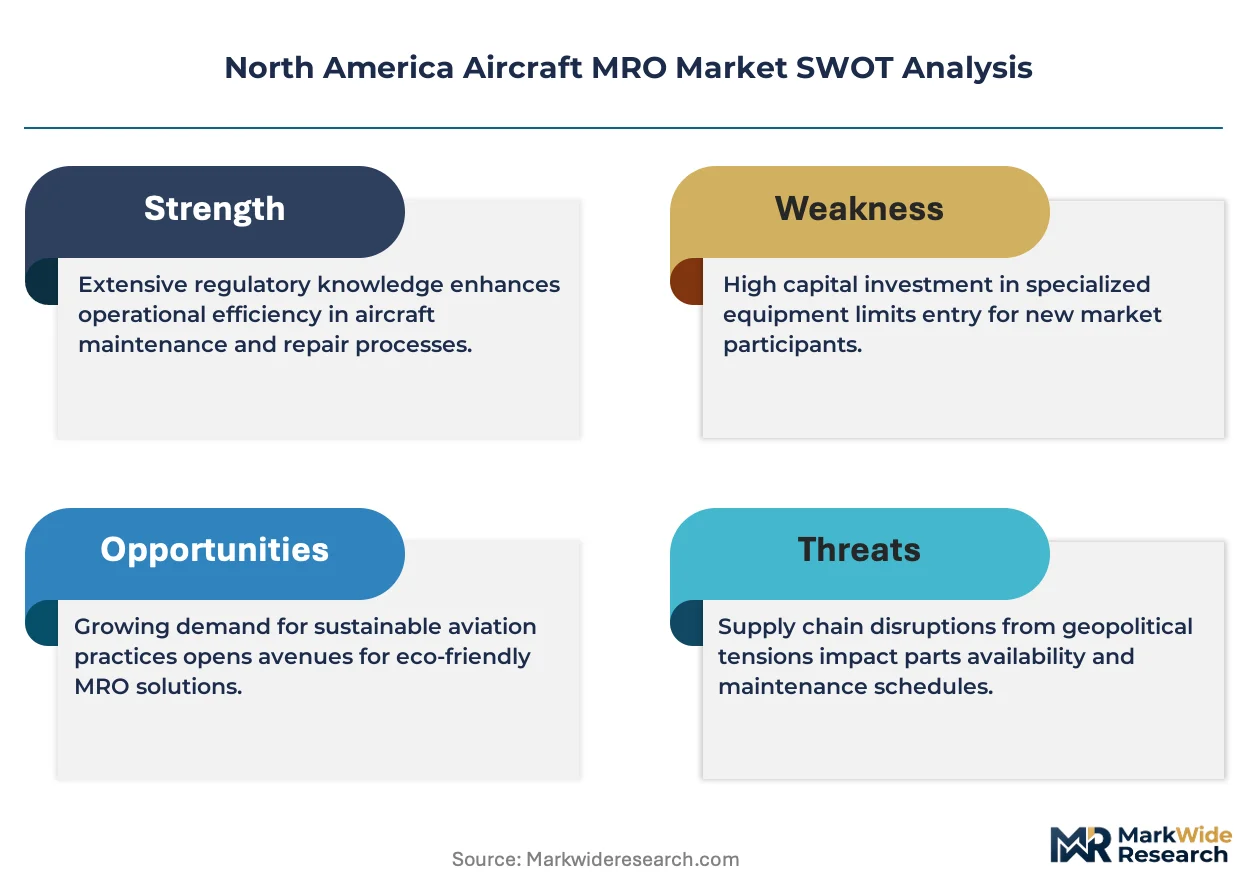
The FAA, Transport Canada, and the EPA collectively govern airworthiness standards, emissions compliance, and hazardous materials handling across the North American MRO footprint. These frameworks elevate barrier costs for new entrants while mandating continuous technician recertification that tightens labor supply. Stakeholders must weigh the capital requirements of greenfield digital infrastructure against the risk of stranded assets as hydrogen-compatible propulsion systems enter the certification pipeline.
Market Dynamics
The FAA's accelerated airworthiness directive cadence and the migration from scheduled to condition-based maintenance protocols are compressing overhaul cycles while demanding real-time fleet health visibility from operators.
Growth Catalysts
- FAA Part 145 Certification Expansion:The FAA's streamlined approval pathways for specialized repair stations are enabling regional facilities to capture engine module work previously concentrated at OEM-affiliated centers.
- Predictive Analytics Platforms:Machine-learning diagnostics deployed by US network carriers are reducing unscheduled engine removals and extending time-on-wing for high-cycle turbofans.
- Southeastern Hub Concentration:Georgia and Florida MRO clusters anchored by Atlanta and Miami international hubs are attracting skilled technician migration from legacy Midwest maintenance bases.
Market Restraints
- Titanium and Superalloy Supply Volatility:Aerospace-grade material sourcing constraints from limited qualified foundries are inflating engine component lead times and overhaul pricing.
- Canadian Labor Pool Constraints:Transport Canada certification requirements combined with demographic shifts are tightening avionics technician availability below replacement rates.
- Hydrogen Propulsion Uncertainty:Emerging hydrogen-compatible turbine architectures risk stranding current engine overhaul infrastructure before depreciation cycles complete.
Strategic Opportunities
- Mexican Nearshoring Expansion:Querétaro and Baja California aerospace corridors offer FAA-aligned regulatory frameworks with labor cost structures below US equivalents for line maintenance.
- Sustainable Aviation Fuel Infrastructure:EPA emissions compliance pathways and airline SAF commitments are creating demand for engine combustor modifications and emissions testing services.
- Blockchain Parts Provenance:Distributed ledger verification converging with IoT sensor data is enabling certified pre-owned component markets with reduced traceability friction.
Industry Challenges
- Avionics Cybersecurity Certification:FAA AC 20-173A compliance timelines for connected aircraft systems are extending software modification approval cycles beyond operational planning horizons.
- Legacy Analog-Digital Integration:Mixed-fleet operators face technician skill bifurcation as aging narrowbodies require analog troubleshooting while new deliveries demand cloud-native diagnostics expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Aircraft MRO Market |
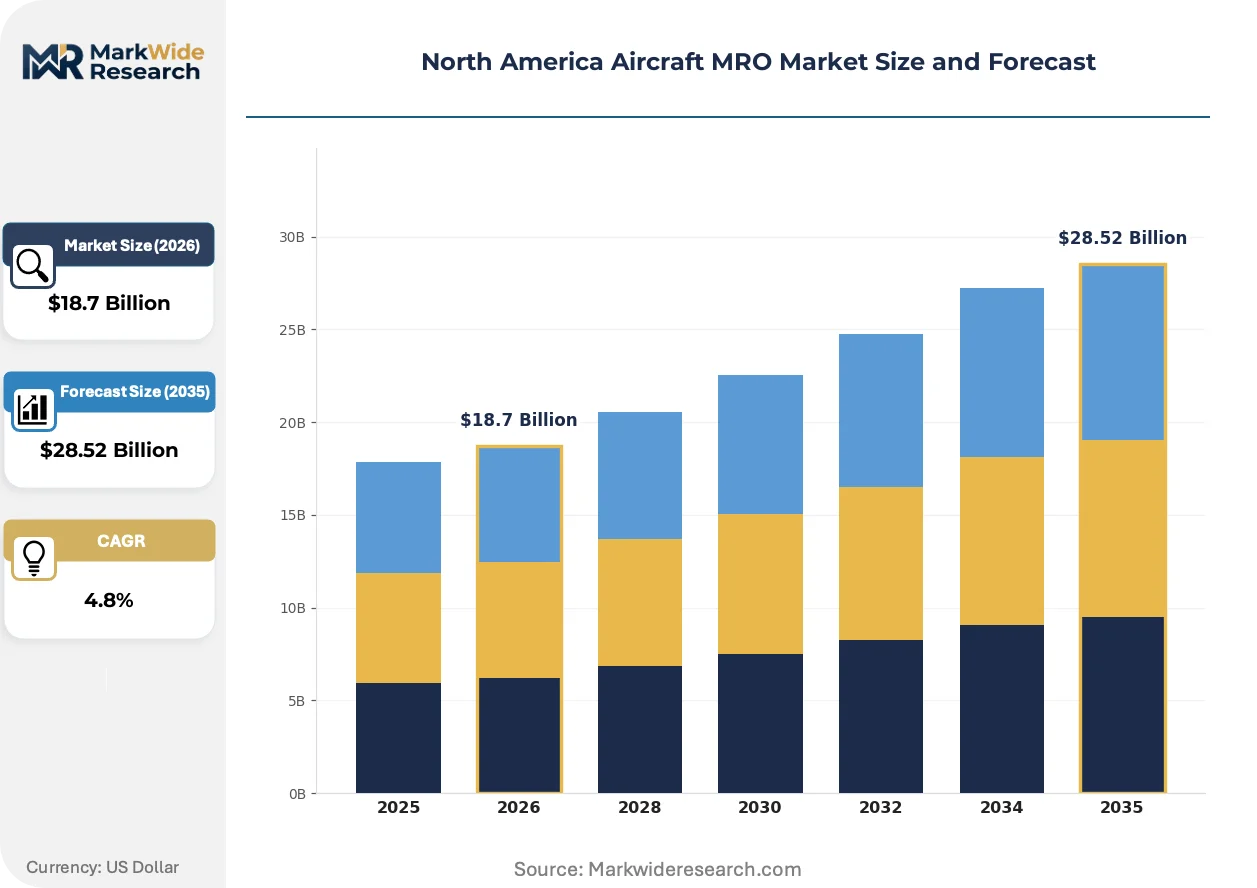
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Maintenance, Component Maintenance, Line Maintenance Platform Type: Commercial Aircraft, Military Aircraft, Helicopters, Drones Maintenance Type: Preventive Maintenance, Corrective Maintenance, Predictive Maintenance, Overhaul Maintenance Delivery Mode: On-Site Services, Off-Site Services, Emergency Services, Scheduled Services |
| Companies Covered | StandardAero, Boeing Global Services, AAR Corp., Lufthansa Technik AG, ST Engineering Aerospace, Delta TechOps, Pratt & Whitney, MTU Maintenance, GE Aviation Services, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Aircraft MRO Market Evolving Landscape
Digital thread architectures are collapsing the information latency between flight operations, maintenance control centers, and component suppliers, enabling synchronous rather than sequential decision-making across the overhaul value chain.
Connected sensor arrays embedded in turbine hot-section components are transmitting real-time vibration, temperature, and erosion data to cloud-based prognostic models. US mainline carriers with fleet-wide deployments are achieving 15-20% extension in mean time between overhauls. This predictive capability is rendering obsolete the calendar-based heavy maintenance visits that governed legacy fleet management.
The FAA's Safety Management System mandate under 14 CFR Part 5 is requiring operators to implement formal risk-based decision frameworks for all maintenance activities. This regulatory pressure is consolidating documentation systems and forcing smaller independent MROs toward standardized digital platforms. Regional turboprop operators in Canada and the US are experiencing the steepest compliance cost curves.
Power-by-the-hour contracts are displacing transactional overhaul purchasing as the dominant commercial model among North American low-cost carriers. These arrangements transfer component reliability risk to OEM-affiliated service providers while locking operators into captive parts supply chains. The shift is most pronounced among airlines with narrowbody fleets concentrated at Atlanta, Dallas-Fort Worth, and Denver hubs.
North America Aircraft MRO Market Segmentation
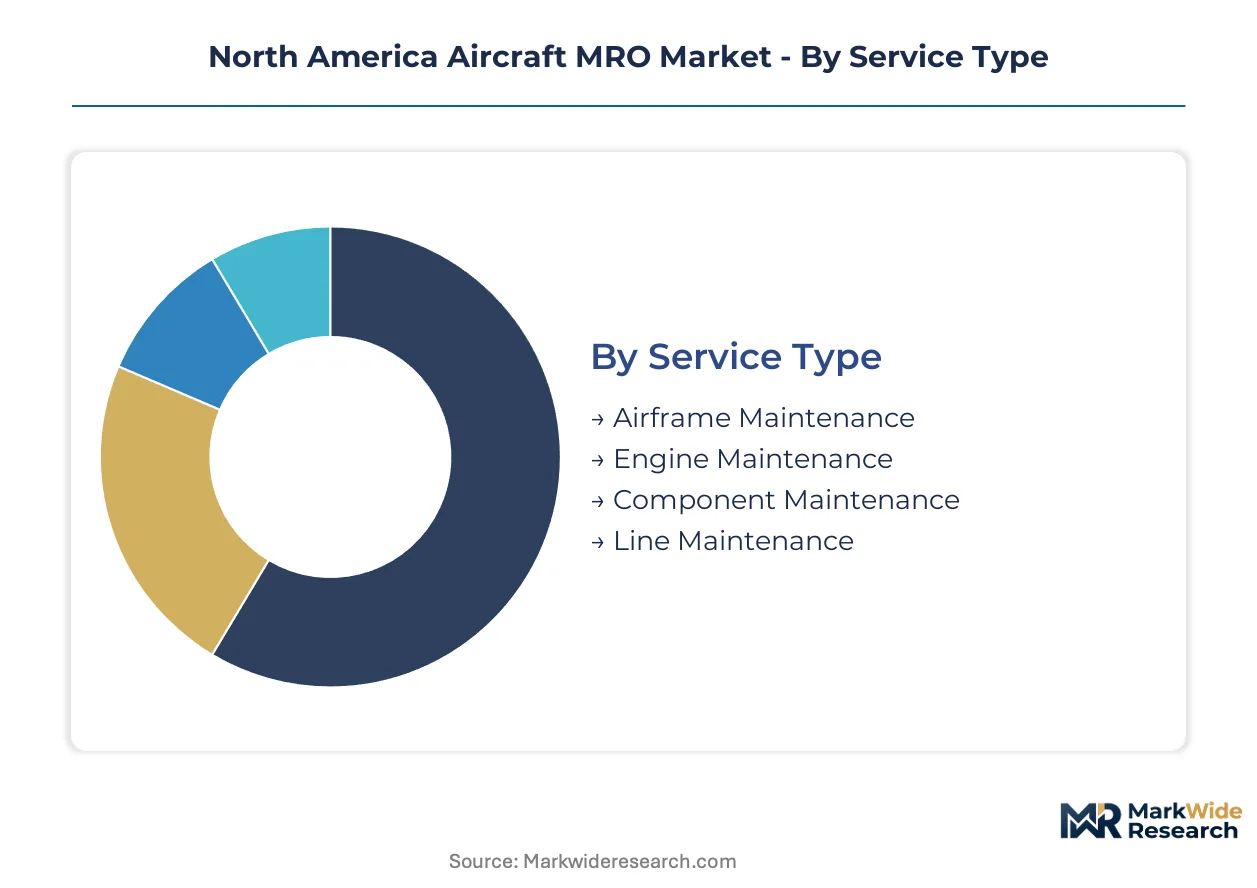
Segmentation in the North America Aircraft MRO Market reveals divergent margin profiles and capital intensity across service modalities. Cycle times, regulatory touchpoints, and labor specialization requirements vary dramatically between engine overhauls and routine line checks.
Service Type:
Cycle times stretch from hours for line maintenance to months for complete engine overhauls, creating distinct working capital and facility requirements across the service spectrum.
- Engine Maintenance:Turbine module overhauls demand specialized cleanroom environments and FAA-certified technician teams for hot-section component restoration. Demand concentrates at OEM-affiliated centers in Georgia and Texas where high-pressure compressor blade replacement cycles drive recurring revenue. Titanium and superalloy supply constraints from qualified foundries are extending turnaround times beyond contractual windows.
- Airframe Maintenance:Heavy structural inspections and corrosion remediation require cavernous hangar bays with jacking systems capable of supporting widebody loads. Canadian operators in Montreal and Vancouver are retrofitting aging narrowbody fleets for avionics upgrades ahead of FAA mandate deadlines.
- Component Maintenance:Landing gear, auxiliary power units, and flight control actuators undergo discrete shop visits with standardized test cell protocols. Mexican facilities in Querétaro are capturing brake and wheel assembly work through FAA-aligned regulatory reciprocity.
- Line Maintenance:Overnight A-checks and turnaround servicing occur at gate positions with mobile tooling kits. Florida hub concentrations at Miami and Orlando anchor the highest flight-line density in the region.
Engine Maintenance anchors the volume base while Predictive Maintenance capabilities embedded in Line Maintenance operations gain share at the steepest rate.
Platform Type:
Cost tiers separate military platforms with classified system requirements from commercial fleets governed by public airworthiness directives.
- Commercial Aircraft:Narrowbody and widebody fleets operated by US network carriers generate predictable heavy maintenance intervals tied to flight hour accumulation. Southeast US MRO clusters in Atlanta and Dallas-Fort Worth capture the majority of scheduled C-check volume.
- Military Aircraft:Defense contractor maintenance depots handle classified avionics and weapons system integration under DoD security protocols. Canadian Forces bases in Cold Lake and Trenton maintain domestic fighter and transport fleets.
- Helicopters:Rotorcraft MRO demands specialized dynamic component balancing and transmission overhaul capabilities distinct from fixed-wing operations. Gulf of Mexico offshore oil transport operators drive demand in Louisiana and Texas.
- Drones:Unmanned aerial system maintenance encompasses composite airframe repair and beyond-visual-line-of-sight communication link certification. FAA Part 107 expansion is creating new inspection protocols for commercial UAV fleets.
Commercial Aircraft sustains the revenue foundation while Drone maintenance infrastructure expands most quickly as regulatory frameworks mature.
Maintenance Type:
Application logic separates calendar-driven preventive protocols from data-triggered condition-based interventions.
- Predictive Maintenance:Machine-learning models applied to vibration and temperature telemetry forecast component failures before functional degradation. US mainline carriers with fleet-wide sensor deployments are achieving extended time-on-wing for high-cycle turbofans.
- Preventive Maintenance:Scheduled inspections at fixed flight hour or calendar intervals governed by manufacturer maintenance planning documents. Transport Canada mandates stricter documentation standards than FAA equivalents for regional operators.
- Corrective Maintenance:Unscheduled repairs triggered by pilot discrepancy reports or ground equipment alerts. Labor availability constraints in Canadian avionics technician pools are inflating emergency response premiums.
- Overhaul Maintenance:Complete disassembly and restoration of major assemblies to zero-time condition. Power-by-the-hour contracts are displacing transactional overhaul purchasing among low-cost carriers.
Preventive Maintenance retains the largest procedure volume while Predictive Maintenance capabilities are climbing the fastest as connected fleet penetration deepens.
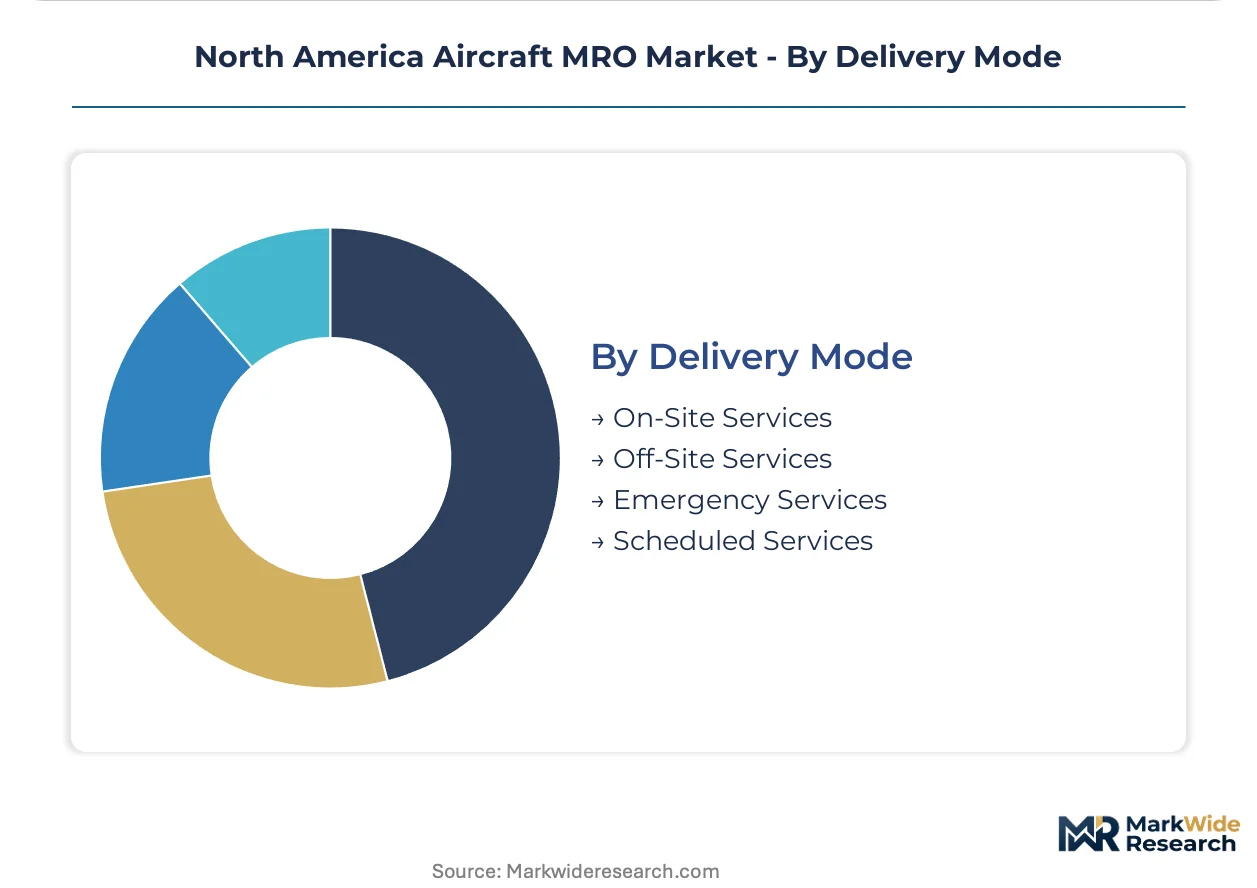
Delivery Mode:
Customer type stratification separates scheduled contractual arrangements from premium-priced emergency interventions.
- Scheduled Services:Pre-planned maintenance visits aligned with operational planning horizons and lease return conditions. Atlanta and Denver hub operators negotiate multi-year exclusive provider agreements.
- On-Site Services:Mobile response teams deploying to airline hangars or remote airfields for A-check and minor repair execution. Florida's high thunderstorm incidence drives demand for rapid structural damage assessment.
- Off-Site Services:Component removal and shipment to specialized repair stations with test cell and cleanroom infrastructure. Mexican nearshoring corridors in Baja California offer cost structures below US equivalents.
- Emergency Services:Aircraft-on-ground response with 24-hour technician dispatch and expedited parts logistics. AOG premiums reflect the operational cost of fleet immobilization at hub airports.
Scheduled Services dominate the contract value base while Emergency Services command the highest margin expansion trajectory as fleet utilization intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Network carriers and low-cost operators concentrate MRO procurement across three distinct national regulatory environments, each with divergent labor availability and infrastructure maturity.
United States
FAA Part 145 repair stations in Georgia and Texas handle the bulk of turbine module overhauls for domestic narrowbody fleets. The FAA's Safety Management System mandate under 14 CFR Part 5 forces documentation standardization across independent operators. Atlanta anchors the Southeast MRO cluster where Delta TechOps and independent providers compete for engine shop visits.
Canada
Transport Canada certification requirements tighten avionics technician supply below replacement rates in Montreal and Vancouver maintenance bases. The Canadian regulator mandates stricter documentation standards than FAA equivalents for regional operators. Cold Lake and Trenton defense depots maintain domestic fighter and transport fleets under classified protocols.
Mexico
Querétaro and Baja California aerospace corridors attract line maintenance work through FAA-aligned regulatory reciprocity and labor cost structures below US equivalents. Mexican facilities capture brake, wheel, and auxiliary power unit assembly repairs. The northern border states position nearshoring operations within overnight logistics reach of Texas and Arizona hubs.
North America Aircraft MRO Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where OEM-affiliated service providers dominate engine overhaul value pools while independent stations capture component and line maintenance niches. Three archetypes define competitive positioning: integrated OEM service arms with captive parts distribution, independent multi-service platforms with geographic scale, and specialized turbine shops with cleanroom certification. Consolidation through M&A and power-by-the-hour contract expansion represent the dominant competitive vectors reshaping operator-supplier relationships.
Among North American-based service providers, StandardAero exemplifies the specialized turbine overhaul archetype, while Boeing Global Services occupies the integrated OEM channel-control position. Delta TechOps represents the airline-captive model where maintenance operations serve internal fleet demands while selectively marketing excess capacity.
| Leading Market Players |
|---|
| StandardAero |
| Boeing Global Services |
| AAR Corp. |
| Lufthansa Technik AG |
| ST Engineering Aerospace |
| Delta TechOps |
| Pratt & Whitney |
| MTU Maintenance |
| GE Aviation Services |
| Others |
Value Network & Pricing Analysis
Atlanta-Miami freight corridors channel titanium alloy shipments from southeastern foundries to Georgia engine shops, where transport cost differentials compound with cleanroom certification tiers to stratify overhaul pricing across OEM-affiliated and independent service providers.
Pricing Analysis
Cost-plus contracts indexed to London Metal Exchange titanium pricing govern long-term engine overhaul agreements between US network carriers and OEM service arms. Three-tier pricing structure across FAA Part 145-certified, Transport Canada-registered, and Mexican-aligned facilities reflects regulatory compliance burden differentials. Pricing pressure stems from superalloy supply constraints extending turnaround times beyond contractual windows. Low-cost carriers with narrowbody fleets concentrated at Dallas-Fort Worth exhibit highest price sensitivity, while legacy network carriers with widebody operations accept premium positioning for guaranteed slot availability.
Supply Chain Analysis
Aerospace-grade titanium sponge feeds from US, Japanese, and Russian primary smelters before conversion at Pennsylvania and Ohio forging facilities. Nickel-based superalloy castings for high-pressure turbine blades draw from Connecticut and Indiana precision foundries with limited qualified supplier pools. Single-source vulnerability concentrates in hot-section component coatings where qualified applicators number below ten across North America. Distribution runs through OEM-captive parts networks and independent component brokers serving regional turboprop operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Aircraft MRO Market tracks commercial aviation cyclical recovery, with fleet utilization rates and airworthiness directive backlogs serving as the primary demand oscillators.
For Market Incumbents: Harden predictive maintenance platform differentiation against emerging analytics specialists by embedding proprietary machine-learning models directly into airline flight operations software. Deepen captive parts distribution control through exclusive power-by-the-hour contract structures that lock narrowbody operators into OEM-affiliated service networks. Accelerate technician certification pipeline investments to offset Transport Canada and FAA recertification bottlenecks tightening labor supply.
For New Entrants and Emerging Players: Mexican nearshoring corridors in Baja California offer underpenetrated line maintenance capacity within overnight logistics reach of Phoenix and Los Angeles hubs. Target brake, wheel, and auxiliary power unit assembly work where FAA-aligned regulatory reciprocity lowers barrier costs versus US facility establishment. Pursue partnership entry with US regional carriers seeking cost relief on overnight A-checks rather than competing head-to-head for engine module overhauls.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized turbine shops with cleanroom certification and established OEM subcontract relationships over diversified multi-service platforms. Five-to-ten year viability hinges on hydrogen-compatible propulsion retrofit capabilities entering certification pipelines. Monitor FAA airworthiness directive cadence acceleration as inflection indicator for demand surge timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Machine-learning diagnostics embedded in Delta TechOps operations extend mean time between overhauls for high-cycle turbofans. |
| Mexican Nearshoring Facility Establishment | Querétaro and Baja California corridors capture line maintenance work through FAA-aligned regulatory reciprocity. |
| Power-by-the-Hour Contract Expansion | Risk-transfer arrangements with low-cost carriers at Atlanta and Denver hubs lock in captive parts supply chains. |
| Superalloy Supply Agreement Diversification | Multi-source titanium and nickel-based alloy procurement mitigates qualified foundry concentration in Connecticut and Indiana. |
| Hydrogen-Compatible Infrastructure Investment | Early cleanroom certification for emerging turbine architectures prevents stranded asset risk as propulsion systems evolve. |
Research Methodology
Operator-level perspectives from airline fleet managers, MRO procurement directors, FAA Part 145 station chiefs, Transport Canada certification officers, and Mexican aerospace corridor developers anchored the qualitative base. Primary field engagement combined with secondary validation against FAA airworthiness directive filings, Transport Canada regulatory updates, airline 10-K maintenance cost disclosures, and aerospace trade flow databases. Bottom-up service-type demand modeling triangulated against top-down fleet projection frameworks.
Scenario-bracketing around fleet renewal acceleration, predictive maintenance penetration, and hydrogen propulsion timeline uncertainty shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass service type, platform category, maintenance protocol, and delivery mode, with additional stratification by hub concentration density. CAGRs derived from fleet growth assumptions, cycle time compression factors, and labor availability constraints specific to Canadian and US technician pools.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hydrogen propulsion specialists or predictive maintenance pure-plays would shift outcomes beyond modeled ranges. Cross-checking against airline capital expenditure guidance and OEM service revenue disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Global Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Asia-Pacific Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
Aircraft Tire Balancer Market
Aircraft Maintenance and MRO Solutions
Business Jet Mro Market
Aircraft Maintenance and MRO Solutions
Aircraft Storage, Preservation and Reactivation Services Market
Aircraft Maintenance and MRO Solutions
Cabin Reconfiguration and Retrofit MRO Services Market
Aircraft Maintenance and MRO Solutions
Aircraft Towing Equipment Market
Aircraft Maintenance and MRO Solutions
North America Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Airline Maintenance Software Market
Aircraft Maintenance and MRO Solutions
GCC Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Vacuum Cleaners Market
Aircraft Maintenance and MRO Solutions
Digital Aerospace MRO Market
Aircraft Maintenance and MRO Solutions
Aircraft Weighing Scales Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Heavy Maintenance Visits Market