
 North America Commercial Aircraft Cabin Interior Market | 2026-2036
North America Commercial Aircraft Cabin Interior Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial Aircraft Cabin Interior Market Analytics
The premium-commodity split in North America commercial aircraft cabin interiors is shifting as full-service carriers invest in lie-flat suites and ambient lighting while regional operators prioritize lightweight, quick-change configurations. Collins Aerospace sustains its position through captive manufacturing of integrated seating and lighting systems for narrow-body retrofits. Safran dominates the lavatory and galleys segment with aluminum-composite hybrid structures certified to FAA flammability standards. Recaro Aircraft Seating differentiates through ergonomic research partnerships with U.S. carriers seeking reduced-weight economy platforms.
North America commercial aircraft cabin interiors encompass the integrated assemblies, fixtures, and environmental systems installed within the pressurized fuselage to ensure passenger safety, comfort, and operational functionality during flight. These systems must meet FAA Part 25 flammability requirements, with composite panels typically rated to 60-second vertical burn tests and seat cushions engineered to 12-second oil-burner criteria. Seats generate the largest revenue pool among product types, driven by fleet-wide retrofit cycles and premium densification programs, while smart cabin solutions represent the fastest-expanding technology segment as carriers deploy IoT-enabled passenger service units and predictive maintenance sensors across Boeing and Airbus platforms operating in U.S. and Canadian airspace.
FAA certification mandates under 14 CFR Part 25, Transport Canada CAR 525 equivalency requirements, and OSHA workplace safety standards for manufacturing facilities collectively shape material selection, supplier qualification timelines, and aftermarket access in this market. The EPA's emerging focus on aircraft interior volatile organic compound emissions is pressuring fabric and adhesive suppliers to reformulate product lines ahead of potential rulemaking. Stakeholders must weigh the capital requirements of next-generation smart cabin platforms against the compressed retrofit windows that U.S. legacy carriers now demand to maintain competitive consistency across hub-and-spoke networks.
Market Dynamics
Fleet retrofit cycles in the United States and Canada are compressing as full-service carriers race to match premium cabin standards across hub-and-spoke networks, forcing suppliers to accelerate certification timelines for fire-resistant composite materials.
Growth Catalysts
- FAA Part 25 Flammability Mandates:The FAA's 60-second vertical burn test and 12-second oil-burner criteria for seat cushions are accelerating material substitution toward phenolic-resin composites and thermoplastic panels in U.S. retrofit programs.
- Premium Densification Programs:Full-service carriers operating Boeing 787 and Airbus A350 fleets are installing lie-flat suites and mood-lighting systems to capture corporate travel revenue.
- Southeast U.S. Manufacturing Cluster:Boeing's final assembly presence in South Carolina and MRO concentration in Georgia and Florida create captive demand for quick-turn interior component supply.
Market Restraints
- Aluminum-Titanium Price Volatility:Lavatory and galley frame producers face margin compression from aerospace-grade metal input cost swings.
- Single-Source Certification Risk:Transport Canada's CAR 525 equivalency requirements often delay dual-certification timelines, locking suppliers into FAA-only qualification pathways.
- Technical Weight-Floor Limitation:Current fire-resistant composites cannot yet match legacy aluminum strength-to-weight ratios for overhead bin structural elements.
Strategic Opportunities
- Canadian Regional Fleet Expansion:Jazz Aviation and Porter Airlines are expanding turboprop and narrow-body fleets, creating demand for lightweight, quick-change economy seating configurations.
- IoT-Enabled Predictive Maintenance:Convergence of cabin sensor networks with edge computing platforms allows carriers to unbundle reactive maintenance contracts.
- EPA Volatile Organic Compound Rulemaking:Anticipated emissions standards for aircraft interior adhesives and fabrics will reward early reformulators with preferred supplier status.
Industry Challenges
- Specialized Certification Engineer Shortage:FAA Designated Engineering Representatives with Part 25 interior system expertise command premium compensation, constraining supplier scale-up capacity.
- Legacy Platform Integration Complexity:Smart cabin retrofits on Boeing 737 NG and Airbus A320ceo fleets require custom wiring harness modifications that extend downtime windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial Aircraft Cabin Interior Market |
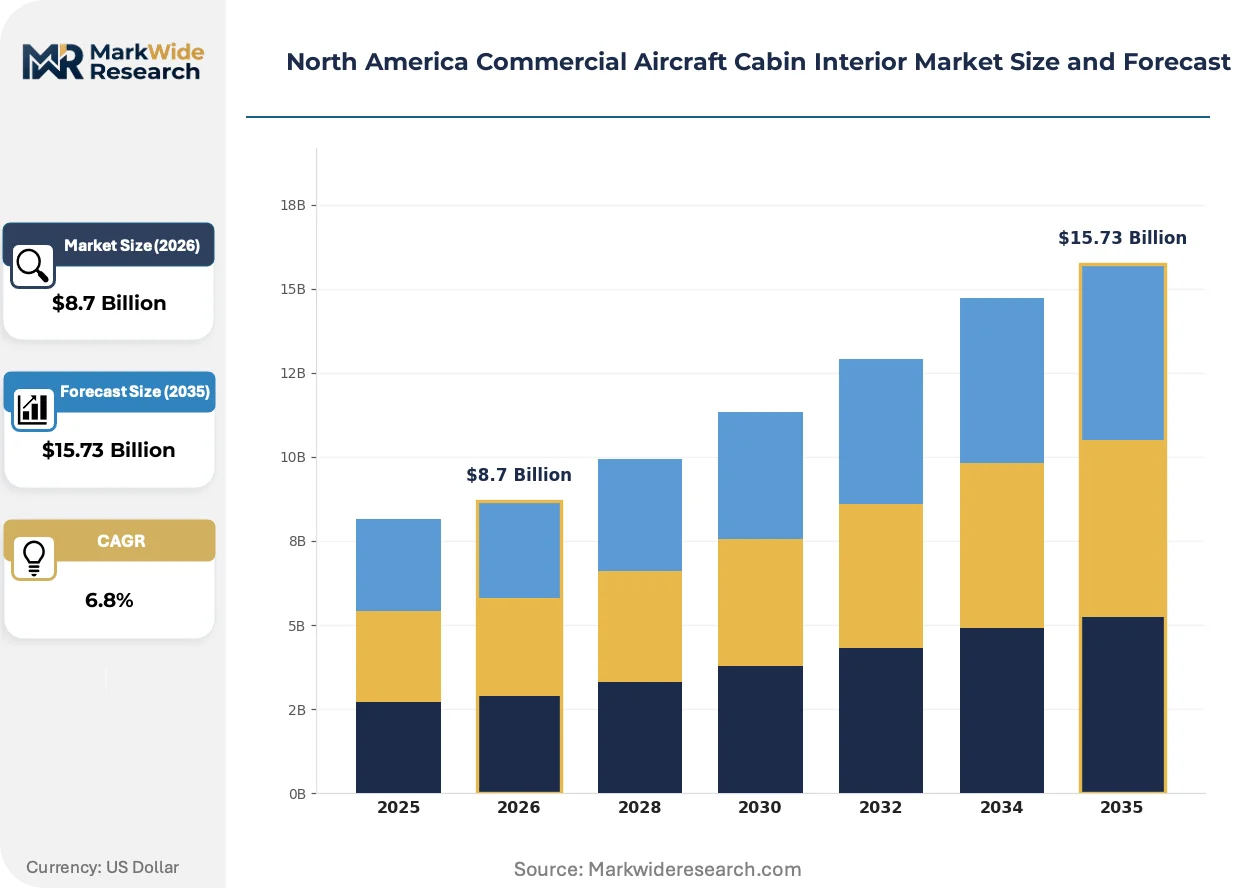
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seats, Lighting Systems, Overhead Compartments, Lavatories Material: Aluminum, Composites, Fabrics, Plastic End User: Airlines, OEMs, MRO Providers, Leasing Companies Technology: In-flight Entertainment, Wi-Fi Connectivity, Smart Cabin Solutions, Noise Reduction Systems |
| Companies Covered | Collins Aerospace, Honeywell International Inc., Panasonic Avionics Corporation, Safran, Jamco Corporation, Recaro Aircraft Seating, Boeing, Astronics Corporation, Haeco Americas, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial Aircraft Cabin Interior Market Evolving Landscape
Connected cabin architectures and predictive maintenance platforms are displacing passive interior systems across North American carrier fleets, while regulatory pressure on material emissions intensifies supplier reformulation cycles.
IoT-enabled passenger service units with integrated seat sensors and environmental monitors are automating real-time occupancy detection and predictive component replacement scheduling. United Airlines and Delta Air Lines are deploying these systems across narrow-body retrofits at accelerated cadences. This automation is compressing traditional maintenance intervals and shifting supplier revenue toward recurring sensor-data service contracts.
The EPA's emerging aircraft interior volatile organic compound emissions framework is pressuring adhesive and fabric suppliers to eliminate formaldehyde-based binders and solvent-borne coatings from production lines. Manufacturers serving Boeing and Airbus final assembly in the U.S. Southeast are pre-qualifying waterborne alternatives ahead of anticipated rulemaking. Seat cushion and panel producers with early reformulation capabilities are securing multi-year sole-source positions with legacy carriers.
Compressed retrofit windows demanded by U.S. hub-and-spoke operators are fragmenting procurement across specialized seating, lighting, and lavatory subcontractors rather than integrated system providers. Airlines now unbundle specification, installation, and certification responsibilities to minimize aircraft downtime. This pattern concentrates in the Southeast, where Georgia and Florida MRO clusters coordinate multi-vendor line-fit operations during narrow-body heavy maintenance checks.
North America Commercial Aircraft Cabin Interior Market Segmentation
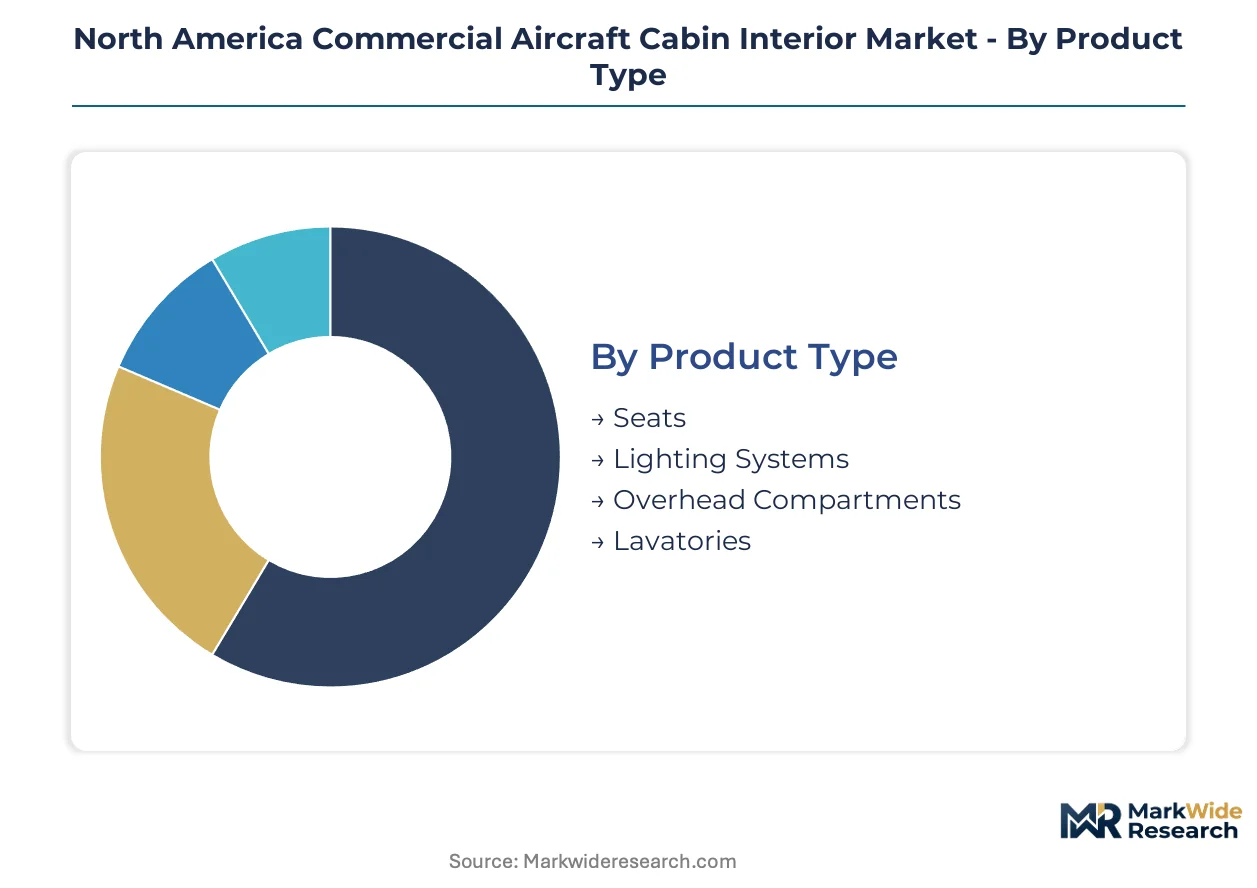
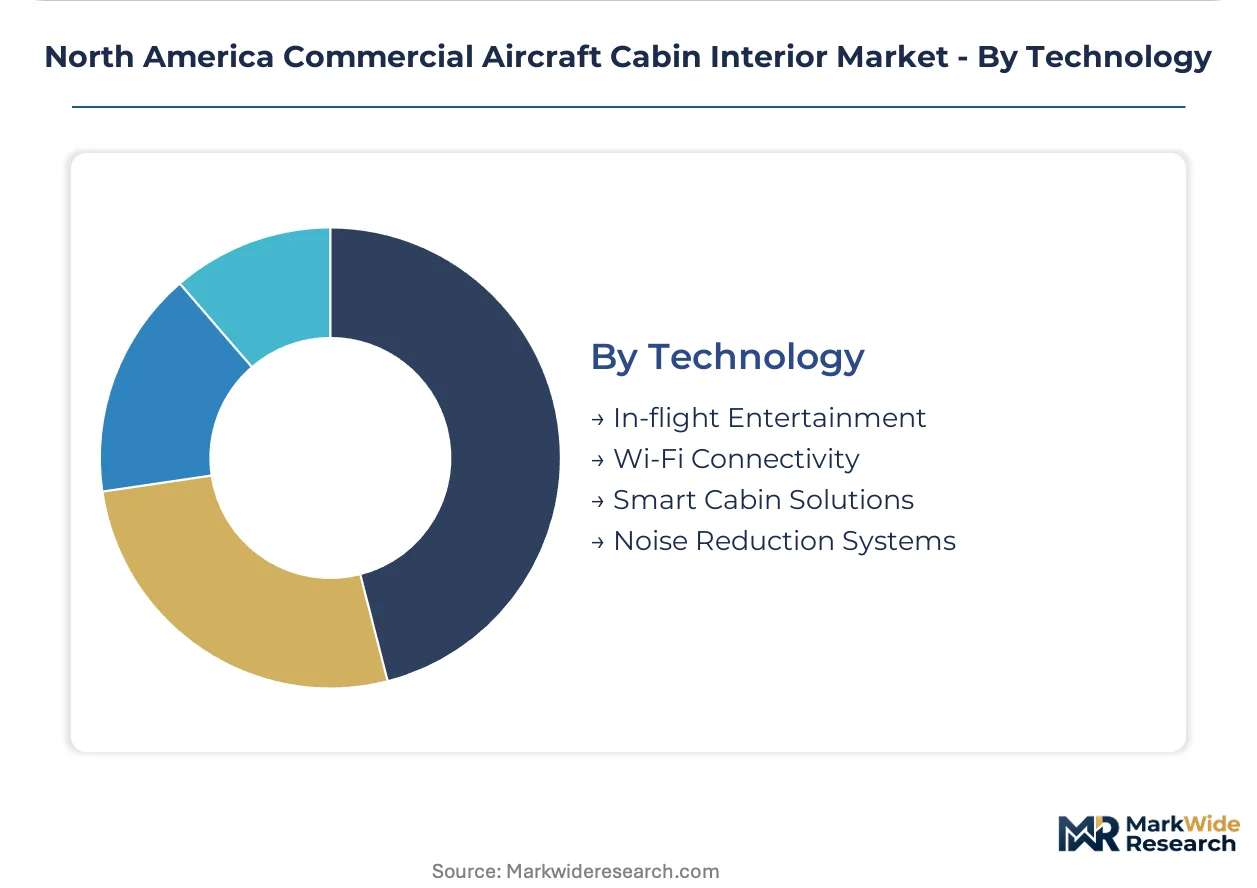
North American carriers segment procurement across product, material, and technology axes to balance FAA Part 25 compliance with fleet modernization timelines. Each dimension carries distinct certification burdens and supplier qualification requirements that reshape competitive positioning.
Product Type:
Technical specification hierarchies determine which assemblies command dedicated engineering resources versus commodity sourcing.
- Seats:Integrated frames with fire-resistant cushioning and 16G dynamic testing certification anchor retrofit spending. U.S. full-service carriers prioritize lie-flat suites for wide-body premium cabins, compressing supplier lead times for dual-density configurations.
- Lighting Systems:LED-based ambient and mood-lighting suites with programmable color temperature control. Southeast U.S. MRO clusters in Georgia and Florida drive concentrated demand for quick-install retrofit kits during narrow-body heavy checks.
- Overhead Compartments:Pivot-bin designs with improved volumetric efficiency for carry-on compliance.
- Lavatories:Aluminum-composite hybrid structures meeting FAA flammability standards with space-optimized footprints.
Seats lead on scale; Lighting Systems lead on momentum.
Material:
Cost tier stratification separates legacy metal specifications from next-generation composite platforms.
- Composites:Phenolic-resin panels and thermoplastic structures rated to 60-second vertical burn tests. Boeing's South Carolina final assembly lines specify these for weight reduction on new-build programs, accelerating supplier capacity expansion.
- Aluminum:Aerospace-grade alloys for lavatory frames and overhead bin structural elements. Transport Canada CAR 525 equivalency delays for alternative materials sustain demand in Canadian retrofit programs.
- Fabrics:Fire-resistant upholstery meeting 12-second oil-burner criteria for seat cushions.
- Plastic:Injection-molded components for non-structural trim and passenger-facing surfaces.
Aluminum retains installed-base dominance; Composites gain share fastest.
End User:
Customer type dictates procurement rhythm, with scheduled maintenance windows versus production line integration demanding distinct supplier capabilities.
- Airlines:Direct procurement for fleet-wide retrofit programs with compressed downtime requirements. U.S. legacy carriers unbundle specification, installation, and certification across specialized vendors to minimize aircraft out-of-service intervals.
- MRO Providers:Georgia and Florida maintenance clusters coordinate multi-vendor line-fit operations during heavy checks, creating captive demand for quick-turn component supply.
- OEMs:Boeing's South Carolina and Airbus U.S. operations specify integrated cabin systems for new-build delivery.
- Leasing Companies:Residual value-focused specifications prioritizing reconfigurable, quick-change interior platforms.
Airlines drive volume concentration; MRO Providers expand most quickly.
Technology:
Maturity curves separate established passenger-facing systems from emerging predictive maintenance platforms.
- Smart Cabin Solutions:IoT-enabled passenger service units with integrated seat sensors and environmental monitors. United Airlines and Delta Air Lines deploy these across narrow-body retrofits, shifting supplier revenue toward recurring sensor-data service contracts.
- Wi-Fi Connectivity:Satellite and air-to-ground systems for passenger broadband. Antenna integration complexity with existing cabin structures sustains specialized installation demand.
- In-flight Entertainment:Seat-back and wireless streaming platforms with content delivery optimization.
- Noise Reduction Systems:Acoustic treatments and active cancellation for cabin quieting.
In-flight Entertainment holds installed-base scale; Smart Cabin Solutions show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled FAA Designated Engineering Representatives and Transport Canada certification engineers anchor the North American supply base, concentrating in aerospace clusters where final assembly and MRO operations drive component demand.
United States
Full-service carriers retrofit wide-body fleets with lie-flat suites and mood-lighting systems to capture corporate travel revenue. FAA Part 25 flammability mandates accelerate material substitution toward phenolic-resin composites and thermoplastic panels. Boeing's final assembly lines in South Carolina and Georgia-Florida MRO clusters generate captive demand for quick-turn interior component supply.
Canada
Jazz Aviation and Porter Airlines expand turboprop and narrow-body fleets, creating demand for lightweight, quick-change economy seating configurations. Transport Canada CAR 525 equivalency requirements sustain demand for aerospace-grade aluminum in lavatory frames and overhead bin structural elements. Montreal and Toronto aerospace corridors concentrate certification engineering talent and composite manufacturing capacity.
Mexico
Aerospace manufacturing expansion in Querétaro and Baja California generates tier-two and tier-three supplier opportunities for interior component fabrication. Mexico's national aerospace regulator aligns certification protocols with FAA standards to facilitate cross-border supply chain integration. Guadalajara and Chihuahua industrial parks attract seating and lighting subsystem producers serving U.S. final assembly.
North America Commercial Aircraft Cabin Interior Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the North American commercial aircraft cabin interior supply base. Tier-one integrators dominate integrated seating and lighting systems, while specialized fabricators capture lavatory, galley, and seating subassembly niches. Three archetypes define competitive positioning: full-system integrators with captive manufacturing, component specialists with deep FAA certification expertise, and regional quick-turn suppliers serving MRO clusters. Dominant competitive moves include strategic partnerships between seating manufacturers and carriers for fleet-wide retrofit programs, plus backward integration by integrators into fire-resistant composite panel production.
Among U.S.-based integrators, Collins Aerospace and Honeywell International Inc. exemplify full-system providers with broad FAA Part 25 qualification portfolios. Safran represents the European-headquartered archetype with established Transport Canada equivalency pathways and aluminum-composite hybrid structure expertise. Recaro Aircraft Seating GmbH occupies the specialized seating tier, anchoring ergonomic research partnerships with North American carriers seeking reduced-weight economy platforms.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell International Inc. |
| Panasonic Avionics Corporation |
| Safran |
| Jamco Corporation |
| Recaro Aircraft Seating |
| Boeing |
| Astronics Corporation |
| Haeco Americas |
| Others |
Value Network & Pricing Analysis
Phenolic-resin composite feedstock moves from Southeast Asian chemical processors through tier-two fabricators in Mexico's Baja California corridor before reaching Boeing's South Carolina assembly lines and Georgia-Florida MRO clusters, with each handoff layering certification premiums onto final component pricing.
Pricing Analysis
Bundled smart-cabin retrofit packages with integrated IoT sensor networks and predictive maintenance software command 40-60% premiums over unbundled hardware-only transactions. Price differentiation hinges on FAA Part 25 certification tier and installation speed—carriers paying for 72-hour line-fit turnaround absorb steep labor surcharges versus standard two-week schedules. Cost compression in aluminum-composite hybrid lavatory frames intensifies as aerospace-grade metal input volatility persists. Regional operators serving Canadian turboprop fleets exhibit highest price sensitivity, while U.S. full-service carriers prioritize speed over unit cost.
Supply Chain Analysis
Warehouse-distribution layers concentrate around Atlanta and Miami hubs serving the Southeast MRO corridor, with regional distribution centers stocking quick-turn seating and lighting modules for 24-hour deployment. Manufacturing capacity clusters in the United States, Canada, and Mexico—South Carolina hosts Boeing final assembly, Montreal anchors composite engineering talent, and Querétaro supplies tier-two subassemblies. Raw material dependencies include phenolic resin precursors, aerospace-grade aluminum, and fire-resistant fabric treatments. Single-source certification risk for Transport Canada CAR 525 equivalency creates regulatory chokepoints. Distribution runs through OEM direct contracts, MRO procurement consortia, and leasing company specification mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America commercial aircraft cabin interiors function as a stable compounder, with fleet retrofit cycles and regulatory refresh mandates generating predictable replacement demand regardless of new aircraft delivery volatility.
For Market Incumbents: Anticipate margin erosion from aluminum-titanium price volatility by securing backward integration into phenolic-resin composite panel production. Defend against emerging quick-turn MRO specialists through captive certification engineering capacity in Georgia and Florida clusters. Prioritize EPA pre-compliance for volatile organic compound emissions to lock in sole-source positions ahead of anticipated rulemaking.
For New Entrants and Emerging Players: Enter via Canadian regional fleet expansion, where Jazz Aviation and Porter Airlines demand lightweight quick-change economy seating with less entrenched supplier relationships. Target the IoT-enabled predictive maintenance segment, where United and Delta deployments prove carrier willingness to unbundle traditional maintenance contracts. Lead with sensor-data service contract models rather than capital equipment sales.
For Investors and Strategic Acquirers: Consolidation pressure builds where FAA Designated Engineering Representative scarcity constrains supplier scale-up capacity. Frame long-term viability around 5-10 year retrofit cycle visibility and regulatory-driven material substitution mandates. Target component specialists with deep Transport Canada equivalency pathways and established Boeing or Airbus line-fit relationships. Watch for EPA emissions rulemaking finalization as inflection signal for early reformulator valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FAA Part 25 Certification Investment | Accelerates supplier qualification timelines for fire-resistant composite seating platforms. |
| Smart Cabin Platform Integration | Enables recurring sensor-data revenue streams with United and Delta narrow-body fleets. |
| MRO Cluster Geographic Expansion | Captures quick-turn retrofit demand concentrated in Georgia and Florida maintenance hubs. |
| EPA Pre-Compliance Reformulation | Secures preferred supplier status ahead of volatile organic compound emissions rulemaking. |
| Canadian Regional Fleet Partnership | Opens turboprop and narrow-body seating demand from Jazz Aviation and Porter Airlines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with FAA Designated Engineering Representatives, airline fleet planning executives, MRO procurement directors, and composite manufacturing plant managers with secondary validation against FAA certification databases, Transport Canada CAR 525 filings, SEC 10-K disclosures from tier-one integrators, and customs records for aerospace-grade material imports. Bottom-up build-ups across seating, lighting, lavatory, and smart cabin product categories were triangulated against top-down market sizing from fleet retrofit cycle analysis.
Comparable-period anchoring established baseline volumes from historical retrofit program data before projecting across the analysis window through segmented modeling by product type, material specification, end-user category, and technology maturity. CAGRs were derived from fitted growth curves applied to carrier fleet plans and regulatory mandate timelines. Key forecast inputs included Boeing and Airbus delivery schedules to North American operators, FAA Part 25 amendment trajectories, and EPA rulemaking commentary.
Inputs from primary stakeholder interviews and regulatory filings were available through the study window; gaps in carrier-specific retrofit budget disclosures introduce uncertainty bands around near-term volume projections. Forecasts reflect documented assumptions regarding fleet age profiles and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Aircraft Galley Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Aerospace Galley Trolley Market
Aircraft Cabin Interior
Commercial Aircraft Interior Lighting Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Lighting Market
Aircraft Cabin Interior
Aircraft Seat Upholstery Market
Aircraft Cabin Interior
Cabin Interior Composites Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Commercial Aircraft in-Flight Entertainment System Market
Aircraft Cabin Interior
Aircraft Floor Panels Market
Aircraft Cabin Interior
Aircraft Cabin Windows, Shades & Blinds Market
Aircraft Cabin Interior
Aircraft Cabin Interiors Market