
 Aircraft Lighting Market | 2026-2036
Aircraft Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Lighting Market Intelligence
North American avionics suppliers is expanding LED manufacturing capacity for next-generation exterior illumination systems. Collins Aerospace leverages its integrated platform strategy to sustain positions across commercial and military application segments. Safran anchors European supply chains through specialized cabin and cockpit lighting architectures. Honeywell International Inc. competes on regulatory compliance depth, positioning its product lines across multiple certification jurisdictions.
Aircraft lighting encompasses engineered illumination systems designed for exterior navigation, interior cabin ambiance, cockpit readability, and emergency egress under operational conditions spanning minus 55 degrees Celsius to 85 degrees Celsius ambient thermal envelopes. These systems employ solid-state emitters, electroluminescent strips, and photometrically calibrated lenses to ensure visibility, crew alertness, and passenger safety during all flight phases. Exterior lighting and LED technology dominate current procurement volumes, with OLED technology representing an emerging structural segment where margin pools concentrate due to limited qualified suppliers. Commercial aircraft application generates the largest revenue base, while military aircraft segments exhibit faster retrofit cycles driven by night-vision compatibility requirements.
FAA airworthiness directives and EASA certification specifications govern photometric output, electromagnetic interference, and fire-smoke toxicity standards for installed lighting equipment. EPA and REACH frameworks additionally constrain substrate materials and coating chemistries used in manufacturing processes. Stakeholders must monitor evolving night-vision goggle compatibility mandates and sustainability disclosure requirements under CSRD as these frameworks reshape procurement specifications and supplier qualification protocols.
Market Dynamics
LED retrofit mandates from FAA and EASA are compressing replacement cycles across commercial fleets, forcing incumbent suppliers to requalify legacy architectures while new entrants exploit solid-state photometric advantages.
Growth Catalysts
- FAA Airworthiness Directives:Mandated anti-collision and emergency egress illumination upgrades are compelling narrow-body operators to accelerate LED conversion programs.
- Night-vision compatibility:Military aircraft segments demand infrared-suppressed exterior lighting, creating specialized procurement pools for qualified emitters.
- REACH substrate constraints:Toxicity restrictions on legacy coating chemistries are favoring solid-state alternatives with compliant material footprints.
Market Restraints
- Indium gallium nitride supply concentration:High-brightness LED die production clusters in East Asian foundries, exposing buyers to single-source geopolitical risk.
- EASA certification timelines:Photometric calibration and electromagnetic interference testing protocols extend qualification periods to 18-24 months.
- OLED qualified supplier scarcity:Limited fabrication capacity for aviation-grade organic emitters concentrates margin capture among two European specialists.
Strategic Opportunities
- India domestic fleet expansion:IndiGo and Air India narrow-body orders create aftermarket lighting demand for regional MRO networks.
- CSRD sustainability disclosure:European carriers must document supply chain emissions, favoring LED retrofits with quantified carbon reduction profiles.
- OLED-cabin convergence:Ambient mood lighting integration with seat-back displays opens premium cabin specification opportunities.
Industry Challenges
- Photometric calibration expertise:Specialized optical engineering talent shortages delay product development cycles at mid-tier suppliers.
- Legacy 28VDC integration:New solid-state architectures must interface with aging airframe electrical buses without triggering arc-fault conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Lighting Market |
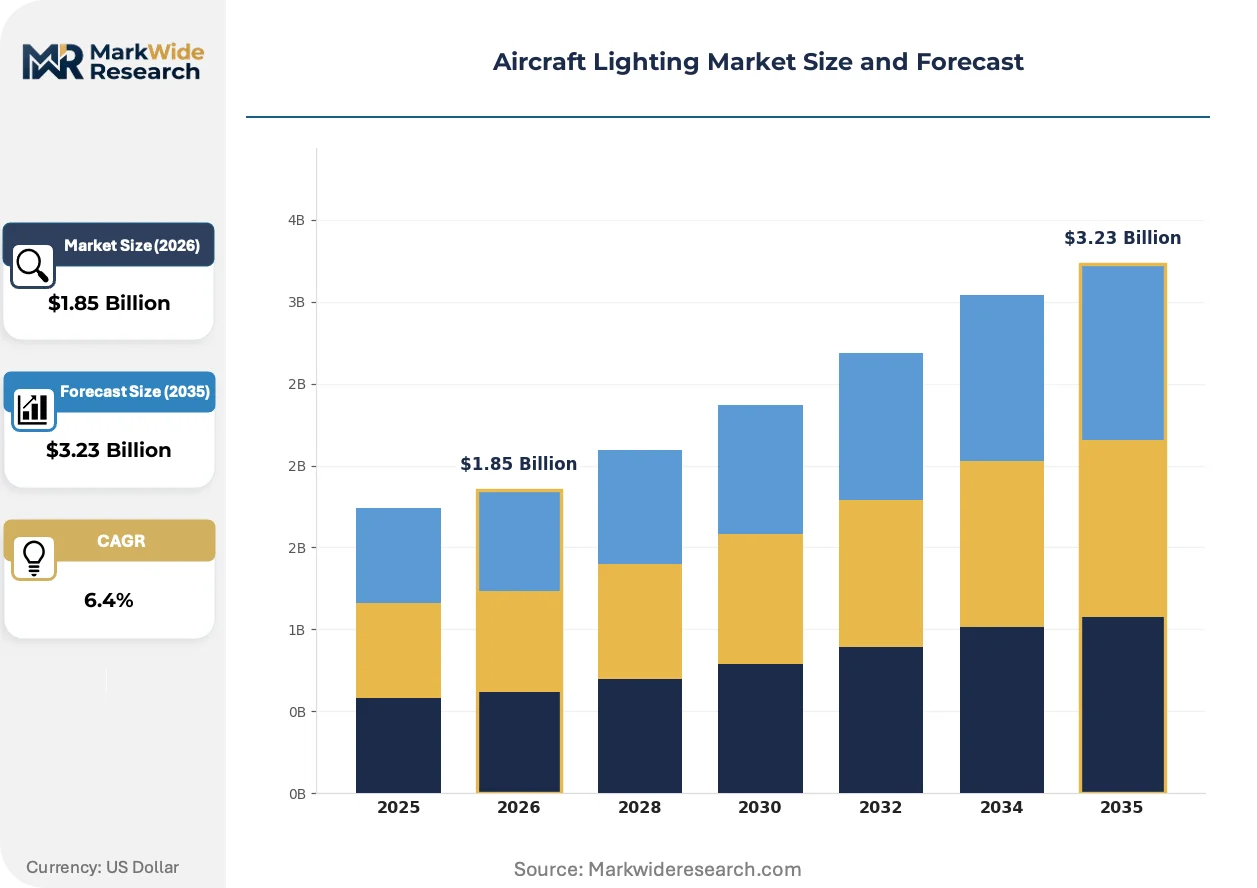
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exterior Lighting, Interior Lighting, Instrument Panel Lighting, Emergency Lighting, Cabin Lighting Technology: LED, Halogen, Fluorescent, Xenon, OLED Application: Commercial Aircraft, Military Aircraft, Private Jets, Helicopters, Spacecraft End User: Airline Operators, Defense Forces, Charter Service Providers, Aerospace Manufacturers, Maintenance Providers |
| Companies Covered | Astronics Corporation, Collins Aerospace, Safran, Honeywell International Inc., Diehl Stiftung & Co. KG, Cobham, STG Aerospace, AeroLEDs, Whelen Aerospace Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Lighting Market Strategic Shifts & Innovations
Solid-state illumination architectures are compressing the competitive moat between avionics incumbents and specialized lighting suppliers. Three forces are redistributing value capture across the supply chain.
Micro-LED matrix arrays is electrifying exterior navigation and landing light applications. Regional jet operators are specifying these emitters for reduced maintenance intervals and improved beam steerability. The technology is electrifying supplier selection criteria, compressing qualification advantages previously held by incandescent specialists.
CSRD disclosure requirements are reshaping procurement specifications for European flag carriers. Scope 3 emissions tracking now extends to installed cabin equipment, forcing suppliers to document manufacturing carbon intensity. Long-haul fleet renewal programs at Lufthansa and Air France-KLM are prioritizing lighting architectures with verified lifecycle assessments.
Airline technical procurement teams are consolidating vendor relationships around integrated platform suppliers. Legacy point-solution lighting contracts are giving way to multi-system avionics packages. This concentration is most visible at US network carriers, where maintenance cost reduction targets favor single-source accountability across exterior, interior, and emergency illumination systems.
Aircraft Lighting Market Segmentation
Aircraft lighting procurement splits across embedded avionics packages and standalone replacement units. Each segmentation axis reveals distinct margin structures, qualification barriers, and supplier concentration patterns that reshape competitive positioning.
Product Type:
Integration depth varies sharply across product categories, with exterior systems typically embedded in wing-root assemblies while cabin and emergency units ship as standalone line-replaceable items.
- Exterior Lighting:Navigation, anti-collision, and landing light assemblies mount in wing leading edges and tail structures. FAA-mandated LED retrofits at US network carriers are compressing replacement cycles for strobe and beacon systems.
- Interior Lighting:Overhead ambient, reading, and galley illumination systems integrate with cabin management computers. German flag carriers are specifying tunable-white LED architectures to support circadian rhythm protocols on long-haul routes.
- Instrument Panel Lighting:Cockpit display backlighting employs dimmable electroluminescent strips and LED edge-lit panels. Night-vision compatibility requirements constrain emitter spectra for military variants.
- Emergency Lighting:Floor-path marking and exit sign systems operate on independent battery buses. EASA certification timelines for photometric output validation extend supplier qualification periods.
- Cabin Lighting:Mood and accent illumination architectures increasingly converge with seat-back entertainment controls. OLED adoption in premium cabins concentrates among European fabrication specialists.
Volume placements concentrate in Exterior Lighting; the faster expansion belongs to Cabin Lighting.
Technology:
Cost tier stratification separates mature incumbent technologies from emerging solid-state architectures with divergent qualification burdens and material input exposures.
- LED:Solid-state emitters dominate current procurement volumes across exterior and interior applications. Indium gallium nitride supply concentration in East Asian foundries exposes buyers to single-source geopolitical risk.
- Halogen:Tungsten-filament sealed-beam units persist in legacy fleet maintenance. REACH substrate constraints on legacy coating chemistries are accelerating displacement timelines.
- Fluorescent:Cold-cathode and compact fluorescent architectures retain positions in cargo hold and utility lighting. Mercury content restrictions under EPA frameworks constrain new installations.
- Xenon:High-intensity discharge systems serve specialized landing and searchlight applications. Military night-vision compatibility mandates favor infrared-suppressed spectral outputs.
- OLED:Organic emitter panels enable conformal surface illumination for premium cabin aesthetics. Limited aviation-grade fabrication capacity concentrates margin capture among qualified European suppliers.
Procurement volume clusters in LED; OLED is climbing the fastest despite supplier scarcity constraints.
Application:
Customer type and operational tempo differentiate procurement patterns, with commercial operators prioritizing total cost of ownership while defense buyers emphasize mission-specific performance envelopes.
- Commercial Aircraft:Narrow-body and wide-body fleet operators drive LED retrofit volumes. Narrow-body programs at Indian carriers IndiGo and Air India are generating aftermarket demand for regional MRO networks.
- Military Aircraft:Fighter, transport, and rotary-wing platforms demand infrared-suppressed and NVG-compatible illumination. Faster retrofit cycles reflect night-vision goggle mandate evolution.
- Private Jets:Business aviation operators specify customizable cabin lighting architectures. Premium segment buyers are integrating OLED mood systems with personalized entertainment controls.
- Helicopters:Rotorcraft applications require vibration-resistant mounting and redundant electrical paths. Search and rescue operators prioritize high-intensity landing light performance.
- Spacecraft:Crewed and uncrewed vehicles demand radiation-hardened emitters with extreme thermal cycling tolerance. Qualification protocols exceed commercial aviation timelines substantially.
Revenue concentration sits with Commercial Aircraft; Military Aircraft exhibits the steepest expansion trajectory.
End User:
Supply chain access and technical specification authority fragment across end-user categories, with OEMs controlling initial fitment and operators driving aftermarket retrofit decisions.
- Airline Operators:Network and low-cost carriers control retrofit timing and vendor selection for in-service fleets. US major carriers are consolidating vendor relationships around integrated platform suppliers.
- Defense Forces:Military procurement agencies specify mission-critical performance parameters and security-cleared supply chains. Night-vision compatibility mandates reshape emitter qualification protocols.
- Charter Service Providers:Fractional ownership and on-demand operators prioritize rapid turnaround and standardized maintenance. Cabin customization demands drive specification diversity.
- Aerospace Manufacturers:Airframe OEMs control initial lighting system selection and integration architecture. Platform-level avionics packages are displacing point-solution lighting contracts.
- Maintenance Providers:MRO networks manage line-replaceable unit logistics and airworthiness directive compliance. Indian domestic MRO capacity expansion is capturing narrow-body lighting demand.
Procurement authority concentrates in Airline Operators; Maintenance Providers are gaining share fastest as fleet ages extend.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium gallium nitride foundries in East Asia supply the high-brightness LED dies that power next-generation aircraft illumination systems. Procurement patterns cluster around three regulatory jurisdictions with divergent certification timelines and fleet modernization priorities.
United States
Narrow-body fleet operators at Delta, United, and American Airlines are accelerating LED retrofit programs to comply with FAA airworthiness directives on anti-collision systems. The FAA mandates stricter photometric output standards for emergency egress illumination by 2027. Wichita, Kansas anchors the maintenance, repair, and overhaul cluster where regional MRO networks process lighting line-replaceable units.
Germany
Lufthansa Group's long-haul fleet renewal prioritizes cabin lighting architectures with verified lifecycle assessments under CSRD sustainability disclosure rules. EASA certification specifications extend photometric calibration testing to 18-24 months for new entrants. Hamburg's aviation manufacturing corridor concentrates final assembly integration for Airbus platforms with embedded exterior illumination systems.
France
Air France-KLM procurement teams consolidate vendor relationships around integrated platform suppliers to reduce maintenance cost complexity. REACH substrate constraints on legacy coating chemistries favor solid-state alternatives with compliant material footprints. Toulouse hosts the airframe engineering cluster where initial lighting system selection occurs for next-generation narrow-body programs.
India
IndiGo and Air India narrow-body orders from Airbus and Boeing generate aftermarket lighting demand for emerging regional MRO networks. The country's national aviation regulator aligns certification protocols with EASA specifications to accelerate supplier qualification. Bangalore and Hyderabad concentrate technical procurement teams for domestic carriers expanding fleet capacity.
United Kingdom
BAE Systems and defense procurement agencies specify night-vision goggle compatible illumination for military rotorcraft and fast-jet platforms. The Civil Aviation Authority enforces electromagnetic interference standards that constrain emitter spectra for cockpit display backlighting. Bristol's aerospace engineering cluster specializes in infrared-suppressed exterior lighting for special mission aircraft.
Aircraft Lighting Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue OLED cabin aesthetics and micro-LED exterior applications. The supplier base stratifies across three tiers: integrated avionics platforms, specialized lighting architects, and regional component fabricators. Dominant competitive moves include consolidation around multi-system contracts and capacity expansion for solid-state emitter manufacturing.
Among integrated platform suppliers, Collins Aerospace and Honeywell International Inc. represent the avionics bundling archetype where lighting contracts merge with flight control and cabin management systems. Safran occupies a position within the European specialist tier, anchoring supply chains through cockpit and cabin lighting architectures. Diehl Stiftung & Co. KG exemplifies the family-owned engineering conglomerate model with captive aerospace electronics capabilities.
| Leading Market Players |
|---|
| Astronics Corporation |
| Collins Aerospace |
| Safran |
| Honeywell International Inc. |
| Diehl Stiftung & Co. KG |
| Cobham |
| STG Aerospace |
| AeroLEDs |
| Whelen Aerospace Technologies |
| Others |
Cost & Logistics Intelligence
Optical engineering talent concentration in Germany's Hamburg aviation corridor drives labor-cost differentials that widen pricing-tier spreads between premium-certified LED architectures and commodity retrofit units. FAA and EASA certification timelines compress margin structures for mid-tier suppliers unable to amortize qualification costs across high-volume production runs.
Pricing Analysis
Warranty and service-bundling arrangements separate contract structures, with integrated platform suppliers like Collins Aerospace and Honeywell packaging multi-year airworthiness support while specialized lighting architects compete on unbundled hardware transactions. Three-tier pricing structure across premium-certified, standard-compliant, and economy retrofit levels reflects differentiation by EASA qualification depth and OEM airframe integration complexity. Pricing pressure stems from LED die commoditization as East Asian foundries expand high-brightness indium gallium nitride capacity. Low-cost carriers and regional MRO networks exhibit highest price sensitivity; defense procurement agencies and premium cabin specifiers demonstrate lowest elasticity.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for aerospace components are reshaping sourcing patterns, compelling suppliers to establish local assembly operations for narrow-body retrofit programs. Indium gallium nitride wafer fabrication concentrates in Taiwan, South Korea, and China; aviation-grade OLED panel production clusters in Germany and France. Critical dependencies include rare-earth phosphors, precision optical lenses, and conformal coating chemistries. Single-source vulnerability runs through East Asian LED die foundries exposed to geopolitical trade restrictions. Distribution runs through airframe OEM integrated avionics packages, regional MRO line-replaceable unit networks, and direct procurement by flag carrier technical teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
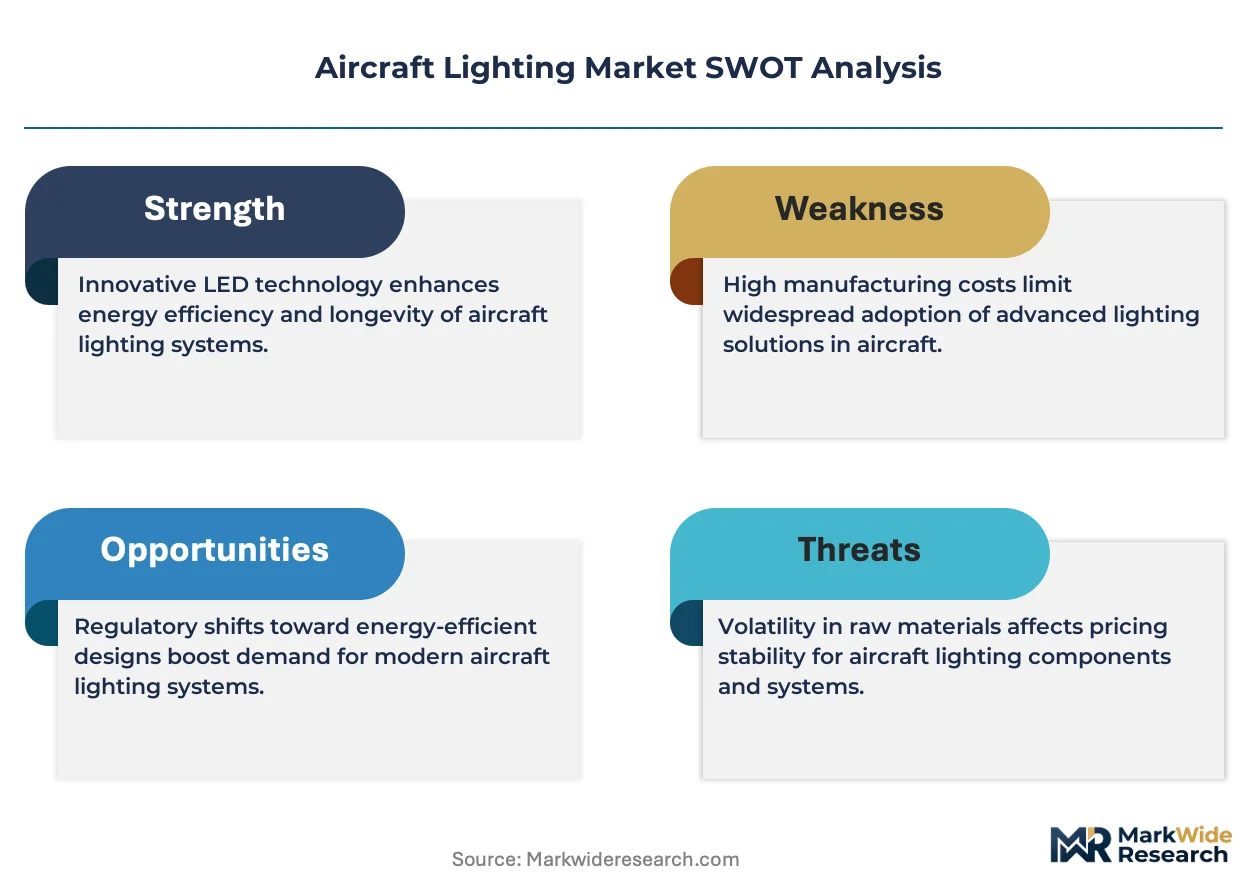
The aircraft lighting sector sits in a technology-transition phase as solid-state LED architectures displace legacy halogen and fluorescent systems across commercial and military fleets.
For Market Incumbents: Lock in long-term platform integration contracts with Airbus and Boeing to defend against specialized lighting suppliers exploiting solid-state photometric advantages. Deepen backward integration into indium gallium nitride packaging to mitigate East Asian foundry concentration risk. Accelerate EASA certification investments for OLED cabin architectures before European fabrication capacity expands. For New Entrants and Emerging Players: CSRD sustainability disclosure rules in Europe open a window for suppliers offering verified lifecycle assessment documentation to Lufthansa and Air France-KLM procurement teams. Target India's emerging MRO networks serving IndiGo and Air India narrow-body fleets as the most penetrable geography. Pursue military night-vision compatibility qualification as a differentiated go-to-market angle against commercial-focused incumbents. For Investors and Strategic Acquirers: Re-rating potential sits with OLED fabrication specialists given premium cabin convergence with seat-back entertainment controls and limited qualified supplier scarcity. Long-term viability favors targets with captive optical engineering talent and EASA certification track records. Watch for inflection in military retrofit cycle acceleration as night-vision goggle mandates evolve across NATO procurement agencies.| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Program Expansion | FAA mandates at Delta and United compress replacement cycles and consolidate vendor relationships. |
| OLED Cabin Architecture Development | European fabrication specialists capture margin pools from Air France-KLM premium specifications. |
| Indium Gallium Nitride Supply Diversification | Backward integration mitigates Taiwan and South Korea foundry concentration risk for Collins Aerospace. |
| EASA Certification Investment | Eighteen-month qualification timelines create defensive moats against mid-tier lighting entrants. |
| Indian MRO Network Partnership | Domestic fleet expansion at IndiGo generates aftermarket lighting demand for regional maintenance providers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with avionics procurement directors, MRO maintenance planners, optical engineering specialists, and FAA certification consultants combined with bottom-up fleet data and top-down aerospace production statistics. Secondary sources encompassed EASA certification specifications, FAA airworthiness directives, REACH substrate restriction databases, and carrier fleet renewal disclosures. Triangulation across these inputs validated segment-level sizing and growth trajectory assumptions.
Granularity-level modeling deployed product-type, technology, application, and end-user dimensions at the country level across the projection horizon. Commercial aircraft LED retrofit volumes, military night-vision compatibility upgrade cycles, and OLED cabin adoption curves in premium segments informed analytical framework construction. CAGRs derived from fitted trend extrapolation cross-checked against fleet age profiles and regulatory mandate timelines. Indium gallium nitride supply elasticity and EASA certification queue lengths served as industry-specific forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for OLED penetration in narrow-body cabins would alter the outlook. Forecasts reflect assumptions around LED die cost trajectories, REACH enforcement intensity, and military procurement budget continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Legal Services Market
Others
8K Technology Market
Others
Middle East and Africa Home Care Packaging Market
Others
Global Hair Loss Treatment Products Market
Others
Kuwait Retail Market
Others
Global Injectable Nanomedicine Market
Others
Gem Faceting Machine Market
Others
Hot Air System Market
Others
Mine Rescue Vehicle Market
Others
Synthetic Leather Market
Others
Global Alpha Cypermethrin Market
Others
Binoculars Market
Others
Brazil Lime Market
Others
Photo Booth/Kiosk Market
Others
Europe Military 4D Printing Market
Others
DIY Smart Home Market