
 Mine Rescue Vehicle Market | 2026-2036
Mine Rescue Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Mine Rescue Vehicle Market Intelligence
Specialized manufacturing capacity for low-volume, high-specification vehicles is restructuring around integrated safety system providers. Drägerwerk AG & Co. KGaA leverages its expertise in respiratory and gas detection systems to lead in integrated life support modules. Caterpillar Inc. adapts its proven heavy equipment platforms for rescue applications, offering robust and scalable solutions. Sandvik AB competes on automation and electrification, developing vehicles for increasingly complex underground environments.
A mine rescue vehicle is a purpose-built mobile unit engineered for emergency response within surface or subterranean mining sites. These vehicles typically feature a reinforced chassis, independent onboard air supplies, and advanced sensor suites for gas detection. Their primary function is to facilitate personnel evacuation, deliver first aid, and perform structural assessments during incidents. Underground Rescue Vehicles constitute the largest vehicle type segment, while demand for Electric Motor powertrains is accelerating to improve air quality and reduce fire risk in confined spaces.
A complex web of national regulations governs vehicle design and deployment. Standards set by the US Mine Safety and Health Administration (MSHA) and Australia's state-level Work Health and Safety acts mandate specific vehicle capabilities. These regulations directly shape equipment requirements for mining companies globally, influencing everything from fire suppression systems to crew cabin integrity. The critical decision for operators involves balancing the initial capital outlay for advanced, compliant vehicles against the total cost of ownership and risk mitigation benefits.
Market Dynamics
The central force shaping the mine rescue vehicle market is the dual pressure from stringent safety regulations and the operational necessity of accessing deeper, more remote mineral deposits. This compels mining operators to invest in technologically advanced, highly compliant emergency response assets.
Growth Catalysts
- Regulatory Mandates:Stricter environmental policies, including China's dual carbon goals, are accelerating the transition to battery-electric powertrains to reduce emissions and fire hazards in confined underground spaces, creating demand for new vehicle architectures.
- Deep-Earth Mining Expansion:The growth of deep and remote mining operations in geographies such as Australia and Chile necessitates vehicles with extended operational ranges, independent life support, and robust chassis to navigate complex subterranean environments.
- Integrated Safety Systems:The adoption of advanced sensor suites for real-time gas detection and structural monitoring requires vehicles that can serve as mobile data and communication hubs, driving demand for digitally integrated platforms.
Market Restraints
- High Capital Outlay:The significant initial investment required for vehicles compliant with rigorous standards, such as those from the US Mine Safety and Health Administration (MSHA), presents a substantial financial barrier for small and mid-sized mining operators.
- Infrastructure Limitations:The lack of reliable charging infrastructure for electric vehicles in remote, off-grid mining sites constrains the adoption of battery-electric models, despite their operational and environmental benefits.
- Specialized Supply Chain:Production of critical components like reinforced crew cabins and integrated respiratory systems is concentrated among a few suppliers, creating risks of production delays and price volatility for vehicle manufacturers.
Strategic Opportunities
- Autonomous Systems Integration:Developing vehicles with semi-autonomous or remote-control capabilities offers a significant opportunity to conduct initial assessments and clear pathways in hazardous zones without risking the lives of rescue personnel.
- Fleet Modernization Programs:Government-backed or corporate-wide fleet modernization initiatives in established mining regions provide a clear pathway for introducing next-generation vehicles with enhanced safety and communication features.
- Modular Vehicle Design:Creating configurable vehicle platforms that allow mining companies to customize modules for specific needs, such as first aid, firefighting, or equipment transport, can address diverse operational requirements and expand market reach.
Industry Challenges
- Technical Skills Gap:A persistent shortage of technicians qualified to service and maintain the complex electronic, battery, and software systems of modern mine rescue vehicles creates operational bottlenecks and increases total cost of ownership. *Legacy System Interoperability: Ensuring new, digitally advanced vehicles can seamlessly communicate with older, analog-based mine-wide tracking and communication systems is a significant technical and logistical hurdle for operators during fleet upgrades.
Report Scope
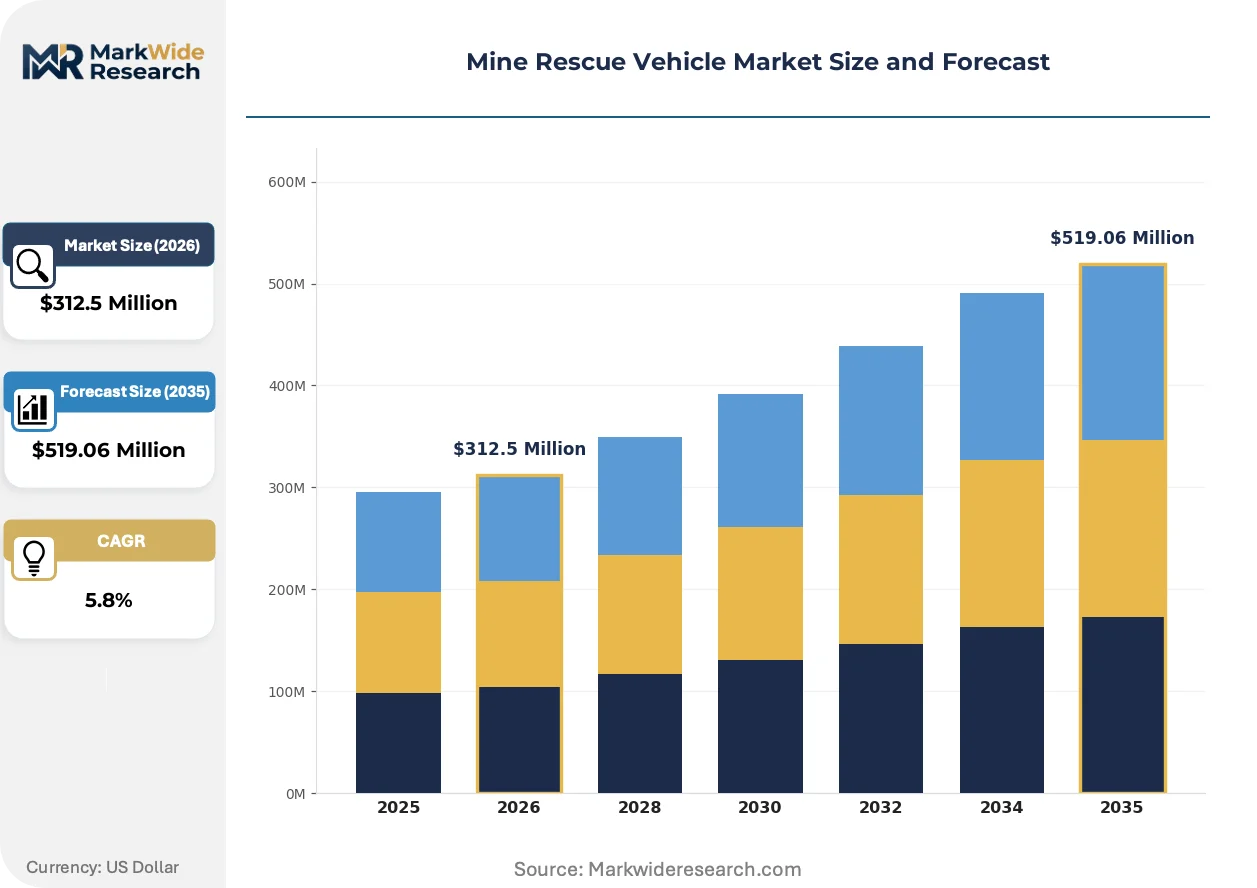
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mine Rescue Vehicle Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Surface Mine Rescue Vehicle, Underground Rescue Vehicle, All-Terrain Rescue Vehicle, Armored Rescue Vehicle Power Source: Diesel Engine, Electric Motor, Hybrid Powertrain, Compressed Natural Gas, Fuel Cell Application: Emergency Evacuation, Firefighting, Gas Detection, First Aid Delivery, Structural Stability Assessment End User: Mining Companies, Safety Agencies, Government Bodies, Private Security Firms |
| Companies Covered | Drägerwerk AG & Co. KGaA, Caterpillar Inc., Hermann Paus Maschinenfabrik GmbH, Sandvik AB, Komatsu Ltd., MacLean Engineering, Normet Group Oy, Getman Corporation, Arva Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mine Rescue Vehicle Market Strategic Shifts & Innovations
Technological advancements in life support and automation are converging with evolving operational demands for greater safety and efficiency. This synthesis is producing a new generation of rescue vehicles designed for resilience in increasingly complex and hazardous underground mining environments.
Onboard air regeneration technology, which scrubs carbon dioxide and replenishes oxygen within a sealed cabin, is a critical innovation. Deep-mine operators are the primary adopters, seeking to extend mission duration without reliance on external air sources. This capability is decentralizing life support from fixed refuge chambers to mobile vehicle platforms, providing unprecedented operational flexibility during an emergency.
Regulatory frameworks are tightening vehicle safety specifications globally. Australia's state-level Work Health and Safety (WHS) acts, for example, are imposing stricter requirements for cabin integrity, fire suppression systems, and fail-safe braking. This directly impacts the Underground Rescue Vehicle segment, compelling manufacturers to re-engineer chassis and safety systems to meet new compliance benchmarks.
A notable shift in acquisition models sees operators moving from direct capital purchases toward long-term leasing and comprehensive service agreements. This change disrupts the traditional equipment sales channel by bundling maintenance, compliance updates, and technician training into a single operational expense. This trend is most pronounced in major mining economies where operators prioritize asset uptime and risk transfer.
Mine Rescue Vehicle Market Segmentation
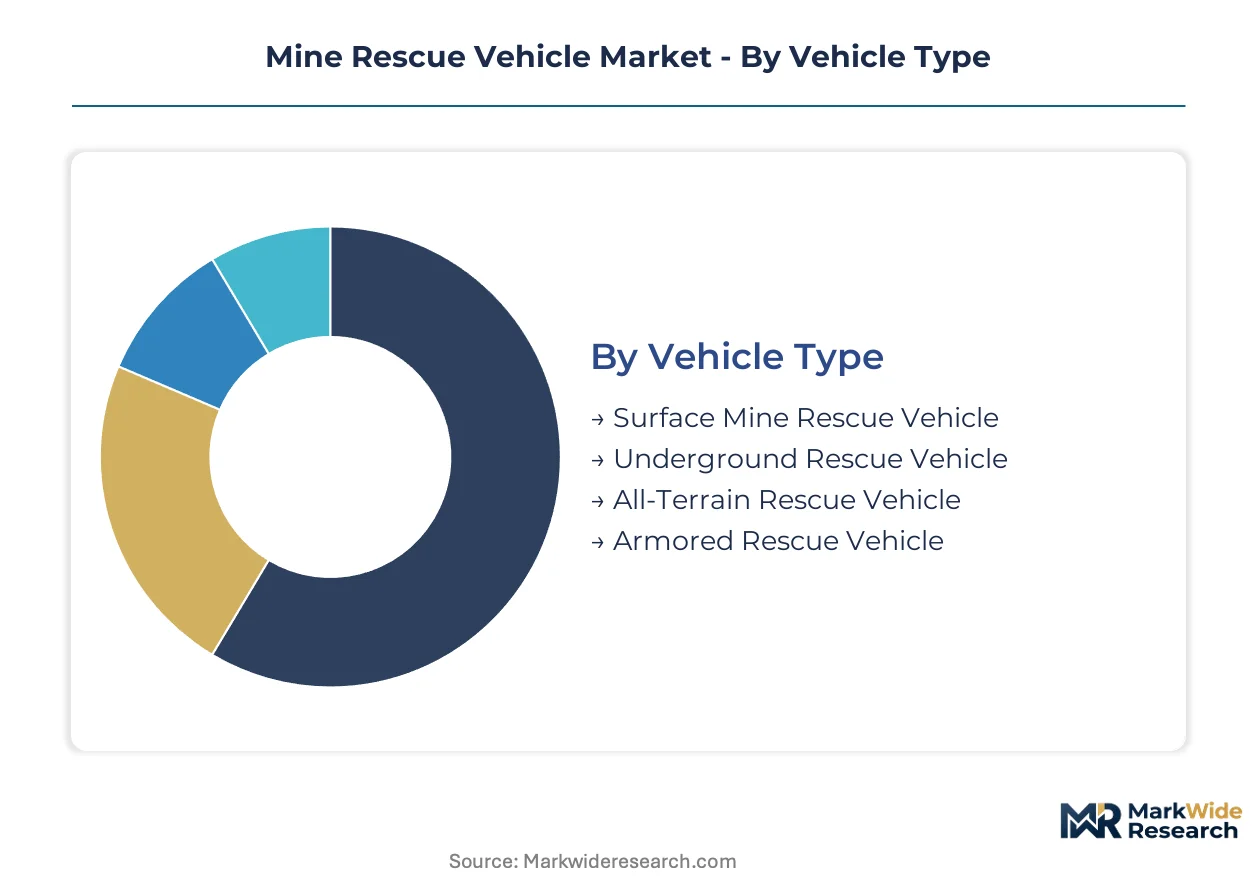
The mine rescue vehicle market segmentation provides critical insights into specialized equipment needs across diverse operational environments. Understanding these distinct segments allows manufacturers to tailor robust solutions that meet stringent safety standards and address unique geological and regulatory challenges in mining operations worldwide.
Vehicle Type:
Compliance with national and regional vehicle certification standards, such as those from the US Mine Safety and Health Administration (MSHA) and Australia's state-level Work Health and Safety (WHS) acts, heavily influences procurement decisions across vehicle types.
- Underground Rescue Vehicle:These purpose-built units are engineered with reinforced chassis, independent onboard air supplies, and advanced sensor suites for subterranean environments. Demand from deep-mine operators in Australia and Chile drives investment in these vehicles, which offer extended operational ranges and robust navigation capabilities in complex tunnels.
- All-Terrain Rescue Vehicle:Designed for navigating challenging surface and open-pit mining landscapes, these vehicles feature enhanced suspension systems and high ground clearance. Operators in remote mining regions, including parts of Canada and South Africa, prioritize these vehicles for rapid response across varied topography and unimproved roads.
- Surface Mine Rescue Vehicle:These vehicles are adapted from commercial platforms, equipped with basic rescue capabilities for accessible surface mining incidents.
- Armored Rescue Vehicle:Offering ballistic protection, these specialized vehicles are deployed in high-risk zones, often in conflict-affected mining regions.
Underground Rescue Vehicles sit at the top of the volume ranking, with All-Terrain Rescue Vehicles climbing the fastest due to expanding remote operations.
Power Source:
Operational efficiency and environmental compliance considerations dictate the selection of power sources, with a clear shift towards cleaner energy solutions impacting vehicle design and infrastructure development.
- Electric Motor:Utilizing battery-electric powertrains, these vehicles produce zero emissions at the point of use, significantly improving air quality and reducing fire risk in confined underground spaces. Mining companies in China and Europe are increasingly adopting electric motors, driven by stringent environmental policies and dual carbon goals.
- Diesel Engine:Historically the dominant power source, diesel engines offer robust power and extended operational range, particularly in remote areas with limited charging infrastructure. Operators in established mining regions like the US and Brazil continue to rely on diesel for heavy-duty applications and proven reliability.
- Hybrid Powertrain:Combining internal combustion with electric motors, hybrid systems offer a balance of range and reduced emissions, providing a transition solution for many operators.
- Compressed Natural Gas:CNG-powered vehicles offer lower emissions compared to diesel, finding niche applications where CNG infrastructure is readily available.
- Fuel Cell:Hydrogen fuel cell technology is emerging as a long-term, zero-emission solution, offering rapid refueling and extended range for future underground operations.
Diesel Engine powertrains currently hold the largest share, while Electric Motor powertrains exhibit the steepest expansion trajectory.
Application:
The primary function required of a mine rescue vehicle shapes its design and specialized equipment, reflecting the diverse emergency scenarios encountered in mining operations.
- Emergency Evacuation:Vehicles configured for emergency evacuation prioritize rapid and safe transport of personnel from hazardous areas, featuring reinforced crew cabins and independent life support modules. This application is paramount for all mining operations, driven by MSHA regulations and Australia's WHS acts that mandate quick egress.
- Gas Detection:Equipped with advanced sensor suites, these vehicles provide real-time monitoring and analysis of atmospheric conditions, identifying dangerous gases and oxygen deficiencies. Mining companies in deep-earth operations, particularly in Chile and South Africa, rely on these systems to assess and map hazardous zones before personnel entry.
- Firefighting:These vehicles integrate specialized fire suppression systems and water/foam delivery capabilities for combating underground or surface fires.
- First Aid Delivery:Designed to transport medical personnel and equipment, these units provide immediate on-site treatment for injured miners.
- Structural Stability Assessment:Vehicles equipped with laser scanners and ground-penetrating radar assess structural integrity after incidents, preventing further collapses.
Emergency Evacuation represents the largest application segment, with Gas Detection capabilities showing significant investment due to integrated safety system trends.
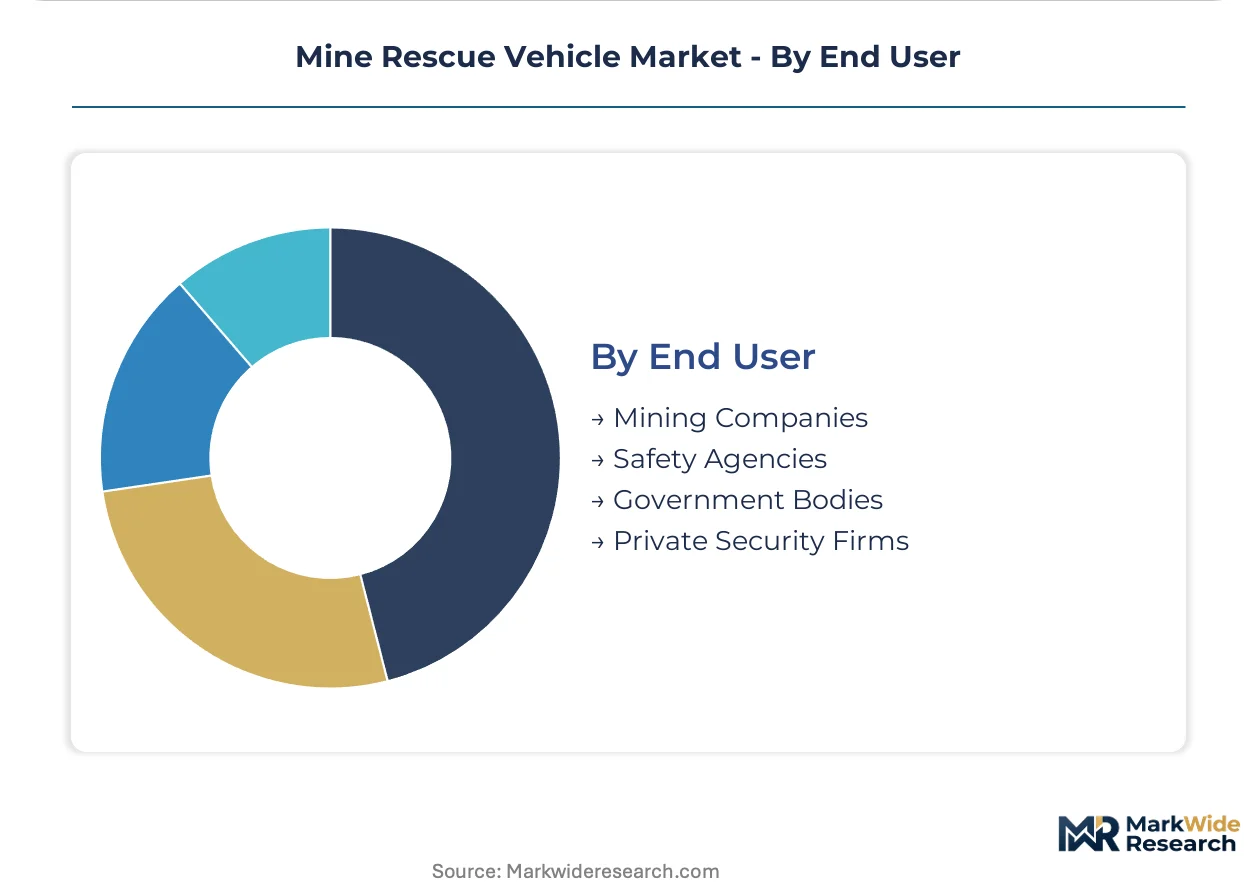
End User:
The procurement and deployment of mine rescue vehicles vary significantly based on the organizational structure and regulatory obligations of the end-user entity.
- Mining Companies:These are the direct purchasers and primary operators of mine rescue vehicles, integrating them into their comprehensive safety and emergency response plans. Large-scale mining companies globally, particularly those with deep and remote operations, drive demand for advanced, compliant vehicles to mitigate operational risks.
- Safety Agencies:Government or independent regulatory bodies and specialized rescue services utilize these vehicles to provide support, training, and direct intervention during major incidents. Agencies in established mining economies such as the US and Australia often maintain their own fleets to assist smaller operators or provide regional response.
- Government Bodies:National and regional government departments procure vehicles for civil defense, disaster response, or to equip state-owned mining entities.
- Private Security Firms:In certain regions, private security contractors operating within mining concessions acquire rescue vehicles for localized emergency response.
Mining Companies constitute the largest end-user segment, while Safety Agencies are steadily increasing their procurement of specialized units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Australia's mining sector prioritizes advanced response capabilities for deep-earth operations, China's focus on environmental mandates drives demand for electric powertrains. This global market for mine rescue vehicles reflects diverse regional priorities influenced by geological conditions, regulatory frameworks, and technological adoption rates.
Australia
Demand for robust underground vehicles stems from extensive deep-mine operations across Australia. Australia's state-level Work Health and Safety (WHS) acts mandate stringent safety specifications for cabin integrity and fire suppression. Western Australia's Pilbara region, a major iron ore hub, sees continuous investment in compliant rescue fleets.
Chile
Operators in Chile require vehicles with extended operational ranges for remote copper mines. The country's mining regulations, often influenced by MSHA standards, emphasize independent life support systems and robust chassis. The Antofagasta region, a key mining center, procures specialized units for high-altitude subterranean environments.
China
Stricter environmental policies in China accelerate the adoption of battery-electric powertrains. China's dual carbon goals specifically drive the transition to zero-emission vehicles in underground settings. Inner Mongolia, a significant coal mining province, actively upgrades its rescue fleet with electric models.
United States
Mining companies in the United States invest in highly compliant vehicles for varied geological conditions. Standards set by the US Mine Safety and Health Administration (MSHA) dictate specific vehicle capabilities, including fire suppression systems and crew cabin integrity. Appalachia's coalfields, a historical mining area, see ongoing modernization of rescue assets.
South Africa
Deep-level gold and platinum mines in South Africa necessitate specialized vehicles for complex subterranean rescues. The country's Mine Health and Safety Act mandates advanced sensor suites for gas detection and structural monitoring. The Witwatersrand Basin, a historic gold mining region, focuses on integrated safety system procurement.
Mine Rescue Vehicle Market Key Industry Players
European producers anchor one tier of specialized mine rescue vehicle manufacturing; North American specialists hold strong positions in robust equipment adaptation. The market structure exhibits a tiered approach, with established heavy equipment manufacturers alongside niche providers of integrated safety systems. Strategic archetypes include diversified industrial conglomerates and focused engineering firms. Companies pursue geographic expansion and technology integration to enhance their offerings.
Within the integrated safety solutions tier, Drägerwerk AG & Co. KGaA, a German-based AG & Co. KGaA, exemplifies leadership in life support modules. Caterpillar Inc., a US-based Inc., represents the heavy equipment adaptation archetype, leveraging its proven platforms for robust and scalable rescue applications. Sandvik AB, a Swedish-based AB, occupies a position among specialists in automation and electrification, developing vehicles for increasingly complex underground environments. These entities collectively demonstrate the diverse approaches to addressing the stringent safety and operational requirements of the mine rescue vehicle market.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Caterpillar Inc. |
| Hermann Paus Maschinenfabrik GmbH |
| Sandvik AB |
| Komatsu Ltd. |
| MacLean Engineering |
| Normet Group Oy |
| Getman Corporation |
| Arva Industries Inc. |
| Others |
Cost & Logistics Intelligence
China's dual carbon goals, for instance, gate qualified battery-electric powertrain suppliers, thereby enabling premium-tier pricing access for compliant vehicle models. This mandate influences both component sourcing and final product cost for mine rescue vehicles.
Pricing Analysis
Capacity additions in specialized component manufacturing across Europe are reshaping price floors for integrated safety systems. Contract-based long-term offtake dominates, driven by high R&D and certification costs for purpose-built equipment. Certification level from MSHA or Australia's WHS acts and comprehensive after-sales service bundling command premium pricing. Pricing pressure stems from the significant initial capital outlay for operators, especially for smaller mines. Small and mid-sized mining operators are most price-sensitive, while large-scale mining companies prioritize compliance and advanced features.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of reinforced crew cabins in Germany and Sweden. Component supply concentrates in Germany, Sweden, and Finland for advanced life support modules and heavy-duty chassis. Raw material dependencies include high-strength steel alloys and specialized filtration media for air regeneration systems. Logistics chokepoints for oversized components pose a structural risk to delivery schedules. Distribution runs through direct sales channels to large mining companies and through regional distributors for smaller operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, driven by a demand-shift toward premium specifications for advanced integrated safety systems. Mining companies prioritize compliance and operational resilience over initial capital outlay.
For Market Incumbents: Deepen integration with mining operators to co-develop next-generation vehicle platforms. Focus on modular vehicle design to counter emerging entrant archetypes offering niche solutions. Invest in advanced battery technology R&D to mitigate the threat of range limitations in deep mines. Leverage existing heavy equipment platforms to maintain cost advantages against specialized safety system providers.
For New Entrants and Emerging Players: Begin with specialized offerings for the rapidly expanding Electric Motor powertrain segment. Target underpenetrated remote mining operations in Canada and South Africa with modular, easily deployable charging solutions. A go-to-market angle involves bundling vehicle sales with long-term service agreements and technician training. Focus on the firefighting application segment which requires specific, high-specification vehicles.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap specialists in niche component manufacturing, particularly for integrated life support systems. The long-term viability of the market is anchored by non-discretionary safety spending and tightening regulations over the next decade. Monitor regulatory updates from the US Mine Safety and Health Administration (MSHA) as a key inflection indicator for compliance-driven demand. Acquire firms with proven expertise in autonomous systems integration.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Battery-Electric Powertrain Portfolio | Addresses stringent environmental mandates and reduces operational risks in underground mining environments. |
| Invest in Autonomous Systems R&D | Enables safer initial assessments in hazardous zones, reducing human exposure during emergencies. |
| Develop Modular Vehicle Platforms | Offers customization for diverse operational needs, expanding market reach across various mining applications. |
| Strengthen After-Sales Service Networks | Ensures high asset uptime and compliance for complex vehicles, critical for remote mining operations. |
| Pursue Strategic Partnerships with Sensor Providers | Enhances real-time gas detection and structural monitoring capabilities, vital for deep-earth mining. |
Research Approach
Bottom-up mining company procurement modeling reconciled against top-down vehicle manufacturing tracking forms the analytical core of this study. Primary interviews with mining safety managers, procurement officers, and vehicle R&D leads provided qualitative insights. Secondary validation drew from MSHA reports, Australian WHS act documentation, and company financial filings. This dual approach ensured robust data triangulation.
An input-output matrix framing structured the quantitative forecast modeling. The analytical framework projected market evolution across the analysis window, segmented by vehicle type, power source, application, and end-user. Compound annual growth rates were derived from historical trends and projected operational shifts. Key inputs included mineral production forecasts and regulatory compliance timelines.
Caveats apply where rapid technological advancements or unforeseen regulatory shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding market dynamics and operator investment patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
5G Devices Market
Others
Smart Badge Market
Others
Mobile Computing Devices Market
Others
TWS Micro-Battery Market
Others
Global Luxury High End Furniture Market
Others
Global Multi Domain Controller Market
Others
Bitcoin Mining Servers Market
Others
Global Hair Loss Treatment Products Market
Others
5G Smartphone Market
Others
Global Flexible PVC Films Market
Others
Global Application Testing Services Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Level Measuring Instrument Market
Others
Europe Air Separation Unit Market
Others
Europe Indoor Air Purification Market
Others
Cryogenic Storage Tanks Market