
 Gem Faceting Machine Market | 2026-2036
Gem Faceting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Gem Faceting Machine Market Insights
ISO 9001 quality management certification is redrawing competitive boundaries in the gem faceting machine sector. Ultra Tec leverages its California-based manufacturing to sustain premium positioning among North American artisans. Zhuode Gem & Jade Machinery anchors supply chains across Asian markets through direct factory channels. Fujian Aite Precision Machinery Co., Ltd. specializes in CNC platforms that dominate industrial jewelry manufacturing workflows.
A gem faceting machine is a precision cutting apparatus that mounts rough gemstones on a dop stick and indexes them against a rotating lap impregnated with diamond abrasive, achieving facet angles within 0.1-degree tolerance to maximize optical brilliance and carat retention. The equipment serves commercial gemcutting operations, custom jewelry studios, and vocational training institutions requiring repeatable, high-yield material processing. Manual and semi-automatic equipment retains stronghold status among artisan workshops where capital constraints limit CNC adoption, while fully automatic and CNC configurations capture expanding share in volume-oriented jewelry manufacturing. Diamond grinding technology leads installed base metrics, though ultrasonic and laser cutting modalities gain traction in specialty applications involving heat-sensitive or inclusion-rich rough material.
FDA oversight of industrial dust exposure and OSHA machinery safety standards shape equipment design requirements for US-based manufacturers and importers. CE marking under EU machinery directives and REACH substance restrictions govern European market access, compelling redesign of coolant systems and electrical assemblies. India's BIS certification mandates for precision engineering equipment create compliance hurdles that favor established suppliers with testing infrastructure. Stakeholders must weigh certification portfolio breadth against segment-specific R&D allocation as technology transitions fragment traditional equipment categories.
Market Dynamics
ISO 9001 quality management certification is redrawing competitive boundaries in the gem faceting machine sector. Ultra Tec leverages its California-based manufacturing to sustain premium positioning among North American artisans. Zhuode Gem & Jade Machinery anchors supply chains across Asian markets through direct factory channels. Fujian Aite Precision Machinery Co., Ltd. specializes in CNC platforms that dominate industrial jewelry manufacturing workflows.
Growth Catalysts
- BIS Certification Mandates:India's tightening precision equipment standards compel jewelry manufacturers to upgrade from manual to semi-automatic systems, accelerating replacement cycles in Mumbai and Surat cutting clusters.
- Vocational Training Infrastructure:Germany's dual education system sustains artisanal demand through state-funded gemology programs that require standardized faceting equipment for certification pathways.
- Diamond Grinding Advances:Improved abrasive impregnation techniques extend lap lifespan by 40%, reducing per-carat processing costs for commercial operations.
Market Restraints
- Diamond Abrasive Volatility:Synthetic diamond powder prices fluctuate with Chinese supply consolidation, squeezing margin on consumables for equipment vendors.
- CE Marking Complexity:EU machinery directives and REACH substance restrictions force coolant system redesigns, extending product development timelines for European market entry.
- Laser Cutting Substitution:Ultrasonic and laser modalities capture share in heat-sensitive rough processing, threatening installed base expansion for traditional grinding platforms.
Strategic Opportunities
- Brazilian Artisan Expansion:Minas Gerais gemstone belts show underpenetrated demand for mid-tier semi-automatic units among independent cutters serving tourmaline and emerald rough traders.
- OSHA-Compliant Dust Systems:US jewelry manufacturers face FDA industrial exposure limits, creating pull for integrated extraction modules as retrofit upgrades.
- CNC-Laser Convergence:Hybrid platforms combining precision indexing with non-contact finishing address inclusion-rich material previously rejected by conventional methods.
Industry Challenges
- Master Cutter Scarcity:Traditional hand-faceting expertise attrition outpaces vocational program output, creating bottleneck for quality control in hybrid production workflows.
- Multi-Certification Burden:Simultaneous BIS, CE, and OSHA compliance requirements fragment R&D budgets, delaying feature development for mid-cap manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gem Faceting Machine Market |
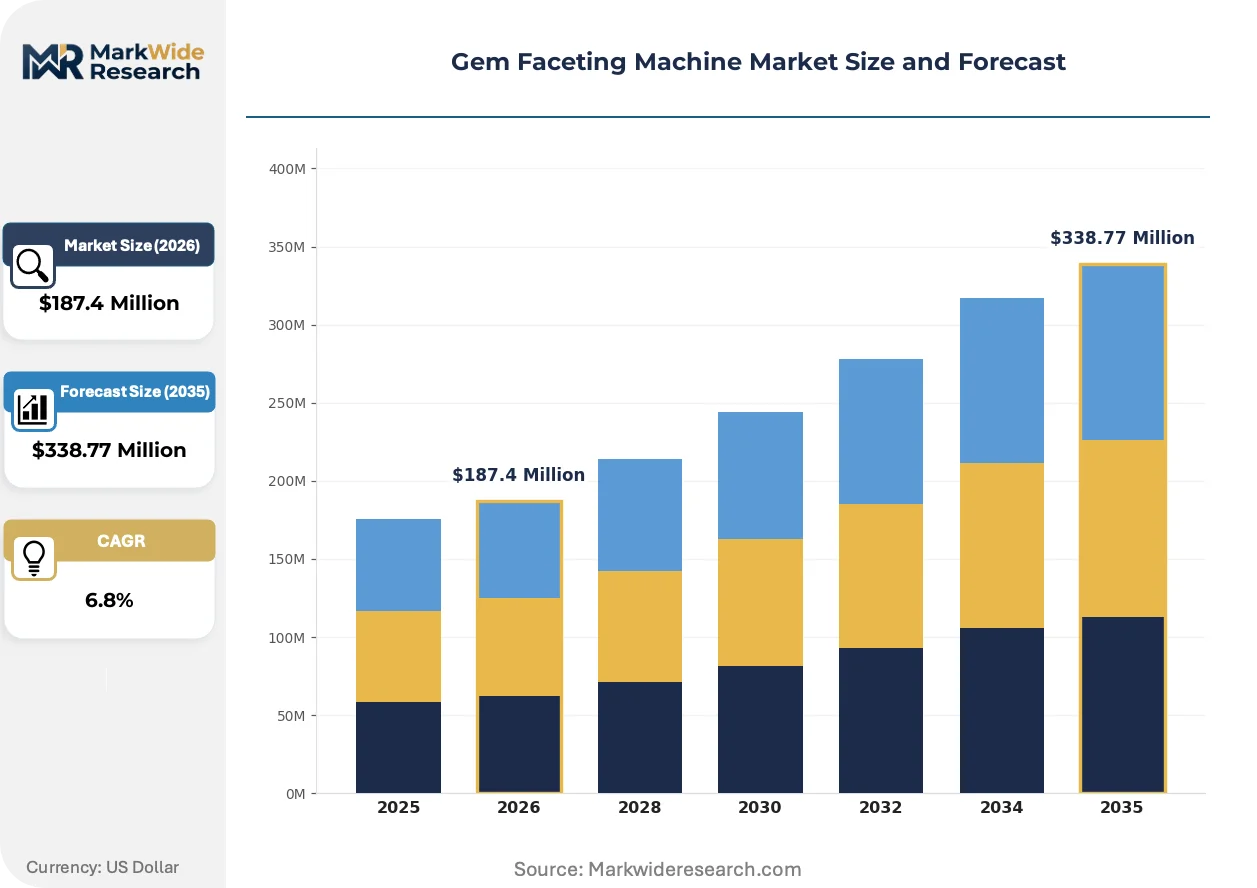
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Semi-Automatic, Fully Automatic, CNC Technology: Diamond Grinding, Laser Cutting, Water Jet, Ultrasonic End User: Jewelry Manufacturers, Artisans, Retailers, Hobbyists Distribution Channel: Online Stores, Specialty Stores, Direct Sales, Distributors |
| Companies Covered | Ultra Tec, Facetron, Polymetric Inc., Sri Rounak Jewellery Equipments, Zhuode Gem & Jade Machinery, Graves, Jersey Instruments, Fujian Aite Precision Machinery Co., Ltd., Shenzhen Hajet Jewelry Equipment Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gem Faceting Machine Market Trends and Innovations
Active technology transitions are fragmenting traditional equipment categories across precision, speed, and automation axes. Regulatory pressure on workplace exposure and material traceability is accelerating platform redesign. Buyer sophistication is compressing switching cycles as certification requirements tighten.
Ultrasonic cutting technology is bifurcating the specialty rough segment from mainstream diamond grinding workflows. Heat-sensitive and heavily included material previously rejected by lap-based processing now commands premium recovery rates in custom jewelry studios. High-value colored stone cutters in Jaipur and Idar-Oberstein are adopting ultrasonic platforms for emerald and tanzanite, compressing addressable market for conventional equipment in this niche.
REACH substance restrictions are compelling coolant chemistry reformulation across European-bound equipment lines. Traditional petroleum-based slurry carriers face substitution with aqueous biodegradable alternatives, requiring pump and seal material upgrades. German and Italian manufacturers are responding fastest, leveraging existing chemical compliance infrastructure to maintain CE marking validity without supply interruption.
Direct factory procurement is displacing distributor networks among volume jewelry manufacturers. Large Mumbai and Bangkok cutting houses now source CNC platforms through Zhuode and Fujian Aite direct channels, extracting 15-20% cost advantages and compressing lead times. After-sales service unbundling follows, with third-party maintenance contractors capturing calibration and repair work previously bundled in distributor margins.
Gem Faceting Machine Market Segmentation
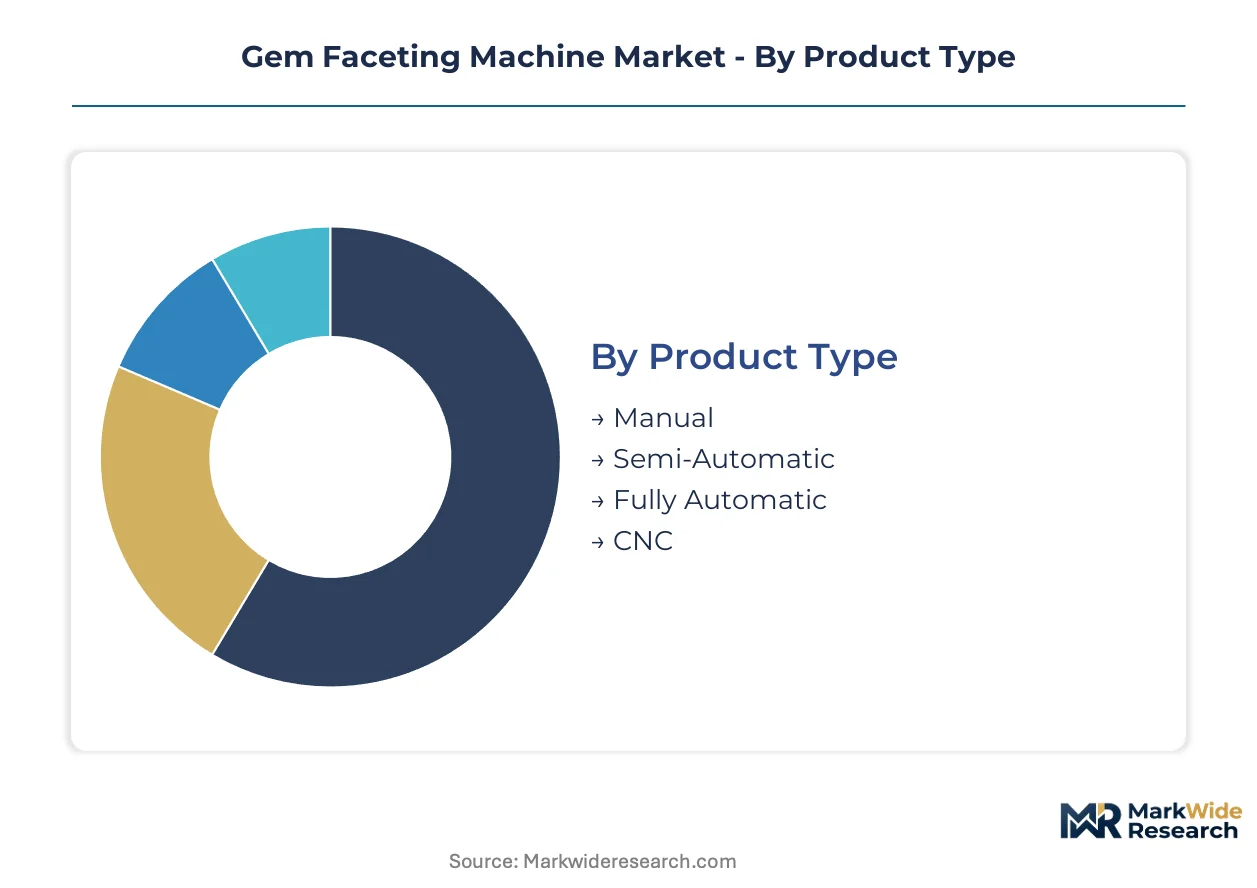
Equipment segmentation in gem faceting machines tracks how automation intensity and precision requirements split buyer budgets across artisan workshops and industrial jewelry houses. Technology modality and channel structure further stratify margin capture between consumables-driven service models and capital-equipment sales.
Product Type:
Margin pools concentrate in semi-automatic and CNC configurations where precision certification requirements justify premium pricing over manual alternatives.
- Manual:Entry-level units employ mechanical indexing heads and hand-cranked rotation mechanisms, achieving facet tolerances of 0.5 degrees. Demand clusters in Indian artisan clusters where BIS certification mandates have not yet displaced traditional equipment, though replacement pressure is mounting.
- CNC:Computer-numerical platforms execute multi-axis cutting programs with 0.02-degree repeatability, integrating vision systems for rough orientation. Jewelry manufacturers in Surat and Bangkok deploy these for diamond melee production where carat retention metrics determine contract viability.
- Semi-Automatic:Motorized lap rotation with manual angle setting bridges cost and precision for mid-tier operations.
- Fully Automatic:Complete process automation from rough alignment to final polish serves high-volume colored stone houses.
Manual equipment holds installed capacity. CNC configurations are rotating up the share rankings.
Technology:
Technology choice maps directly to rough material characteristics, with diamond grinding dominating mainstream applications while specialty modalities capture heat-sensitive niches.
- Diamond Grinding:Rotary laps impregnated with synthetic diamond abrasive achieve material removal rates of 0.1mm per minute on corundum. The installed base spans commercial cutting houses in India, Thailand, and China where abrasive consumables generate recurring revenue streams for equipment vendors.
- Ultrasonic:High-frequency mechanical vibration drives abrasive slurry against fragile material without thermal stress. Custom jewelry studios in Idar-Oberstein and Jaipur adopt these platforms for emerald and tanzanite where inclusion patterns previously rejected stones from conventional processing.
- Laser Cutting:Pulsed beam ablation enables non-contact kerfing of heat-sensitive rough.
- Water Jet:Pressurized abrasive slurry cutting suits preforming operations on large crystal specimens.
Diamond grinding retains volume dominance. Ultrasonic systems are gaining share fastest in specialty applications.
End User:
Customer type determines equipment specification, with jewelry manufacturers prioritizing throughput metrics and artisans emphasizing portability and power requirements.
- Jewelry Manufacturers:Volume-oriented operations in Mumbai and Shenzhen specify CNC platforms with automated rough handling, requiring ISO 9001 traceability for contract jewelry house compliance. These buyers negotiate direct factory procurement to extract cost advantages from Zhuode and Fujian Aite channels.
- Hobbyists:Enthusiast cutters in Germany sustain demand for compact semi-automatic units through state-funded vocational gemology programs that mandate standardized equipment for certification pathways.
- Artisans:Independent cutters in Brazil's Minas Gerais belts seek mid-tier semi-automatic configurations.
- Retailers:Jewelry retail chains with in-house cutting services deploy equipment for customization and repair workflows.
Jewelry manufacturers command equipment specification trends. Hobbyist demand is climbing the fastest through vocational program linkages.
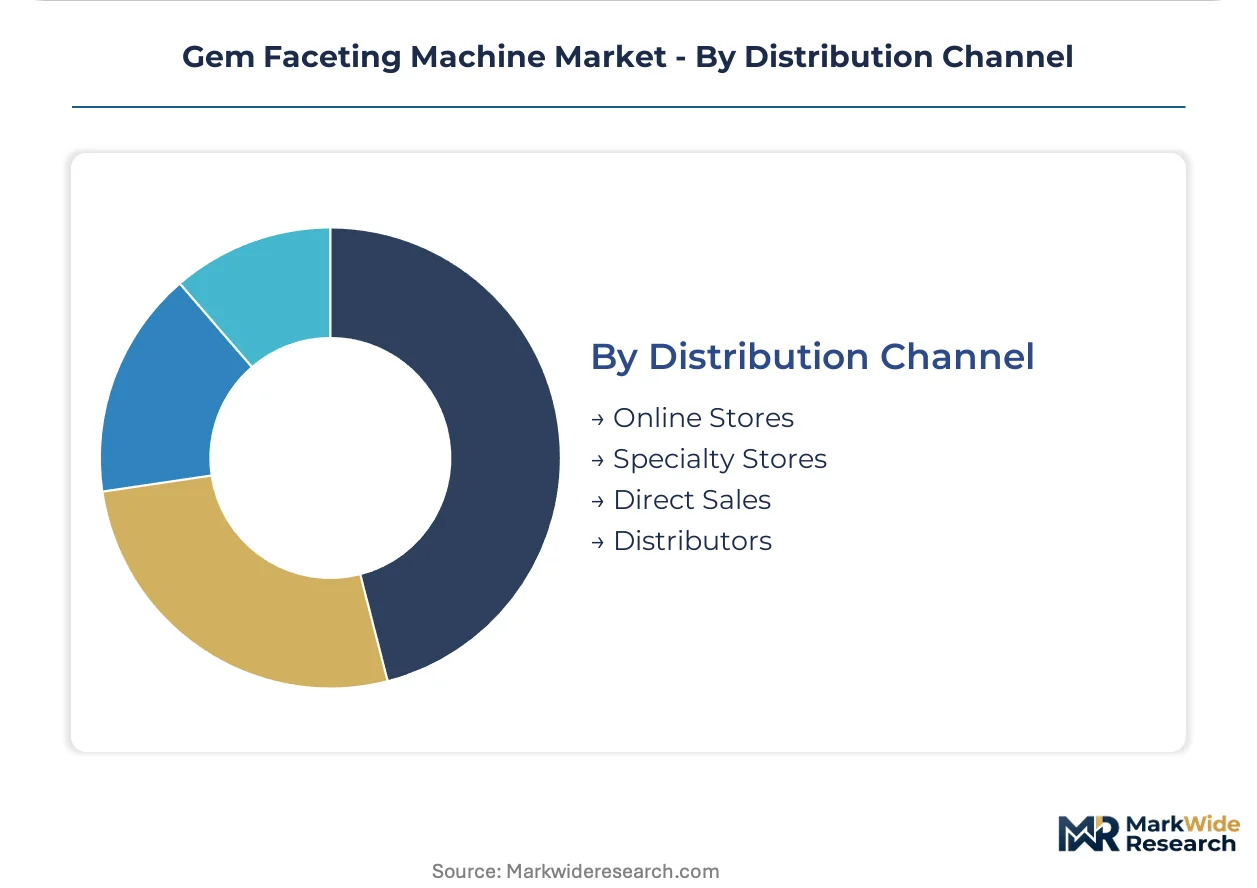
Distribution Channel:
Channel structure is bifurcating between direct factory relationships for volume buyers and retained distributor networks for service-dependent artisan segments.
- Direct Sales:Factory-direct procurement by large cutting houses extracts 15-20% cost advantages and compresses lead times, particularly for CNC platforms from Chinese manufacturers. After-sales service unbundling follows, with third-party maintenance contractors capturing calibration work.
- Specialty Stores:Regional equipment dealers provide hands-on demonstration and local service infrastructure that artisan buyers in Germany and the United States require for capital equipment decisions.
- Online Stores:E-commerce penetration concentrates in consumables and entry-level manual equipment.
- Distributors:Traditional channel partners retain relevance where installation and training services bundle with equipment sale.
Direct sales channels are expanding most quickly among volume manufacturers. Specialty stores defend position in artisan and hobbyist segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BIS certification mandates for precision engineering equipment are accelerating equipment replacement cycles among jewelry manufacturers. Germany's state-funded vocational gemology programs sustain artisanal demand through standardized equipment requirements. The United States, China, and Brazil round out the five-country analysis based on cutting house concentration and regulatory development.
India
Jewelry manufacturers in Mumbai and Surat drive demand for semi-automatic and CNC configurations as BIS certification tightens equipment standards. The Bureau of Indian Standards mandates precision tolerances that manual systems cannot reliably achieve, forcing upgrade investments. Cutting clusters in Gujarat's diamond processing belt report accelerated replacement timelines for faceting machinery.
Germany
Dual education system funding sustains hobbyist demand through gemology certification programs requiring standardized equipment. REACH substance restrictions and CE marking under EU machinery directives govern equipment chemistry and safety design. Idar-Oberstein's colored stone cutting tradition anchors specialty ultrasonic platform adoption for heat-sensitive material processing.
United States
Artisan workshops and custom jewelry studios concentrate demand for premium manual and semi-automatic units. OSHA machinery safety standards and FDA industrial dust exposure limits shape equipment design requirements for domestic manufacturers and importers. California-based precision equipment fabrication serves North American artisan markets with premium positioning.
China
Volume jewelry manufacturing in Shenzhen and Guangzhou drives CNC platform procurement through direct factory channels. National precision equipment standards align with export market certification requirements for CE and BIS-marked machinery. Fujian province's machinery manufacturing base supplies industrial-grade faceting systems to domestic and Asian export markets.
Brazil
Independent cutters in Minas Gerais gemstone belts generate underpenetrated demand for mid-tier semi-automatic configurations serving tourmaline and emerald rough traders. ANVISA workplace safety regulations apply to commercial cutting operations with employee exposure considerations. São Paulo's jewelry manufacturing corridor represents expansion potential for certified precision equipment distribution.
Gem Faceting Machine Market Competitive Landscape
Player mix skews toward mid-cap precision machinery specialists with regional manufacturing footprints. The vendor base separates into three tiers: California-based artisan equipment fabricators, Chinese industrial-scale CNC producers, and European precision engineering houses. Consolidation pressure operates through direct factory procurement displacing distributor networks, while technology licensing agreements accelerate CNC-laser hybrid platform development.
Among Chinese industrial-scale fabricators, Fujian Aite Precision Machinery Co., Ltd. and Shenzhen Hajet Jewelry Equipment Co., Ltd. occupy positions serving volume jewelry manufacturing workflows. Zhuode Gem & Jade Machinery anchors supply chain relationships across Asian markets. Ultra Tec represents the artisan-premium archetype with North American manufacturing positioning. These three exemplify the geographic and tier-based stratification governing competitive dynamics.
| Leading Market Players |
|---|
| Ultra Tec |
| Facetron |
| Polymetric Inc. |
| Sri Rounak Jewellery Equipments |
| Zhuode Gem & Jade Machinery |
| Graves |
| Jersey Instruments |
| Fujian Aite Precision Machinery Co., Ltd. |
| Shenzhen Hajet Jewelry Equipment Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
BIS certification mandates in India simultaneously gate supplier qualification and stratify price tiers, forcing jewelry manufacturers to pay premiums for tested equipment while locking out uncertified competitors from Surat and Mumbai procurement lists. This regulatory filter compresses margin for mid-tier vendors unable to absorb testing costs, while ISO 9001 holders capture pricing power through compliance bundling.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with ISO 9001 and CE-marked CNC platforms commanding substantial premiums over unmarked manual alternatives. Three-tier pricing structure across premium, standard, and economy levels aligns with automation intensity and precision tolerance, though cost compression in the standard tier is intensifying because Chinese direct-factory channels bypass distributor markups. Hobbyist buyers in Germany exhibit lowest price sensitivity due to state-funded vocational program subsidies, while independent artisans in Brazil's Minas Gerais belts drive hardest bargain negotiations.
Supply Chain Analysis
Port congestion on Shenzhen-Shanghai to Mumbai trade lanes elevates inbound logistics costs for precision machinery imports, compressing margin on European-bound shipments transiting through Singapore hubs. Manufacturing concentrates in China's Fujian and Guangdong provinces, Germany's precision engineering belt, and California's artisan equipment fabricators. Synthetic diamond abrasive supply draws from Chinese producers, Japanese ceramic bearing specialists, and Taiwanese servo motor suppliers. Single-source vulnerability in synthetic diamond powder exposes vendors to Chinese supply consolidation shocks. Distribution runs through direct factory relationships for volume buyers and retained specialty dealers for artisan segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service unbundling generates recurring revenue streams expanding faster than hardware sales, with third-party calibration and consumables replenishment capturing margin previously embedded in distributor channels. This service-attach dynamic reorients vendor economics toward lifetime customer value rather than transactional equipment turnover.
For Market Incumbents: Consolidate certification infrastructure investments to defend against emerging Chinese CNC-laser hybrid platforms threatening the industrial jewelry manufacturing segment. Deepen backward integration into synthetic diamond abrasive production to offset Chinese supply consolidation volatility. Capture channel control through exclusive service partnerships with Mumbai and Surat cutting houses. For New Entrants and Emerging Players: Aftermarket calibration and repair services for installed CNC bases represent the most penetrable white-space target, as Fujian Aite and Zhuode under-serve legacy equipment maintenance. Brazil's Minas Gerais artisan belts offer geography-specific entry point for mid-tier semi-automatic configurations. Deploy mobile demonstration units to overcome capital equipment purchase hesitation among independent cutters. For Investors and Strategic Acquirers: India's BIS certification deadline reshapes the acquisition landscape toward tested equipment portfolios with compliant manufacturing footprints. Long-term viability favors precision machinery specialists with multi-regional certification breadth rather than single-market players. Target acquisition archetype: mid-cap CNC platform developers with existing CE marking and BIS application pipelines. Watch for ultrasonic technology adoption inflection in Jaipur and Idar-Oberstein colored stone studios as signal of modality shift.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Portfolio Buildout | BIS, CE, and OSHA compliance unlocks parallel market access across India, Europe, and North America procurement lists. |
| Consumables-First Service Model | Diamond abrasive and coolant replenishment subscriptions generate recurring revenue independent of equipment replacement cycles. |
| Direct Factory Channel Expansion | Bypassing distributor networks extracts margin compression advantages for volume jewelry manufacturers in Bangkok and Shenzhen. |
| Ultrasonic Platform R&D Investment | Heat-sensitive rough processing capability captures emerald and tanzanite cutters migrating from conventional grinding workflows. |
| Vocational Program Equipment Partnerships | Germany's state-funded gemology certification pathways mandate standardized equipment, locking in multi-year replacement demand. |
Research Methodology
Initial hypotheses were tested against primary input from equipment procurement managers at Mumbai and Surat cutting houses, aftermarket service technicians, and gemology program administrators, then refined through secondary validation. Primary fieldwork encompassed maintenance directors at commercial jewelry manufacturers, OEM procurement teams seeking CNC platforms, and aftermarket service heads managing calibration workflows. Secondary sources included BIS certification registries, CE marking databases under EU machinery directives, customs records tracking precision machinery imports, and SEC filings from publicly traded jewelry equipment distributors. Bottom-up equipment shipment tallies were triangulated against top-down jewelry manufacturing capacity estimates.
Variance decomposition across product type, technology modality, end-user category, and geographic regulatory cluster shaped the analytical framework. Segmentation dimensions modeled encompassed automation intensity, cutting technology, customer type, and channel structure. CAGRs were derived through logistic diffusion curves fitted to certification-driven replacement timelines and vocational program enrollment trajectories. Industry-specific forecast inputs included BIS compliance deadline schedules and REACH substance restriction implementation phases.
Underlying assumptions cover steady BIS enforcement intensity, stable synthetic diamond abrasive pricing, and continued German vocational program funding, with deviation risk concentrated in regulatory delay, supply consolidation shocks, or modality substitution acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Aluminium Clad Printed Circuit Board Market
Others
Binoculars and Mounting Solutions Market
Others
Asia-Pacific Road Safety Market
Others
AI In Government And Public Services Market
Others
Hybrid Switchgear Market
Others
Mini Personal Computer Market
Others
South America Halal Food and Beverages Market
Others
Asia-Pacific Eyelash Serum Market
Others
Lined Tank Market
Others
Aircraft Lighting Market
Others
Process Instrumentation Equipment Market
Others
Connected Wearable Patches Market
Others
Global Multi Domain Controller Market
Others
Animal Feed Alternative Protein Market
Others
Safety Instrumented System (SIS) Market
Others
China Automotive LED Lighting Market