
 Binoculars Market | 2026-2036
Binoculars Market Size, Share, and Industry Trends Forecast 2026-2036
Binoculars Market Analysis
The binoculars category is pivoting on a widening gap between premium European glass and mass-market Asian output, with lens coating complexity and chassis material separating price tiers by an order of magnitude. Swarovski Optik leverages in-house fluorite crystal grinding to sustain margin density in the hunting segment. Nikon Corporation anchors volume scale across Asia-Pacific distribution networks. Zeiss differentiates through astronomical specialty lines that command technical loyalty among observatory procurement officers.
Binoculars are paired optical instruments with aligned objective lenses and eyepieces, typically specified by magnification power and objective diameter, that deliver stereoscopic vision for distant observation; roof-prism configurations employ Schmidt-Pechan or Abbe-König prism paths to yield slim, straight-barrel housings favored by mobile users. Porro-prism variants retain cost advantages in marine and budget wildlife segments where bulk tolerance runs higher. Thermal technology is displacing traditional infrared in search-and-rescue procurement cycles, while digital integration into night-vision units creates firmware-dependent upgrade revenue streams absent from purely optical platforms.
FCC equipment authorization governs digital and infrared models sold in the United States, while CE marking under the EU Radio Equipment Directive constrains transmission-capable units entering European channels. ISO 14133-1 establishes mechanical and environmental test protocols that military and professional buyers embed as tender prerequisites. Stakeholders must monitor how dual-use export control expansions affect thermal-binocular shipments to defense-adjacent customers without triggering licensing thresholds.
Market Dynamics
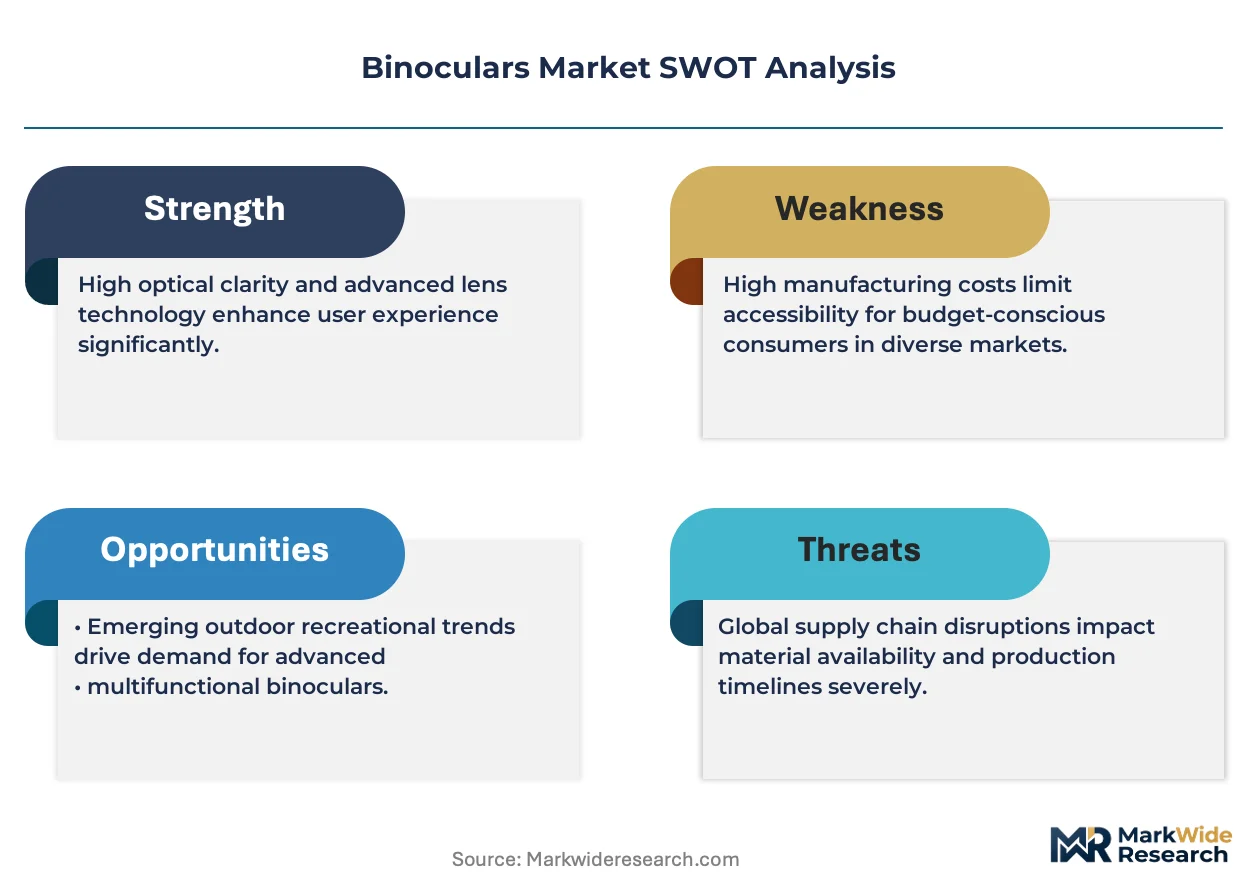
REACH-mandated lead-glass phase-outs in Europe are redirecting R&D capital toward eco-friendly crown-glass formulations, compressing traditional supply chains while opening specialty niches for compliant manufacturers.
Growth Catalysts
- Wildlife tourism fleet renewal:East African safari operators are standardizing on roof-prism configurations for guide portability, creating sustained bulk procurement cycles.
- REACH compliance innovation:European manufacturers investing in lead-free optical glass are capturing defense and professional tenders that exclude legacy formulations.
- Thermal sensor convergence:Search-and-rescue agencies are replacing traditional infrared units with thermal-binocular hybrids, opening firmware-upgrade revenue streams.
Market Restraints
- Rare-earth coating volatility:Magnesium fluoride and anti-reflective dielectric deposition costs fluctuate with Chinese export quotas, squeezing margin on mid-tier products.
- Precision-optics concentration:German clusters around Wetzlar and Oberkochen control critical grinding expertise, creating single-source vulnerability for fluorite crystal supply.
- Digital night-vision substitution:Smartphone-integrated telephoto arrays and clip-on thermal cameras erode casual-user demand for entry-level binoculars.
Strategic Opportunities
- Indian wildlife hospitality expansion:Luxury lodge construction in Madhya Pradesh and Karnataka is generating first-time demand for premium roof-prism units among domestic operators.
- Astronomical observatory procurement:Research institutions are specifying apochromatic triplet objectives for spectrographic calibration, creating technical-loyalty lock-in.
- FCC authorization pathways:Digital and infrared models gaining streamlined equipment authorization are penetrating US law-enforcement channels previously blocked by certification delays.
Industry Challenges
- Optical engineer scarcity:Master glass grinders and prism-alignment specialists are retiring faster than apprenticeship programs in Germany and Japan can replenish them.
- Dual-use export licensing:Thermal-binocular shipments to defense-adjacent customers risk triggering ITAR thresholds, requiring legal review that extends sales cycles by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Binoculars Market |
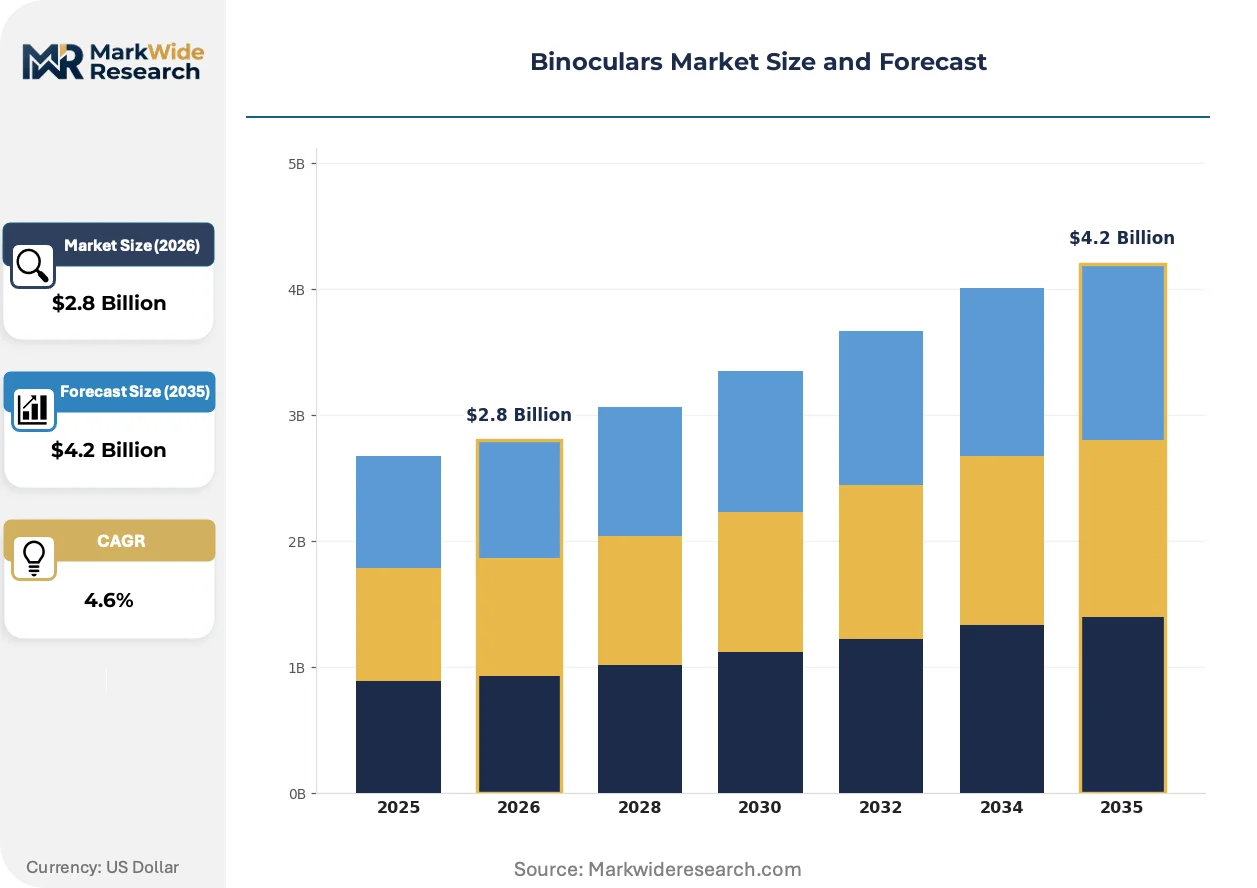
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roof Prism, Porro Prism, Military, Night Vision End User: Wildlife Observers, Birdwatchers, Hunters, Marine Enthusiasts Technology: Optical, Digital, Infrared, Thermal Application: Sports, Astronomy, Surveillance, Search & Rescue |
| Companies Covered | Leica, Celestron, Nikon Corporation, Vixen Optics, Canon, Swarovski Optik, Bushnell, Steiner, Zeiss, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Binoculars Market Emerging Trajectories
Digital integration and environmental compliance are bifurcating the competitive landscape between firmware-dependent platforms and purely optical heritage products, with coating chemistry and chassis alloys becoming primary differentiation vectors.
Fluorite crystal grinding is expanding into mid-tier hunting and birding segments as automated polishing reduces unit costs. Retailers in the American Midwest are stocking these models for whitetail deer season. The technology is expanding into price brackets previously served by standard ED glass, compressing premium-tier boundaries.
REACH substance restrictions on lead-containing optical glass are forcing reformulation of crown-glass melts across European foundries. Manufacturers must revalidate refractive indices and dispersion coefficients under new chemistries. German precision-optics houses are absorbing these costs to maintain CE-marked access, while Asian competitors face retesting barriers.
Observatory procurement officers are consolidating vendor relationships around astronomical specialty lines that bundle calibration documentation and long-term service agreements. This specification-driven purchasing replaces transactional equipment buying. North American research institutions are leading this consolidation, embedding ISO 14133-1 environmental testing as tender prerequisites.
Binoculars Market Segmentation
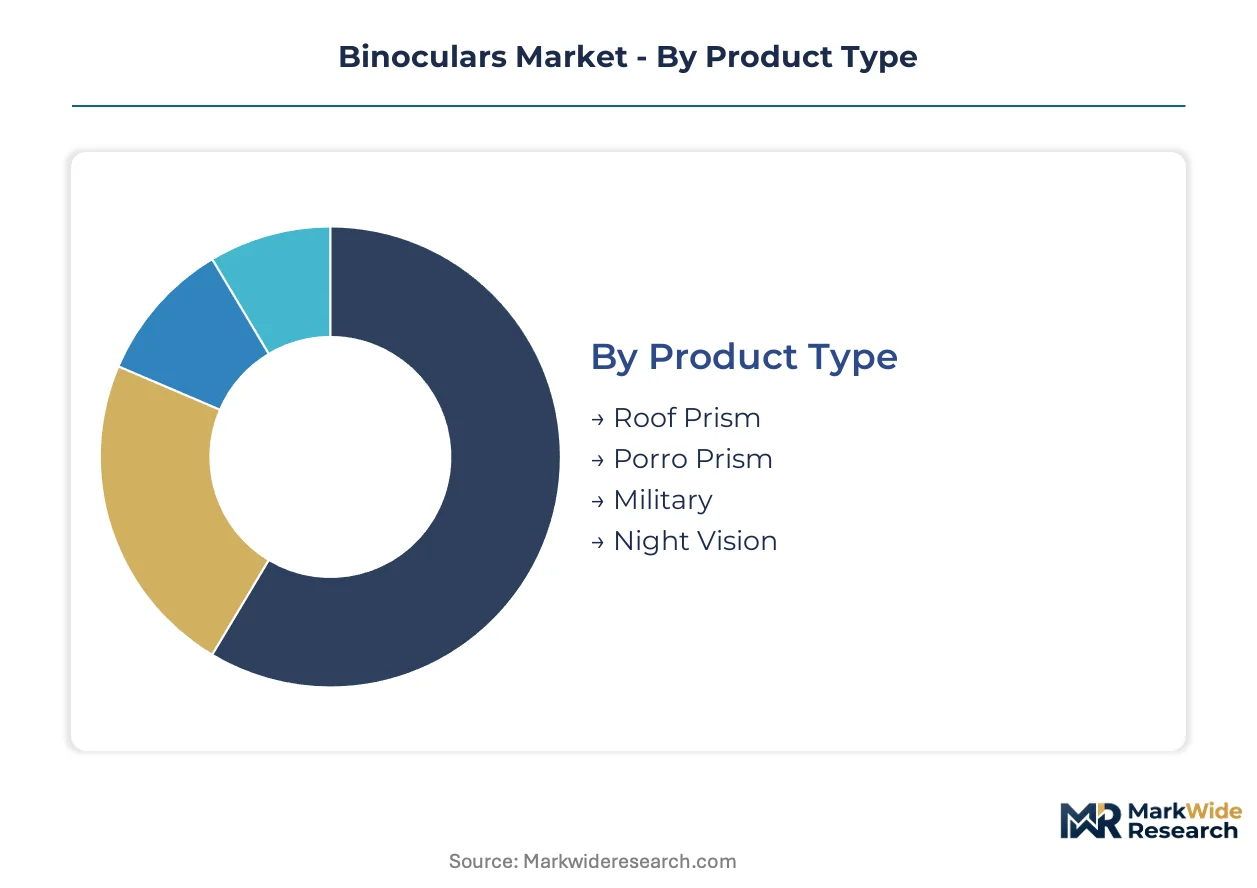
Binoculars manufacturers configure production lines around prism geometry and optical technology, with coating complexity and chassis alloys separating price tiers by an order of magnitude. Segment boundaries are hardening as REACH-mandated lead-glass phase-outs in Europe redirect R&D capital toward compliant crown-glass formulations.
Product Type:
Supply concentration clusters around German precision-optics houses in Wetzlar and Oberkochen, where fluorite crystal grinding expertise controls premium-tier output.
- Roof Prism:Schmidt-Pechan or Abbe-König prism paths yield slim, straight-barrel housings. Safari operators in Kenya and Tanzania are standardizing these configurations for guide portability, creating sustained bulk procurement cycles from East African wildlife tourism fleets.
- Porro Prism:Offset barrel design retains cost advantages where bulk tolerance runs higher. Marine enthusiasts and budget wildlife observers in coastal India and Southeast Asia drive volume demand for these heavier, optically efficient alternatives.
- Military:Ruggedized chassis meeting ISO 14133-1 environmental protocols.
- Night Vision:Image intensifier tubes or digital sensors enabling low-light observation.
Today's leader: Roof Prism. Tomorrow's challenger: Night Vision.
End User:
Cost tier stratification separates premium European glass from mass-market Asian output, with warranty terms and calibration documentation becoming purchase determinants.
- Wildlife Observers:Lodge operators and safari guides requiring durable, weather-sealed instruments. Luxury hospitality construction in Madhya Pradesh and Karnataka is generating first-time premium roof-prism demand among domestic Indian operators.
- Birdwatchers:Apochromatic triplet objectives and close-focus capabilities dominate specifications. North American research institutions are consolidating vendor relationships around astronomical specialty lines that bundle long-term service agreements.
- Hunters:Whitetail deer season drives Midwestern US retailer stocking patterns.
- Marine Enthusiasts:Waterproofing and nitrogen purging are non-negotiable specifications.
Volume concentrates with Wildlife Observers. Margin expansion favors Birdwatchers.
Technology:
Application requirements are bifurcating procurement between purely optical heritage products and firmware-dependent digital platforms.
- Optical:Purely mechanical light-gathering without electronic components. Traditional crown-glass and ED glass formulations face REACH retesting barriers for Asian competitors, while German manufacturers absorb reformulation costs to maintain CE-marked access.
- Digital:Sensor-based capture with firmware upgrade pathways. FCC equipment authorization is streamlining penetration into US law-enforcement channels previously blocked by certification delays.
- Infrared:Active illumination systems for low-light observation.
- Thermal:Uncooled microbolometer arrays detecting heat signatures. Search-and-rescue agencies are replacing traditional infrared units with thermal-binocular hybrids, opening recurring firmware-upgrade revenue absent from optical platforms.
Optical commands installed base. Thermal is gaining share fastest.
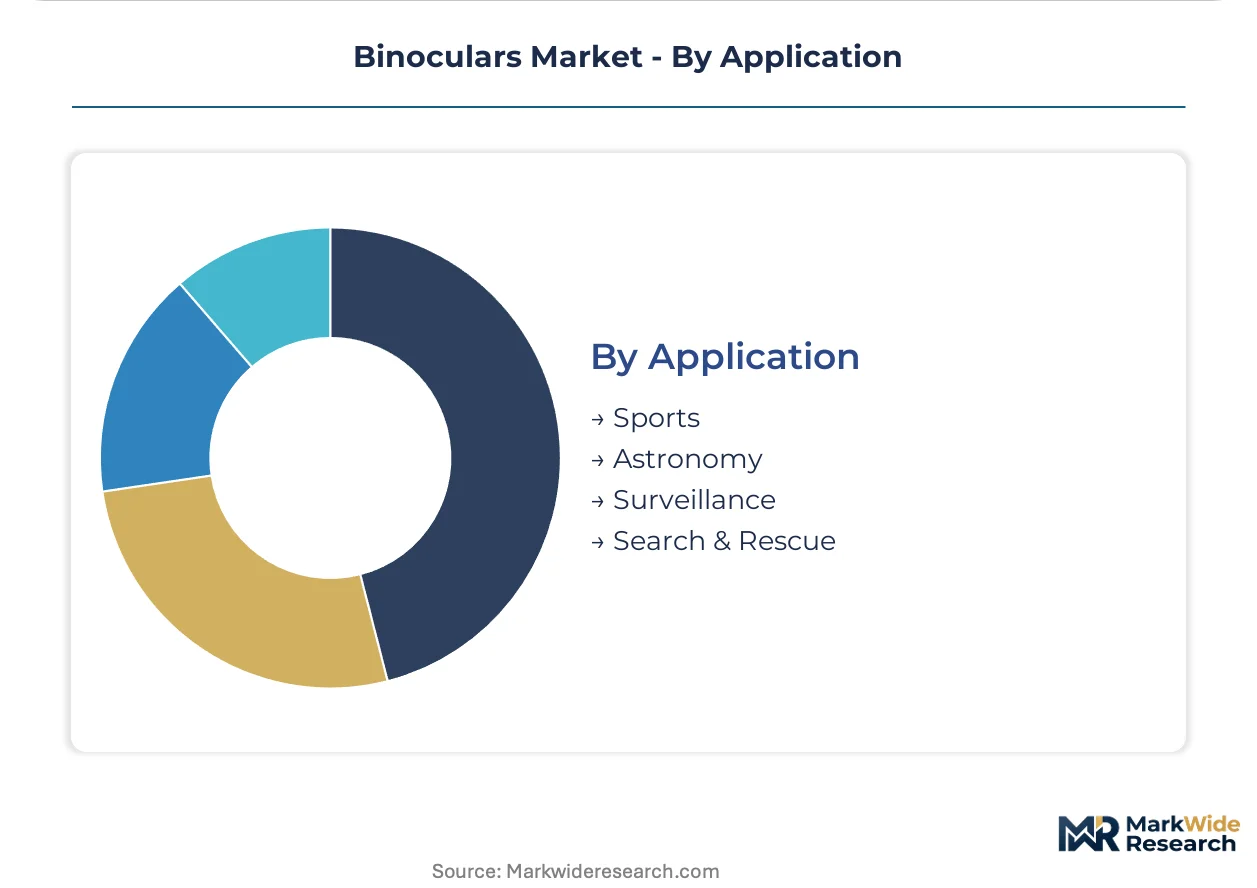
Application:
Customer type determines specification stringency, with observatory procurement officers embedding ISO 14133-1 environmental testing as tender prerequisites.
- Sports:Lightweight configurations for stadium and field event viewing. Automated polishing is expanding fluorite crystal grinding into mid-tier hunting and birding price brackets previously served by standard ED glass.
- Astronomy:Large objective diameters and apochromatic correction for celestial observation. Research institutions are specifying calibration documentation and long-term service agreements, replacing transactional equipment buying with technical-loyalty lock-in.
- Surveillance:Extended eye relief and tripod compatibility for prolonged use.
- Search & Rescue:Thermal sensor convergence and GPS integration for coordinate logging.
Astronomy anchors premium pricing. Search & Rescue shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Master glass grinders and prism-alignment specialists cluster in southern Germany and central Japan, anchoring precision-optics output that sustains premium-tier manufacturing. Their apprenticeship pipelines lag retirement rates, tightening supply of critical expertise.
Germany
Precision-optics houses around Wetzlar and Oberkochen dominate fluorite crystal grinding for hunting and birding segments. ECHA REACH enforcement mandates lead-free optical glass reformulations, redirecting R&D budgets toward compliant crown-glass melts. Bavarian foundries absorb these validation costs to preserve CE-marked export access.
United States
Midwestern retailers stock automated-polish fluorite models for whitetail deer season, expanding premium glass into mid-tier price brackets. FCC equipment authorization streamlines digital and infrared model penetration into law-enforcement procurement channels. Arizona and Colorado host defense-adjacent thermal-binocular integrators navigating ITAR licensing thresholds.
Japan
Optical engineer apprenticeship programs in Hokkaido and Nagano struggle to replenish retiring master grinders faster than attrition. METI industrial standards govern JIS-certified export specifications for marine and astronomical lines. Tokyo-based distributors anchor Asia-Pacific volume scale across premium roof-prism configurations.
India
Luxury lodge construction in Madhya Pradesh and Karnataka generates first-time premium roof-prism demand among domestic wildlife hospitality operators. BIS certification requirements create retesting barriers for imported optical glass formulations. Gujarat assembly plants source Porro-prism chassis for Southeast Asian marine enthusiasts.
Kenya
Safari operators in the Masai Mara and Amboseli ecosystems standardize roof-prism configurations for guide portability, creating sustained bulk procurement cycles. Kenya Wildlife Service concession requirements embed durability specifications into operator equipment tenders. Nairobi distributors coordinate East African fleet renewal logistics for tourism conglomerates.
Binoculars Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across coating chemistry and chassis alloy selection. The vendor base stratifies into three tiers: heritage European houses controlling fluorite grinding expertise, Asian volume manufacturers scaling ED glass output, and digital integrators capturing firmware-dependent upgrade revenue. Strategic moves concentrate on automated polishing investments that compress premium-tier boundaries and REACH compliance acquisitions that secure CE-marked European access.
Within the heritage optics tier, Leica GmbH and Swarovski Optik exemplify precision-manufacturing archetypes anchored in German-speaking industrial clusters. Nikon Corporation occupies a position bridging volume scale across Asia-Pacific distribution with premium-tier credibility in astronomical specialty lines. These three represent distinct competitive positions: family-owned engineering depth, vertically integrated crystal grinding control, and transnational brand equity spanning consumer and professional segments.
| Leading Market Players |
|---|
| Leica |
| Celestron |
| Nikon Corporation |
| Vixen Optics |
| Canon |
| Swarovski Optik |
| Bushnell |
| Steiner |
| Zeiss |
| Others |
Supply Flow & Price Mechanics
Magnesium fluoride spot pricing and Chinese rare-earth export quota announcements cascade through anti-reflective coating costs, compressing mid-tier margins while German manufacturers absorb REACH-driven crown-glass reformulation expenses to preserve premium-tier pricing power.
Pricing Analysis
Bundled calibration documentation and long-term service agreements separate observatory procurement from transactional retail sales, with astronomical specialty lines commanding three-tier pricing structure across premium, standard, and economy levels based on fluorite crystal grinding precision and ISO 14133-1 certification tier. Safari fleet operators in Kenya and Tanzania exhibit highest price sensitivity due to bulk volume negotiations, while North American research institutions show lowest sensitivity given grant-funded capital budgets and technical-loyalty lock-in. Pricing pressure stems from automated polishing technology expanding fluorite grinding into mid-tier brackets previously served by standard ED glass.
Supply Chain Analysis
CE marking and FCC equipment authorization gate market access for transmission-capable units, with German precision-optics clusters around Wetzlar and Oberkochen and Japanese grinding facilities in Hokkaido and Nagano anchoring fluorite crystal supply. Crown-glass formulations draw from Bavarian foundries and Asian optical glass producers, while magnesium fluoride coatings and rare-earth dielectric materials rest on Chinese export quota policies. Single-source vulnerability concentrates in master grinder expertise as apprenticeship pipelines lag retirement rates. Distribution runs through Nairobi distributors coordinating East African fleet logistics, Tokyo-based Asia-Pacific volume channels, and Midwestern US retailers serving seasonal hunting demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Binoculars procurement functions as a regulatory compounder where ECHA REACH substance restrictions on lead-containing optical glass redirect R&D budgets and reshape competitive access to European tenders.
For Market Incumbents: Anchor fluorite crystal grinding expertise through automated polishing investments that compress premium-tier boundaries and absorb reformulation costs faster than Asian competitors facing retesting barriers. Defend against digital night-vision substitution by bundling firmware-upgrade pathways into thermal-binocular hybrids for search-and-rescue agencies. Prioritize CE-marked access preservation through captive crown-glass supply relationships with compliant Bavarian foundries.
For New Entrants and Emerging Players: Direct-to-consumer digital channels bypass incumbent distributor relationships in the American Midwest hunting segment and Indian wildlife hospitality procurement. Target Madhya Pradesh and Karnataka luxury lodge construction generating first-time premium roof-prism demand among domestic operators previously served by rental fleets. Pursue FCC streamlined authorization pathways for law-enforcement thermal-binocular penetration previously blocked by certification delays.
For Investors and Strategic Acquirers: Asymmetric upside sits with automated polishing technology specialists bridging fluorite grinding into mid-tier price brackets and REACH-compliant crown-glass formulation assets securing European tender access. Long-term viability favors manufacturers controlling both optical heritage credibility and firmware-dependent upgrade revenue streams. Monitor thermal sensor convergence adoption rates in search-and-rescue procurement cycles as inflection indicator for platform transition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fluorite Polishing Investment | Expands premium glass into mid-tier hunting and birding price brackets previously served by ED glass. |
| REACH-Compliant Crown-Glass Reformulation | Preserves CE-marked European access while Asian competitors face retesting barriers under ECHA enforcement. |
| Thermal-Binocular Firmware Platform Development | Captures recurring upgrade revenue from search-and-rescue agencies replacing traditional infrared units. |
| East African Safari Fleet Distribution Partnership | Locks in sustained bulk procurement cycles from Kenya and Tanzania wildlife tourism operators. |
| Astronomical Specialty Line Service Agreement Bundling | Replaces transactional equipment buying with technical-loyalty lock-in among observatory procurement officers. |
Methodological Framework
Bottom-up wildlife tourism and astronomical observatory modeling reconciled against top-down precision-optics manufacturing tracking forms the analytical core of this study. Primary interviews with safari fleet procurement managers, observatory instrumentation officers, optical glass foundry technical directors, and Midwestern hunting retailer category buyers combined with secondary validation against ECHA REACH substance restriction databases, FCC equipment authorization filings, ISO 14133-1 test protocol documentation, and customs trade data for magnesium fluoride and rare-earth coating materials.
Historical trendline analysis of roof-prism versus Porro-prism configuration mix, thermal sensor convergence adoption curves, and lead-glass phase-out compliance timelines established baseline trajectory parameters. The projection framework segments by prism geometry, end-user archetype, technology platform, and application requirement, with CAGRs derived from regression analysis against wildlife hospitality construction permits, defense-adjacent thermal procurement budgets, and automated polishing technology diffusion rates.
The model assumes a particular technology adoption path; alternative pathways for smartphone-integrated telephoto substitution or uncooled microbolometer cost curves would alter the outlook. Forecasts reflect assumptions regarding ECHA enforcement consistency, Chinese rare-earth export quota stability, and German apprenticeship pipeline replenishment rates. A model refresh is warranted upon material change in REACH substance restriction scope or thermal-binocular ITAR licensing threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Taiwan Retail Market
Others
Refractometer Market
Others
Workstation Desktops Market
Others
Heat Treatment Furnace Market
Others
China Cloud Gaming Technology Market
Others
Binoculars and Mounting Solutions Market
Others
China Automotive LED Lighting Market
Others
Grna Market
Others
Indoor LBS Market
Others
Europe Electric Forklift Market
Others
Liposomes Market
Others
Latin America Fire Sprinklers Market
Others
Construction Wearables Market
Others
Interference Mitigation Filters Market
Others
Linear Shaft Market
Others
Global Smartphone ODM Market