
 Global Aircraft Lighting Systems Market | 2026-2036
Global Aircraft Lighting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aircraft Lighting Systems Market Intelligence
The rise of performance-based leasing models for aircraft components is fragmenting the supplier base for lighting systems. This operational shift allows specialized firms to compete on total cost of ownership rather than just upfront price. Honeywell International Inc. leverages its extensive avionics portfolio to offer integrated cockpit and cabin solutions. Thales specializes in advanced cabin electronics and passenger experience systems, creating a distinct competitive position in the market.
Aircraft lighting systems are integrated networks of exterior and interior lights essential for flight safety, aircraft visibility, and the overall cabin environment. These systems must adhere to strict performance standards for luminosity and durability under extreme vibration and temperature fluctuations. The shift to LED technology is now dominant, displacing legacy halogen and incandescent options across most aircraft applications. While commercial aircraft constitute the largest application segment, demand for specialized lighting in unmanned aerial vehicles is growing rapidly.
Product design and market access are governed by strict airworthiness directives from bodies like the US Federal Aviation Administration (FAA). In parallel, regulations such as the EU's CE marking requirements dictate electromagnetic compatibility and safety standards, directly influencing component engineering and testing protocols. Suppliers must now decide whether to compete on component-level innovation or on integrated, software-defined cabin systems.
Market Dynamics
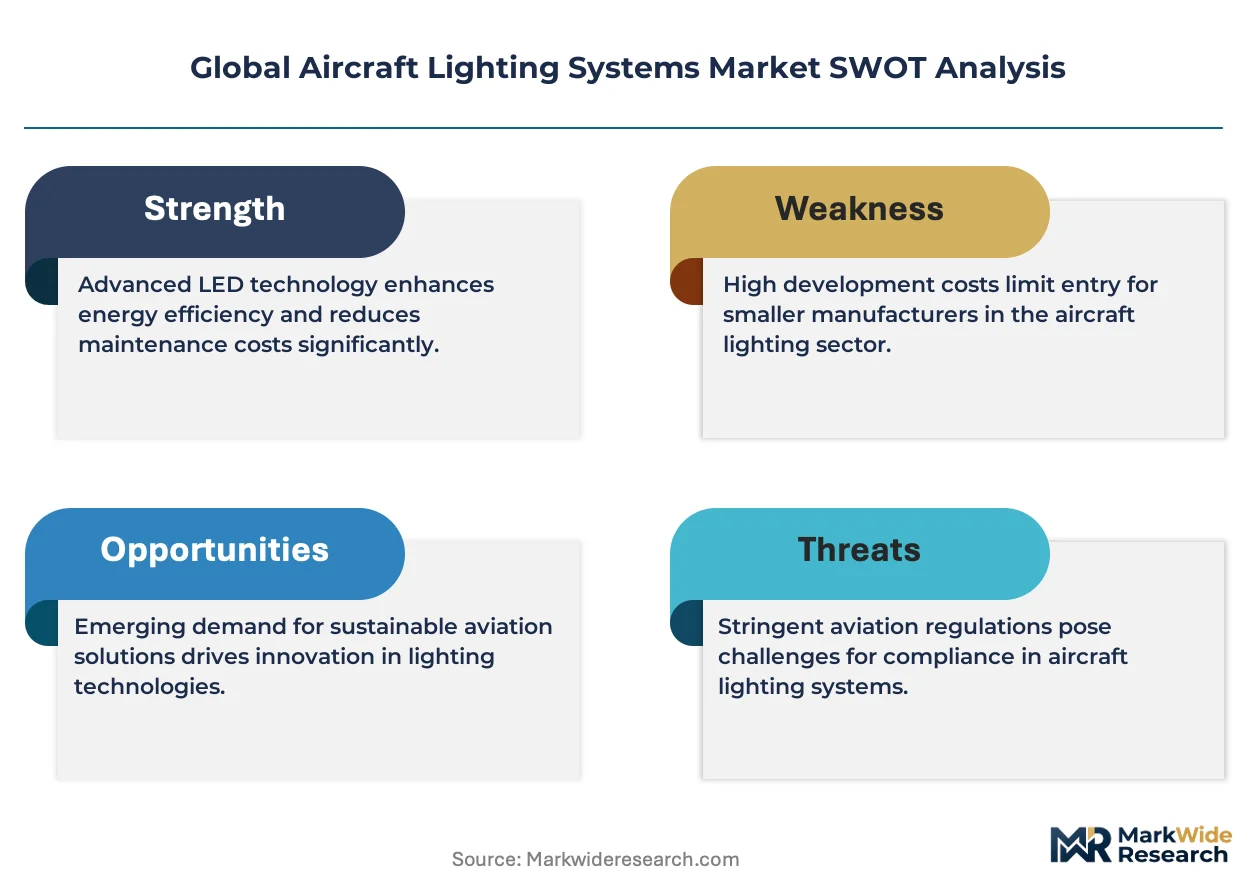
The market's central dynamic is the push for rapid LED adoption against the friction of stringent airworthiness certification. This tension dictates product development timelines for manufacturers in the US and France.
Growth Catalysts
- LED Retrofits:The upgrade cycle in the commercial fleet replaces legacy systems with efficient LEDs, driven by airline goals for lower maintenance and fuel costs.
- Passenger Experience:Airlines invest in dynamic lighting to differentiate cabin interiors, creating demand for sophisticated, software-controlled systems, especially in wide-body jets.
- UAV Segment Growth:The unmanned aerial vehicle market requires specialized, lightweight lighting for navigation, opening a new application segment.
Market Restraints
- Certification Barriers:New products face lengthy testing to meet airworthiness standards from bodies like the FAA, creating high entry costs and delaying market access.
- Integration Complexity:Integrating new lighting into legacy aircraft avionics is expensive, often deterring smaller operators from pursuing retrofits.
- Supplier Concentration:The limited pool of suppliers meeting aerospace quality standards creates potential supply chain bottlenecks for OEMs.
Strategic Opportunities
- Li-Fi Integration:The convergence of lighting with data transmission via Light Fidelity (Li-Fi) offers a path to integrated cabin systems providing illumination and connectivity.
- Performance-Based Services:Shifting to leasing and maintenance contracts for lighting systems allows suppliers to capture recurring revenue based on reliability and total cost of ownership.
- Advanced Air Mobility:The emerging market for electric vertical take-off and landing (eVTOL) aircraft creates demand for unique, ultra-lightweight lighting solutions.
Industry Challenges
- Software Integration:The shift to software-defined lighting requires new engineering skills to integrate controls with central cabin management systems, creating talent gaps.
- Electromagnetic Compatibility:Ensuring new LED drivers comply with strict EMC rules, such as the EU's CE marking, without interfering with avionics is a persistent challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aircraft Lighting Systems Market |
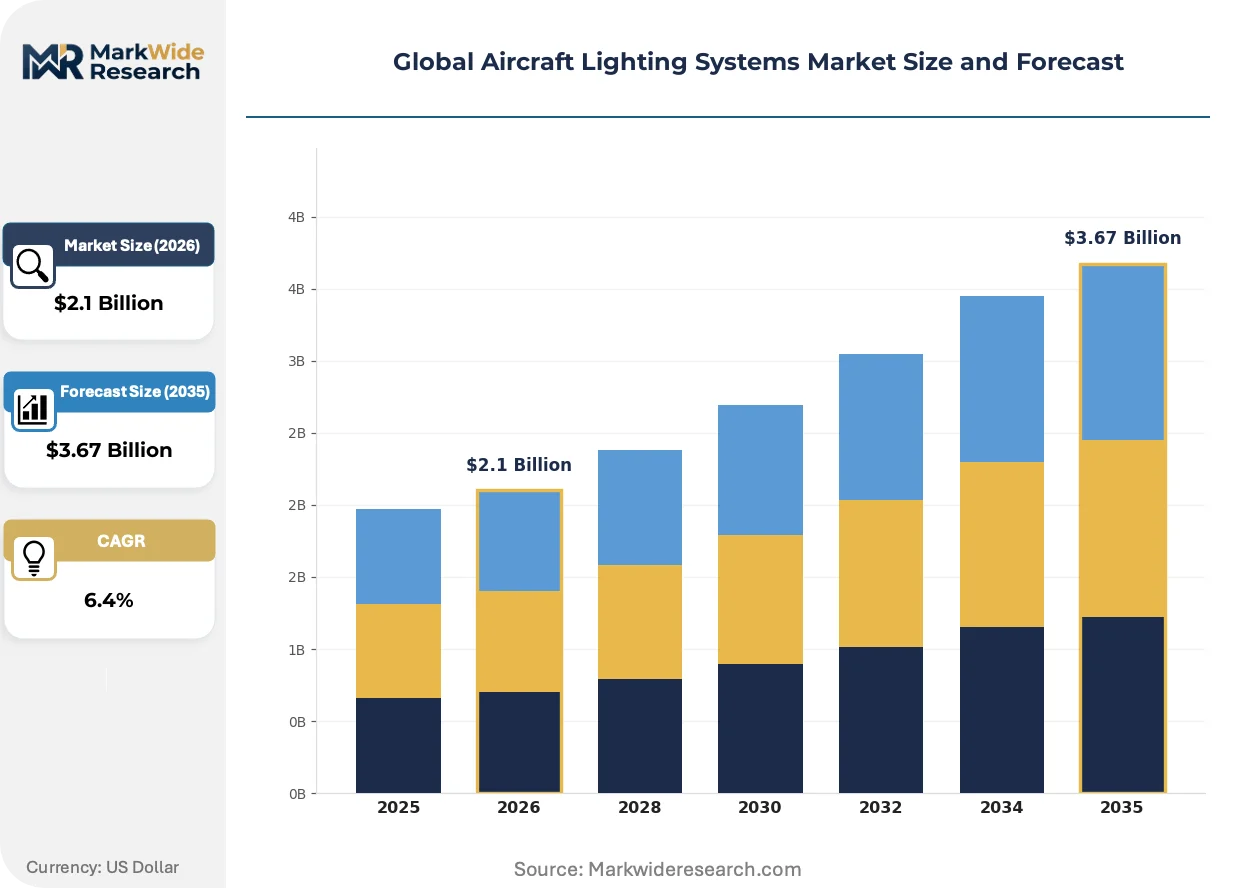
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Landing Lights, Taxi Lights, Cabin Lights, Navigation Lights, Anti-Collision Lights Technology: LED, Halogen, Incandescent, HID, Electroluminescent Application: Commercial Aircraft, Military Aircraft, Business Jets, Helicopters, Unmanned Aerial Vehicles End User: Aircraft Manufacturers, Maintenance Providers, Airlines, Defense Contractors |
| Companies Covered | Astronics Corporation, RTX Corporation, Diehl Stiftung & Co. KG, Honeywell International Inc., Thales, Luminator Aerospace, STG Aerospace Limited, Cobham plc, Aveo Engineering Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aircraft Lighting Systems Market Strategic Shifts & Innovations
Aircraft lighting is evolving from a standalone hardware function into an integrated element of the digital cabin and cockpit. This shift prioritizes software-defined features, data connectivity, and system-level performance over component-level specifications alone.
Smart lighting systems embed microcontrollers and sensors directly into fixtures to monitor performance and environmental conditions. Commercial airline operators are rapidly adopting these systems for predictive maintenance and real-time control. This onboard intelligence is hybridizing the traditional lighting fixture with functions previously managed by centralized cabin control units, simplifying system architecture.
The European Union's directives on Restriction of Hazardous Substances (RoHS) and waste electronics (WEEE) influence material selection for lighting components sold into the region. This forces a global supply chain response, pushing manufacturers towards lead-free solders and more recyclable composite materials for housings and lenses. The commercial aircraft segment is most affected, requiring detailed material declarations and end-of-life management plans.
A shift towards total cost of ownership (TCO) models is changing how airlines acquire and maintain lighting systems. This disrupts the traditional transactional sale of individual components, favoring suppliers who can offer comprehensive service and upgrade packages over the aircraft's lifecycle. This trend is most visible in the North American and European markets for cabin retrofits.
Global Aircraft Lighting Systems Market Segmentation
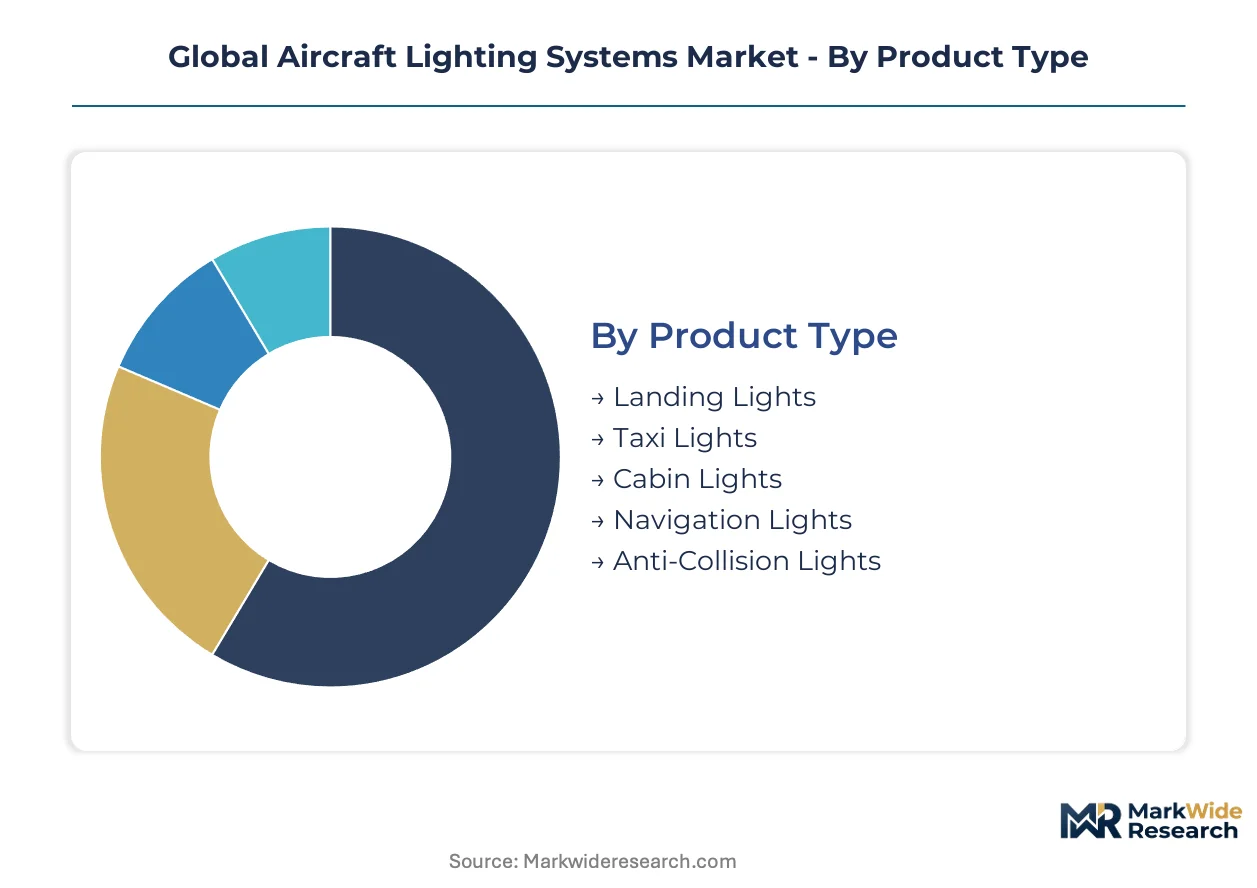
Understanding the Global Aircraft Lighting Systems Market through segmentation reveals distinct demand patterns and competitive dynamics. Each segment responds to unique regulatory pressures, technological advancements, and operational requirements. This granular view helps stakeholders identify areas of high growth and specific challenges across the industry.
Product Type:
The product type segmentation highlights varying replacement cycles and technological refresh rates within aircraft lighting systems. Cabin lighting systems often see faster upgrade cycles due to passenger experience demands, while exterior lights are replaced based on wear and regulatory compliance.
- Cabin Lights:These systems provide illumination for passenger comfort, emergency egress, and aesthetic appeal within the aircraft interior. Demand for dynamic, software-controlled cabin lighting concentrates in the commercial aircraft segment, driven by airline efforts to enhance passenger experience.
- Navigation Lights:Essential for aircraft visibility and collision avoidance, these external lights meet strict international aviation regulations for color and intensity. The shift to LED technology for navigation lights is widespread across all aircraft types, ensuring greater reliability and reduced maintenance for operators.
- Landing Lights:Powerful external lights illuminate the runway during takeoff and landing operations.
- Taxi Lights:These lights provide visibility on the ground during taxiing, crucial for ground operations.
- Anti-Collision Lights:Flashing or strobe lights increase aircraft visibility to other air traffic, particularly in busy airspace.
Landing Lights dominate the installed base for external systems. Cabin Lights are where expansion concentrates for interior applications.
Technology:
Technology segmentation illustrates the industry's progression from legacy illumination sources to modern, energy-efficient solutions. The maturity of each technology influences its adoption rate, cost profile, and regulatory compliance within the aerospace sector.
- LED:Light-Emitting Diode technology offers superior energy efficiency, extended lifespan, and precise control over light output and color. Commercial aircraft retrofits and new installations in the United States and France overwhelmingly favor LED systems due to their operational cost savings and design flexibility.
- Halogen:These lamps utilize a tungsten filament encased in a halogen gas-filled bulb, providing bright, focused light. While being phased out, halogen systems still exist in older aircraft fleets, particularly for exterior lighting functions, due to their established performance and lower initial cost.
- Incandescent:Traditional incandescent bulbs use a heated filament to produce light and represent the oldest lighting technology in aviation.
- HID:High-Intensity Discharge lamps offer powerful illumination, often found in specialized applications requiring high brightness.
- Electroluminescent:These thin, flexible light sources are used for backlighting instruments and cabin signage, known for their uniform glow.
LED technology represents the fastest-growing segment, rapidly displacing legacy Halogen and Incandescent options across the market.
Application:
The application segmentation categorizes aircraft lighting systems based on the specific type of aerial platform. Each application presents unique requirements concerning performance, durability, weight, and certification, influencing product design and market demand.
- Commercial Aircraft:This segment includes passenger and cargo planes, representing the largest application for interior and exterior lighting systems. Retrofits for cabin lighting in commercial aircraft drive significant demand, especially among major airlines in North America and Europe seeking enhanced passenger experience.
- Unmanned Aerial Vehicles:UAVs require specialized, lightweight, and compact lighting solutions for navigation, collision avoidance, and operational signaling. The rapid expansion of the UAV market, particularly for delivery and surveillance drones, creates a new and dynamic demand pool for innovative lighting.
- Military Aircraft:Fighter jets, transport planes, and bombers utilize lighting systems adapted for stealth, night vision compatibility, and extreme operational conditions.
- Business Jets:Private and corporate jets demand high-end, customizable cabin lighting systems that prioritize luxury and passenger comfort.
- Helicopters:Rotorcraft require durable lighting for navigation, landing, and interior cabin illumination, often subjected to high vibration environments.
Commercial Aircraft constitutes the largest volume application for aircraft lighting systems. Unmanned Aerial Vehicles are expanding most quickly as a new application segment.
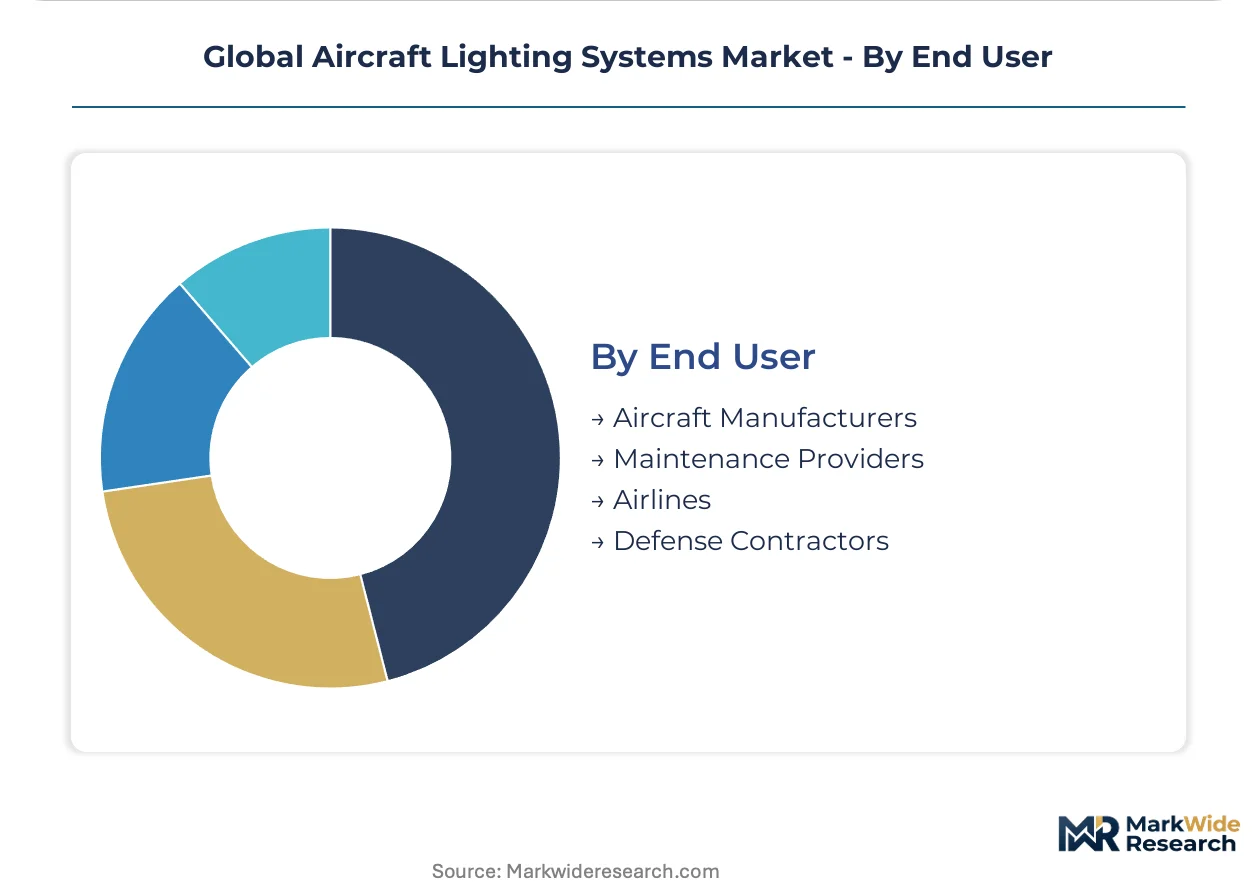
End User:
End-user segmentation identifies the primary purchasers and integrators of aircraft lighting systems. Each end-user group has distinct procurement processes, technical specifications, and priorities, shaping supplier engagement and product development.
- Aircraft Manufacturers:Original Equipment Manufacturers (OEMs) integrate lighting systems into new aircraft during the production phase, demanding components that meet specific design, weight, and performance criteria. Boeing and Airbus, for example, specify advanced LED systems for their new commercial aircraft programs.
- Airlines:Commercial airlines procure lighting systems for fleet upgrades, retrofits, and routine maintenance, focusing on reliability, energy efficiency, and passenger experience. Major carriers in the United States frequently invest in dynamic cabin lighting to differentiate their services.
- Maintenance Providers:These firms purchase replacement and upgrade lighting components for aircraft undergoing maintenance, repair, and overhaul (MRO).
- Defense Contractors:Companies supplying military aircraft and equipment purchase specialized lighting solutions tailored to defense specifications and operational requirements.
Aircraft Manufacturers represent the initial point of sale for new aircraft lighting systems. Airlines drive recurring revenue through retrofit and maintenance purchases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global aircraft lighting systems market exhibits varied import and export dynamics, reflecting localized manufacturing strengths and demand centers. Established aerospace hubs drive innovation and production, while emerging markets focus on fleet expansion and maintenance. This geographic distribution influences supply chain resilience and technology adoption rates.
United States
The United States market experiences significant demand for commercial aircraft retrofits and specialized lighting for unmanned aerial vehicles. Airworthiness directives from the US Federal Aviation Administration (FAA) govern product design and certification processes. Aerospace manufacturing in Wichita continues to innovate, developing advanced LED systems for both new aircraft and existing fleets.
France
France maintains strong demand for sophisticated cabin lighting systems, particularly for new commercial aircraft programs from Airbus. European Union's CE marking requirements directly influence component engineering and testing protocols for market access. Toulouse serves as a major aerospace cluster, integrating cutting-edge lighting solutions into next-generation aircraft designs.
Germany
German aerospace manufacturers require high-performance lighting solutions for both commercial and military aircraft applications. The European Aviation Safety Agency (EASA) mandates rigorous certification for all new aircraft components, including lighting systems. Hamburg's aerospace industry benefits from MRO activities and Airbus production facilities, driving demand for durable lighting technologies.
Japan
Japanese aerospace firms prioritize lightweight and energy-efficient lighting for their advanced aircraft platforms. Japan Civil Aviation Bureau (JCAB) standards ensure strict safety and performance compliance for all installed systems. Nagoya's concentration of precision engineering companies contributes to the development of specialized lighting components and integrated solutions.
China
China's rapidly expanding commercial aircraft fleet generates substantial demand for both interior and exterior lighting systems. Civil Aviation Administration of China (CAAC) regulations guide the certification and deployment of new lighting technologies. Xi'an's aerospace industrial base supports domestic aircraft manufacturing, integrating modern lighting into locally produced aircraft.
Global Aircraft Lighting Systems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the global aircraft lighting systems market. The market structure exhibits a tiered consolidation, with a few large players offering integrated solutions alongside numerous niche component providers. Strategic archetypes include diversified aerospace conglomerates, dedicated lighting system manufacturers, and specialized electronics firms. These companies frequently engage in strategic partnerships to expand their portfolio and achieve greater market access, often through technology licensing or co-development efforts.
Within the diversified aerospace conglomerate tier, Honeywell International Inc. and Thales occupy significant positions, leveraging their extensive avionics and cabin electronics portfolios to offer integrated solutions. Astronics Corporation exemplifies a dedicated lighting system manufacturer, focusing on advanced illumination solutions for various aircraft applications across commercial and military segments. These firms anchor the industry by providing both integrated systems and critical components, while also driving innovation in areas like software-defined lighting and Li-Fi integration. Their presence ensures a competitive landscape that balances broad system offerings with specialized component expertise.
| Leading Market Players |
|---|
| Astronics Corporation |
| RTX Corporation |
| Diehl Stiftung & Co. KG |
| Honeywell International Inc. |
| Thales |
| Luminator Aerospace |
| STG Aerospace Limited |
| Cobham plc |
| Aveo Engineering Group |
| Others |
Cost & Logistics Intelligence
Wichita's long-standing aerospace manufacturing capacity directly influences downstream pricing power for aircraft lighting systems. This concentration of specialized production capabilities allows established suppliers to command premium pricing for certified components, reflecting the high barriers to entry in aerospace manufacturing.
Pricing Analysis
Industrial OEM buyers anchor long-term contract-based pricing for new aircraft lighting systems. Price differentiation arises from stringent certification levels, such as FAA and EASA compliance, and the degree of customization required for integrated cabin systems. Pricing pressure stems from the rapid adoption of LED technology, which offers lower total cost of ownership for airlines over the aircraft lifecycle. Commercial airlines demonstrate high price sensitivity for retrofit projects, prioritizing operational savings from new installations.
Supply Chain Analysis
Upstream component sourcing for aircraft lighting relies heavily on specialized electronics and material suppliers. Geographic supply concentration centers in the United States, France, and Germany for complex assemblies and integrated systems. Key raw material dependencies include high-brightness LEDs, specialized polymers for lenses, and microcontrollers for smart lighting systems. Single-source vulnerability for highly specialized, certified components poses a structural risk within the aerospace supply chain. Distribution runs primarily through direct sales channels to aircraft manufacturers and MRO providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, driven by the widespread transition to LED technology across the global commercial fleet.
For Market Incumbents: Pre-empt competitive threats from specialized electronics firms by accelerating R&D in software-defined lighting and Li-Fi integration. Consolidate market share through strategic acquisitions of niche technology providers that offer advanced sensor integration capabilities. Invest in expanding certification expertise across new regulatory frameworks for emerging air mobility platforms, mitigating the risk of new entrant disruption.
For New Entrants and Emerging Players: The rapidly growing Unmanned Aerial Vehicle (UAV) segment and Advanced Air Mobility (AAM) platforms represent highly penetrable entry points. Target specialized ultra-lightweight lighting solutions for navigation and signaling in these new application areas. A go-to-market angle focusing on rapid prototyping and agile certification pathways for specific niche requirements will differentiate offerings.
For Investors and Strategic Acquirers: Long-term, this sits as a technology-driven consolidation play because the market is shifting from hardware to integrated, software-defined systems. Identify acquisition targets with strong intellectual property in smart lighting controls or advanced material science for lightweighting. The signal to watch is the pace of regulatory approval for Li-Fi-enabled cabin systems and eVTOL lighting standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Software-Defined Lighting Platforms | Enhances system flexibility and integration with central cabin management systems for airlines. |
| Secure Advanced Material Supply Agreements | Ensures access to lightweight composites and specialized polymers for next-generation aircraft designs. |
| Pursue Li-Fi Technology Partnerships | Integrates data transmission capabilities into lighting fixtures, offering new cabin connectivity solutions. |
| Expand Certification Capabilities for eVTOLs | Positions the company to address the unique lighting requirements of emerging air mobility platforms. |
| Acquire Niche Sensor Integration Specialists | Strengthens offerings in smart lighting systems with real-time performance monitoring and environmental control. |
Research Approach
A spread of perspectives from aircraft engineers, airline procurement officers, MRO specialists, and regulatory body representatives converged on the working assumptions. This study combined extensive primary interviews with rigorous secondary validation from sources such as FAA directives, EASA mandates, and industry association reports. Bottom-up and top-down triangulation ensured robust market sizing and forecast accuracy across all segments.
Demand-supply balance formed the core analytical framework across the analysis window, projecting market evolution. Segmentation dimensions modeled included product type, technology, application, end-user, and aircraft class, such as wide-body versus narrow-body. Compound annual growth rates were derived from historical data trends and projected adoption curves, with key forecast inputs including global aircraft delivery schedules and LED penetration rates in retrofit markets.
Practitioners should monitor certification delays and raw material price volatility for early signals that could necessitate forecast revisions. Forecasts reflect assumptions regarding technological advancements and regulatory stability over the projection horizon. Cross-checking against external aerospace industry benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mini Pcs Market
Others
Connected TV Market
Others
Digital Audio Decoders Market
Others
Hypersensitivity Market
Others
Global Supply Chain Risk Management Software Market
Others
Wearable AI Market
Others
Space Cables Market
Others
Construction Wearables Market
Others
Computer on Module Market
Others
Global Digital Caliper Market
Others
Pickup Truck Market
Others
Halogen Free Flame Retardant Bopet Films Market
Others
Biopharma Plastics Market
Others
Viral Vector Contract Development and Manufacturing Organization (CDMO) Market
Others
Italy 3D Printing Construction Market
Others
Advanced Fiber-Based Gasket Market