
 Europe Military 4D Printing Market | 2026-2036
Europe Military 4D Printing Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Military 4D Printing Market Analytics
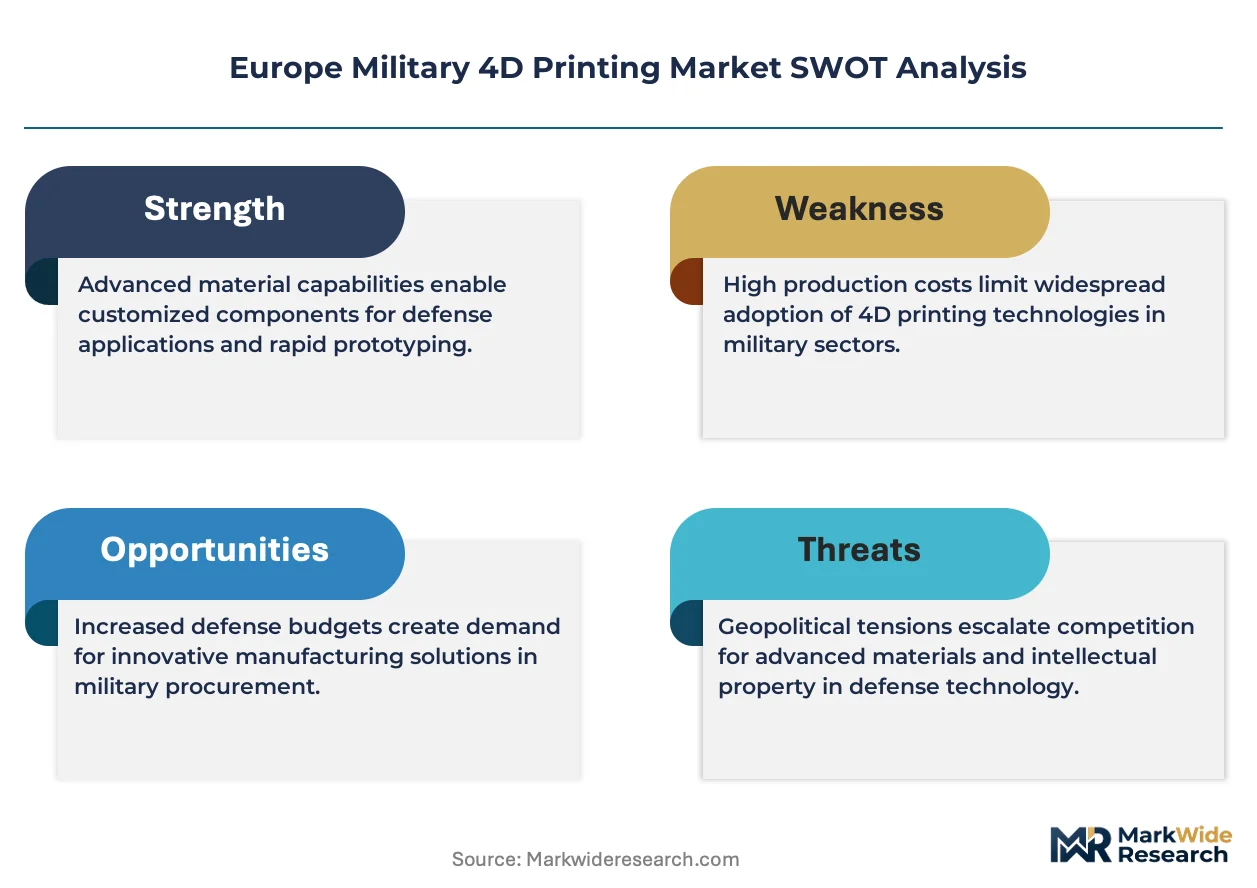
Modular weapon system configurations is rebalancing procurement patterns across European defense ministries. EOS GmbH leverages its laser sintering heritage to anchor high-reliability metal adaptive structures for military end users. Stratasys Ltd. competes through polymer expertise and channel control in deployable maintenance cells. Materialise NV differentiates via software-integrated build preparation that extends digital thread continuity from design to field operation.
Europe Military 4D Printing denotes additive manufacturing processes where printed objects autonomously transform shape, property, or function in response to external stimuli such as temperature, moisture, or electromagnetic fields, typically employing smart materials with programmed shape-memory behavior at layer resolutions below 100 microns. Its primary purpose centers on reducing logistics burden through self-assembling components and enabling field-repairable systems without fixed tooling infrastructure. Thermoplastics and adaptive materials command current volume leadership due to established supply chains and faster qualification pathways with military agencies. Embedded electronics and bio-inspired printing represent the fastest-expanding technology clusters as defense contractors pursue multifunctional structures combining sensing, actuation, and load-bearing in single builds.
REACH chemical safety standards, CE marking requirements for defense-critical systems, and the EU AI Act's emerging provisions on autonomous material behavior collectively shape product qualification timelines and market access conditions for suppliers. The European Defence Fund and EDA capability development programs channel public R&D investment toward dual-use 4D printing applications with explicit technology sovereignty objectives. Stakeholders must monitor how forthcoming harmonized military material standards interact with national procurement preferences to determine viable commercialization pathways.
Market Dynamics
Adaptive material qualification under REACH and the EU AI Act is compressing product development timelines while fragmenting supplier certification pathways across European defense ministries.
Growth Catalysts
- EU Green Deal mandates:Biodegradable polymer feedstocks gain procurement preference in German and French military tenders, accelerating supplier retooling toward sustainable chemistries.
- Field-repairable systems demand:Deployable maintenance cells reduce logistics burden for expeditionary forces, with thermoplastic adaptive structures enabling tool-free component replacement in theater.
- European Defence Fund allocations:Public R&D investment channels toward dual-use 4D printing applications with explicit technology sovereignty objectives, lowering private capital risk for early-stage developers.
Market Restraints
- Smart material input concentration:Shape-memory polymer precursors rely on limited German and Dutch specialty chemical suppliers, creating vulnerability to supply disruption.
- REACH compliance friction:Novel adaptive material chemistries face extended ECHA registration timelines, delaying military qualification by 18-36 months versus conventional alternatives.
- Fixed tooling substitution ceiling:High-reliability metal components in aerospace applications resist full displacement by 4D-printed equivalents due to established fatigue-life databases.
Strategic Opportunities
- Underpenetrated Nordic markets:Sweden and Finland maintain nascent 4D printing defense programs, offering first-mover positioning for adaptive structure suppliers before formal tender standardization.
- Embedded electronics convergence:Multifunctional structures combining sensing, actuation, and load-bearing in single builds open new specification categories in unmanned systems procurement.
- EDA capability development programs:European Defence Agency funding for cross-border technology demonstration projects reduces national procurement fragmentation barriers.
Industry Challenges
- Multiphysics simulation talent scarcity:Build preparation for stimulus-responsive materials requires combined expertise in thermal, mechanical, and electromagnetic modeling that defense contractors struggle to source.
- CE marking timeline compression:Harmonized military material standards remain under development, forcing suppliers to pursue parallel national certification tracks in Germany, France, and the United Kingdom.
- Digital thread integration complexity:Field-deployed 4D printing cells must interface with legacy logistics management systems that lack native adaptive manufacturing data structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Military 4D Printing Market |
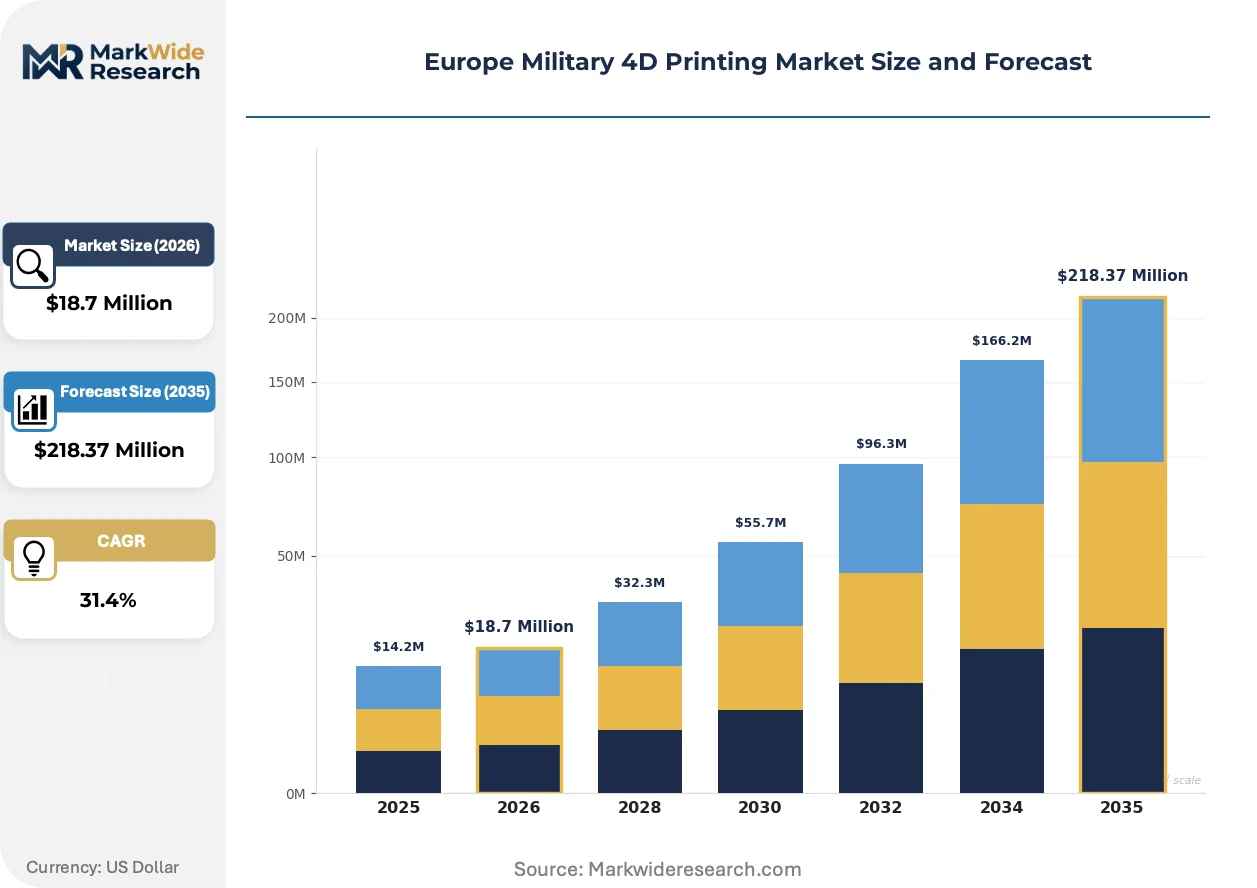
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $218.37 Million |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Materials, Biodegradable Polymers, Thermoplastics, Carbon Fiber End User: Defense Contractors, Aerospace Manufacturers, Military Agencies, Research Institutions Application: Weapon Systems, Supply Chain Logistics, Maintenance Repair, Prototyping Technology: Multi-Material Printing, Bio-Inspired Printing, Embedded Electronics, Adaptive Materials |
| Companies Covered | Stratasys Ltd., EOS GmbH, 3D Systems Corporation, Dassault Systèmes, Materialise NV, 3T Additive Manufacturing Ltd., Renishaw plc, Autodesk Inc., ExOne, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Military 4D Printing Market Evolving Landscape
Bio-inspired printing architectures and embedded intelligence layers are redefining performance benchmarks for military adaptive structures, with procurement specifications increasingly mandating multifunctional capability rather than passive mechanical properties.
Programmable shape-memory alloys with sub-100-micron layer resolution are expanding into deployable antenna and morphing airframe applications. French aerospace primes are qualifying these materials for satellite and unmanned aerial vehicle programs, compressing traditional multi-part assembly into single-build components that reconfigure post-deployment without external power.
REACH chemical safety standards are tightening precursor substance registration requirements for novel adaptive polymers. ECHA's 2023-2027 substance evaluation roadmap prioritizes defense-reactive chemistries, extending qualification timelines but creating competitive moats for suppliers with established registration portfolios, particularly in German industrial corridors where aerospace and defense procurement offices co-locate.
Defense ministries are consolidating specification-setting authority through centralized technical offices, displacing fragmented base-level procurement. The United Kingdom's Defence Equipment and Support organization now mandates adaptive structure performance data through standardized test protocols, compressing supplier evaluation cycles while raising technical entry barriers for smaller additive manufacturing service bureaus.
Europe Military 4D Printing Market Segmentation
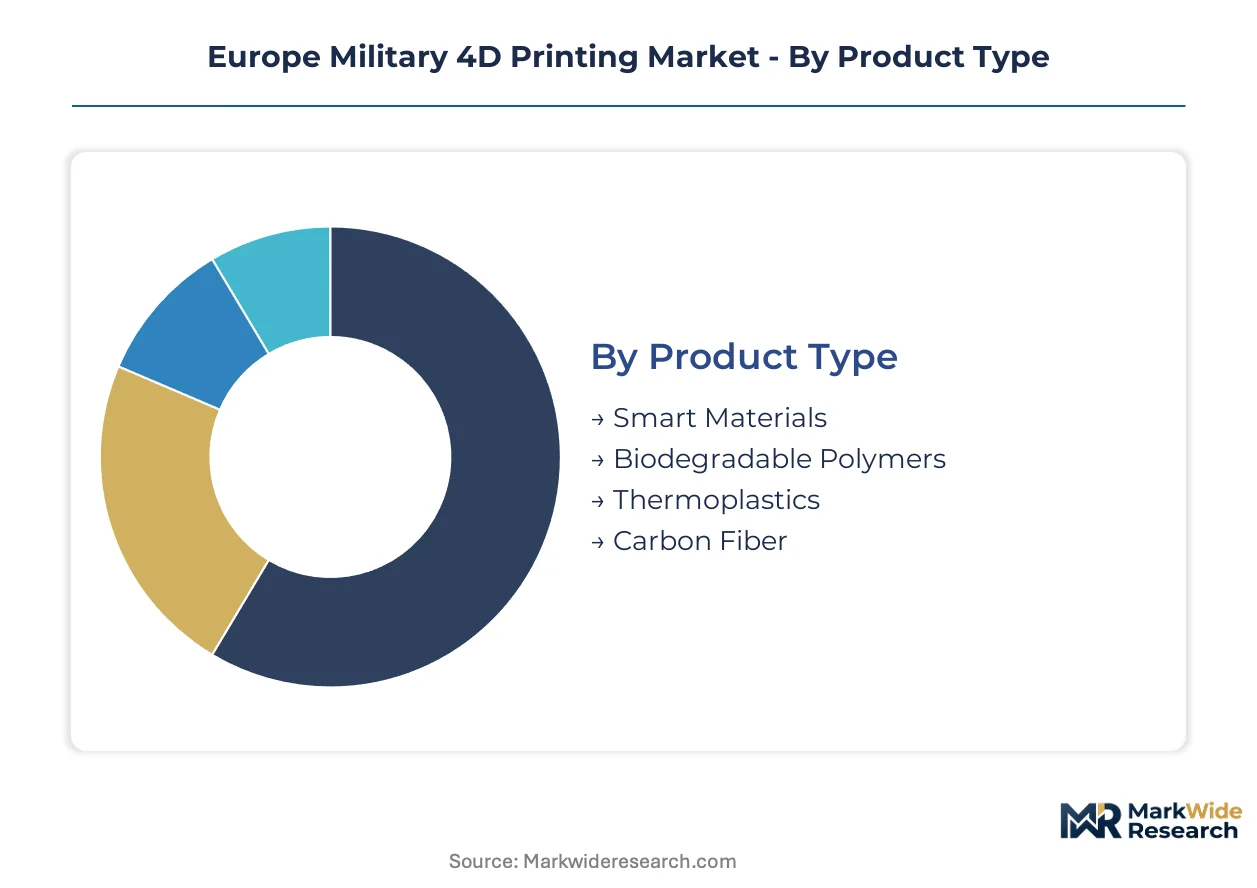
Segmentation in Europe Military 4D Printing reveals distinct procurement hierarchies across material chemistry, end-user sophistication, and application criticality. Defense ministries prioritize qualification pathways over raw performance, creating tiered adoption curves that suppliers must navigate.
Product Type:
Volume leadership concentrates in established polymer feedstocks with REACH registration, while premium positioning shifts toward stimulus-responsive chemistries with extended qualification timelines.
- Smart Materials:Shape-memory polymers and alloys programmed for autonomous transformation under thermal or electromagnetic stimulus. German defense contractors concentrate demand for deployable antenna and morphing airframe applications where field reconfiguration eliminates mechanical actuators. REACH registration portfolios create competitive moats for established suppliers.
- Biodegradable Polymers:EU Green Deal procurement preferences accelerate adoption in expeditionary logistics where disposal constraints dominate operational planning. French military tenders now mandate sustainable feedstocks for non-structural components, compressing supplier retooling timelines.
- Thermoplastics:PA12 and PEEK variants with established fatigue databases dominate current procurement volumes.
- Carbon Fiber:Continuous fiber reinforcement for load-bearing adaptive structures in aerospace applications.
Today's leader: Thermoplastics. Tomorrow's challenger: Smart Materials.
End User:
Procurement authority centralization is displacing fragmented base-level purchasing, with technical specification-setting migrating to centralized defense equipment organizations.
- Defense Contractors:Rheinmetall and Thales anchor demand for qualified adaptive structures in weapon prototyping programs. Their co-location with military procurement offices in German industrial corridors compresses iteration cycles. CE marking requirements for defense-critical systems raise technical entry barriers for smaller additive manufacturing service bureaus.
- Aerospace Manufacturers:Airbus Defence and Space qualifies programmable shape-memory alloys for satellite deployable structures. Sub-100-micron layer resolution specifications mandate precision that fragments supplier certification pathways across national procurement systems.
- Military Agencies:UK's Defence Equipment and Support organization now mandates standardized adaptive structure performance data.
- Research Institutions:European Defence Agency capability programs channel cross-border technology demonstration funding.
Defense Contractors concentrate current procurement value. Aerospace Manufacturers represent the steepest expansion trajectory as morphing airframe specifications mature.
Application:
Logistics burden reduction is displacing performance optimization as the primary procurement driver across European defense ministries.
- Weapon Systems:Modular configurations enable rapid caliber and mission profile adaptation without fixed tooling infrastructure. German and French programs prioritize self-assembling components that reduce forward-deployed spare part inventories. ECHA substance evaluation roadmaps extend qualification timelines for novel chemistries.
- Supply Chain Logistics:Deployable maintenance cells with tool-free component replacement address expeditionary force sustainment challenges. Thermoplastic adaptive structures dominate current procurement due to faster field qualification pathways.
- Maintenance Repair:Field-repairable systems eliminate dependency on rear-echelon fabrication capacity.
- Prototyping:Rapid iteration for concept validation before formal military qualification.
Weapon Systems anchor premium procurement. Supply Chain Logistics is gaining share fastest as logistics burden metrics enter tender evaluation frameworks.
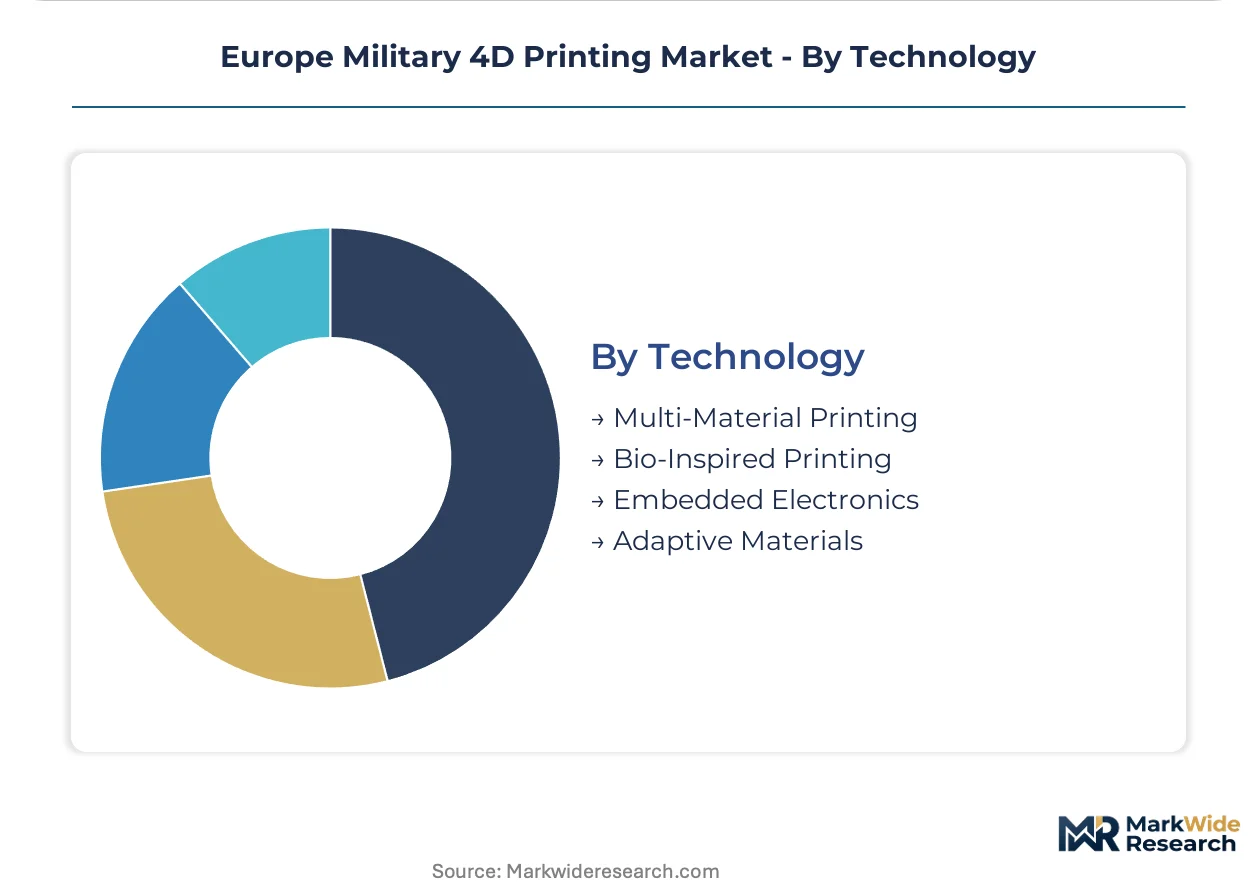
Technology:
Convergence of sensing, actuation, and load-bearing in single builds is redefining procurement specifications beyond passive mechanical properties.
- Embedded Electronics:Multifunctional structures combining antenna arrays, sensors, and structural elements in unified builds. French unmanned systems programs specify these for reduced part count and electromagnetic signature management. EU AI Act provisions on autonomous material behavior shape qualification timelines.
- Adaptive Materials:Stimulus-responsive chemistries with programmed shape-memory behavior at layer resolutions below 100 microns. Limited German and Dutch specialty chemical supplier concentration creates supply vulnerability that procurement offices monitor.
- Multi-Material Printing:Graduated property transitions within single components.
- Bio-Inspired Printing:Architectural patterns mimicking natural structures for optimized strength-to-weight ratios.
Adaptive Materials command current volume. Embedded Electronics represents the fastest-growing specification category as multifunctional requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's military 4D printing industry traces its operational roots to post-Cold War German defense industrial consolidation, when laser sintering expertise from aerospace subcontracting scaled into military qualification pathways. This heritage now shapes procurement patterns across the continent.
Germany
Rheinmetall and Thales anchor demand for adaptive weapon prototyping in the defense industrial corridor spanning Munich to Oberpfaffenhofen. The EU AI Act's provisions on autonomous material behavior compress development timelines for stimulus-responsive systems. Bavaria's aerospace primes co-locate with military procurement offices, enabling rapid iteration cycles for deployable maintenance cells.
France
Airbus Defence and Space qualifies programmable shape-memory alloys for satellite deployable structures with sub-100-micron resolution specifications. REACH chemical safety standards from ECHA extend qualification timelines for novel adaptive polymers by 18-36 months. The Île-de-France cluster concentrates unmanned systems programs demanding multifunctional structures combining sensing and load-bearing.
United Kingdom
Defence Equipment and Support now mandates standardized adaptive structure performance data through centralized technical offices, displacing fragmented base-level procurement. CE marking requirements for defense-critical systems raise entry barriers for smaller additive manufacturing service bureaus. The Midlands aerospace corridor hosts qualification programs for field-repairable thermoplastic components.
Sweden
Saab's defense programs drive nascent 4D printing adoption for expeditionary logistics applications with tool-free component replacement specifications. The European Defence Agency channels cross-border technology demonstration funding toward Nordic adaptive structure suppliers. Stockholm's research institutions partner with Finnish counterparts on bio-inspired printing architectures for strength-to-weight optimization.
Netherlands
Specialty chemical suppliers in the Eindhoven region concentrate shape-memory polymer precursor production, creating supply vulnerability that procurement offices monitor. ECHA's substance evaluation roadmap prioritizes defense-reactive chemistries through 2027. The Brabant manufacturing belt integrates software-integrated build preparation with legacy logistics management systems.
Europe Military 4D Printing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across qualification portfolio depth, with established REACH registration holdings commanding pricing power over unregistered entrants. The vendor base stratifies into three tiers: laser sintering heritage firms, polymer channel specialists, and software-integrated build preparation providers. Dominant competitive moves include strategic partnerships with defense procurement offices and portfolio diversification toward biodegradable feedstocks aligned with EU Green Deal mandates.
Within the laser sintering archetype, EOS GmbH exemplifies premium positioning through metal adaptive structure qualification for military end users. Stratasys Ltd. and Materialise NV occupy complementary positions across polymer expertise and software-integrated digital thread continuity. These three entities represent distinct competitive vectors: hardware heritage, material channel control, and design-to-field software integration.
| Leading Market Players |
|---|
| Stratasys Ltd. |
| EOS GmbH |
| 3D Systems Corporation |
| Dassault Systèmes |
| Materialise NV |
| 3T Additive Manufacturing Ltd. |
| Renishaw plc |
| Autodesk Inc. |
| ExOne |
| Others |
Value Network & Pricing Analysis
Sovereign-backed defense contractors and family-owned specialty chemical producers anchor supply-side ownership structures, compressing margin flexibility for downstream adaptive material suppliers while concentrating pricing power among REACH-registered incumbents in German industrial corridors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs adaptive material transactions, with certification grade under EU AI Act compliance and volume scale in military tenders serving as the primary price differentiation drivers. Cost compression in standard-grade thermoplastics is intensifying because biodegradable polymer feedstock suppliers face retooling investments to meet EU Green Deal mandates. Defense contractors exhibit the lowest price sensitivity due to qualification pathway rigidity, while research institutions demonstrate highest sensitivity given discretionary budget constraints.
Supply Chain Analysis
Domestic-content mandates under the European Defence Fund are reshaping sourcing patterns toward EU-27 qualified suppliers, displacing non-European precursor providers. Geographic supply concentration centers on Germany, the Netherlands, and France for shape-memory polymer precursors and laser sintering hardware. Raw material dependencies draw from specialty chemical feedstocks, precision optical components, and high-purity metal powders. Single-source vulnerability in Dutch shape-memory polymer precursor production creates structural supply risk. Distribution runs through defense procurement offices co-located with aerospace primes in Bavaria and Île-de-France clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH chemical safety standards and EU AI Act provisions on autonomous material behavior compound demand for pre-qualified adaptive structures.
For Market Incumbents: Extend REACH registration portfolios into novel biodegradable polymer chemistries before ECHA's substance evaluation roadmap tightens precursor access. Consolidate software-integrated build preparation capabilities to defend against emerging channel specialists threatening digital thread continuity. Vertical integration into German specialty chemical supply secures shape-memory polymer precursor access against Dutch supplier concentration risk.
For New Entrants and Emerging Players: Launch via embedded electronics convergence specifications in French unmanned systems programs where multifunctional structure demand outpaces qualified supplier capacity. Target Nordic expeditionary logistics applications in Sweden and Finland before formal tender standardization raises technical entry barriers. Position around bio-inspired printing architectures as a differentiation vector against established laser sintering heritage firms.
For Investors and Strategic Acquirers: Valuations sit cheapest among software-integrated build preparation providers lacking defense procurement office relationships. Long-term viability over a multi-year horizon hinges on EDA capability development program funding continuity and harmonized military material standard adoption. Watch ECHA registration portfolio depth as the primary inflection signal distinguishing acquirable specialists from stranded technology developers.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Portfolio Expansion | ECHA compliance moats protect margin position against unregistered entrants in German defense corridors. |
| Embedded Electronics Capability Buildout | French unmanned systems procurement mandates multifunctional structures combining sensing and load-bearing. |
| Biodegradable Polymer Feedstock Transition | EU Green Deal tender preferences accelerate supplier retooling toward sustainable chemistries. |
| Software-Integrated Digital Thread Investment | Build preparation continuity from design to field operation differentiates against hardware-centric competitors. |
| Nordic Market Pre-Standardization Entry | Swedish and Finnish expeditionary logistics programs offer first-mover positioning before tender formalization. |
Research Methodology
Bottom-up defense contractor procurement modeling reconciled against top-down adaptive material supplier capacity tracking forms the analytical core. Primary interviews with defense procurement officers, additive manufacturing R&D directors, ECHA regulatory affairs specialists, and aerospace prime supply chain managers combined with secondary validation from EDA capability development program disclosures, ECHA substance registration databases, and national military tender documentation. Triangulation across these sources ensures segment-level volume and value estimates reflect actual qualification pathway timelines and procurement authority centralization trends.
Historical trendline analysis of laser sintering and polymer additive manufacturing adoption in European defense applications informs the projection framework. Segmentation dimensions modeled include material chemistry tier, end-user sophistication level, application criticality, and technology convergence pattern. CAGRs derive from fitted adoption curves adjusted for REACH compliance friction and EU AI Act implementation pace. Industry-specific forecast inputs encompass ECHA substance evaluation roadmap priorities and European Defence Fund allocation trajectories across the analysis window.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration or delay, supply disruption in Dutch specialty chemical production, and breakthrough displacement of stimulus-responsive materials by alternative adaptive technologies. Forecasts reflect assumptions about procurement office co-location benefits and harmonized standard adoption timelines. A small set of named triggers warrants ongoing watch: ECHA registration timeline compression, EU AI Act enforcement interpretation, and Nordic defense program formalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Tobacco Packaging Market
Others
Smart Plug Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Electrical Calibration Equipment Market
Others
Massive Machine Type Communication in Healthcare Market
Others
South America Orange Market
Others
Residential Electrical Conduit Market
Others
Europe Medical Simulation Market
Others
Idaas Market
Others
Global OTA Testing Market
Others
Radar Speed Signs Market
Others
Binoculars and Mounting Solutions Market
Others
Internet of Things Testing Market
Others
Magnetic Stripe Readers Market
Others
South America Halal Food and Beverages Market
Others
Industrial Gauges Market