
 Global Hair Loss Treatment Products Market | 2026-2036
Global Hair Loss Treatment Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hair Loss Treatment Products Market Foresight
The EU Green Deal is pivoting formulation chemistry across hair loss treatment portfolios toward biodegradable excipients and reduced environmental persistence. L'Oréal S.A. anchors its European manufacturing with REACH-compliant active delivery systems and dedicated green chemistry labs. Procter & Gamble leverages consumer packaged goods scale to sustain mass-market minoxidil distribution across North American retail pharmacy networks. Pierre Fabre Laboratories specializes in dermatology-grade prescription portfolios that compete on clinical validation rather than price positioning.
Hair loss treatment products comprise pharmacological and cosmetic formulations designed to arrest follicle miniaturization, stimulate anagen phase extension, or cosmetically conceal thinning areas through keratin microfiber deposition or scalp pigmentation. Minoxidil-based solutions function as potassium channel openers that increase cutaneous blood flow to the follicular unit, while finasteride operates via 5-alpha-reductase inhibition to reduce dihydrotestosterone-mediated follicle atrophy. The product type dimension shows minoxidil sustaining the largest revenue pool due to over-the-counter accessibility, though hair growth serums incorporating peptide complexes and growth factor derivatives represent the fastest-expanding margin category as consumers migrate toward premium positioning. Within distribution channels, online retailers now capture disproportionate growth velocity relative to retail pharmacy, reflecting telehealth integration and subscription-based replenishment models that lock in recurring revenue.
FDA oversight of topical hair growth drugs and the EU MDR framework for dermatological devices create divergent compliance burdens that shape regional market access timelines and clinical trial investment requirements. India's CDSCO and China's NMPA maintain distinct bioequivalence standards for generic finasteride formulations that filter which manufacturers achieve commercialization rights. Stakeholders must monitor regulatory divergence between cosmetic and drug classification thresholds, as this boundary determines whether novel peptide-based formulations face prescription controls or achieve direct consumer marketing freedom.
Market Dynamics
Telehealth platform integration is compressing the traditional prescription pathway for hair loss therapies, collapsing the gap between diagnosis and treatment initiation while shifting pharmacy revenue toward direct-to-consumer fulfillment networks.
Growth Catalysts
- EU Green Deal chemical mandates:REACH-compliant reformulation requirements are accelerating biodegradable excipient adoption across European manufacturing facilities, creating first-mover advantages for compliant suppliers.
- Dermatology clinic channel expansion:Physician-directed protocols now capture disproportionate patient flow as consumers seek clinical validation for treatment selection, elevating prescription-grade portfolio demand.
- Peptide complex innovation:Growth factor derivative formulations are penetrating premium positioning tiers, commanding margin expansion beyond commoditized minoxidil alternatives.
Market Restraints
- API supply concentration:Generic finasteride active pharmaceutical ingredient production clusters in specific Asian manufacturing zones, exposing formulation partners to single-source vulnerability and customs processing delays.
- Regulatory classification friction:Cosmetic-drug boundary ambiguity under FDA and EU MDR frameworks forces dual-track compliance investment for novel peptide-based delivery systems before market access clarity emerges.
- Topical absorption ceiling:Cutaneous bioavailability limitations for large-molecule growth factors constrain clinical efficacy claims, compressing differentiation potential against established small-molecule alternatives.
Strategic Opportunities
- Subscription-based replenishment models:Direct-to-consumer platforms in the United States are locking recurring revenue through automated refill protocols, reducing patient attrition and acquisition cost amortization.
- India CDSCO bioequivalence pathway:Distinct generic approval standards for finasteride formulations create regulatory arbitrage for manufacturers achieving domestic manufacturing certification ahead of multinational entrants.
- Scalp microbiome modulation:Convergence of dermatological science and cosmetic positioning enables novel product categories occupying the regulatory gap between drug and personal care classification thresholds.
Industry Challenges
- Clinical trial design complexity:FDA hair growth endpoint requirements demand extended longitudinal studies with standardized photography protocols, extending time-to-market for novel mechanism candidates beyond typical dermatological development timelines.
- Telehealth platform integration friction:Legacy pharmacy distribution networks face technical reconfiguration demands to interface with prescription API systems from emerging digital health platforms, straining IT infrastructure budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hair Loss Treatment Products Market |
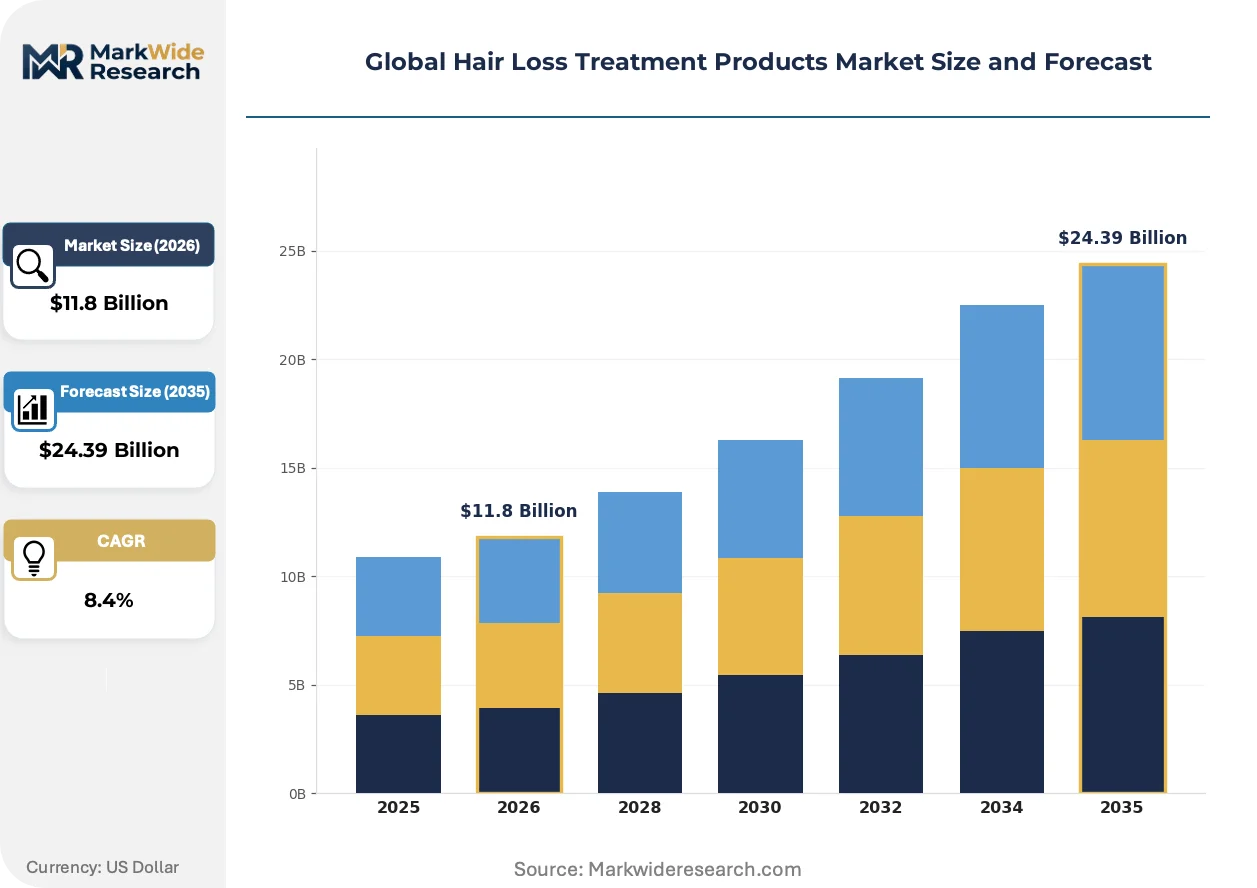
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minoxidil, Finasteride, Hair Growth Serums, Nutritional Supplements, Hair Fibers, Others Application: Androgenic Alopecia, Alopecia Areata, Telogen Effluvium, Scarring Alopecia, Trichotillomania End User: Dermatology Clinics, Trichology Centers, Beauty Salons, Pharmacies, E-commerce Platforms Distribution Channel: Retail Pharmacy, Online Retailers, Direct Sales, Specialist Distributors, Medical Stores |
| Companies Covered | The Procter & Gamble Company, L'Oréal S.A., Unilever, Merck & Co., Inc., Johnson & Johnson, Sun Pharmaceutical Industries Ltd, Cipla, Dr. Reddy's Laboratories Ltd., Pierre Fabre Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hair Loss Treatment Products Market Shifts & Advancements
Formulation science is pivoting toward biomimetic delivery systems that bypass traditional absorption barriers, while regulatory pressure and channel disintermediation simultaneously reshape competitive positioning across value chain tiers.
Low-level laser therapy devices are expanding into home-use segments previously dominated by clinic-based treatment protocols. Dermatology practices in Germany and South Korea now bundle these devices with topical prescriptions, compressing the addressable market for standalone hardware manufacturers while expanding recurring consumable attachment rates.
REACH authorization requirements for persistent organic pollutants are forcing excipient substitution across European manufacturing networks. Suppliers reformulating with plant-derived penetration enhancers face extended stability testing timelines, compressing near-term launch windows for portfolio refreshes while creating regulatory moats for compliant incumbents.
Patient acquisition through social media dermatology influencers is displacing traditional physician referral pathways in Brazil and Mexico. Telehealth platforms leverage algorithmic content distribution to identify early-stage hair loss candidates, funneling diagnostic consultations toward affiliated prescription fulfillment networks and fragmenting traditional pharmacy foot traffic.
Global Hair Loss Treatment Products Market Segmentation
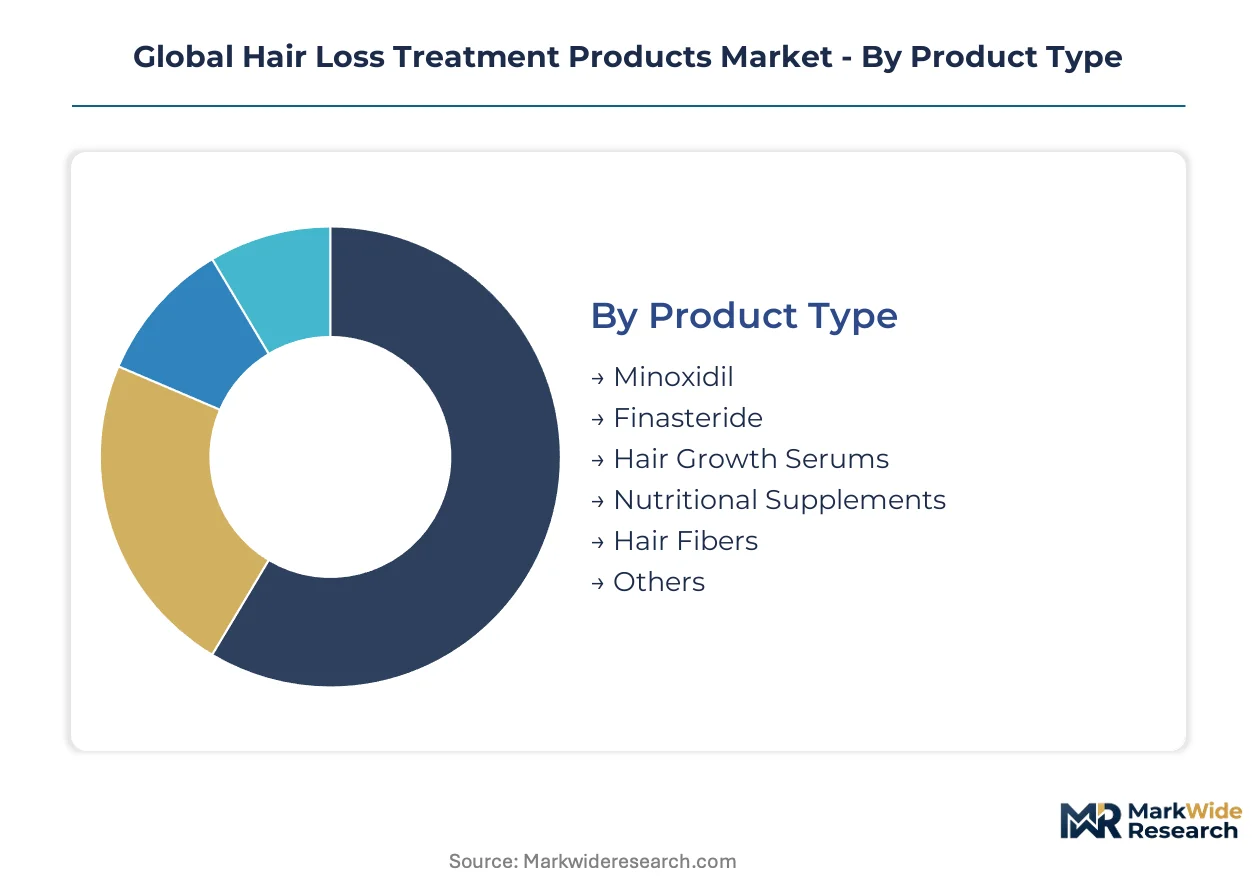
Segmentation in hair loss treatment products determines pricing power, regulatory pathway, and channel economics. Product chemistry and end-user setting together dictate whether formulations command prescription premiums or compete as mass-market commodities.
Product Type:
Upgrade cycles in this market track patent expiry and formulation innovation, with patients cycling between established small-molecule therapies and emerging biologic alternatives.
- Minoxidil:Potassium channel opener formulations dominate unit volume through over-the-counter availability across US retail pharmacy networks. Demand concentrates in North America where direct-to-consumer telehealth platforms bundle topical solutions with subscription replenishment.
- Hair Growth Serums:Peptide complex and growth factor derivative formulations penetrate premium positioning tiers, commanding margin expansion beyond commoditized alternatives. Adoption accelerates in Germany and South Korea where dermatology clinics bundle these with home-use laser devices.
- Finasteride:5-alpha-reductase inhibitors operate via prescription controls in most jurisdictions, with generic API production concentrated in Asian manufacturing zones.
- Nutritional Supplements:Biotin and mineral complexes occupy the cosmetic-drug regulatory boundary, enabling direct marketing freedom.
- Hair Fibers:Keratin microfiber deposition systems provide immediate cosmetic concealment without pharmacological claims.
- Others:Adjunct categories including scalp pigmentation and prosthetic systems serve niche aesthetic demands.
Minoxidil sits at the top of the volume ranking, with hair growth serums climbing the fastest.
Application:
Application-based segmentation aligns with diagnostic specificity and reimbursement eligibility, with pattern hair loss commanding the largest addressable population.
- Androgenic Alopecia:Pattern hair loss driven by dihydrotestosterone-mediated follicle miniaturization represents the primary indication for minoxidil and finasteride protocols. Patient flow concentrates in United States dermatology clinics where physician-directed validation drives prescription-grade portfolio selection.
- Alopecia Areata:Autoimmune-mediated patchy hair loss requires immunomodulatory interventions, expanding the addressable market for corticosteroid and JAK inhibitor pipelines. Treatment demand clusters in specialty dermatology centers across France and Japan where advanced biologic access is concentrated.
- Telogen Effluvium:Stress-triggered diffuse shedding responds to nutritional supplementation and trigger removal rather than pharmacological intervention.
- Scarring Alopecia:Irreversible follicular destruction limits therapeutic options to disease arrest rather than regeneration.
- Trichotillomania:Behavioral hair pulling requires psychiatric comanagement, constraining pure dermatology product applicability.
Androgenic alopecia captures the dominant revenue share, with alopecia areata demonstrating the steepest expansion trajectory as biologic pipelines mature.
End User:
End-user channel selection determines clinical validation requirements and pricing architecture, with institutional settings commanding premium positioning.
- Dermatology Clinics:Physician-directed protocols now capture disproportionate patient flow as consumers seek clinical validation for treatment selection. Channel expansion accelerates in Germany where bundled device-and-formula protocols compress standalone hardware markets.
- E-commerce Platforms:Direct-to-consumer fulfillment networks leverage telehealth integration and subscription-based replenishment models that lock in recurring revenue. Platform growth concentrates in the United States where prescription API systems interface with digital health infrastructure.
- Trichology Centers:Specialized hair science facilities bridge cosmetic and medical positioning.
- Beauty Salons:Non-clinical settings are limited to cosmetic-grade products without pharmacological claims.
- Pharmacies:Traditional retail pharmacy networks face technical reconfiguration demands to interface with emerging digital health platforms.
Dermatology clinics anchor the premium tier by volume, while e-commerce platforms gain share fastest through telehealth integration.
Distribution Channel:
Channel structure reflects regulatory classification thresholds and patient acquisition economics, with digital platforms displacing traditional pharmacy foot traffic.
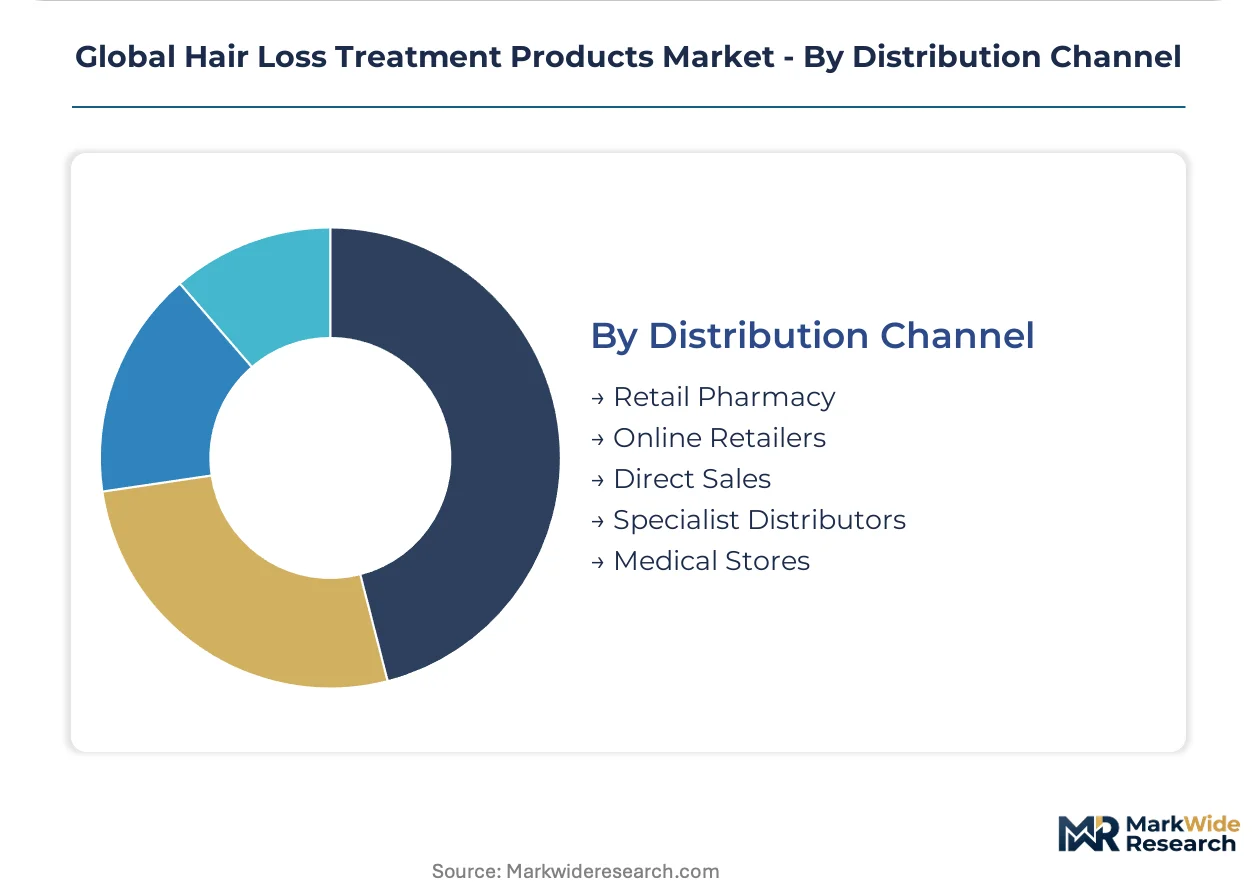
- Online Retailers:Subscription-based replenishment models reduce patient attrition and acquisition cost amortization through automated refill protocols. Channel velocity concentrates in US direct-to-consumer networks where telehealth diagnosis collapses the gap between consultation and treatment initiation.
- Retail Pharmacy:Mass-market minoxidil distribution sustains volume across North American networks, though legacy infrastructure faces technical demands to interface with prescription API systems from digital health platforms.
- Direct Sales:Manufacturer-controlled channels enable margin capture but limit reach.
- Specialist Distributors:Dermatology-focused logistics serve clinic and hospital procurement.
- Medical Stores:Institutional supply chains support hospital outpatient dispensing.
Retail pharmacy maintains volume leadership, with online retailers expanding most quickly through subscription lock-in mechanics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The hair loss treatment industry traces its modern commercial origins to United States pharmaceutical development of minoxidil in the 1980s, with subsequent formulation advances spreading through European dermatology networks and Asian manufacturing clusters.
United States
Direct-to-consumer telehealth platforms drive prescription volume for topical and oral therapies, collapsing traditional diagnosis-to-treatment timelines. FDA oversight of topical hair growth drugs shapes clinical trial investment requirements and endpoint standardization. Dermatology practices in New York and Los Angeles anchor physician-directed protocol adoption, bundling prescription-grade portfolios with home-use device recommendations.
Germany
REACH-compliant reformulation mandates accelerate biodegradable excipient adoption across manufacturing facilities. EU MDR framework for dermatological devices creates distinct compliance burdens for laser therapy hardware. The Rhine-Ruhr industrial corridor hosts specialized suppliers reformulating with plant-derived penetration enhancers under extended stability testing protocols.
China
NMPA maintains distinct bioequivalence standards for generic finasteride formulations that filter commercialization rights. Domestic manufacturing certification creates regulatory arbitrage for local producers ahead of multinational entrants. Yangtze River Delta clusters concentrate active pharmaceutical ingredient production, exposing formulation partners to single-source vulnerability.
India
CDSCO bioequivalence pathway for generic finasteride enables domestic manufacturers to achieve approval ahead of foreign competitors. Sun Pharmaceutical Industries Ltd and Dr. Reddy's Laboratories Ltd anchor generic API production capacity. Mumbai-Pune pharmaceutical corridor supplies formulation partners globally, though customs processing delays periodically disrupt supply chains.
South Korea
Dermatology clinics bundle low-level laser therapy devices with topical prescriptions, compressing standalone hardware markets while expanding consumable attachment rates. MFDS regulates device-therapy combination protocols. Seoul Capital Area concentrates advanced clinic networks and home-use device distribution, driving premium positioning for peptide complex formulations.
Global Hair Loss Treatment Products Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation chemistry and channel access dimensions. The market structure fragments between mass-market consumer packaged goods distributors and specialized dermatology-grade prescription portfolios. Three archetypes dominate: telehealth-integrated direct-to-consumer platforms, REACH-compliant European formulators, and generic API-integrated Asian manufacturers. Competitive moves concentrate on subscription-based replenishment model deployment and regulatory arbitrage through domestic manufacturing certification.
Within the consumer packaged goods tier, The Procter & Gamble Company and Unilever occupy positions anchored in retail pharmacy network scale. L'Oréal S.A. exemplifies the European formulator archetype with dedicated green chemistry labs. Among prescription-grade specialists, Merck & Co., Inc. and Pierre Fabre Laboratories represent clinical validation-focused positioning. Sun Pharmaceutical Industries Ltd and Dr. Reddy's Laboratories Ltd sit within the generic API-integrated manufacturing tier. Johnson & Johnson and Cipla occupy intermediate positions spanning consumer and professional channels.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| L'Oréal S.A. |
| Unilever |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Sun Pharmaceutical Industries Ltd |
| Cipla |
| Dr. Reddy's Laboratories Ltd. |
| Pierre Fabre Laboratories |
| Others |
Supply & Pricing Matrix
Telehealth-driven subscription procurement in the United States is forcing supply chain reconfiguration toward direct-to-consumer fulfillment networks, compressing wholesale margins while elevating last-mile logistics costs as the dominant pricing determinant.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by clinical validation depth and channel access. Price differentiation rests on FDA prescription classification versus cosmetic positioning, with dermatology clinic distribution commanding substantial premiums over retail pharmacy alternatives. Cost compression in the mass-market minoxidil tier is intensifying because telehealth platforms bypass traditional wholesale markups. Small-molecule generic formulations exhibit highest buyer price sensitivity, while peptide complex serums retain inelastic demand among clinic-directed patients.
Supply Chain Analysis
REACH-compliant manufacturing certification gates European supplier participation, filtering formulation partners by green chemistry capability. Active pharmaceutical ingredient production clusters in India, China, and select Italian manufacturing zones, with generic finasteride synthesis drawing from concentrated Asian chemical intermediates. Single-source vulnerability permeates the peptide derivative segment where specialized bioreactor capacity remains scarce. Distribution runs through direct-to-consumer platforms fastest, though retail pharmacy networks sustain volume leadership in North American minoxidil replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into competitive advantage, with the EU Green Deal's chemical safety mandates accelerating demand for compliant formulation partners.
For Market Incumbents: Lock in backward integration into active pharmaceutical ingredient supply through captive manufacturing certification in India or China, insulating against customs processing disruptions. Secure REACH-compliant green chemistry lab capacity ahead of competitor portfolio refreshes, converting regulatory burden into supply scarcity rent. For New Entrants and Emerging Players: Scalp microbiome modulation technologies offer a technology-first wedge into the regulatory gap between cosmetic and drug classification thresholds. Target the trichology center channel in Brazil and Mexico where social media dermatology influencers displace traditional physician referrals, deploying algorithmic patient acquisition as the primary go-to-market mechanism. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic manufacturing-certified Indian generic producers positioned ahead of multinational bioequivalence filings. Five-to-ten year viability hinges on regulatory arbitrage durability rather than pipeline depth alone. Watch for FDA clarification on peptide-based growth factor classification thresholds as the decisive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Subscription-Based Replenishment Model Deployment | Telehealth platforms in the United States lock recurring revenue through automated refill protocols that reduce patient attrition. |
| REACH-Compliant Green Chemistry Lab Investment | European manufacturing facilities achieve first-mover advantage in biodegradable excipient adoption under EU Green Deal mandates. |
| Domestic Manufacturing Certification in India | CDSCO bioequivalence pathway enables generic finasteride producers to secure commercialization rights ahead of foreign entrants. |
| Peptide Complex Formulation Pipeline Expansion | Dermatology clinics in Germany and South Korea bundle growth factor derivatives with home-use laser devices, expanding consumable attachment. |
| Direct-to-Consumer Telehealth Platform Integration | Prescription API system interfaces collapse diagnosis-to-treatment timelines while shifting pharmacy revenue toward fulfillment networks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dermatology clinic directors, telehealth platform executives, regulatory affairs specialists at formulation manufacturers, and retail pharmacy procurement managers with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and REACH authorization databases. Bottom-up patient flow modeling and top-down revenue triangulation anchored volume and value estimates.
Comparable-period anchoring linked projection assumptions to historical prescription volume trends and clinic visit patterns across the analysis window. Segmentation dimensions spanned product chemistry tier, distribution channel architecture, end-user setting, and regional regulatory cluster. CAGRs derived from longitudinal patient cohort tracking and pricing trajectory analysis, with telehealth penetration rates and green chemistry compliance timelines as industry-specific forecast inputs.
The model holds under stable regulatory classification boundaries; deviation in FDA peptide-drug determination or EU MDR device-therapy bundling rules would shift channel economics materially. A model refresh is warranted upon material change in REACH authorization timelines or CDSCO bioequivalence standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
North America Micro Market
Others
Stand-Up Pouch Valves Market
Others
Fresh Durian Market
Others
Europe Travel Retail Market
Others
Asia-Pacific Social Media Management Market
Others
Ceramic Machinery Market
Others
Dry-Cleaning and Laundry Services Market
Others
Middle East Location-Based Services Market
Others
UK Cat Food Market
Others
Rugged Devices Market
Others
Europe Meditation Market
Others
US 3D Printing Construction Market
Others
Idaas Market
Others
North America Healthcare Flexible Packaging Market
Others
Global Smartphone ODM Market
Others
Level Measuring Instrument Market