
 Kuwait Retail Market | 2026-2036
Kuwait Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Retail Market Insights
Sustainable packaging materials is broadening product economics across grocery and home goods categories. Alshaya Group leverages its franchise portfolio to sustain brand density across luxury and mid-range tiers. Lulu Hypermarket anchors fresh food procurement through backward integration into regional supply chains. Majid Al Futtaim competes on experiential retail formats that differentiate mall assets from standard shopping centers.
Kuwait Retail encompasses the sale of finished consumer goods through physical and digital channels to end users, spanning perishable foodstuffs, durable electronics, apparel, and household merchandise with inventory turnover cycles ranging from daily replenishment for groceries to seasonal rotation for fashion. Its commercial purpose centers on matching household and individual consumption needs with localized product assortments, payment flexibility, and fulfillment convenience. The grocery segment leads transaction volume due to recurring purchase frequency, while electronics commands margin concentration from premium pricing and warranty attach rates. Online channels represent the fastest-growing distribution vector as logistics networks and digital payment penetration mature, though hypermarkets retain basket-size advantages through one-stop assortment breadth.
Kuwait's Ministry of Commerce and Industry enforces consumer protection standards that shape product labeling, return policies, and e-commerce seller registration requirements. The Central Bank of Kuwait governs digital payment infrastructure and fintech participation, directly enabling or constraining online retail transaction flow. Stakeholders must monitor how regulatory tightening on cross-border e-commerce and data localization intersects with platform expansion strategies to determine capital allocation between digital and physical channel development.

Market Dynamics
Kuwait's retail sector is experiencing structural compression as digital payment infrastructure matures and the Ministry of Commerce and Industry tightens consumer protection frameworks for e-commerce transactions. Young professional residents in Kuwait City and Salmiya corridors are accelerating channel migration toward mobile-first purchasing behaviors.
Growth Catalysts
- Consumer Protection Frameworks:Kuwait's Ministry of Commerce and Industry mandates stricter e-commerce seller registration and return policies. These regulations build transaction trust and reduce friction for first-time digital buyers.
- Logistics Infrastructure Clustering:Warehouse and fulfillment networks concentrate along the Kuwait City-Salmiya corridor. Proximity to dense residential populations enables same-day delivery economics for grocery and electronics categories.
- Digital Payment Penetration:The Central Bank of Kuwait governs fintech participation and digital wallet standards. Expanded payment rails reduce cash-handling costs for merchants and unlock subscription-based retail models.
Market Restraints
- Import Dependency for Electronics:Kuwait retains minimal domestic manufacturing for smartphones, laptops, and appliances. Currency fluctuation and shipping lane congestion transmit directly to shelf-price volatility.
- Commercial Real Estate Concentration:Premium mall assets in Kuwait City and Salmiya command elevated occupancy costs. Smaller retailers face margin compression from rent escalation clauses tied to footfall guarantees.
- Labor Market Tightness:Retail operations rely heavily on expatriate workforce segments. Visa quota restrictions and wage inflation in logistics functions constrain store expansion timelines.
Strategic Opportunities
- Hawalli Governorate Penetration:Suburban corridors east of Kuwait City show rising household formation rates with underserved mall density. Early movers can secure anchor tenant positions before rent premiums adjust.
- Fresh Food Backward Integration:Regional supply chain partnerships with Saudi and UAE agricultural producers reduce perishables spoilage. Direct procurement relationships bypass wholesale markups and improve margin capture.
- Experiential Format Differentiation:Entertainment-anchored retail concepts attract extended dwell times. Mixed-use developments combining cinema, dining, and curated merchandise resist pure-play e-commerce substitution.
Industry Challenges
- Last-Mile Temperature Control:Grocery e-commerce requires refrigerated fleet assets that strain capital deployment. Kuwait's summer heat peaks demand specialized vehicle specifications absent from standard logistics networks.
- Cross-Border Data Localization:Regulatory tightening on customer data storage complicates platform expansion strategies. Retailers must architect separate technical infrastructure for Kuwaiti transaction records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Retail Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clothing, Electronics, Groceries, Home Goods Price Tier: Luxury, Mid-Range, Budget, Discount Distribution Channel: Online, Hypermarkets, Traditional Markets, Convenience Stores Customer Type: Residents, Tourists, Corporates, Students |
| Companies Covered | Alshaya Group, The Sultan Center, Lulu Hypermarket, Majid Al Futtaim, Alghanim Industries, Carrefour, Al Mulla Group, Kout Food Group, United Foodstuff Industries Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Retail Market Trends and Innovations
Mobile commerce architectures are reshaping how Kuwaiti retailers architect customer journeys, with payment integration and inventory visibility converging into single-platform experiences. Three distinct vectors are compressing traditional competitive advantages.
AI-powered demand forecasting is overtaking static replenishment systems in grocery and fashion categories. Majid Al Futtaim and Alshaya Group deploy machine learning models that adjust stock positioning hourly based on weather, events, and social sentiment. This capability is compressing working capital requirements and reducing end-of-season markdown depth.
Kuwait's Ministry of Commerce and Industry implemented mandatory product labeling standards for imported electronics and apparel. The regulation forces sellers to disclose country of origin, material composition, and warranty terms in Arabic. Electronics retailers with complex supplier networks face the steepest compliance costs, accelerating consolidation toward distributors with in-house certification capabilities.
Subscription-based replenishment models are capturing recurring grocery and personal care purchases that previously cycled through hypermarket baskets. Young professional households in Salmiya and Jabriya prioritize convenience over assortment breadth. This behavioral shift is most visible in dairy, household cleaners, and premium pet food categories where auto-delivery locks in supplier relationships.
Kuwait Retail Market Segmentation
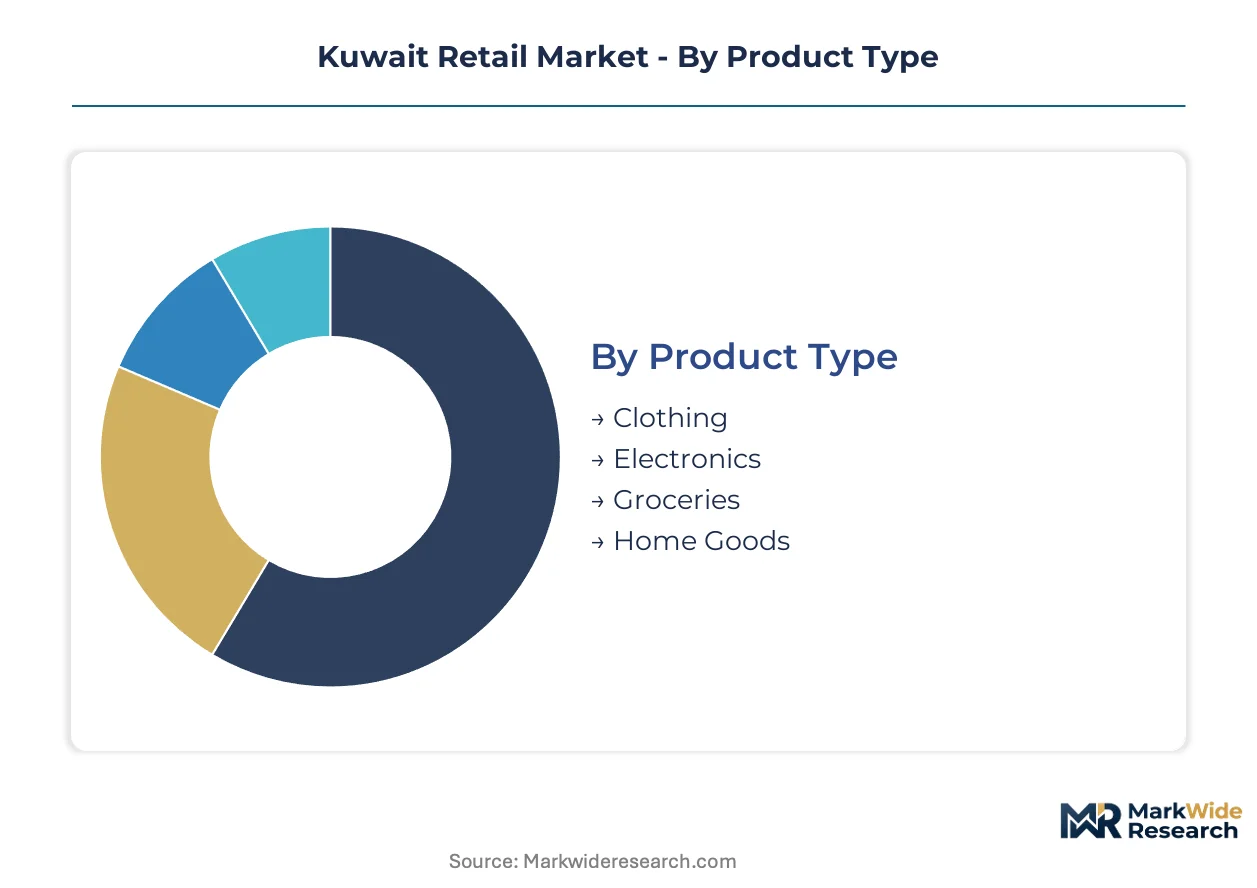
Segmentation reveals how capital deployment and margin capture vary across Kuwait's retail landscape. Product mix and channel configuration determine working capital intensity, while customer composition shapes loyalty economics and basket profitability.
Product Type:
Capital intensity diverges sharply across product categories, with electronics and home goods demanding the highest inventory investment per square meter.
- Clothing:Seasonal rotation cycles compress working capital efficiency. Kuwait City and Salmiya corridors concentrate fashion demand where Alshaya Group's franchise density enables rapid style turnover.
- Electronics:Premium smartphones and laptops carry high unit values with extended warranty attach revenue. Young professionals in Jabriya and Hawalli drive replacement cycles, though import dependency exposes margins to currency fluctuation.
- Groceries:Daily replenishment requirements dominate transaction volume. Lulu Hypermarket's backward integration into regional agricultural supply chains reduces spoilage losses in perishables.
- Home Goods:Slower inventory velocity requires larger warehouse footprints. Demand clusters around new household formation in suburban governorates with limited mall density.
Most installed capacity flows through Groceries. Expansion is steepest in Electronics.
Price Tier:
Margin structure stratifies across pricing tiers, with luxury commanding the highest gross margins but requiring experiential store formats.
- Luxury:Experiential service standards and exclusive distribution rights justify premium positioning. Majid Al Futtaim's mall assets in Kuwait City concentrate high-net-worth footfall for watch and leather goods categories.
- Mid-Range:Franchise-operated brands balance accessibility with quality signaling. Alshaya Group's portfolio density across this tier captures young professional household formation.
- Budget:Private-label penetration and simplified service models reduce operating costs. Hypermarket operators leverage scale procurement to undercut specialized retailers on household essentials.
- Discount:Hard-discount formats with limited SKUs and warehouse-style presentation target price-sensitive expatriate segments. Store economics depend on high inventory turnover and minimal staff-to-customer ratios.
Revenue concentration sits with Mid-Range. Share gains are climbing fastest in Discount.
Distribution Channel:
Channel economics reshape competitive positioning as logistics infrastructure and digital payment rails mature across Kuwait's urban corridors.
- Online:Mobile-first architectures integrate payment and inventory visibility into unified platforms. Same-day delivery economics concentrate in the Kuwait City-Salmiya corridor where warehouse proximity enables grocery and electronics fulfillment.
- Hypermarkets:One-stop assortment breadth sustains basket-size advantages over specialized competitors. Temperature-controlled fresh food sections require capital-intensive refrigeration infrastructure that smaller formats cannot replicate.
- Traditional Markets:Negotiated pricing and sensory product evaluation retain preference among older demographic segments. Souk Al-Mubarakiya anchors this channel with concentrated textile and gold merchant density.
- Convenience Stores:Proximity-based impulse purchasing captures emergency replenishment occasions. Petroleum retail operators leverage forecourt locations for extended hours and high-frequency traffic.
Transaction volume concentrates in Hypermarkets. Digital channel expansion is accelerating most quickly in Online.
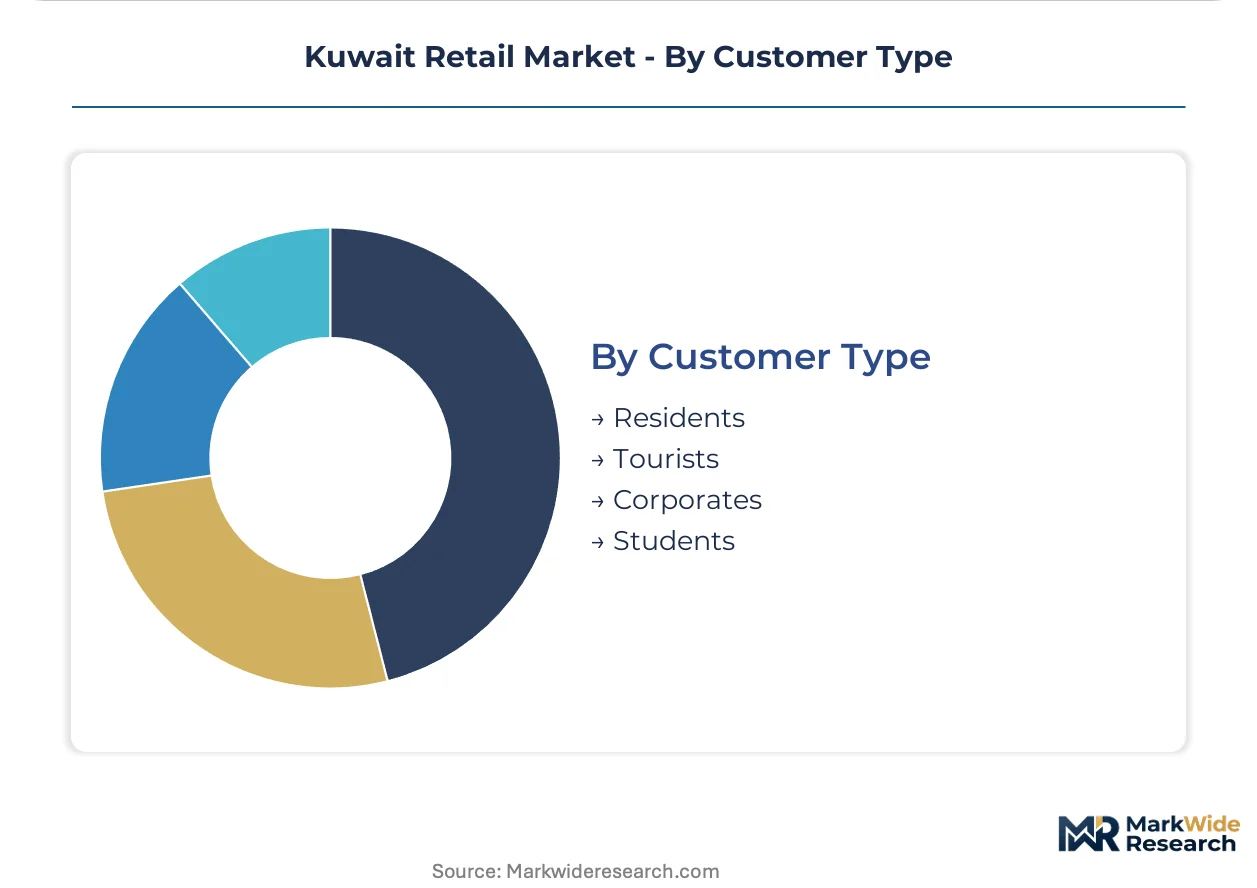
Customer Type:
Customer composition determines loyalty program design and promotional calendar intensity across Kuwait's retail ecosystem.
- Residents:Recurring purchase patterns enable subscription-based replenishment models for groceries and personal care. Young professional households in Salmiya and Jabriya prioritize convenience over assortment breadth.
- Tourists:Seasonal demand spikes concentrate in luxury and souvenir categories. Mall operators coordinate with hospitality partners to capture transit spending from Gulf Cooperation Council visitors.
- Corporates:Bulk procurement contracts for electronics and office supplies emphasize volume pricing and dedicated account management. Tender processes favor distributors with certification capabilities for Ministry of Commerce and Industry compliance.
- Students:Price sensitivity and digital-native behavior drive mobile commerce adoption. Back-to-school seasonal peaks concentrate electronics and apparel demand in late summer months.
Revenue foundation rests with Residents. Corporate segment growth is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kuwait City-Salmiya corridor anchors retail density through concentrated mall assets and fulfillment infrastructure. Young professional households drive electronics and premium apparel demand through mobile-first purchasing behaviors. The Central Bank of Kuwait governs digital payment rails that enable same-day delivery economics across grocery and electronics categories.
Kuwait City Governorate
Luxury watch and leather goods demand concentrates in The Avenues Mall and 360 Mall complexes. The Ministry of Commerce and Industry mandates Arabic-language product labeling for all imported electronics and apparel. Retailers in Sharq and Qibla districts deploy experiential formats combining cinema, dining, and curated merchandise to extend dwell times.
Hawalli Governorate
Salmiya and Jabriya corridors show rising household formation with underserved mall density relative to population growth. Consumer protection frameworks require stricter e-commerce seller registration and standardized return policies. Logistics providers cluster warehouse assets along the Fourth Ring Road to enable same-day grocery fulfillment for young professional residents.
Ahmadi Governorate
Petroleum retail operators leverage forecourt locations for convenience store expansion targeting emergency replenishment occasions. The Ministry of Commerce and Industry tightened cross-border data localization requirements for customer transaction records. Fahaheel and Mangaf districts concentrate hypermarket development serving industrial workforce segments with price-sensitive purchasing patterns.
Farwaniya Governorate
Expatriate-dense neighborhoods in Riggae and Jleeb Al-Shuyoukh sustain demand for budget-tier apparel and household essentials. Central Bank of Kuwait digital wallet standards reduce cash-handling costs for merchants in high-volume corridors. Traditional souk formats in Farwaniya district retain negotiated pricing preferences among older demographic segments.
Kuwait Retail Market Competitive Landscape
Franchise portfolio diversification dominates the current landscape as operators defend market position through brand density across price tiers. The vendor base concentrates around family-owned conglomerates with vertical control over real estate and supply chain functions. Three archetypes define competitive positioning: franchise aggregators with multi-brand portfolios, hypermarket operators with backward-integrated fresh food procurement, and mall developers with experiential format differentiation. Capacity expansion into suburban corridors and strategic partnerships with regional agricultural producers represent the dominant competitive vectors.
Within the franchise-aggregator tier, Alshaya Group and Alghanim Industries occupy positions defined by brand density across luxury and mid-range segments. Alshaya leverages its portfolio breadth to capture young professional household formation in Salmiya and Jabriya corridors. Alghanim Industries anchors its position through diversified holdings spanning retail, automotive, and consumer durables. Among hypermarket specialists, Lulu Hypermarket exemplifies backward integration into regional supply chains, while Majid Al Futtaim represents the experiential-format archetype through mall assets that combine entertainment and retail functions. The Sultan Center and Carrefour sit within the grocery-dominant tier where fresh food procurement capabilities determine margin capture.
| Leading Market Players |
|---|
| Alshaya Group |
| The Sultan Center |
| Lulu Hypermarket |
| Majid Al Futtaim |
| Alghanim Industries |
| Carrefour |
| Al Mulla Group |
| Kout Food Group |
| United Foodstuff Industries Group |
| Others |
Pricing and Supply Chain Analysis
Brent crude price movements cascade through Kuwait's retail economy via shipping fuel surcharges and polymer packaging costs, compressing margins in grocery and home goods while electronics retailers absorb currency fluctuation through warranty attach revenue. Young professional households in Salmiya and Jabriya corridors experience this pass-through as shelf-price volatility in fresh food categories and premium apparel, driving subscription-based replenishment adoption to lock in predictable expenditure.
Pricing Analysis
Input-cost pass-through from freight and polymer indices shapes three-tier pricing structure across premium, standard, and economy levels in Kuwait's retail landscape. Electronics retailers differentiate through after-sales service bundling and warranty tier depth, while grocery operators compete on volume scale and private-label penetration. Pricing pressure stems from import dependency for smartphones and appliances, with currency fluctuation transmitting directly to shelf prices. Expatriate workforce segments in Farwaniya and Ahmadi governorates exhibit highest price sensitivity, whereas luxury watch and leather goods buyers in Kuwait City show least elasticity.
Supply Chain Analysis
Direct-to-hypermarket procurement channels handle bulk fresh food demand through Lulu Hypermarket's backward integration into Saudi and UAE agricultural supply chains. Kuwait's retail sector draws finished electronics from China, South Korea, and Vietnam, with perishable groceries sourcing from regional producers in Saudi Arabia, UAE, and Jordan. Single-source vulnerability concentrates in smartphone component supply from East Asian fabrication facilities. Distribution runs through mall-anchored retail complexes in Kuwait City and Salmiya corridors, with emerging warehouse clustering along Fourth Ring Road enabling same-day fulfillment economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
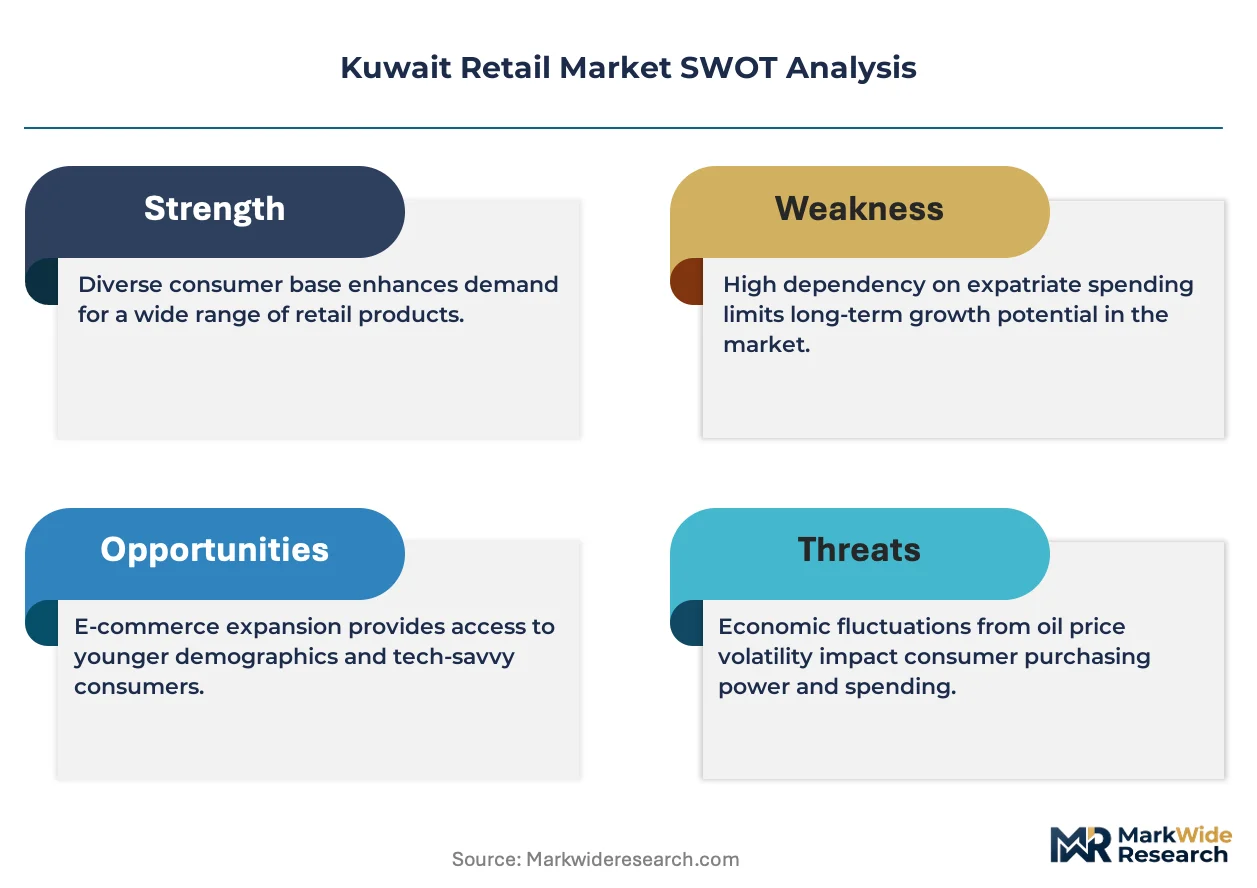
Kuwait Retail functions as a stable compounder anchored by recurring grocery purchase frequency and young professional household formation in dense urban corridors. Digital payment maturation and logistics infrastructure clustering create durable competitive moats for operators with scale procurement capabilities.
For Market Incumbents: Deepen backward integration into regional agricultural supply chains to defend fresh food margins against spoilage losses and wholesale markup compression. Alshaya Group and Majid Al Futtaim should expand experiential format differentiation in Hawalli Governorate before rent premiums adjust to population growth. Anchor tenant positioning in underserved suburban corridors represents the priority defensive lever against emerging hypermarket entrants.
For New Entrants and Emerging Players: Logistics providers with refrigerated fleet assets offer the most accessible partnership pathway for grocery e-commerce penetration. Hawalli Governorate's rising household formation with limited mall density presents the most penetrable white-space geography. Corporate bulk procurement contracts for electronics and office supplies provide a tender-based entry angle with less brand-dependent competition than consumer segments.
For Investors and Strategic Acquirers: Asymmetric upside sits with franchise aggregators possessing multi-brand portfolio density across mid-range and luxury tiers. Long-term viability across a 5-10 year window favors operators with vertical control over real estate and supply chain functions. The signal to watch is Ministry of Commerce and Industry enforcement patterns on cross-border e-commerce seller registration, which will determine capital allocation velocity between digital and physical channel development.
| Strategic Initiative | Industry Significance |
|---|---|
| Fresh Food Backward Integration | Direct procurement from Saudi and UAE agricultural producers bypasses wholesale markups and reduces perishables spoilage. |
| Experiential Format Differentiation | Majid Al Futtaim's cinema-dining-retail mixed-use developments resist pure-play e-commerce substitution through extended dwell times. |
| Digital Payment Infrastructure Expansion | Central Bank of Kuwait fintech standards unlock subscription-based replenishment models for young professional households. |
| Suburban Mall Development | Early anchor tenant positioning in Hawalli Governorate corridors captures household formation before rent escalation clauses activate. |
| Regulatory Compliance Certification | In-house Arabic labeling capabilities for Ministry of Commerce and Industry mandates accelerate consolidation toward compliant distributors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with retail operations directors, category buyers at hypermarket chains, franchise portfolio managers, logistics providers, and Central Bank of Kuwait regulatory affairs specialists with secondary validation. Secondary sources included customs and trade flow databases, Ministry of Commerce and Industry regulatory filings, Central Bank payment system disclosures, and mall operator occupancy reports. Bottom-up channel volume estimates and top-down macroeconomic triangulation converged on segment-level outputs.
Segment-weighting approaches distributed analytical effort across product type, price tier, distribution channel, and customer type dimensions, with additional granularity applied to regional corridor differentiation within Kuwait's governorates. CAGRs were derived from historical trajectory analysis adjusted for structural shift assumptions including digital payment penetration curves and logistics infrastructure buildout timelines. Forecast inputs incorporated household formation projections, expatriate workforce visa quota patterns, and cross-border e-commerce regulatory enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to currency fluctuation, shipping lane congestion, and labor market tightness in logistics functions. Periodic stress-testing of base assumptions is recommended given import dependency exposure and evolving Ministry of Commerce and Industry consumer protection frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Asia-Pacific Road Safety Market
Others
Asia-Pacific Medical Simulation Market
Others
US Mobile MRI Services Market
Others
India 3D Printing Construction Market
Others
Video Conferencing Hardware Market
Others
Global Retail Media Networks Market
Others
CAR T Cell Therapy Market
Others
Billet Market
Others
Security Bottles Market
Others
Augmented Reality (AR) in Warehousing and Logistics Market
Others
China Smart Home Market
Others
Europe Indoor Air Purification Market
Others
Inorganic Tin Chemicals Market
Others
Fire Sprinkler Market
Others
Europe Travel Retail Market
Others
Vo5g Market