
 Middle East and Africa Home Care Packaging Market | 2026-2036
Middle East and Africa Home Care Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Home Care Packaging Market Foresight
Refill subscription services for surface cleaners and laundry detergents is decoupling packaging from single-use retail formats across the Middle East and Africa. Amcor PLC leverages its regional film extrusion footprint to supply downgauged pouch structures for concentrated refills. Mondi Group anchors East African supply through Kraft paper-based flexible packaging tailored for detergent powders. Huhtamaki competes in North Africa with molded fiber trays and paper-based barrier solutions for dishwasher tablets.
Home care packaging encompasses primary and secondary containers engineered to protect, dispense, and preserve household cleaning, laundry, and air care formulations; specifications include multilayer coextruded films with oxygen transmission rates below 0.5 cc/m²/day and trigger sprayers delivering 0.9-1.1 ml per actuation. Plastic bottles retain volume leadership across household end users due to established blow-molding infrastructure and cost efficiency at scale. Pouches register the fastest expansion among packaging types as brand owners downgauge material usage and optimize cube utilization in logistics. Pumps command premium positioning within hotels and healthcare facilities where controlled dosing and aesthetic differentiation support higher unit economics.
SASO in Saudi Arabia mandates recyclability labeling and restricts heavy metal content in packaging substrates, redirecting converter investment toward mono-material polyolefin structures. South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility regulations that obligate home care brands to finance collection and recycling of post-consumer plastic packaging. Egypt's Egyptian Organization for Standardization and Quality aligns with regional harmonization efforts for food-contact-grade materials used in surface cleaner applications. Stakeholders must track evolving EPR fee structures and recyclability certification requirements as these frameworks mature and expand coverage across additional product categories.
Market Dynamics
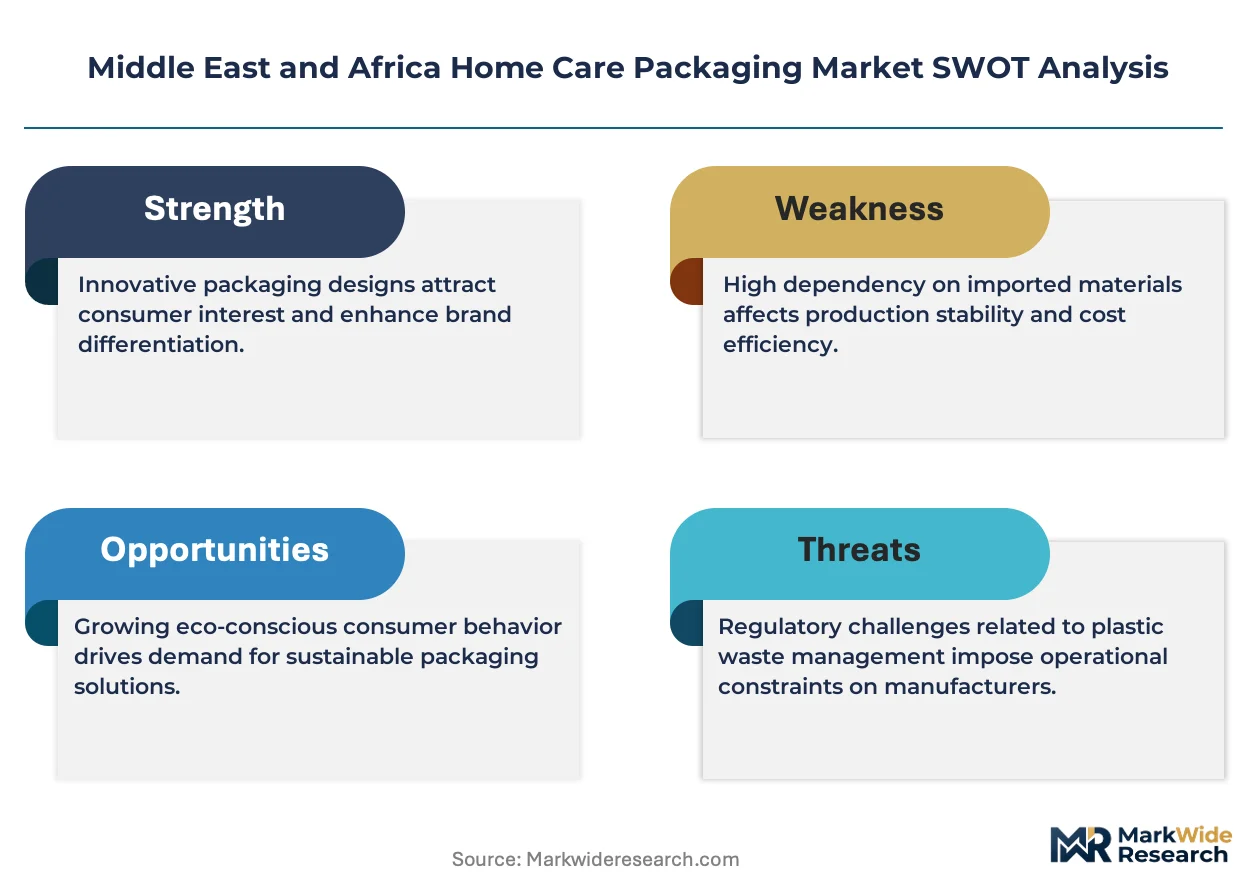
Saudi Arabia's SASO recyclability mandates and South Africa's extended producer responsibility fees are forcing converters to abandon multilayer laminates in favor of mono-material polyolefin structures, restructuring material procurement across the entire regional supply base.
Growth Catalysts
- Hotel dispenser retrofit programs:Hospitality chains across Dubai and Riyadh are installing premium refillable pump systems for surface cleaners and hand soaps, displacing single-use amenity bottles and creating sustained demand for durable dispenser hardware.
- South Africa EPR framework maturation:The Department of Forestry, Fisheries and the Environment's escalating producer fees for non-recyclable packaging are accelerating brand owner investment in collection infrastructure and post-consumer recycling partnerships.
- Concentrated chemistry advances:Downgauged pouch structures for ultra-concentrated laundry and dish formulations are reducing per-use packaging mass by over sixty percent, enabling logistics cost compression for distributors serving Nigeria's urban corridor.
Market Restraints
- Polyolefin resin import dependency:Regional converters rely on polymer feedstock shipments through Gulf ports, exposing margin structures to Red Sea shipping disruptions and currency volatility in Egyptian pound and Nigerian naira denominated contracts.
- Multilayer film recycling incompatibility:Existing mechanical recycling infrastructure cannot process metallized or adhesive-laminated flexible packaging, stranding legacy detergent pouch formats outside circular economy pathways and increasing EPR compliance costs.
- Trigger sprayer component concentration:Precision mold tooling for consistent 0.9-1.1 ml actuation volumes is concentrated among a limited supplier base in East Asia, creating lead time vulnerability for North African brand owners.
Strategic Opportunities
- Kenya refill station network expansion:Informal retail channels in Nairobi and Mombasa present first-mover potential for bulk detergent dispensing systems that eliminate single-use sachet dependency in low-income household segments.
- UAE hospitality sustainability certification:Dubai's green building standards and hotel star rating criteria now reward packaging waste reduction, creating regulatory tailwind for dispenser system suppliers targeting premium property renovations.
- Paper barrier hybrid convergence:Integration of thin-film oxygen barriers with molded fiber substrates for dishwasher tablet formats opens technical white space between Mondi's kraft paper dominance and Huhtamaki's fiber tray capabilities.
Industry Challenges
- Mono-material conversion tooling costs:Shifting extrusion lines from multilayer coextrusion to certified recyclable single-substrate films requires capital outlay that mid-scale Egyptian and Nigerian converters cannot access through local debt markets.
- SASO heavy metal testing bottlenecks:Certification backlog at Saudi accredited laboratories extends product launch timelines by four to six months for surface cleaner packaging requiring food-contact-grade material validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Home Care Packaging Market |
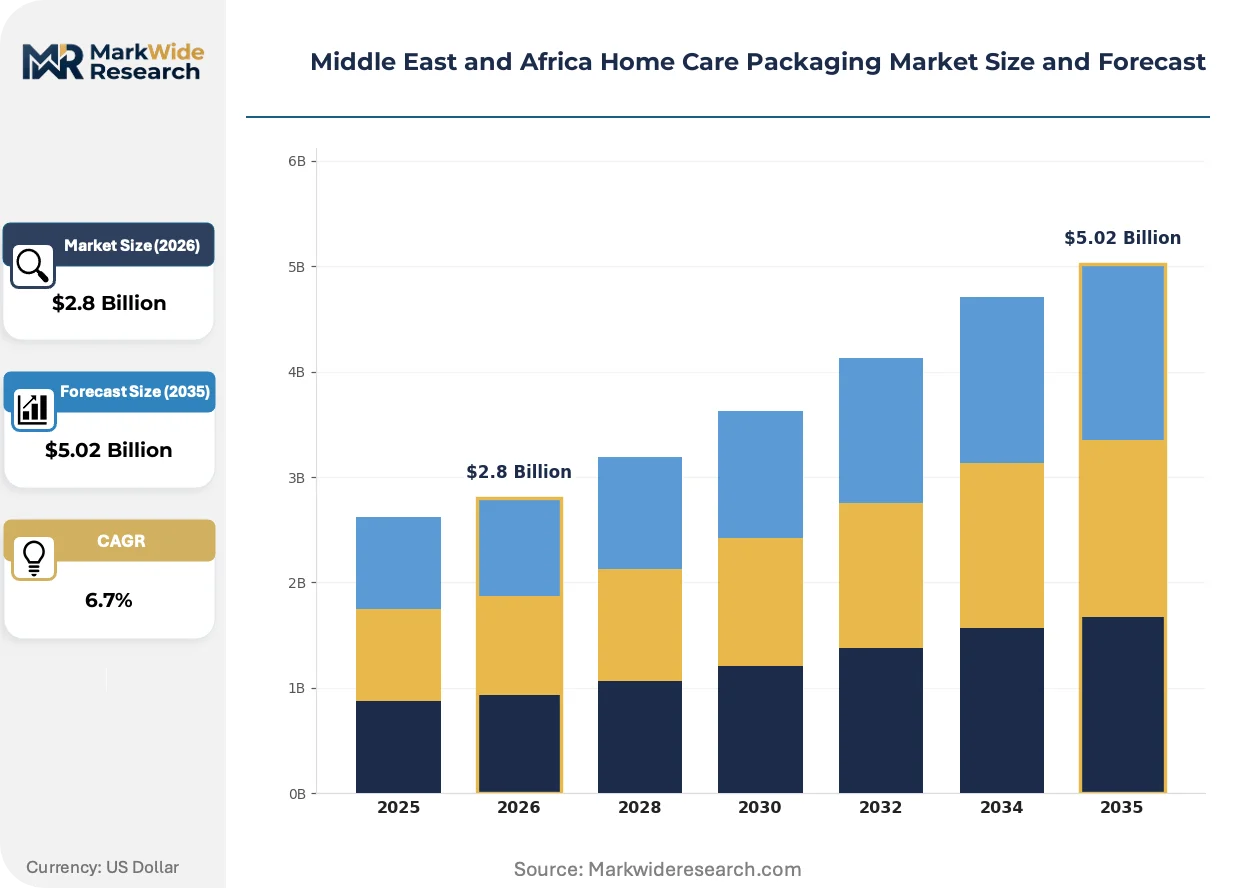
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Bottles, Pouches, Jars, Cartons Closure Type: Screw Caps, Flip Tops, Pumps, Sprayers Material: Plastic, Glass, Metal, Paper End User: Households, Hotels, Healthcare Facilities, Educational Institutions |
| Companies Covered | Amcor PLC, Mondi Group, Huhtamaki, AptarGroup Inc, DS Smith PLC, Silgan Holdings Inc, Napco National, ENPI Group, ProAmpac, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Home Care Packaging Market Shifts & Advancements
Active reshaping of the Middle East and Africa home care packaging landscape centers on three vectors: automation of quality assurance in converter operations, regulatory harmonization across Gulf and sub-Saharan frameworks, and procurement consolidation among hospitality and healthcare institutional buyers.
Machine vision inspection systems are automating defect detection in high-speed pouch sealing lines, replacing manual sampling protocols that previously allowed oxygen transmission rate failures to reach brand owners. Saudi converter operations serving Unilever and Procter & Gamble regional distribution hubs are deploying these systems at throughput rates exceeding four hundred pouches per minute. This automation is compressing quality-related rejection rates and enabling just-in-time supply contracts that were previously unviable due to batch variability risk.
SASO's alignment with GCC Standardization Organization frameworks is creating regulatory convergence across Saudi Arabia, UAE, and Kuwait, reducing the compliance burden for pan-regional brand owners who previously managed country-specific labeling and material certification requirements. The industrial consequence is accelerated product registration timelines and reduced reformulation costs for surface cleaners distributed across multiple Gulf markets. Detergent powder packaging in flexible formats shows the strongest response, with converters consolidating previously separate Saudi and Emirati production runs.
Institutional procurement consolidation among hospital groups and hotel chains is displacing fragmented spot purchasing of cleaning consumables with multi-year framework agreements that specify packaging performance metrics including refill compatibility and end-of-life recyclability. Healthcare procurement departments in South Africa's Western Cape and Gauteng provinces now embed packaging sustainability scoring in supplier selection criteria. This pattern is most visible in Cape Town's private hospital cluster, where group purchasing organizations have reduced active packaging suppliers from twelve to four over thirty-six months.
Middle East and Africa Home Care Packaging Market Segmentation
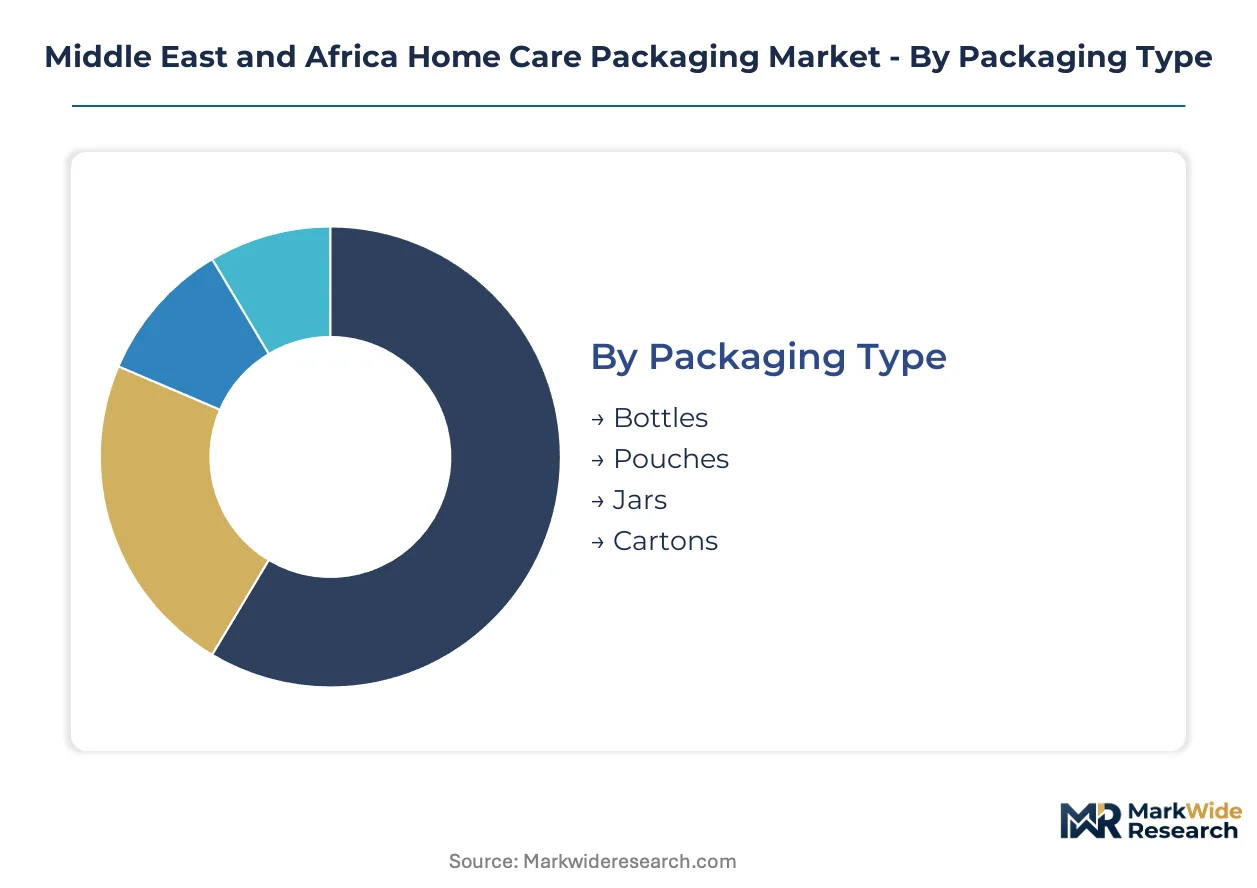
Home care packaging in the Middle East and Africa fragments across four critical dimensions that determine converter investment priorities and brand owner procurement strategies. Understanding these splits reveals where volume concentration clashes with sustainability mandates and regulatory compliance costs.
Packaging Type:
Volume leadership sits with established blow-molded formats, while downgauged flexible structures capture the steepest expansion trajectory as logistics efficiency and EPR fees reshape procurement calculus.
- Bottles:HDPE and PET blow-molded containers dominate household laundry and surface cleaner applications due to established regional extrusion infrastructure in Egypt and Saudi Arabia. Saudi Arabia's SASO recyclability mandates are accelerating mono-material HDPE conversion for Unilever and Procter & Gamble regional distribution.
- Pouches:Multilayer coextruded films and spouted stand-up formats are gaining share fastest in Nigeria's urban corridor as concentrated chemistry reduces per-use packaging mass by over sixty percent. Downgauged structures from Amcor's regional film extrusion footprint enable logistics cost compression for Lagos and Kano distributors.
- Jars:Wide-mouth PP containers serve abrasive scrub powders and solid air care blocks across South African retail channels.
- Cartons:Folding carton formats concentrate in premium dishwasher tablet and laundry pod segments where Mondi Group's kraft paper-based flexible packaging anchors East African supply.
Today's leader: Bottles. Tomorrow's challenger: Pouches.
Closure Type:
Dispensing precision and controlled dosing separate premium hospitality applications from mass-market household formats, with regulatory pressure on recyclability driving mono-material conversion across all categories.
- Screw Caps:Standard HDPE and PP threaded closures remain the default for bulk detergent bottles across Egyptian and Nigerian converter operations, though SASO heavy metal testing bottlenecks extend certification timelines.
- Flip Tops:Hinged PP closures for surface cleaner bottles are consolidating procurement as South Africa's EPR framework maturation forces redesign for mechanical recycling compatibility.
- Pumps:Precision mold tooling for consistent 0.9-1.1 ml actuation volumes commands premium positioning within Dubai and Riyadh hotel dispenser retrofit programs. Controlled dosing and aesthetic differentiation support higher unit economics in healthcare procurement consolidation across Western Cape and Gauteng provinces.
- Sprayers:Trigger mechanisms delivering 0.9-1.1 ml per actuation face lead time vulnerability due to concentrated East Asian supplier bases, exposing North African brand owners to procurement risk.
Pumps extract premium margins in hospitality; sprayers confront supply fragility.
Material:
Substrate selection now pivots on recyclability certification rather than unit cost alone, with mono-material polyolefin structures displacing multilayer laminates under Saudi and South African regulatory pressure.
- Plastic:PET, HDPE, and PP retain volume leadership across household end users due to cost efficiency at scale and established blow-molding infrastructure. SASO mandates and South Africa's EPR fees are forcing abandonment of multilayer laminates in favor of certified recyclable single-substrate films.
- Glass:Premium positioning in boutique air care and specialty surface cleaner segments concentrates in UAE hospitality sustainability certification pathways.
- Metal:Aerosol cans and tinplate containers serve insecticide and air freshener applications with limited regional production capacity.
- Paper:Huhtamaki's molded fiber trays and paper-based barrier solutions for dishwasher tablets compete in North Africa, while Mondi Group's kraft paper flexible formats target detergent powder segments.
Plastic dominates tonnage; paper barriers open technical white space.
End User:
Procurement consolidation among institutional buyers is displacing fragmented spot purchasing with multi-year framework agreements that embed packaging sustainability scoring.
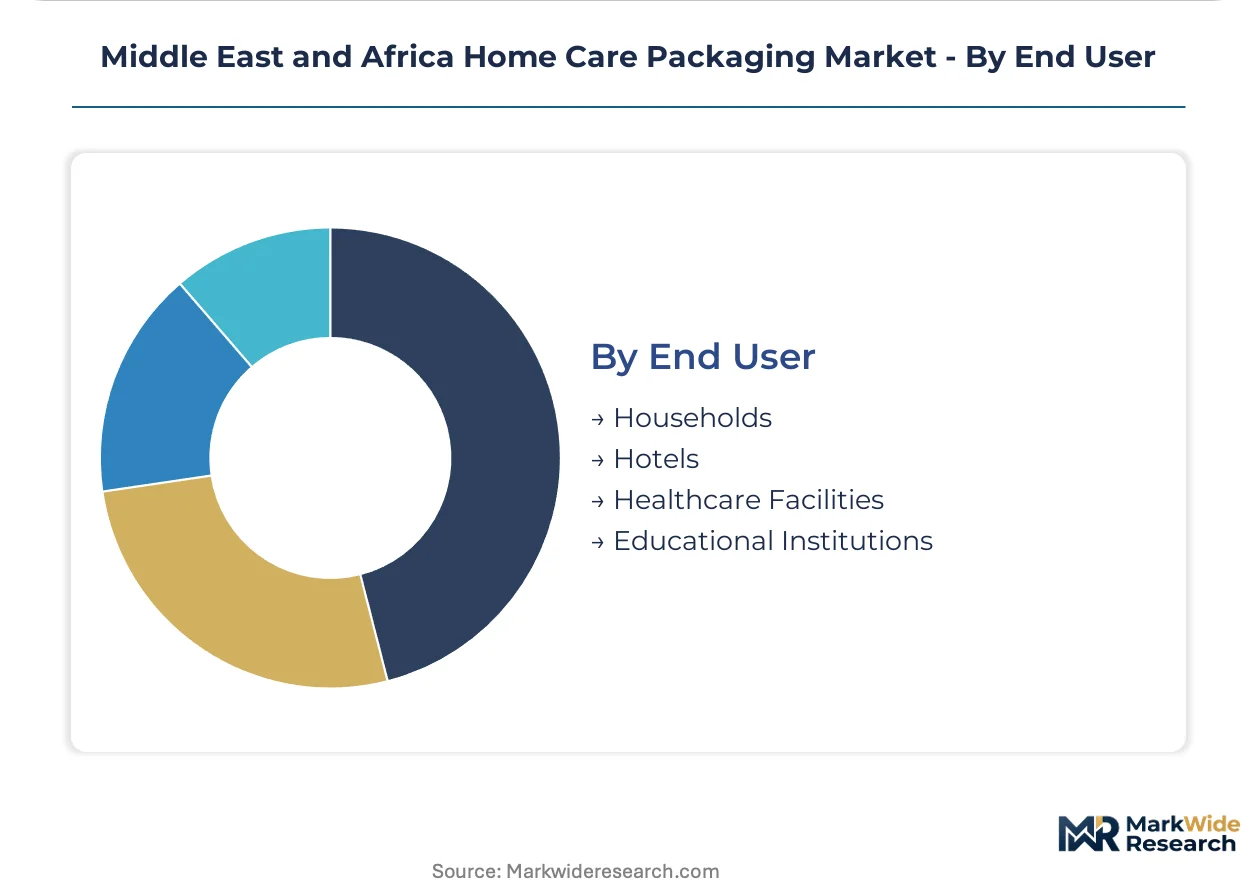
- Households:Sachet-based detergents expand in Lagos and Kano as Nigeria's urban household sector concentrates demand, though Kenya refill station networks present first-mover potential to eliminate single-use dependency.
- Hotels:Hospitality chains across Dubai and Riyadh are installing premium refillable pump systems, displacing single-use amenity bottles and creating sustained demand for durable dispenser hardware under green building standards.
- Healthcare Facilities:South Africa's Western Cape and Gauteng provinces embed packaging sustainability scoring in supplier selection criteria, reducing active packaging suppliers from twelve to four over thirty-six months in Cape Town's private hospital cluster.
- Educational Institutions:Bulk procurement frameworks for schools and universities concentrate in Egyptian and Moroccan public sector tendering with limited sustainability requirements.
Households anchor volume; hotels and healthcare drive specification upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's SASO mandates are accelerating mono-material conversion faster than South Africa's EPR framework, yet both regulations are restructuring procurement across the entire Middle East and Africa supply base.
Saudi Arabia
Hotel dispenser retrofit programs in Riyadh and Jeddah are displacing single-use amenity bottles with premium refillable pump systems. SASO recyclability mandates and heavy metal restrictions are redirecting converter investment toward certified mono-material polyolefin structures. The Eastern Province industrial corridor hosts blow-molding operations supplying Unilever and Procter & Gamble regional distribution hubs with automated quality assurance systems.
South Africa
Healthcare procurement consolidation across Western Cape and Gauteng provinces is embedding packaging sustainability scoring in supplier selection criteria. The Department of Forestry, Fisheries and the Environment's escalating EPR fees for non-recyclable packaging are accelerating brand owner investment in collection infrastructure. Cape Town's private hospital cluster has reduced active packaging suppliers from twelve to four over thirty-six months through group purchasing organization frameworks.
United Arab Emirates
Dubai's green building standards and hotel star rating criteria now reward packaging waste reduction, creating regulatory tailwind for dispenser system suppliers. Hospitality chains across Dubai and Abu Dhabi are installing durable refillable hardware for surface cleaners and hand soaps. The Jebel Ali industrial zone concentrates flexible packaging conversion serving both local hospitality demand and re-export markets across the Gulf.
Nigeria
Sachet-based detergents are expanding rapidly in Lagos and Kano as Nigeria's urban household sector concentrates demand. Downgauged pouch structures for ultra-concentrated formulations are reducing per-use packaging mass by over sixty percent, enabling logistics cost compression for distributors. The Lagos-Ibadan corridor serves as the primary distribution node for converter supply reaching West African retail channels.
Egypt
Established blow-molding infrastructure in Cairo and Alexandria continues to dominate household laundry and surface cleaner applications despite currency volatility in Egyptian pound denominated polymer contracts. The Egyptian Organization for Standardization and Quality is aligning with regional harmonization efforts for food-contact-grade materials used in surface cleaner applications. Converter operations in the Suez Canal Economic Zone face extended lead times due to Red Sea shipping disruptions affecting polyolefin resin imports.
Middle East and Africa Home Care Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with institutional procurement consolidation favoring suppliers capable of multi-year framework agreements. The market structures around three tiers: multinational packaging conglomerates with regional film extrusion footprints, mid-scale converters serving country-specific demand, and hospitality-focused dispenser hardware specialists. Competitive moves center on mono-material conversion tooling investments and post-consumer recycling partnerships to manage EPR compliance costs.
Among multinational converters with regional manufacturing presence, Amcor PLC, Mondi Group, and Huhtamaki occupy distinct positioning archetypes. Amcor leverages its film extrusion footprint to supply downgauged pouch structures. Mondi anchors East African supply through kraft paper-based flexible formats. Huhtamaki competes with molded fiber trays and paper-based barrier solutions. These three represent the primary competitive anchors shaping material substitution patterns across the Middle East and Africa.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi Group |
| Huhtamaki |
| AptarGroup Inc |
| DS Smith PLC |
| Silgan Holdings Inc |
| Napco National |
| ENPI Group |
| ProAmpac |
| Others |
Supply & Pricing Matrix
Mono-material polyolefin conversion is restructuring both cost economics and supply concentration across Middle East and Africa home care packaging. Egyptian and Nigerian converters face capital barriers to extrusion line retooling while Saudi SASO certification backlogs extend product launch timelines, compressing margin recovery windows for mid-scale operators.
Pricing Analysis
Capacity additions in Saudi Arabia's Eastern Province industrial corridor are reshaping price floors for HDPE blow-molded containers as automated quality assurance systems enable just-in-time supply contracts. Three-tier pricing structure across premium dispenser hardware, standard mono-material bottles, and economy multilayer pouches reflects SASO compliance certification tiers and volume scale. Pricing pressure stems from Egyptian pound and Nigerian naira volatility in polymer feedstock contracts. Household sachet buyers in Lagos and Kano exhibit highest price sensitivity; Dubai hospitality procurement shows lowest sensitivity due to green building certification requirements.
Supply Chain Analysis
Polyolefin resin supply rests on Gulf port shipments through Jebel Ali and Suez Canal Economic Zone entry points, with Egyptian converters drawing from Saudi and UAE petrochemical output. Downgauged pouch films, precision pump mold tooling, and kraft paper barrier substrates constitute critical input dependencies. Single-source vulnerability concentrates in East Asian trigger sprayer component suppliers, exposing North African brand owners to lead time fragility. Distribution runs through Lagos-Ibadan and Nairobi-Mombasa corridors serving informal retail channels, with Jebel Ali anchoring Gulf re-export networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement consolidation among Dubai and Riyadh hospitality chains elevates dispenser hardware specifications above commodity bottle economics.
For Market Incumbents: Acquire automated quality assurance systems and mono-material extrusion tooling to defend against Egyptian and Nigerian mid-scale converters locked out of local debt markets for SASO-compliant retooling. Consolidate procurement relationships with Unilever and Procter & Gamble regional distribution hubs before certification backlogs clear. Prioritize backward integration into polymer compounding to hedge currency volatility in Egyptian pound denominated resin contracts. For New Entrants and Emerging Players: E-commerce direct refill subscription models offer white-space penetration in Kenya's informal retail corridor, bypassing established Lagos-Kano sachet distribution networks. Target Nairobi refill station infrastructure as the most penetrable geography given limited incumbent dispenser hardware presence. Pursue hospitality sustainability certification partnerships with Dubai green building standards assessors to unlock premium property renovation procurement channels. For Investors and Strategic Acquirers: Valuations sit cheapest among Egyptian mid-scale converters with stranded multilayer laminate capacity and limited access to mono-material conversion financing. Long-term viability favors suppliers with demonstrated SASO certification throughput and post-consumer recycling partnerships managing South Africa EPR fee structures. Watch Kenya refill station network buildout velocity as inflection indicator for sachet displacement economics.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Conversion | SASO recyclability mandates in Saudi Arabia redirect converter investment toward certified polyolefin structures. |
| Refill Station Network Expansion | Kenya's informal retail channels present first-mover potential to eliminate single-use sachet dependency. |
| Automated Quality Assurance Deployment | Machine vision systems at Saudi converter operations compress rejection rates for Unilever supply contracts. |
| Post-Consumer Recycling Partnership | South Africa EPR framework maturation obligates brand owners to finance collection infrastructure investment. |
| Paper Barrier Hybrid Development | Integration of thin-film oxygen barriers with molded fiber substrates opens technical white space for dishwasher tablets. |
Research Methodology
Coverage spans the Gulf Cooperation Council, West Africa, East Africa, and Southern Africa, with primary inputs from each regional cluster. The analysis combines interviews with packaging procurement managers at Unilever and Procter & Gamble regional hubs, converter operations directors in Egypt and Saudi Arabia, and hospitality sustainability officers in Dubai. Secondary validation draws from SASO technical regulations, South Africa Department of Forestry, Fisheries and the Environment EPR fee schedules, Egyptian Organization for Standardization and Quality harmonization frameworks, and GCC Standardization Organization convergence protocols. Bottom-up volume modeling triangulates against top-down value estimates across packaging type, material substrate, and end-user segmentation.
Rate-of-change decomposition separates volume effects from value mix shifts across the projection horizon. The analytical framework models packaging type substitution dynamics, material compliance cost pass-through, and regional regulatory cluster divergence. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs include concentrated chemistry adoption curves for ultra-concentrated laundry formulations and hospitality dispenser retrofit penetration rates in Dubai and Riyadh.
The model assumes a particular technology adoption path for mono-material polyolefin conversion; alternative pathways for multilayer laminate recycling breakthrough would alter the outlook. Forecasts reflect assumptions regarding SASO certification backlog resolution, Red Sea shipping disruption persistence, and Nigerian naira stabilization. A small set of named triggers—Kenya refill station network velocity, South Africa EPR fee escalation trajectories, and Egyptian converter debt market access—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Ambient Assisted Living and Smart Home Market
Others
Binoculars and Mounting Solutions Market
Others
PC As a Service Market
Others
France Automotive LED Lighting Market
Others
Global Healthcare/Medical Simulation Market
Others
South America Orange Market
Others
Human Enhancement Technology Market
Others
Hypersensitivity Market
Others
Communication Base Station Body Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Molybdenum-99 Market
Others
High-Performance Films Market
Others
Global Drug Discovery Informatics Market
Others
Italy 3D Printing Construction Market
Others
Enterprise Video Market
Others
Kuwait Retail Market