
 Aircraft Exterior Lighting Market | 2026-2036
Aircraft Exterior Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Exterior Lighting Market Analysis
Modular LED retrofit kits bundled with line-replaceable units is realigning procurement patterns among airline operators seeking faster turnaround. Honeywell International Inc. leverages its integrated avionics platform to bundle lighting controls with flight management systems. Collins Aerospace anchors its position through captive supply agreements with Boeing and Airbus fuselage programs. Safran competes on thermal management expertise, extending its landing light portfolio into high-intensity discharge alternatives.
Aircraft exterior lighting comprises position lights, anti-collision strobes, landing beams, and taxi illuminators engineered to FAA/EASA photometric standards for candela output, beam spread, and chromaticity; these systems ensure conspicuity during ground maneuvering and flight phases in instrument meteorological conditions. LED technology dominates new installations for its luminance efficacy and mean time between failures, while halogen retains share in general aviation retrofit budgets. Aerospace OEMs concentrate margin pools in factory-fitted anti-collision and landing light assemblies, whereas MRO Providers capture recurring revenue from heavy maintenance replacement cycles.
FAA airworthiness directives and EASA CS-25 certification standards govern strobe intensity, color boundaries, and electromagnetic compatibility, compelling manufacturers to maintain dual compliance documentation. The EU AI Act and REACH substance restrictions are beginning to affect automated inspection systems and phosphor chemistries in LED manufacturing. Stakeholders must monitor how emerging supersonic and advanced air mobility platforms rewrite visibility rules for non-conventional airframe geometries.
Market Dynamics
LED retrofit cycles are compressing replacement timelines for narrow-body fleets while FAA and EASA photometric standards tighten certification burdens on legacy incandescent inventories.
Growth Catalysts
- FAA Airworthiness Directives:Mandates on strobe intensity and chromaticity boundaries force replacement of non-compliant legacy units across US-registered commercial fleets.
- LED Thermal Management:Advances in phosphor chemistry and heat-sink design extend mean time between failures beyond 50,000 hours, reducing heavy maintenance downtime.
- Narrow-Body Fleet Density:High utilization rates on single-aisle routes accelerate wear on position lights and anti-collision systems, driving recurring MRO demand.
Market Restraints
- Dual Certification Costs:Simultaneous FAA and EASA compliance documentation inflates engineering overhead for each new luminaire design.
- Phosphor Supply Concentration:Rare-earth element processing for LED phosphors clusters in China, exposing manufacturers to export quota volatility.
- Halogen Price Anchoring:General aviation operators retain incandescent landing lights due to lower upfront replacement costs, slowing LED penetration in piston and turboprop segments.
Strategic Opportunities
- Advanced Air Mobility:Electric vertical take-off and landing platforms require novel visibility rules for non-conventional airframe geometries without traditional wingtip positions.
- EU AI Act Alignment:Automated optical inspection systems for LED binning and quality control must adapt to algorithmic transparency requirements, creating compliance service demand.
- Modular Line-Replaceable Units:Bundled retrofit kits with plug-and-play connectors enable faster turnaround at MRO facilities, shifting procurement toward integrated subsystem contracts.
Industry Challenges
- Photometric Calibration Expertise:Shortage of technicians trained in candela measurement and beam-spread testing under CS-25 standards delays certification timelines.
- Legacy Electromagnetic Compatibility:LED drivers interfere with existing avionics bus architectures, requiring redesign of shielding and filtering for retrofit installations.
- REACH Phosphor Restrictions:ECHA substance restrictions on cadmium and lead in semiconductor packaging force reformulation of warm-white LED chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Exterior Lighting Market |
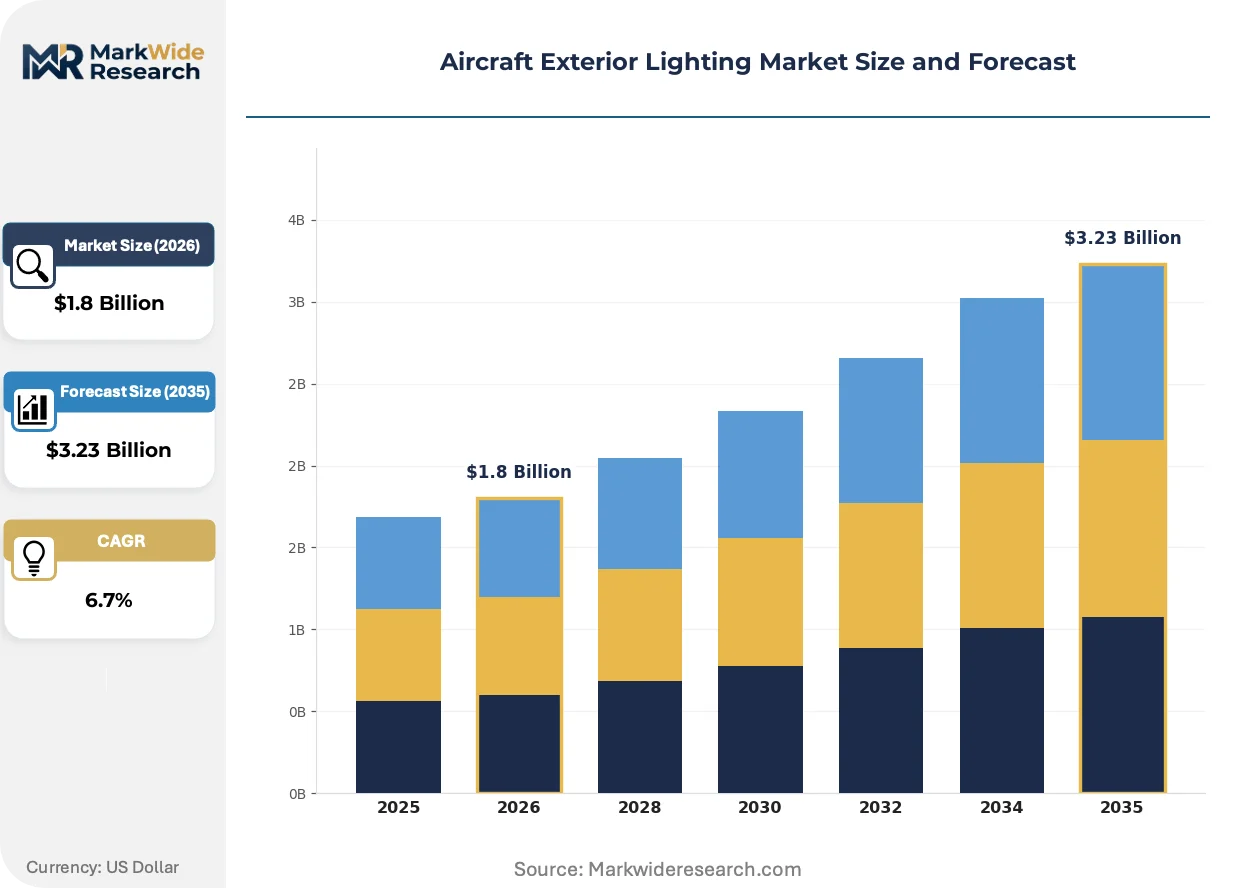
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Position Lights, Anti-Collision Lights, Landing Lights, Taxi Lights Technology: LED, Halogen, Xenon, Incandescent End User: Aerospace OEMs, MRO Providers, Airlines, General Aviation Installation Type: Retrofit, New Installation, Line Maintenance, Heavy Maintenance |
| Companies Covered | Honeywell International Inc., Collins Aerospace (RTX Corporation), Astronics Corporation, Safran, Luminator Technology Group, Whelen Aerospace Technologies, Diehl Stiftung & Co. KG, Cobham Limited, Aveo Engineering Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Exterior Lighting Market Emerging Trajectories
Digital beam-shaping and intelligent thermal feedback are redefining how exterior lighting subsystems integrate with aircraft health monitoring, compressing the boundary between illumination and avionics.
High-intensity LED arrays with programmable intensity curves are overtaking xenon strobe systems in anti-collision applications. Regional carriers operating high-cycle narrow-body routes are adopting these units to eliminate gas-discharge tube replacement intervals. The technology is overtaking incumbent platforms by collapsing lifetime operating costs and enabling synchronized pulse patterns across fleet liveries.
EASA CS-25 certification standards now mandate expanded chromaticity boundaries for position lights to accommodate LED spectral variance. Manufacturers must maintain dual compliance matrices with FAA AC 20-30B guidance, inflating documentation burdens. Anti-collision strobe suppliers serving European-registered aircraft face the steepest adaptation costs as they reconcile divergent photometric testing protocols.
Airline technical procurement teams now specify line-replaceable unit compatibility rather than component-level sourcing, consolidating vendor relationships at the subsystem tier. MRO providers capture this shift by stocking pre-configured retrofit kits with integrated drivers and connectors. The United States exhibits the most pronounced consolidation, where major carriers negotiate multi-year lighting subsystem contracts tied to heavy maintenance intervals.
Aircraft Exterior Lighting Market Segmentation
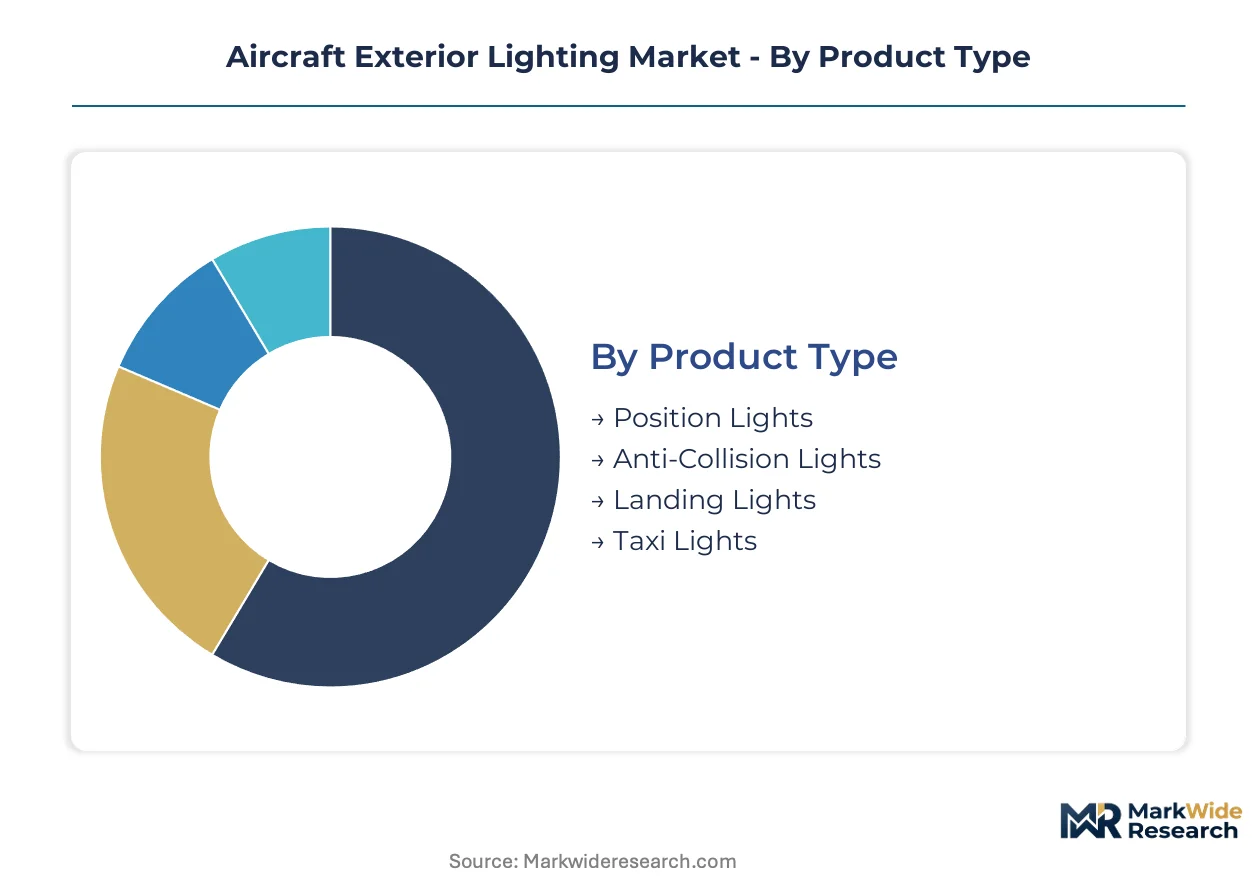
Segmentation in aircraft exterior lighting reveals how procurement authority, regulatory compliance burdens, and fleet utilization patterns fragment demand across fundamentally different buying logics. Understanding these divides explains why LED retrofits accelerate in airline fleets while halogen persists in piston aviation.
Product Type:
Aerospace OEMs and MRO providers prioritize different performance attributes when specifying exterior lighting subsystems, creating divergent specification hierarchies across the four functional categories.
- Position Lights:Red port, green starboard, and white aft navigation beacons mounted on wingtips and tail conform to FAA AC 20-30B and EASA CS-25 chromaticity boundaries. Narrow-body carriers operating high-cycle domestic routes in the United States generate replacement demand as LED spectral variance forces earlier-than-expected unit swaps.
- Anti-Collision Lights:High-intensity strobes and rotating beacons ensure conspicuity in instrument meteorological conditions; synchronized pulse patterns across fleet liveries now drive airline procurement specifications. FAA mandates on strobe intensity are forcing replacement of legacy xenon units across US-registered commercial fleets.
- Landing Lights:High-intensity forward beams for final approach and touchdown phases retain halogen share in general aviation retrofit budgets due to lower upfront costs.
- Taxi Lights:Lower-intensity nose-mounted illuminators for ground maneuvering see fastest LED conversion as thermal management advances extend mean time between failures.
Position lights lead volumes today; taxi lights are gaining share fastest.
Technology:
Technology selection tracks directly to fleet age, maintenance interval economics, and the regulatory pressure differential between commercial and general aviation segments.
- LED:Solid-state emitters with phosphor-converted white output dominate new installations through luminance efficacy exceeding 100 lumens per watt and mean time between failures surpassing 50,000 hours. Narrow-body fleet retrofits in the United States concentrate demand as airlines seek to compress heavy maintenance downtime.
- Halogen:Tungsten-halogen lamps retain installed base in general aviation piston and turboprop segments where operators prioritize capital preservation over lifecycle cost optimization.
- Xenon:Gas-discharge strobes face displacement as high-intensity LED arrays with programmable intensity curves eliminate replacement intervals.
- Incandescent:Legacy filament technology persists only in aged general aviation fleets pending airframe retirement.
LED leads volumes today; xenon is losing share fastest to solid-state alternatives.
End User:
Procurement authority and technical specification control sit with different stakeholders depending on whether lighting subsystems ship factory-fitted or enter service through aftermarket channels.
- Aerospace OEMs:Boeing and Airbus fuselage programs anchor factory-fitted anti-collision and landing light assemblies through captive supply agreements with tier-one lighting suppliers.
- MRO Providers:Heavy maintenance replacement cycles generate recurring revenue as line-replaceable unit compatibility specifications consolidate vendor relationships at the subsystem tier.
- Airlines:Technical procurement teams now negotiate multi-year lighting subsystem contracts tied to heavy maintenance intervals, shifting sourcing from component-level to integrated retrofit kits.
- General Aviation:Owner-operators and fixed-base operators retain price sensitivity that sustains halogen incandescent share despite LED lifecycle advantages.
Aerospace OEMs lead volumes today; MRO providers are gaining share fastest as fleet age extends retrofit cycles.
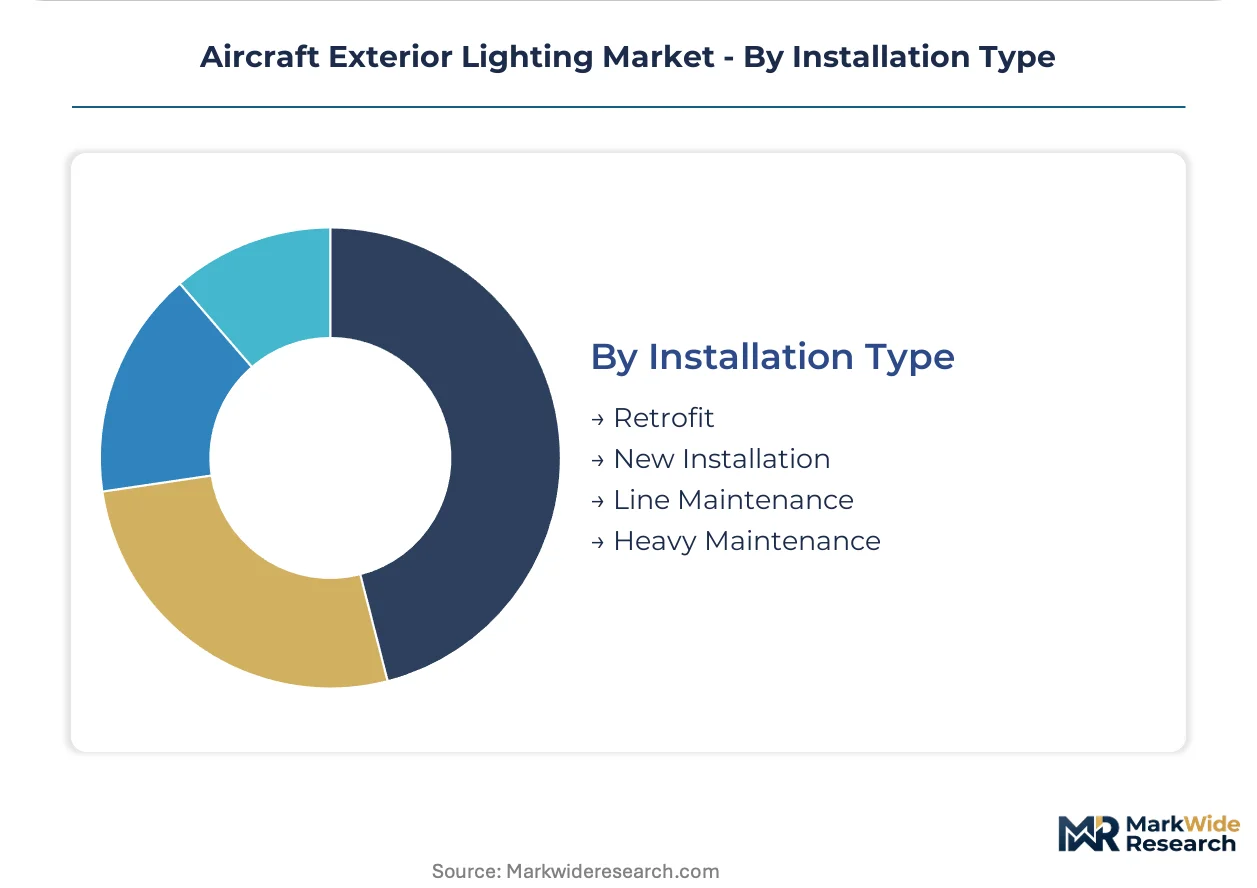
Installation Type:
The installation event type determines whether lighting procurement occurs through capital equipment budgets, operating maintenance reserves, or emergency airworthiness directive compliance spending.
- Retrofit:LED conversion of legacy incandescent and halogen positions accelerates as FAA airworthiness directives on strobe intensity force scheduled replacement of non-compliant units.
- New Installation:Factory-fitted LED subsystems ship with OEM airframes under multi-year supply agreements; EASA CS-25 certification standards mandate expanded chromaticity boundaries that increase documentation burdens.
- Line Maintenance:Rapid turnaround replacement of failed units at gate positions favors modular line-replaceable units with plug-and-play connectors.
- Heavy Maintenance:Scheduled C-check and D-check intervals enable comprehensive lighting subsystem overhaul, consolidating procurement into integrated contracts.
Retrofit leads volumes today; heavy maintenance is gaining share fastest as narrow-body fleet density extends replacement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aircraft exterior lighting manufacturing traces its industrial lineage to post-war aerospace clusters in the United States and Western Europe, where defense contractors first standardized photometric testing protocols for military airframes. These legacy centers continue to anchor production capacity and certification expertise.
United States
FAA airworthiness directives on strobe intensity and chromaticity boundaries drive replacement demand across US-registered commercial fleets. The agency's AC 20-30B guidance on position light photometry compels manufacturers to maintain dual compliance documentation with European standards. Wichita, Kansas and the Dallas-Fort Worth metroplex concentrate MRO provider networks and tier-one supplier facilities serving narrow-body retrofit cycles.
Germany
EASA CS-25 certification standards mandate expanded chromaticity boundaries that increase engineering overhead for LED luminaire designs bound for European-registered aircraft. REACH substance restrictions on cadmium and lead in semiconductor packaging force reformulation of warm-white LED chemistries. Bavaria and Baden-Württemberg host precision optics manufacturers supplying heat-sink assemblies and phosphor-converted emitters to Airbus fuselage programs.
France
Supersonic platform development and advanced air mobility prototypes are rewriting visibility rules for non-conventional airframe geometries without traditional wingtip positions. The country's national aerospace regulator enforces EASA-aligned electromagnetic compatibility standards for LED driver integration. The Toulouse-Blagnac cluster anchors Safran's thermal management expertise and landing light portfolio expansion into high-intensity discharge alternatives.
United Kingdom
Automated optical inspection systems for LED binning must adapt to EU AI Act algorithmic transparency requirements, creating compliance service demand among quality control equipment suppliers. The Civil Aviation Authority maintains harmonized standards with EASA on photometric calibration protocols. South West England and the Midlands concentrate specialty coating facilities for electromagnetic shielding in retrofit installations.
China
Rare-earth element processing for LED phosphors clusters in Jiangxi and Inner Mongolia, exposing manufacturers to export quota volatility and supply concentration risk. The Ministry of Industry and Information Technology enforces GB standards on semiconductor packaging that increasingly diverge from FAA and EASA protocols. The Yangtze River Delta integrates phosphor chemistry research with downstream LED assembly for commercial aviation export markets.
Aircraft Exterior Lighting Market Vendor Landscape
The competitive structure tilts toward diversified aerospace conglomerates with captive avionics platforms and integrated subsystem bundling capabilities. Tier-one suppliers anchor factory-fitted positions through multi-year supply agreements with Boeing and Airbus fuselage programs, while specialist lighting manufacturers compete on thermal management expertise and MRO retrofit turnaround speed. Two dominant competitive moves are reshaping positioning: strategic partnerships bundling lighting controls with flight management systems, and backward integration into phosphor chemistry and heat-sink design to secure LED supply chains.
Within the diversified conglomerate tier, Honeywell International Inc. and Collins Aerospace exemplify platform-integrated positioning through avionics bundling strategies. Safran occupies a specialist position anchored in thermal management capabilities. Among independent lighting specialists, Astronics Corporation and Luminator Technology Group represent the MRO-facing retrofit segment with modular line-replaceable unit portfolios. Diehl Stiftung & Co. KG exemplifies European captive supply structures tied to regional OEM programs.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Collins Aerospace (RTX Corporation) |
| Astronics Corporation |
| Safran |
| Luminator Technology Group |
| Whelen Aerospace Technologies |
| Diehl Stiftung & Co. KG |
| Cobham Limited |
| Aveo Engineering Group |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in German precision optics and French thermal management anchor supply discipline through multi-generational engineering expertise, insulating premium LED luminaire pricing from commodity volatility while compressing margins on halogen retrofit tiers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FAA-EASA dual-certified LED anti-collision systems from single-certification units and legacy halogen replacements. Price differentiation rests on certification grade and thermal management performance tier, with premium tiers commanding sustained premiums for synchronized pulse-pattern capability. Cost compression in economy halogen segments is intensifying because general aviation owner-operators prioritize capital preservation over lifecycle economics. Airlines demonstrate least price sensitivity due to heavy maintenance interval bundling, while piston fleet operators exhibit acute upfront cost consciousness.
Supply Chain Analysis
Direct-to-OEM channels handle factory-fitted demand from Boeing and Airbus fuselage programs, while MRO-facing distributors stock modular retrofit kits for line-replaceable unit compatibility. Geographic supply concentration clusters in the United States, Germany, and China, with rare-earth phosphor processing anchored in Jiangxi and Inner Mongolia. Raw material dependencies draw from gallium nitride substrates, rare-earth phosphor chemistries, and aluminum heat-sink alloys. Single-source vulnerability in Chinese rare-earth export quotas exposes LED manufacturers to supply interruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through LED thermal management premiumization as phosphor chemistry advances compress replacement intervals and elevate subsystem bundling value.
For Market Incumbents: Anchor factory-fitted positions through captive supply agreements with Boeing and Airbus fuselage programs while deepening backward integration into phosphor chemistry to secure LED supply chains against Chinese export quota volatility. Defend against MRO consolidation by accelerating line-replaceable unit certification to match heavy maintenance intervals. For New Entrants and Emerging Players: The mid-tier price-point gap between Honeywell-Collins avionics-bundled premiums and economy halogen retrofits offers white-space entry for thermal-management specialists targeting regional airline retrofit demand. General aviation piston segments remain most penetrable due to incumbent neglect of price-sensitive owner-operators. Pursue FAA STC (Supplemental Type Certificate) pathways for plug-and-play LED landing light kits as the fastest certification-to-revenue channel. For Investors and Strategic Acquirers: Diversified aerospace conglomerates with integrated avionics platforms are the most active acquirer in this space, seeking lighting control bundling capabilities. Targets with proprietary phosphor-converted white LED chemistries and EASA CS-25 certification matrices offer durable competitive moats. Monitor FAA airworthiness directive issuance frequency as the inflection indicator for retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Phosphor Chemistry Backward Integration | Secures rare-earth supply chains against Chinese export quota volatility for LED manufacturers. |
| Line-Replaceable Unit Certification Acceleration | Aligns product lifecycles with airline heavy maintenance intervals to capture MRO demand. |
| Dual FAA-EASA Compliance Investment | Unlocks factory-fitted positions on Boeing and Airbus programs through unified documentation. |
| Advanced Air Mobility Visibility Rule Development | Positions suppliers for eVTOL platform demand as non-conventional airframes rewrite standards. |
| Thermal Management IP Acquisition | Consolidates expertise in heat-sink design extending LED mean time between failures beyond 50,000 hours. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with airline technical procurement directors, MRO facility managers, FAA certification engineers, and tier-one supplier program managers with secondary validation against FAA airworthiness directive databases, EASA CS-25 certification filings, and customs trade records for LED phosphor materials. Bottom-up fleet retrofit demand modeling and top-down OEM production forecasts were triangulated to anchor volume estimates.
Historical reference periods spanning installed base age distributions and replacement cycle economics anchored the projection horizon across the analysis window. Segmentation dimensions modeled include product type, technology platform, end-user procurement authority, and installation event category, with narrow-body fleet utilization intensity and regulatory compliance deadlines as industry-specific forecast inputs. CAGRs were derived from replacement cycle compression rates and LED penetration trajectory analysis.
Caveats apply where FAA airworthiness directive timing, EASA chromaticity boundary revisions, or Chinese rare-earth export policy shifts could materially shift the outlook. Forecasts reflect assumptions on fleet age profiles and retrofit budget allocation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Webinar and Webcast Market
Others
Global Military Lighting Market
Others
Pickup Truck Market
Others
8K Technology Market
Others
US Mobile MRI Services Market
Others
Latin America Contract Packaging Market
Others
Global Pregnancy Tracker Apps Market
Others
UK Real Estate Hospitality Market
Others
Global Car Wax Market
Others
India Battery E-Commerce Market
Others
Sports Events Market
Others
Construction Fabrics Market
Others
Toy Packaging Market
Others
Europe Aircraft Lighting Systems Market
Others
Augmented Reality (AR) in Manufacturing Market
Others
Belt Press Filter Market