
 Hot Air System Market | 2026-2036
Hot Air System Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Air System Market Analysis
The split between premium and commodity tiers is shifting around energy efficiency certification and connected controls. Daikin Industries leverages its inverter heritage to dominate high-specification industrial heat pump installations. Lennox International anchors its position through captive distribution and aftermarket service contracts in North American manufacturing corridors. Gree Electric competes on manufacturing scale, occupying the high-volume, price-sensitive segment for standard hot air blowers.
Hot air systems are forced-air thermal processing equipment that deliver controlled heated air streams, typically operating between 50°C and 600°C depending on application, using centrifugal or axial blowers coupled with electric resistance elements, gas burners, or infrared panels. Their primary industrial purpose is to achieve uniform, rapid heat transfer for drying coatings, curing adhesives, or baking food products without direct flame contact. The convection oven category retains the largest installed base but carries mature margins, while infrared heating technology captures expanding share in electronics curing lines where precise zone control reduces thermal damage. Hot air dryer demand in textile finishing is accelerating fastest, driven by water recovery mandates and accelerated line speeds.
The EPA enforces emissions thresholds for gas-fired industrial combustion equipment under New Source Performance Standards, pushing end users toward electric and infrared alternatives. CE marking under the EU Machinery Directive and evolving Ecodesign requirements for industrial fans constrain market access for non-compliant suppliers. China's GB standards for industrial electric heating equipment, administered by SAMR, set efficiency benchmarks that shape export competitiveness. Stakeholders must monitor how building electrification codes and carbon border adjustments redirect procurement specifications across their installed base.
Market Dynamics
The EU F-Gas Regulation is forcing a wholesale re-architecture of industrial heating infrastructure, redirecting capital from vapor-compression heat pumps toward electric resistance and infrared panel systems across European manufacturing facilities.
Growth Catalysts
- Food Processing Throughput Mandates:Industrial bakeries and snack manufacturers in Germany are expanding convection oven capacity to meet line-speed targets, triggering replacement cycles for legacy hot air blowers with higher-capacity units.
- CE Marking Compliance:The EU Machinery Directive's evolving Ecodesign requirements for industrial fans are filtering non-compliant suppliers from the market, concentrating demand among certified equipment providers.
- Water Recovery Directives:Textile finishing facilities face tightening wastewater regulations, accelerating hot air dryer installations that enable closed-loop water systems while maintaining fabric throughput.
Market Restraints
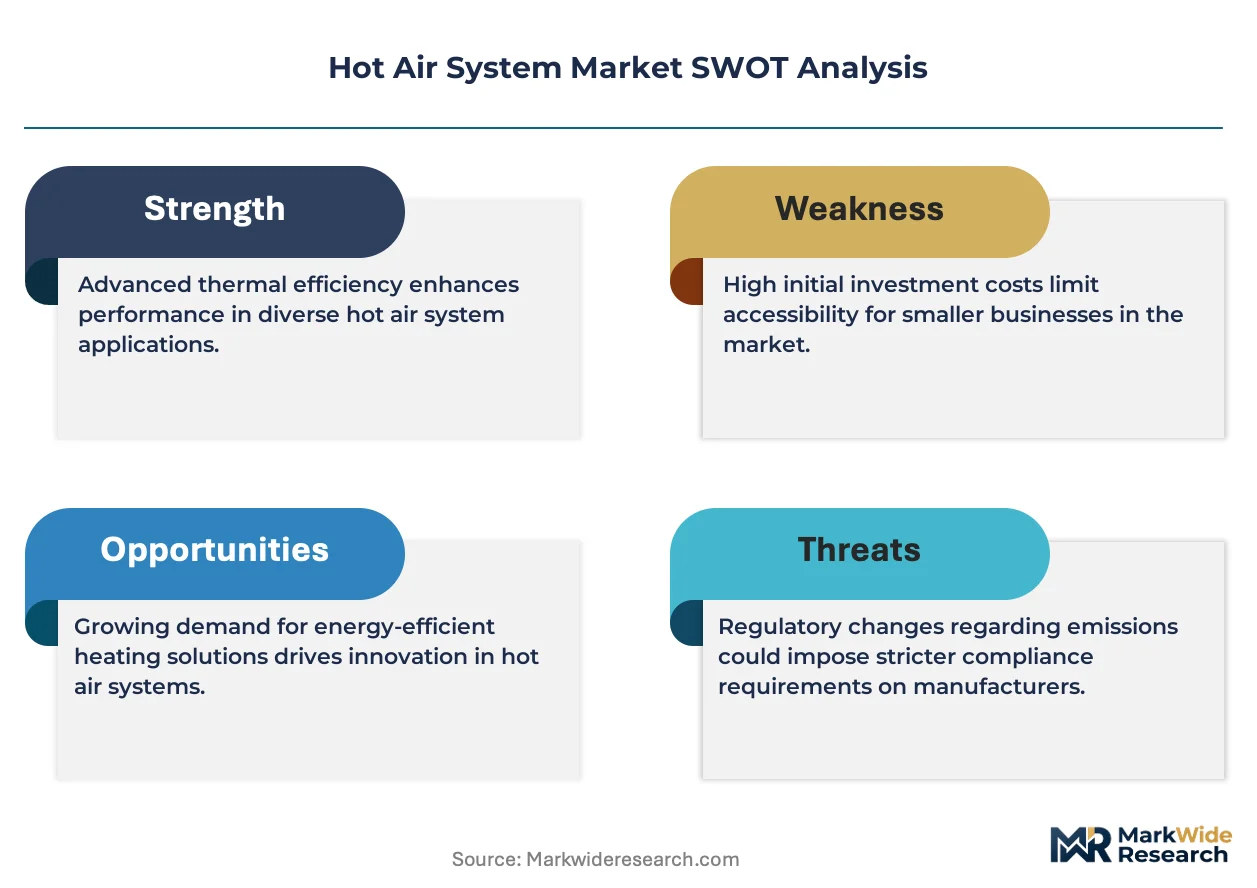
- Copper and Aluminum Price Volatility:Electric resistance heating elements and motor windings depend on base metal inputs subject to commodity exchange fluctuations, compressing margins for standard-equipment manufacturers.
- Gas Infrastructure Lock-In:Mature industrial parks in the US Rust Belt retain depreciated gas-fired combustion systems, creating replacement friction against electric alternatives despite EPA New Source Performance Standards.
- Infrared Substitution in Electronics:Zone-controlled infrared curing lines deliver precise thermal profiles for PCB and semiconductor packaging, displacing convection ovens in high-value coating applications.
Strategic Opportunities
- India PLI Scheme for Textiles:Production-linked incentives for technical textiles and apparel manufacturing are stimulating greenfield facility construction with modern hot air processing infrastructure.
- Connected Controls Convergence:Integration of IoT-enabled temperature zoning with predictive maintenance algorithms opens premium pricing tiers for equipment vendors serving automotive paint shop networks.
- Carbon Border Adjustment Mechanism:EU importers of processed goods face embedded emissions accounting, pushing non-EU suppliers to upgrade to certified electric heating systems to maintain market access.
Industry Challenges
- Heat Transfer Engineering Talent Scarcity:The specialized knowledge required for computational fluid dynamics modeling of air distribution patterns is concentrating among a shrinking pool of senior technicians approaching retirement.
- Legacy System Integration Complexity:Brownfield installations must interface hot air equipment with existing SCADA architectures and building management systems, extending commissioning timelines and inflating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Air System Market |
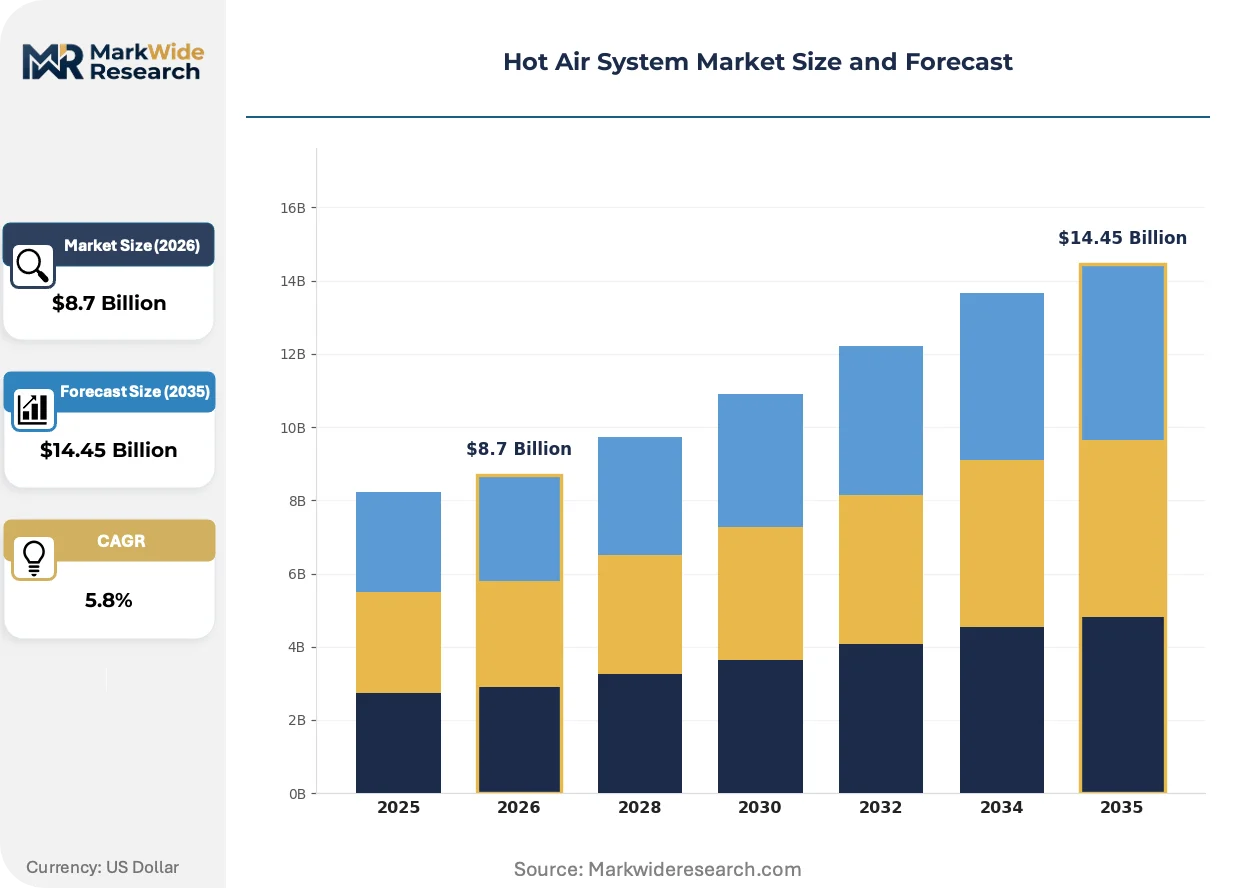
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convection Oven, Hot Air Blower, Hot Air Dryer, Heat Gun End User: Manufacturing, Food Processing, Textile, Electronics Heating Technology: Infrared, Electrical, Induction, Gas Application: Drying, Heating, Curing, Baking |
| Companies Covered | Midea, Lennox International, Daikin Industries, Mitsubishi Electric, Rheem Manufacturing, Carrier Global, Trane Technologies, LG Electronics, Gree Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Air System Market Emerging Trajectories
Digitalization of thermal process control is compressing the gap between specification-grade and commodity equipment, while regulatory pressure on refrigerants accelerates electric heating architectures.
Variable-frequency drive technology paired with centrifugal blowers is automating airflow modulation in response to real-time temperature feedback. Automotive paint shops in Stuttgart and Wolfsburg are deploying these systems to eliminate thermal overshoot during curing cycles. The technology is automating quality control previously requiring manual intervention, reducing rework rates and energy consumption simultaneously.
China's GB standards for industrial electric heating equipment, administered by SAMR, are tightening efficiency benchmarks for equipment sold domestically and exported. Domestic manufacturers must redesign coil geometries and insulation packages to meet tiered performance bands. Export-oriented suppliers in Guangdong and Jiangsu provinces are accelerating certification timelines to maintain competitiveness in Southeast Asian markets.
Service unbundling is fragmenting the traditional equipment-plus-installation bundle. End-users in North American manufacturing corridors are separating capital procurement from aftermarket maintenance, sourcing blowers and heating elements through distributors while contracting specialized firms for thermal system commissioning. This pattern is most pronounced among mid-sized food processors seeking to preserve internal engineering capacity without carrying full service overhead.
Hot Air System Market Segmentation
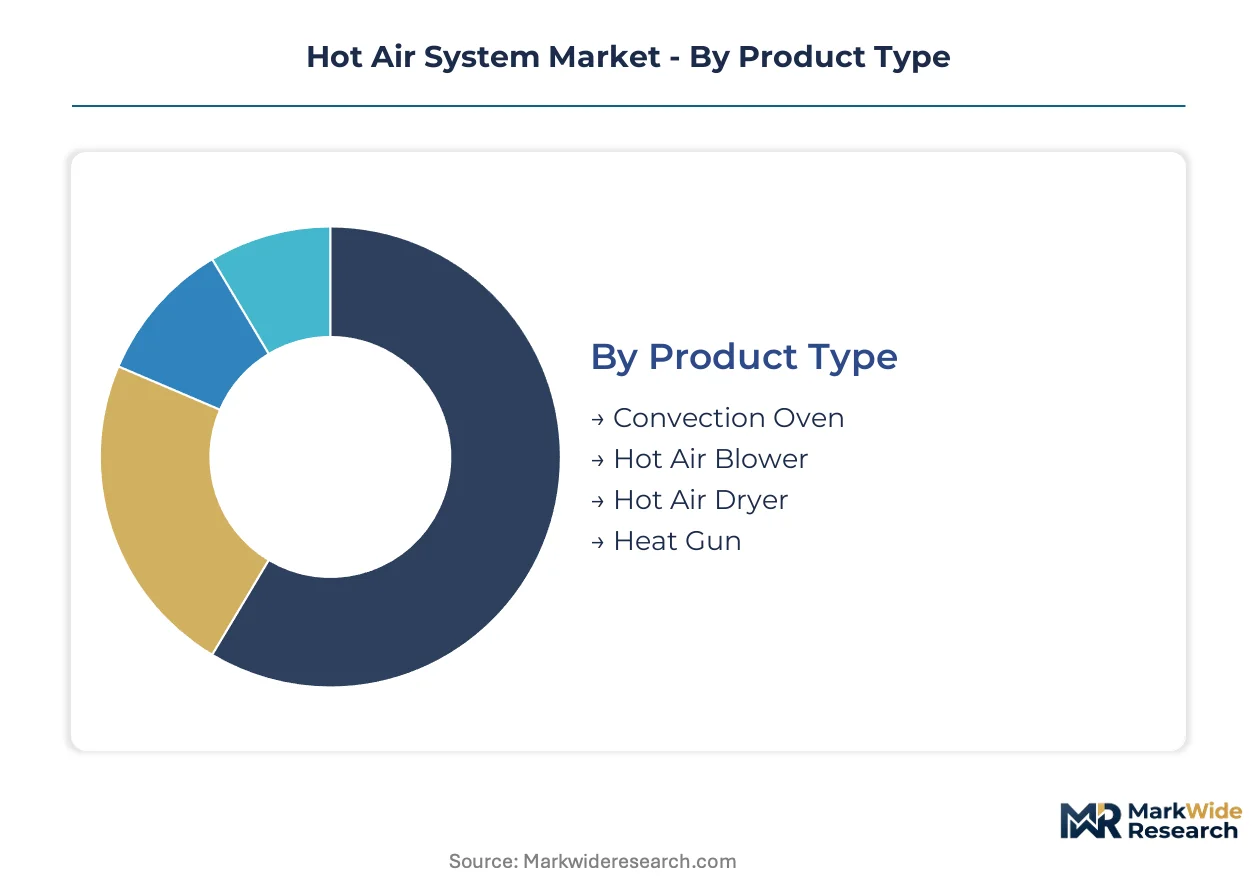
Hot air system procurement decisions pivot on thermal precision requirements, energy infrastructure availability, and integration complexity with existing production lines. Segmentation reveals where electric architectures displace gas combustion and which end-use verticals command premium pricing for connected controls.
Product Type:
Standalone hot air blowers serve discrete workstations while convection ovens and dryers embed into continuous production architectures.
- Convection Oven:Enclosed chambers with forced-air circulation achieve uniform temperature distribution across 50°C to 300°C operating ranges. German industrial bakeries in Munich and Stuttgart drive replacement demand as throughput mandates force capacity upgrades beyond legacy equipment limits.
- Hot Air Blower:Portable or fixed-mount units deliver directed heated air streams for localized drying or preheating tasks. Automotive paint shops in Wolfsburg specify inverter-driven blowers with real-time temperature feedback to eliminate thermal overshoot during curing cycles.
- Hot Air Dryer:Continuous-process equipment removes moisture from textiles, coatings, or food products through controlled airflow. Textile finishing facilities in Tamil Nadu install these systems to meet water recovery mandates while maintaining line speeds.
- Heat Gun:Handheld devices provide concentrated heat for shrink-wrapping, paint stripping, or small-batch soldering operations. Electronics contract manufacturers in Shenzhen use precision heat guns for PCB rework and component removal.
Convection ovens lead volumes today; hot air dryers are gaining share fastest.
End User:
Customer segmentation tracks capital intensity differences between process industries and discrete manufacturing.
- Manufacturing:Automotive, aerospace, and general fabrication facilities deploy hot air systems for surface preparation, coating cure, and parts preheating. US Rust Belt manufacturers face replacement friction against electric alternatives due to depreciated gas infrastructure.
- Food Processing:Bakeries, snack production, and prepared meal facilities require sanitary-design convection equipment with washdown capabilities. German food processors expand hot air dryer installations to meet throughput targets under EU hygiene regulations.
- Textile:Dyeing, finishing, and technical fabric production depends on continuous hot air processing for moisture removal. India's PLI scheme for technical textiles stimulates greenfield facility construction with modern processing infrastructure.
- Electronics:PCB assembly, semiconductor packaging, and display manufacturing demand precise thermal profiles. Zone-controlled infrared curing lines displace convection ovens in high-value coating applications where thermal damage risks are critical.
Food processing commands the largest equipment spend; electronics shows the steepest expansion trajectory.
Heating Technology:
Technology choice reflects regulatory pressure on refrigerants and carbon intensity alongside precision requirements.
- Infrared:Radiant heat panels deliver zone-controlled thermal profiles without convective airflow. Electronics curing lines in Stuttgart and Wolfsburg deploy infrared systems to reduce thermal damage during sensitive component processing.
- Electrical:Resistance heating elements convert grid electricity to thermal energy with zero point-of-use emissions. The EU F-Gas Regulation redirects capital toward electric architectures as vapor-compression heat pumps face phase-down.
- Induction:Electromagnetic field generation heats ferrous workpieces directly without intermediate air heating. Specialized metal treatment applications in automotive component manufacturing use induction for rapid, controllable heating cycles.
- Gas:Natural gas or propane combustion delivers high thermal output at lower unit energy cost. EPA New Source Performance Standards enforce emissions thresholds that push end users toward electric alternatives despite infrastructure lock-in.
Electrical heating leads new installations; infrared captures expanding share in precision applications.
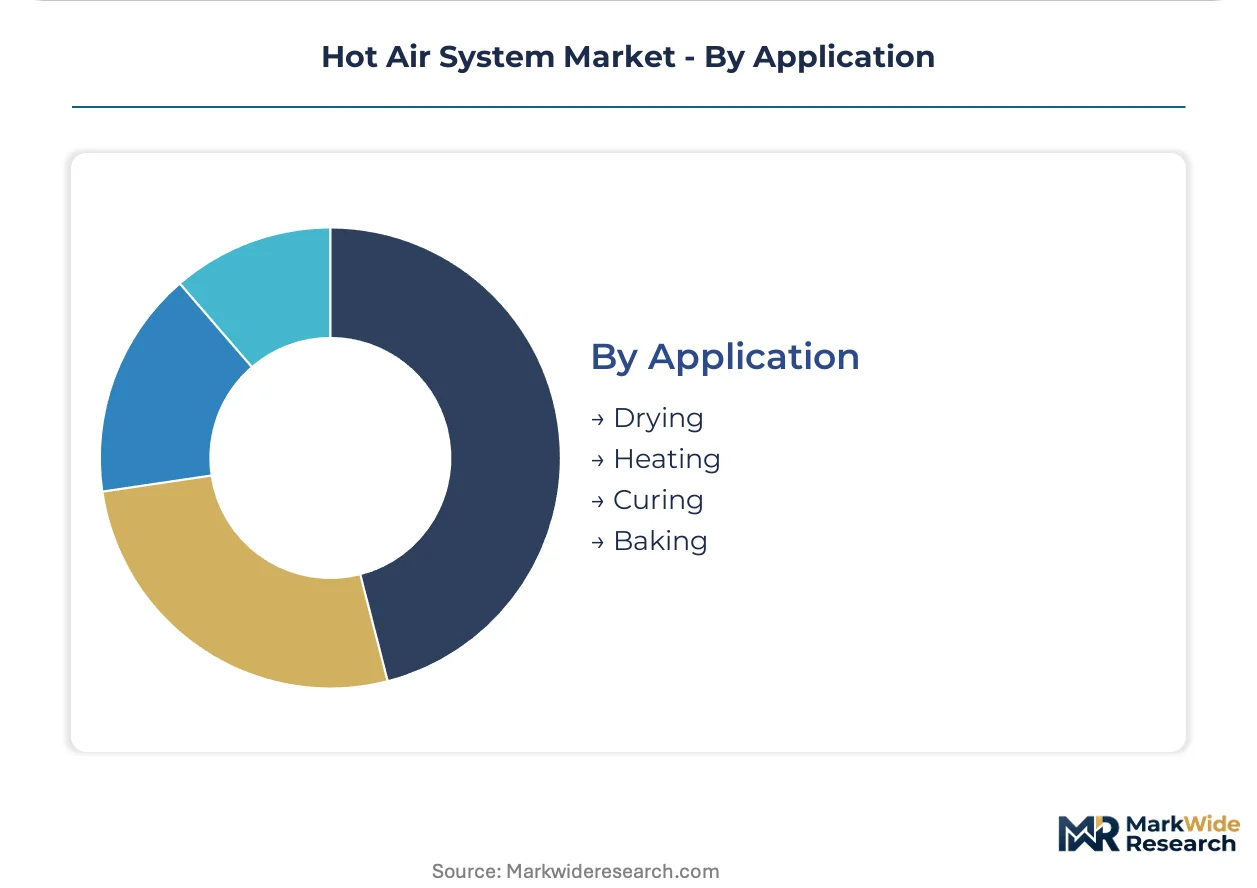
Application:
Application segmentation aligns equipment specifications with thermal transfer mechanisms and process duration.
- Drying:Moisture removal from textiles, coatings, food products, or agricultural materials through heated airflow. Water recovery directives in European textile finishing accelerate hot air dryer installations that enable closed-loop systems.
- Heating:Workpiece or environment temperature elevation for process preparation or worker comfort. Manufacturing facilities in North American corridors separate heating element procurement from system commissioning to preserve internal engineering capacity.
- Curing:Polymerization or hardening of coatings, adhesives, and composite materials through controlled thermal exposure. Automotive paint shops specify connected controls with predictive maintenance algorithms to reduce rework rates.
- Baking:Thermal processing of food products to achieve texture, color, and safety specifications. Industrial bakeries in Germany replace legacy hot air blowers with higher-capacity units to meet line-speed targets.
Drying applications dominate equipment shipments; curing commands the highest per-unit pricing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heat transfer engineering talent concentrates in Germany's industrial belt and China's manufacturing provinces, anchoring regional demand patterns for precision thermal equipment.
Germany
Industrial bakeries in Munich and Stuttgart drive replacement cycles for convection ovens as throughput mandates exceed legacy hot air blower capacity. The EU F-Gas Regulation redirects capital toward electric resistance architectures, phasing down vapor-compression heat pumps. Automotive paint shops in Wolfsburg specify inverter-driven blowers with real-time temperature feedback to eliminate thermal overshoot during curing cycles.
United States
Rust Belt manufacturers face replacement friction against electric alternatives due to depreciated gas-fired combustion infrastructure. The EPA enforces emissions thresholds under New Source Performance Standards, pushing end users toward electric and infrared heating systems. Food processing facilities in the Midwest expand hot air dryer installations to meet line-speed targets under USDA hygiene regulations.
China
Export-oriented suppliers in Guangdong and Jiangsu provinces accelerate certification timelines to maintain competitiveness in Southeast Asian markets. SAMR-administered GB standards tighten efficiency benchmarks for industrial electric heating equipment sold domestically and exported. Electronics contract manufacturers in Shenzhen deploy precision heat guns for PCB rework and component removal.
India
Production-linked incentives for technical textiles stimulate greenfield facility construction with modern hot air processing infrastructure. The PLI scheme administered by the Ministry of Textiles channels investment toward Tamil Nadu and Gujarat. Textile finishing facilities in Coimbatore install continuous hot air dryers to meet water recovery mandates while maintaining fabric throughput.
Japan
Automotive and electronics manufacturers demand precise thermal profiles for semiconductor packaging and display manufacturing. METI efficiency standards shape procurement specifications for industrial heating equipment. Industrial clusters in Nagoya and Osaka specify zone-controlled infrared curing lines to reduce thermal damage during sensitive component processing.
Hot Air System Market Vendor Landscape
Top-tier vendors anchor premium-tier positioning through energy efficiency certification and connected controls, while mid-tier fabricators compete on manufacturing scale and aftermarket service reach. The market structure concentrates around three strategic archetypes: inverter-heritage specialists, captive distribution networks, and high-volume commodity producers. Dominant competitive moves include strategic partnerships for IoT-enabled temperature zoning and geographic expansion into India's PLI-stimulated textile corridor.
Among Japanese multinationals, Daikin Industries and Mitsubishi Electric represent the inverter-heritage archetype, leveraging variable-frequency drive expertise to capture specification-grade industrial installations. Lennox International anchors the captive distribution model through aftermarket service contracts in North American manufacturing corridors. Gree Electric occupies the scale-driven position, competing on manufacturing volume for standard hot air blowers in price-sensitive segments.
| Leading Market Players |
|---|
| Midea |
| Lennox International |
| Daikin Industries |
| Mitsubishi Electric |
| Rheem Manufacturing |
| Carrier Global |
| Trane Technologies |
| LG Electronics |
| Gree Electric |
| Others |
Supply Flow & Price Mechanics
Inverter-driven blower technology is displacing conventional fixed-speed architectures across European automotive paint shops, simultaneously compressing unit manufacturing costs and concentrating procurement power among certified suppliers with variable-frequency drive expertise. German industrial bakeries and North American food processors now face divergent cost structures as electric resistance heating elements replace depreciated gas combustion systems under tightening emissions frameworks.
Pricing Analysis
The bundled-vs-unbundled service split now defines pricing architecture across equipment tiers. Three-tier pricing structure across premium, standard, and economy levels separates connected-control installations with predictive maintenance algorithms from basic convection ovens and commodity hot air blowers. Price differentiation hinges on CE marking compliance under evolving Ecodesign requirements and aftermarket service contract duration. Cost compression in the standard-equipment tier is intensifying because copper and aluminum commodity volatility squeezes margin on electric resistance coil and motor winding inputs. Mid-sized food processors in North American manufacturing corridors exhibit highest price sensitivity, separating capital procurement from thermal system commissioning to preserve internal engineering capacity without carrying full service overhead.
Supply Chain Analysis
Reverse-logistics flows for blower motor refurbishment and heating element remanufacturing are emerging as cost-control mechanisms for aftermarket service networks serving installed base equipment in Germany and the United States. Component manufacturing concentrates in China, Germany, and Japan, with export-oriented suppliers in Guangdong and Jiangsu provinces accelerating certification timelines to maintain Southeast Asian market access. Supply chains draw from copper wire, aluminum extrusions, and silicon steel laminations as primary material inputs. Single-source vulnerability around specialized induction coil geometries for precision electronics curing applications presents structural risk. Distribution runs through captive service networks for premium-tier equipment and industrial distributors for standard blowers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation operates as a regulatory compounder, forcing wholesale re-architecture of industrial heating infrastructure and redirecting capital toward electric resistance and infrared panel systems across European manufacturing facilities.
For Market Incumbents: Extend connected-controls capabilities into predictive maintenance algorithms for automotive paint shop networks, defending installed base relationships against infrared substitution in electronics curing lines. Deepen backward integration into variable-frequency drive manufacturing to secure margin position as copper and aluminum commodity volatility compresses standard-equipment profitability. Prioritize certification investment for SAMR-administered GB standards to maintain export competitiveness into Southeast Asian markets. For New Entrants and Emerging Players: Capture white-space opportunity in India's PLI-stimulated technical textiles corridor, where greenfield facility construction in Tamil Nadu and Gujarat demands modern hot air dryer infrastructure with water recovery integration. Target mid-sized North American food processors seeking unbundled procurement of heating elements separate from system commissioning. Lead with IoT-enabled temperature zoning as the go-to-market angle, automating quality control previously requiring manual intervention in baking and curing applications. For Investors and Strategic Acquirers: Valuations sit cheapest among captive distribution networks with aftermarket service contract density in North American manufacturing corridors, where depreciation of gas-fired infrastructure creates replacement friction and extends equipment life cycles. Long-term viability over the five-to-ten year window favors vendors with inverter heritage and energy efficiency certification authority. Acquisition target archetype: mid-tier fabricators with manufacturing scale in standard hot air blowers but lacking connected-controls capability. Monitor carbon border adjustment mechanism implementation as the signal to watch for demand inflection toward certified electric heating systems among non-EU suppliers seeking market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Manufacturing | Captive supply of variable-frequency drive components insulates margin from copper and aluminum commodity volatility. |
| IoT-Enabled Temperature Zoning Partnership | Automotive paint shops in Stuttgart and Wolfsburg deploy real-time feedback systems to eliminate thermal overshoot during curing cycles. |
| CE Marking and Ecodesign Certification Acceleration | Filters non-compliant suppliers from EU market access, concentrating demand among certified equipment providers. |
| India PLI Corridor Facility Establishment | Production-linked incentives for technical textiles stimulate greenfield construction with modern processing infrastructure in Tamil Nadu. |
| Service Contract Unbundling Strategy | Mid-sized food processors in North American corridors separate capital procurement from aftermarket maintenance to preserve engineering capacity. |
Methodological Framework
Coverage spans Germany, the United States, China, India, and Japan, with primary inputs from each market combining interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads alongside secondary validation. Trade data from customs authorities, SEC filings from listed HVAC and industrial equipment manufacturers, Ecodesign directive implementation reports, and SAMR GB standard certification databases anchor quantitative baselines. Bottom-up equipment shipment analysis triangulates against top-down industrial energy consumption projections.
Granularity-level modeling disaggregates volume and value outputs by product type, heating technology, end-use vertical, and application across the analysis window. Convection oven, hot air blower, hot air dryer, and heat gun categories were modeled separately with distinct replacement cycle assumptions. Electrical, infrared, induction, and gas combustion technology shares were projected based on regulatory phase-down schedules and precision requirements. CAGRs were derived from regression analysis of historical capital expenditure patterns in food processing and automotive manufacturing against throughput mandate intensities.
Regulatory enforcement delays, commodity price spikes beyond historical volatility bands, and faster-than-anticipated infrared substitution in electronics curing are the dominant revision risks that could compress electric heating equipment demand or accelerate technology transitions. Forecasts reflect documented assumptions regarding EU F-Gas Regulation implementation timelines and India PLI scheme disbursement continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Mobile Computer Cart Market
Others
Refractometer Market
Others
Mobile Computing Devices Market
Others
Global Smart Home Installation Service Market
Others
Japan Smart Home Market
Others
Asia Pacific Cloud Infrastructure Testing Services Market
Others
Aircraft Lighting Market
Others
Aerospace and Defense Fiber Optic Cables Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Middle East Location-Based Services Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
Asia-Pacific Telecom Transformers Market
Others
Global Hair Loss Treatment Products Market
Others
Global Cryogenic Tanks Market
Others
Heavy Duty Traps Market
Others
5G Devices Market