
 Europe Aircraft Lighting Systems Market | 2026-2036
Europe Aircraft Lighting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Aircraft Lighting Systems Market Analytics
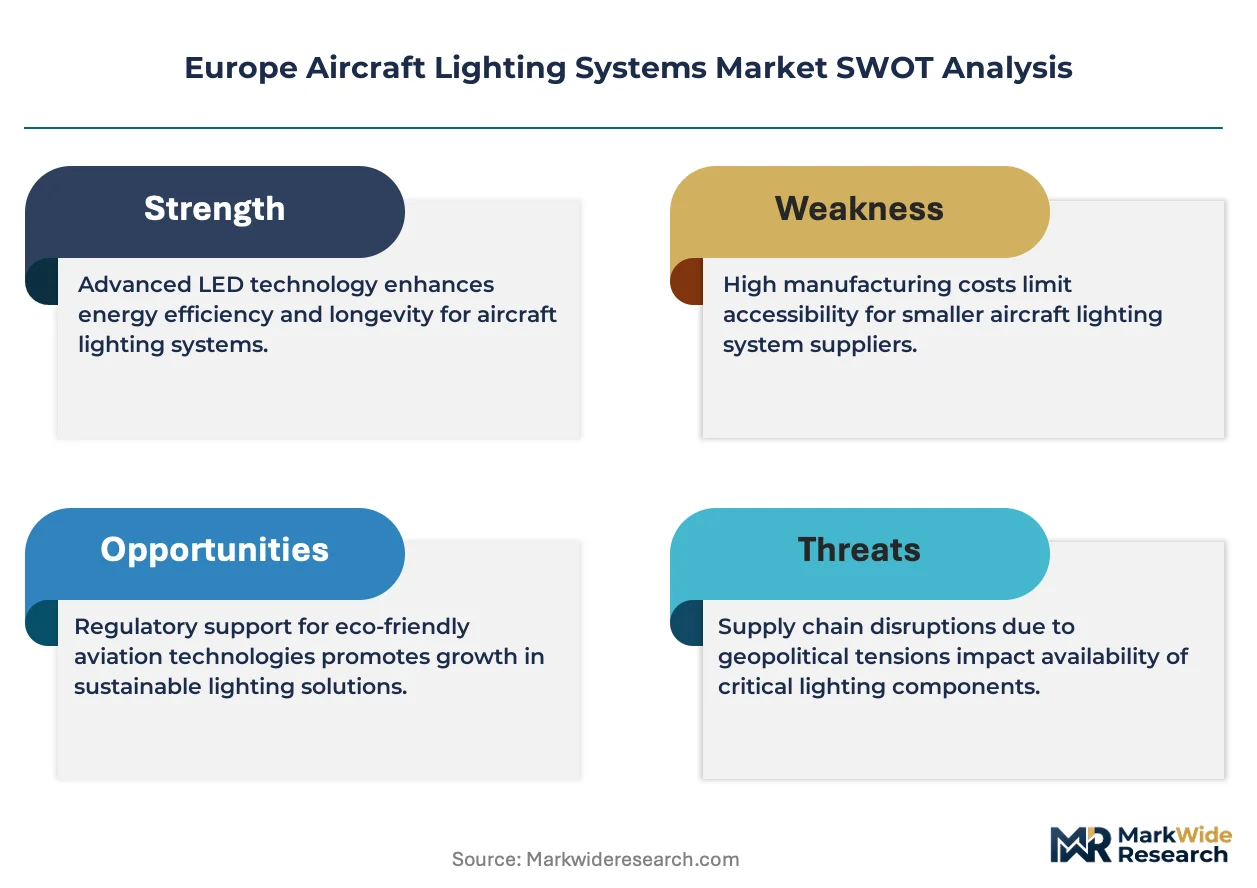
Subscription-based maintenance contracts for LED cabin retrofits is recalibrating how European airlines budget lighting upgrades across fleet cycles. Collins Aerospace leverages its integrated avionics-to-lighting pipeline to capture recurring service revenue on narrowbody platforms. Diehl Stiftung & Co. KG anchors German manufacturing scale across both OEM fit and aftermarket channels. Safran competes through specialized emergency lighting systems that meet EASA's evolving evacuation-visibility mandates.
Aircraft lighting systems encompass interior, exterior, emergency, and signage illumination subsystems engineered to specific photometric, chromaticity, and reliability parameters such as color temperatures ranging from 2700K to 6500K and minimum luminous intensities measured in candela for runway visibility. These systems serve critical functions spanning passenger experience enhancement, flight crew operational readability, airframe visibility to other aircraft, and regulatory-compliant evacuation path marking. Interior lighting commands the largest installed base across European commercial fleets, though exterior LED wingtip and landing light retrofits represent the fastest-expanding margin pool as operators pursue fuel-burn reductions through weight savings. LED technology dominates new production while HALO and fluorescent technologies retain positions in legacy military platforms where recertification costs delay replacement cycles.
EASA's CS-25 airworthiness standards and the EU's REACH chemical restrictions jointly constrain material selection for phosphor coatings and housing compounds in lighting assemblies sold across member states. The EU Green Deal's embodied-carbon tracking requirements are forcing suppliers to document supply chain emissions for cabin retrofit bids tendered by flag carriers. Stakeholders must monitor how EASA's upcoming photobiological safety standards for blue-enriched LED spectra reshape product roadmaps and testing protocols.
Market Dynamics
Retrofit-driven demand from European commercial fleets is compressing supplier lead times while EASA tightens photometric compliance windows, forcing lighting integrators to reconfigure certification pipelines around accelerated cabin modernization programs.
Growth Catalysts
- EU Green Deal embodied-carbon mandates:Flag carriers across France, Germany, and Spain now require documented supply chain emissions for retrofit bids, pulling LED cabin upgrades into fleet renewal schedules ahead of original replacement timelines.
- LED weight-reduction physics:Narrowbody operators in Italy and the Netherlands are prioritizing exterior LED retrofits for landing and wingtip assemblies to capture fuel-burn savings across high-cycle short-haul routes.
- EASA CS-25 evacuation-visibility standards:Updated photometric requirements for emergency path marking are mandating floor-proximity lighting replacements in aging single-aisle fleets registered in Portugal and Ireland.
Market Restraints
- Phosphor coating input volatility:Rare-earth element pricing for LED phosphor formulations fluctuates with Chinese export quotas, squeezing margin stability for European lighting module assemblers.
- Toulouse-area supply clustering:Airbus supply chain concentration around southwestern France creates single-point vulnerability for lighting procurement, with limited qualified alternative sources in central or eastern Europe.
- REACH chemical restriction friction:ECHA's evolving substance restrictions on housing compounds and thermal interface materials force reformulation cycles that delay product qualification by 8-14 months.
Strategic Opportunities
- Polish and Romanian MRO channel penetration:Independent maintenance facilities in eastern Europe lack OEM-authorized lighting retrofit capabilities, opening aftermarket service contracts for certified third-party integrators.
- Photobiological safety standard preparation:EASA's anticipated blue-enriched LED spectra regulations will require redesigned testing protocols, rewarding suppliers who pre-invest in spectral measurement infrastructure.
- Cabin-to-cockpit system convergence:Integration of ambient lighting with flight deck alert systems creates cross-departmental procurement budgets at flag carriers seeking unified human-factors certification.
Industry Challenges
- EASA certification timeline compression:Photometric testing backlog at designated engineering representatives extends STC approval cycles, straining airline fleet planning departments.
- Legacy fluorescent inventory rationalization:Operators maintaining mixed LED-fluorescent fleets face spare parts complexity and technician training bifurcation across maintenance bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Aircraft Lighting Systems Market |
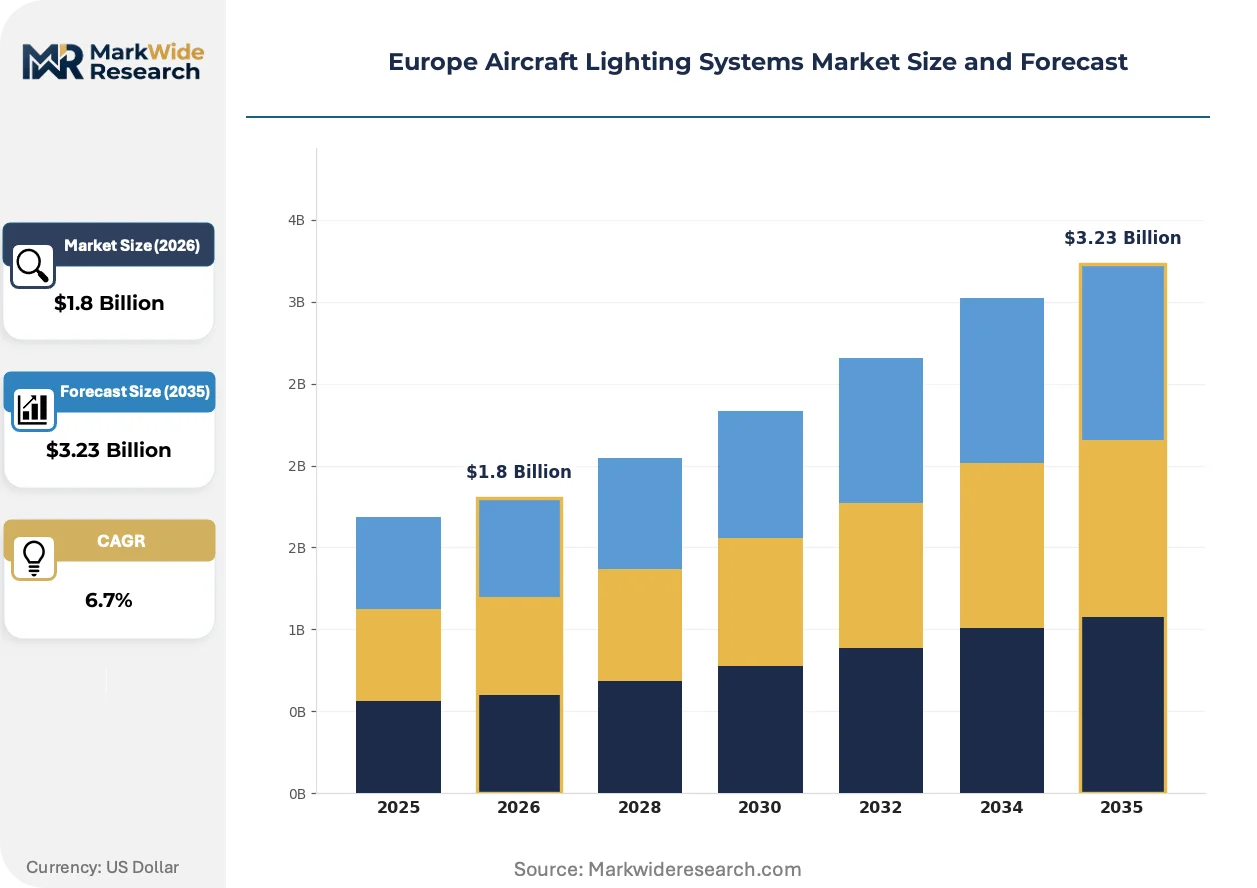
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Lighting, Exterior Lighting, Emergency Lighting, Signage Lighting Technology: LED, HALO, Incandescent, Fluorescent Application: Commercial Aircraft, Military Aircraft, Business Jets, Helicopters End User: Aircraft Manufacturers, MRO Providers, Airlines, Government Agencies |
| Companies Covered | Collins Aerospace, Safran, Honeywell International Inc., Diehl Stiftung & Co. KG, Astronics Corporation, Oxley Group, STG Aerospace Limited, Whelen Aerospace Technologies, Madelec Aero, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Aircraft Lighting Systems Market Evolving Landscape
Lighting system architecture is fragmenting into interchangeable sub-modules as airlines demand configuration flexibility without full recertification, while regulatory pressure on spectral safety and embodied carbon accelerates product obsolescence cycles.
Addressable LED strip architectures are modularizing cabin illumination into zone-controllable segments that permit post-delivery reconfiguration. Lufthansa and Air France-KLM are specifying these systems for new narrowbody deliveries to enable rapid cabin rebranding between seasonal schedules. This modularity is compressing the traditional 12-year lighting replacement cycle into 6-8 year refresh intervals.
EASA's forthcoming photobiological safety standards for blue-enriched LED spectra are forcing suppliers to redesign emission profiles and documentation protocols. German lighting integrators face the steepest compliance burden due to their concentration in high-lumen cockpit and reading light assemblies. The regulation is pushing manufacturers toward amber-dominant spectral distributions that reduce circadian disruption risk.
Subscription-based maintenance contracts are displacing capital-purchase models for LED retrofits across Scandinavian and Benelux carriers. These arrangements transfer obsolescence risk to suppliers while locking in recurring revenue streams. British Airways and Iberia have piloted such programs for widebody cabin upgrades, with performance metrics tied to mean-time-between-failure rates rather than equipment delivery.
Europe Aircraft Lighting Systems Market Segmentation
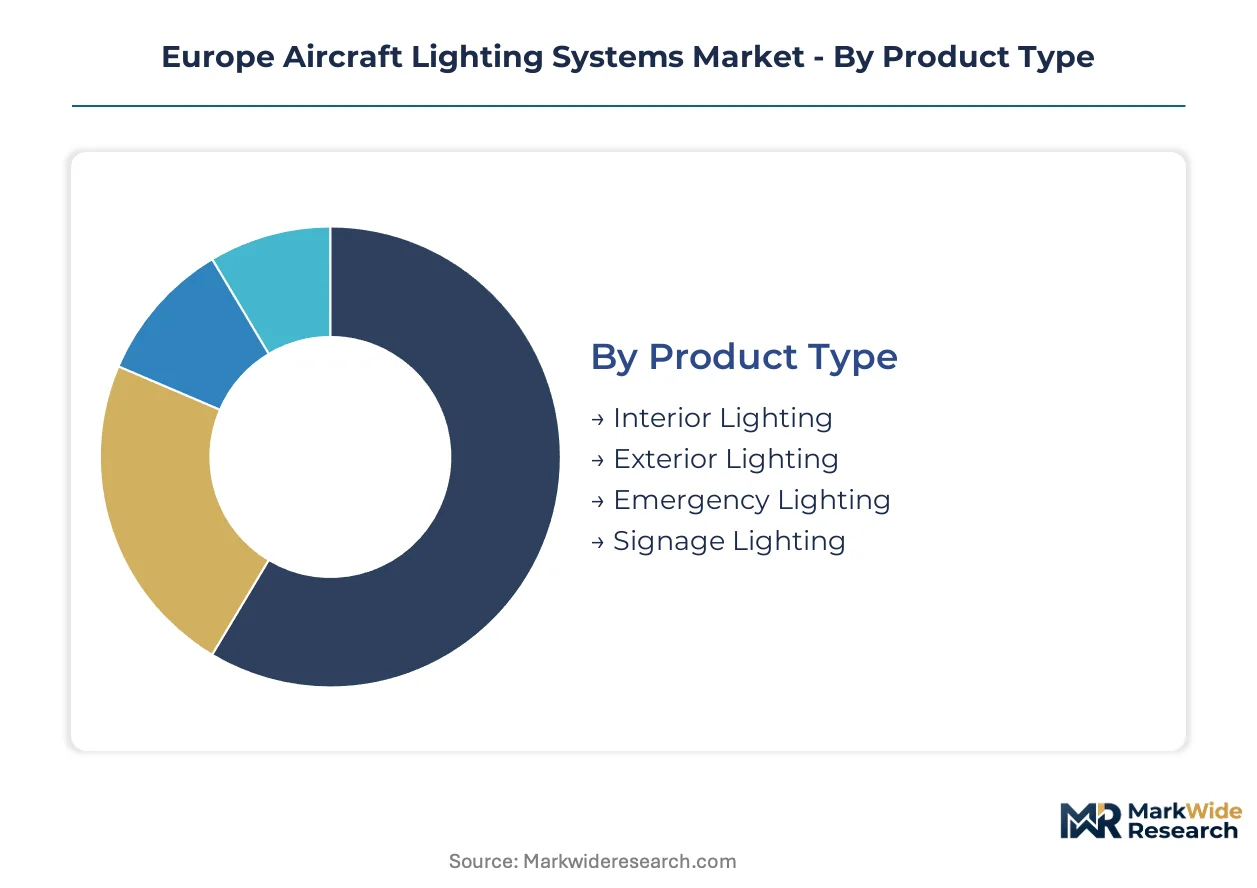
Segmentation in Europe's aircraft lighting market reveals divergent technology lifecycles and procurement pathways. Interior and exterior systems follow separate upgrade rhythms, while LED displacement of legacy technologies accelerates unevenly across military and commercial fleets.
Product Type:
Interior lighting commands the volume base across European narrowbody and widebody fleets, while exterior retrofits capture premium margins through fuel-burn reduction claims.
- Interior Lighting:Encompasses cabin ambient, reading, and galley illumination with color temperatures spanning 2700K to 6500K. Demand clusters in France and Germany where Air France-KLM and Lufthansa pursue cabin modernization programs ahead of lease return cycles.
- Exterior Lighting:Wingtip, landing, and taxi light assemblies engineered for candela intensity and airframe visibility. Italian and Dutch operators prioritize these LED retrofits for weight savings on high-cycle short-haul routes, expanding the fastest among product categories.
- Emergency Lighting:Floor-proximity path marking and evacuation signage meeting EASA CS-25 photometric mandates. Aging single-aisle fleets in Portugal and Ireland drive replacement demand.
- Signage Lighting:Exit markers and informational displays with chromaticity compliance for passenger readability. Procurement ties to complete cabin reconfiguration contracts rather than standalone upgrades.
Today's leader: Interior Lighting. Tomorrow's challenger: Exterior Lighting.
Technology:
LED dominates new production lines while legacy technologies persist where recertification economics delay replacement.
- LED:Solid-state illumination with phosphor-converted white emission, thermal management requirements, and 50,000-hour rated lifespans. EASA's tightening photometric compliance windows and EU Green Deal embodied-carbon tracking pull LED specifications into retrofit tenders.
- HALO:Halogen-based systems retaining position in legacy military platforms where airworthiness recertification costs outweigh efficiency gains. Limited procurement outside defense maintenance contracts.
- Incandescent:Tungsten-filament technology confined to oldest operational fleets and non-critical applications. REACH chemical restrictions on housing materials accelerate phase-out timelines.
- Fluorescent:Cold-cathode and compact fluorescent systems in mixed-fleet operators facing spare parts complexity. ECHA substance restrictions on phosphor coatings force reformulation cycles extending qualification delays.
LED holds installed base dominance. Fluorescent exit paths create the steepest compliance burden for remaining operators.
Application:
Commercial aviation concentrates procurement volume while military and business aviation segments exhibit divergent upgrade incentives.
- Commercial Aircraft:Narrowbody and widebody platforms with 150+ passenger capacity driving bulk lighting procurement. Retrofit demand from Scandinavian and Benelux carriers shifts purchasing toward subscription maintenance models.
- Military Aircraft:Fighter, transport, and surveillance platforms with mission-specific NVIS-compatible lighting requirements. Budget cycles and platform longevity delay LED adoption compared to commercial equivalents.
- Business Jets:Corporate and VIP configurations emphasizing cabin customization and rapid reconfiguration. Addressable LED strip architectures enable seasonal rebranding without full recertification.
- Helicopters:Rotary-wing platforms with vibration-resistant mounting and weight-critical specifications. Offshore and emergency medical operators in the North Sea corridor drive specialized demand.
Commercial Aircraft anchors current revenue. Business Jets expand most quickly through customization premiums.
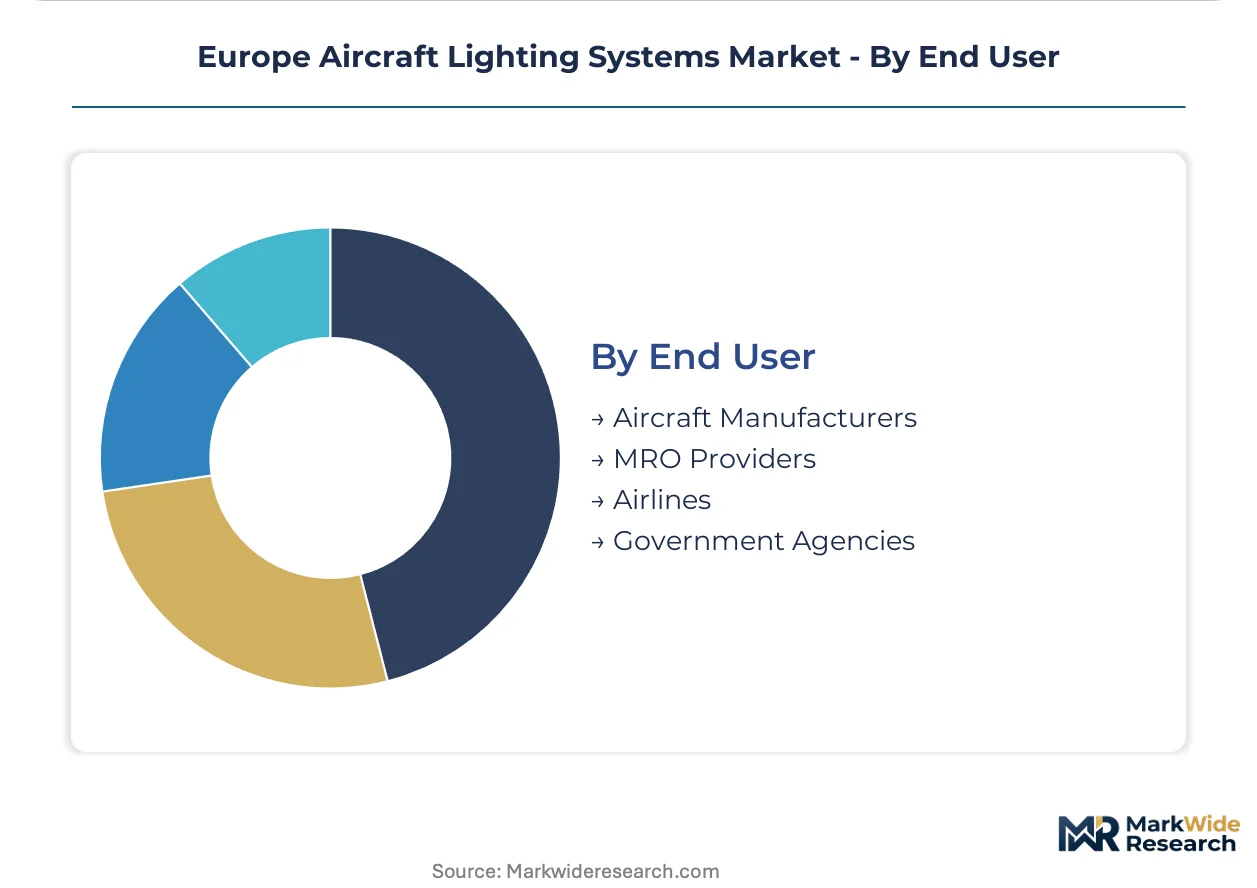
End User:
OEM fit channels compete with aftermarket retrofit pathways as fleet age profiles diverge across European operators.
- Aircraft Manufacturers:Airbus and smaller OEMs specifying lighting systems at production. Toulouse-area supply chain clustering concentrates procurement toward southwestern French integrators.
- MRO Providers:Maintenance facilities performing cabin retrofits and airworthiness directives. Independent eastern European MROs in Poland and Romania lack OEM-authorized lighting capabilities, opening third-party service contracts.
- Airlines:Flag carriers and low-cost operators balancing capital budgets against fuel-burn reduction claims. British Airways and Iberia pilot subscription models transferring obsolescence risk to suppliers.
- Government Agencies:Defense procurement bodies with platform-specific requirements and extended replacement cycles. Budget approval timelines lag commercial aviation by 18-36 months.
Airlines dominate retrofit spending. MRO Providers gain share fastest through independent certification investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates more Airbus supply chain procurement than Germany, yet German manufacturers retain stronger aftermarket retrofit penetration across central European MRO networks.
France
Air France-KLM's fleet renewal programs and Airbus production clustering around Toulouse pull lighting procurement toward southwestern French integrators. EASA's CS-25 evacuation-visibility standards compress certification timelines for emergency path marking systems. The Occitanie aerospace corridor hosts specialized lighting module assemblers serving both OEM fit and airline retrofit channels.
Germany
Lufthansa Group's narrowbody modernization and Diehl Stiftung's manufacturing scale anchor demand across Bavaria and Baden-Württemberg. REACH chemical restrictions on phosphor coatings force reformulation cycles extending product qualification delays. The Hamburg aviation cluster concentrates cockpit lighting specialists facing steep compliance burdens from forthcoming EASA photobiological safety standards.
United Kingdom
British Airways and Virgin Atlantic pilot subscription-based maintenance contracts for widebody cabin upgrades, transferring obsolescence risk to suppliers. The UK Civil Aviation Authority aligns with EASA photometric requirements post-Brexit, maintaining regulatory continuity for lighting certifications. London-area engineering consultancies support STC approval cycles for addressable LED strip architectures.
Italy
ITA Airways and low-cost operators prioritize exterior LED retrofits for landing and wingtip assemblies to capture fuel-burn savings on high-cycle Mediterranean routes. The EU Green Deal's embodied-carbon tracking requirements pull LED specifications into retrofit tenders ahead of original replacement timelines. Lombardy-based MRO facilities lack OEM-authorized lighting capabilities, opening third-party service contracts.
Netherlands
KLM's narrowbody fleet pursues rapid cabin rebranding capabilities through modular LED configurations between seasonal schedules. ECHA substance restrictions on thermal interface materials delay product qualification by 8-14 months for Dutch lighting distributors. The Randstad aviation logistics corridor channels procurement toward Scandinavian and Benelux subscription maintenance models.
Europe Aircraft Lighting Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated avionics-to-lighting pipelines capturing recurring service revenue while independent module assemblers compete on retrofit speed. The vendor base organizes around three archetypes: full-system integrators with certification infrastructure, component specialists focused on photometric compliance, and regional fabricators serving MRO channels. Consolidation pressure concentrates among emergency lighting specialists as EASA tightens evacuation-visibility mandates. Dominant competitive moves include backward integration into phosphor formulation supply and geographic expansion into eastern European MRO networks.
Within the full-system integrator tier, Collins Aerospace and Honeywell International Inc. exemplify diversified aerospace conglomerates leveraging avionics-to-lighting pipelines for recurring revenue capture. Diehl Stiftung & Co. KG anchors German manufacturing scale across OEM fit and aftermarket channels. Safran occupies a specialized position in emergency lighting systems aligned with EASA's evolving evacuation-visibility mandates. These three represent distinct strategic postures: diversified platform integration, regional manufacturing dominance, and regulatory-specialized niche capture.
| Leading Market Players |
|---|
| Collins Aerospace |
| Safran |
| Honeywell International Inc. |
| Diehl Stiftung & Co. KG |
| Astronics Corporation |
| Oxley Group |
| STG Aerospace Limited |
| Whelen Aerospace Technologies |
| Madelec Aero |
| Others |
Value Network & Pricing Analysis
Flag carriers in France and Germany command procurement leverage through multi-fleet retrofit programs, anchoring subscription-based maintenance contracts as the dominant pricing structure across European commercial aviation. EASA certification timelines and REACH chemical restrictions compress supplier margins while concentrating negotiating power with Airbus-anchored OEM channels.
Pricing Analysis
Capacity additions in Poland and Romania are reshaping price floors for aftermarket lighting retrofits as independent MRO facilities expand certification capabilities. Three-tier pricing structure across premium, standard, and economy levels separates OEM-authorized integrators from third-party module assemblers and regional fabricators. Pricing pressure stems from rare-earth phosphor input volatility and ECHA reformulation delays extending qualification cycles. Low-cost carriers exhibit highest price sensitivity, while business jet operators prioritize customization premiums over unit cost.
Supply Chain Analysis
Regional distribution centers in Toulouse, Hamburg, and London coordinate hub-and-spoke patterns for lighting module delivery across European MRO networks. Manufacturing concentrates in France, Germany, and the United Kingdom, with phosphor coating inputs drawing from Chinese rare-earth processing and Taiwanese LED chip fabrication. Single-source vulnerability around Toulouse-area Airbus clustering creates procurement concentration risk. Distribution runs through OEM-authorized integrators for new production and independent eastern European channels for retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA's forthcoming photobiological safety standards for blue-enriched LED spectra function as a regulatory compounder, forcing redesign investments that favor pre-certified suppliers with spectral measurement infrastructure already deployed.
For Market Incumbents: Extend backward integration into phosphor formulation supply to insulate margin stability from Chinese export quota volatility. Deepen certification pipeline investments to compress STC approval cycles as EASA tightens photometric compliance windows. Lock in multi-year subscription contracts with Scandinavian and Benelux carriers to transfer obsolescence risk and secure recurring revenue streams against emerging third-party integrators. For New Entrants and Emerging Players: Capture aftermarket service contracts in Polish and Romanian MRO channels where OEM-authorized lighting capabilities remain underdeveloped. Target independent maintenance facilities lacking EASA-certified emergency lighting retrofit expertise as the most penetrable entry point. Lead with rapid STC approval capabilities and modular LED strip architectures that enable post-delivery cabin reconfiguration without full recertification. For Investors and Strategic Acquirers: Aerospace conglomerates with integrated avionics-to-lighting pipelines are the most active acquirer in this space, seeking emergency lighting specialists to consolidate EASA compliance capabilities. Long-term viability hinges on spectral safety regulation preparation and embodied-carbon documentation infrastructure across the projection horizon. Watch for EASA photobiological safety standard publication timing as the critical inflection indicator for product roadmap winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphor Supply | Captive rare-earth sourcing insulates Diehl and Collins from Chinese quota volatility. |
| EASA Photobiological Safety Pre-Certification | Early spectral measurement infrastructure deployment rewards German cockpit lighting specialists. |
| Eastern European MRO Channel Expansion | Polish and Romanian facility partnerships unlock aftermarket retrofit share outside Toulouse clustering. |
| Subscription Maintenance Model Pilot | British Airways and Iberia programs transfer LED obsolescence risk to suppliers. |
| Modular LED Strip Architecture Launch | Lufthansa and Air France-KLM specifications enable rapid cabin rebranding between seasonal schedules. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with lighting system procurement directors at flag carriers, EASA certification engineers, MRO facility managers, and phosphor coating suppliers with secondary validation. EASA CS-25 airworthiness directives, REACH substance restriction updates, EU Green Deal embodied-carbon tracking guidelines, and customs trade data for LED module imports anchored the secondary foundation. Bottom-up fleet retrofit demand modeling and top-down OEM production schedules were triangulated against supplier revenue disclosures.
Historical reference periods spanning production line deliveries and aftermarket retrofit cycles anchored the forecast window across the projection horizon. Segmentation dimensions modeled include product type, technology platform, application category, and end-user channel, with EASA compliance tier and supply chain carbon documentation capability as industry-specific overlay variables. CAGRs were derived from fitted growth curves calibrated to announced fleet renewal programs and retrofit tender timelines. Fuel-burn reduction claims from exterior LED weight savings and evacuation-visibility mandate compliance deadlines served as key forecast inputs.
Underlying measurement precision varies by segment; interior lighting and LED technology categories carry tighter precision than legacy fluorescent and military applications due to more transparent procurement data. Forecasts reflect documented assumptions around EASA regulatory publication timing, rare-earth pricing stability, and airline capital expenditure commitment levels. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
South Korea Smart Home Market
Others
Global Hair Loss Treatment Products Market
Others
5G Devices Market
Others
Powder Coating Equipment Market
Others
Global Extruded Plastics Market
Others
Mobile Computing Devices Market
Others
Europe Intercom Devices Market
Others
Signal Transformer Market
Others
North America Printed Signage Market
Others
Global Supply Chain Risk Management Software Market
Others
Composite Copper Foil Production Equipment Market
Others
Silicone Molding Machinery Market
Others
Wood Stoves Market
Others
Industrial Gauges Market
Others
UK Cat Food Market
Others
Flexographic Printing Plate Market