
 8K Technology Market | 2026-2036
8K Technology Market Size, Share, and Industry Trends Forecast 2026-2036
8K Technology Market Intelligence
South Korea's display fab expansion is reconfiguring supply availability for 8K panels. Samsung Electronics leverages vertical integration from semiconductor to finished display, sustaining cost advantages across the value chain. BOE Technology Group anchors volume production of large-format panels, competing aggressively on manufacturing scale. LG Electronics differentiates through OLED technology leadership in premium television segments.
8K technology denotes imaging and display systems with horizontal resolution of approximately 7680 pixels, requiring 33.2 megapixels per frame and bandwidth exceeding 48 Gbps for uncompressed transmission. These specifications serve professional cinematography, medical visualization, and immersive simulation where detail fidelity determines operational utility. Display panels occupy the largest value share among product categories, driven by television and digital signage procurement. OLED technology commands premium positioning in cinematography and broadcast monitoring applications where color accuracy justifies higher unit economics. MicroLED represents the fastest-growing technology segment for commercial signage and luxury residential installations, though manufacturing yields remain constrained.
FCC broadcast spectrum rules in the United States, MIIT ultra-high-definition standards in China, and EU Ecodesign requirements under the EU Green Deal collectively shape product certification cycles and energy efficiency mandates. Japan's METI has established 8K broadcast transmission protocols that influence encoder and decoder specifications across Asian supply chains. Stakeholders must monitor regulatory divergence between terrestrial broadcast standards and streaming-centric compression formats as deployment models fragment.
Market Dynamics
Broadcast infrastructure mandates in Japan, South Korea, and China are compressing panel procurement cycles while tightening certification requirements for transmission equipment. This regulatory momentum is pulling display fab capacity toward East Asian manufacturing clusters.
Growth Catalysts
- MIIT Ultra-High-Definition Standards:China's certification tightening for 8K video transmission equipment is forcing encoder and decoder upgrades across domestic supply chains, expanding addressable hardware demand.
- Medical Visualization:Surgical robotics and pathology imaging systems require 33.2 megapixel frame fidelity, creating specialized procurement channels for diagnostic-grade panels.
- East Asian Manufacturing Clusters:Co-location of display fabs and camera module suppliers in Seoul, Beijing, and Tokyo reduces logistics friction and accelerates prototype-to-production cycles.
Market Restraints
- MicroLED Manufacturing Yields:Commercial signage and luxury residential installations face supply constraints from defect-prone epitaxial growth processes, limiting volume scaling.
- 48 Gbps Bandwidth Requirements:Uncompressed 8K transmission demands fiber infrastructure upgrades that terrestrial broadcasters in legacy markets cannot absorb without subsidy frameworks.
- OLED Input Cost Concentration:Premium cinematography and broadcast monitoring applications depend on limited organic emitter material suppliers, creating margin volatility.
Strategic Opportunities
- Immersive Simulation:Military training and architectural visualization systems represent underpenetrated demand for detail-fidelity displays where pixel density determines operational utility.
- EU Ecodesign Requirements:Energy efficiency mandates under the EU Green Deal favor next-generation panel technologies that exceed legacy power consumption thresholds.
- Streaming-Centric Compression:Convergence of AV1 and VVC codecs enables bandwidth-efficient 8K delivery over IP networks, opening distribution channels beyond terrestrial broadcast.
Industry Challenges
- Terrestrial-to-IP Standard Divergence:Broadcast engineers must maintain parallel certification tracks for ATSC 3.0 and streaming-centric formats, fragmenting R&D allocation.
- Color Science Talent Scarcity:Professional cinematography and medical imaging applications require specialists who bridge display physics with perceptual calibration protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 8K Technology Market |
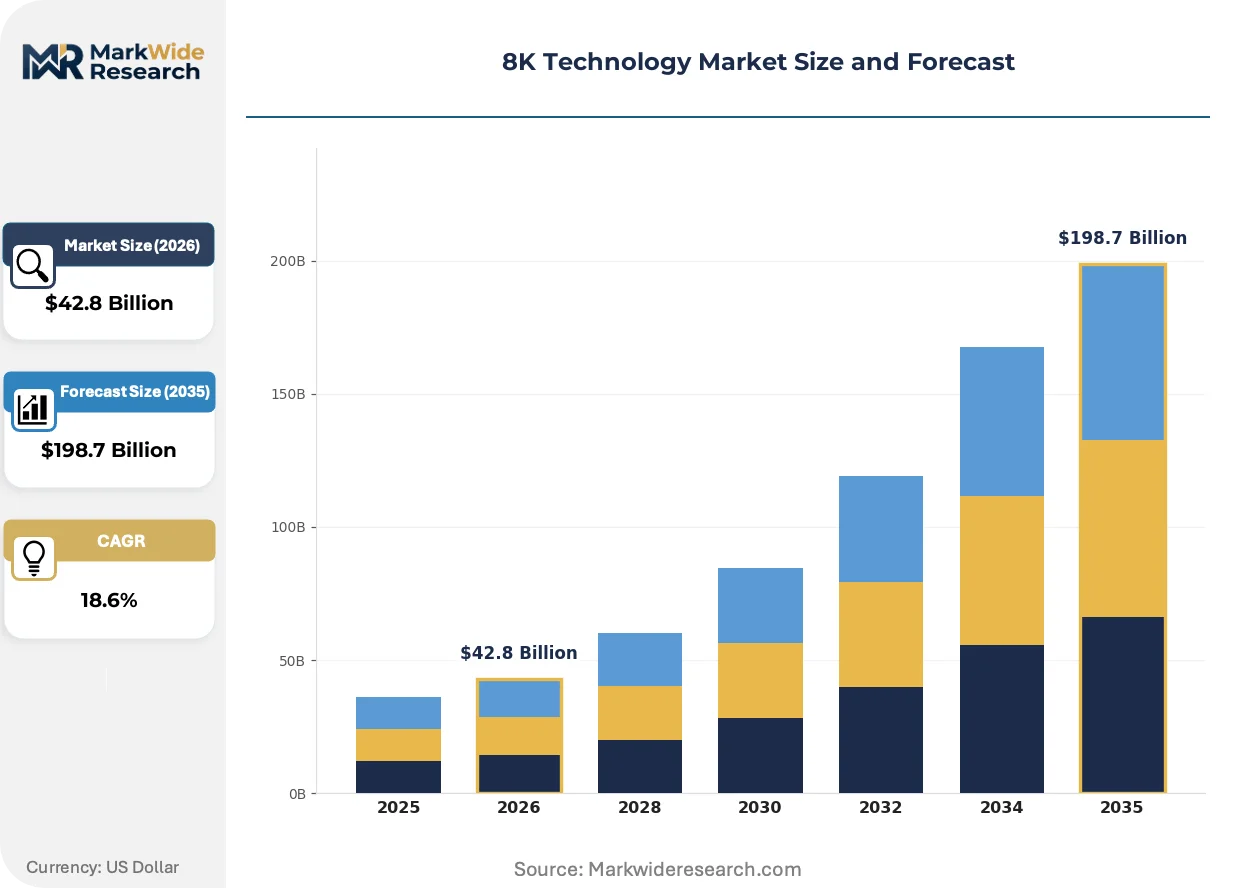
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $198.7 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Panels, Cameras, Processors, Storage Devices, Cables, Connectors Technology: LED, OLED, QLED, MicroLED, MiniLED, LCD Application: Broadcasting, Cinematography, Simulation Systems, Digital Signage, Video Conferencing, Virtual Reality End User: Media Studios, Event Production Companies, Educational Institutions, Military Training Centers, Corporate Enterprises, Entertainment Venues |
| Companies Covered | BOE Technology Group, Sharp Corporation, Samsung Electronics, Dell Technologies, Canon Inc., LG Electronics, TCL Electronics, Panasonic Corporation, Sony Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
8K Technology Market Strategic Shifts & Innovations
Codec virtualization and cloud-native production workflows are separating image processing from dedicated hardware, compressing capital requirements for content creators. This shift is redrawing competitive boundaries between semiconductor, software, and display vendors.
AI-driven upscaling silicon is virtualizing the traditional demarcation between native and interpolated 8K content. Post-production houses in Los Angeles and London are adopting real-time enhancement pipelines that reduce raw capture bandwidth requirements. The technology is virtualizing storage and transmission cost structures that previously favored 4K acquisition.
METI broadcast transmission protocols are mandating specific encoder and decoder specifications that cascade through Asian supply chains. Equipment vendors must recertify hardware for Japan's 8K terrestrial standards before accessing adjacent markets. Professional monitor manufacturers face compressed product cycles as these specifications iterate.
Buyers in cinematography and medical imaging are unbundling after-sales calibration from hardware procurement, treating color accuracy as a subscription service. This behavior compresses upfront equipment margins while extending vendor revenue duration. Seoul and Tokyo clusters show the strongest concentration of this purchasing pattern.
8K Technology Market Segmentation
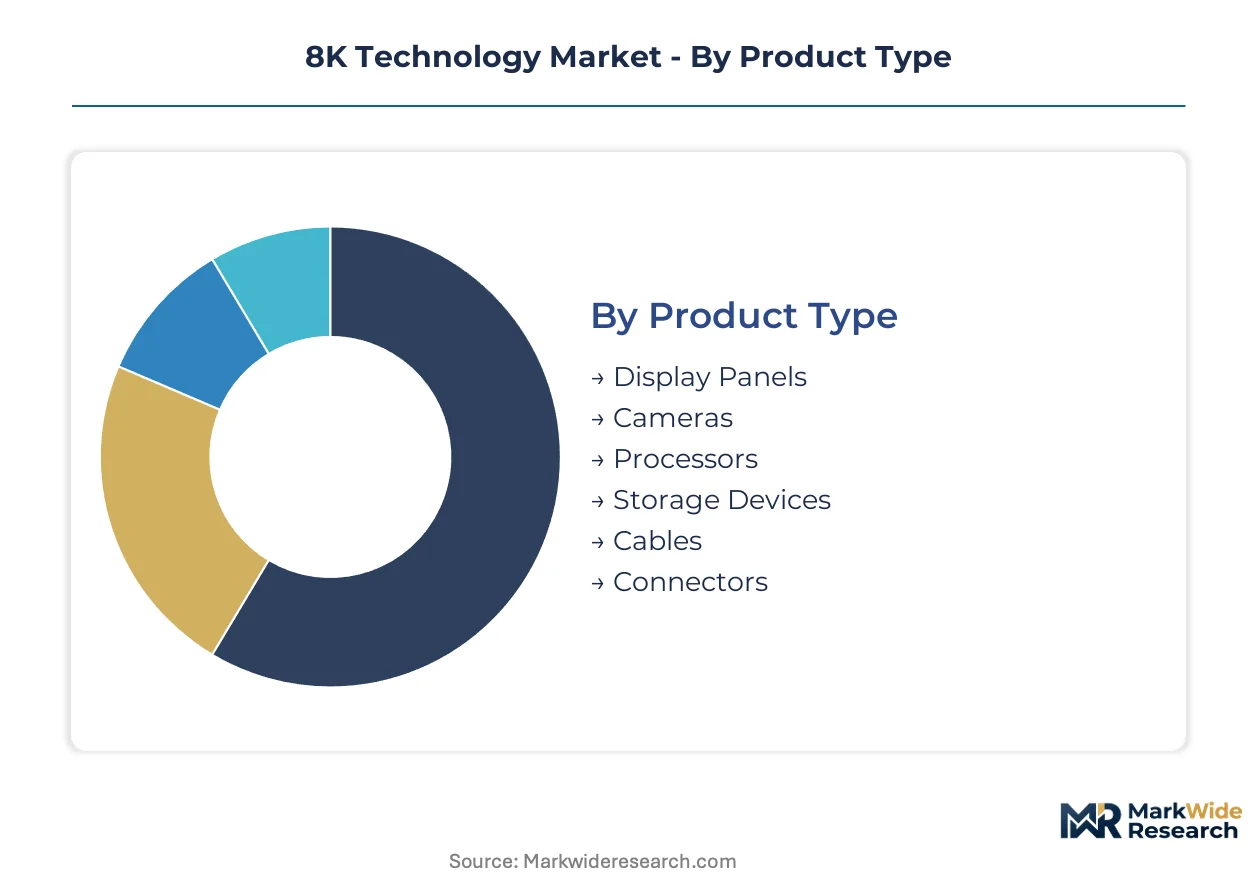
8K technology deployment fragments across incompatible hardware ecosystems, compression standards, and procurement workflows. Each segment carries distinct margin profiles, certification requirements, and replacement cycles that determine vendor resource allocation.
Product Type:
Cost tier separation across the hardware stack determines procurement bundling patterns and margin capture opportunities.
- Display Panels:Large-format LCD and OLED substrates dominate capital expenditure in broadcast infrastructure and residential premium segments. Procurement concentrates in Seoul and Beijing manufacturing clusters where glass substrate supply tightens pricing leverage.
- Cameras:33.2 megapixel image sensors with 7680-pixel horizontal resolution require specialized CMOS fabrication at leading-edge semiconductor nodes. Demand clusters in Los Angeles cinematography houses and Tokyo broadcast equipment rental pools.
- Processors:Real-time 8K encoding and AI-driven upscaling silicon separates professional from prosumer equipment tiers.
- Storage Devices:NVMe arrays with sustained write bandwidth above 800 MB/s handle uncompressed 48 Gbps streams.
- Cables:Fiber optic and active copper assemblies certified for HDMI 2.1 and DisplayPort 2.1 protocols.
- Connectors:Miniaturized high-density interfaces for camera rigs and medical visualization systems.
Display panels command the established base. The steepest expansion runs through processors.
Technology:
Application requirements for color accuracy, luminance range, and pixel density create divergent technology adoption curves.
- LED:Direct-lit and edge-lit configurations serve cost-sensitive digital signage and corporate video conferencing installations where brightness uniformity matters more than black level performance.
- OLED:Self-emissive organic compounds deliver infinite contrast ratios and sub-millisecond response times. Cinematography colorists in London and Los Angeles specify OLED reference monitors for HDR mastering workflows where perceptual accuracy determines deliverable acceptance.
- QLED:Quantum dot enhancement layers extend color gamut coverage for broadcast monitoring applications.
- MicroLED:Chip-scale LED transfer yields constrain volume despite superior luminance efficiency for daylight-viewable signage.
- MiniLED:Thousands of local dimming zones bridge performance gaps at intermediate price points.
- LCD:Mature manufacturing infrastructure supports commodity large-format deployments.
OLED anchors premium positioning. MicroLED climbs the fastest despite yield constraints.
Application:
Customer workflow integration depth varies dramatically across use cases, from plug-and-play signage to custom-engineered simulation environments.
- Broadcasting:Terrestrial transmission infrastructure in Japan, South Korea, and China mandates encoder and decoder certification against METI and MIIT specifications. Equipment replacement cycles compress as standards iterate.
- Cinematography:Camera acquisition and post-production pipelines require frame-accurate synchronization across distributed rendering farms. Productions in New Zealand and Iceland leverage 8K oversampling for visual effects plate photography.
- Simulation Systems:Military training and architectural visualization demand pixel-dense curved arrays with sub-frame latency.
- Digital Signage:Retail and transportation hubs prioritize sunlight readability over color fidelity.
- Video Conferencing:Enterprise deployments emphasize camera auto-framing and bandwidth adaptation.
- Virtual Reality:Head-mounted displays approaching retinal resolution reduce screen-door artifacts.
Broadcasting holds the installed base. Simulation systems gain share fastest in defense procurement channels.
End User:
Procurement sophistication and total cost of ownership calculation methods diverge sharply across institutional buyer types.
- Media Studios:Post-production houses in Los Angeles, London, and Mumbai amortize equipment across project-based revenue. Color science talent scarcity forces outsourcing of calibration services.
- Event Production Companies:Rental inventory turnover prioritizes durability and rapid deployment over specification extremes.
- Educational Institutions:University media programs balance pedagogical demonstration value against constrained capital budgets.
- Military Training Centers:Immersive dome and cave installations require custom integration with simulation software.
- Corporate Enterprises:Boardroom and experience center deployments emphasize wireless presentation and IT manageability.
- Entertainment Venues:Stadium and arena LED mesh installations prioritize service access and weather resistance.
Media studios represent the core revenue foundation. Military training centers drive the steepest technology specification escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT standards in China anchor the dominant geography, compressing certification timelines for transmission equipment and pulling display fab investment toward East Asian manufacturing clusters. Japan's METI protocols and South Korea's fab expansion complete the regulatory-industrial triangle that shapes procurement patterns.
China
Domestic demand for ultra-high-definition broadcast infrastructure drives encoder and decoder upgrades across state-owned network operators. MIIT certification tightening for 8K video transmission equipment mandates hardware refreshes that expand addressable equipment demand. Beijing and Shenzhen manufacturing clusters co-locate display panel production with camera module assembly, reducing prototype-to-production cycles for integrated systems.
Japan
METI-established 8K broadcast transmission protocols mandate specific encoder and decoder specifications that cascade through equipment supply chains. Terrestrial broadcast infrastructure mandates compress replacement cycles for professional monitors and studio hardware. Tokyo and Osaka clusters concentrate professional cinematography rental pools and broadcast equipment integration facilities serving NHK and commercial networks.
South Korea
Display fab expansion in Seoul metropolitan area reconfigures panel supply availability for global television and digital signage procurement. Domestic content regulations favor locally manufactured transmission equipment for KBS and MBC network upgrades. Suwon and Gumi industrial zones anchor vertical integration from semiconductor fabrication through finished display assembly.
United States
FCC broadcast spectrum rules shape terrestrial transmission equipment certification cycles distinct from streaming-centric deployment models. Hollywood post-production houses in Los Angeles drive demand for reference monitors and oversampling camera systems. Professional cinematography rental pools in New York and Atlanta create secondary demand centers for acquisition hardware.
Germany
EU Ecodesign requirements under the EU Green Deal impose energy efficiency mandates that favor next-generation panel technologies exceeding legacy power thresholds. Broadcast engineering consultancies in Munich and Cologne maintain parallel certification tracks for terrestrial and IP-based distribution. Industrial visualization specialists in Stuttgart and Wolfsburg deploy simulation-grade displays for automotive design workflows.
8K Technology Market Key Industry Players
Vertically integrated conglomerates and specialized component suppliers split the market into distinct competitive spheres. Korean and Japanese conglomerates leverage captive semiconductor and display fabrication to compress cost structures across the value chain. Chinese panel specialists compete on manufacturing scale and government-backed capacity expansion. Two dominant competitive moves define current positioning: backward integration into raw material supply and strategic partnerships for codec virtualization.
Among Korean electronics conglomerates, Samsung Electronics and LG Electronics occupy positions that exemplify vertical integration archetypes. BOE Technology Group anchors the Chinese manufacturing scale tier. Canon Inc. and Sony Corporation represent Japanese specialists with entrenched positions in professional imaging equipment. Sharp Corporation and Panasonic Corporation sit within the diversified industrial electronics segment with broadcast infrastructure exposure.
| Leading Market Players |
|---|
| BOE Technology Group |
| Sharp Corporation |
| Samsung Electronics |
| Dell Technologies |
| Canon Inc. |
| LG Electronics |
| TCL Electronics |
| Panasonic Corporation |
| Sony Corporation |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese LCD fabs is compressing panel pricing and forcing Korean manufacturers toward OLED premium positioning. This utilization imbalance redistributes margin capture upstream to semiconductor foundries and specialized emitter material suppliers.
Pricing Analysis
East Asian panel pricing diverges from North American and European landed costs by freight and tariff differentials. Pricing stratifies across premium OLED cinematography monitors, standard QLED broadcast equipment, and economy LCD digital signage tiers. Cost compression in large-format LCD stems from BOE and TCL capacity additions. Event production rental houses exhibit highest price sensitivity; medical imaging systems show lowest.
Supply Chain Analysis
Export controls on advanced lithography equipment constrain Chinese access to leading-edge CMOS fabrication for 33.2 megapixel sensors. Supply concentrates in South Korea, Japan, and Taiwan for display glass and semiconductor inputs. Organic emitter materials and quantum dot precursors draw from limited chemical suppliers. Single-source vulnerability runs through Japanese photoresist and German deposition equipment. Distribution runs through Seoul and Beijing manufacturing clusters to global integration facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Codec virtualization and cloud-native production workflows are fragmenting procurement patterns, creating specialized niches for upscaling silicon vendors and calibration service providers.
For Market Incumbents: Pre-empt MicroLED yield improvements by securing epitaxial growth equipment ahead of capacity constraints. Lock in long-term organic emitter supply contracts before material scarcity intensifies. Defend against AI upscaling substitution by embedding real-time enhancement into reference monitor firmware.
For New Entrants and Emerging Players: Military training simulation systems in the United States and Germany represent the most penetrable entry point for curved-array integrators lacking broadcast certification heritage. Medical pathology imaging in Indian and Southeast Asian hospital networks offers secondary white-space with lower regulatory barriers. Partner with established color science subscription services to bypass talent scarcity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MicroLED transfer equipment and AI upscaling silicon design. Five-to-ten-year viability favors acquisition targets with captive calibration service revenue and METI/MIIT certification track records. Watch for AV1 and VVC codec licensing inflection as signal of streaming-centric hardware demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Emitters | Reduces margin volatility from limited Japanese and German chemical suppliers. |
| AI Upscaling Silicon Development | Captures value from post-production houses adopting real-time enhancement pipelines. |
| METI Certification Pre-Approval | Accelerates market access across Japanese terrestrial broadcast infrastructure mandates. |
| MicroLED Epitaxial Partnership | Addresses yield constraints blocking volume scaling for daylight-viewable signage. |
| Calibration-as-a-Service Platform | Extends revenue duration as buyers unbundle color accuracy from hardware procurement. |
Research Approach
Cross-validation between broadcast engineering consultancies and display panel procurement data anchors the qualitative findings. Primary interviews with cinematography colorists, broadcast equipment rental managers, surgical robotics engineers, and military simulation integrators combined with secondary validation against MIIT certification registries, METI protocol documentation, FCC spectrum filings, and EU Ecodesign compliance databases. Bottom-up equipment shipment analysis and top-down broadcast infrastructure investment tracking triangulate market sizing.
Calibration against historical panel price elasticities and encoder deployment cycles refines the analytical framework across the projection horizon. Segmentation dimensions include display technology, application workflow depth, end-user procurement sophistication, and regional regulatory cluster. CAGRs derive from capacity expansion announcements correlated with certification timeline compression. Forecast inputs incorporate MicroLED yield improvement trajectories and AV1/VVC codec adoption curves.
Practitioners should monitor MIIT certification iteration pace and MicroLED defect rate trajectories for early signals. Forecasts reflect assumptions on terrestrial-to-IP standard convergence and organic emitter supply stability. Material shifts in export control enforcement or streaming codec royalty structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Underwater Light Market
Others
Global Smart Home Installation Service Market
Others
US Cat Food Market
Others
Trusted Platform Module (TPM) Market
Others
Asia-Pacific Legal Services Market
Others
Programmatic Display Market
Others
Motor Grader Market
Others
US Tablet Market
Others
Europe Refrigerated Display Cases Market
Others
Global Snow Sports Apparel Market
Others
Canada Laser Hair Removal Market
Others
Toy Packaging Market
Others
Smart Home Market
Others
Global Military Apparel Market
Others
Middle East Smart Home Market
Others
Global Personal Care Packaging Market