
 Aircraft Flight Control System Market | 2026-2036
Aircraft Flight Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Flight Control System Market Analysis
European actuator manufacturing is pivoting toward electromechanical replacements for hydraulic legacy systems. Collins Aerospace leverages deep integration with Airbus and Boeing platforms to sustain long-term supply agreements. Honeywell International Inc. anchors North American defense contracts through its advanced redundant control architectures. Safran S.A. competes in the narrowbody retrofit segment with lightweight electromechanical actuators.
An aircraft flight control system comprises the cockpit interfaces, control computers, actuators, and sensors that translate pilot commands into aerodynamic surface movements, typically operating with latency below 50 milliseconds and redundancy levels of triple or quadruple modular design. Fly-by-Wire technology dominates new commercial deliveries as geometric and hardwired systems retreat to legacy military platforms and general aviation. Civil Aviation end users generate the largest revenue pool among customer categories, while Drones represent the fastest-expanding application segment driven by urban air mobility prototypes and defense loitering munitions.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate fail-operational performance for transport category aircraft flight controls, forcing OEMs to invest in redundant computing lanes and dissimilar software architectures. The EU AI Act introduces emerging compliance obligations for autonomous flight decision algorithms, while China's CAAC aligns with NMPA-equivalent processes for indigenous narrowbody certification. Stakeholders must monitor how military export control regimes reshape supplier eligibility for dual-use actuator technologies.
Market Dynamics
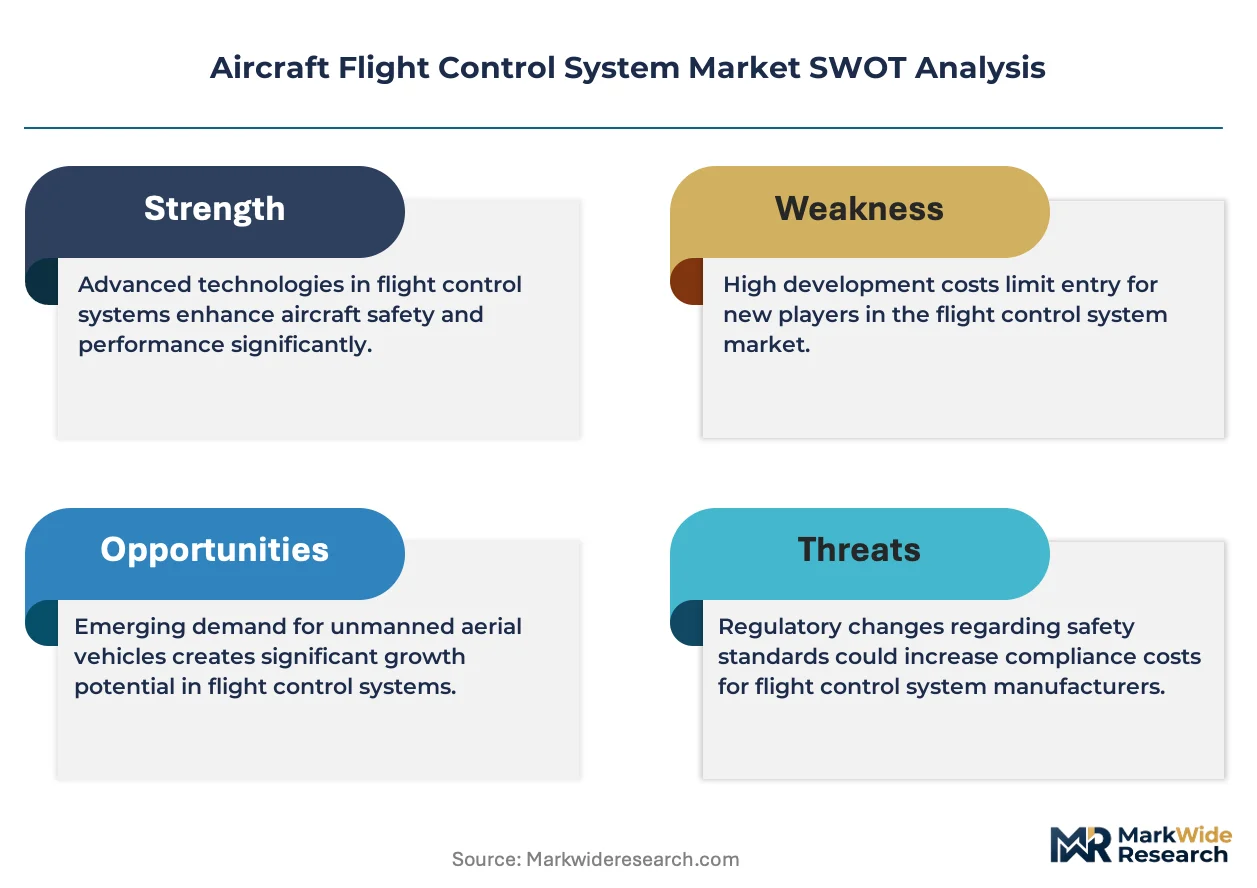
Digital fly-by-wire architectures are displacing mechanical linkages across both commercial and military platforms, driven by FAA Part 25 and EASA CS-25 mandates for fail-operational redundancy that force triple-modular computing lane investments.
Growth Catalysts
- FAA Part 25 Certification Mandates:Transport category aircraft must demonstrate fail-operational performance, compelling OEMs to adopt redundant digital architectures.
- Urban Air Mobility Prototypes:Electric vertical take-off and landing developers require lightweight electromechanical actuators for distributed propulsion control.
- NATO Defense Procurement:Allied military modernization programs prioritize digital flight control retrofits for legacy fighter and transport fleets.
Market Restraints
- Rare Earth Magnet Supply Concentration:High-performance electromechanical actuators depend on neodymium supply chains concentrated in China's processing infrastructure.
- Dual-Use Export Controls:ITAR and EU dual-use regulations restrict actuator technology transfers, fragmenting supplier eligibility for military-adjacent platforms.
- Validation Timeline Compression:Dissimilar software architecture requirements for triple-redundant systems extend certification cycles beyond typical program schedules.
Strategic Opportunities
- India Defense Indigenization:The country's PLI scheme and Make in India defense corridors create localized actuator manufacturing demand for indigenous fighter programs.
- Autonomous Flight Algorithm Compliance:The EU AI Act introduces certification pathways for machine-learning-based control decisions in unmanned systems.
- Electromechanical-Hydraulic Hybrid Convergence:Power-by-wire architectures combining electric signaling with hydraulic force generation address thermal constraints in widebody applications.
Industry Challenges
- Embedded Software Engineering Scarcity:Real-time operating system expertise for DO-178C compliant control computers remains concentrated among defense contractors.
- Legacy Platform Integration Friction:Mechanical-to-digital retrofit programs face airframe modification costs that exceed original equipment replacement economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Flight Control System Market |
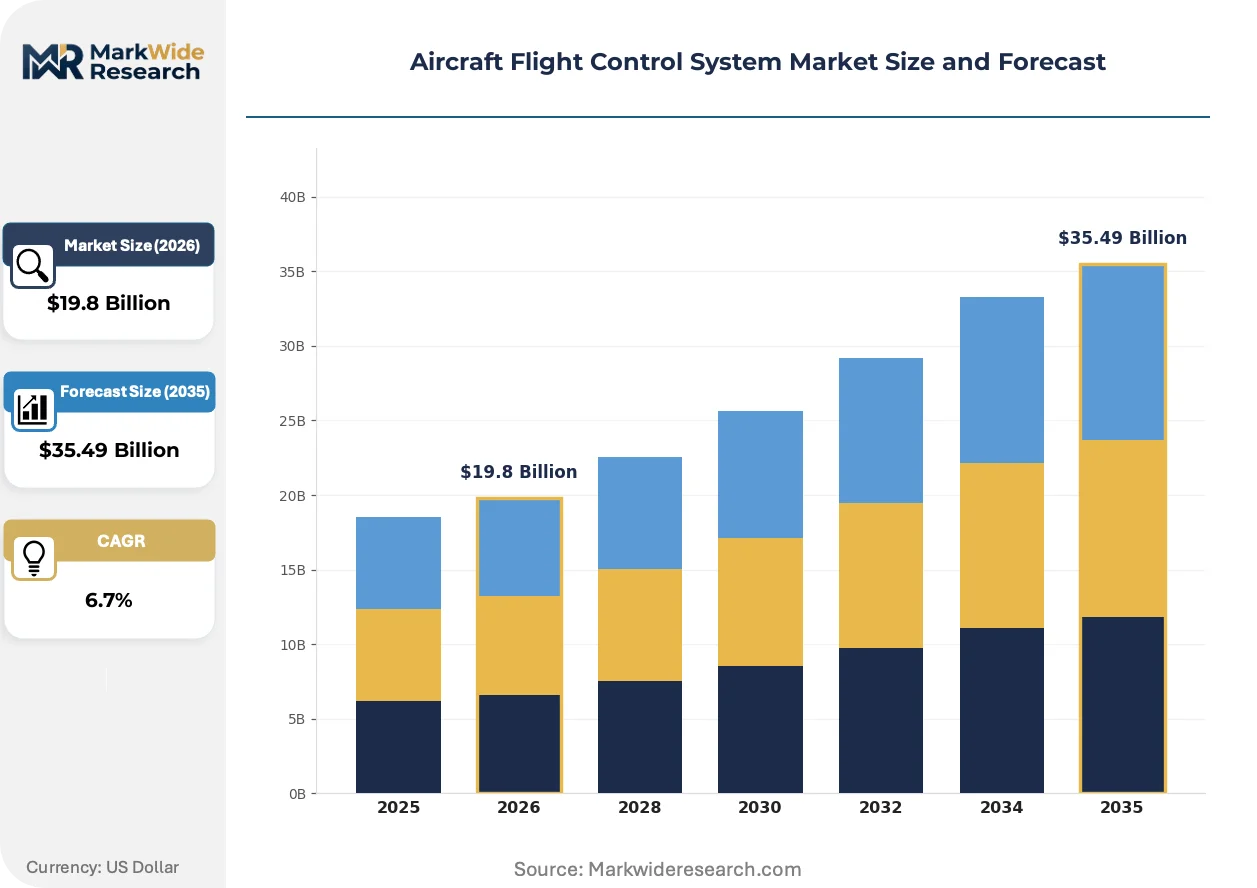
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $35.49 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fly-by-Wire, Geometric, Hardwired, Digital End User: Civil Aviation, Military, Maintenance, OEMs Application: Commercial Aircraft, Military Aircraft, Drones, Spacecraft Control Mechanism: Swashplate, Sidestick, Yoke, Control Stick |
| Companies Covered | Collins Aerospace, Thales Group, Honeywell International Inc., Woodward Inc., Parker Hannifin Corporation, BAE Systems, Moog Inc., Liebherr-International AG, Safran S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Flight Control System Market Emerging Trajectories
Control surface actuation is undergoing fundamental architecture change as electromechanical systems capture design wins previously reserved for hydraulic power. Three interconnected developments define this transition.
Electromechanical actuator technology is electrifying primary flight control surfaces on next-generation narrowbody aircraft. Boeing and Airbus procurement teams specify ball-screw and roller-screw mechanisms for aileron and elevator actuation, eliminating centralized hydraulic distribution. This shift is electrifying supply chain requirements as tier-one suppliers build captive motor winding and power electronics capabilities.
EASA CS-25 Amendment 25-157 and FAA harmonized rules now mandate enhanced upset recovery protection through envelope-limiting flight control laws. Aircraft OEMs must demonstrate predictable handling qualities through full stall and deep-stall regimes. Widebody programs in Europe and North America face the steepest compliance costs, with retrofit obligations extending to in-service fleets.
Airline technical procurement teams now bundle flight control spares with long-term power-by-the-hour maintenance contracts. Lessors and flag carriers in the Middle East and Southeast Asia negotiate actuator availability guarantees rather than discrete unit purchases. This reconfiguration compresses supplier margins while locking in decade-long service revenue streams for OEM-affiliated maintenance providers.
Aircraft Flight Control System Market Segmentation
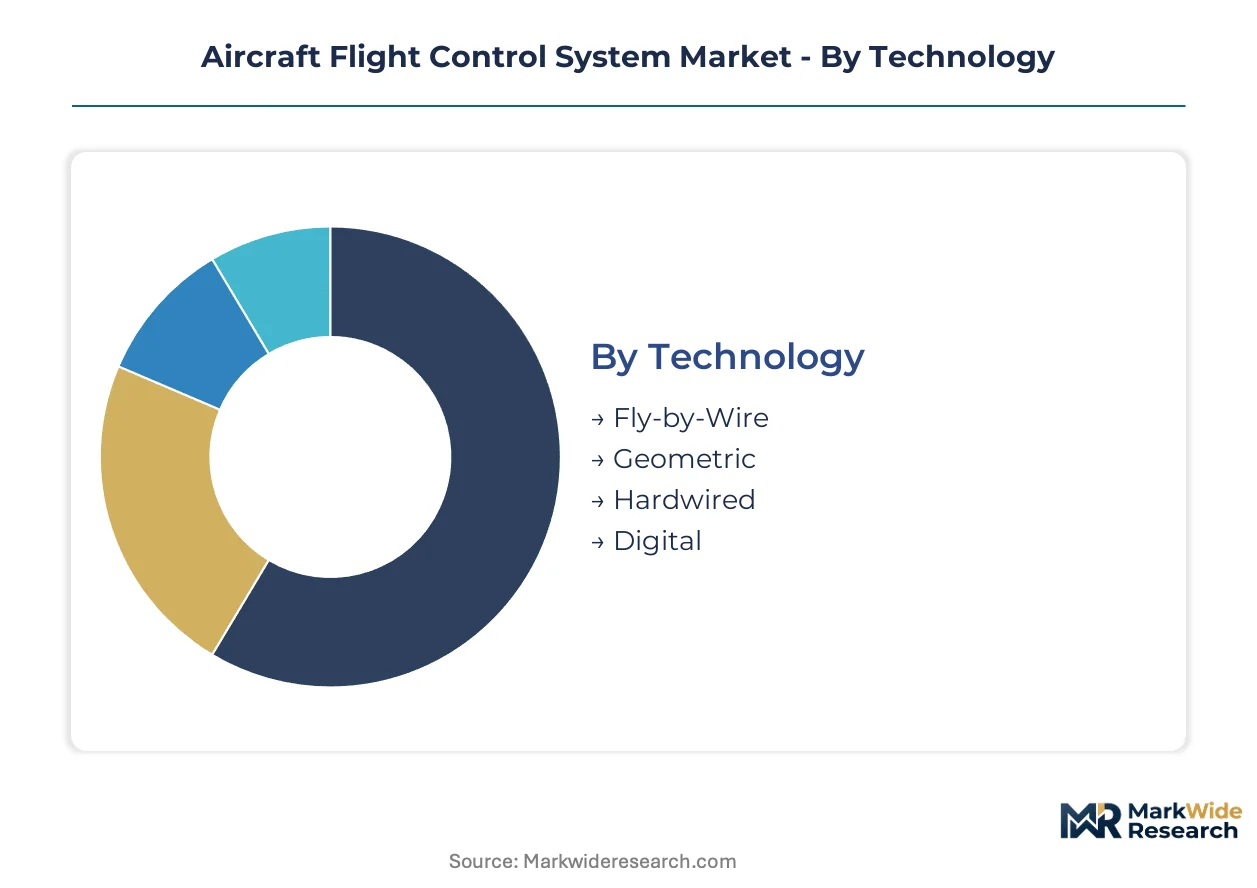
Aircraft flight control system segmentation reveals how technology maturity, procurement authority, and platform architecture dictate supplier engagement models and certification pathways. Understanding these divisions clarifies where electromechanical retrofits concentrate versus where legacy hydraulic architectures persist.
Technology:
Standalone flight control computers operate independently in general aviation retrofits, while embedded architectures dominate integrated airliner platforms requiring synchronized multi-surface coordination.
- Fly-by-Wire:Digital signal transmission replaces mechanical linkages through triple-redundant computing lanes. FAA Part 25 mandates for transport category aircraft drive adoption across Boeing and Airbus narrowbody programs.
- Geometric:Mechanical advantage linkages persist in legacy military trainer aircraft and general aviation where electromagnetic interference resilience outweighs weight penalties. Demand concentrates in Eastern European defense refurbishment contracts.
- Hardwired:Direct electrical signaling without digital intermediaries serves as backup architectures in some military platforms. Procurement runs through defense contractors with ITAR clearance for actuator integration.
- Digital:Full-authority digital control with envelope protection algorithms represents the frontier for urban air mobility developers. EASA CS-25 Amendment 25-157 compliance costs filter supplier participation.
Fly-by-Wire leads volumes today; Digital is gaining share fastest.
End User:
Procurement authority shapes contract structures, with fleet operators demanding power-by-the-hour availability guarantees while defense agencies prioritize technology transfer clauses.
- Civil Aviation:Airlines and lessors negotiate long-term actuator spares bundled with maintenance contracts. Middle Eastern flag carriers drive specifications for thermal resilience in high-ambient operating conditions.
- Military:NATO procurement offices mandate digital retrofit architectures for legacy fighter fleets. Export control compliance fragments supplier eligibility across allied defense programs.
- Maintenance:Third-party MRO providers seek aftermarket actuator refurbishment capabilities. India's Make in India defense corridors attract localized repair station investments.
- OEMs:Boeing and Airbus procurement teams specify ball-screw mechanisms for primary surface actuation. Tier-one suppliers build captive motor winding capabilities to meet electrification roadmaps.
Civil Aviation commands the largest revenue pool; Military is expanding most quickly through NATO modernization cycles.
Application:
Platform scale determines actuator force requirements, with distributed propulsion architectures in emerging segments demanding miniaturized electromechanical units.
- Commercial Aircraft:Narrowbody and widebody programs specify centralized flight control computers with remote electronics units at each surface. EASA and FAA harmonized rules for upset recovery protection extend retrofit obligations to in-service fleets.
- Military Aircraft:Fighter and transport platforms integrate fire-control and flight-control functions through unified digital buses. India's indigenous fighter programs create localized manufacturing demand under PLI incentives.
- Drones:Urban air mobility prototypes require lightweight electromechanical actuators for tilt-rotor and distributed propulsion control. The EU AI Act introduces certification pathways for autonomous decision algorithms.
- Spacecraft:Reaction control systems and re-entry vehicle aerodynamic surfaces demand radiation-hardened computing architectures. Procurement volumes remain constrained by launch frequency limitations.
Commercial Aircraft anchors current installations; Drones show the steepest expansion trajectory.
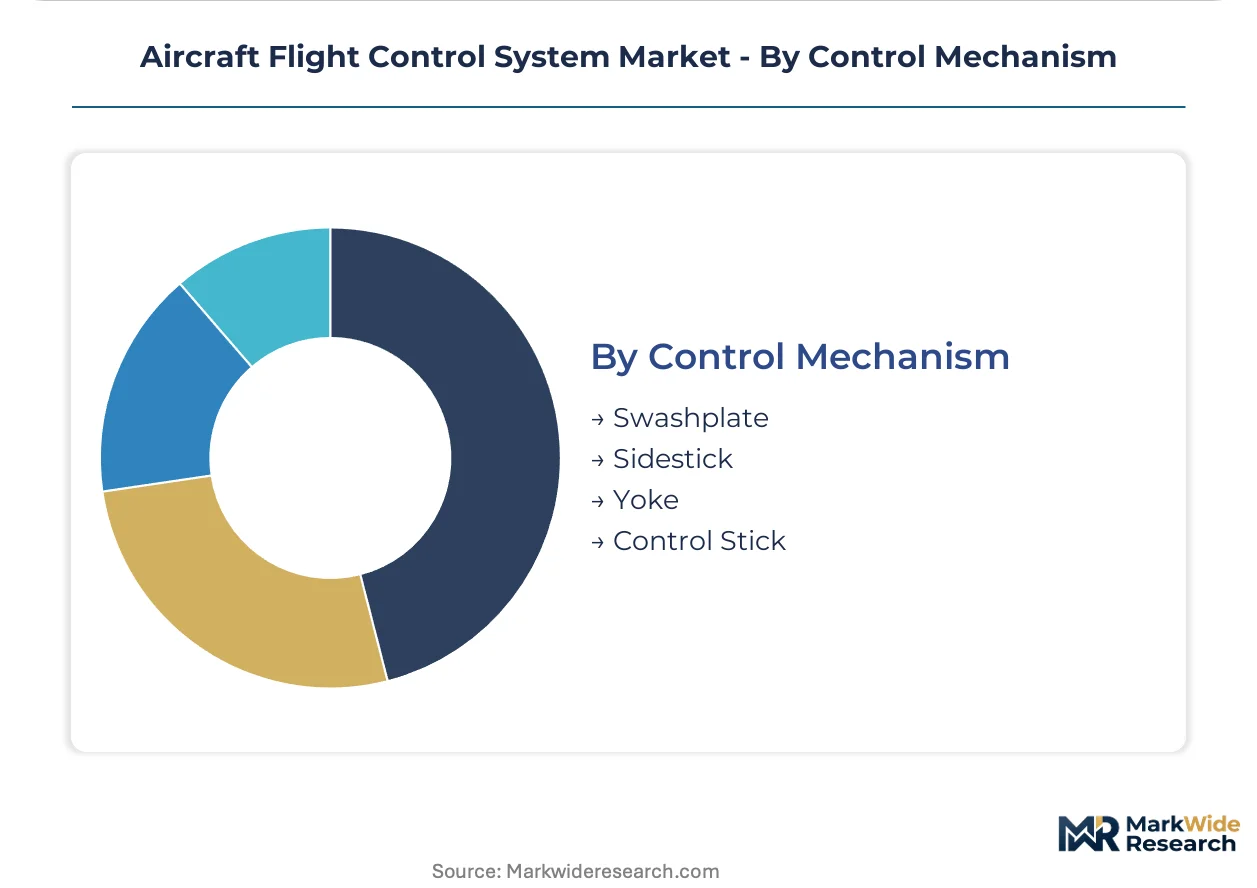
Control Mechanism:
Human-machine interface selection reflects pilot training infrastructure and emergency handling philosophy, with sidestick adoption concentrated in automated flight deck environments.
- Swashplate:Cyclic and collective control in rotorcraft demands complex mechanical or electromechanical mixing. Helicopter OEMs in the United States specify redundant hydraulic backup for primary actuation.
- Sidestick:Airbus-standard side-mounted controllers enable centralized armrest positioning and automated envelope protection. Asian-Pacific airlines with high automation adoption rates specify this configuration.
- Yoke:Boeing-preference column-mounted controls persist in pilot training pathways requiring manual trim wheel access. Legacy fleet commonality drives continued specification in certain regional markets.
- Control Stick:Center-mounted sticks dominate military fighter platforms where rapid roll rate commands require minimal hand movement. Defense procurement mandates for handling qualities standardization influence selection.
Yoke retains the largest installed base; Sidestick is climbing the fastest through new narrowbody deliveries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between FAA Part 25 mandates and EASA CS-25 amendments creates compliance-cost arbitrage, pushing electromechanical actuator assembly toward jurisdictions with streamlined dual-certification pathways. Manufacturers migrate final integration to clusters where defense procurement intersects with commercial aviation infrastructure.
United States
Defense budget allocations through the Department of Defense sustain demand for redundant digital flight control architectures in fighter and transport modernization programs. FAA certification protocols for fail-operational systems enforce triple-modular computing investments across Boeing supply chains. The Seattle-Tacoma aerospace corridor concentrates actuator integration facilities serving both commercial narrowbody and military platforms.
Germany
Luftwaffe fleet renewal drives procurement of fly-by-wire retrofits for legacy Tornado replacements under NATO interoperability standards. EASA CS-25 Amendment 25-157 mandates for upset recovery protection impose validation costs on Hamburg-based flight control computer manufacturers. The Bavarian aerospace cluster around Munich hosts specialized testing facilities for envelope-limiting control law verification.
France
Airbus procurement specifications for electromechanical primary surface actuation anchor demand in Toulouse and Nantes industrial zones. The EU AI Act introduces emerging compliance obligations for autonomous flight algorithms affecting urban air mobility developers in the Paris-Saclay deep-tech cluster. Dassault Aviation's Rafale export programs sustain military flight control production in Bordeaux.
India
Indigenous fighter programs under the Make in India defense corridor generate localized actuator manufacturing demand through PLI scheme incentives. DGFT import substitution policies for defense aerospace components redirect supply chain investments toward Bangalore and Hyderabad clusters. HAL's Tejas production line requires captive flight control system capabilities.
United Kingdom
Tempest sixth-generation fighter development consolidates flight control research in Lancashire and Bristol aerospace centers. BAE Systems integration contracts for NATO platforms sustain demand for ITAR-compliant actuator technologies. CAA alignment with EASA post-Brexit maintains certification pathway access for Farnborough-based control system suppliers.
Aircraft Flight Control System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue urban air mobility and drone control niches where certification burdens remain lighter. The vendor base concentrates among defense-anchored conglomerates with captive aerospace divisions and specialized actuator houses with electromechanical expertise. Three archetypes dominate: platform-integrated OEM affiliates, independent motion control specialists, and diversified industrial conglomerates with aerospace exposure. Competitive moves center on backward integration into motor winding and power electronics, plus long-term service contracts bundling spares with availability guarantees.
Within the platform-integrated tier, Collins Aerospace and Honeywell International Inc. exemplify archetypes leveraging deep OEM relationships for narrowbody specification lock-in. Safran S.A. occupies a position representing European electromechanical specialization for lightweight actuator applications. Thales Group anchors the avionics-integrated control computer segment where software certification capabilities create defensive moats.
| Leading Market Players |
|---|
| Collins Aerospace |
| Thales Group |
| Honeywell International Inc. |
| Woodward Inc. |
| Parker Hannifin Corporation |
| BAE Systems |
| Moog Inc. |
| Liebherr-International AG |
| Safran S.A. |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between fail-operational flight control computers and general aviation retrofits manifests in divergent pricing architectures and supplier qualification pathways. FAA Part 25 and EASA CS-25 compliance tiers command triple-modular computing premiums while uncertified actuator assemblies compete on unit economics alone.
Pricing Analysis
Distributor margins for electromechanical actuators compress under direct-to-OEM procurement consolidation by Boeing and Airbus. Pricing stratifies across DO-178C certified control computers, ITAR-restricted military architectures, and commercial-off-the-shelf drone components. Cost compression in widebody actuator retrofits intensifies as envelope-limiting control law validation extends certification cycles. Defense procurement offices exhibit lowest price sensitivity; urban air mobility developers face acute capital constraints.
Supply Chain Analysis
India's PLI scheme and domestic-content mandates for defense aerospace components are redirecting actuator winding and power electronics investments toward Bangalore and Hyderabad clusters. Rare earth magnet processing draws from China's neodymium infrastructure; precision ball-screw manufacturing rests on German and Japanese machine tool capabilities. Single-source vulnerability concentrates in radiation-hardened semiconductor foundries. Distribution runs through tier-one system integrators holding captive Boeing and Airbus supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aircraft flight control system market compounds steadily as regulatory mandates for fail-operational redundancy perpetuate replacement cycles across commercial and military fleets.
For Market Incumbents: Cement specification lock-in through backward integration into motor winding and power electronics captive production. Deepen DO-178C software certification capabilities as envelope-limiting control law mandates expand validation burdens. Threat: emerging electromechanical specialists from India's defense corridors eroding aftermarket actuator refurbishment margins. For New Entrants and Emerging Players: Enter via urban air mobility distributed propulsion control where EASA CS-25 Amendment 25-157 compliance costs filter incumbent participation. White-space targets include lightweight tilt-rotor actuators and autonomous flight algorithm certification under EU AI Act pathways. Go-to-market: direct engineering partnerships with eVTOL developers bypassing traditional aerospace distribution. For Investors and Strategic Acquirers: Consolidation pressure builds where ITAR-compliant actuator technologies face dual-use export control fragmentation limiting supplier eligibility. Long-term viability favors platforms with embedded software certification moats and defense procurement anchoring. Acquisition target: mid-cap electromechanical specialists with captive motor winding and EASA/FAA dual-certification track records. Signal to watch: NATO defense procurement acceleration for legacy fleet digital retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor Winding | Captive supply of neodymium actuator motors insulates Collins Aerospace and Honeywell from rare earth magnet volatility. |
| DO-178C Software Certification Investment | EASA CS-25 Amendment 25-157 envelope-limiting mandates expand addressable market for Thales Group's avionics-integrated control computers. |
| Localized Manufacturing Under PLI Incentives | India's defense corridor investments position Safran S.A. and BAE Systems for HAL Tejas and indigenous fighter program sourcing. |
| Power-by-the-Hour Service Contracts | Long-term actuator availability guarantees lock Middle Eastern flag carriers into decade-long revenue streams with OEM-affiliated maintenance providers. |
| EU AI Act Compliance Pathway Development | Machine-learning-based autonomous flight algorithm certification creates first-mover advantage for urban air mobility control system suppliers. |
Methodological Framework
Multiple input streams — flight control system procurement officers at tier-one suppliers, FAA certification engineers, EASA airworthiness authorities, and defense acquisition program managers — were reconciled against secondary validation from FAA Part 25 airworthiness directives, EASA CS-25 amendment filings, NATO defense procurement databases, and SEC 10-K disclosures from aerospace conglomerates. Bottom-up actuator unit economics and top-down fleet replacement cycle modeling were triangulated to cross-validate market sizing.
Data-stream reconciliation across the projection horizon employed technology-acceptance curves for fly-by-wire penetration, platform-specific content-per-aircraft assumptions, and defense budget allocation trajectories. Segmentation dimensions modeled encompass technology architecture, end-user procurement authority, application platform scale, and regional regulatory cluster. CAGRs were derived from fitted growth curves against historical delivery data and announced OEM backlog commitments. Industry-specific forecast inputs included announced narrowbody production rate adjustments and NATO fleet modernization schedules.
The model holds under stable regulatory certification timelines and intact rare earth magnet supply chains; deviation in ITAR export control enforcement or neodymium processing disruptions would shift replacement cycle assumptions. Forecasts reflect documented base-case assumptions regarding EASA-FAA harmonization progress and defense procurement continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Asia-Pacific General Aviation Market
Aircraft
Aviation Crew Management System Market
Aircraft
Aircraft Wheels Brakes Market
Aircraft
Tandem Rotor Helicopter Market
Aircraft
Global Ultralight and Light Aircraft Market
Aircraft
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Electric VTOL (Evtol) Aircraft Market
Aircraft
Commercial Helicopter Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
America Freighter Aircraft Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
North America Military Helicopters Market
Aircraft
Evtol (Electric Vertical Takeoff and Landing) Airplane Market