
 Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market | 2026-2036
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market Insights
The FAA's updated airworthiness directives on electromagnetic transparency is restructuring the cost-of-entry calculus for new radome suppliers. Honeywell Aerospace leverages its avionics integration depth to sustain long-term contracts with major airframers. Collins Aerospace anchors its position through proprietary composite manufacturing processes that reduce signal attenuation across Ka-band frequencies. General Dynamics Mission Systems competes primarily on military certification breadth, dominating classified platform integrations.
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems are electromagnetic-transparent enclosures, typically fabricated from quartz-fiber-reinforced cyanate ester or ceramic matrix composites, designed to protect phased-array antennas while maintaining insertion loss below 0.5 dB across 2–300 GHz operational windows. These structures enable uninterrupted satellite communications and future terrestrial 6G backhaul for military and commercial aircraft operating at Mach 0.85+ speeds. Conformal radomes represent the fastest-growing product category as UAV platforms and stealth airframes drive demand for aerodynamically integrated antenna housings rather than protruding fixed installations. The broadband technology segment commands the deepest margin pools due to the technical complexity of achieving consistent dielectric performance across widely separated frequency allocations. Military communications applications lead absolute volume, though satellite data relay for commercial aviation is narrowing the gap as airlines pursue consistent connectivity over polar routes.
The FAA's electromagnetic interference standards and the EU's CE marking requirements for aeronautical equipment collectively shape product development timelines and testing expenditures for radome manufacturers seeking multi-jurisdiction approvals. The Department of Defense's MIL-STD-810 environmental testing protocols further constrain material selection and design validation cycles for defense-facing suppliers. Stakeholders must monitor spectrum allocation decisions by the FCC and equivalent national bodies, as 6G frequency designations will determine the next generation of radome dielectric specifications and antenna integration architectures.
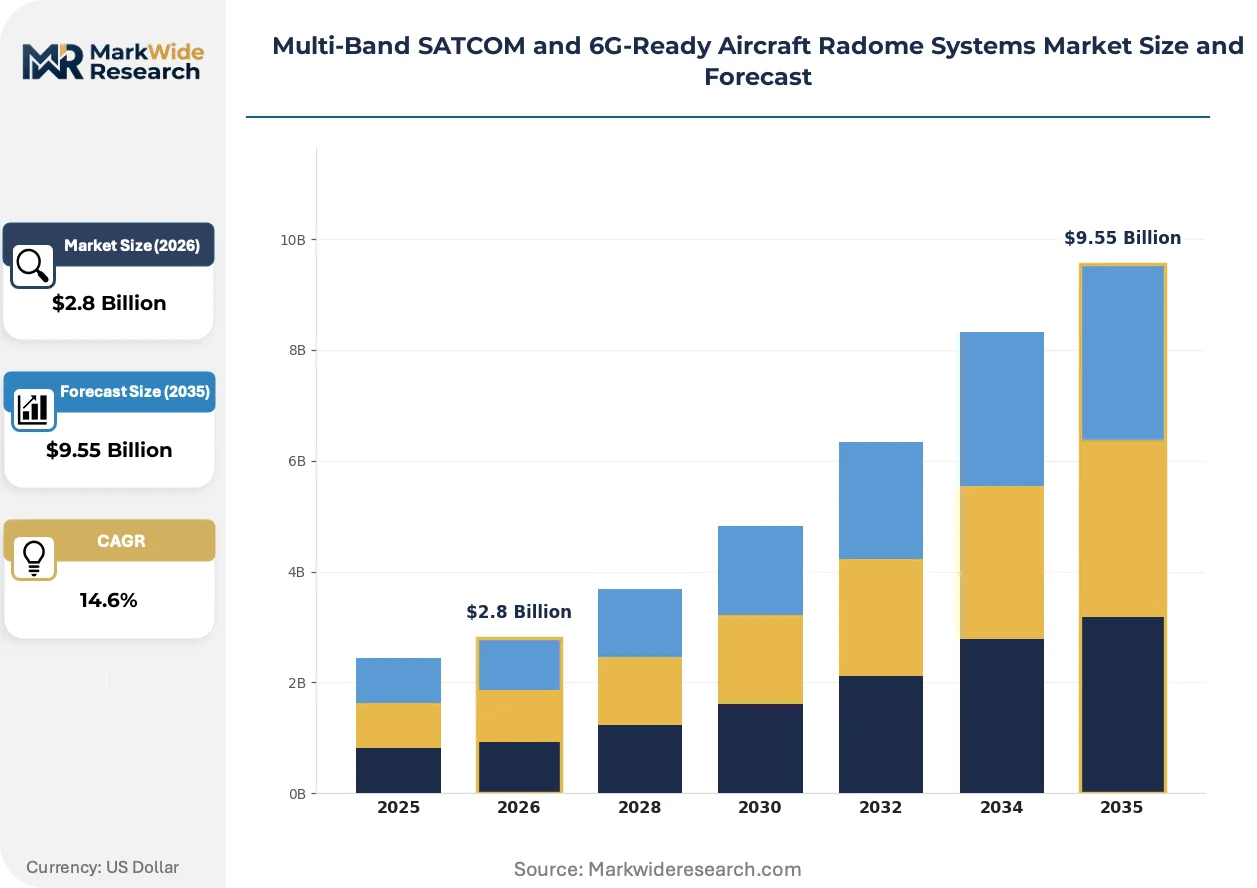
Market Dynamics
The FAA's electromagnetic transparency mandates are compressing supplier qualification timelines while simultaneously expanding the addressable market for certified composite radome manufacturers. This regulatory pressure is restructuring competitive entry barriers around material science capabilities and testing infrastructure ownership.
Growth Catalysts
- Ka-band frequency proliferation:Military and commercial aviation operators are migrating SATCOM loads to higher frequencies, requiring radomes with dielectric constants below 3.5 across 26.5–40 GHz windows.
- EU Green Deal aviation decarbonization targets:The European Commission's emissions reduction framework is accelerating lightweight composite adoption, as every kilogram of radome weight reduction translates to fuel savings over aircraft lifecycle.
- Conformal antenna integration:Stealth airframe programs and UAV platforms are eliminating protruding radome geometries in favor of skin-integrated solutions that preserve aerodynamic profiles.
Market Restraints
- Quartz fiber supply concentration:High-purity quartz precursor production clusters in three manufacturing regions, creating input vulnerability for cyanate ester composite fabricators.
- MIL-STD-810 validation costs:Department of Defense environmental testing protocols impose six-figure certification expenditures per radome design variant, freezing out capital-constrained entrants.
- Metamaterial substitution threat:Frequency-selective surface technologies are emerging as alternative electromagnetic transparency solutions for narrowband military applications.
Strategic Opportunities
- India defense modernization:The country's indigenous fighter programs and UAV procurements under the Defence Acquisition Procedure are creating first-mover advantages for radome suppliers establishing local testing partnerships.
- 6G terahertz backhaul:Convergence of satellite communications and terrestrial 6G networks above 100 GHz is opening specification windows for ceramic matrix composite architectures.
- FCC spectrum auction outcomes:Pending millimeter-wave designations for aeronautical mobile services will mandate new radome dielectric specifications, rewarding pre-positioned R&D investments.
Industry Challenges
- Multiphysics simulation talent scarcity:Computational electromagnetics and structural finite element analysis convergence requires hybrid skill sets absent from conventional aerospace engineering pipelines.
- Legacy platform retrofit complexity:Existing aircraft radome attachment geometries and antenna footprints constrain upgrade paths without airframe modification.
- Cross-certification timeline fragmentation:Divergent FAA, EASA, and military authority validation cycles force parallel testing tracks that extend product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Radomes, Conformal Radomes, Deployable Radomes, Aerodynamic Radomes, Articulated Radomes Technology: Microwave Absorptive, Broadband, Multi-Band Frequency, Composite Materials, Smart Materials Application: Military Communications, Commercial Aviation, Satellite Data Relay, UAV Communication, Space Missions End User: Aircraft Manufacturers, Satellite Operators, Defense Contractors, Aerospace Integrators |
| Companies Covered | General Dynamics Mission Systems, Honeywell Aerospace, Collins Aerospace, Cobham, Spirit AeroSystems, Meggitt, GKN Aerospace, FACC, Kaman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market Trends and Innovations
Computational materials discovery is compressing radome development cycles from years to months, while regulatory harmonization efforts are beginning to consolidate multi-jurisdiction approval pathways. These forces are converging to reshape how manufacturers prioritize R&D investments and testing infrastructure.
Additive manufacturing of ceramic matrix composites is automating the production of geometrically complex radome geometries that were previously impossible to mold or machine. Defense prime contractors are adopting these processes for low-rate initial production of conformal UAV radomes. This automation is compressing lead times for custom antenna integration while reducing scrap rates in high-value ceramic precursor materials.
The FAA's updated airworthiness directives on electromagnetic transparency are mandating insertion loss documentation across operational temperature ranges for all new radome certifications. This policy is forcing manufacturers to expand thermal testing capabilities and revise material qualification protocols. Commercial aviation suppliers serving United States-based airframers are responding by integrating environmental chambers into production lines rather than outsourcing validation.
Airline procurement departments are consolidating SATCOM radome purchases under fleet-wide connectivity upgrade contracts rather than acquiring components separately from antenna and modem vendors. This bundling is disintermediating traditional radome distributors and favoring system integrators with airframer direct relationships. The pattern is most visible among United States legacy carriers pursuing polar route connectivity standardization across widebody fleets.
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market Segmentation
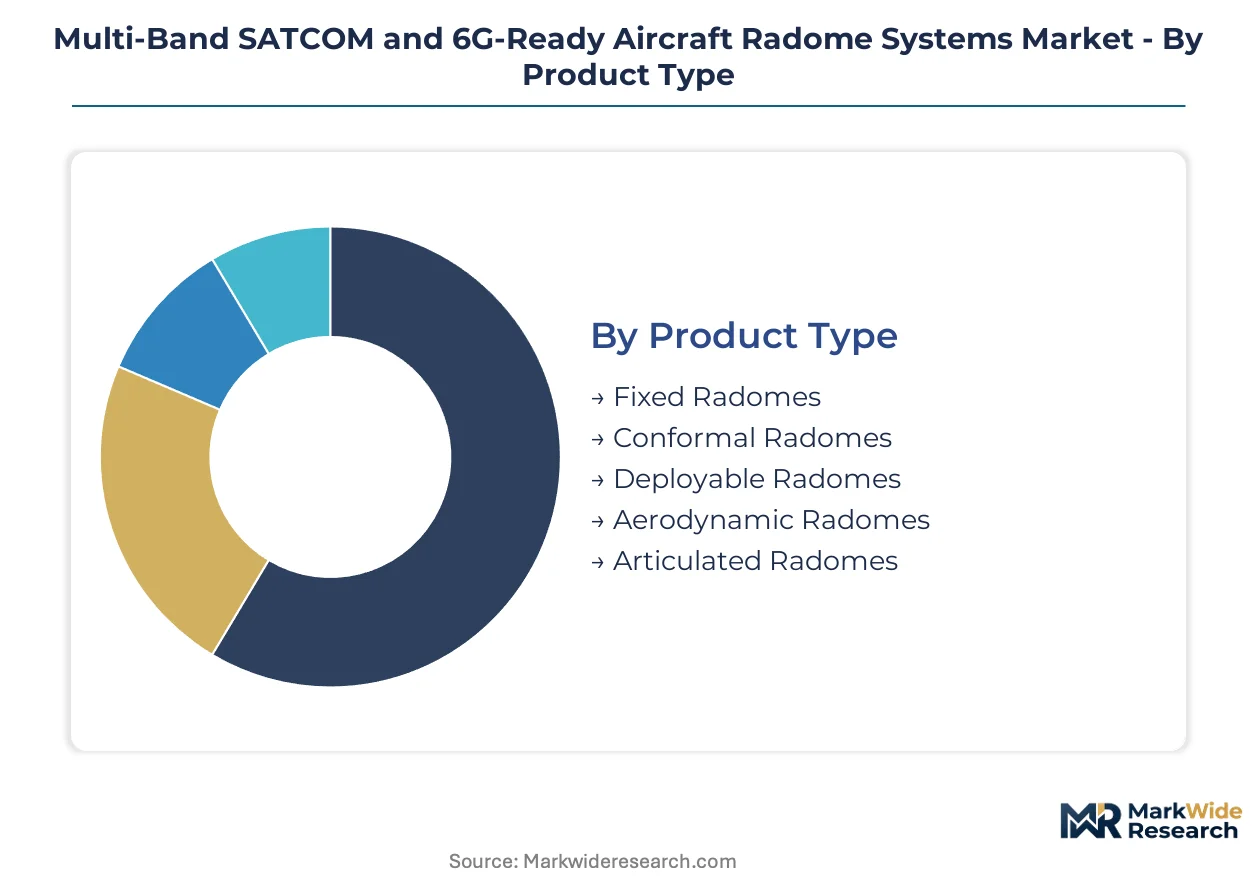
Radome procurement patterns diverge sharply across product geometries and frequency-handling specifications. Military platform integrators prioritize electromagnetic performance under MIL-STD-810 stress conditions, while commercial carriers optimize for fuel-burn reduction through lightweight composite architectures.
Product Type:
Structural integration geometry determines aerodynamic penalty and antenna coverage trade-offs for each airframe application.
- Fixed Radomes:Traditional nose-mounted or dorsal installations using quartz-fiber-reinforced cyanate ester shells. Demand concentrates in United States-based commercial aviation retrofit programs where airlines seek polar route SATCOM continuity without airframe modification.
- Conformal Radomes:Skin-integrated composite panels that eliminate protrusion drag. Stealth airframe programs and next-generation UAV platforms in NATO member states are driving specification intensification for these geometries.
- Deployable Radomes:Mechanically actuated enclosures for intermittent SATCOM use. Specialized satellite data relay aircraft in Australia and Canada employ these for on-demand connectivity.
- Aerodynamic Radomes:Streamlined profiles optimized for Mach 0.85+ cruise regimes. Business jet manufacturers in Switzerland and Brazil specify these for reduced fuel consumption on transoceanic routes.
- Articulated Radomes:Gimbal-mounted assemblies enabling dynamic antenna pointing. Space mission support aircraft operated by national space agencies require these for tracking fast-moving orbital assets.
Mature deployment sits with Fixed Radomes. Newer deployment is concentrated in Conformal Radomes.
Technology:
Dielectric engineering sophistication separates premium suppliers from commodity fabricators in certification-intensive procurement.
- Microwave Absorptive:Ferrite-loaded composites that reduce radar cross-section through controlled energy dissipation. Military low-observable platforms in the United Kingdom and France mandate these for signature management.
- Broadband:Ceramic matrix architectures maintaining insertion loss below 0.5 dB across 2–300 GHz. Ka-band proliferation in United States military SATCOM modernization programs drives specification intensity here.
- Multi-Band Frequency:Segmented dielectric structures with zone-optimized constants. Dual-use aircraft serving both military and commercial roles in Germany and Japan favor these for operational flexibility.
- Composite Materials:Quartz-fiber and aramid-reinforced cyanate ester systems. Volume production for commercial aviation concentrates procurement in this category due to established supply chains.
- Smart Materials:Adaptive dielectrics with electrically tunable properties. Experimental 6G terahertz backhaul trials in South Korea and Finland are validating these for future spectrum agility.
Composite Materials anchor current procurement volumes. Smart Materials are climbing the fastest as 6G specification windows open.
Application:
Operational environment severity dictates material qualification depth and testing expenditure allocation.
- Military Communications:Hardened enclosures for tactical data links and strategic SATCOM. Classified platform integrations in the United States dominate absolute demand and certification complexity.
- Commercial Aviation:Passenger connectivity and cockpit datalink radomes. United States legacy carriers pursuing fleet-wide standardization are consolidating procurement under system integrator contracts.
- Satellite Data Relay:High-gain antenna protection for earth observation downlink. Government-operated relay aircraft in Canada and Australia maintain specialized requirements.
- UAV Communication:Lightweight conformal solutions for extended endurance platforms. India's indigenous drone programs under Defence Acquisition Procedure are emerging as volume drivers.
- Space Missions:Extreme environment radomes for atmospheric reentry and launch support. National space agency aircraft in France and Japan require thermal shock-resistant ceramic architectures.
Military Communications absorbs the deepest R&D investment. UAV Communication is gaining share fastest as platform proliferation accelerates.
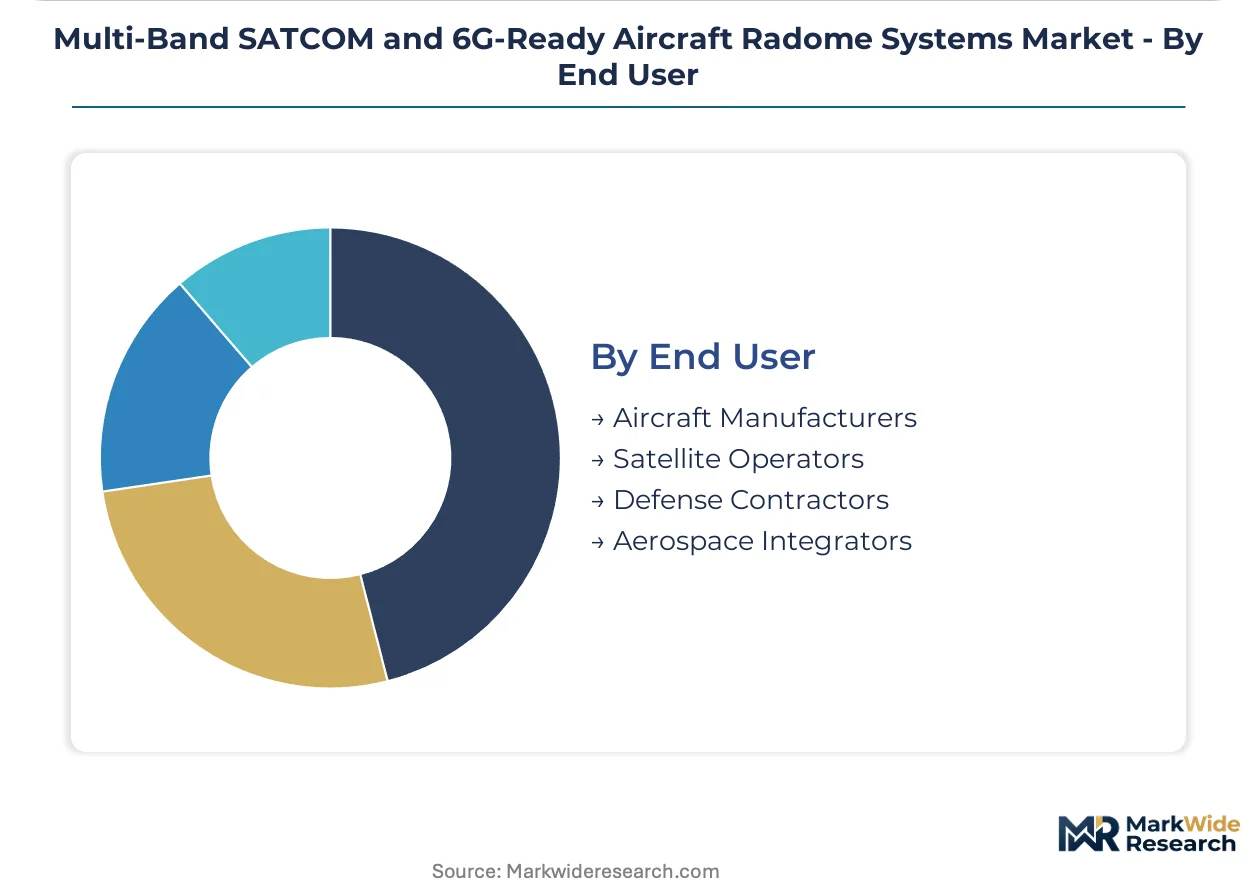
End User:
Procurement authority location shapes technical specification development and certification pathway selection.
- Aircraft Manufacturers:Airframer-direct radome integration during original equipment production. Boeing and Airbus supply chains in the United States and France specify these for new-build widebodies.
- Satellite Operators:Specialized relay aircraft modification programs. SES and Intelsat fleet upgrades in Luxembourg and the United States concentrate demand here.
- Defense Contractors:Platform-integrated procurement for classified programs. Lockheed Martin and BAE Systems programs in the United States and United Kingdom dominate military volume.
- Aerospace Integrators:Third-party modification and MRO radome installation. L3Harris and Thales service operations across NATO member states handle retrofit demand.
Defense Contractors command the longest contract tenures. Aircraft Manufacturers are expanding specification influence through design-phase integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States military SATCOM modernization programs and commercial 6G trials concentrate demand in North American aerospace clusters. European defense procurement and decarbonization mandates shape secondary demand centers. Asian indigenous fighter and UAV programs are emerging as volume growth poles.
United States
Defense contractors in Texas and California drive classified platform integrations for next-generation aerial systems. The FAA's updated airworthiness directives on electromagnetic transparency mandate expanded composite material certifications for all new radome designs. Greater Seattle's aerospace corridor hosts testing partnerships between airframers and SATCOM integrators pursuing polar route connectivity standardization.
United Kingdom
Stealth airframe programs and low-observable platform requirements sustain demand for microwave absorptive radome architectures. Ministry of Defence procurement frameworks prioritize MIL-STD-810 environmental testing protocols for tactical data link enclosures. The South West England aerospace cluster around Bristol maintains specialized composite manufacturing for military antenna integration.
Germany
Dual-use aircraft serving military and commercial roles favor multi-band frequency radome configurations for operational flexibility. The EU Green Deal aviation decarbonization framework accelerates lightweight composite adoption across Bundeswehr and Lufthansa procurement pipelines. Bavaria's Munich-Augsburg corridor concentrates radome R&D for ceramic matrix dielectric engineering.
India
Indigenous fighter programs and UAV procurements under the Defence Acquisition Procedure create first-mover advantages for suppliers establishing local testing partnerships. The country's national aerospace regulator mandates BIS certification alignment with MIL-STD-810 stress conditions for defense-facing imports. Bangalore's aerospace manufacturing cluster hosts emerging partnerships between HAL and foreign radome specialists.
South Korea
Experimental 6G terahertz backhaul trials validate smart material radomes with electrically tunable dielectric properties. The national spectrum authority's pending millimeter-wave designations for aeronautical mobile services will mandate new certification protocols. Seoul's defense electronics corridor concentrates KF-21 fighter platform integration programs requiring conformal antenna housings.
Multi-Band SATCOM and 6G-Ready Aircraft Radome Systems Market Competitive Landscape
United States producers anchor the premium tier through defense certification depth; European specialists hold positions in lightweight commercial aviation architectures. The vendor base stratifies across three tiers: avionics-integrated system houses, composite manufacturing specialists, and platform-embedded defense primes. Strategic moves concentrate on airframer direct contracting consolidation and captive testing infrastructure expansion.
Among United States-based contractors, General Dynamics Mission Systems, Honeywell Aerospace, and Collins Aerospace exemplify the dominant competitive archetypes. General Dynamics Mission Systems occupies a position within classified platform integration workflows. Honeywell Aerospace represents the avionics-integrated system house model with airframer direct relationships. Collins Aerospace anchors the composite manufacturing specialist tier through proprietary dielectric process control. These three entities collectively illustrate how certification breadth, integration depth, and material science capabilities define sustainable positioning.
| Leading Market Players |
|---|
| General Dynamics Mission Systems |
| Honeywell Aerospace |
| Collins Aerospace |
| Cobham |
| Spirit AeroSystems |
| Meggitt |
| GKN Aerospace |
| FACC |
| Kaman Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between MIL-STD-810 hardened platforms and commercial aviation retrofit programs manifests in both pricing power and supply chain configurations. Premium-tier radome suppliers capture sustained margins through captive testing infrastructure ownership, while commodity fabricators face cost compression from consolidated airline procurement.
Pricing Analysis
Volume concentrates in composite material radomes for commercial aviation, while margin pools deepen in broadband ceramic matrix architectures for military SATCOM. Price differentiation rests on certification grade—FAA airworthiness directives versus MIL-STD-810 environmental protocols—and dielectric performance across Ka-band windows. Pricing pressure stems from airline fleet-wide connectivity bundling that disintermediates component distributors. Commercial carriers exhibit highest price sensitivity, whereas classified platform integrators prioritize electromagnetic performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with high-purity quartz fiber precursor production clustering in the United States, Germany, and Japan. Cyanate ester resin systems and ceramic matrix composite feedstocks draw from specialized chemical manufacturers concentrated in these same jurisdictions. Supply chain risk centers on tariff exposure for defense-critical materials subject to export control classifications. Distribution runs through airframer-direct channels for original equipment production and aerospace integrator networks for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics define this market, with MIL-STD-810 validation infrastructure scarcity propping pricing for certified defense-facing suppliers.
For Market Incumbents: Anchor positioning through backward integration into quartz fiber precursor supply and expansion of thermal testing chamber capacity. Metamaterial substitution threats in narrowband military applications demand accelerated R&D in ceramic matrix dielectric engineering. Certification investment remains the critical lever for sustaining long-term airframer-direct contracts. For New Entrants and Emerging Players: India's indigenous UAV programs under the Defence Acquisition Procedure represent the most penetrable buyer archetype for establishing local testing partnerships. Experimental 6G terahertz trials in South Korea and Finland offer specification windows for smart material radome validation. A go-to-market angle through aerospace integrator subcontracting bypasses direct airframer qualification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with composite manufacturing specialists possessing proprietary dielectric process control given FCC spectrum auction catalysts. Long-term viability over the next decade hinges on positioning for 6G frequency designation outcomes. The signal to watch is BIS certification alignment progress for foreign suppliers entering Indian defense procurement pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Testing Infrastructure Expansion | MIL-STD-810 environmental chamber ownership locks in defense contract access against capital-constrained rivals. |
| Local Testing Partnership Formation | Indian BIS certification alignment under Defence Acquisition Procedure opens indigenous fighter and UAV procurement channels. |
| Ceramic Matrix Composite R&D Scale-Up | Broadband dielectric architectures position suppliers for Ka-band military SATCOM modernization program awards. |
| Airframer-Direct Contract Consolidation | Fleet-wide connectivity bundling by United States legacy carriers disintermediates traditional distribution intermediaries. |
| Smart Material Validation Investment | Electrically tunable dielectric development captures 6G terahertz backhaul specification windows in South Korea and Finland. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with radome engineering directors, defense procurement officers, airline fleet managers, and FAA certification specialists combined with FAA airworthiness directive documentation, Department of Defense contract announcements, and EASA technical reports. Bottom-up segment sizing and top-down macro validation triangulated volume and value estimates.
Data-stream reconciliation across product geometry, frequency-handling specification, and end-use application dimensions shaped the analytical framework. Modeled segments spanned fixed versus conformal radome architectures, broadband versus multi-band frequency technologies, and military communications versus commercial aviation applications. CAGRs derived from regression analysis against defense modernization budget trajectories and airline connectivity upgrade cycles, with dielectric constant performance thresholds and composite material adoption curves as industry-specific forecast inputs.
Revisions become necessary when FCC spectrum allocation decisions, EU Green Deal aviation decarbonization mandate accelerations, or quartz fiber supply disruptions materialize. Forecasts reflect documented assumptions about certification timeline standardization and 6G frequency designation timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Heavy-Lift Helicopter Market
Aircraft
Aviation Market
Aircraft
Aircraft Seals Market
Aircraft
Europe Helicopters Market
Aircraft
Aircraft Leasing Market
Aircraft
United States Aerospace and Defense Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Crashworthy Aircraft Seats Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Aerospace Winglet System Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Aircraft Lavatory System Market
Aircraft
Middle East and Africa Military Helicopters Market
Aircraft
Aircraft Wheels Market
Aircraft
Commercial Aircraft Wing Market
Aircraft
Civil Helicopter Market