
 Commercial Helicopter Market | 2026-2036
Commercial Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Helicopter Market Intelligence
Aftermarket service revenue is fragmenting across OEM-controlled networks and independent maintenance, repair, and overhaul providers. Airbus Helicopters leverages its global parts distribution system to sustain recurring revenue streams from legacy fleets. Leonardo S.p.A. competes through specialized military-to-civilian conversion programs that extend platform service lives. Bell Textron Inc. anchors its position in the light-twin segment through channel control over certified training academies.
A commercial helicopter is a rotary-wing aircraft certified under civil aviation regulations for revenue-generating operations, typically featuring turboshaft engines delivering 500 to 2,000 shaft horsepower and main rotor diameters spanning 35 to 80 feet depending on payload class. These platforms serve industrial roles including personnel transport to offshore energy installations, emergency medical evacuation, and aerial fire suppression where runway-independent vertical flight is operationally essential. Light helicopters dominate unit shipments across tourism and flight training applications where acquisition cost sensitivity shapes procurement decisions. Heavy helicopters command disproportionate value share in offshore oil-and-gas crew change missions requiring 12-plus passenger capacity and extended over-water endurance. Multi-rotor configurations are gaining engineering attention for unmanned cargo platforms, though manned commercial operations remain concentrated on single-main-rotor designs with anti-torque tail rotors.
FAA Part 27 and Part 29 airworthiness standards govern type certification in the United States, while EASA CS-27 and CS-29 establish parallel requirements across European Union member states, with both frameworks intensifying focus on crash-resistant fuel systems and bird-strike tolerance. The EU Green Deal and associated Sustainable Aviation Fuel mandates are pressuring operators to evaluate turbine engine retrofit pathways and hybrid-electric propulsion alternatives. Stakeholders must monitor certification timeline compression for advanced air mobility entrants that could redraw competitive boundaries between traditional helicopter manufacturers and electrically propelled vertical-lift startups.
Market Dynamics
Hybrid-electric propulsion architectures are compressing certification timelines and forcing incumbents to restructure R&D allocation across legacy turboshaft programs. FAA Part 33 engine standards and EASA CS-E requirements are tightening emissions benchmarks that legacy turbine designs struggle to meet without fundamental airframe redesign.
Growth Catalysts
- Urban air mobility infrastructure:Vertiport construction in the United States and Germany is creating dedicated demand corridors for electric vertical-lift platforms. Municipal zoning reforms in Dallas and Los Angeles are accelerating site approvals.
- Sustainable Aviation Fuel mandates:The EU Green Deal is compelling offshore operators to blend SAF into turbine fuel pools. Refinery capacity expansion in Rotterdam is improving supply security for North Sea logistics fleets.
- Helicopter Emergency Medical Services fleet renewal:Aging single-engine platforms are reaching hour limits across Italian and Spanish regions. Hospital networks are consolidating procurement to secure volume pricing on twin-engine replacements.
Market Restraints
- Turboshaft engine supply concentration:Safran and Pratt & Whitney Canada control critical powerplant output for light and medium segments. Geopolitical friction risks disrupting just-in-time delivery to final assembly lines.
- Crash-resistant fuel system retrofit costs:FAA AD 2016-17-11 and EASA AD 2016-0175-E impose structural modifications on pre-1994 airframes. Compliance expenses often exceed residual aircraft value for aging light singles.
- Fixed-wing air ambulance substitution:Pilatus PC-24 and Beechcraft King Air platforms are capturing longer-range medical evacuation missions. Pressurized cabin performance advantages are displacing rotorcraft on inter-hospital transfers.
Strategic Opportunities
- Unmanned cargo in maritime logistics:Norwegian offshore operators are piloting multi-rotor platforms for deck-to-platform supply runs. Autonomous flight rules under EASA SAIL II are enabling beyond-visual-line-of-sight trials.
- Military-to-civilian conversion programs:Surplus UH-60 and Mi-17 airframes are entering civil registers through supplemental type certificates. Firefighting tanker modifications are extending airframe economic life.
- Digital predictive maintenance:Health and usage monitoring systems are creating aftermarket revenue streams independent of flight hours. Airbus Helicopters' Skywise platform is conditioning operator expectations for real-time component tracking.
Industry Challenges
- Airframe and powerplant mechanic shortages:FAA-certified A&P schools are producing insufficient graduates to replace retiring technicians. Specialized turboshaft repair skills are concentrating at OEM-affiliated training centers.
- Certification timeline compression for novel propulsion:FAA Part 23 rewrite and EASA SC-VTOL are creating parallel compliance pathways. Applicants face uncertainty on which framework minimizes time-to-market for hybrid architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Helicopter Market |
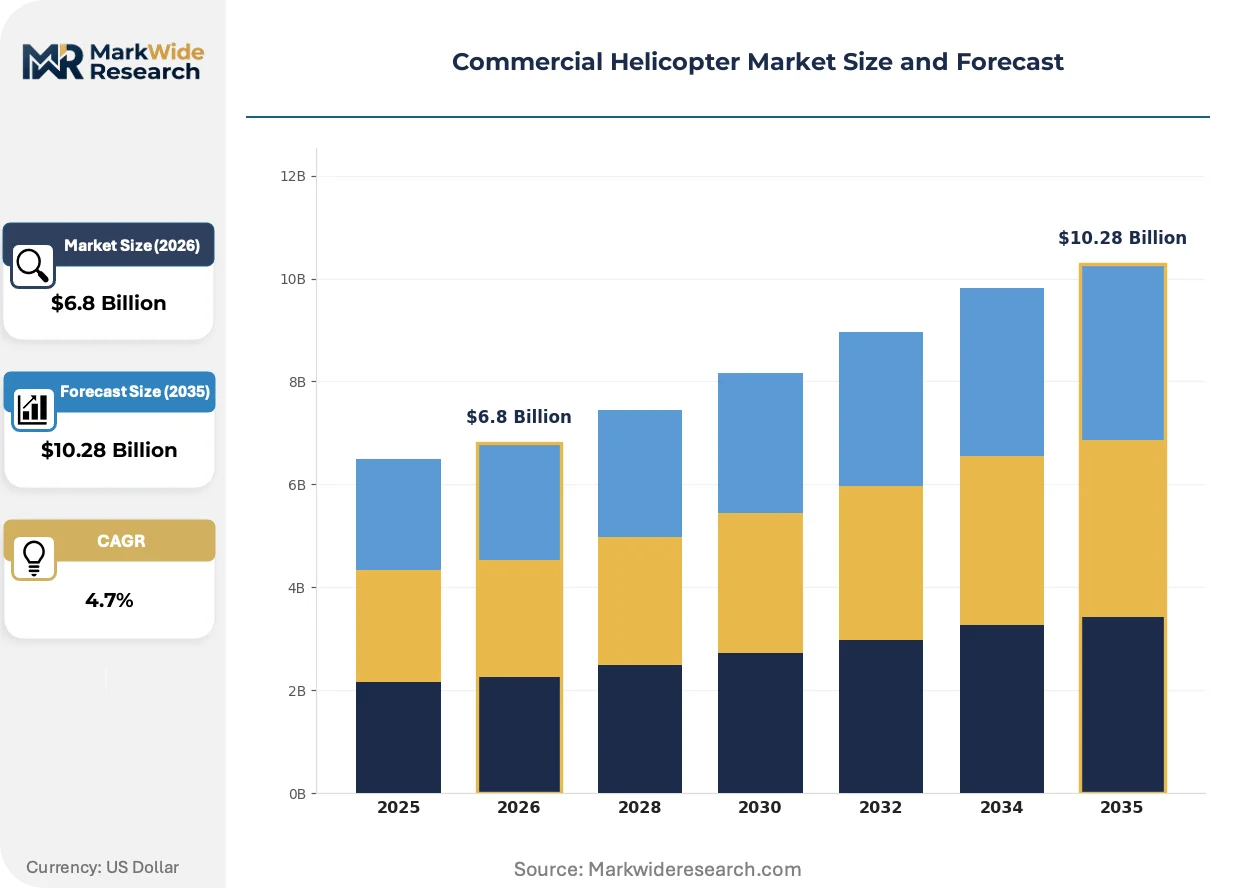
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Helicopters, Medium Helicopters, Heavy Helicopters, Super Heavy Helicopters End User: Emergency Medical Services, Offshore Services, Tourism, Law Enforcement Configuration: Single Rotor, Multi-Rotor, Tandem Rotor, Coaxial Rotor Application: Cargo Transport, Aerial Surveying, Search and Rescue, Firefighting |
| Companies Covered | Lockheed Martin Corporation (Sikorsky), Russian Helicopters, Airbus Helicopters, Hindustan Aeronautics Limited, MD Helicopters Inc., Bell Textron Inc., Robinson Helicopter Company, Korea Aerospace Industries Ltd., Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Helicopter Market Strategic Shifts & Innovations
Digital twin architectures are penetrating flight test and maintenance operations, compressing development cycles and unbundling traditional service revenue models. Three distinct vectors are reshaping competitive positioning.
Digital twin technology is virtualizing physical airframe behavior through real-time sensor fusion and physics-based modeling. Offshore operators in the North Sea are deploying these systems to predict gearbox fatigue before component replacement. This capability is virtualizing scheduled maintenance intervals into condition-triggered interventions, eroding the hourly-based MRO contracts that sustained legacy revenue streams.
EASA CS-29 Amendment 7 and FAA Part 29 Amendment 64 are mandating enhanced crashworthiness standards including energy-absorbing seats and improved occupant protection. Manufacturers are redesigning cabin structures to meet dynamic testing requirements without weight penalties that compromise payload-range performance. Heavy helicopter segments serving oil-and-gas crew change missions face the steepest compliance costs due to passenger density configurations.
Power-by-the-hour contracts are fragmenting into unbundled component-level service agreements. Charter operators in the Gulf of Mexico are negotiating separate coverage for engines, dynamics, and avionics rather than comprehensive airframe packages. This disaggregation is most visible among mid-size fleet operators seeking transparency into true maintenance cost drivers.
Commercial Helicopter Market Segmentation
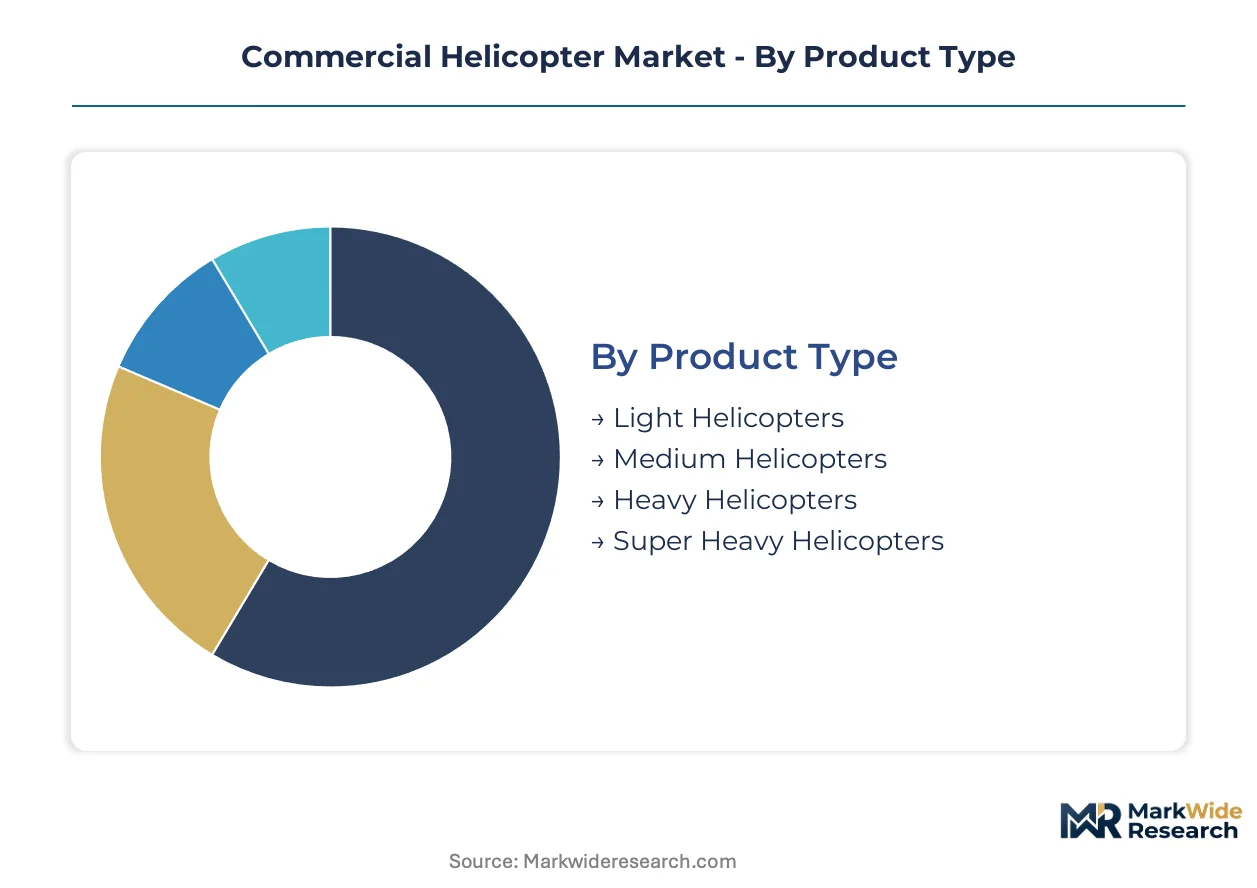
Commercial helicopter procurement patterns diverge sharply across payload classes and mission profiles. Operators select platforms based on hour-cost economics, regulatory certification tiers, and infrastructure compatibility rather than unit price alone.
Product Type:
The use-case spectrum spans hour-limited training operations through multi-day offshore endurance missions requiring auxiliary fuel systems.
- Light Helicopters:Single-turbine platforms under 3,175 kg maximum takeoff weight dominate flight school fleets and urban tourism circuits. FAA Part 27 certification keeps acquisition costs accessible for owner-operators in Florida and Arizona training clusters.
- Medium Helicopters:Twin-engine configurations between 3,175 kg and 7,000 kg serve hospital networks requiring IFR capability for night patient transfers. Italian and Spanish EMS consolidation programs are driving twin-engine replacements for aging single-turbine fleets.
- Heavy Helicopters:Platforms exceeding 7,000 kg with 12-plus passenger capacity anchor North Sea and Gulf of Mexico crew change logistics. Extended over-water endurance requirements favor these units despite higher fuel burn per seat-mile.
- Super Heavy Helicopters:Specialized aerial crane configurations above 20,000 kg lift capacity serve construction and firefighting tanker roles. Limited production runs concentrate at single OEM facilities with multi-year order backlogs.
The dominant share belongs to Light Helicopters, while Medium Helicopters is closing the gap fastest.
End User:
Customer procurement sophistication varies from municipal budget cycles to corporate fleet standardization mandates.
- Emergency Medical Services:Hospital networks and dedicated air ambulance operators specify twin-engine redundancy for patient-critical missions. FAA Part 135 certificate holders in Texas and California are consolidating regional fleets to secure volume pricing from OEMs.
- Offshore Services:Oil-and-gas majors contract helicopter transport through integrated logistics providers covering platform crew changes. North Sea operators face EU Green Deal pressure to blend sustainable aviation fuel into turbine fuel pools.
- Tourism:Scenic flight operators in Grand Canyon and Hawaiian island circuits prioritize cabin visibility and noise footprint over speed. Seasonal demand concentration creates utilization challenges for owner-operators.
- Law Enforcement:State and federal agencies procure surveillance-configured platforms with electro-optical sensor integration. Federal grant programs in the United States partially offset acquisition costs for municipal police aviation units.
Emergency Medical Services commands the largest procurement volume, though Offshore Services generates the highest revenue per airframe.
Configuration:
Rotor architecture selection determines payload efficiency, noise signature, and maintenance interval economics.
- Single Rotor:Conventional main rotor with anti-torque tail rotor dominates certified production. Simplified mechanical architecture keeps direct maintenance costs lowest for high-cycle training applications.
- Multi-Rotor:Unmanned cargo platforms with distributed electric propulsion are entering maritime logistics trials under EASA SAIL II rules. Norwegian offshore operators are piloting deck-to-platform supply runs with reduced weather minimums.
- Tandem Rotor:Overlapping rotor discs eliminate tail rotor power loss for heavy-lift efficiency. Military-derived designs serve logging and construction sectors requiring precision external load placement.
- Coaxial Rotor:Contra-rotating main rotors remove anti-torque requirement, compacting airframe footprint for shipboard operations. Russian-derived designs face Western certification barriers limiting civil market penetration.
Single Rotor retains overwhelming unit share, yet Multi-Rotor is expanding most quickly in unmanned cargo segments.
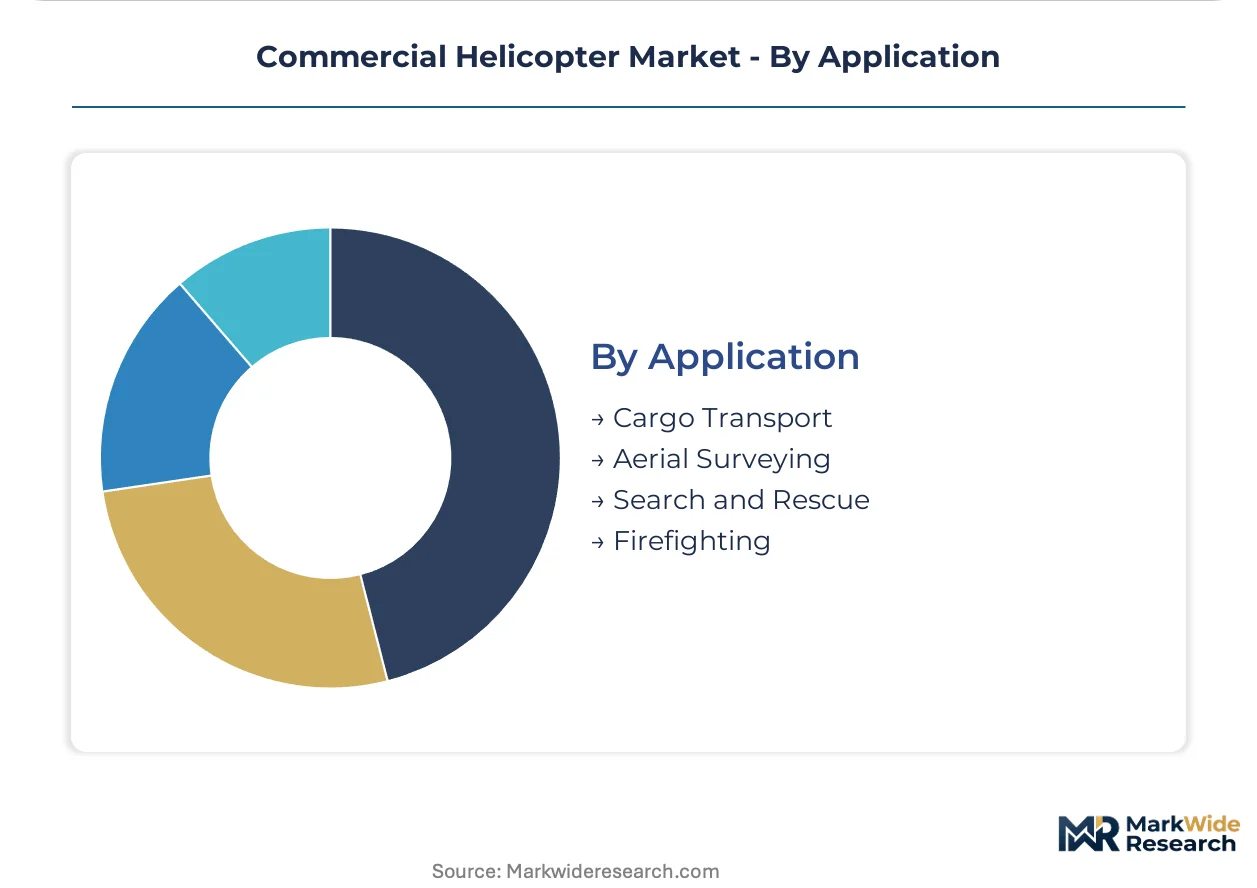
Application:
Mission-specific equipment fit determines platform residual value and secondary market liquidity.
- Cargo Transport:Internal and external load capability supports logistics chains lacking runway infrastructure. Amazon and UPS are evaluating unmanned rotorcraft for last-mile delivery in suburban corridors.
- Aerial Surveying:Lidar and multispectral sensor integration requires stable hover performance and low-vibration transmission mounts. Geological and utility inspection contracts in Australia and Canada drive specialized equipment demand.
- Search and Rescue:Winch-equipped cabins with night vision goggle compatibility serve coast guard and alpine rescue services. EASA CS-29 crashworthiness mandates are raising cabin modification costs for legacy fleet extensions.
- Firefighting:Bambi bucket and fixed tank configurations require rapid power reserve for hot-and-high density altitude operations. Surplus military airframe conversions through supplemental type certificates are extending economic life for tanker fleets.
Cargo Transport leads application segment value, while Firefighting shows the steepest expansion trajectory in aerial fire suppression contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Flight training operators in Arizona and Florida prioritize acquisition cost above all else. Offshore logistics buyers in Norway and the United Kingdom accept premium pricing for payload-range performance.
United States
Urban air mobility infrastructure investments in Dallas and Los Angeles are accelerating vertiport site approvals. FAA Part 135 certification requirements govern emergency medical services fleet consolidation across Texas and California hospital networks. The Gulf of Mexico offshore logistics corridor sustains replacement demand for aging medium-twin platforms serving oil-and-gas crew changes.
Germany
Municipal zoning reforms in urban centers are creating dedicated demand corridors for electric vertical-lift platforms. EU Green Deal Sustainable Aviation Fuel mandates pressure offshore operators to blend SAF into turbine fuel pools. The North Sea logistics hub around Hamburg and Bremen faces refinery capacity constraints despite Rotterdam supply expansion.
United Kingdom
North Sea oil-and-gas decommissioning schedules are compressing heavy helicopter utilization forecasts. EASA CS-29 airworthiness standards apply through retained EU law alignment, tightening crash-resistant fuel system requirements. Aberdeen maintains its concentration of offshore aviation service providers despite fleet downsizing pressures.
Italy
Hospital network consolidation across Lombardy and Veneto is driving twin-engine replacements for aging single-turbine EMS fleets. EASA CS-27 certification pathways keep light helicopter procurement accessible for regional air ambulance operators. The Milan-Turin corridor hosts specialized maintenance facilities serving Mediterranean tourism circuits.
Norway
Offshore operators are piloting multi-rotor unmanned cargo platforms for deck-to-platform supply runs under EASA SAIL II autonomous flight rules. Stavanger and Bergen clusters concentrate maritime logistics aviation expertise. Beyond-visual-line-of-sight trials are reducing weather minimums for North Sea platform resupply missions.
Commercial Helicopter Market Key Industry Players
Capability concentration sits with established rotorcraft manufacturers holding decades of certification expertise; scale advantage sits with diversified aerospace conglomerates leveraging cross-program engineering resources. The market structure reflects a tiered hierarchy where full-spectrum OEMs control premium segments and specialized producers occupy niche payload classes. Two strategic archetypes dominate: vertically integrated airframers with captive powerplant relationships, and modular platform specialists emphasizing rapid configuration flexibility. Competitive moves center on military-to-civilian conversion program expansion and digital predictive maintenance platform deployment.
Within the diversified aerospace tier, Lockheed Martin Corporation and Airbus Helicopters exemplify scale-driven positioning through extensive certification portfolios and global service networks. Leonardo S.p.A. occupies a specialized position emphasizing twin-engine configurations for emergency medical services and offshore logistics missions. Bell Textron Inc. anchors the light-twin segment through established channel relationships with certified training academies and regional air ambulance operators.
| Leading Market Players |
|---|
| Lockheed Martin Corporation (Sikorsky) |
| Russian Helicopters |
| Airbus Helicopters |
| Hindustan Aeronautics Limited |
| MD Helicopters Inc. |
| Bell Textron Inc. |
| Robinson Helicopter Company |
| Korea Aerospace Industries Ltd. |
| Leonardo S.p.A. |
| Others |
Cost & Logistics Intelligence
Overcapacity in light-twin final assembly lines across France and Italy is compressing base airframe margins while concentrating pricing power in aftermarket service tiers. OEMs are responding by unbundling power-by-the-hour contracts into component-level agreements that extract value from health and usage monitoring data streams.
Pricing Analysis
Aftermarket parts and service revenue tiers now drive lifetime value capture across commercial helicopter fleets. Three-tier pricing structure across premium OEM-certified, standard independent MRO, and economy surplus parts segments stratifies buyer options by certification grade and traceability documentation. Cost compression in light-single segments is intensifying because aging airframes face crash-resistant fuel system retrofit costs exceeding residual value. Flight training operators in Arizona and Florida exhibit highest price sensitivity, while North Sea offshore logistics buyers accept premium positioning for payload-range performance and over-water endurance.
Supply Chain Analysis
Contract manufacturing concentration for critical dynamic components sits with Safran and Pratt & Whitney Canada foundries in France and Canada. Turboshaft engine output draws from specialized machining clusters in the United States and Germany for precision gearbox housings and turbine blade castings. Single-source vulnerability in engine control system semiconductors creates exposure to automotive sector demand surges. Distribution runs through OEM-controlled parts depots in Dallas, Hamburg, and Singapore, with independent distributors capturing legacy fleet maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial helicopter platforms are approaching a platform-economics inflection as digital predictive maintenance ecosystems interoperate with urban air mobility infrastructure investments. Health and usage monitoring system data portability between OEMs and operators is reshaping value capture architecture.
For Market Incumbents:Entrench certification expertise as a defensive moat against electrically propelled vertical-lift entrants by accelerating FAA Part 33 and EASA CS-E compliance pathways for hybrid architectures. Deepen backward integration into avionics software stacks to control data interfaces that condition operator platform loyalty. Lockheed Martin Corporation and Airbus Helicopters should expand military-to-civilian conversion program throughput to absorb surplus airframe supply and extend service revenue horizons.
For New Entrants and Emerging Players:Pursue unmanned cargo logistics white space in Norwegian and UK North Sea maritime resupply corridors where EASA SAIL II autonomous flight rules are lowering operational barriers. Target firefighting tanker modification segments where supplemental type certificate pathways reward rapid airframe reconfiguration capabilities. A go-to-market angle anchored in deck-to-platform supply run pilot programs with integrated logistics providers minimizes direct OEM sales channel conflict.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting downward across digital predictive maintenance sub-segments as software margins displace hardware-dependent revenue streams. Long-term viability across the analysis window favors acquisition targets with captive data platform installations and recurring service contract backlogs. The signal to watch is vertiport infrastructure deployment velocity in Dallas and Los Angeles as a leading indicator of electric vertical-lift platform substitution pressure on traditional helicopter demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid-Electric Propulsion Certification | FAA Part 33 and EASA CS-E compliance secures market access against electrically propelled entrants. |
| Digital Predictive Maintenance Platform Deployment | Airbus Helicopters' Skywise architecture conditions operator expectations for real-time component tracking. |
| Military-to-Civilian Conversion Program Expansion | Surplus UH-60 and Mi-17 airframe conversions extend economic life through firefighting tanker modifications. |
| Vertiport Infrastructure Partnership | Dallas and Los Angeles municipal zoning reforms accelerate site approvals for urban air mobility corridors. |
| Sustainable Aviation Fuel Supply Agreement | Rotterdam refinery capacity expansion improves SAF supply security for North Sea logistics fleets. |
Research Approach
The analysis maps light, medium, heavy, and super-heavy payload classes, each validated through fleet managers at offshore logistics operators, EMS procurement directors at hospital networks, chief pilots at flight training academies, and MRO facility directors. Primary interview findings triangulate against FAA certification databases, EASA type certificate records, SEC 10-K filings from listed aerospace conglomerates, and customs trade data for turbine engine imports. Bottom-up airframe shipment tracking reconciles with top-down operator fleet renewal surveys.
Assumption sets held fuel price volatility and regulatory timeline compression for novel propulsion architectures as fixed boundary conditions across the projection horizon. Segmentation dimensions modeled include payload class, end-user mission profile, rotor configuration architecture, and regional regulatory cluster. CAGRs derive from logistic curve fitting against replacement cycle data and hour-limit retirement schedules. Forecast inputs incorporate vertiport infrastructure deployment timelines and SAF blending mandate compliance trajectories.
Macroeconomic conditions sit as an overlay; deviation in offshore oil-and-gas capital expenditure cycles or EU Green Deal enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions on certification timeline compression and powerplant supply concentration. Quarterly review of FAA Part 23 rewrite progress and EASA SC-VTOL framework finalization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Civil Helicopter Market
Aircraft
Europe Aircraft Manufacturing Market
Aircraft
Hybrid Aircraft Market
Aircraft
Aircraft Nacelle Systems Market
Aircraft
Aircraft Pushback Tugs Market
Aircraft
North America Business Jet Market
Aircraft
Global Aircraft Towbars Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Military Helicopters Market
Aircraft
Aircraft Window Frame Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Europe Aircraft Engines Market
Aircraft
Commercial Aircraft Landing Gear Market
Aircraft
Europe Aviation Market
Aircraft
Onboard Oxygen Generating System (OBOGS) Market