
 Mine Clearance System Market | 2026-2036
Mine Clearance System Market Size, Share, and Industry Trends Forecast 2026-2036
Mine Clearance System Market Analysis
Software-defined mission planning is rebalancing contract economics toward recurring service revenue alongside hardware sales. Rheinmetall AG leverages its armored vehicle heritage to dominate integrated platform tenders. DOK-ING d.o.o. anchors the unmanned ground vehicle segment with specialized flail and tiller configurations. MineWolf Systems AG differentiates through dual-use engineering that spans military specification and humanitarian demining protocols.
Mine clearance systems encompass mechanized and robotic platforms, sensor arrays, and explosive ordnance disposal tools engineered to detect, neutralize, or remove landmines and unexploded ordnance from contaminated terrain. These systems integrate ground-penetrating radar arrays, magnetic anomaly detectors, and mechanical flails operating at depths up to 30 centimeters to ensure route verification and area reduction for subsequent manual clearance. Detection equipment commands the largest share of solution spending due to sensor miniaturization and multi-sensor fusion requirements. Humanitarian missions represent the fastest-growing application segment as donor-funded programs shift from manual to mechanized clearance to meet Ottawa Treaty deadlines.
The International Mine Action Standards, EU CE marking for robotic systems, and national defence procurement regulations across NATO member states collectively shape product certification pathways and market access conditions. Compliance with ISO 9001 quality management and ISO 14001 environmental standards increasingly filters eligibility for United Nations Development Programme tenders. Stakeholders must monitor evolving autonomous systems liability frameworks and export control classifications that will determine which platform architectures qualify for restricted theatre deployments.
Market Dynamics
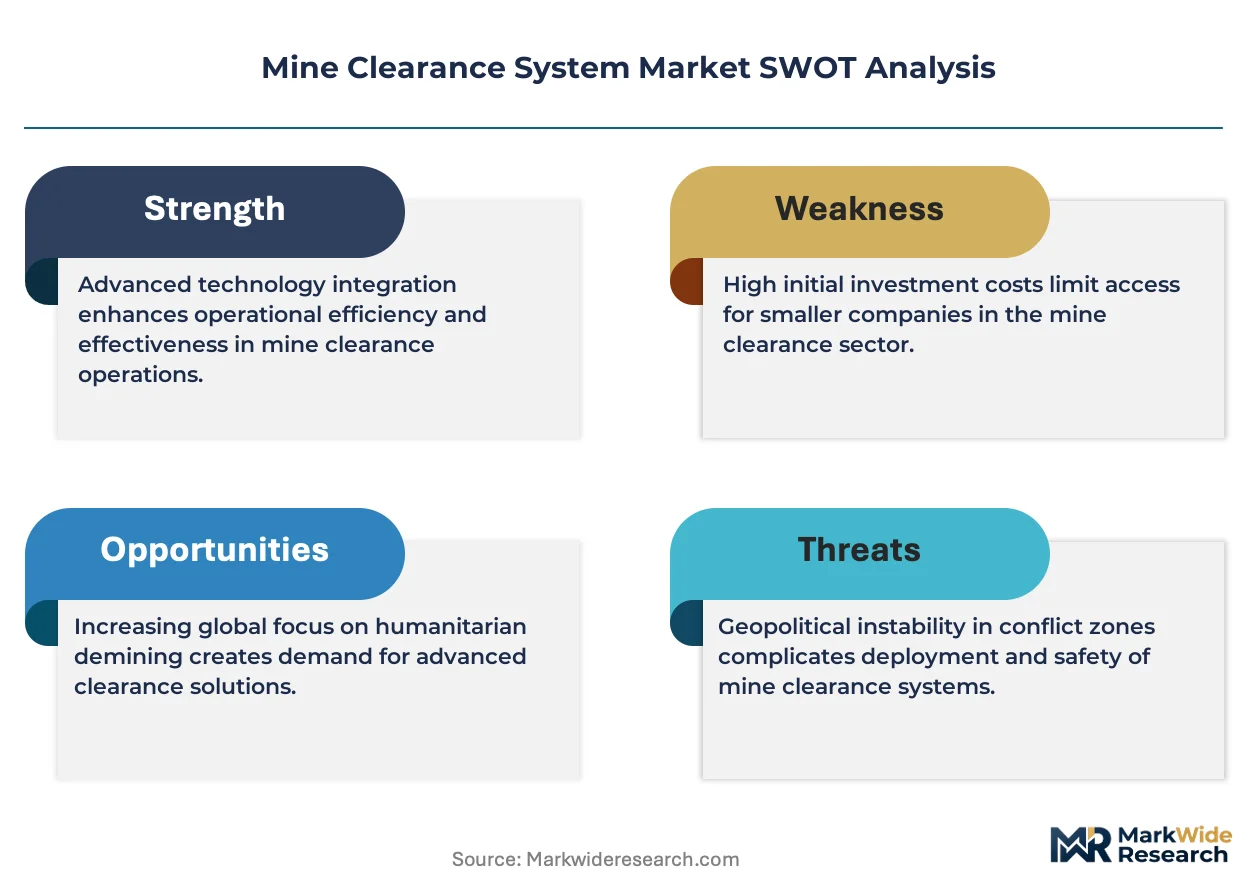
Software-defined mission planning is restructuring contract economics toward recurring service revenue streams that supplement hardware sales, while autonomous detection certification requirements under EU standards are accelerating platform replacement cycles.
Growth Catalysts
- EU CE marking for robotic systems:Updated certification pathways for autonomous detection platforms are accelerating procurement timelines for defense and humanitarian operators seeking standardized equipment.
- Legacy contamination in Cambodia:Decades of unexploded ordnance sustain long-term deployment contracts and recurring maintenance revenue for mechanized clearance fleets.
- Ground-penetrating radar miniaturization:Sensor fusion requirements are expanding platform capabilities and driving replacement demand for aging single-sensor detection equipment.
Market Restraints
- Sensor component concentration:Specialized magnetic anomaly detector subsystems rely on limited semiconductor fabrication capacity concentrated in East Asian supply chains.
- Export control classifications:Dual-use technology restrictions under Wassenaar Arrangement protocols create licensing friction for autonomous platform transfers to conflict theatres.
- Manual clearance substitution:Low-cost human demining teams remain competitive in donor-funded humanitarian programs with constrained equipment budgets.
Strategic Opportunities
- Ukraine reconstruction demand:Post-conflict territory clearance requirements will sustain multi-year mechanized platform deployment contracts as contamination extends across agricultural and infrastructure zones.
- Drone-swarm integration:Convergence of unmanned aerial systems with ground-based robotic platforms enables area-reduction surveying that compresses manual clearance timelines.
- Outcome-based service contracting:Donor agencies are pivoting from equipment purchase to cleared-land payment models that transfer operational risk to platform operators.
Industry Challenges
- Autonomous systems liability frameworks:Unclear fault attribution for platform malfunctions in active minefields complicates insurance and operator certification protocols.
- Multi-sensor calibration expertise:Shortage of technicians capable of integrating ground-penetrating radar with electromagnetic induction arrays limits field deployment readiness.
- NATO interoperability standards:Divergent national specifications for communication protocols and data formats fragment procurement and complicate multinational mission coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mine Clearance System Market |
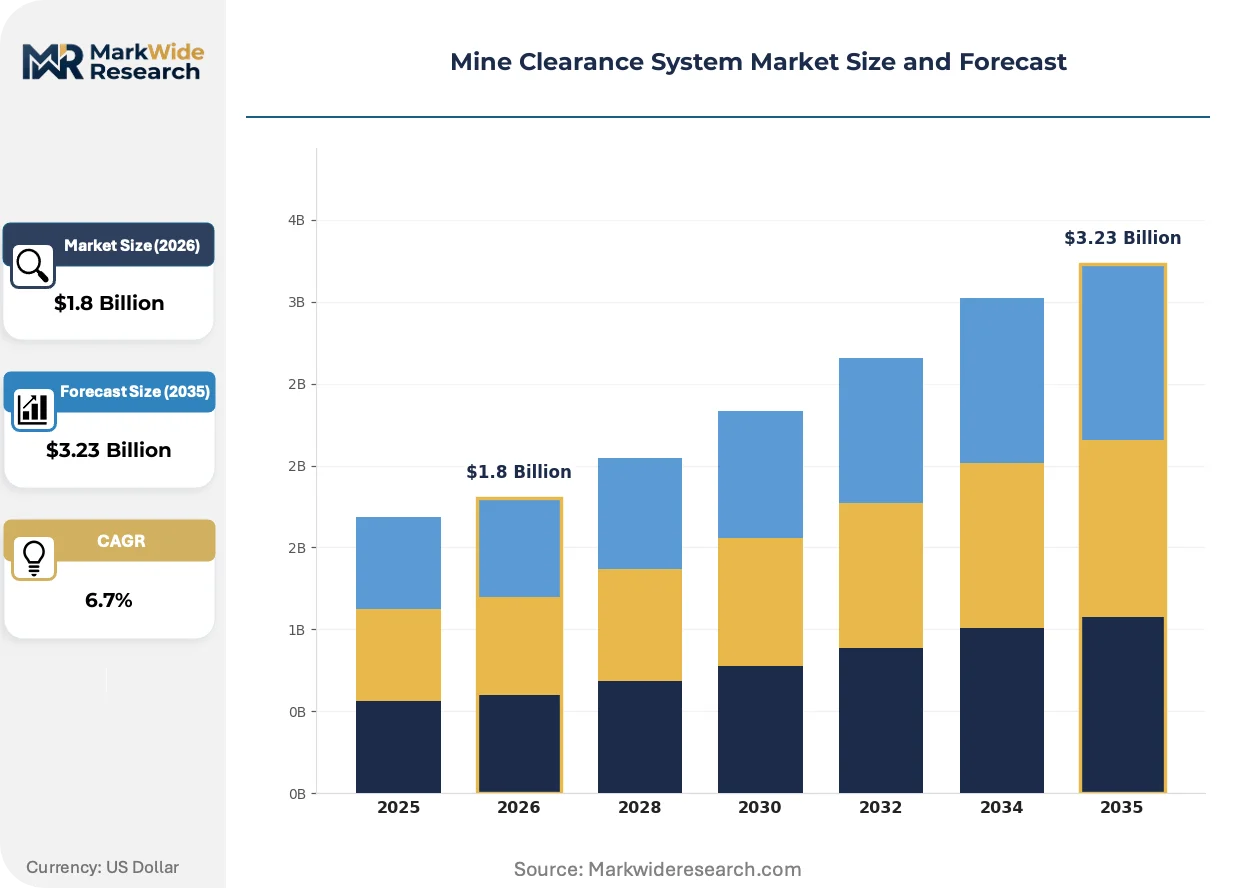
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution: Ground Robots, UAVs, Manual Tools, Detection Equipment End User: Government Agencies, NGOs, Defence Forces, Private Contractors Technology: Laser Detection, Magnetic Sensors, Ground Penetrating Radar, Chemical Sensors Application: Combat Zones, Humanitarian Missions, Infrastructure Projects, Environmental Remediation |
| Companies Covered | MineWolf Systems AG, FAE Group, Rheinmetall AG, CEFA, Hydrema Holdings ApS, Pearson Engineering, Armtrac Limited, Aardvark Clear Mine Ltd, DOK-ING d.o.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mine Clearance System Market Emerging Trajectories
Autonomous platform architectures are displacing remotely operated systems as the dominant engineering paradigm, while regulatory pressure on detection accuracy is accelerating sensor fusion development.
Multi-sensor fusion arrays combining ground-penetrating radar with electromagnetic induction and infrared thermography are expanding into route verification missions previously reserved for manual clearance teams. Humanitarian demining organizations in Southeast Asia are adopting these platforms to meet Ottawa Treaty deadlines. The technology is expanding into service contract structures where operators guarantee cleared-area outcomes rather than equipment availability.
REACH regulations on restricted substances in electronics are forcing redesigns of sensor housing materials and cable insulation for European-deployed platforms. Industrial consequence includes extended product development cycles and supplier qualification requirements for component vendors. Detection equipment manufacturers serving NATO member states are responding by establishing EU-based material certification pipelines.
Buyer concentration among United Nations Development Programme tender aggregators is compressing vendor qualification timelines and unbundling after-sales service from hardware procurement. Traditional equipment distributors are losing position to direct manufacturer relationships with donor-funded program managers. This pattern is most visible in Afghanistan and Cambodia where multi-year framework agreements consolidate purchasing authority.
Mine Clearance System Market Segmentation
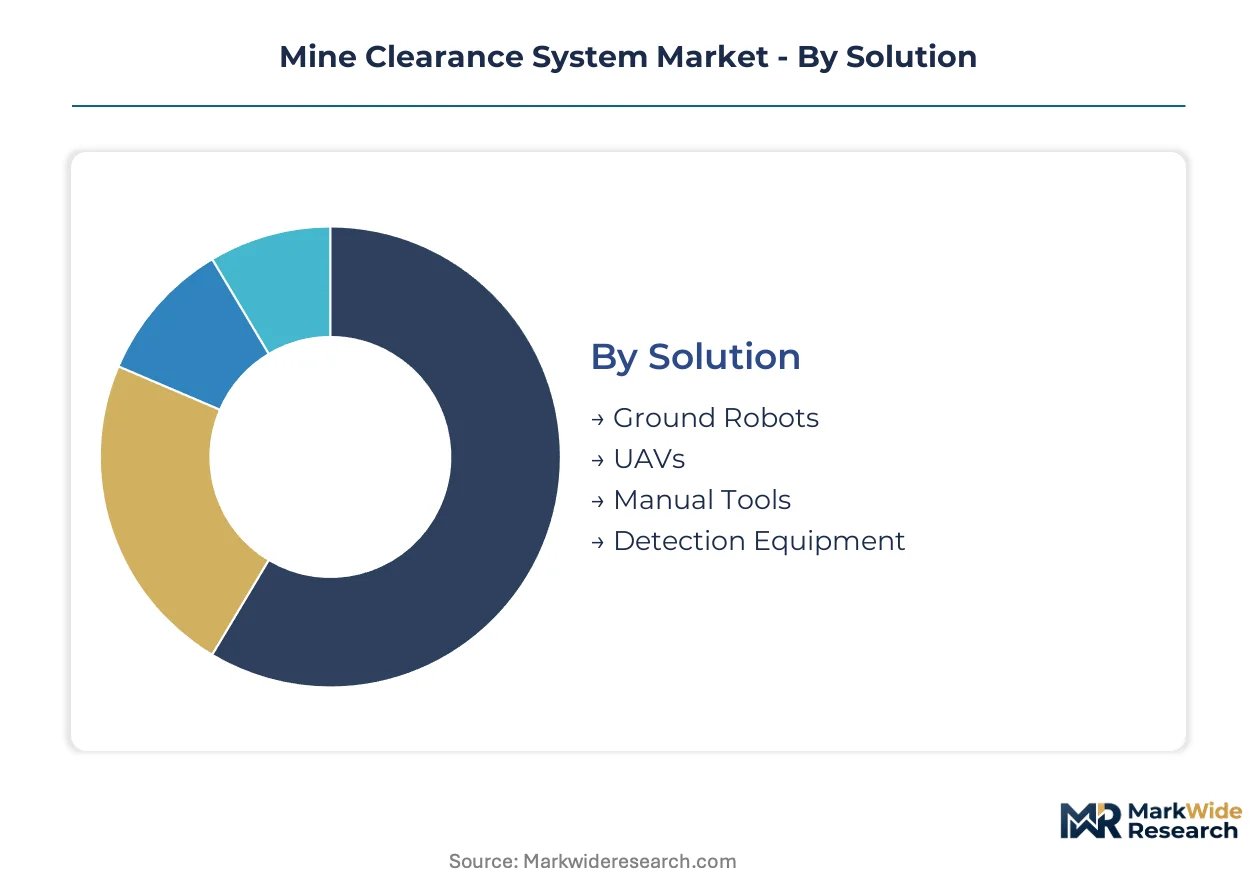
Segmentation in mine clearance systems reveals how procurement authority, operational risk tolerance, and regulatory compliance requirements reshape vendor positioning across distinct customer and technology categories. Understanding these divisions exposes where contract values concentrate and which capability gaps create entry opportunities for specialized suppliers.
Solution:
Supply concentration in robotic platforms has shifted procurement leverage toward integrated system vendors capable of delivering detection-to-neutralization workflows rather than point-product manufacturers.
- Ground Robots:Unmanned ground vehicles integrate mechanical flails, tillers, and sensor payloads for autonomous area reduction in high-threat environments. Demand concentrates with defence forces in Ukraine and Afghanistan pursuing fleet standardization under NATO interoperability protocols, though autonomous liability frameworks remain unresolved.
- Detection Equipment:Multi-sensor arrays combining ground-penetrating radar with electromagnetic induction dominate solution spending due to CE marking requirements and UN tender specifications. Procurement in Cambodia and donor-funded programs across Southeast Asia favors certified platforms with established maintenance networks.
- UAVs:Aerial platforms enable rapid area survey and route verification prior to ground deployment, compressing manual clearance timelines in agricultural reconstruction zones.
- Manual Tools:Prodders, detectors, and protective equipment persist in constrained-budget humanitarian programs where mechanized alternatives face donor resistance.
Today's leader: Detection Equipment. Tomorrow's challenger: Ground Robots.
End User:
Cost tier differentiation separates capital-intensive defence procurement from outcome-based humanitarian contracting, with margin structures varying dramatically across these buyer categories.
- Defence Forces:Military operators demand hardened platforms with encrypted communications, NATO-standard data formats, and rapid deployment logistics. Procurement concentrates in Ukraine, Poland, and Baltic states responding to territorial contamination and forward deployment requirements.
- Government Agencies:National mine action authorities in Afghanistan and Cambodia manage framework agreements consolidating multi-year equipment and service procurement under UNDP coordination mechanisms.
- NGOs:Humanitarian demining organizations operate under Ottawa Treaty deadlines with donor-dependent budgets, favoring leased or service-contracted equipment over capital purchases.
- Private Contractors:Commercial clearance firms serving infrastructure and resource extraction projects in contaminated territories purchase specialized platforms for defined-scope contracts.
Defence Forces command premium pricing. NGOs are expanding most quickly through outcome-based service adoption.
Technology:
Application context determines sensor selection, with military route verification demanding different performance profiles than humanitarian area clearance.
- Ground Penetrating Radar:Subsurface imaging arrays detect non-metallic mines and distinguish clutter from threat objects, essential for plastic-cased ordnance common in Southeast Asian contamination. Miniaturization trends are expanding deployment on small robotic platforms.
- Magnetic Sensors:Electromagnetic induction detectors identify metallic components in legacy Soviet and NATO ordnance across Ukrainian and Balkan contamination zones. Supply constraints in specialized semiconductor fabrication create delivery vulnerability.
- Laser Detection:Standoff optical systems enable surface and near-surface threat location without physical ground contact, suited for infrastructure survey missions.
- Chemical Sensors:Explosive vapor detection technologies support confirmation sampling in high-clutter environments where electromagnetic methods generate excessive false positives.
Ground Penetrating Radar leads technology investment. Magnetic Sensors face supply concentration risk.
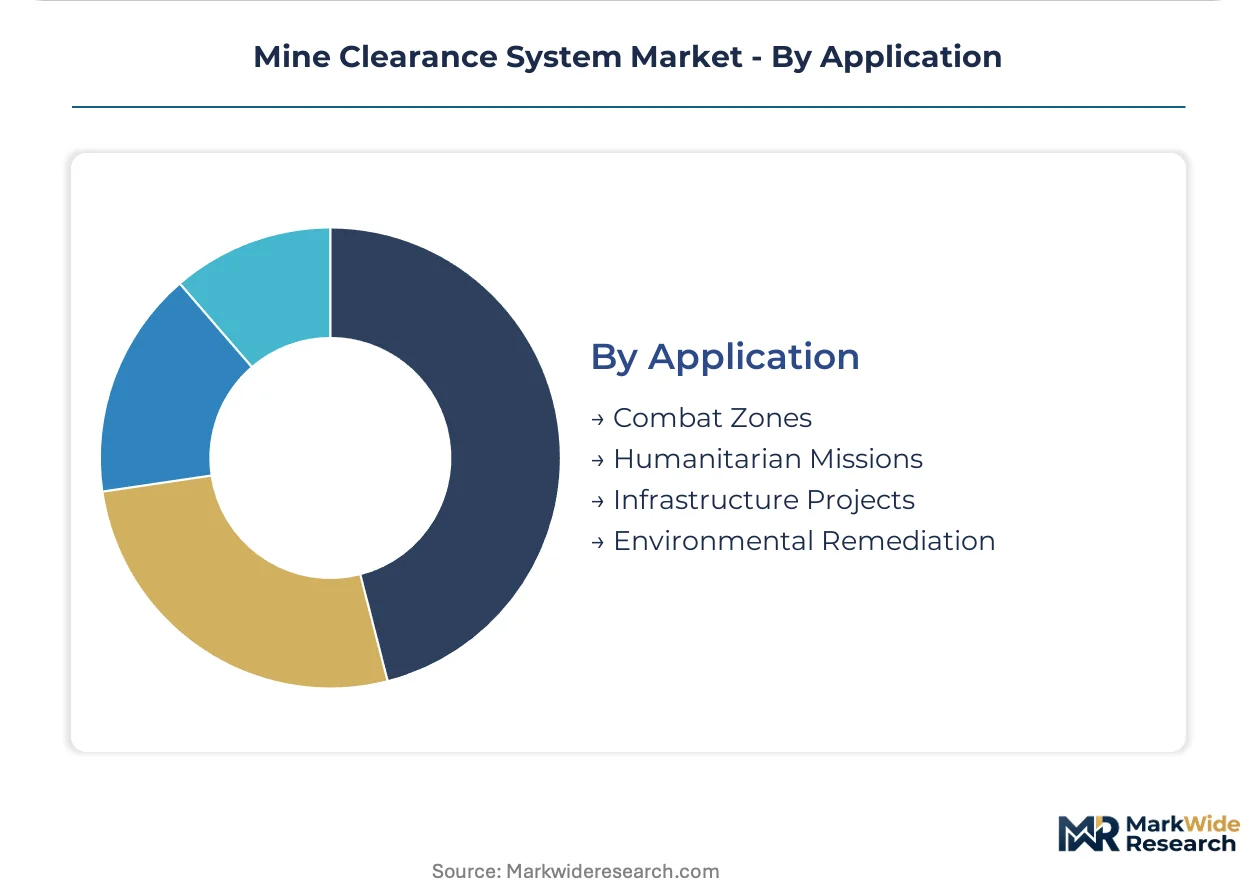
Application:
Volume concentration in humanitarian missions is reshaping product development priorities toward donor-certifiable platforms with simplified operator training requirements.
- Humanitarian Missions:Donor-funded clearance programs in Cambodia, Afghanistan, and Laos pursue mechanization to meet Ottawa Treaty obligations, driving demand for robust, maintainable equipment suited to tropical and arid field conditions.
- Combat Zones:Active conflict and immediate post-conflict environments in Ukraine require rapid route opening and area denial breaching, prioritizing speed and operator protection over clearance completeness.
- Infrastructure Projects:Pipeline, road, and agricultural development in formerly contested territories demands certified clearance documentation for insurance and financing compliance.
- Environmental Remediation:Former military training ranges and testing areas require systematic ordnance removal prior to ecological restoration or civilian land release.
Humanitarian Missions claim the steepest expansion trajectory. Combat Zones sustain near-term revenue concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ukraine sustains the steepest procurement acceleration for mechanized clearance platforms, while Cambodia anchors long-term service contract value through decades of residual contamination requiring systematic removal.
Ukraine
Defence procurement for route verification and area denial breaching dominates platform deployment across contaminated agricultural and infrastructure zones. NATO interoperability standards shape equipment specifications for encrypted communications and data format compliance. Kyiv and eastern oblasts concentrate fleet deployment contracts as territorial clearance extends into reconstruction-phase requirements.
Cambodia
Legacy ordnance from conflict decades sustains multi-year framework agreements for mechanized area reduction under donor-funded programs. Ottawa Treaty deadline pressure accelerates shift from manual to robotic clearance platforms. Siem Reap and northwestern provinces host concentrated demining operations serving agricultural land release objectives.
Afghanistan
UNDP-coordinated tender mechanisms consolidate procurement authority for humanitarian clearance programs across residual contamination zones. ISO 9001 and ISO 14001 certification filters eligibility for equipment vendors seeking multi-year maintenance contracts. Kabul and southern regions sustain deployment of ground-penetrating radar arrays for route verification missions.
Germany
REACH regulations on restricted substances in electronics force sensor housing redesigns and extended supplier qualification cycles for platforms deployed in European theatres. CE marking requirements for autonomous detection systems accelerate certification pathways for defence and humanitarian operators. Rheinmetall's armored vehicle heritage anchors integrated platform tenders serving NATO standardization objectives.
United States
Defence procurement for robotic clearance platforms concentrates in programmes requiring encrypted communications and rapid deployment logistics for expeditionary operations. Export control classifications under Wassenaar Arrangement protocols create licensing friction for autonomous platform transfers. Virginia and Texas host defence contractor clusters supplying sensor fusion arrays for military route verification missions.
Mine Clearance System Market Vendor Landscape
Top-tier vendors anchor integrated system tenders, while specialized component suppliers occupy niche certification pathways. The vendor base stratifies across three tiers: armored vehicle heritage conglomerates, unmanned ground vehicle specialists, and detection equipment component manufacturers. Two strategic archetypes dominate competitive positioning—platform integrators leveraging vehicle manufacturing legacies, and robotics specialists engineering purpose-built flail and tiller configurations. Competitive moves concentrate on sensor fusion technology licensing and backward integration into semiconductor fabrication for magnetic anomaly detector subsystems.
Within the platform integrator tier, Rheinmetall AG represents armored vehicle heritage positioning for NATO defence tenders, while DOK-ING d.o.o. anchors the unmanned ground vehicle specialist archetype with Croatian engineering origins. MineWolf Systems AG occupies a position spanning military specification and humanitarian demining protocol requirements, exemplifying dual-use engineering differentiation. These three entities collectively illustrate how geographic origin and corporate structure shape competitive archetype allocation across defence procurement and donor-funded humanitarian segments.
| Leading Market Players |
|---|
| MineWolf Systems AG |
| FAE Group |
| Rheinmetall AG |
| CEFA |
| Hydrema Holdings ApS |
| Pearson Engineering |
| Armtrac Limited |
| Aardvark Clear Mine Ltd |
| DOK-ING d.o.o. |
| Others |
Supply Flow & Price Mechanics
Technician scarcity in Southeast Asia concentrates multi-sensor calibration expertise, widening labor-cost differentials between premium NATO-certified platforms and economy-tier humanitarian equipment. This workforce asymmetry feeds directly into pricing-tier spreads that separate defence procurement from donor-funded programs.
Pricing Analysis
Capacity additions in Croatia and Germany are reshaping price floors for unmanned ground vehicle platforms as DOK-ING and Rheinmetall expand fabrication throughput. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Price erosion runs through the economy tier as low-cost manual clearance teams compete for UNDP tenders. Defence Forces exhibit lowest price sensitivity due to encrypted communications and rapid deployment requirements; NGOs face acute budget constraints that compress equipment procurement timelines.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale defence procurement while donor-funded programs route through UNDP tender aggregators. Semiconductor fabrication for magnetic anomaly detector subsystems concentrates in Taiwan, South Korea, and Japan. Sensor housing materials draw from specialized polymers subject to REACH regulatory restrictions. Single-source vulnerability in electromagnetic induction array components creates delivery risk for European-deployed platforms. Distribution runs through manufacturer-direct relationships with national mine action authorities in Afghanistan and Cambodia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in mine clearance systems rests on sensor miniaturization cost curves and the shift toward outcome-based service contracting that captures recurring revenue beyond hardware sales.
For Market Incumbents: Lock in certification pathways under EU CE marking for autonomous detection systems before competitor platforms complete validation cycles. Anchor long-term framework agreements with UNDP-coordinated tenders in Cambodia and Afghanistan to secure maintenance revenue streams. Capacity addition in Germany by Rheinmetall threatens pricing power for armored vehicle heritage positioning; respond by deepening backward integration into magnetic sensor semiconductor sourcing.
For New Entrants and Emerging Players: CE marking in Germany opens a window for specialized UAV-ground robot integration platforms that compress area-reduction timelines for Ukrainian reconstruction contracts. White-space targets include drone-swarm surveying for agricultural land release in Southeast Asia and outcome-based service contracting models that transfer operational risk from donor agencies. Penetrate through lease-to-service structures with humanitarian NGOs facing Ottawa Treaty deadline pressure.
For Investors and Strategic Acquirers: Valuations sit cheapest among unmanned ground vehicle specialists with dual-use engineering capabilities spanning military specification and humanitarian demining protocols. Long-term viability centers on autonomous platform architectures displacing remotely operated systems as liability frameworks mature. Acquisition target archetype: robotics specialists with established CE marking and ISO 14001 certification pipelines. Signal to watch: NATO interoperability standard convergence on communication protocols and data formats.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Technology Licensing | Ground-penetrating radar miniaturization enables deployment on small robotic platforms for route verification. |
| Backward Integration into Semiconductor Fabrication | Captive supply of magnetic anomaly detector subsystems reduces East Asian supply chain concentration risk. |
| Outcome-Based Service Contracting | Cleared-land payment models transfer operational risk and extend revenue beyond equipment sales. |
| CE Marking Certification Investment | EU regulatory compliance accelerates procurement timelines for defence and humanitarian operators. |
| Drone-Swarm Integration Development | UAV convergence with ground platforms compresses manual clearance timelines in Ukrainian agricultural zones. |
Methodological Framework
Direct dialogue with mine action program managers, defence procurement officers, sensor engineering leads, and UNDP tender coordinators grounded qualitative assessment. Secondary validation drew from Ottawa Treaty implementation reports, NATO standardization agreements, EU CE marking directives, and customs data on robotic platform trade flows. Bottom-up equipment deployment tallies triangulated against top-down donor funding disbursement records.
Top-down macroeconomic indicators on defence spending and humanitarian aid flows anchored the analytical lens, while bottom-up vendor shipment data and certification timelines shaped segment-level projections. Segmentation dimensions modeled include solution type, end-user category, sensor technology, and application context across the analysis window. CAGRs derived from equipment replacement cycle acceleration under autonomous detection requirements and sensor fusion adoption curves.
Revisions become necessary when Wassenaar Arrangement export control classifications shift, autonomous systems liability frameworks crystallize, or REACH regulatory amendments force sensor housing redesigns. Forecasts reflect assumptions on donor budget continuity, NATO interoperability standard convergence, and semiconductor fabrication capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Missiles and Missile Defense Systems Market
Defense and Military Systems and Equipment
Soldier System Market
Defense and Military Systems and Equipment
Counter-IED Systems Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Military Phased Array Antenna Market
Defense and Military Systems and Equipment
Anti-Drone Guns Market
Defense and Military Systems and Equipment
Military Embedded System Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Saudi Arabia Defense Market
Defense and Military Systems and Equipment
Land-Based Smart Weapons Market
Defense and Military Systems and Equipment
Military Actuators Market
Defense and Military Systems and Equipment
Europe Defense Logistics Market
Defense and Military Systems and Equipment
Military Laser Systems Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market