
 North America Military Helicopters Market | 2026-2036
North America Military Helicopters Market Size, Share, and Industry Trends Forecast 2026-2036
North America Military Helicopters Market Analytics
US rotorcraft manufacturing capacity is expanding across Arizona and Texas production corridors. Sikorsky Aircraft Corporation leverages its Connecticut engineering base to sustain heavy-lift development programs. Bell Textron Inc. anchors the tiltrotor segment with specialized vertical-lift architectures. Lockheed Martin Corporation dominates integrated mission systems and sensor fusion packages for armed reconnaissance variants.
North America military helicopters are turbine-powered rotary-wing platforms designed for armed assault, troop transport, and battlefield surveillance, typically operating at cruise speeds of 120-170 knots with service ceilings above 12,000 feet. Their primary purpose centers on force projection, casualty evacuation, and logistical sustainment in contested airspace. Attack helicopters command the largest share of defense procurement budgets due to anti-armor mission requirements, while composite materials technology represents the fastest-growing segment as airframes adopt carbon-fiber rotor blades and fuselage structures to reduce radar cross-section and improve fuel efficiency. Utility helicopters remain the most mature category with established supply chains and predictable replacement cycles across Air National Guard units.
The FAA enforces airworthiness certification under Part 29 standards for transport-category rotorcraft, while the DoD imposes MIL-STD-810 environmental testing and MIL-STD-461 electromagnetic compatibility requirements that extend development timelines and raise supplier qualification barriers. The EPA regulates turbine engine emissions under Clean Air Act provisions, pushing manufacturers toward more efficient combustion architectures. Stakeholders must monitor congressional appropriations for Future Vertical Lift program funding and assess how domestic content requirements in defense authorization acts reshape subcontractor sourcing across the supply base.
Market Dynamics
The Future Vertical Lift program is compressing development cycles as the US Army demands next-generation rotorcraft with open-system architectures. This procurement shift forces incumbents to abandon proprietary avionics stacks and adopt modular mission computers that accelerate upgrade pathways.
Growth Catalysts
- DoD Acquisition Reform:The Pentagon's rapid prototyping mandates slash fielding timelines for experimental tiltrotor configurations. Program offices now bypass traditional milestone reviews for digitally-certified platforms.
- Composite airframe adoption:Carbon-fiber rotor blades reduce radar cross-section while extending component life cycles. Arizona and Texas manufacturing clusters attract specialized tooling suppliers.
- Armed reconnaissance modernization:Air National Guard units replace aging scout helicopters with sensor-fused variants. Procurement concentrates in southwestern test ranges where integrated training corridors operate.
Market Restraints
- Turbine engine supply concentration:Domestic propulsion manufacturers face capacity constraints on high-output turboshaft variants. Single-source dependencies create program schedule vulnerabilities.
- FAA Part 29 certification friction:Transport-category airworthiness standards impose multi-year validation timelines on new rotorcraft architectures. Environmental testing requirements raise qualification barriers for subsystem vendors.
- Skilled airframe technician scarcity:Composite repair certification programs produce insufficient qualified personnel. Maintenance depots compete with commercial aviation for bonded-structure specialists.
Strategic Opportunities
- Canadian Arctic patrol requirements:NORAD modernization drives demand for cold-weather utility variants with extended-range fuel systems. Ottawa's defense procurement aligns with continental security frameworks.
- AI-enabled predictive maintenance:Machine learning algorithms applied to vibration monitoring reduce unscheduled downtime. Fleet operators contract for data-analytics services separate from hardware acquisition.
- Mexican naval aviation expansion:Counter-narcotics missions require shipboard-capable helicopters with corrosion-resistant coatings. Pacific and Gulf coast bases present fleet renewal opportunities.
Industry Challenges
- MIL-STD-810 environmental testing bottlenecks:Climatic chamber availability limits parallel qualification of multiple subsystems. Test range scheduling conflicts delay low-rate initial production decisions.
- Legacy avionics integration complexity:Retrofit programs struggle with obsolete databus architectures that resist modern sensor interfaces. Software patch certification consumes disproportionate engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Military Helicopters Market |
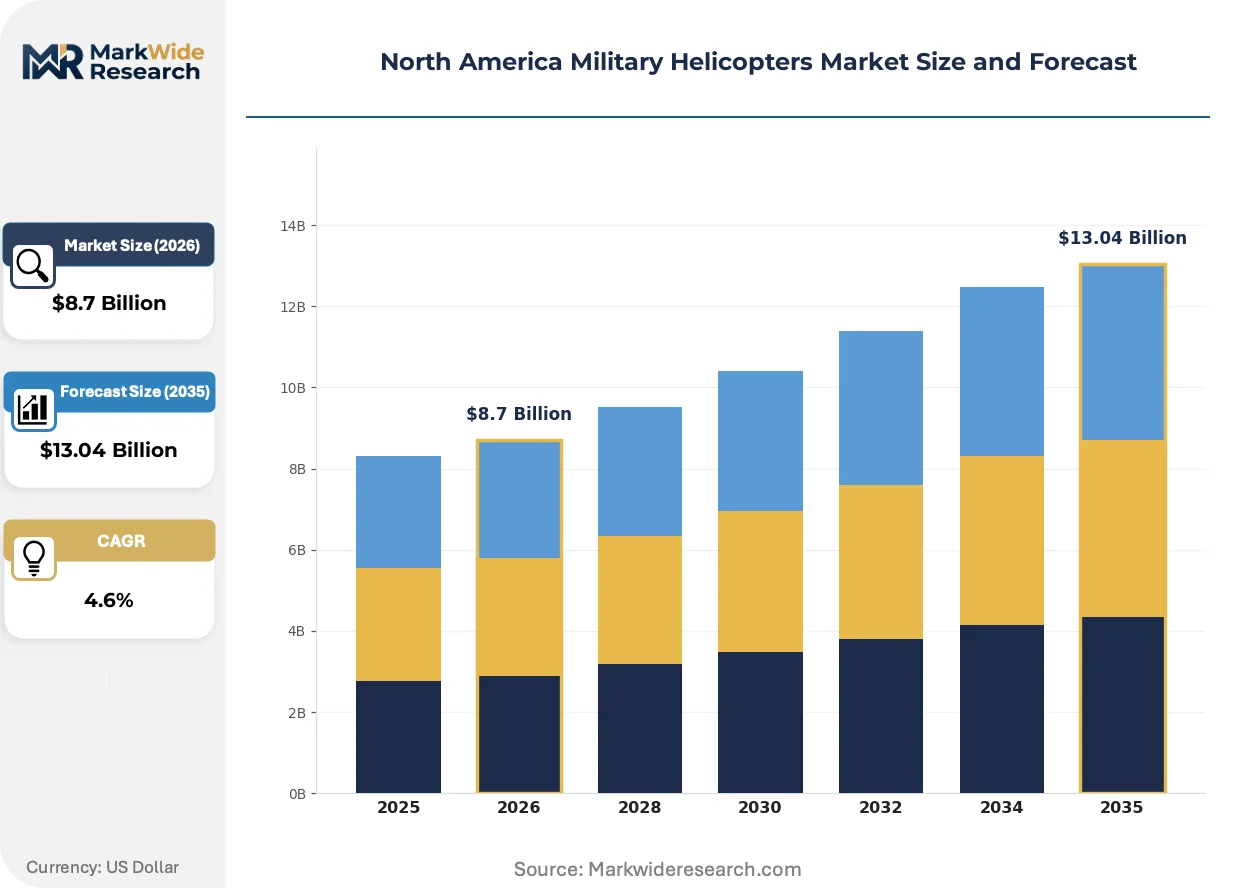
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Attack Helicopters, Transport Helicopters, Reconnaissance Helicopters, Utility Helicopters Technology: Fly-by-Wire, Turboshaft Engines, Avionic Systems, Composite Materials End User: Military Forces, Air National Guard, Special Operations, Government Agencies Application: Combat Operations, Search & Rescue, Medical Evacuations, Logistics Support |
| Companies Covered | Lockheed Martin Corporation, The Boeing Company, Airbus SE, Textron Inc., Leonardo S.p.A., Bell Textron Inc., Sikorsky Aircraft Corporation, MD Helicopters LLC, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Military Helicopters Market Evolving Landscape
Autonomous flight systems are penetrating military rotorcraft faster than regulatory frameworks can adapt. This divergence between technical capability and operational authorization defines current competitive positioning.
Fly-by-wire flight control systems are automating pilot workload reduction in high-threat environments. Attack helicopter squadrons adopt limited-authority autonomy for nap-of-earth navigation. This capability compression enables single-pilot operations in previously dual-crew mission profiles.
The FAA's updated Part 29 Special Conditions for fly-by-wire rotorcraft impose software assurance requirements borrowed from commercial transport categories. Manufacturers must demonstrate equivalent safety levels through formal methods verification. Heavy-lift segments absorb the highest compliance costs as they pursue civil-military dual certification.
Defense procurement offices now unbundle airframe acquisition from sustainment services through performance-based logistics contracts. Fleet managers purchase flight hours rather than spare parts inventories. This shift concentrates most visibly in National Guard units across southwestern states where contractor logistics support already dominates depot maintenance.
North America Military Helicopters Market Segmentation
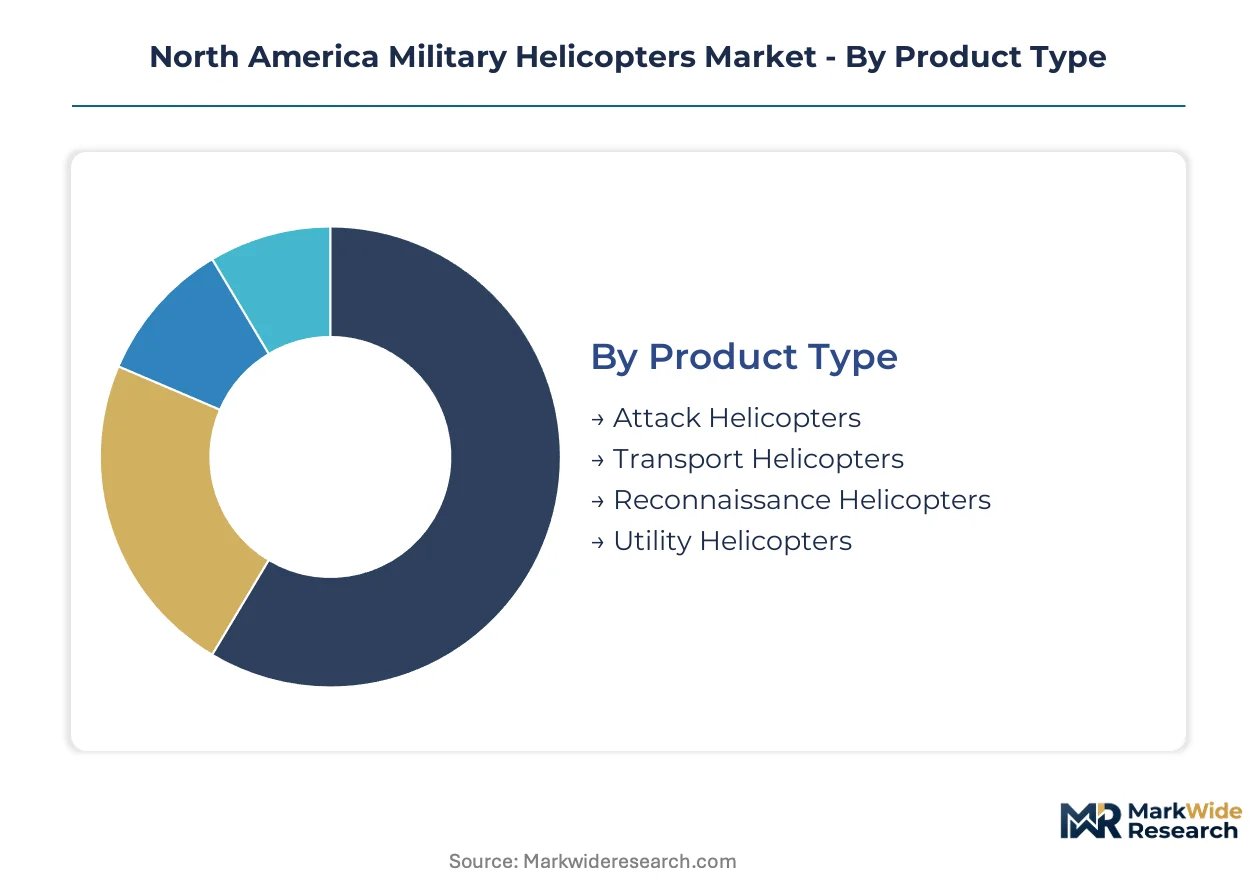
Segmentation reveals how procurement budgets fragment across mission profiles and technical architectures. Attack helicopters command premium unit costs while utility variants drive fleet volume. Understanding these splits exposes where suppliers compete on performance versus where they compete on sustainment economics.
Product Type:
Capital intensity peaks with attack platforms requiring integrated armor and weapons systems, while utility categories spread fixed costs across higher production runs.
- Attack Helicopters:These platforms integrate chain guns, anti-tank missiles, and sensor fusion suites into armored airframes. The southwestern United States concentrates demand where test ranges validate nap-of-earth tactics against simulated air defenses.
- Utility Helicopters:Modular cabins accommodate troop transport, cargo sling-loads, and medical evacuation configurations with minimal reconfiguration. Air National Guard units across Arizona and Texas corridors sustain replacement cycles for these workhorse fleets.
- Transport Helicopters:Heavy-lift architectures require dual-engine redundancy and extended-range fuel systems for battalion-scale movements.
- Reconnaissance Helicopters:Lightweight airframes prioritize sensor payload capacity over armor protection for stealthy battlefield surveillance.
Utility helicopters absorb the bulk of installed capacity; attack helicopters are expanding most quickly.
Technology:
Development cost structures diverge sharply between mature propulsion systems and emerging flight control architectures requiring software certification.
- Composite Materials:Carbon-fiber rotor blades and fuselage structures reduce radar cross-section while extending component life cycles. Manufacturing clusters in Connecticut and Texas attract specialized autoclave tooling suppliers serving both military and adjacent commercial programs.
- Fly-by-Wire:Digital flight control systems replace mechanical linkages with triple-redundant electronic channels. FAA Part 29 Special Conditions impose software assurance requirements that extend validation timelines for manufacturers pursuing civil-military dual certification.
- Turboshaft Engines:High-output powerplants dominate propulsion with established overhaul intervals and depot repair networks.
- Avionic Systems:Modular mission computers enable rapid sensor upgrades without airframe modification.
Composite materials adoption is climbing the fastest; turboshaft engines retain the largest installed base.
End User:
Procurement authority fragmentation creates distinct contracting rhythms between federal program offices and state-level Guard bureaus.
- Military Forces:Active-duty Army aviation brigades prioritize next-generation rotorcraft through Future Vertical Lift program channels. Congressional appropriations committees shape multi-year procurement schedules for these high-visibility acquisitions.
- Air National Guard:State-funded units balance federal mission requirements with governor-directed emergency response roles. Southwestern states leverage integrated training corridors to maximize readiness per flight hour.
- Special Operations:Classified requirements drive rapid fielding of modified platforms outside standard acquisition milestones.
- Government Agencies:Border patrol and counter-narcotics missions generate demand for surveillance-configured rotorcraft with extended loiter endurance.
Military forces command the dominant share of procurement volume; special operations is gaining share fastest.
Application:
Mission-criticality determines spare parts stocking strategies and contractor logistics support terms across operational categories.
- Combat Operations:Armed assault and close air support missions demand hardened airframes with redundant flight systems. DoD acquisition reform enables rapid prototyping of experimental configurations for contested airspace penetration.
- Medical Evacuations:Dedicated cabin configurations for casualty transport require rapid ingress-egress doors and life-support equipment mounts. Training corridors in the southwestern United States integrate MEDEVAC procedures into combined arms exercises.
- Search & Rescue:Hoist-equipped variants operate across maritime and mountain environments with specialized weather radar.
- Logistics Support:External cargo hook systems enable supply runs to forward operating bases without landing zone preparation.
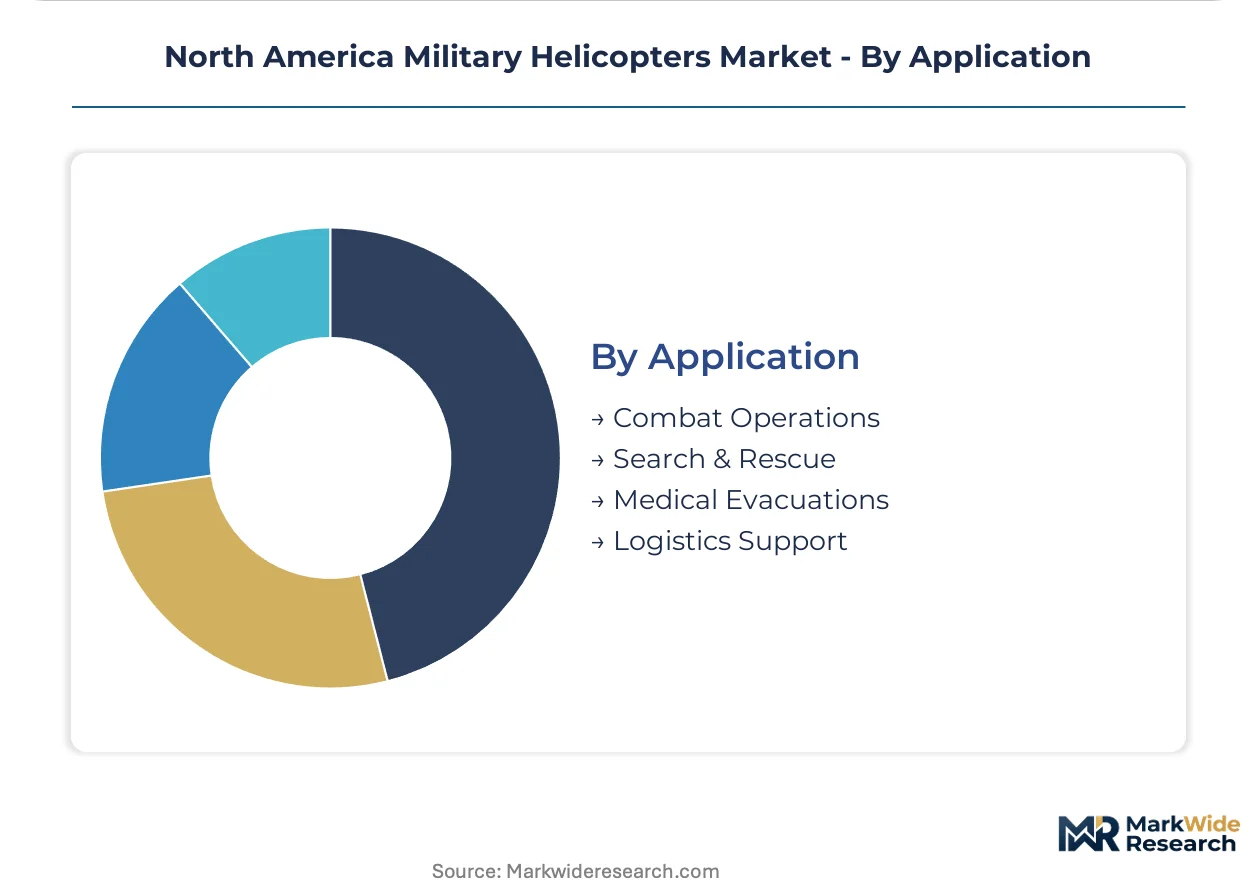
Combat operations dominates budget allocation; medical evacuations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium alloy supply from Canadian mining operations feeds southwestern US manufacturing corridors where rotorcraft production clusters. Arizona and Texas test ranges anchor validation infrastructure for next-generation platforms.
United States
The US Army's Future Vertical Lift program drives procurement of attack and utility variants across Arizona and Texas training corridors. FAA Part 29 airworthiness standards and DoD acquisition reform shape certification timelines for digitally-certified platforms. Connecticut engineering bases sustain heavy-lift development while southwestern manufacturing clusters attract specialized composite tooling suppliers.
Canada
NORAD modernization drives demand for cold-weather utility helicopters with extended-range fuel systems across Arctic patrol routes. Ottawa's defense procurement aligns with continental security frameworks under bilateral agreements. Quebec and Ontario manufacturing facilities support cross-border supply chains for turboshaft engine components.
Mexico
Naval aviation expansion for counter-narcotics missions generates demand for shipboard-capable helicopters with corrosion-resistant coatings. Pacific and Gulf coast bases present fleet renewal opportunities under security cooperation frameworks. Northern border states concentrate maintenance depots serving continental rotorcraft logistics networks.
North America Military Helicopters Market Competitive Landscape
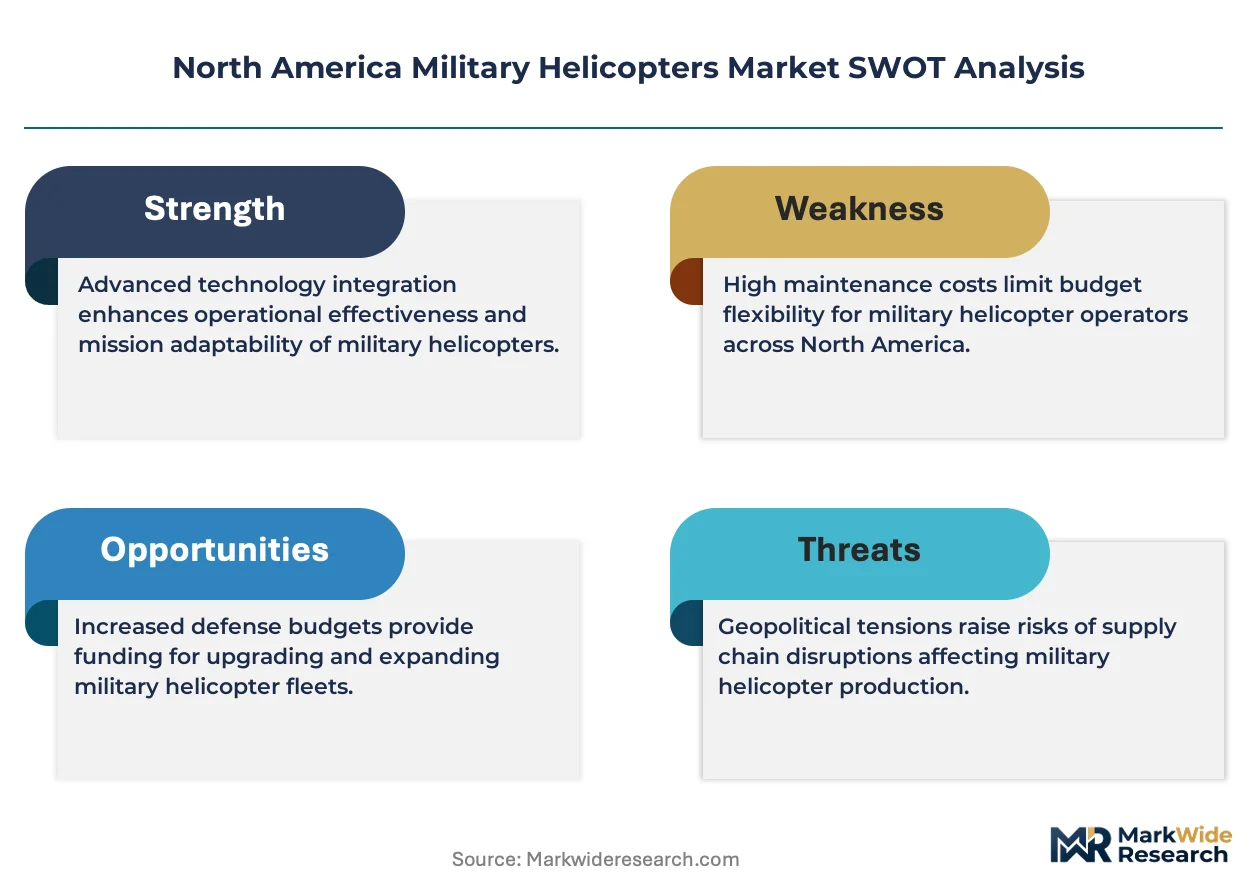
Established producers occupy the standard tier; emerging entrants pursue specialized mission system integration. The vendor base concentrates around three dominant airframe manufacturers with entrenched DoD relationships. Two strategic archetypes define competitive positioning: vertically integrated platform builders and modular subsystem specialists. Consolidation pressure intensifies as program offices demand open-system architectures that erode proprietary avionics lock-in.
Within the integrated platform tier, Lockheed Martin Corporation and The Boeing Company exemplify full-spectrum defense contractors with rotorcraft divisions. Sikorsky Aircraft Corporation occupies a position as a heritage manufacturer with deep Army aviation relationships. These three entities represent the dominant competitive anchors as program offices unbundle airframe acquisition from sustainment services through performance-based logistics contracts.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| The Boeing Company |
| Airbus SE |
| Textron Inc. |
| Leonardo S.p.A. |
| Bell Textron Inc. |
| Sikorsky Aircraft Corporation |
| MD Helicopters LLC |
| Northrop Grumman Corporation |
| Others |
Value Network & Pricing Analysis
Composite airframe technician concentrations across Arizona and Texas manufacturing corridors feed directly into pricing-tier spreads, as labor-cost differentials between certified bonded-structure specialists and conventional metalworkers widen the gap between premium fly-by-wire platforms and standard utility configurations.
Pricing Analysis
Performance-based logistics contracts unbundle airframe acquisition from sustainment services, shifting procurement toward flight-hour purchasing rather than spare parts ownership. Price differentiation rests on certification grade—FAA Part 29 dual-use platforms command premiums over military-only variants—while margins tighten in utility categories where Air National Guard units prioritize lowest total ownership cost. Attack helicopter configurations show least price sensitivity due to anti-armor mission criticality; reconnaissance variants face acute budget pressure from sensor payload cost escalation.
Supply Chain Analysis
Skilled workforce availability in Connecticut engineering bases and southwestern production clusters constrains parallel development of multiple rotorcraft programs. Manufacturing draws from titanium alloy feedstock out of Canadian mining operations, carbon-fiber prepeg from domestic autoclave facilities, and high-output turboshaft castings concentrated among single-source domestic propulsion houses. Single-source engine dependencies create acute program schedule vulnerabilities. Distribution runs through prime contractor logistics support networks with depot maintenance concentrated in Texas and Arizona corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America military helicopters market sits in a technology-transition phase as fly-by-wire flight control architectures displace mechanical linkage systems across attack and heavy-lift segments.
For Market Incumbents: To counter open-system architecture mandates from Future Vertical Lift program offices, Sikorsky Aircraft Corporation and Bell Textron Inc. must abandon proprietary avionics lock-in and accelerate modular mission computer adoption. Backward integration into carbon-fiber rotor blade manufacturing secures supply continuity as Arizona tooling clusters reach capacity constraints. Certification investment in FAA Part 29 Special Conditions for civil-military dual use preserves pricing premiums in heavy-lift categories. For New Entrants and Emerging Players: The price-point gap between premium sensor-fused attack platforms and economy utility configurations offers entry space for subsystem specialists targeting reconnaissance helicopter modernization. Mexican naval aviation expansion for counter-narcotics missions presents the most penetrable geography, with corrosion-resistant coating capabilities as the decisive go-to-market wedge. NORAD Arctic patrol requirements in Canada reward cold-weather fuel system expertise over full airframe development. For Investors and Strategic Acquirers: Re-rating potential sits with modular avionics integrators given DoD acquisition reform acceleration of rapid prototyping pathways. Long-term viability over the projection horizon favors suppliers with demonstrated MIL-STD-810 environmental testing capacity rather than pure airframe assemblers. The inflection signal to watch is congressional appropriations timing for Future Vertical Lift program tranches, which determines subcontractor order visibility.| Strategic Initiative | Industry Significance |
|---|---|
| Open-System Architecture Adoption | Modular mission computers enable rapid sensor upgrades without airframe redesign, satisfying Future Vertical Lift mandates. |
| Composite Manufacturing Scale-Up | Carbon-fiber rotor blade capacity expansion in Arizona corridors reduces radar cross-section while extending component life cycles. |
| Performance-Based Logistics Contracting | Flight-hour purchasing models shift sustainment risk to contractors and concentrate revenue in southwestern depot networks. |
| Civil-Military Dual Certification | FAA Part 29 compliance unlocks commercial heavy-lift markets and commands pricing premiums over military-only variants. |
| Predictive Maintenance Platform Development | AI-enabled vibration monitoring contracts separate data-analytics services from hardware acquisition, creating recurring revenue streams. |
Research Methodology
Multi-period observation of congressional appropriations patterns, FAA certification timelines, and DoD program milestone schedules anchored the trend analysis, supplemented by interviews with Army aviation program executives, composite manufacturing plant managers, Air National Guard procurement officers, and turboshaft engine depot maintenance directors. Secondary validation drew from FAA Part 29 airworthiness directives, DoD acquisition reform policy memoranda, SEC 10-K filings from prime contractors, and congressional defense authorization act text. Bottom-up triangulation across platform-level procurement data and top-down reconciliation against federal budget authority figures ensured consistency.
Input-output matrices mapped turboshaft engine supply capacity against attack and utility helicopter production schedules across the projection horizon. Segmentation dimensions modeled include product type, technology adoption curve, end-user procurement authority, and application mission criticality. CAGRs derived from fitted curves on historical program expenditure patterns, adjusted for announced Future Vertical Lift acceleration timelines. Industry-specific forecast inputs incorporated MIL-STD-810 test range scheduling constraints and composite technician certification pipeline throughput.
Inputs from prime contractor earnings disclosures and congressional budget justification documents were available through the study window; gaps in classified special operations procurement introduce uncertainty bands in reconnaissance segment projections. Forecasts reflect documented assumptions on program acceleration rates and supply chain capacity expansion. A small set of triggers—FAA Part 29 rulemaking delays, turboshaft engine single-source disruptions, and congressional continuing resolution impacts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Landing Gear Market
Aircraft
Air Speed Indicator Market
Aircraft
GCC Business Jet Market
Aircraft
Hybrid Aircraft Market
Aircraft
Asia-Pacific Heavy-Lift Helicopter Market
Aircraft
Aircraft Cargo Container Market
Aircraft
Asia-Pacific Business Jet Market
Aircraft
Europe Business Jet Market
Aircraft
Commercial Aircraft Lighting Market
Aircraft
Small Evtol Aircraft Market
Aircraft
North America Aviation Market
Aircraft
Aerospace Winglet System Market
Aircraft
Tilt Rotor Aircraft Market
Aircraft
Aircraft Hangar Market
Aircraft
Aircraft Flight Control Computers Market
Aircraft
Aviation Market