
 Defense Tactical Computers Market | 2026-2036
Defense Tactical Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Defense Tactical Computers Market Analysis
Specialized embedded systems engineering talent is reorganizing how prime contractors and subsystem suppliers allocate development resources across the defense electronics base. General Dynamics Corp. leverages its deep integration with U.S. Army ground vehicle programs to sustain long-term production pipelines for rack-mountable command systems. BAE Systems Plc anchors European demand through its dominance in UK and Swedish armored vehicle electronics. Elbit Systems Ltd. competes aggressively in the ruggedized handheld segment, particularly across Israel Defense Forces modernization cycles and allied export programs.
Defense tactical computers are hardened computing platforms engineered to operate across temperature extremes, shock, vibration, and electromagnetic interference, typically conforming to MIL-STD-810 environmental standards and MIL-STD-461 electromagnetic compatibility requirements for battlefield command, sensor fusion, and real-time data processing. Ruggedized technology occupies the largest installed base due to decades of proven deployment across ground and naval platforms, while AI-enhanced systems represent the fastest-expanding margin pool as militaries embed machine learning for predictive maintenance and automated threat classification. Embedded product types lead in unit volume within armored vehicle architectures, whereas portable configurations capture growing share among dismounted soldier programs requiring reduced size, weight, and power.
The U.S. Department of Defense enforces MOSA compliance through acquisition regulations, forcing suppliers toward modular architectures that accelerate technology refresh and reduce vendor lock. NATO's STANAG interoperability standards shape transatlantic procurement, with E.U. defense agencies increasingly referencing CE marking and EU AI Act risk classifications for autonomous targeting subsystems. Stakeholders must monitor how export control harmonization between the U.S. International Traffic in Arms Regulations and emerging EU defense procurement frameworks affects cross-border subsystem integration timelines.
Market Dynamics
The U.S. Department of Defense's MOSA mandate is forcing subsystem suppliers to abandon proprietary architectures in favor of modular interfaces that accelerate technology refresh cycles and erode long-standing vendor lock-in advantages across military procurement channels.
Growth Catalysts
- AI-Enhanced Targeting Subsystems:NATO member states are embedding machine learning into armored vehicle electronics for automated threat classification, creating demand for edge-computing platforms that process sensor fusion in real time.
- MIL-STD-810H Compliance Mandates:The latest environmental testing standard revision is accelerating replacement cycles for legacy tactical computers that cannot meet expanded shock and vibration thresholds.
- Swedish Armored Vehicle Modernization:Sweden's CV90 fleet upgrade program is generating sustained procurement pipelines for ruggedized command-and-control electronics through 2030.
Market Restraints
- Semiconductor Supply Concentration:Advanced node fabrication for radiation-hardened processors concentrates in a single East Asian supplier base, exposing defense primes to geopolitical disruption risk.
- ITAR Export Friction:The U.S. International Traffic in Arms Regulations creates multi-month licensing delays for cross-border subsystem integration, compressing program timelines for allied procurement.
- Power Density Limitations:Thermal management constraints in sealed, fanless enclosures cap processing performance for dismounted soldier applications below commercial-equivalent benchmarks.
Strategic Opportunities
- Australian Land 400 Program:Phase 3 vehicle procurement is creating openings for non-U.S. suppliers to establish MOSA-compliant subsystem footprints in a Five Eyes ally with limited domestic electronics manufacturing.
- EU AI Act Risk Classification:The European Union's regulatory framework for autonomous targeting systems is creating tiered compliance pathways that favor suppliers with pre-certified algorithmic transparency documentation.
- 5G Military Waveform Convergence:Integration of tactical edge computing with private 5G networks is enabling new dismounted soldier applications that bypass traditional vehicle-mounted infrastructure.
Industry Challenges
- Embedded Systems Talent Scarcity:Defense electronics primes face acute shortages of engineers proficient in both real-time operating systems and MOSA interface standards.
- Cross-Domain Certification Complexity:Suppliers must simultaneously satisfy U.S. Army ground vehicle, U.S. Navy shipboard, and NATO STANAG electromagnetic compatibility requirements, multiplying test cycle duration.
- Legacy Bus Architecture Integration:New modular systems must maintain backward compatibility with MIL-STD-1553 data buses that persist in fielded platforms despite four-decade-old bandwidth limitations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Defense Tactical Computers Market |
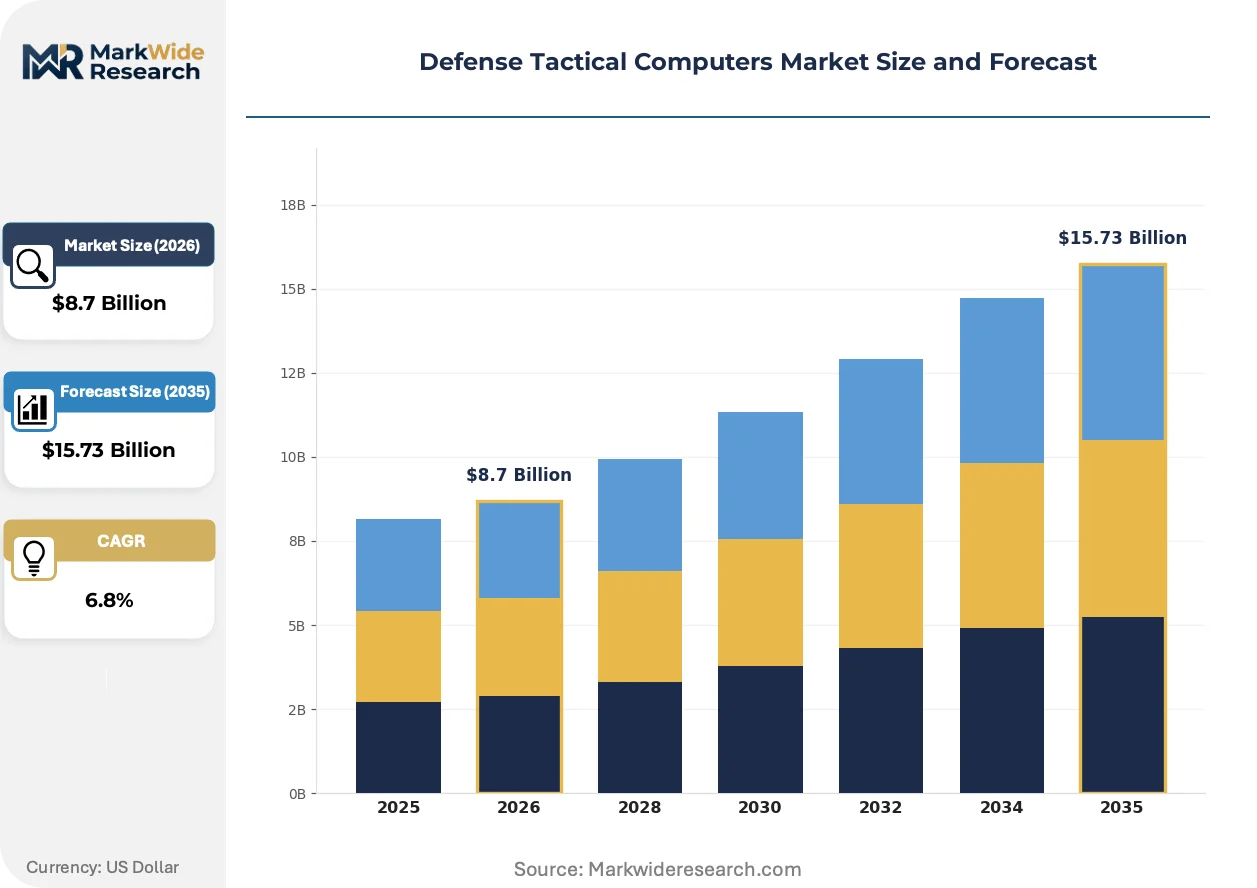
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Rack-Mountable, Embedded, Handheld Technology: AI-Enhanced, Ruggedized, Cloud-Mapped, IoT-Enabled End User: Military, Government Agencies, Defense Contractors, Law Enforcement Application: Situational Awareness, Command Control, Data Analysis, Simulation |
| Companies Covered | BAE Systems Plc, General Dynamics Corp., Elbit Systems Ltd., Leonardo Spa, Curtiss-Wright Corp., Honeywell International Inc., Mercury Systems Inc., Saab AB, Cornet Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Defense Tactical Computers Market Emerging Trajectories
Battlefield computing architectures are fragmenting along two paths: centralized vehicle-mounted processing for armored formations and distributed edge nodes for dismounted operations, with AI inference capabilities determining competitive positioning in both segments.
Modular open systems architecture is decomposing traditional vertically integrated supply chains by mandating standardized interfaces between computing, communications, and sensor subsystems. U.S. Army ground vehicle program offices are requiring MOSA compliance in all new procurements, compressing margins for suppliers that previously captured value through proprietary integration. This decomposition is enabling smaller subsystem specialists to compete for slots once reserved to prime contractors.
The EU AI Act's risk classification framework for autonomous weapon subsystems is reshaping European procurement documentation requirements. Defense agencies in Germany and France now mandate algorithmic explainability assessments for targeting computers that incorporate machine learning, extending vendor qualification timelines. Suppliers with pre-established technical documentation pipelines are capturing preferential evaluation status in E.U. defense tenders.
Allied defense ministries are consolidating tactical computer procurement through framework agreements that bundle hardware, software, and sustainment into single-vendor relationships. The UK Ministry of Defence's Land Systems operating model is displacing transactional component purchasing with decade-long integrated support contracts. This consolidation is most visible in NATO's eastern flank, where Poland and Romania are adopting similar bundled procurement structures to accelerate interoperability with U.S. formations.
Defense Tactical Computers Market Segmentation
Segmentation in defense tactical computers reveals how procurement priorities diverge between established platform integrators and emerging subsystem specialists. Each dimension exposes distinct compliance burdens, margin structures, and technology refresh cycles that reshape competitive positioning across NATO allied programs.
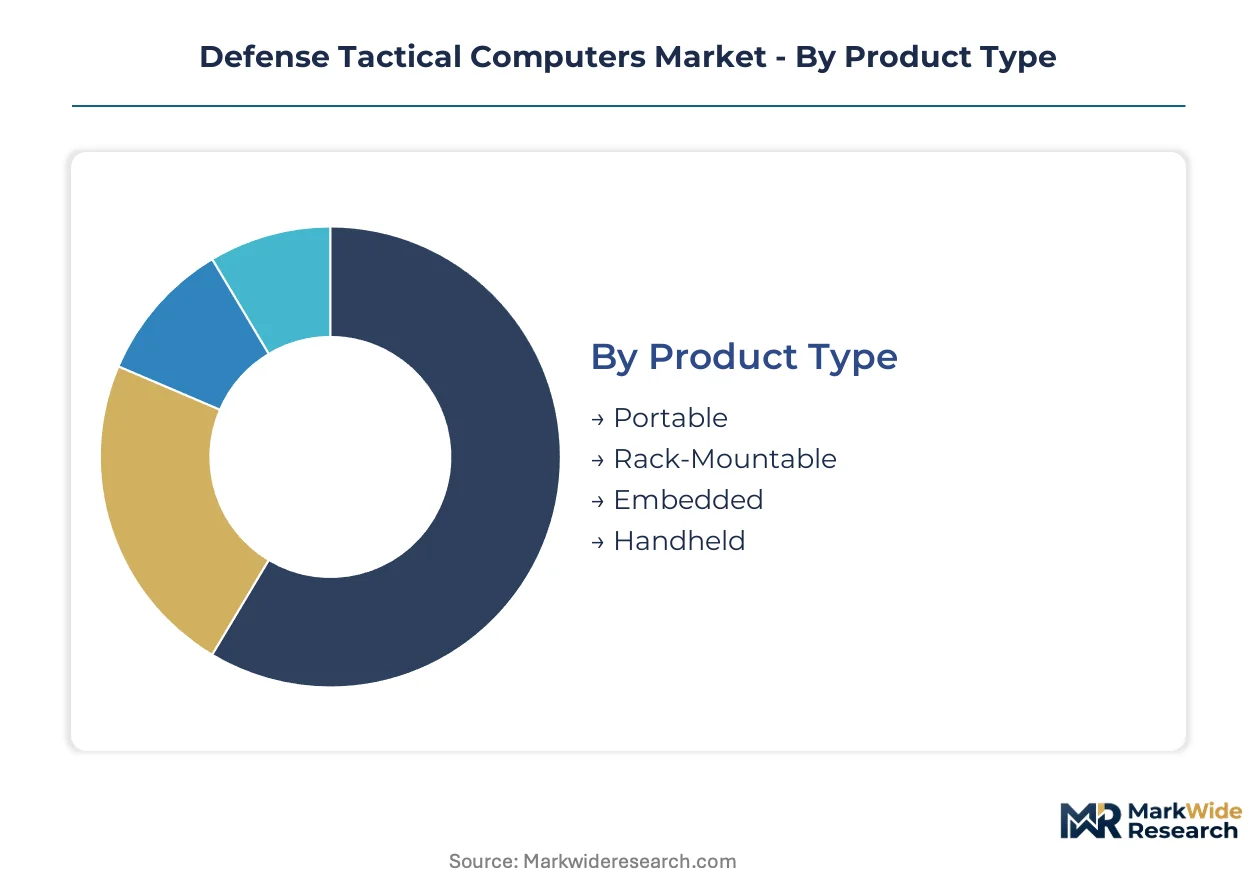
Product Type:
Domestic procurement concentrates in vehicle-mounted configurations across U.S. Army and European armored programs, while export-led demand drives portable and handheld variants for coalition partner dismounted soldier modernization.
- Rack-Mountable:These chassis-based systems integrate into armored vehicle hulls with MIL-STD-810H shock isolation and conduction cooling. U.S. Army ground vehicle programs anchor procurement through prime contractor relationships with decade-long production pipelines.
- Embedded:Compact compute modules mount directly into weapon systems and sensor suites with real-time operating system architectures. German and Swedish armored vehicle electronics programs sustain the densest procurement concentration as CV90 and Leopard fleet upgrades accelerate.
- Portable:Briefcase and tablet configurations serve forward command posts with reduced size, weight, and power constraints. Australian Land 400 Phase 3 vehicle procurement creates openings for MOSA-compliant subsystem integration.
- Handheld:Palm-sized units support dismounted soldier networks with sealed fanless enclosures. Israeli Defense Forces modernization cycles and allied export programs drive competitive intensity in this segment.
Rack-mountable systems command the established base. The steepest expansion runs through embedded modules as AI inference migrates to sensor-edge architectures.
Technology:
Cost tier stratification separates premium AI-enhanced platforms from baseline ruggedized systems, with algorithmic certification documentation becoming a decisive bid evaluation factor in EU defense tenders.
- Ruggedized:Hardened electronics withstand temperature extremes, vibration, and electromagnetic interference per MIL-STD-461 requirements. Decades of field deployment across NATO ground and naval platforms sustain this segment's installed base dominance.
- AI-Enhanced:Edge-computing platforms embed machine learning accelerators for predictive maintenance and automated threat classification. The EU AI Act's risk classification framework mandates algorithmic explainability assessments that extend vendor qualification timelines for suppliers lacking pre-established documentation pipelines.
- Cloud-Mapped:Distributed architectures link tactical edge nodes to rear-echelon processing through military-grade waveforms. Five Eyes alliance interoperability requirements concentrate demand in U.S., UK, and Australian programs.
- IoT-Enabled:Sensor fusion networks aggregate platform health and environmental data for fleet-wide analytics. Private 5G military waveform convergence enables new dismounted soldier applications bypassing traditional vehicle infrastructure.
Ruggedized technology retains volume leadership. AI-Enhanced configurations are climbing the fastest as militaries embed machine learning for real-time decision support.
End User:
Customer type determines contract structure, with military end users demanding integrated support agreements while defense contractors prioritize component sourcing flexibility for system integration programs.
- Military:Armed forces procurement dominates unit volume through framework agreements bundling hardware, software, and sustainment. The UK Ministry of Defence's Land Systems operating model exemplifies the shift from transactional purchasing to decade-long integrated support contracts.
- Defense Contractors:Subsystem suppliers purchase computing modules for integration into larger weapon system architectures. The U.S. Department of Defense's MOSA mandate forces these integrators toward modular interfaces that erode proprietary vendor lock-in advantages.
- Government Agencies:Border security and intelligence organizations procure specialized configurations for fixed-site and deployable operations. Poland and Romania are adopting bundled procurement structures to accelerate interoperability with U.S. formations.
- Law Enforcement:Tactical units acquire ruggedized portable systems for special operations and crisis response. Domestic procurement concentrates in national police modernization programs with limited cross-border standardization.
Military end users command the established base. The steepest expansion runs through defense contractors as MOSA decomposition enables smaller subsystem specialists to compete for slots once reserved to primes.
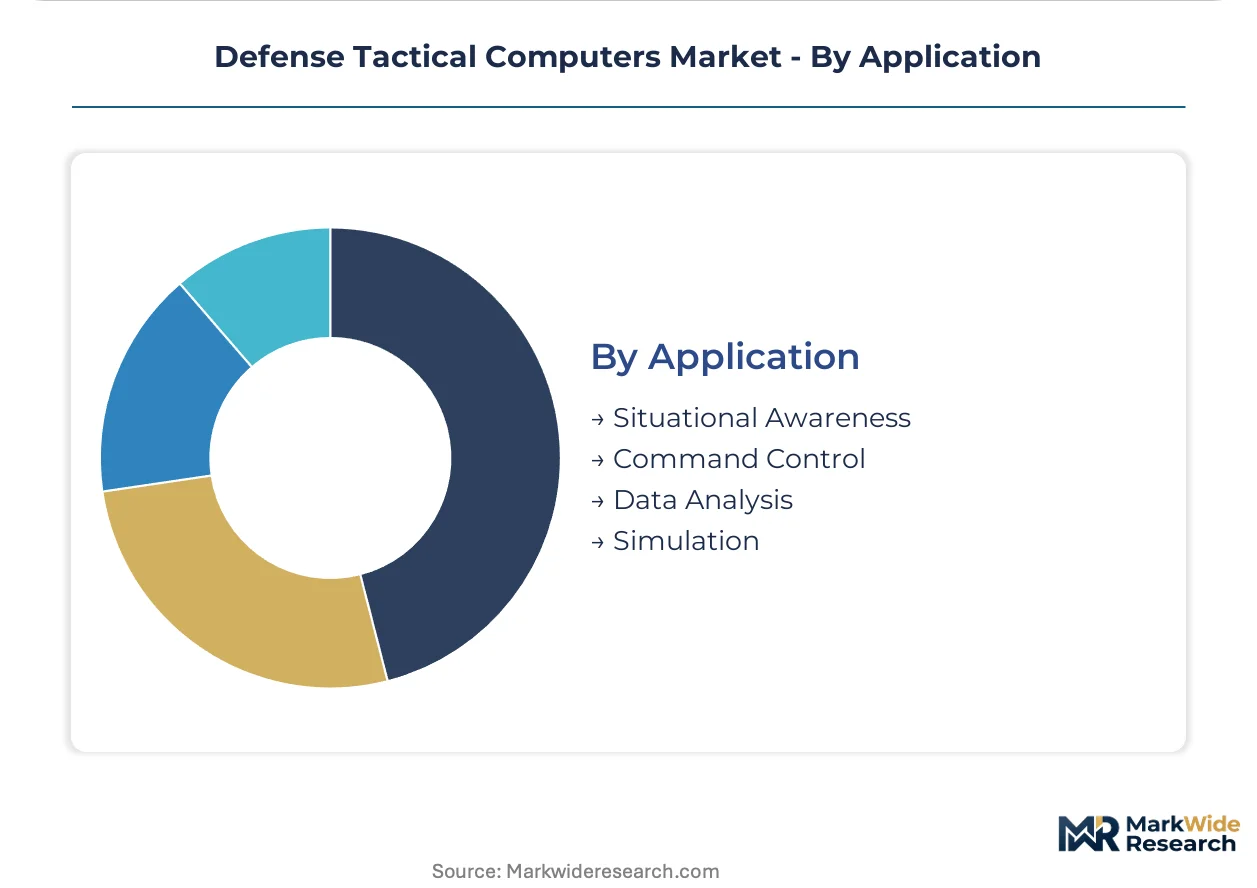
Application:
Application maturity stratifies between battlefield-proven command functions and emerging simulation workloads that demand commercial-equivalent processing performance within sealed military enclosures.
- Command Control:Battle management systems coordinate force movements and fire support with hardened networking stacks. NATO STANAG interoperability standards shape transatlantic procurement alignment across U.S., German, and Australian programs.
- Situational Awareness:Sensor fusion platforms aggregate radar, electro-optical, and signals intelligence into unified tactical displays. Thermal management constraints in sealed enclosures cap processing performance below commercial benchmarks for dismounted soldier applications.
- Data Analysis:Post-mission processing and intelligence exploitation require storage-intensive configurations with removable media security features. Export control harmonization between ITAR and emerging EU defense procurement frameworks affects cross-border subsystem integration timelines.
- Simulation:Training systems replicate combat environments with graphics-intensive processing demands. Power density limitations in fanless tactical enclosures constrain adoption compared to vehicle-mounted alternatives.
Command control applications command the established base. The steepest expansion runs through situational awareness as AI-enhanced sensor fusion migrates to armored vehicle electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Department of Defense anchors procurement volume through MOSA-mandated acquisition regulations that reshape supplier compliance requirements across allied defense electronics programs.
United States
U.S. Army ground vehicle programs drive sustained demand for rack-mountable command systems with decade-long production pipelines. The Department of Defense enforces modular open systems approach compliance through acquisition regulations, forcing subsystem suppliers toward standardized interfaces. Huntsville, Alabama's defense electronics cluster hosts prime contractor integration facilities supporting armored vehicle modernization.
Germany
Leopard fleet upgrades and armored vehicle electronics programs sustain dense procurement concentration for embedded compute modules. The EU AI Act's risk classification framework mandates algorithmic explainability assessments for targeting computers with machine learning. Bavaria's defense industrial base around Munich and Augsburg hosts subsystem specialists serving NATO STANAG interoperability requirements.
Australia
Land 400 Phase 3 vehicle procurement creates openings for non-U.S. suppliers to establish MOSA-compliant subsystem footprints in a Five Eyes ally. The country's defense procurement framework emphasizes interoperability with U.S. formations through aligned battlefield network standards. South Australia's defense technology precinct near Adelaide concentrates vehicle electronics integration activity.
Sweden
CV90 fleet upgrade programs generate sustained procurement pipelines for ruggedized command-and-control electronics through 2030. Swedish defense procurement aligns with NATO STANAG standards while maintaining national industrial participation requirements. Stockholm's aerospace and defense cluster hosts BAE Systems' armored vehicle electronics operations serving Nordic and export markets.
Israel
Israel Defense Forces modernization cycles drive competitive intensity in ruggedized handheld tactical computer segments for dismounted soldier networks. The country's defense export control framework shapes cross-border subsystem integration timelines for allied procurement programs. Tel Aviv's defense technology corridor concentrates handheld systems engineering talent and rapid prototyping capabilities.
Defense Tactical Computers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with prime contractors commanding long-term production pipelines while subsystem suppliers compete for modular slots. The structure tilts toward consolidation in vehicle-mounted systems and fragmentation in portable configurations. Two archetypes dominate: vertically integrated defense primes with platform relationships, and MOSA-compliant subsystem specialists leveraging standardized interfaces. Competitive moves center on strategic partnerships for technology refresh acceleration and portfolio diversification into AI-enhanced edge computing.
Among U.S.-based integrated primes, General Dynamics Corp. and Curtiss-Wright Corp. occupy positions anchoring domestic armored vehicle electronics procurement. BAE Systems Plc exemplifies the European prime archetype with platform integration relationships across UK and Swedish programs. Elbit Systems Ltd. represents the specialist tier's aggressive export-oriented model in handheld and dismounted soldier segments.
| Leading Market Players |
|---|
| BAE Systems Plc |
| General Dynamics Corp. |
| Elbit Systems Ltd. |
| Leonardo Spa |
| Curtiss-Wright Corp. |
| Honeywell International Inc. |
| Mercury Systems Inc. |
| Saab AB |
| Cornet Technology Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term integrated support contracts lock in supply access and price visibility for defense tactical computers, binding prime contractors to decade-long hardware-sustainment bundles that insulate procurement from spot-market volatility while compressing margins for subsystem suppliers lacking similar contractual anchors.
Pricing Analysis
Price spreads between U.S. and European procurement run 15-25% for equivalent MIL-STD-810H configurations, reflecting ITAR compliance overhead and localized certification requirements. Three-tier pricing structure across mission-critical, standard ruggedized, and legacy support tiers dominates, with differentiation driven by AI-enhanced processing capability and algorithmic transparency documentation under EU AI Act frameworks. Cost compression in standard ruggedized tiers intensifies as MOSA compliance erodes proprietary integration premiums. Defense contractors exhibit highest price sensitivity due to compressed program margins, while military end users prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Inbound logistics costs for radiation-hardened processors spike during East Asian port congestion episodes, with container availability constraints on transpacific lanes extending lead times for advanced node fabrication. Supply concentrates in Taiwan for leading-edge foundry capacity, the United States for defense-qualified packaging, and Germany for precision thermal management components. Raw material dependencies span gallium nitride substrates, high-reliability capacitors, and conformal coating chemistries. Single-source vulnerability in advanced semiconductor lithography equipment feeds from export control restrictions under U.S. ITAR and emerging EU defense procurement frameworks. Distribution runs through prime contractor integration facilities rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The defense tactical computers market represents high-growth disruption as AI inference migration to sensor-edge architectures redefines competitive positioning, with the U.S. Department of Defense's MOSA mandate accelerating technology refresh cycles and decomposing vertically integrated supply chains.
For Market Incumbents: Consolidate platform integration relationships through exclusive decade-long support contracts that preempt MOSA-driven supplier substitution. Deepen backward integration into radiation-hardened processor packaging to offset single-source foundry risk. Lock in embedded systems engineering talent pools in Huntsville and Munich defense clusters before capability scarcity intensifies qualification timelines. For New Entrants and Emerging Players: Anchor in Australian Land 400 Phase 3 vehicle procurement as a Five Eyes entry point with limited domestic electronics manufacturing and explicit MOSA compliance requirements. Target dismounted soldier handheld segments where Israeli Defense Forces export programs create non-U.S. supplier openings. Pursue algorithmic transparency pre-certification under EU AI Act risk classifications to capture preferential evaluation status in German and French tenders. For Investors and Strategic Acquirers: MOSA-compliant subsystem specialists with pre-established STANAG certification pipelines represent the highest-conviction acquisition archetype for portfolio exposure to defense electronics modernization. Long-term viability hinges on sustained NATO allied spending alignment and successful navigation of ITAR-EU export control harmonization. Watch for EU AI Act enforcement patterns as the decisive inflection signal for algorithmic documentation capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| MOSA Compliance Certification | Unlocks prime contractor integration slots under U.S. Army acquisition regulations. |
| AI Accelerator Integration | Captures fastest-expanding margin pool in armored vehicle sensor-edge architectures. |
| EU AI Act Pre-Certification | Accelerates vendor qualification timelines in German and French defense tenders. |
| Five Eyes Market Entry | Establishes subsystem footprints in Australian Land 400 and allied export programs. |
| Radiation-Hardened Packaging Investment | Reduces single-source vulnerability in advanced node semiconductor supply. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of U.S. Department of Defense acquisition regulations, NATO STANAG documentation, and EU defense procurement frameworks. Primary interviews engaged program managers at U.S. Army ground vehicle offices, subsystem engineering directors at European armored vehicle primes, and procurement leads at Australian Defense Force. Secondary sources encompassed ITAR licensing databases, CE marking registries, and defense electronics trade flow records. Bottom-up unit demand modeling triangulated against top-down military budget allocation analysis.
Segmentation dimensions modeled span product type (rack-mountable, embedded, portable, handheld), technology tier (ruggedized, AI-enhanced, cloud-mapped, IoT-enabled), end user (military, defense contractor, government agency, law enforcement), and application (command control, situational awareness, data analysis, simulation). CAGRs derived from regression analysis of historical procurement cycles against projected platform modernization timelines. Industry-specific forecast inputs incorporated CV90 and Leopard fleet upgrade schedules alongside MOSA mandate implementation phasing.
Material uncertainties — semiconductor supply disruption, ITAR-EU regulatory friction, and AI Act enforcement variability — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained NATO allied spending alignment and successful technology refresh cycle acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Defense and Military Systems and Equipment
Mechanical and Electronic Fuzes Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Displays Market
Defense and Military Systems and Equipment
Mergers and Acquisitions (Manda) in Aerospace and Defense Market
Defense and Military Systems and Equipment
Military Load Carriage System Market
Defense and Military Systems and Equipment
Europe Defense Logistics Market
Defense and Military Systems and Equipment
Mission Management System Market
Defense and Military Systems and Equipment
Anti-Jamming Equipment Market
Defense and Military Systems and Equipment
Defense Integrated Antenna Market
Defense and Military Systems and Equipment
Cognitive Electronic Warfare System Market
Defense and Military Systems and Equipment
Radar Warning Receiver Market
Defense and Military Systems and Equipment
Bio-Defense Market
Defense and Military Systems and Equipment
United Kingdom Defense Market
Defense and Military Systems and Equipment
Global Battlefield Management System Market
Defense and Military Systems and Equipment
Military Helmet and Helmet Mounted Display Systems Market
Defense and Military Systems and Equipment
Middle East and Africa Defense Market
Defense and Military Systems and Equipment
Military Laser Systems Market