
 Aircraft Flight Control Computers Market | 2026-2036
Aircraft Flight Control Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Flight Control Computers Market Analysis
DO-254 and DO-178C certification tiers is redrawing supplier hierarchies in the aircraft flight control computers landscape. Honeywell International Inc. leverages its integrated avionics portfolio to dominate the fly-by-wire segment. Moog Inc. specializes in high-reliability electromechanical actuation interfaces that anchor military platform programs. Safran S.A. competes through European supply chain proximity and EASA certification depth.
Aircraft flight control computers are embedded computing platforms that process sensor inputs and execute control surface commands through digital or analog signal paths, typically operating with fault-tolerant architectures and redundant channels to meet 10^-9 probability-of-failure thresholds per flight hour. These systems serve as the central nervous system of modern aircraft, translating pilot or autopilot commands into aerodynamic response. Fly-by-wire systems command the largest value pool given their penetration in new commercial platforms, while FPGA-based technology segments attract R&D investment for deterministic latency performance. Maintenance service providers represent an expanding end-user channel as aging fleets require control computer overhaul and retrofit.
FAA certification under DO-254 and DO-178C governs hardware and software integrity levels for US-registered aircraft, while EASA CS-25 airworthiness standards enforce equivalent design assurance in Europe. China's CAAC harmonization with these standards shapes market access for foreign suppliers serving COMAC programs. Stakeholders must monitor regulatory divergence between FAA and EASA on autonomous flight control architectures as certification pathways for reduced-crew operations crystallize.
Market Dynamics
DO-254 and DO-178C certification requirements are compressing supplier timelines while fragmenting procurement authority between OEMs and tier-one integrators. This regulatory pressure is redrawing competitive boundaries across hardware and software domains.
Growth Catalysts
- FAA Certification Mandates:DO-254 hardware assurance levels and DO-178C software integrity tiers are forcing fleet upgrades and retrofit cycles across US-registered commercial aircraft.
- Commercial Fleet Expansion:Next-generation narrowbody and widebody programs are embedding fly-by-wire architectures as baseline configurations, expanding addressable hardware volumes.
- FPGA Determinism:Field-programmable gate arrays delivering sub-millisecond latency are displacing legacy processor-based control loops in safety-critical flight surface actuation.
Market Restraints
- Semiconductor Supply Concentration:Radiation-hardened and high-reliability chip fabrication concentrates in limited foundry capacity, creating single-source vulnerability for aerospace-grade components.
- Certification Cost Escalation:DO-254 Level A hardware verification and DO-178C Level A software validation require multi-year engineering cycles that lock out mid-tier suppliers.
- Electromechanical Actuator Substitution:Hydraulic backup systems retain preference in certain military platforms, limiting pure fly-by-wire penetration in defense end-uses.
Strategic Opportunities
- Urban Air Mobility:eVTOL manufacturers are procuring certifiable control computers before regulatory frameworks crystallize, creating first-mover supplier relationships.
- CAAC Harmonization:China's alignment with FAA and EASA standards is opening access for foreign suppliers to COMAC C919 and future indigenous programs.
- Retrofit Channel Expansion:Maintenance, repair, and overhaul providers are building in-house electronics capabilities to capture aging fleet control computer refurbishment demand.
Industry Challenges
- Embedded Software Talent Scarcity:DO-178C qualified engineers with safety-critical coding experience command premium compensation and extended recruitment timelines.
- Legacy System Integration Friction:Analog-to-digital interface complexity in partial fly-by-wire retrofits generates unexpected verification burden and schedule overruns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aircraft Flight Control Computers Market |
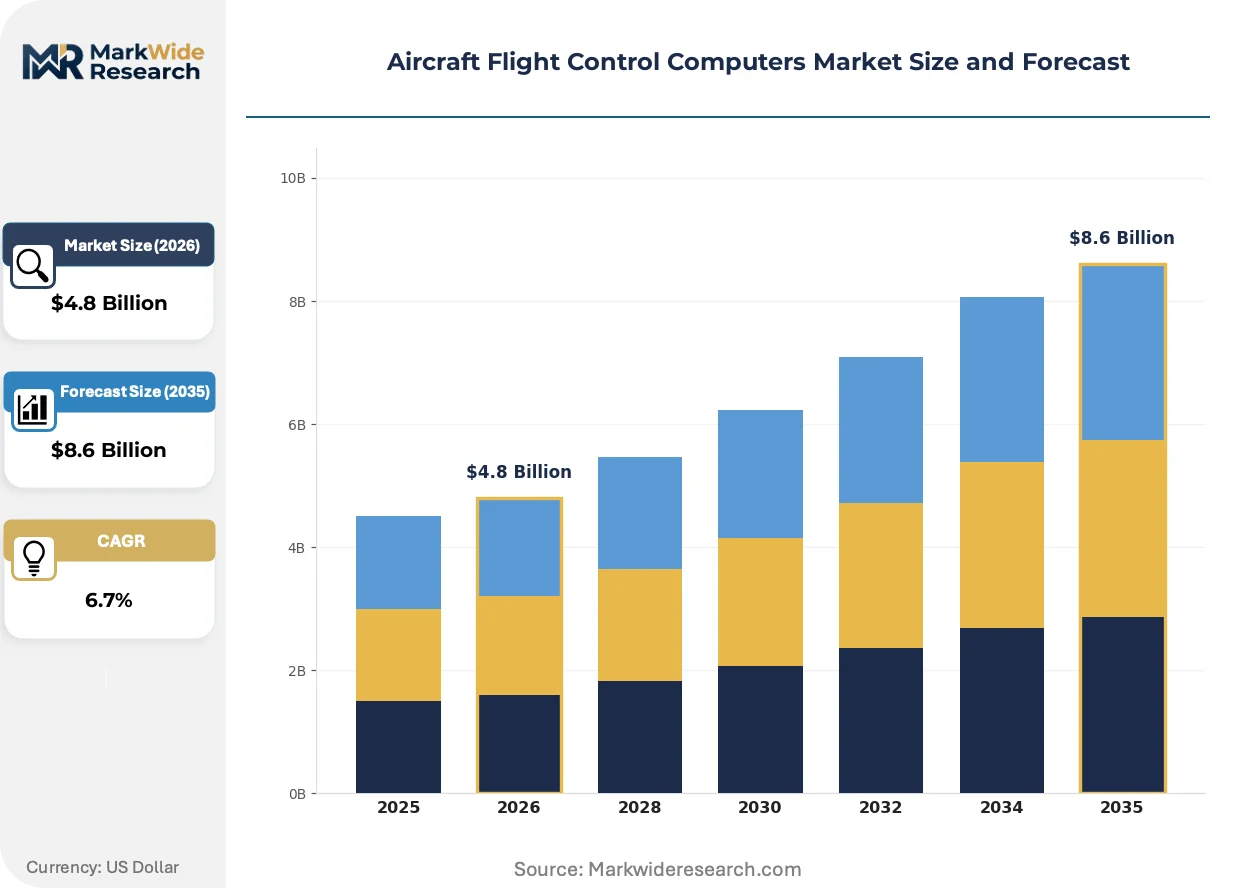
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Control Systems, Analog Control Systems, Fly-by-Wire Systems, Hydraulic Control Systems End User: Commercial Aviation, Military Aviation, Aerospace Manufacturers, Maintenance Service Providers Technology: Microprocessor-Based Systems, FPGA-Based Systems, DSP-Based Systems, Avionics Integration Application: Flight Stability, Navigation Control, Takeoff and Landing Assistance, Auto-Pilot Systems |
| Companies Covered | Curtiss-Wright Corporation, Moog Inc., Honeywell International Inc., Liebherr Group, Collins Aerospace, Safran S.A., Thales Group, Rockwell Collins-RTX Corporation, BAE Systems plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Flight Control Computers Market Emerging Trajectories
Control computer architectures are converging toward integrated modular avionics while certification methodologies lag hardware evolution. This tension is forcing concurrent engineering approaches that compress traditional development sequences.
Multi-core processors with partitioned operating systems are replacing single-core architectures in primary flight control applications. Commercial OEMs are adopting these platforms for weight and power reduction. The technology is miniaturizing enclosure volumes while maintaining fault isolation through hardware virtualization layers.
EASA CS-25 airworthiness standards are tightening software tool qualification requirements under ED-12C updates. This policy shift is extending verification timelines and increasing third-party tool vendor liability exposure. European suppliers are responding by bringing toolchains in-house to control certification risk.
Airline procurement teams are consolidating flight control computer sourcing under fleet-wide lifecycle contracts rather than airframe-program discrete purchases. This behavior compresses supplier margins while extending contractual service obligations. The shift is most pronounced among US-based network carriers with standardized narrowbody fleets.
Aircraft Flight Control Computers Market Segmentation
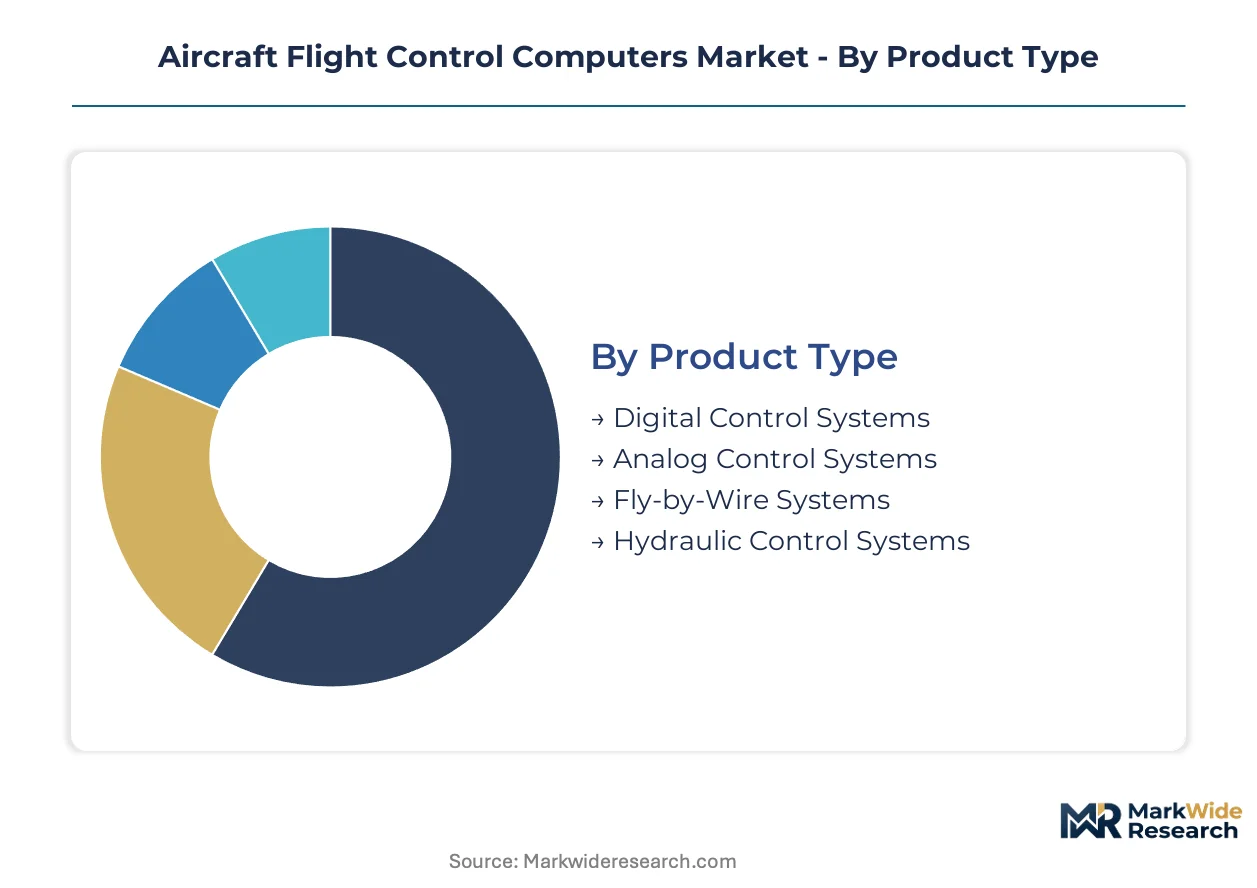
Segmentation in the aircraft flight control computers market reveals how procurement channels bifurcate between OEM airframe contracts and aftermarket retrofit flows. Understanding these pathways exposes margin concentration points and certification burden distribution across hardware categories.
Product Type:
Channel mix varies sharply: fly-by-wire systems flow through Boeing and Airbus direct procurement, while analog retrofits concentrate in MRO distributor networks serving aging regional fleets.
- Digital Control Systems:These architectures employ redundant processing channels with dissimilar hardware to prevent common-mode failures. Commercial narrowbody programs in the United States anchor procurement volumes as airlines modernize cockpit electronics under FAA-mandated ADS-B and related equipage rules.
- Fly-by-Wire Systems:Electronic flight control replaces mechanical linkages with data buses and servo actuators, demanding DO-254 Level A certification for all hardware elements. Airbus A320 family and Boeing 787 programs in France and the United States consume the dominant share of these systems, with suppliers embedding multi-year service contracts.
- Analog Control Systems:Legacy architectures persist in cargo conversions and regional turboprop fleets where certification grandfather rights reduce retrofit economics.
- Hydraulic Control Systems:Backup hydraulic channels remain mandatory in military platforms requiring battle damage tolerance, constraining pure fly-by-wire penetration in defense procurement.
By volume, Fly-by-Wire Systems leads. By growth pace, Digital Control Systems is ahead.
End User:
Cost tier stratification separates this category: military programs absorb premium pricing for radiation-hardened components while commercial airlines drive standardization for unit cost reduction.
- Commercial Aviation:Network carriers and low-cost operators constitute the largest addressable pool, with procurement consolidating under fleet-wide avionics upgrade programs. United States-based carriers with standardized Boeing 737 MAX and Airbus A320neo fleets are negotiating multi-year control computer supply agreements that bundle initial provisioning with rotable pool access.
- Military Aviation:Fighter and transport platforms demand extended temperature range operation and electromagnetic pulse hardening beyond commercial specifications. The United States Department of Defense primes—Lockheed Martin, Boeing Defense, Northrop Grumman—source through sole-source or limited-competition contracts with cost-plus fee structures.
- Aerospace Manufacturers:Tier-one integrators such as Spirit AeroSystems and GKN Aerospace procure control computers as subassemblies for airframe sections delivered to final assembly lines.
- Maintenance Service Providers:Lufthansa Technik, ST Engineering, and AAR Corp are building in-house electronics repair stations to capture control computer overhaul demand as warranty periods expire on delivered fleets.
Commercial Aviation commands the largest revenue share. Military Aviation carries the steepest expansion trajectory as modernization cycles accelerate.
Technology:
Volume concentration tracks with platform generation: microprocessor systems dominate current production, while FPGA platforms are displacing legacy architectures in new program bids.
- Microprocessor-Based Systems:Multi-core processors with partitioned operating systems enable weight reduction through integration of multiple control functions onto single hardware modules. Boeing 787 and Airbus A350 programs utilize these platforms extensively.
- FPGA-Based Systems:Field-programmable gate arrays deliver deterministic sub-millisecond latency required for primary flight surface actuation. eVTOL developers in the United States and Germany are procuring certifiable FPGA control computers ahead of regulatory framework crystallization.
- DSP-Based Systems:Digital signal processors handle sensor fusion tasks in navigation and stability augmentation loops.
- Avionics Integration:Integrated modular avionics architectures consolidate flight control with communication and surveillance functions, reducing line-replaceable unit count.
Microprocessor-Based Systems holds the installed base. FPGA-Based Systems is climbing the fastest as latency requirements tighten.
Application:
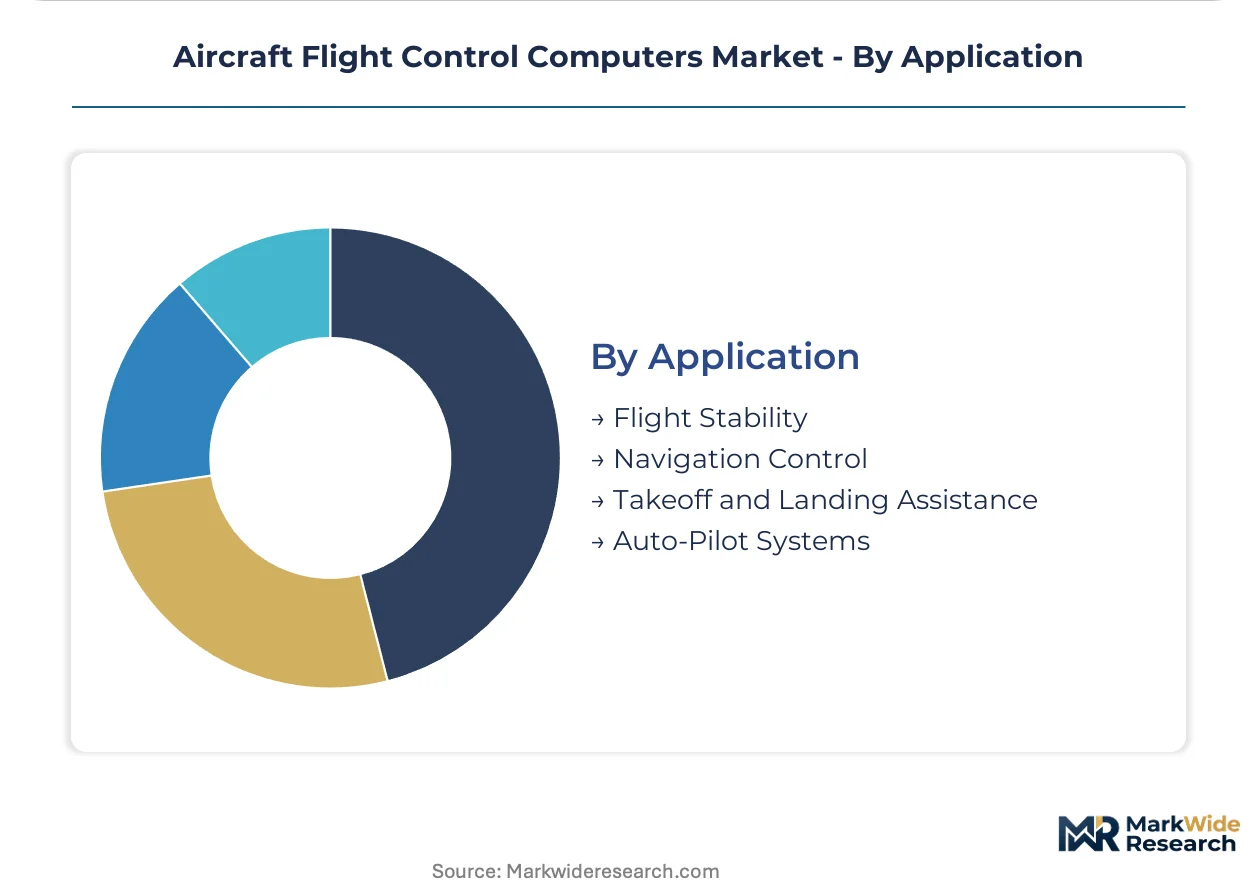
Maturity gradients separate this dimension: auto-pilot systems represent established functionality with stable specifications, while takeoff and landing assistance incorporates evolving sensor fusion.
- Flight Stability:Augmentation systems prevent loss-of-control events through automatic envelope protection. All commercial transport aircraft now incorporate these functions as baseline, with certification under FAA AC 25-7C and EASA CS-AWF.
- Auto-Pilot Systems:Three-axis autopilot with approach mode capability is standard equipment in business jets and above. Garmin and Collins Aerospace dominate retrofit installations in the United States and European general aviation fleets.
- Navigation Control:Flight management system integration with inertial and satellite navigation sources enables required navigation performance operations.
- Takeoff and Landing Assistance:Autoland and automatic ground spoiler deployment functions demand highest integrity levels and multi-sensor validation architectures.
Auto-Pilot Systems represents the largest installed volume. Takeoff and Landing Assistance is gaining share fastest as CAT III autoland requirements spread to single-aisle platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in flight control computers tilt toward net imports in emerging aerospace programs while established manufacturing hubs maintain component trade surpluses. Procurement patterns track regulatory alignment with FAA and EASA certification regimes. Supplier footprints concentrate where final assembly lines anchor demand.
United States
Boeing commercial and defense primes drive procurement volumes for DO-254 certified hardware. FAA mandates for ADS-B equipage and redundant flight control architectures accelerate retrofit cycles. Wichita, Kansas hosts a dense cluster of avionics integrators serving business jet and general aviation platforms.
France
Airbus final assembly lines in Toulouse and Hamburg-bound supply chains generate concentrated demand for EASA CS-25 certified systems. The country's national aerospace regulator enforces ED-12C software tool qualification requirements that extend verification timelines. Paris-Saclay corridor houses specialized engineering firms supporting flight control algorithm development.
Germany
Diehl Aviation and premium tier suppliers source control computers for Airbus A350 and A320neo programs. The KBA and national aerospace standards body align with EASA harmonization frameworks for autonomous flight control certification. Munich-Stuttgart industrial belt concentrates electromechanical actuator manufacturing for fly-by-wire integration.
China
COMAC C919 indigenous program creates import substitution pressure while CAAC harmonization with FAA standards opens access for foreign suppliers. The country's national aviation regulator shapes market access through type certification reciprocity negotiations. Shanghai-Pudong aerospace cluster anchors flight control system integration for narrowbody development.
United Kingdom
BAE Systems and defense primes sustain demand for military-grade control computers with electromagnetic pulse hardening. The national aerospace regulator maintains bilateral certification agreements with FAA and EASA that facilitate component trade. Bristol and Southwest England host specialized electronics manufacturing for fighter and transport platforms.
Aircraft Flight Control Computers Market Vendor Landscape
Concentration sits with diversified avionics conglomerates that bundle flight control hardware with integrated cockpit systems. The vendor base stratifies across three tiers: full-stack avionics providers, specialized electromechanical actuation houses, and defense-focused electronics contractors. Structural consolidation proceeds through OEM captive sourcing decisions and long-term fleet service contracts rather than horizontal M&A. Technology licensing agreements and joint certification programs constitute the dominant competitive moves.
Among diversified avionics conglomerates, Honeywell International Inc. and Collins Aerospace exemplify the full-stack archetype spanning hardware and software certification depth. Moog Inc. occupies a distinct position as an electromechanical actuation specialist with military platform anchoring. Safran S.A. represents European supply chain proximity advantages through EASA certification infrastructure. Thales Group and BAE Systems plc sit within the defense-tier vector where electromagnetic hardening and extended temperature specifications command premium positioning. These five entities collectively illustrate how regulatory certification depth, geographic supply chain alignment, and end-use specialization partition competitive terrain.
| Leading Market Players |
|---|
| Curtiss-Wright Corporation |
| Moog Inc. |
| Honeywell International Inc. |
| Liebherr Group |
| Collins Aerospace |
| Safran S.A. |
| Thales Group |
| Rockwell Collins-RTX Corporation |
| BAE Systems plc |
| Others |
Supply Flow & Price Mechanics
Long-term fleet lifecycle contracts lock in supply access and price visibility for aircraft flight control computers, binding OEM procurement teams to multi-year service obligations that compress supplier margins while extending contractual coverage across Boeing and Airbus narrowbody programs. FAA DO-254 and DO-178C certification tiers stratify pricing by hardware assurance level, with Level A systems commanding substantial premiums over lower-tier configurations.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that bundle initial provisioning with rotable pool access across standardized narrowbody fleets. Price differentiation separates DO-254 Level A certified hardware from lower-assurance tiers, with volume scale and after-sales service bundling as secondary drivers. Cost compression in mid-tier digital control systems is intensifying because airline procurement teams are consolidating sourcing under fleet-wide agreements. Low-cost carriers exhibit highest price sensitivity, while military programs absorb premium pricing for radiation-hardened specifications.
Supply Chain Analysis
Port congestion on trans-Pacific trade lanes elevates inbound logistics costs for aerospace-grade semiconductors sourced from Taiwan, South Korea, and the United States. Radiation-hardened chip fabrication draws from limited foundry capacity, with ceramic packaging substrates and high-reliability capacitors as critical dependencies. Single-source vulnerability concentrates in radiation-tolerant FPGA production. Distribution runs through Boeing and Airbus direct procurement channels for fly-by-wire systems, while MRO distributor networks handle analog retrofit flows for aging regional fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of DO-178C qualified engineers with safety-critical coding experience constrains supplier expansion and locks in competitive advantage for incumbents with established certification infrastructure. This talent gap justifies defensive investment in workforce development and certification pipeline control.
For Market Incumbents: Secure captive certification capacity by bringing DO-178C toolchains in-house to control verification risk and reduce third-party vendor liability exposure under EASA ED-12C updates. Extend backward integration into radiation-hardened semiconductor sourcing to mitigate single-source foundry vulnerability. Consolidate channel control through long-term fleet service contracts that lock out emerging competitors from rotable pool access.
For New Entrants and Emerging Players: Aftermarket retrofit service gaps where incumbents under-serve aging regional turboprop fleets present accessible entry points with reduced certification burden from grandfather rights. Target MRO distributor networks in the United States and Europe for analog-to-digital interface modules. Pursue partnership-based go-to-market angles with established electromechanical actuator suppliers to bypass direct OEM procurement barriers.
For Investors and Strategic Acquirers: Specialized FPGA control computer developers with eVTOL program anchoring represent prime acquisition targets as urban air mobility certification frameworks crystallize. Long-term viability hinges on regulatory alignment with FAA and EASA autonomous flight control pathways. Watch for CAAC type certification reciprocity negotiations as the inflection signal for COMAC C919 supplier access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| DO-178C Toolchain In-Housing | Reduces EASA ED-12C liability exposure and compresses verification timelines for flight control software. |
| Radiation-Hardened Semiconductor Sourcing | Mitigates single-source foundry risk for aerospace-grade FPGA and processor components. |
| eVTOL Control Computer Certification | Establishes first-mover supplier relationships before FAA urban air mobility frameworks finalize. |
| Fleet Lifecycle Contract Consolidation | Locks in multi-year revenue streams with United States network carriers through bundled provisioning. |
| CAAC Harmonization Alignment | Opens access to COMAC C919 and future indigenous programs through regulatory reciprocity positioning. |
Methodological Framework
Desk research of FAA certification filings, EASA CS-25 airworthiness directives, and OEM procurement disclosures preceded structured interviews with flight control system engineering directors, airline fleet procurement managers, MRO aftermarket specialists, and DO-178C qualified software architects. Secondary validation drew from SEC 10-K avionics segment disclosures, customs trade data for aerospace semiconductors, and industry association technical publications. Bottom-up installation base estimates triangulated against top-down OEM delivery projections.
Variance decomposition across product type, end user, technology platform, and application dimensions shaped the analytical framework over the projection horizon. Segmentation modeling incorporated fly-by-wire penetration rates, FPGA displacement trajectories, and military modernization cycle phasing. CAGRs derived from unit volume forecasts multiplied by certification-tier pricing bands, with fleet retirement curves and retrofit conversion rates as aviation-specific inputs.
Forecasts assume regulatory continuity in FAA DO-254/DO-178C and EASA CS-25 regimes; material policy shifts on autonomous flight control certification would require re-modeling. Semiconductor supply constraints, CAAC reciprocity negotiations, and eVTOL regulatory crystallization pace represent specific revision triggers. Recalibration cycles align with material shifts in fleet delivery schedules and certification standard updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Manufacturing Market
Aircraft
Light Sport Aircraft (LSA) Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Fighter Aircraft Market
Aircraft
Global Helicopter Market
Aircraft
Ultra-Light Aircraft Market
Aircraft
Flap Track Fairing Drag Reduction Upgrade Kits Market
Aircraft
Commercial Aircraft Fadec Market
Aircraft
Military Multirole Aircraft Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Amphibious Aircraft Market
Aircraft
Commercial Aircraft Lavatory System Market
Aircraft
Aircraft Galley Systems Market
Aircraft
Latin America Business Jet Market
Aircraft
Global Business Jets Market
Aircraft
Aero Wing Market