
 Evtol (Electric Vertical Takeoff and Landing) Airplane Market | 2026-2036
Evtol (Electric Vertical Takeoff and Landing) Airplane Market Size, Share, and Industry Trends Forecast 2026-2036
Evtol (Electric Vertical Takeoff and Landing) Airplane Market Insights
Composite fiber-reinforced polymers are shifting from aluminum in eVTOL airframe construction, cutting weight fractions by roughly one-third while preserving structural integrity under multirotor load cycles. Joby Aviation leverages in-house composite manufacturing to control fuselage costs across its five-seat tiltrotor design. Archer Aviation anchors its Midnight platform on proprietary battery-pack architecture that sustains energy density targets for 100-mile regional routes. Lilium competes through its ducted-fan approach, differentiating on acoustic signatures suited for dense European urban corridors.
An electric vertical takeoff and landing airplane is a piloted or autonomous fixed-wing or multicraft aerial vehicle powered by distributed electric propulsion, typically operating at cruise speeds between 100 and 200 knots with ranges of 50 to 250 nautical miles depending on battery configuration and aerodynamic layout. Its primary commercial purpose is to bypass surface congestion through point-to-point aerial transport of passengers or time-critical cargo in metropolitan and peri-urban environments. The passenger product type currently leads order backlogs, though cargo configurations for logistics transport are attracting fleet commitments from delivery services seeking to decouple last-mile speed from ground infrastructure limits. Multirotor technology dominates near-term certification activity, while lift-plus-cruise architectures are positioning for longer-range regional commute segments where aerodynamic efficiency determines operating economics.
The FAA administers Part 23 and emerging powered-lift certification pathways that dictate airworthiness testing protocols and pilot qualification standards for US operators. EASA's SC-VTOL special condition and EU AI Act provisions for autonomous decision systems are shaping product design requirements and market access timelines across European jurisdictions. China's CAAC coordinates type certification with MIIT battery-safety standards, creating a parallel regulatory track that accelerates domestic deployment. Stakeholders must monitor which regulator's certification reciprocity agreements gain traction first, as mutual recognition will determine where manufacturing investment and fleet deployment concentrate.
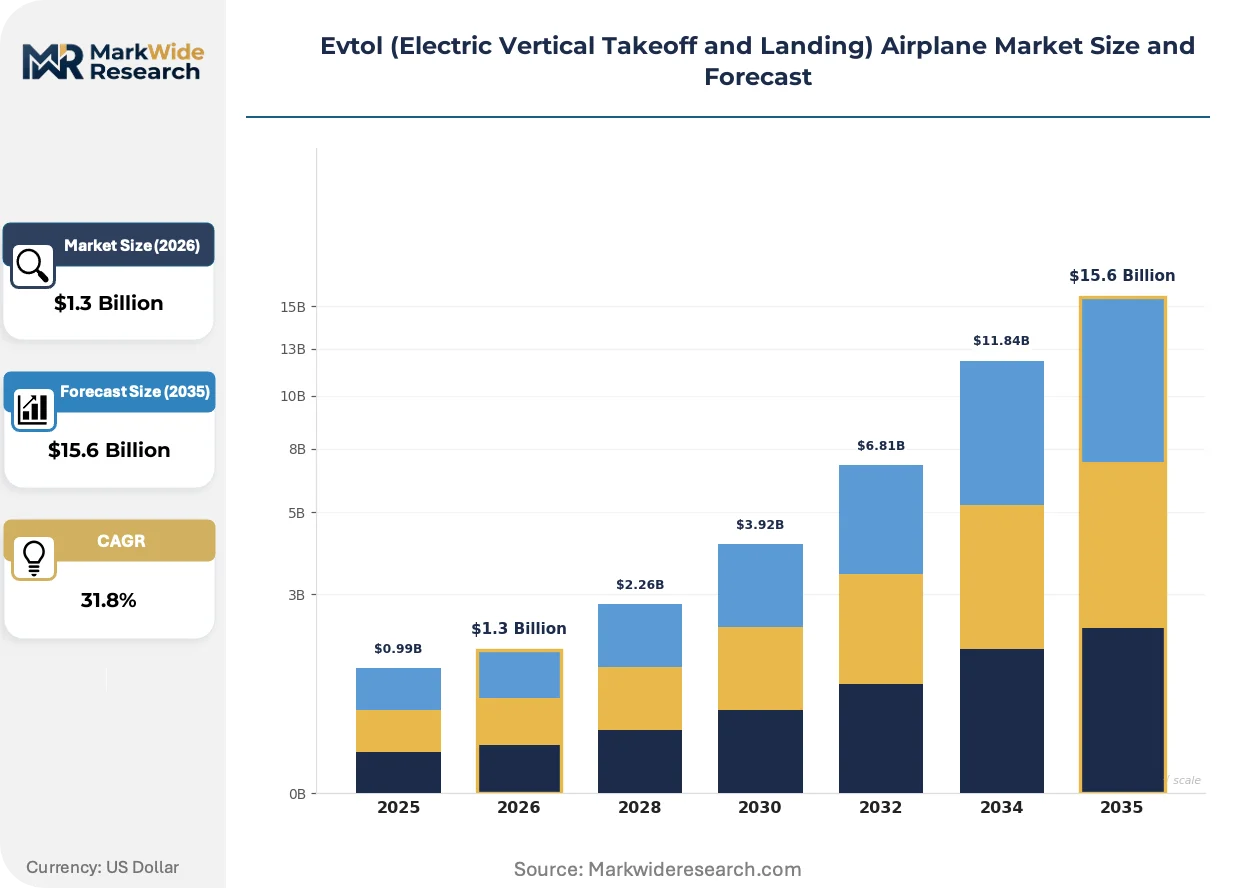
Market Dynamics
Composite airframe adoption is compressing certification timelines while battery energy density plateaus force architects toward hybrid-electric or hydrogen range-extension for regional routes beyond 100 nautical miles.
Growth Catalysts
- FAA Part 23 Reforms:Streamlined powered-lift certification pathways reduce type approval duration for US manufacturers, accelerating piloted entry-into-service timelines.
- Urban Air Mobility Infrastructure:Vertiport construction in Dubai and São Paulo creates dedicated takeoff-landing nodes that decouple eVTOL operations from legacy airport congestion.
- Lithium-Silicon Anode Chemistries:Next-generation cell architectures push pack-level energy density toward 300 Wh/kg thresholds, extending viable mission profiles for multirotor platforms.
Market Restraints
- Battery Supply Concentration:Cathode precursor refining concentrates in Chinese processing facilities, exposing non-domestic OEMs to raw material access volatility and export control risk.
- Pilot Qualification Bottlenecks:FAA powered-lift type ratings lack established training syllabi, forcing operators to fund bespoke simulator infrastructure before revenue service.
- Acoustic Footprint Limits:European urban noise ordinances below 65 dB at 100 meters altitude constrain ducted-fan and open-rotor designs to lower-thrust operational envelopes.
Strategic Opportunities
- Autonomous Cargo Corridors:EASA SC-VTOL frameworks for unmanned operations below 500 feet AGL enable nighttime logistics routes across Rotterdam-Antwerp port clusters without pilot overhead.
- Intercity Regional Networks:Germany's KBA coordination with rail operators positions eVTOL as feeder links to high-speed trunk lines, capturing 50-150 kilometer commute segments.
- Vertiport Real Estate Arbitrage:Redevelopment of underutilized parking structures in São Paulo's Pinheiros district converts ground-level congestion points into aerial access nodes.
Industry Challenges
- Composite Repair Technician Scarcity:Airframe damage tolerance assessment requires specialized NDT certification that exceeds standard A&P mechanic training, constraining fleet maintainability.
- Software Verification Burden:FAA AC 20-174D guidance for autonomous flight control systems demands exhaustive model-based testing that extends development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Evtol (Electric Vertical Takeoff and Landing) Airplane Market |
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $15.6 Billion |
| CAGR (2026 – 2036) | 31.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passenger, Cargo, Surveillance, Emergency Response, Training Technology: Multirotor, Lift-plus-Cruise, Tiltrotor, Ducted Fan, Coaxial Use Case: Urban Air Mobility, Regional Commute, Logistics Transport, Disaster Management, Aerial Survey End User: Aerospace Manufacturers, Government Agencies, Delivery Services, Emergency Services, Private Operators |
| Companies Covered | Joby Aviation, Archer Aviation, EHang, Eve Holding, Beta Technologies, Vertical Aerospace, Volocopter, Wisk Aero, Lilium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Evtol (Electric Vertical Takeoff and Landing) Airplane Market Trends and Innovations
Thermal management architectures and distributed propulsion control systems are reshaping platform economics, while regulatory frameworks crystallize around noise, autonomy, and airspace integration priorities.
Solid-state battery cell designs with ceramic electrolyte separators are electrifying energy storage safety margins for lithium-metal chemistries. Cargo operators in the UAE are trialing these packs for high-cycle desert environments where thermal runaway risk compounds. This electrifying shift is compressing insurance premium spreads between conventional lithium-ion and next-generation architectures.
EASA's SC-VTOL special condition mandates single-failure-proof flight control redundancy for Category Enhanced operations above 120 knots. European OEMs must demonstrate loss-of-thrust continuation across all flight phases, driving adoption of hexacopter-plus-pusher configurations. The ducted-fan segment faces the steepest compliance cost escalation as acoustic and safety requirements converge.
Vertiport access fees are displacing per-mile operating cost as the dominant procurement metric for fleet operators. Charter services in Dubai now negotiate slot-based landing rights rather than fuel-plus-crew contracts. This behavioral pivot is most pronounced in Chinese urban clusters where CAAC coordinates vertiport scheduling with municipal traffic management systems.
Evtol (Electric Vertical Takeoff and Landing) Airplane Market Segmentation
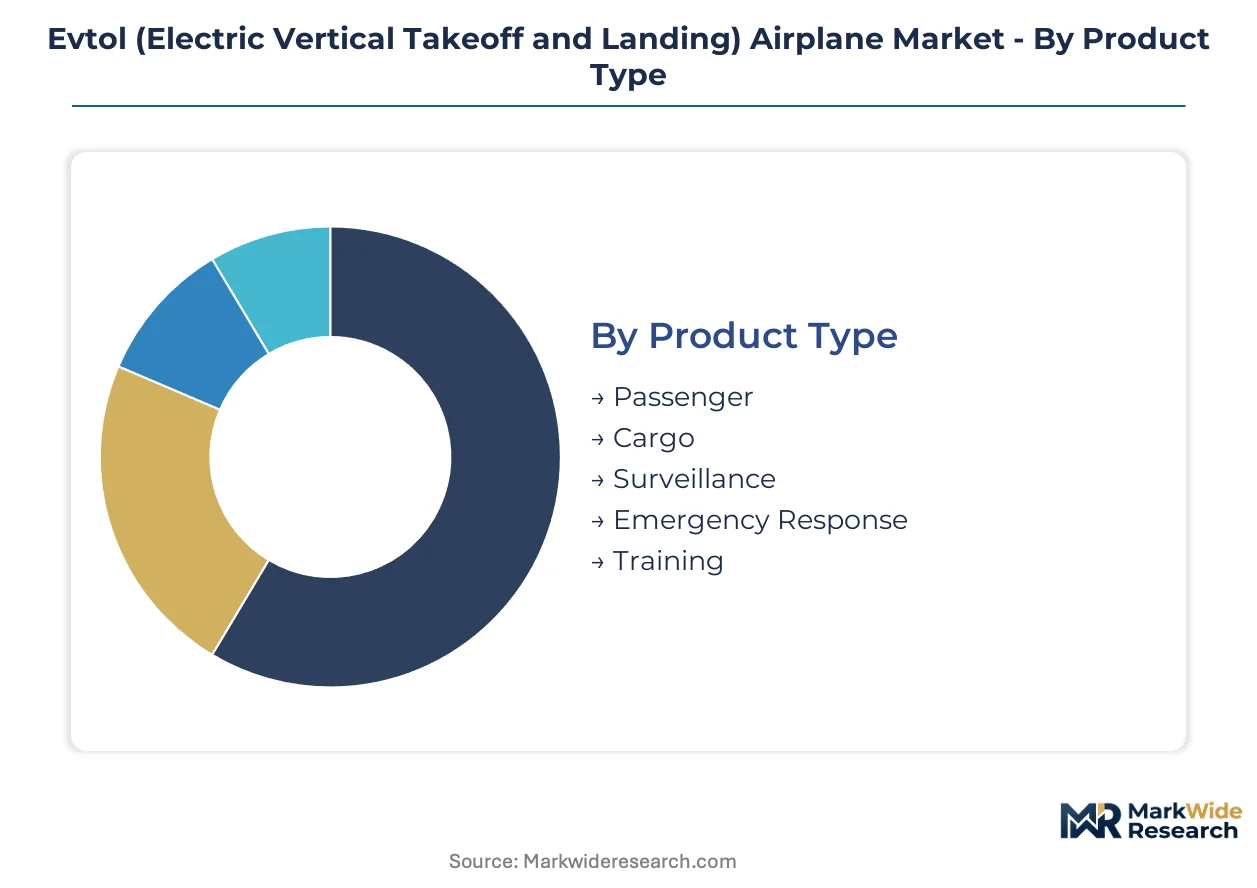
eVTOL market segmentation reveals divergent technology maturities and revenue concentration points. Product type and technology categories show the sharpest divergence between near-term commercial viability and long-term architectural bets. Understanding these splits guides capital allocation across certification timelines and infrastructure requirements.
Product Type:
Volume concentration sits with passenger configurations while premium pricing attaches to specialized mission profiles.
- Passenger:Five-seat configurations dominate order backlogs as Dubai and São Paulo operators scale pilot programs for point-to-point urban routes. FAA Part 23 reforms accelerate type approval for piloted entry-into-service, though autonomous certification timelines remain uncertain.
- Cargo:Payload-optimized designs with dedicated battery compartments attract fleet commitments from delivery services seeking to bypass ground infrastructure constraints. EASA SC-VTOL frameworks for unmanned operations below 500 feet enable nighttime logistics corridors without pilot overhead.
- Surveillance:Sensor-integrated platforms with extended loiter endurance serve border patrol and infrastructure monitoring missions.
- Emergency Response:Medical evacuation configurations with rapid patient loading systems address time-critical trauma transport.
- Training:Dual-control variants support powered-lift type rating development as FAA syllabi crystallize.
Today's leader: Passenger. Tomorrow's challenger: Cargo.
Technology:
Architectural choices trade acoustic signature against aerodynamic efficiency and certification complexity.
- Multirotor:Distributed electric propulsion with fixed-pitch rotors dominates near-term certification activity through mechanical simplicity and redundant thrust distribution. China's CAAC coordinates type approval with MIIT battery-safety standards, accelerating domestic deployment ahead of Western regulators.
- Lift-plus-Cruise:Separate hover and cruise propulsion systems optimize aerodynamic efficiency for 100-250 nautical mile regional segments. Germany's KBA coordination with rail operators positions this architecture as feeder links to high-speed trunk lines.
- Tiltrotor:Proprotors pivot between vertical and horizontal thrust vectors, consolidating propulsion count but adding mechanical complexity.
- Ducted Fan:Enclosed rotor designs reduce acoustic footprint below 65 dB thresholds for European urban noise ordinances.
- Coaxial:Counter-rotating rotor stacks maximize thrust density within compact fuselage envelopes.
Multirotor captures current certification momentum. Lift-plus-Cruise gains share fastest as regional networks mature.
Use Case:
Application segmentation maps directly onto infrastructure readiness and regulatory permissioning timelines.
- Urban Air Mobility:Vertiport-dependent operations in metropolitan cores concentrate initial commercial deployment where municipal traffic management integration exists.
- Regional Commute:Intercity corridors of 50-150 kilometers exploit eVTOL speed advantages over ground transport without requiring extensive new infrastructure.
- Logistics Transport:Time-critical cargo routes prioritize payload density over passenger comfort specifications.
- Disaster Management:Rapid deployment requirements favor platforms with minimal ground support dependencies.
- Aerial Survey:Precision mapping and inspection missions leverage low-altitude maneuverability.
Urban Air Mobility anchors near-term revenue. Regional Commute represents the steepest expansion trajectory as battery energy density crosses 300 Wh/kg thresholds.
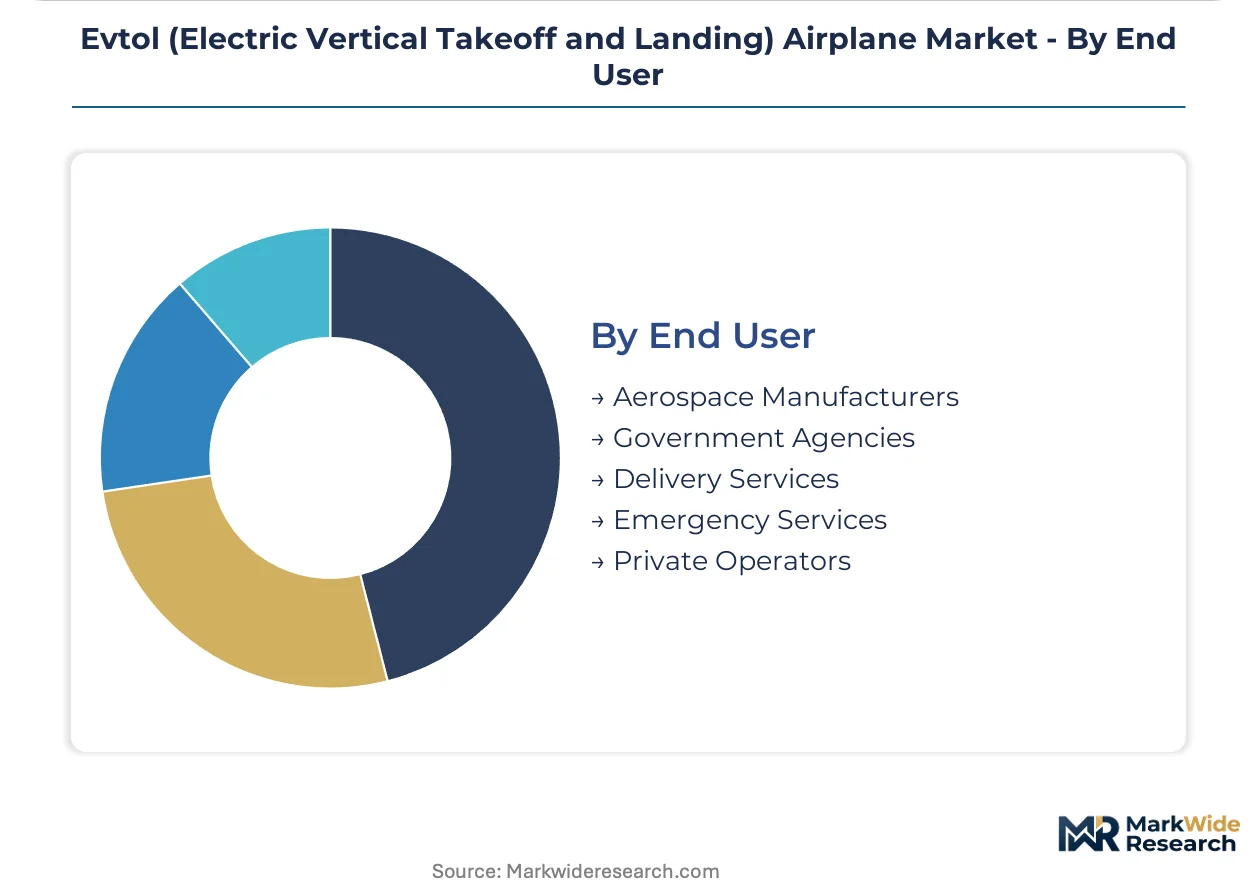
End User:
Procurement authority fragments across public certification sponsorship and private fleet economics.
- Aerospace Manufacturers:Vertical integration into composite airframe production and proprietary battery architectures controls unit economics.
- Government Agencies:Defense and public safety procurement establishes operational precedents that de-risk commercial certification pathways.
- Delivery Services:High-cycle logistics operators drive demand for autonomous cargo configurations with minimized pilot overhead.
- Emergency Services:Hospital networks and fire departments prioritize dispatch reliability over per-mile operating cost.
- Private Operators:Charter services negotiate slot-based vertiport access fees rather than traditional fuel-plus-crew contracts.
Delivery Services command the fastest-growing procurement trajectory. Government Agencies provide regulatory cover for technology maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the dominant manufacturing cluster for electric vertical takeoff and landing aircraft, with EHang and local supply chains compressing production cycles ahead of Western competitors. Dubai and São Paulo operate the most advanced pilot programs for passenger transport, while regulatory reciprocity agreements between the FAA, EASA, and CAAC determine where fleet deployment concentrates.
China
CAAC coordinates type certification with MIIT battery-safety standards, creating a parallel regulatory track that accelerates domestic deployment. The Yangtze River Delta and Pearl River Delta host concentrated airframe manufacturing and battery pack assembly operations. EHang pushes commercial deployment in Guangzhou and Shenzhen ahead of Western certification timelines.
United States
FAA Part 23 reforms streamline powered-lift certification pathways, reducing type approval duration for domestic manufacturers. Joby Aviation leverages in-house composite manufacturing in California to control fuselage costs across its tiltrotor design. Archer Aviation anchors proprietary battery-pack architecture development in the San Francisco Bay Area for regional route economics.
Germany
EASA's SC-VTOL special condition and EU AI Act provisions shape product design requirements and market access timelines. The KBA coordinates with rail operators to position eVTOL as feeder links to high-speed trunk lines, targeting 50-150 kilometer commute segments. Lilium competes through ducted-fan development in Munich, differentiating on acoustic signatures for dense European urban corridors.
United Arab Emirates
MOHAP and the country's aviation regulator coordinate vertiport scheduling with municipal traffic management systems in Dubai. Vertiport construction creates dedicated takeoff-landing nodes that decouple eVTOL operations from legacy airport congestion. Charter services in Dubai negotiate slot-based landing rights rather than traditional fuel-plus-crew contracts.
Brazil
ANVISA and aviation authorities align on operational safety frameworks as São Paulo operators scale pilot programs. Redevelopment of underutilized parking structures in the Pinheiros district converts ground-level congestion points into aerial access nodes. Eve Holding, with its São Paulo roots, leverages local regulatory relationships to advance urban air mobility corridors.
Evtol (Electric Vertical Takeoff and Landing) Airplane Market Competitive Landscape
Proprietary battery and composite manufacturing investments dominate the current landscape as OEMs seek cost control over critical subsystems. The vendor base clusters around three strategic archetypes: aerospace incumbents repurposing rotorcraft expertise, automotive suppliers leveraging electric powertrain scale, and pure-play eVTOL specialists owning full-stack development. Two competitive moves define positioning: backward integration into composite airframe production and strategic vertiport real estate partnerships that secure landing slot access.
Among US-based developers, Joby Aviation and Archer Aviation exemplify the full-stack specialist archetype with captive manufacturing capabilities. EHang anchors the Chinese tier with integrated flight control and autonomous systems development. European representation concentrates in Lilium and Volocopter, each occupying distinct positions on the acoustic-performance spectrum for urban certification pathways.
| Leading Market Players |
|---|
| Joby Aviation |
| Archer Aviation |
| EHang |
| Eve Holding |
| Beta Technologies |
| Vertical Aerospace |
| Volocopter |
| Wisk Aero |
| Lilium |
| Others |
Pricing and Supply Chain Analysis
Fleet operators in Dubai and São Paulo anchor demand concentration for eVTOL platforms, locking procurement negotiations around slot-based vertiport access fees rather than traditional asset ownership models. This buyer archetype concentration compresses upfront capital requirements while amplifying recurring revenue predictability for OEMs.
Pricing Analysis
Input-cost pass-through from lithium-silicon anode cell architectures and composite fiber-reinforced polymers dominates pricing formation across multirotor and lift-plus-cruise platforms. Three-tier pricing structure across premium certified, standard compliant, and economy developmental tiers separates FAA Part 23 type-approved aircraft from pre-certification prototypes and experimental-category units. Pricing pressure stems from cathode precursor refining concentration in Chinese processing facilities exposing non-domestic OEMs to raw material access volatility. Delivery services exhibit highest price sensitivity due to high-cycle logistics economics, while emergency medical operators prioritize dispatch reliability over per-mile cost.
Supply Chain Analysis
Freight cost escalation for cathode active materials and ceramic electrolyte separators amplifies landed cost differentials between Asian cell manufacturers and Western pack assemblers. Supply concentration centers on China for battery cell production, South Korea for separator membranes, and Japan for electrolyte additives. The eVTOL supply chain draws from aerospace-grade carbon fiber precursors, rare-earth permanent magnets for distributed propulsion motors, and aviation-certified power electronics. Single-source vulnerability concentrates in solid-state electrolyte ceramic processing capacity. Distribution runs through vertiport real estate operators who capture landing slot economics ahead of aircraft OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The eVTOL market compounds steadily as regulatory reciprocity agreements between FAA, EASA, and CAAC compress certification timelines and de-risk fleet deployment capital.
For Market Incumbents: Deepen backward integration into composite airframe production to defend margin position against emerging automotive suppliers leveraging electric powertrain scale. Secure captive battery-pack architecture development in California or Shenzhen to control energy density roadmaps. Anchor vertiport real estate partnerships in São Paulo's Pinheiros district and Dubai's MOHAP-coordinated nodes to lock landing slot access ahead of competitor fleet scaling. For New Entrants and Emerging Players: EASA SC-VTOL frameworks for unmanned operations below 500 feet AGL in the Rotterdam-Antwerp corridor open a window for autonomous cargo configurations without pilot overhead burden. Target nighttime logistics routes where acoustic footprint constraints relax operational envelopes. Pursue vertiport access fee arbitrage through redevelopment of underutilized parking structures rather than greenfield infrastructure development. For Investors and Strategic Acquirers: Aerospace manufacturers with rotorcraft expertise represent the most active acquirer category in this space, seeking electric propulsion capabilities to complement legacy turbine portfolios. Acquisition targets should display integrated flight control development and CAAC or FAA certification progress. Monitor EASA-FAA reciprocity agreement momentum as the signal indicating where manufacturing investment and fleet deployment capital will concentrate.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Battery Architecture Development | Archer Aviation's pack-level energy density targets secure 100-mile regional route economics against hybrid-electric alternatives. |
| Vertiport Real Estate Partnership | Dubai's slot-based landing rights model converts ground congestion points into aerial access nodes with recurring revenue. |
| Composite Manufacturing Integration | Joby Aviation's in-house fuselage production controls unit costs across tiltrotor certification pathways. |
| Autonomous Flight Control Certification | EHang's integrated systems development accelerates CAAC approval timelines ahead of Western competitors. |
| Ducted-Fan Acoustic Optimization | Lilium's Munich-based development targets EASA SC-VTOL noise ordinances below 65 dB for European urban corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with eVTOL program executives, FAA certification leads, vertiport real estate developers, battery cell procurement managers, and urban air mobility operators with secondary validation against CAAC type certification databases, EASA SC-VTOL special condition filings, SEC 10-K disclosures from listed developers, and municipal traffic management integration records. Bottom-up fleet deployment models and top-down addressable market sizing triangulated volume estimates.
Segment-weighting across product type, technology architecture, use case, and end user dimensions shaped the analytical framework over the projection horizon. CAGRs derived from battery energy density improvement curves, regulatory approval timeline distributions, and vertiport infrastructure investment pipelines. Modeled inputs included lithium-silicon anode commercialization schedules, FAA Part 23 reform implementation progress, and EASA-EU AI Act autonomous system provisions.
Revisions become necessary when battery supply concentration triggers export control restrictions, acoustic footprint regulations tighten below current 65 dB thresholds, or pilot qualification bottlenecks extend powered-lift type rating development beyond current simulator infrastructure capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
India Aviation Market
Aircraft
Global Commercial Aircraft Seat Actuation Market
Aircraft
Europe Military Helicopters Market
Aircraft
Online in-Flight Shopping Market
Aircraft
Europe Attack Helicopter Market
Aircraft
Asia-Pacific Commercial Aircraft Market
Aircraft
Amphibious Aircraft Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market
Aircraft
Aircraft Band Clamps Market
Aircraft
Air Deflector Market
Aircraft
Aircraft Seals Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
France Aviation Market
Aircraft
Helicopter Flight Control Systems Market
Aircraft
GCC Business Jet Market
Aircraft
Global LW Sport Aircraft Market