
 Tandem Rotor Helicopter Market | 2026-2036
Tandem Rotor Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Tandem Rotor Helicopter Market Analysis
Carbon-fiber reinforced polymer is repositioning airframe economics in tandem rotor programs by cutting empty weight while preserving load-bearing capacity. Boeing Vertol leverages its heritage Chinook production infrastructure to sustain cost advantages in heavy-lift contracts. Lockheed Martin Corporation anchors military demand through its Sikorsky-Boeing Defiant program, while Airbus Helicopters competes in the civil heavy-lift niche with upgraded Super Puma derivatives.
A tandem rotor helicopter employs two main rotors mounted longitudinally on separate pylons, eliminating the need for an anti-torque tail rotor and enabling true vertical center-of-gravity loading across its 20,000-pound-plus payload class. Military Helicopters dominate product-type volume as defense budgets prioritize heavy-lift modernization, while Search and Rescue Helicopters represent the fastest-growing application segment driven by alpine and maritime agency requirements. Composite Materials technology commands premium positioning as manufacturers substitute titanium and aluminum in rotor hubs and transmission housings.
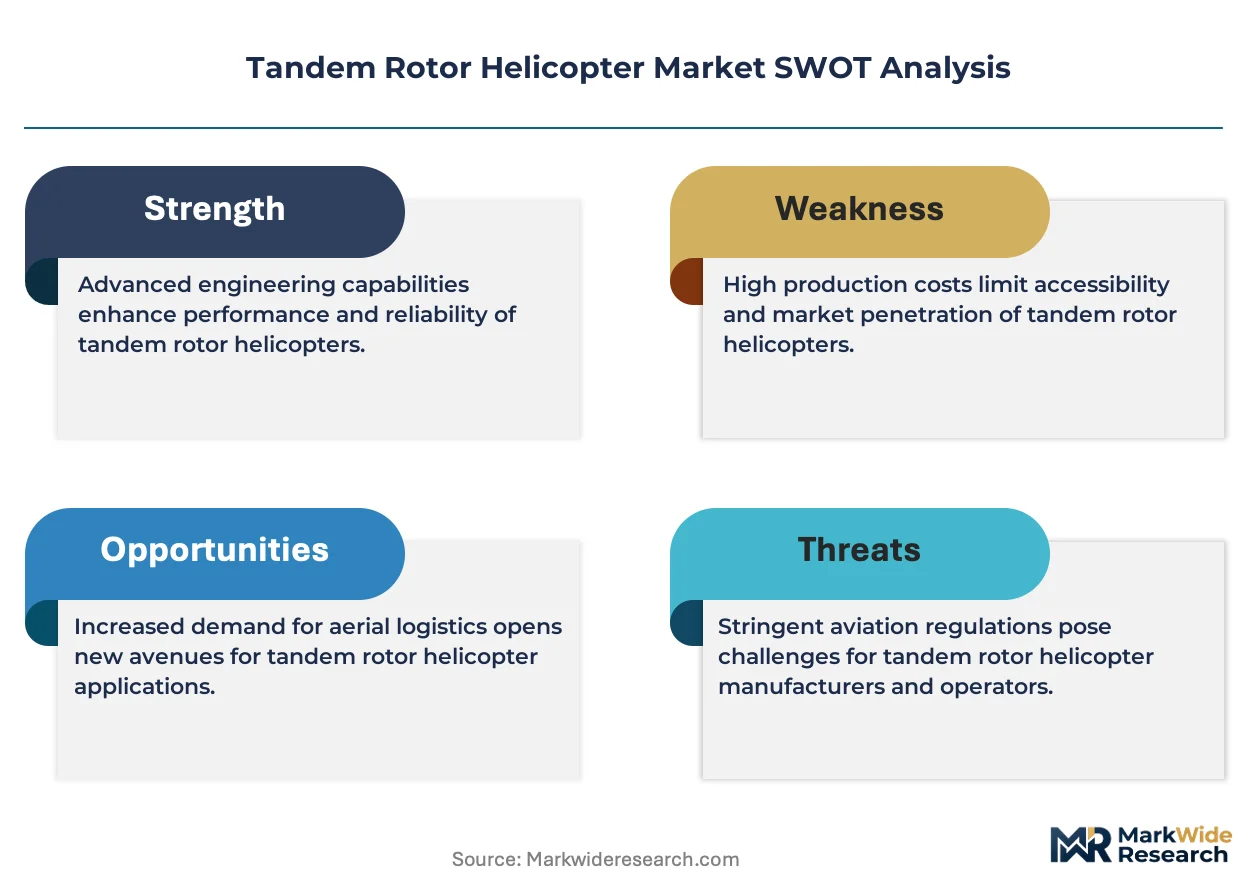
FAA Part 29 transport-category standards and EASA CS-29 certification frameworks govern airworthiness for civil tandem rotor operations, while military variants face MIL-STD-810 environmental testing and DEF STAN 00-970 design requirements. These regulatory layers extend development timelines but create barriers that favor incumbents with established certification track records. Stakeholders must weigh sustainment investments against clean-sheet electrification architectures as hybrid propulsion matures.
Market Dynamics
Carbon-fiber reinforced polymer substitution is compressing airframe weight thresholds while FAA Part 29 certification mandates extend development timelines, creating a structural tension between performance gains and regulatory compliance burdens.
Growth Catalysts
- NATO Heavy-Lift Modernization:Alliance members are renewing aging vertical-lift fleets through multi-year procurement frameworks. Defense budget allocations favor tandem rotor platforms for their payload density in contested logistics environments.
- Composite Material Certification:FAA and EASA have established accelerated pathways for polymer-matrix airframe components. Manufacturers are exploiting these frameworks to reduce empty weight without sacrificing structural load limits.
- Maritime Search and Rescue Expansion:Coastal agencies from Norway to Japan are procuring tandem rotor units for extended-range SAR missions. These platforms eliminate tail rotor failure risks in high-wind overwater operations.
Market Restraints
- Titanium Supply Concentration:Rotor hub forgings depend on Russian and Chinese sponge titanium feedstocks. Western sanctions and export controls have compressed available supply channels for critical rotating components.
- Dual Certification Burden:Civil-military hybrid programs must satisfy both FAA Part 29 and MIL-STD-810 testing regimes. This dual-track validation adds engineering overhead that deters new market entrants.
- Electrification Substitution:Tiltrotor and compound helicopter architectures are capturing defense evaluation contracts. These alternatives promise speed advantages that challenge traditional tandem rotor value propositions.
Strategic Opportunities
- Indian Defense Indigenization:India's Ministry of Defence is soliciting foreign partners for domestic heavy-lip production under offset mandates. The PLI scheme for aerospace components creates tariff advantages for local assembly operations.
- Hybrid-Electric Retrofit Kits:Convergence of turbine engines with battery-electric auxiliary power units is opening aftermarket modernization pathways. Operators can extend range without full airframe replacement.
- Urban Air Mobility Infrastructure:Vertiport construction in Dubai and Singapore is creating demand for heavy-lift construction helicopters. Tandem rotor units offer precision load placement in confined urban zones.
Industry Challenges
- Rotor Dynamics Simulation Talent:Computational fluid dynamics expertise for coaxial and tandem rotor interaction modeling remains scarce. Universities produce fewer specialists than program demands require.
- Legacy Avionics Integration:New glass cockpit architectures must interface with analog-era hydraulic flight control systems. This hybrid integration extends test flight schedules and defers revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tandem Rotor Helicopter Market |
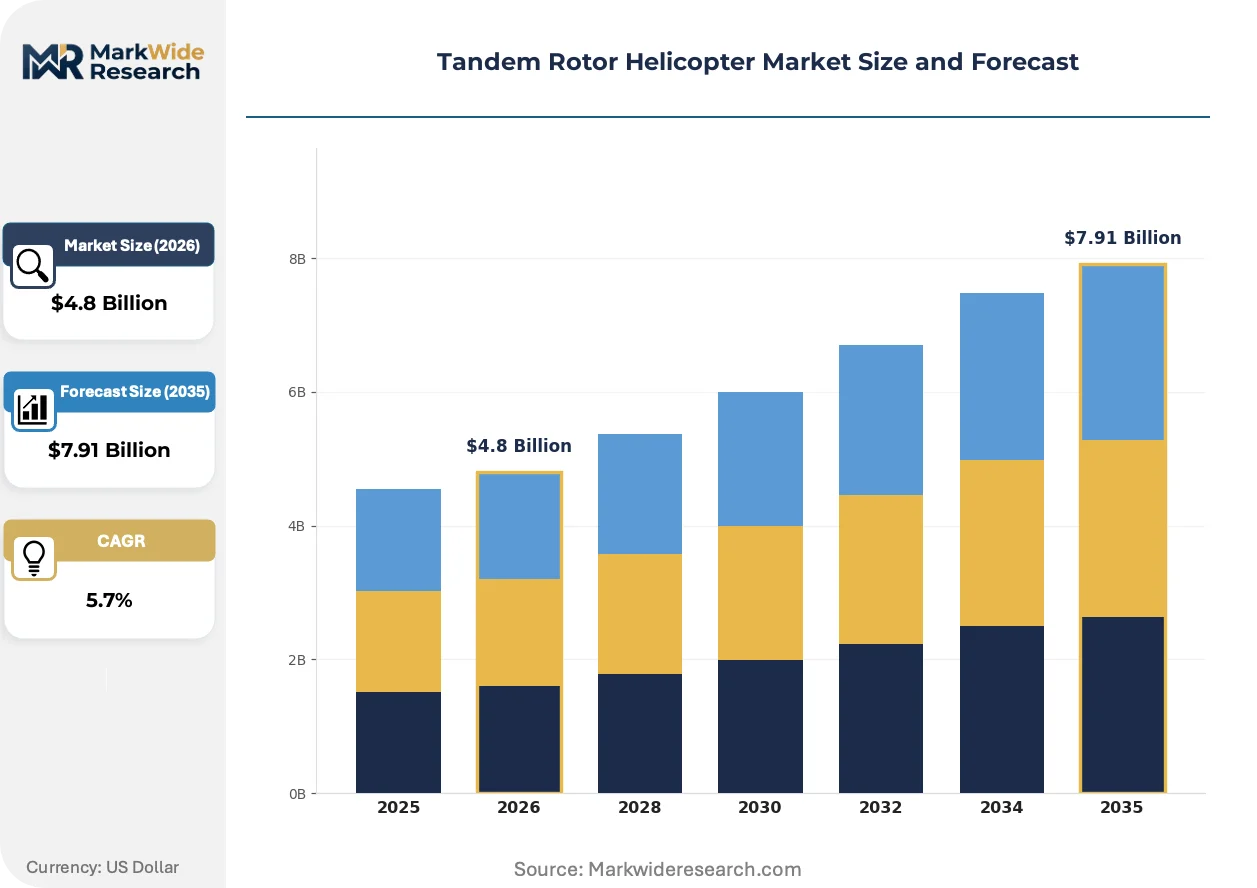
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Military Helicopters, Cargo Helicopters, Civilian Helicopters, Search and Rescue Helicopters Application: Transport Operations, Emergency Medical Services, Search Operations, Firefighting End User: Defense Sector, Commercial Operators, Government Agencies, Civil Services Technology: Fly-by-Wire Systems, Avionics, Composite Materials, Advanced Propulsion |
| Companies Covered | Lockheed Martin Corporation, Leonardo Helicopters, Boeing Vertol, Mitsubishi Heavy Industries, Russian Helicopters, Sikorsky Aircraft, Bell Textron, Korean Aerospace Industries, Airbus Helicopters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tandem Rotor Helicopter Market Emerging Trajectories
Material science breakthroughs and regulatory recalibration are compressing development cycles while opening new operational envelopes for heavy-lift platforms previously constrained by mechanical limitations.
Fly-by-wire flight control systems are modularizing traditional mechanical linkages in tandem rotor architectures. Military operators are mandating these digital interfaces for reduced pilot workload in degraded visual environments. This shift is modularizing supply chains as avionics specialists displace legacy hydraulics vendors.
EASA CS-29 Amendment 7 is tightening crashworthiness standards for transport-category rotorcraft occupant protection. Manufacturers must redesign fuel system integrity and seat attachment points to satisfy updated head-injury criteria. Civil heavy-lift programs face the steepest compliance costs as retrofitting existing airframes proves structurally prohibitive.
Performance-based logistics contracts are displacing traditional time-and-material sustainment arrangements in defense procurement. Operators now pay for availability hours rather than individual spare parts, transferring inventory risk to OEMs. This reconfiguration is most advanced in United States Army vertical-lift programs, where Boeing Vertol and Sikorsky compete on cost-per-flight-hour metrics.
Tandem Rotor Helicopter Market Segmentation
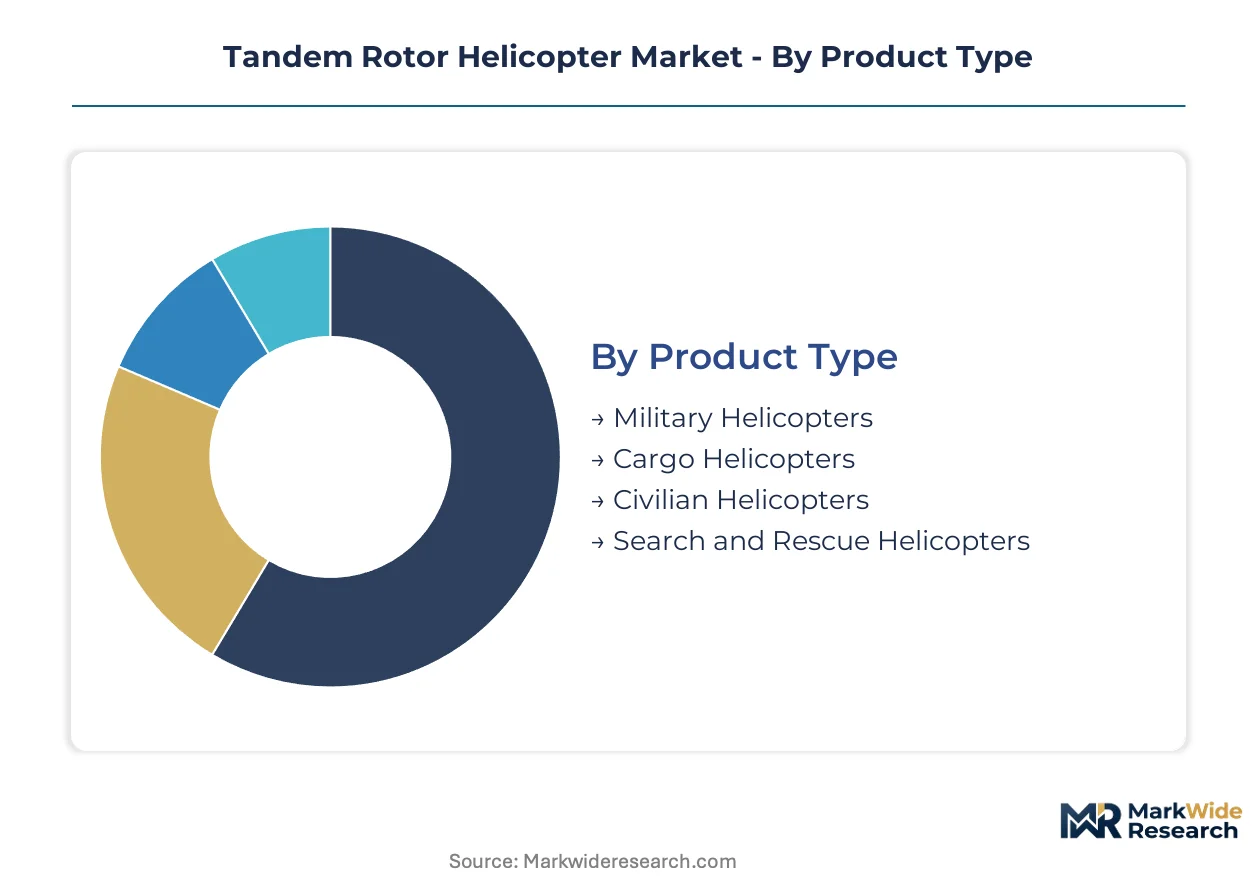
Segmentation in tandem rotor helicopters reveals how payload specifications, certification tiers, and operator economics partition demand across radically different procurement cycles. Each dimension exposes distinct margin structures and technology adoption rates that reshape competitive positioning.
Product Type:
Supply concentration in heavy-lift airframe fabrication tilts procurement leverage toward established military integrators with FAA Part 29 and MIL-STD-810 certification track records.
- Military Helicopters:Heavy-lift platforms designed for contested logistics environments carry 20,000-pound-plus payloads across extended operational radii. United States Army and Marine Corps vertical-lift modernization programs concentrate demand in domestic production facilities.
- Search and Rescue Helicopters:Extended-range configurations eliminate tail rotor failure risks in high-wind maritime conditions. Norwegian and Japanese coastal agencies are expanding fleet acquisitions for alpine and overwater rescue missions.
- Cargo Helicopters:Civil heavy-lift units optimized for precision external load placement in infrastructure construction.
- Civilian Helicopters:Transport-category rotorcraft serving executive transport and utility roles under EASA CS-29 frameworks.
Military Helicopters absorb the bulk of installed capacity; Search and Rescue Helicopters are expanding most quickly.
Application:
Cost tier differentiation separates defense-grade mission systems from commercial utility configurations, with avionics suites representing the primary variable cost driver.
- Transport Operations:Troop and equipment movement in tactical environments demands fly-by-wire redundancy and degraded visual environment capability. NATO alliance members are renewing aging fleets through multi-year procurement frameworks.
- Firefighting:External tank configurations for aerial water delivery require rapid fill-and-dump cycles in high-temperature operating envelopes. California Department of Forestry and Fire Protection and Australian state agencies drive specification requirements.
- Emergency Medical Services:Patient evacuation platforms with pressurized cabins and medical equipment hardpoints.
- Search Operations:Maritime and alpine detection missions with integrated sensor suites and extended loiter endurance.
Transport Operations command the largest share of program funding; Firefighting is climbing the fastest as climate adaptation budgets expand.
End User:
Volume concentration in defense procurement creates asymmetric supplier relationships, with performance-based logistics contracts transferring inventory risk to OEMs.
- Defense Sector:National military services with multi-decade platform lifecycles and integrated training ecosystems. United States, United Kingdom, and Indian Ministry of Defence programs anchor production schedules.
- Government Agencies:Coast guard and border patrol services with mixed civil-military mission profiles. Search and rescue mandates in Norway, Japan, and Canada shape specification priorities.
- Commercial Operators:Oil and gas sector transport and construction helicopter services.
- Civil Services:Police aviation and municipal emergency response units.
Defense Sector absorbs the bulk of installed capacity; Government Agencies are gaining share fastest as maritime security budgets expand.
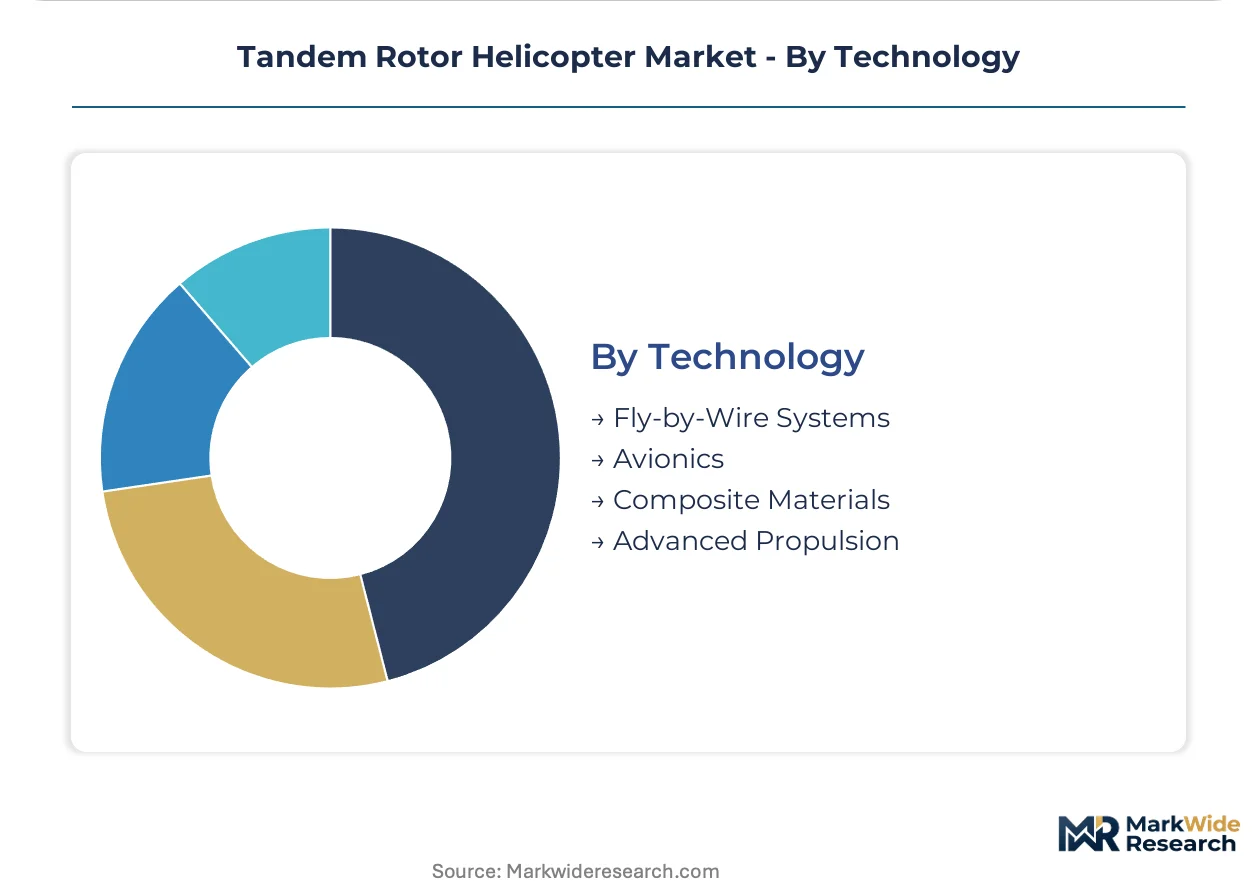
Technology:
Margin concentration in avionics and composite processing is displacing legacy hydraulics vendors as digital flight control architectures modularize supply chains.
- Composite Materials:Carbon-fiber reinforced polymer substitution in rotor hubs and transmission housings cuts empty weight while preserving structural load limits. FAA and EASA accelerated certification pathways are compressing qualification timelines for polymer-matrix airframe components.
- Fly-by-Wire Systems:Digital flight control interfaces reduce pilot workload and enable precision load placement in degraded visual environments. Military operators are mandating these architectures for new heavy-lift programs.
- Avionics:Glass cockpit systems requiring hybrid integration with analog-era hydraulic flight control linkages.
- Advanced Propulsion:Hybrid-electric auxiliary power units and turbine-electric architectures for range extension.
Composite Materials command premium positioning in new airframe programs; Fly-by-Wire Systems are expanding most quickly as military specifications harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States Army and Marine Corps vertical-lift modernization programs concentrate procurement volume in domestic production facilities. NATO alliance members are renewing aging heavy-lift fleets through multi-year frameworks. Maritime search and rescue agencies in Norway and Japan are expanding tandem rotor acquisitions for extended-range missions.
United States
Army Future Vertical Lift and Marine Corps heavy-lift programs drive sustained production demand at Boeing Vertol's Pennsylvania facilities. FAA Part 29 certification requirements govern civil variants while MIL-STD-810 testing applies to military configurations. Philadelphia-area manufacturing clusters specialize in rotor hub forgings and transmission assembly for defense contracts.
United Kingdom
Royal Air Force and Royal Navy heavy-lift requirements anchor demand for Chinook fleet sustainment and potential replacement programs. DEF STAN 00-970 design requirements apply to military rotorcraft alongside EASA CS-29 for civil operations. Southwest England maintenance hubs perform deep overhaul work on existing tandem rotor platforms.
Germany
Bundeswehr heavy-lift modernization and search and rescue fleet renewal create dual-track procurement opportunities. EASA CS-29 Amendment 7 crashworthiness standards tighten occupant protection mandates for transport-category operations. Bavaria-based engineering consultancies specialize in composite airframe certification for European helicopter programs.
India
Ministry of Defence indigenization initiatives seek foreign partners for domestic heavy-lift production under offset mandates. PLI scheme for aerospace components creates tariff advantages for local assembly operations. Bengaluru and Hyderabad clusters host joint venture facilities for military helicopter manufacturing and MRO services.
Japan
Coast Guard and Maritime Self-Defense Force search and rescue programs prioritize tandem rotor units for high-wind overwater operations. METI industrial policy supports domestic aerospace supply chain development through technology partnerships. Nagoya-area manufacturing centers produce transmission components for regional helicopter assembly programs.
Tandem Rotor Helicopter Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense integrators commanding premium positioning in military procurement cycles. The vendor base concentrates around established FAA Part 29 and MIL-STD-810 certification holders, creating barriers for new entrants. Three archetypes dominate: legacy military contractors with production infrastructure, civil heavy-lift specialists with EASA track records, and emerging Asian fabricators leveraging offset partnerships. Competitive moves center on performance-based logistics contracting and composite material certification acceleration.
Within the legacy defense contractor tier, Boeing Vertol and Lockheed Martin Corporation occupy positions sustained by Chinook production heritage and Sikorsky-Boeing Defiant program participation. Leonardo Helicopters and Airbus Helicopters exemplify the civil-military dual-track approach with Super Puma derivatives and European certification expertise. Korean Aerospace Industries represents the emerging partnership archetype, leveraging domestic industrial policy to capture offset-driven assembly opportunities.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Leonardo Helicopters |
| Boeing Vertol |
| Mitsubishi Heavy Industries |
| Russian Helicopters |
| Sikorsky Aircraft |
| Bell Textron |
| Korean Aerospace Industries |
| Airbus Helicopters |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between FAA Part 29 transport-category platforms and military MIL-STD-810 configurations splits both pricing power and supplier qualification burdens across divergent procurement channels. Premium-tier manufacturers command cost-per-flight-hour premiums through performance-based logistics contracts, while commodity-tier operators face margin compression from titanium supply constraints and dual-track validation overhead.
Pricing Analysis
Volume concentration in defense procurement absorbs program-scale discounts, while margin capture clusters in fly-by-wire avionics and composite rotor hub assemblies where Boeing Vertol and Sikorsky exercise supplier control. Price differentiation hinges on certification pedigree—FAA Part 29 and MIL-STD-810 track records command 15-25% premiums over uncertified alternatives—and on after-sales bundling through availability-based contracts. Cost compression in titanium-dependent rotating components is intensifying because Russian and Chinese sponge titanium feedstocks face Western sanctions, forcing substitution toward aerospace-grade aluminum-lithium alloys. Government agencies exhibit highest price sensitivity due to fixed parliamentary appropriations, while defense primes demonstrate lowest sensitivity where mission-critical specifications override unit cost.
Supply Chain Analysis
Dual-sourcing requirements for rotor hub forgings and transmission housings mandate Boeing Vertol and Airbus Helicopters to qualify secondary suppliers in Japan and South Korea alongside domestic Pennsylvania and Bavaria facilities. The supply chain draws from titanium sponge concentrated in Russia and China, carbon-fiber prepreg anchored in Japan and the United States, and precision gearing from German and Swiss machining clusters. Single-source vulnerability in Russian titanium feedstocks exposes Western programs to export control disruption, compounded by logistics chokepoints in Black Sea shipping lanes. Distribution runs through OEM-direct military procurement channels for defense variants and certified dealer networks for civil heavy-lift operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-fiber composite substitution and fly-by-wire digitization are displacing mechanical-hydraulic flight control architectures, compressing development cycles while extending platform lifecycles through retrofit pathways.
For Market Incumbents: Extend certification track record advantages into hybrid-electric auxiliary power unit retrofits, leveraging existing FAA Part 29 and MIL-STD-810 validation frameworks to capture aftermarket modernization demand. Threats from tiltrotor compound helicopter alternatives—promising speed advantages in contested logistics—demand accelerated composite material certification investment to preserve payload-density positioning. Capacity addition in Indian joint venture facilities under PLI scheme offsets creates tariff-advantaged assembly nodes for Asian defense procurement.
For New Entrants and Emerging Players: Fly-by-wire modularization as a technology-first wedge opens supplier entry points as avionics specialists displace legacy hydraulics vendors in Boeing Vertol and Sikorsky supply chains. Maritime search and rescue configurations for Norwegian and Japanese coastal agencies represent the most penetrable segment, with specification requirements less encumbered by multi-decade military training ecosystems. Go-to-market execution should anchor on EASA CS-29 Amendment 7 crashworthiness compliance as a certification differentiator against uncertified competitors.
For Investors and Strategic Acquirers: Exit pathways concentrate in defense contractor acquisition of composite airframe specialists and avionics modular suppliers, with Korean Aerospace Industries and emerging Indian joint ventures representing mid-cap consolidation targets. Long-term viability across the analysis window hinges on hybrid-electric technology maturation and sustainment contract renewal rates at United States Army and Marine Corps programs. Signal to watch: FAA accelerated certification pathway expansion for polymer-matrix components, which would compress qualification timelines and reshape competitive moats.
| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material Certification Acceleration | FAA and EASA streamlined pathways compress rotor hub qualification timelines for Boeing Vertol and Airbus Helicopters programs. |
| Hybrid-Electric Retrofit Kit Development | Convergence of turbine engines with battery-electric auxiliary units extends range for United States Army heavy-lift modernization. |
| Indian Joint Venture Assembly | PLI scheme tariff advantages position Bengaluru and Hyderabad facilities for Ministry of Defence offset fulfillment. |
| Performance-Based Logistics Contracting | Availability-hour pricing transfers inventory risk to OEMs in United States Army vertical-lift procurement frameworks. |
| Maritime SAR Specification Capture | Norwegian and Japanese coastal agency requirements eliminate tail rotor failure risks in high-wind overwater operations. |
Methodological Framework
Defense procurement databases, FAA type certificate records, and EASA CS-29 regulatory filings formed the secondary backbone, cross-referenced with customs trade data on titanium sponge and carbon-fiber prepreg movements. Primary interviews with rotorcraft program managers at Boeing Vertol and Airbus Helicopters, supply chain directors at transmission and avionics specialists, and procurement officers at United States Army Aviation and Missile Command validated demand assumptions. Bottom-up triangulation aggregated unit production forecasts by platform variant against top-down defense budget appropriation analysis across NATO members and Indo-Pacific operators.
Bottom-up modeling projected installed base renewal cycles and aftermarket parts consumption, while top-down analysis cross-checked against national defense white papers and vertical-lift modernization program disclosures. Segmentation dimensions spanned product type, application, end user, and technology adoption stage across the analysis window. CAGRs derived from regression analysis of historical procurement volumes weighted by program announcement timing, with composite material penetration rates and fly-by-wire specification mandates as primary forecast inputs.
Several conditions sit outside the modeled scope, including unannounced platform cancellations, geopolitical disruption to titanium supply channels, and breakthrough electrification architectures rendering tandem rotor configurations obsolete. Deviation in FAA or EASA certification timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Aircraft Ailerons Market
Aircraft
Asia-Pacific Military Helicopters Market
Aircraft
Military Aircraft Market
Aircraft
Global Helicopter Market
Aircraft
Aircraft Container & Pallet Loader Market
Aircraft
Search and Rescue Aircraft Market
Aircraft
Global Business Aircraft Market
Aircraft
Amphibious Aircraft Market
Aircraft
Middle-East and Africa Turboprop Aircraft Market
Aircraft
High-Bypass Engine Nacelle External Aerodynamic Optimization Kits Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Asia-Pacific Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Manufacturing Market
Aircraft
Strategic Bomber Market
Aircraft
South Korea Aerospace and Defense Market
Aircraft
Aerospace Turbojet Market