
 Italy Space Electronics Market | 2026-2036
Italy Space Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Space Electronics Market Insights
Italian space electronics manufacturing is pivoting toward higher-reliability satellite subsystems. Thales Alenia Space leverages its Turin and Rome facilities to sustain dual-use production lines for both civilian and defense orbital platforms. Leonardo anchors Italy's position in radar and electronic warfare payloads through concentrated R&D spending in Milan and Pomezia. Sitael competes in the small satellite and electric propulsion segment, differentiating through in-house microsatellite bus integration.
Italy space electronics encompasses radiation-hardened semiconductors, power conditioning units, and telemetry command subsystems engineered for operation in orbital environments with total ionizing dose thresholds exceeding 100 krad(Si). These components enable continuous function in vacuum conditions across temperature swings from minus 150 to plus 120 degrees Celsius, serving telecommunications constellations and Earth observation constellations as primary demand anchors. Satellite Components leads product type revenue generation due to recurring replacement cycles in geostationary platforms, while Ground Systems registers the fastest expansion as Italy builds downlink infrastructure for Copernicus and IRIS² participation. Government Agencies dominate end user procurement through ASI and Ministry of Defense contracts, though Private Companies are capturing share in the emerging in-orbit servicing and space situational awareness sectors.
ASI coordinates national space policy under Italy's Space Economy National Plan, while EU Green Deal and F-Gas Regulation compliance requirements shape thermal control subsystem specifications for European launchers. BIS and CE marking standards govern terrestrial testing and qualification protocols for flight electronics exported beyond Italian borders. Stakeholders must monitor how ESA's Terrae Novae exploration roadmap redirects procurement priorities toward lunar and deep-space qualified electronics.
Market Dynamics
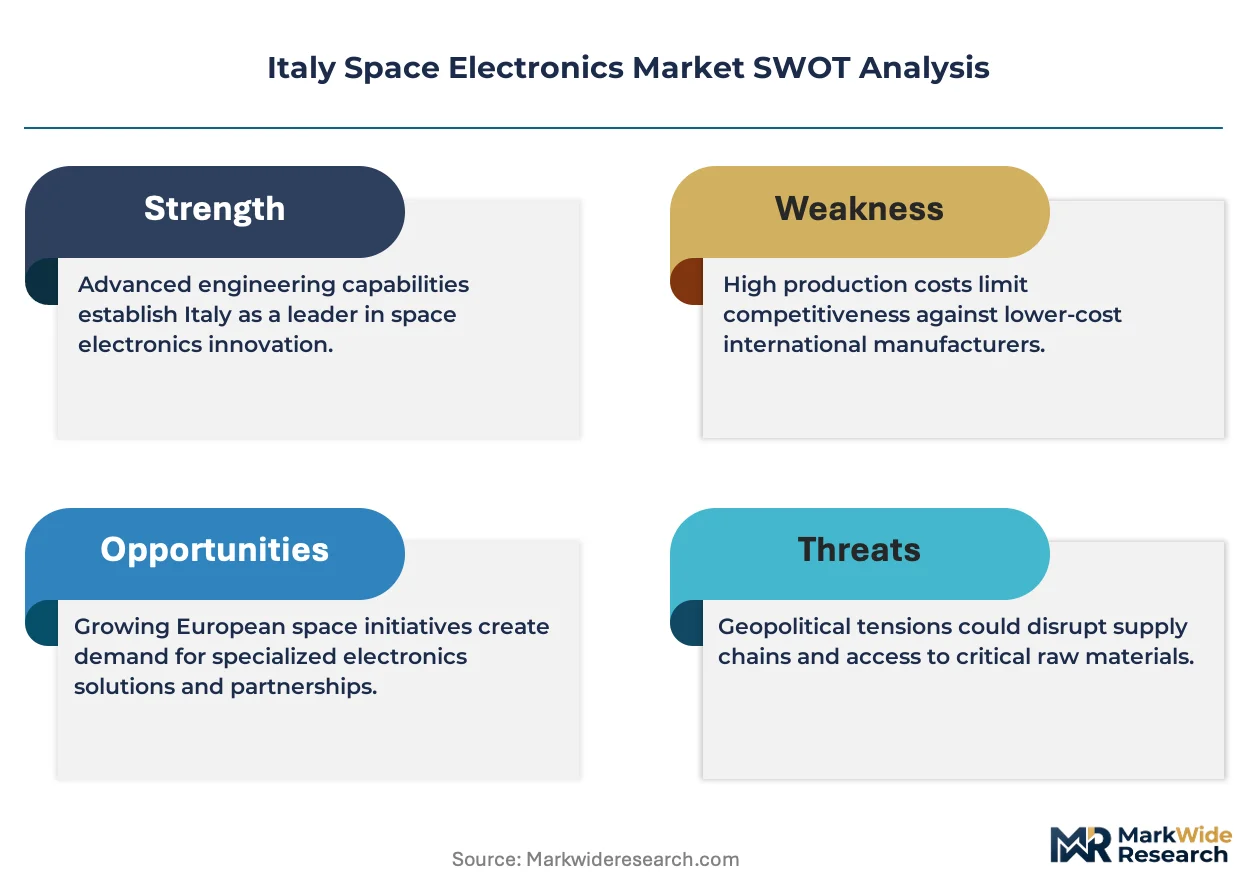
Italy's space electronics sector is restructuring around EU funding conditionality that ties procurement to domestic capability thresholds, forcing suppliers to relocate testing and qualification infrastructure to the Lazio corridor.
Growth Catalysts
- EU Space Programme alignment:Italy's Space Economy National Plan channels ASI and Ministry of Defense contracts toward components qualified under ESA standards, creating predictable demand pipelines for radiation-hardened subsystem manufacturers.
- IRIS² constellation buildout:Secure connectivity satellite procurement is accelerating ground segment investments, with Lazio-based integrators capturing downlink infrastructure contracts.
- Electric propulsion adoption:Hall-effect thruster integration into small satellite buses is expanding addressable market for power conditioning units engineered for kilowatt-class orbital maneuvering.
Market Restraints
- Rad-hard semiconductor supply concentration:Foundry capacity for 100 krad(Si)-qualified wafers concentrates in a single European supplier, creating single-source vulnerability for telemetry command subsystems.
- F-Gas Regulation compliance costs:EU thermal control mandates are forcing redesign of heritage satellite cooling loops, extending qualification timelines for established product lines.
- Geostationary replacement cycle compression:Extended operational lifespans of existing telecom platforms are deferring procurement of new flight electronics, pressuring near-term revenue recognition.
Strategic Opportunities
- In-orbit servicing emergence:Docking mechanism electronics and refueling sensors represent unpenetrated demand from emerging private operators seeking life-extension capabilities for aging constellations.
- Copernicus downstream expansion:Earth observation data commercialization is creating procurement pull for edge-processing payloads that reduce downlink bandwidth requirements.
- Dual-use technology convergence:Defense electronic warfare specifications are migrating into civilian radar payloads, opening cross-funded R&D pathways through Ministry of Defense programs.
Industry Challenges
- Radiation effects engineering talent scarcity:Total ionizing dose modeling and single-event upset mitigation expertise concentrates among retiring specialists, constraining design team scaling.
- CE marking timeline variability:BIS terrestrial testing protocols for flight electronics exports exhibit inconsistent interpretation across notified bodies, creating certification uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Space Electronics Market |
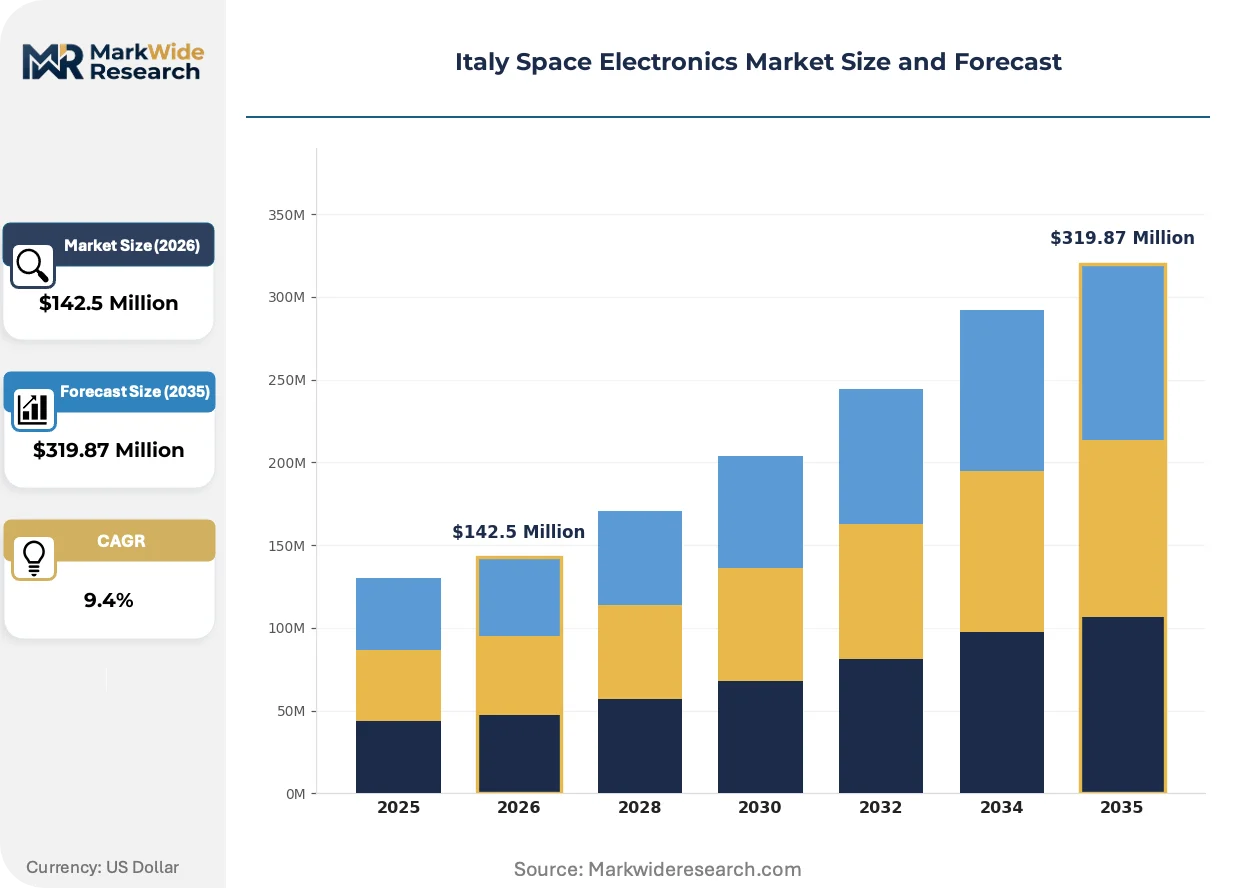
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $319.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Satellite Components, Ground Systems, Launch Vehicle Electronics, Payload Systems Application: Telecommunication, Earth Observation, Scientific Research, Navigation Technology: Microelectronics, Power Systems, Control Systems, Communication Systems End User: Government Agencies, Private Companies, Research Institutions, Defense Contractors |
| Companies Covered | Thales Alenia Space, Leonardo, Sitael, STMicroelectronics, Telespazio, Airbus Italia, Intecs Solutions, Leaf Space, Antech Space, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Space Electronics Market Trends and Innovations
Italian manufacturers are reconfiguring product architectures around modularity mandates from prime contractors, compressing non-recurring engineering costs while accelerating platform customization.
Gallium nitride power conversion is consolidating position in satellite bus electrical systems. The material enables higher switching frequencies at reduced thermal mass compared to silicon heritage designs. ASI-funded science missions and commercial constellation operators are adopting GaN-based conditioning units for mass-constrained small satellites. This transition is consolidating supplier tiers as only Turin and Rome facilities possess the cleanroom infrastructure for space-qualified GaN packaging.
EU Green Deal thermal specifications are forcing subsystem redesign across European launch vehicle programs. F-Gas Regulation phase-down schedules are accelerating adoption of alternative working fluids in satellite thermal control loops. Italian payload integrators serving Ariane and Vega launchers must requalify heritage hardware under revised environmental protocols, compressing development calendars for deep-space missions.
Consolidated procurement through ASI central contracting is displacing fragmented agency purchasing. Prime contractors now bid integrated satellite solutions rather than discrete component lots, compressing Tier 2 supplier margins. This concentration is most visible in Lazio, where Thales Alenia Space and Leonardo have absorbed previously independent subsystem vendors into captive supply chains for government orbital platforms.
Italy Space Electronics Market Segmentation
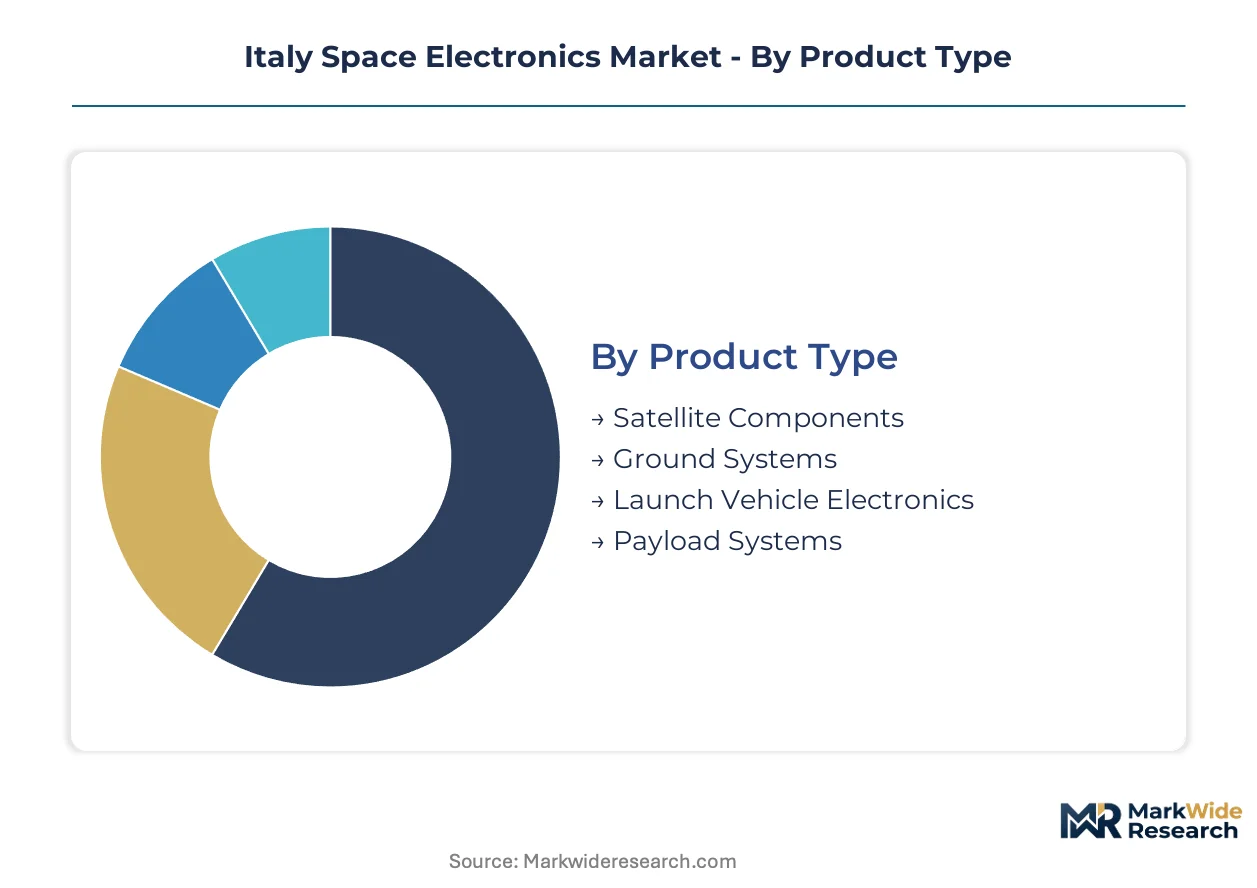
Italy's space electronics procurement flows through distinct technical and institutional channels. Understanding how satellite subsystems, ground infrastructure, and payload electronics partition across end-users reveals where ASI funding concentrates and where private operators are penetrating.
Product Type:
Standalone flight hardware dominates procurement volumes, while embedded subsystem integration is accelerating as prime contractors consolidate supply chains.
- Satellite Components:Radiation-hardened semiconductors, power conditioning units, and telemetry command subsystems engineered for 100 krad(Si) total ionizing dose thresholds. Demand concentrates in Lazio's Rome-Turin corridor from Thales Alenia Space and Leonardo prime contracting, driven by recurring replacement cycles in geostationary telecommunications platforms.
- Ground Systems:Downlink infrastructure, mission control terminals, and data processing centers supporting constellation operations. Procurement is accelerating in the Lazio region from IRIS² secure connectivity buildout and Copernicus participation requirements, with ASI central contracting displacing fragmented agency purchasing.
- Launch Vehicle Electronics:Avionics packages and guidance subsystems for Ariane and Vega launcher families.
- Payload Systems:Instrument-specific electronics for Earth observation and scientific mission packages.
Satellite Components leads volumes today; Ground Systems is gaining share fastest.
Application:
Commercial telecommunications anchor procurement scale, while Earth observation and scientific missions reshape technical specifications through EU programme alignment.
- Telecommunication:Geostationary and low-Earth-orbit constellation electronics for broadband and secure government communications. Procurement flows through ASI and Ministry of Defense contracts under Italy's Space Economy National Plan, though extended operational lifespans of heritage platforms are compressing near-term replacement demand.
- Earth Observation:Synthetic aperture radar and optical payload electronics for Copernicus programme participation. Italian integrators in Milan and Pomezia are capturing downstream commercialization opportunities through edge-processing payloads that reduce downlink bandwidth requirements.
- Scientific Research:Instrumentation electronics for ASI-funded exploration and astronomy missions.
- Navigation:Signal generation and timing subsystems for Galileo programme contribution.
Telecommunication leads volumes today; Earth Observation is climbing the fastest.
Technology:
Power conversion and microelectronics concentrate manufacturing investment, while control and communication systems face margin pressure from modular architecture mandates.
- Microelectronics:Radiation-hardened integrated circuits and application-specific integrated circuits for orbital computing. Foundry capacity for qualified wafers concentrates at a single European supplier, creating single-source vulnerability for telemetry command subsystem manufacturers.
- Power Systems:Gallium nitride-based conditioning units and battery management electronics for small satellite buses. Turin and Rome facilities with space-qualified GaN cleanroom infrastructure are consolidating supplier tiers as ASI-funded missions adopt higher switching frequency designs.
- Control Systems:Attitude determination and orbital maneuvering electronics.
- Communication Systems:Transponder and antenna pointing control subsystems.
Power Systems leads volumes today; Microelectronics faces the steepest supply concentration constraints.
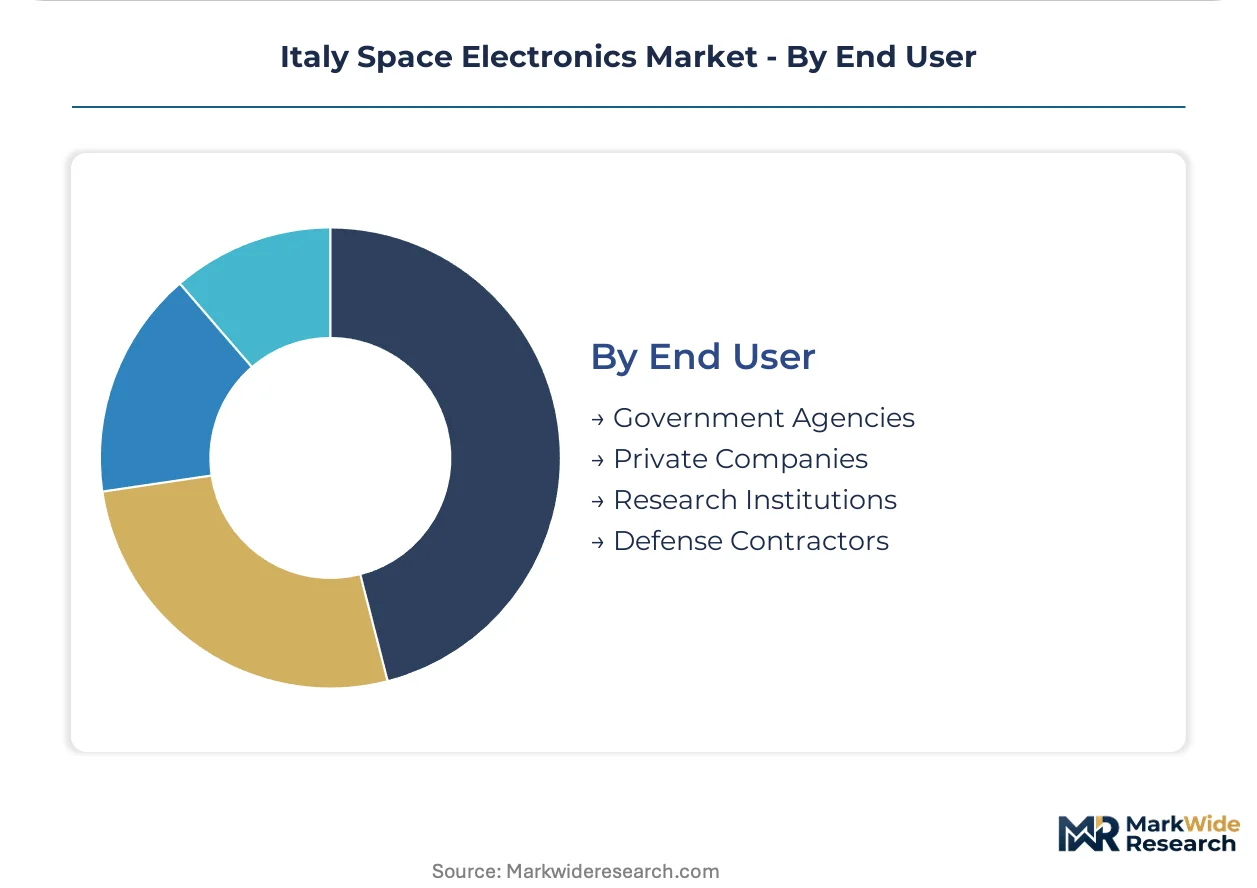
End User:
Government procurement dominates contract value, while private operators and research institutions fragment demand across specialized mission profiles.
- Government Agencies:ASI and Ministry of Defense procurement for dual-use orbital platforms. Centralized contracting under Italy's Space Economy National Plan is compressing Tier 2 supplier margins as primes bid integrated satellite solutions rather than discrete component lots.
- Private Companies:Commercial constellation operators and emerging in-orbit servicing ventures. Demand for docking mechanism electronics and refueling sensors is penetrating from life-extension service providers seeking capabilities for aging constellations.
- Research Institutions:University and laboratory electronics for technology demonstration missions.
- Defense Contractors:Classified payload electronics for electronic warfare and signals intelligence platforms.
Government Agencies lead volumes today; Private Companies show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between ESA funding jurisdictions are redirecting qualification infrastructure toward regions with streamlined ESA-ECSS certification pathways. Italy's Space Economy National Plan exploits this arbitrage by concentrating testing assets in Lazio, capturing procurement that might otherwise migrate to France or Germany.
Lombardy
Milan anchors Italy's radar and electronic warfare payload development through Leonardo's concentrated R&D spending. The region captures Ministry of Defense dual-use contracts that channel civilian technology into defense orbital platforms. ASI-funded science mission electronics undergo final integration at Pomezia facilities south of Rome, but Milan-based design teams originate the architectures.
Piedmont
Turin hosts Thales Alenia Space manufacturing for both civilian telecommunications constellations and defense platforms. The facility's cleanroom infrastructure supports gallium nitride power conditioning unit packaging for small satellite buses. EU Green Deal thermal specifications are forcing redesign of heritage cooling loops at this site, compressing development calendars for deep-space missions.
Lazio
Rome's space industrial cluster concentrates satellite component procurement from government agencies under centralized ASI contracting. The region is absorbing testing and qualification infrastructure relocated from other Italian regions to meet EU Space Programme funding conditionality. IRIS² secure connectivity ground segment investments are accelerating fastest here, with downlink infrastructure contracts captured by Lazio-based integrators.
Veneto
Padua and Venice metropolitan areas host specialized suppliers for telemetry command subsystems and radiation-hardened semiconductor packaging. These facilities serve as Tier 2 vendors to prime contractors in Lazio and Piedmont. F-Gas Regulation compliance costs are forcing thermal control subsystem redesigns that extend qualification timelines for established product lines manufactured in this region.
Italy Space Electronics Market Competitive Landscape
Lazio and Piedmont producers anchor the prime contractor tier; Lombardy specialists hold the payload electronics segment. The market structure concentrates around three to four vertically integrated groups that absorbed previously independent subsystem vendors. Two strategic archetypes dominate: dual-use platform integrators serving ASI and Ministry of Defense contracts, and electric propulsion specialists capturing small satellite bus demand. Competitive moves center on captive supply chain absorption and cleanroom infrastructure expansion for gallium nitride packaging.
Within the prime contractor tier, Thales Alenia Space and Leonardo occupy positions exemplifying dual-use integration capability. Thales Alenia Space represents the geography-anchored archetype with Turin and Rome facilities sustaining production lines for both civilian and defense orbital platforms. Leonardo exemplifies the R&D-intensive payload specialist through concentrated spending in Milan and Pomezia for radar and electronic warfare electronics. Sitael sits within the emerging specialist archetype, competing in small satellite and electric propulsion segments through in-house microsatellite bus integration.
| Leading Market Players |
|---|
| Thales Alenia Space |
| Leonardo |
| Sitael |
| STMicroelectronics |
| Telespazio |
| Airbus Italia |
| Intecs Solutions |
| Leaf Space |
| Antech Space |
| Others |
Pricing and Supply Chain Analysis
Captive supply chain absorption by Thales Alenia Space and Leonardo anchors both procurement leverage and margin defense in Italy's space electronics sector. Prime contractors' backward integration into radiation-hardened subsystem manufacturing concentrates pricing power with Lazio and Piedmont producers serving ASI and Ministry of Defense contracts.
Pricing Analysis
Direct-to-OEM contracting compresses distributor margins as ASI central purchasing displaces fragmented agency procurement. Three-tier pricing structure across radiation-hardened, automotive-grade, and commercial-off-the-shelf qualification levels reflects ESA certification investment and volume scale. Cost compression in heritage geostationary replacement cycles is intensifying because extended operational lifespans defer new flight electronics procurement. Private constellation operators exhibit highest price sensitivity; defense contractors absorbing Ministry of Defense dual-use contracts show lowest.
Supply Chain Analysis
Workforce scarcity in radiation effects engineering concentrates manufacturing investment in Turin and Rome facilities with established cleanroom infrastructure. Foundry capacity for qualified wafers draws from a single European supplier, creating single-source vulnerability for telemetry command subsystem producers. Gallium nitride substrates and rad-hard semiconductor packaging feed from specialized Tier 2 vendors in Veneto serving prime contractors in Lazio and Piedmont. Distribution runs through ESA-qualified integrator networks with CE marking protocols governing terrestrial testing for export-bound flight electronics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's space electronics market compounds steadily through EU Space Programme funding conditionality that locks in domestic procurement pipelines. ASI central contracting under the Space Economy National Plan creates predictable demand anchoring for qualified subsystem manufacturers.
For Market Incumbents: Lock in captive supply of radiation-hardened semiconductor packaging capacity at Turin and Rome cleanroom facilities to defend against emerging electric propulsion specialists capturing small satellite bus demand. Deepen backward integration into gallium nitride power conditioning unit manufacturing before F-Gas Regulation compliance costs extend competitor qualification timelines.
For New Entrants and Emerging Players: Enter via in-orbit servicing electronics for life-extension capabilities targeting aging telecommunications constellations, the most penetrable segment as private operators fragment from ASI-dominated procurement. Pursue edge-processing payload development for Copernicus downstream commercialization through partnerships with Milan-based radar integrators.
For Investors and Strategic Acquirers: Roll-up economics work for specialized telemetry command subsystem vendors because ESA qualification barriers prevent rapid new entrant replication and prime contractor consolidation has displaced independent Tier 2 suppliers. Target facilities with existing 100 krad(Si) testing infrastructure in the Lazio corridor. Watch ASI Terrae Novae exploration roadmap procurement redirection toward lunar-qualified electronics as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Infrastructure Expansion | Turin and Rome facilities capture gallium nitride packaging demand from ASI-funded small satellite missions. |
| ESA Qualification Investment | ECSS certification pathways in Lazio attract procurement that might otherwise migrate to French or German competitors. |
| Dual-Use Technology Convergence | Ministry of Defense electronic warfare specifications open cross-funded R&D pathways for civilian radar payloads. |
| In-Orbit Servicing Capability Buildout | Docking mechanism electronics address unpenetrated demand from private life-extension service providers. |
| Copernicus Downstream Partnership | Edge-processing payload integration with Milan-based Leonardo facilities reduces constellation downlink bandwidth requirements. |
Research Methodology
Coverage spans Italy's Lazio, Piedmont, Lombardy and Veneto regions, with primary inputs from each corridor's prime contractor engineering directors, ASI procurement officials, Tier 2 subsystem vendor technical leads, and Ministry of Defense program managers. Secondary validation draws from ESA contract award databases, ASI annual reports, EU Space Programme funding disclosures, and ECSS standard documentation. Bottom-up segment sizing triangulates against top-down EU space economy expenditure aggregates.
Rate-of-change decomposition separates volume growth from mix shift across satellite components, ground systems, and payload electronics over the projection horizon. Segmentation dimensions modeled include product type, application, technology tier, and end-user procurement channel, with ESA funding allocation patterns and F-Gas Regulation compliance timelines as industry-specific forecast inputs. CAGRs derive from fitted growth curves anchored to disclosed contract values and prime contractor capacity expansion announcements.
The model holds under sustained EU Space Programme funding and stable ESA-ASI procurement coordination; deviation in radical hardening requirements for lunar or deep-space missions would shift component qualification timelines and foundry allocation priorities. Material deviation in rad-hard semiconductor foundry capacity or IRIS² constellation deployment schedules warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
Space-Based C4ISR Market
Space
France Space Electronics Market
Space
Near Space Robotics Market
Space
Space Ground Station Equipment Market
Space
Space Service Market
Space
India Aviation, Defense, and Space Market
Space
South Korea Space Electronics Market
Space
Africa Space Electronics Market
Space
Space Debris Monitoring and Removal Market
Space
Europe Space Electronics Market
Space
Space Transportation Market
Space
Space Launch Services Market
Space
Space Mining Market
Space
US Space Launch Services Market
Space
Japan Space Electronics Market
Space
Suborbital Space Tourism Market