
 Global Ultralight and Light Aircraft Market | 2026-2036
Global Ultralight and Light Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultralight and Light Aircraft Market Outlook
Buyer concentration is rebalancing across flight schools and agricultural operators as individual aviation enthusiasts fragment into smaller purchasing units. Textron Aviation leverages its Cessna brand heritage and certified training aircraft portfolio to sustain institutional contracts with North American academies. Pipistrel specializes in electric propulsion architectures and competes aggressively in the European light sport segment through Slovenia-based manufacturing.
Ultralight and light aircraft encompass fixed-wing and weight-shift controlled machines operating below maximum takeoff weight thresholds, typically constructed from aluminum alloys, carbon fiber composites, or fabric-covered steel tube frames for recreational, training, and utility missions. Kit planes occupy the premium margin pool where owner-assembled certification reduces regulatory burden and manufacturing overhead. Gliders retain mature demand in European alpine regions while powered paragliders capture emerging recreational interest across Southeast Asian tourism markets.
FAA Part 103 governs ultralight vehicle operations in the United States while EASA CS-LSA standardizes light sport aircraft certification across European member states, with both frameworks directly shaping product design constraints and market access conditions. ISO 2244 and ASTM F2245 provide international baseline safety and construction standards that manufacturers must navigate for cross-border sales eligibility. Stakeholders must monitor evolving electric propulsion certification pathways and battery energy density thresholds as these technical boundaries will determine next-generation product viability and geographic market permissions.
Market Dynamics
Electric propulsion certification pathways are compressing product development timelines while battery energy density thresholds determine which airframe architectures achieve commercial viability. FAA and EASA rulemaking on electric light sport aircraft is forcing manufacturers to redesign powertrain integration strategies ahead of formal standards publication.
Growth Catalysts
- FAA Part 103 ultralight framework:The United States maintains minimal pilot certification requirements for vehicles under 254 pounds empty weight, sustaining accessible entry points for recreational aviation enthusiasts and homebuilt kit purchasers.
- Carbon fiber composite manufacturing:Automated fiber placement and resin transfer molding are reducing airframe weight ratios while improving fatigue resistance for high-cycle training operations.
- Flight school fleet renewal:North American and European academies are replacing aging piston trainers with modern light sport aircraft featuring glass cockpit avionics and reduced fuel consumption profiles.
Market Restraints
- Lithium-ion battery cost volatility:Electric propulsion architectures face input price uncertainty from cathode material supply concentration in China, compressing margin projections for battery-powered ultralight designs.
- Aviation gasoline supply fragmentation:100LL fuel availability is contracting at rural airfields across the United States and Australia, stranding conventional piston aircraft in regions lacking alternative fuel infrastructure.
- EASA CS-LSA certification timeline:European light sport aircraft approval processes average 18-24 months, creating regulatory friction against faster-moving experimental amateur-built categories.
Strategic Opportunities
- Southeast Asian tourism markets:Powered paragliders and weight-shift trikes are capturing emerging recreational demand in Thailand and Vietnam where coastal infrastructure supports low-cost aerial experience packages.
- EU Green Deal aviation incentives:European member states are introducing purchase subsidies and operating tax exemptions for electric light sport aircraft, accelerating fleet electrification timelines.
- Direct-to-consumer digital sales:Kit plane manufacturers are bypassing traditional dealer networks through online configuration tools and factory-supported builder assistance programs, capturing margin previously allocated to distribution intermediaries.
Industry Challenges
- Composite technician scarcity:Airframe repair stations face qualified labor shortages for carbon fiber damage assessment and scarf repair techniques, extending aircraft-on-ground durations for training fleet operators.
- Electric propulsion integration complexity:Battery thermal management systems and motor controllers require avionics software competencies absent from traditional airframe and powerplant mechanic training curricula.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultralight and Light Aircraft Market |
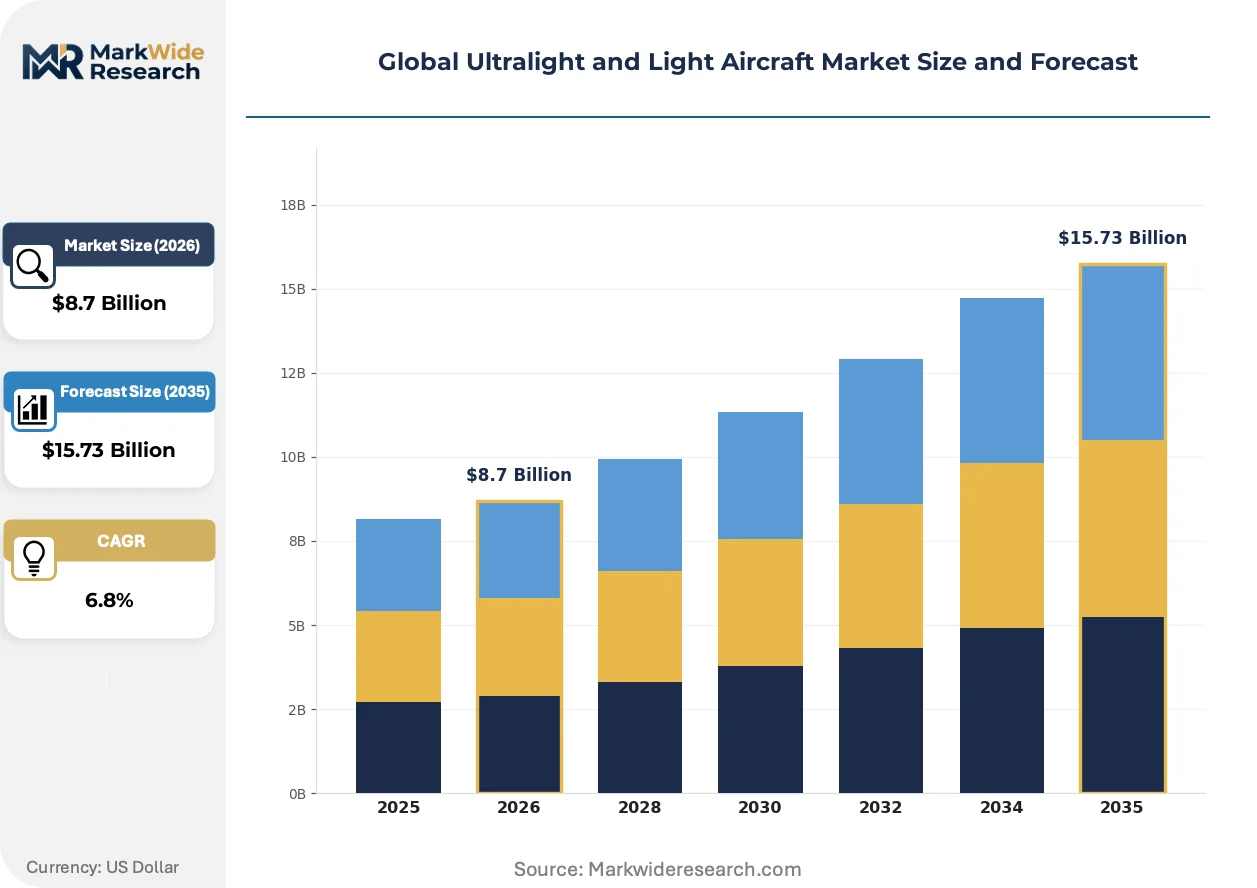
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Trikes, Kit Planes, Gliders, Powered Paragliders Application: Recreational Flying, Flight Training, Agricultural Use, Aerial Photography End User: Aviation Enthusiasts, Flight Schools, Agricultural Producers, Photography Businesses Distribution Channel: Direct Sales, Online Retail, Aircraft Dealers, Trade Shows |
| Companies Covered | Textron Aviation, Cirrus Aircraft, Pilatus Aircraft, Piper Aircraft, Cessna Aircraft Company, Costruzioni Aeronautiche TECNAM SpA, Flight Design General Aviation GmbH, Pipistrel, Evektor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultralight and Light Aircraft Market Strategic Shifts
Propulsion electrification is rewriting airframe design constraints while digital manufacturing tools compress kit plane assembly timelines. Regulatory frameworks are racing to catch up with battery chemistries and autonomous flight software capabilities.
Electric distributed propulsion is converging with conventional fixed-wing architectures to enable novel vertical takeoff configurations previously impractical with piston engines. Flight schools in Germany and Australia are evaluating twin-motor electric trainers for reduced noise footprint and simplified maintenance protocols. This convergence is compressing the performance gap between light sport and general aviation categories for sub-600 kg operations.
EASA CS-LSA amendments addressing electric propulsion certification are forcing manufacturers to submit battery management system documentation alongside traditional airframe stress analysis. Slovenian and Czech producers are accelerating type certificate applications to secure first-mover positioning before harmonized standards finalize. Light sport segments with shorter design cycles are absorbing these compliance costs more readily than legacy ultralight categories.
Builder-assist programs are displacing pure kit assembly for time-constrained owner-pilots seeking experimental amateur-built certification benefits without multi-year construction commitments. Factory completion centers in the United States and Czech Republic now offer supervised build environments where manufacturers retain quality control over critical structural assemblies. This hybrid procurement model concentrates in markets where regulatory familiarity with experimental categories supports resale value retention.
Global Ultralight and Light Aircraft Market Segmentation
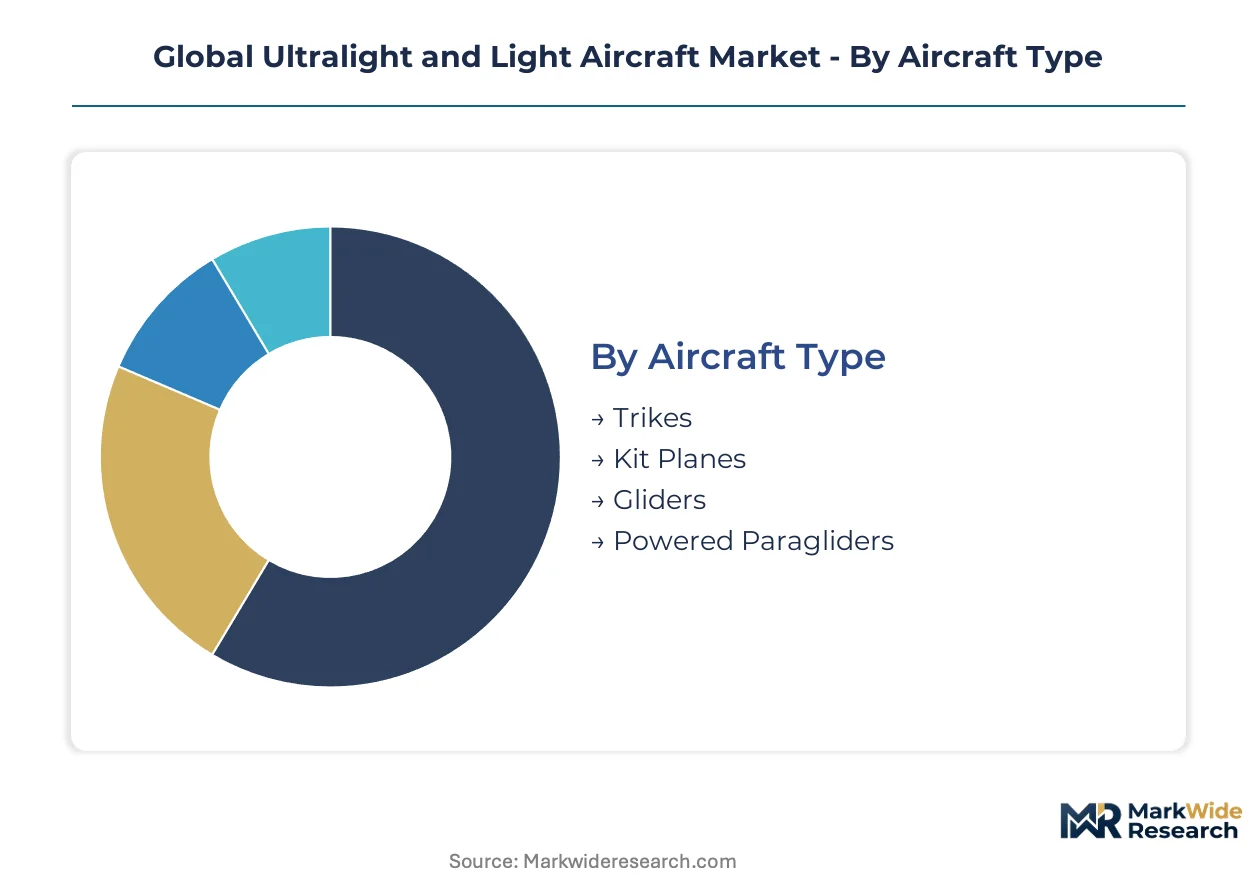
Segmentation in the ultralight and light aircraft market determines regulatory pathways, pricing tiers, and customer acquisition costs. Certification requirements vary dramatically across aircraft categories, creating distinct margin structures and geographic market access conditions for manufacturers.
Aircraft Type:
Certification burden fragments sharply across this dimension: FAA Part 103 exempts the lightest categories from pilot licensing entirely, while EASA CS-LSA imposes design standards that kit plane assemblers navigate through owner-built experimental pathways.
- Trikes:Weight-shift controlled aircraft with fabric wings mounted on tricycle undercarriages, typically constructed from aluminum tubing and Dacron sailcloth. Demand concentrates in Australian coastal tourism corridors and Thai aerial experience operators where minimal training requirements reduce customer acquisition friction. FAA Part 103 compliance allows rental operations without commercial pilot certification in the United States.
- Kit Planes:Owner-assembled airframes sold in component form, spanning metal, composite, and tube-and-fabric construction methods. German and Czech manufacturers dominate this segment through builder-assist programs that compress assembly timelines while preserving experimental amateur-built regulatory benefits. EASA oversight of kit documentation creates 12-18 month approval timelines versus faster FAA experimental certification in the United States.
- Gliders:Unpowered fixed-wing aircraft optimized for thermal soaring, constructed from fiberglass or carbon fiber composite shells. European alpine clubs in Switzerland and Austria sustain mature demand through shared-ownership structures.
- Powered Paragliders:Backpack-mounted propulsion units attached to ram-air wings, offering the lowest entry cost and weight footprint. Vietnamese and Indonesian tourism operators are expanding fleet orders for coastal aerial photography packages.
Leading the category by volume: Kit Planes. Growing fastest: Powered Paragliders.
Application:
Cost tier stratification separates recreational entry points from commercial utility missions, with training operations commanding premium pricing for certified aircraft and agricultural applications requiring specialized equipment integration.
- Recreational Flying:Personal aviation for sport and leisure, spanning weekend cross-country touring to local sightseeing circuits. Australian and United States enthusiasts drive demand for trikes and powered paragliders where weather patterns support year-round operations.
- Flight Training:Structured pilot certification programs operating certified light sport aircraft with dual controls and glass cockpit avionics. North American academies are replacing aging Cessna 152 fleets with modern Rotax-powered trainers featuring reduced fuel burn and simplified maintenance protocols.
- Agricultural Use:Crop dusting and aerial application missions requiring reinforced airframes and chemical hopper integration. Brazilian and Argentine operators favor low-wing kit plane configurations for spray boom stability.
- Aerial Photography:Commercial imaging and survey missions demanding stable platforms with camera mount integration. German and Austrian operators combine glider tow launches with electric sustainer motors for silent thermal photography.
Flight Training commands the highest average transaction values. Aerial Photography is expanding most quickly on tourism and surveying demand.
End User:
Customer type determines procurement channel preferences and aftermarket service expectations, with institutional buyers prioritizing fleet standardization and individual enthusiasts accepting higher variability for customization flexibility.
- Aviation Enthusiasts:Individual owner-pilots purchasing for personal recreation, spanning kit plane builders to ready-to-fly trike operators. United States buyers favor direct manufacturer relationships and online configuration tools that bypass traditional dealer markups.
- Flight Schools:Institutional training operators requiring type-certified aircraft with documented maintenance histories and parts availability guarantees. European academies concentrate procurement with Slovenian and Czech manufacturers offering EASA CS-LSA type certificates and regional service networks.
- Agricultural Producers:Farming cooperatives and aerial application contractors operating specialized spray aircraft. Brazilian soybean belt operators prioritize payload capacity and chemical corrosion resistance over fuel efficiency metrics.
- Photography Businesses:Commercial imaging studios and survey contractors integrating stabilized camera gimbals and LiDAR sensors. German operators favor electric sustainer gliders for reduced noise footprint in protected airspace corridors.
Flight Schools represent the most concentrated purchasing volume. Photography Businesses are gaining share fastest on content creation and infrastructure inspection demand.
Distribution Channel:
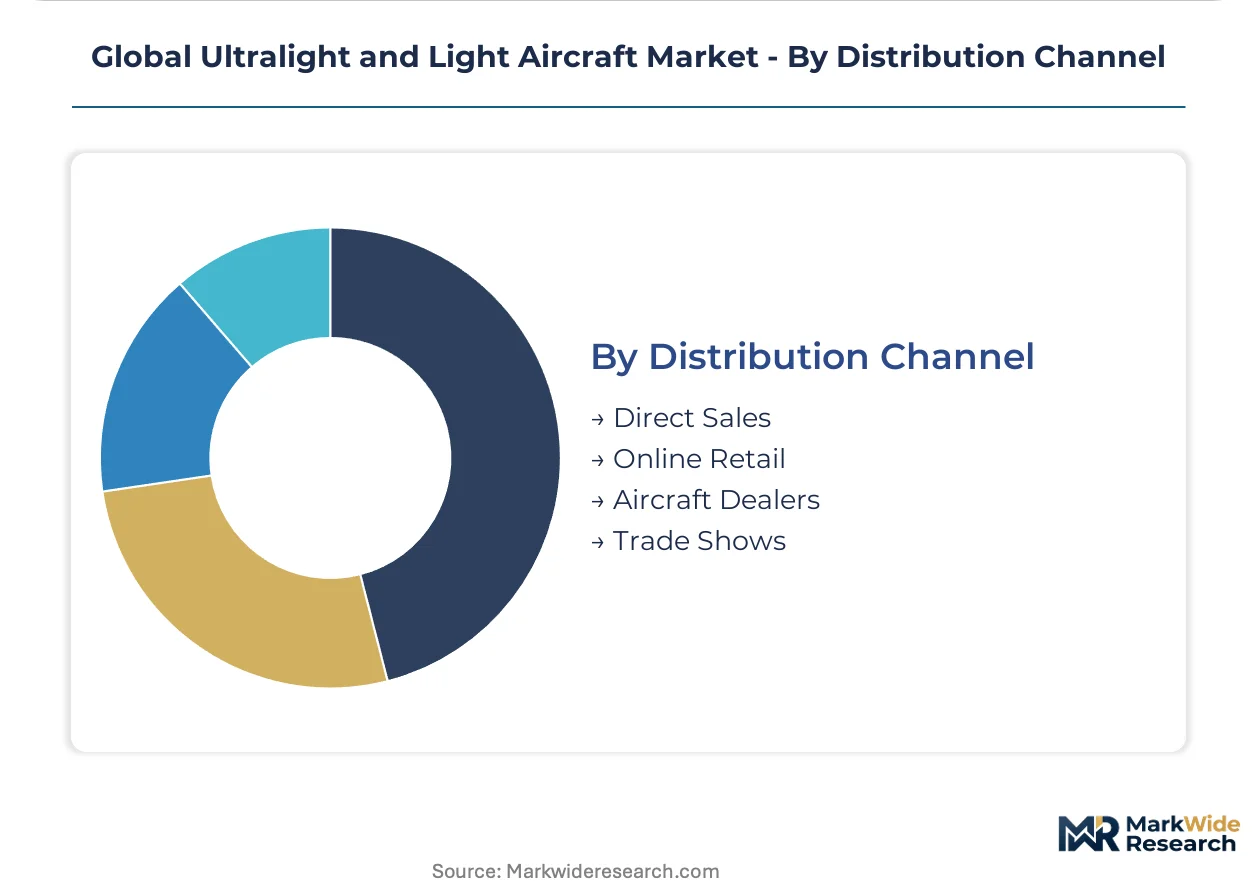
Supply concentration varies dramatically across channels, with direct sales capturing margin from dealer networks while trade shows sustain relationship-based procurement in experimental amateur-built categories.
- Direct Sales:Manufacturer-to-customer transactions spanning factory showrooms, phone consultations, and digital configuration platforms. Czech and Slovenian producers leverage direct channels to control pricing and capture margin previously allocated to independent dealers.
- Online Retail:E-commerce platforms for parts, accessories, and complete aircraft configurations with remote builder support. United States kit plane manufacturers use video documentation and factory-assisted build programs to reduce customer completion timelines.
- Aircraft Dealers:Independent and manufacturer-authorized retail networks offering demonstration flights, financing, and local service. Australian trike distribution runs through regional dealers with coastal tourism operator relationships.
- Trade Shows:Exhibition-based sales at events including AirVenture Oshkosh and AERO Friedrichshafen where manufacturers debut prototypes and secure fleet commitments. German and United States shows dominate order intake for experimental category aircraft.
Direct Sales leads the category by volume. Online Retail is climbing the fastest on digital-native buyer demographics and factory-assisted build program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational aviation infrastructure concentrates in the United States, Germany, and Australia, where pilot training networks and regulatory frameworks sustain fleet demand. Flight school expansions and kit plane manufacturing clusters anchor regional output variations.
United States
Flight academies in Florida and Arizona are replacing aging piston trainers with modern Rotax-powered light sport aircraft. FAA Part 103 maintains minimal certification requirements for ultralight vehicles under 254 pounds empty weight, preserving accessible entry points for homebuilt enthusiasts. The Sun Belt corridor from Texas to California hosts the densest concentration of kit plane manufacturers and builder-assist completion centers.
Germany
European light sport aircraft certification timelines average 18-24 months, creating regulatory friction that domestic manufacturers navigate through experimental amateur-built pathways. EASA CS-LSA amendments addressing electric propulsion are forcing battery management system documentation alongside traditional airframe stress analysis. Bavarian and Baden-Württemberg regions cluster glider clubs and electric sustainer motor integration specialists serving alpine tourism operators.
Australia
Coastal tourism corridors in Queensland and New South Wales sustain trike and powered paraglider rental operations where minimal training requirements reduce customer acquisition friction. The country's national aviation regulator maintains recreational aviation standards that align with FAA frameworks for weight-shift controlled aircraft. Sydney and Melbourne metropolitan areas concentrate flight schools transitioning fleets to glass cockpit avionics and reduced fuel consumption profiles.
Brazil
Agricultural spray operators in Mato Grosso and São Paulo states favor low-wing kit plane configurations for crop dusting stability and chemical hopper integration. ANVISA oversight of aerial application chemicals intersects with aviation certification requirements for reinforced airframes. The soybean belt drives specialized equipment demand where payload capacity and corrosion resistance outweigh fuel efficiency metrics.
Thailand
Powered paragliders and weight-shift trikes capture emerging recreational demand in Phuket and Pattaya coastal zones where low-cost aerial experience packages target tourism markets. The country's tourism ministry has designated aviation recreation zones with simplified operational permits for foreign-owned equipment. Bangkok-based distributors are expanding fleet orders to serve Indonesian and Vietnamese tourism operators seeking comparable infrastructure.
Global Ultralight and Light Aircraft Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue electric propulsion certification and builder-assist program expansion. The vendor base stratifies across certified aircraft manufacturers, kit plane fabricators, and electric aviation specialists with divergent regulatory compliance burdens. Three archetypes dominate: heritage brands with institutional training contracts, composite-focused European specialists, and electric-first challengers racing EASA rulemaking timelines. Competitive moves concentrate on geographic certification stacking and factory-assisted build program scaling.
Among heritage-tier manufacturers, Textron Aviation and Cessna Aircraft Company represent the institutional training contract archetype through established relationships with North American flight academies. Pipistrel occupies a position within the electric propulsion specialist tier, exemplifying Slovenian manufacturing concentration in the European light sport segment. Cirrus Aircraft anchors the premium certified aircraft category with glass cockpit integration standards that training fleet operators specify for replacement procurement cycles.
| Leading Market Players |
|---|
| Textron Aviation |
| Cirrus Aircraft |
| Pilatus Aircraft |
| Piper Aircraft |
| Cessna Aircraft Company |
| Costruzioni Aeronautiche TECNAM SpA |
| Flight Design General Aviation GmbH |
| Pipistrel |
| Evektor |
| Others |
Value Chain & Pricing Dynamics
The EU Green Deal aviation incentives gate qualified supply for electric light sport aircraft while reserving premium-tier pricing access for manufacturers with EASA CS-LSA type certificates and documented battery management systems. Flight schools and agricultural operators face divergent procurement economics where certification burden directly determines margin capture.
Pricing Analysis
The volume-vs-margin split separates kit plane assemblers capturing owner-built experimental benefits from certified aircraft manufacturers commanding institutional training contracts. Three-tier pricing structure across certified, experimental amateur-built, and pure ultralight categories reflects FAA Part 103 exemption levels versus EASA CS-LSA compliance costs. Price differentiation centers on certification grade and after-sales service bundling, with European academies paying premiums for regional service networks. Pricing pressure stems from lithium-ion cathode material supply concentration in China, compressing margin projections for battery-powered designs. Agricultural producers in Brazil exhibit highest price sensitivity on payload capacity metrics, while North American flight schools prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Domestic-content mandates in Brazil and emerging Southeast Asian markets are reshaping sourcing patterns for airframe assemblies and propulsion components. Manufacturing gravity centers on the United States, Germany, and the Czech Republic for kit plane fabrication, with Slovenia anchoring electric propulsion specialization. Raw material dependencies span carbon fiber precursors from Japan, aluminum alloys from Russia and China, and lithium battery cells from South Korean producers. Single-source vulnerability concentrates in battery thermal management system controllers, where avionics software competencies lag traditional airframe mechanic training. Distribution runs through factory completion centers in the Sun Belt and Bavaria, bypassing traditional dealer networks for builder-assist programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around electric propulsion certification capabilities, with EASA rulemaking timelines forcing weaker airframe specialists without battery integration expertise toward exit.
For Market Incumbents: Deploy builder-assist program scaling to defend against pure kit manufacturers compressing assembly timelines. Secure backward integration into carbon fiber composite fabrication to offset technician scarcity extending aircraft-on-ground durations. Lock institutional training contracts through glass cockpit avionics standardization before electric-first challengers secure EASA CS-LSA amendments. For New Entrants and Emerging Players: Launch via direct-to-consumer digital sales channels targeting Australian and Thai tourism operators with powered paraglider configurations. Capture white-space in Southeast Asian coastal experience packages where minimal training requirements reduce customer acquisition friction. Prioritize EU Green Deal subsidy eligibility through electric sustainer motor integration for alpine glider clubs. For Investors and Strategic Acquirers: First-mover type certificate applications from Slovenian and Czech producers are the leading indicator that electric light sport aircraft certification stacking is accelerating. Long-term viability favors manufacturers with demonstrated battery management system documentation and regional service network density. Target acquisition archetypes include composite-focused European specialists with experimental amateur-built regulatory familiarity and factory completion center assets.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion Certification Stacking | EASA CS-LSA amendments force battery management system documentation alongside airframe stress analysis. |
| Builder-Assist Program Expansion | Factory completion centers in the United States and Czech Republic compress customer assembly timelines. |
| Backward Integration into Composites | In-house carbon fiber fabrication mitigates technician scarcity for damage assessment and scarf repair. |
| Direct-to-Consumer Digital Sales | Online configuration tools bypass dealer markups and capture margin from aviation enthusiasts. |
| Regional Service Network Density | European academies concentrate procurement with manufacturers offering EASA type certificates and local maintenance support. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with flight school fleet managers, kit plane manufacturer operations directors, EASA certification specialists, and agricultural spray operators combined with FAA type certificate databases, EASA design approval registries, and ASTM F2245 compliance documentation. Bottom-up triangulation across aircraft type, application, end user, and distribution channel segmentation reconciled with top-down macroeconomic indicators.
Data-stream reconciliation across production volume disclosures, fleet renewal announcements, and regulatory amendment drafts shaped the analytical framework across the analysis window. Segmentation dimensions modeled include aircraft type, application mission, end user archetype, and distribution channel, with electric propulsion certification status as a cross-cutting modifier. CAGRs derived from historical fleet replacement cycles and projected training demand expansion, incorporating battery energy density improvement curves and aviation gasoline supply fragmentation patterns.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for electric light sport aircraft viability. Forecasts reflect assumptions on EASA rulemaking finalization timelines and EU Green Deal subsidy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
North America Aviation Market
Aircraft
Docking System Market
Aircraft
Hybrid Aircraft Market
Aircraft
Aircraft Windshield Wiper and Washer System Market
Aircraft
Aircraft Door Market
Aircraft
Global Business Jets Market
Aircraft
Aviation Market
Aircraft
Middle-East and Africa Helicopters Market
Aircraft
India Winglets Market
Aircraft
Air Speed Indicator Market
Aircraft
Southeast Asia Aviation Market
Aircraft
Enhanced Flight Vision Systems ( EFVS) Market
Aircraft
Experimental Amateur-Built (E-AB) Aircraft Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Global Aircraft Tugs Market
Aircraft
Wing Inspection and Taxi Lighting Upgrade Kits Market